
 Drone Lens Market | 2026-2036
Drone Lens Market Size, Share, and Industry Trends Forecast 2026-2036
Drone Lens Market Insights
FAA Part 107 is broadening the cost-of-entry calculus for commercial drone operators by mandating remote pilot certification and operational waivers. Sony Semiconductor Solutions Group leverages its CMOS sensor-lens integration to dominate high-resolution cinematography applications. Teledyne FLIR LLC anchors thermal imaging demand through its infrared lens portfolios for inspection services. ams-OSRAM AG specializes in compact optical modules that reduce payload weight for extended flight endurance.
A drone lens is a precision optical assembly engineered with aspherical elements and multi-coating layers to minimize aberrations across vibration-prone aerial platforms, typically specified by focal length, aperture range, and image circle compatibility with compact camera sensors. Wide angle and zoom configurations lead product type demand due to their versatility in mapping solutions and cinematography, while infrared technology captures expanding margin pools as thermal inspection requirements proliferate. Autofocus systems are displacing manual alternatives in commercial segments where operator attention must prioritize flight path over lens adjustment.
FAA regulations in the United States, EASA drone framework provisions in Europe, and China's CAAC low-altitude economy policies collectively shape airspace access, payload certification, and operational altitude ceilings that directly determine lens durability and optical performance specifications. ISO 21384-3 unmanned aircraft systems standards further codify imaging quality benchmarks for survey-grade applications. Stakeholders must monitor evolving beyond-visual-line-of-sight waiver expansions and their implications for long-range telephoto lens demand.
Market Dynamics
The convergence of FAA Part 107 certification expansion and DJI's ecosystem dominance in China is compressing development cycles for optical assemblies while elevating durability specifications for vibration-prone aerial platforms.
Growth Catalysts
- Multispectral imaging adoption:Agriculture enterprises deploy crop health assessment systems requiring specialized lens coatings that filter discrete wavelength bands for vegetation index calculation.
- CAAC low-altitude economy policies:China's regulatory framework accelerates commercial airspace access for payload-carrying unmanned systems across logistics and inspection verticals.
- Thermal inspection proliferation:Infrastructure operators mandate infrared-capable optics for electrical grid and pipeline monitoring, expanding addressable use cases beyond visible-spectrum cinematography.
Market Restraints
- CMOS sensor supply concentration:Japanese and Korean semiconductor foundries control high-resolution imaging chip output, creating input bottlenecks for lens-integrated module manufacturers.
- Payload weight constraints:Extended flight endurance requirements impose strict mass limits on glass element counts and housing materials, compressing optical design degrees of freedom.
- EASA operational category fragmentation:Europe's open-specific-certified framework creates certification complexity that slows equipment approval timelines for cross-border service providers.
Strategic Opportunities
- Beyond-visual-line-of-sight waivers:FAA expansion of BVLOS authorizations for agricultural and energy inspection operators creates demand for long-range telephoto configurations with enhanced stabilization.
- Autofocus system convergence:Machine vision algorithms paired with ultrasonic or phase-detect modules enable hands-free operation for single-pilot commercial deployments.
- India's PLI scheme for drones:Production-linked incentives for domestic unmanned system manufacturing attract lens assembly investments targeting price-sensitive surveying and mapping segments.
Industry Challenges
- ISO 21384-3 compliance timelines:Survey-grade imaging quality benchmarks require extensive vibration testing and thermal cycling validation that extends product development schedules.
- Optical design talent scarcity:Aspherical element engineering and multi-coating process expertise concentrates in legacy camera industry hubs, constraining workforce expansion for aerial-specialized manufacturers.
- Integration complexity with legacy gimbal systems:Third-party lens mounts must adapt to proprietary communication protocols from established drone OEMs, fragmenting interoperability standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drone Lens Market |
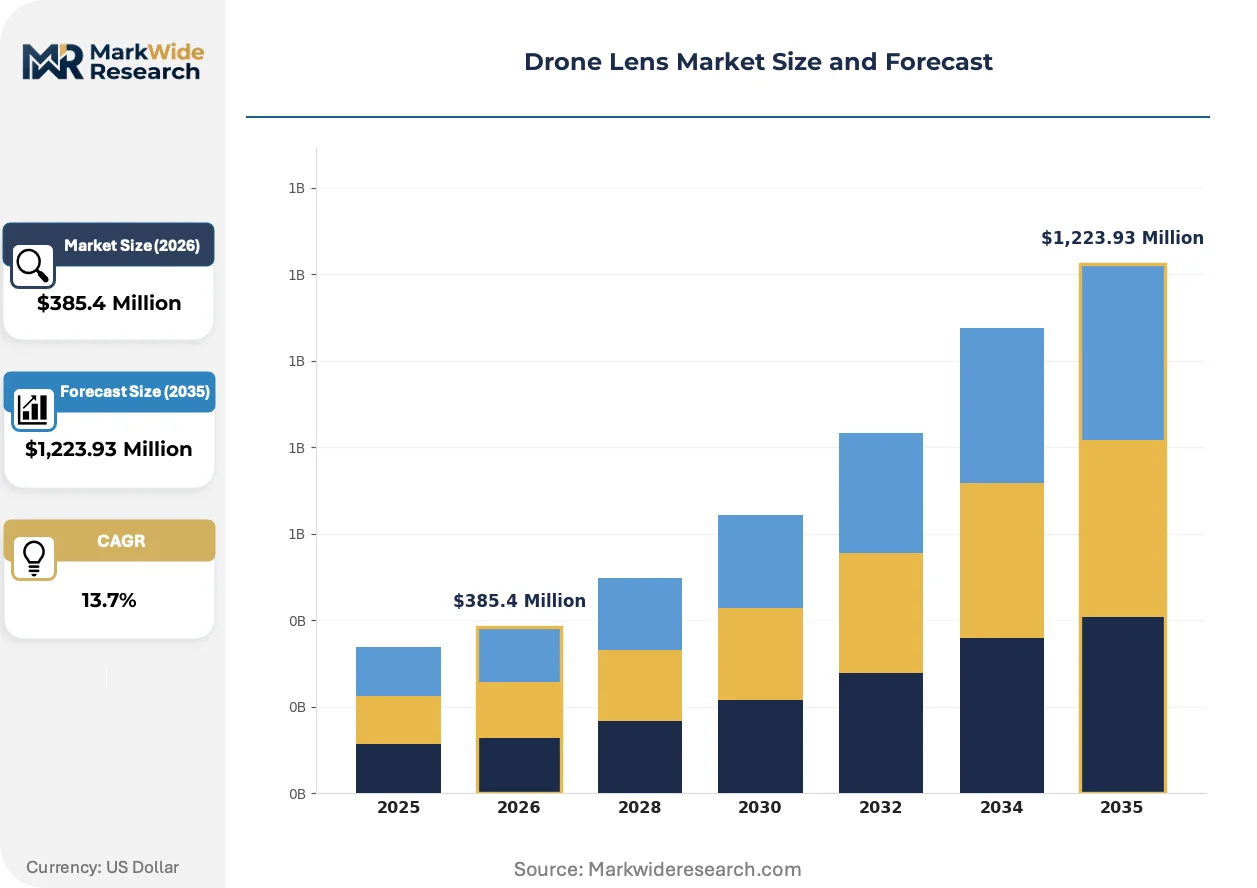
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $1,223.93 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wide Angle, Telephoto, Prime, Fisheye, Zoom, Macro Technology: Optical Image Stabilization, Autofocus, Manual Focus, Aspherical Lens, Infrared, Polarized Application: Inspection Services, Aerial Surveying, Cinematography, Mapping Solutions, Agriculture Monitoring, Surveillance End User: Film Production Companies, Surveying Firms, Security Agencies, Farming Enterprises, Environmental Consultants, Infrastructure Auditors |
| Companies Covered | Sony Semiconductor Solutions Group, Teledyne FLIR LLC, ams-OSRAM AG, Bosch Sensortec GmbH, TE Connectivity, RTX, KVH Industries, Inc., LeddarTech Holdings Inc., Sentera, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drone Lens Market Trends and Innovations
Computational photography architectures and regulatory waiver expansions are redefining optical performance benchmarks while compressing traditional hardware upgrade cycles across commercial unmanned platforms.
Swappable lens mount systems with integrated electronic contacts are absorbing data transmission and power management functions previously handled by separate camera bodies. Survey and cinematography operators now demand rapid focal length changes without gimbal recalibration. This convergence is absorbing aftermarket third-party adapter margins into OEM-controlled ecosystem revenues.
EASA's specific category operational risk assessments now mandate redundant imaging pathways for flights over populated areas. Equipment manufacturers must certify dual-sensor configurations with synchronized recording capabilities. European infrastructure inspection providers are responding by specifying lens assemblies with dual-output architectures that satisfy these contingency requirements without payload duplication.
Direct procurement relationships between large agricultural cooperatives and optical specialists are displacing distributor-mediated equipment sales in North American grain belt regions. Volume buyers negotiate custom spectral filtering specifications for crop-specific monitoring applications. This channel compression is most visible across Midwestern US farming enterprises operating fleets exceeding fifty airframes per operation.
Drone Lens Market Segmentation
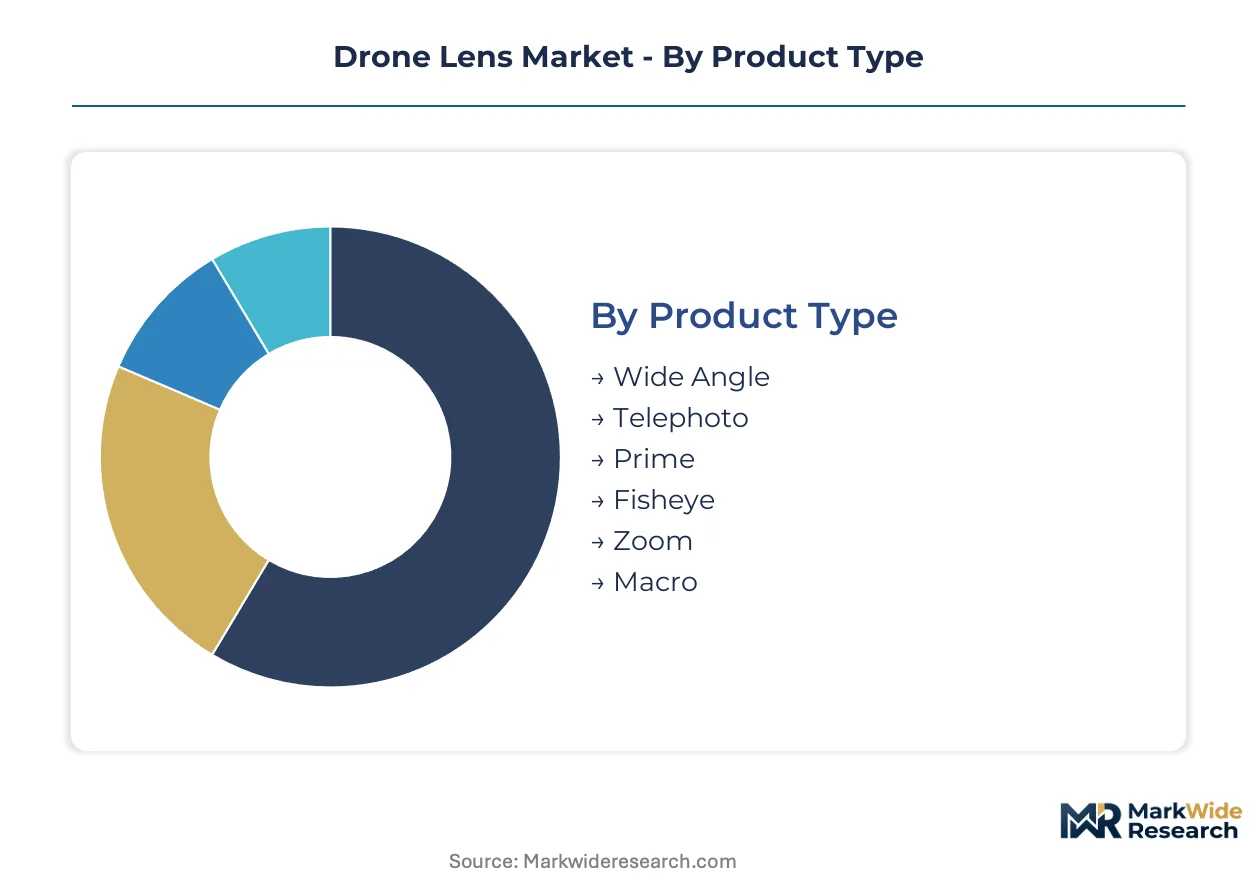
Drone lens specifications diverge sharply across payload constraints and imaging objectives. Optical assemblies must balance vibration tolerance, weight limits, and sensor compatibility while serving distinct commercial workflows from multispectral agriculture to thermal infrastructure audit.
Product Type:
Focal length and field-of-view specifications determine gimbal integration complexity and capture versatility across flight profiles.
- Wide Angle:Short focal lengths between 10-24mm capture expansive terrain with minimal distortion correction requirements. Surveying firms in the United States deploy these configurations for cadastral mapping where ground coverage per flight pass directly reduces operational costs.
- Zoom:Variable focal ranges enable single-lens flexibility for inspection operators working at varying standoff distances from electrical transmission infrastructure. China's logistics inspection sector drives demand for parfocal designs that maintain focus through magnification changes.
- Telephoto:Extended reach optics for beyond-visual-line-of-sight wildlife and perimeter monitoring.
- Prime:Fixed focal length assemblies optimized for maximum aperture and minimal aberration in cinematography.
- Fisheye:Ultra-wide hemispherical capture for 360-degree photogrammetry and immersive content.
- Macro:Close-focus capabilities for detailed defect identification in precision agriculture and industrial quality control.
Mature deployment sits with Wide Angle configurations in established surveying workflows. Newer deployment is concentrated in Zoom variants as inspection operators seek payload consolidation.
Technology:
Stabilization and focus mechanisms absorb the largest engineering margins as operators prioritize hands-free capture during complex flight maneuvers.
- Optical Image Stabilization:Moving lens element groups compensate for platform vibration and wind gust interference. European cinematography operators under EASA specific category mandates specify these systems for flights over populated areas where retake feasibility is limited.
- Infrared:Thermal wavelength transmission through germanium or chalcogenide glass elements enables electrical grid and pipeline monitoring after dark. Infrastructure auditors in Texas and California deploy these configurations for substation inspection where heat signature anomalies predict equipment failure.
- Autofocus:Phase-detect or contrast-based systems reduce pilot cognitive load during dynamic tracking shots.
- Manual Focus:Direct control preferred by cinematographers for deliberate rack focus effects.
- Aspherical Lens:Non-spherical surface profiles reduce element count and overall mass.
- Polarized:Glare reduction coatings for water surface and glass facade inspection.
Volume concentration favors Optical Image Stabilization in commercial fleets. Margin expansion is steepest in Infrared as thermal inspection penetrates new verticals.
Application:
Workflow-specific imaging requirements dictate spectral sensitivity, resolution targets, and data processing pipelines.
- Agriculture Monitoring:Multispectral and NDVI-capable coatings filter discrete wavelength bands for vegetation stress detection. Farming enterprises in Iowa and Illinois negotiate direct procurement contracts with optical specialists for crop-specific spectral configurations.
- Inspection Services:Thermal and high-resolution visible-spectrum optics for predictive maintenance of critical infrastructure. Energy utilities across the United States specify dual-sensor redundancy to satisfy FAA waiver requirements for flights over transmission corridors.
- Aerial Surveying:Metric photogrammetry with calibrated distortion parameters.
- Cinematography:Cine-specified T-stops and consistent color rendering across lens sets.
- Mapping Solutions:Orthorectification-optimized optics with minimal radial distortion.
- Surveillance:Low-light performance and long-range telephoto for perimeter security.
Equipment refresh cycles are longest in Mapping Solutions where survey-grade certification creates switching costs. Steepest expansion trajectory belongs to Agriculture Monitoring as cooperatives scale fleet sizes.
End User:
Procurement authority and volume scale vary dramatically across organizational types and funding mechanisms.
- Surveying Firms:Professional geomatics services with recurring equipment refresh cycles and calibration discipline. These operators in Germany and France maintain ISO 21384-3 compliance documentation as competitive differentiation in public tender processes.
- Farming Enterprises:Agricultural cooperatives and large-scale operators integrating drone imagery into precision agriculture platforms. Midwestern US grain belt operations exceeding fifty airframes per site negotiate custom spectral filtering directly with lens manufacturers.
- Film Production Companies:Project-based rental and purchase decisions tied to specific directorial requirements.
- Security Agencies:Government and private perimeter protection with encrypted data transmission requirements.
- Environmental Consultants:Ecological monitoring and compliance documentation for regulatory submission.
- Infrastructure Auditors:Utility and transportation asset condition assessment with predictive maintenance integration.
Contracting sophistication is highest among Surveying Firms with formal vendor qualification programs. Procurement velocity is accelerating fastest among Farming Enterprises as cooperative buying consolidates fragmented demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's CAAC-designated low-altitude economy demonstration zones concentrate drone lens manufacturing and testing infrastructure, attracting component suppliers with tax incentives and streamlined airspace access protocols.
United States
FAA Part 107 certification expansion is broadening the commercial pilot pool while mandating equipment durability standards for vibration-prone aerial platforms. The agency's beyond-visual-line-of-sight waiver program for agricultural and energy inspection operators is accelerating demand for long-range telephoto configurations. Texas and California infrastructure auditors deploy thermal-capable optics for electrical grid substation monitoring where heat signature anomalies predict equipment failure.
China
CAAC low-altitude economy policies accelerate commercial airspace access for payload-carrying unmanned systems across logistics and inspection verticals. DJI's ecosystem dominance in Shenzhen drives lens specification trends across commercial and consumer segments. The Pearl River Delta manufacturing cluster absorbs precision optical assembly investments targeting domestic and export markets with compressed development cycles.
Germany
EASA's specific category operational risk assessments mandate redundant imaging pathways for flights over populated areas, requiring dual-sensor certification. Surveying firms in Bavaria and North Rhine-Westphalia maintain ISO 21384-3 compliance documentation as competitive differentiation in public tender processes. Stuttgart's automotive heritage feeds precision engineering talent into aspherical element manufacturing for aerial-specialized optics.
India
The PLI scheme for drones attracts lens assembly investments targeting price-sensitive surveying and mapping segments. Farming enterprises in Maharashtra and Gujarat negotiate direct procurement contracts with optical specialists for crop-specific spectral configurations. Bangalore's aerospace and precision engineering ecosystem supports component testing and calibration infrastructure development.
Japan
CMOS sensor supply concentration in Japanese semiconductor foundries creates input bottlenecks for lens-integrated module manufacturers. METI industrial policy supports precision optics R&D for unmanned systems integration. Tokyo and Osaka metropolitan areas concentrate optical design talent with legacy camera industry expertise in aspherical element engineering.
Drone Lens Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the drone lens market structure. Tier-one sensor-integrated module suppliers leverage semiconductor manufacturing scale against specialized optical houses optimizing weight-constrained aerial applications. Strategic archetypes include CMOS sensor-lens integrators, thermal infrared specialists, and compact optical module designers. Dominant competitive moves center on ecosystem lock-in through proprietary mount systems and direct procurement relationships with large agricultural cooperatives.
Within the sensor-integrated tier, Sony Semiconductor Solutions Group and Teledyne FLIR LLC exemplify divergent specialization vectors—one anchored in visible-spectrum cinematography resolution, the other in thermal wavelength transmission for infrastructure audit applications. Among European-focused component suppliers, ams-OSRAM AG occupies a position representing compact optical module miniaturization for extended flight endurance requirements.
| Leading Market Players |
|---|
| Sony Semiconductor Solutions Group |
| Teledyne FLIR LLC |
| ams-OSRAM AG |
| Bosch Sensortec GmbH |
| TE Connectivity |
| RTX |
| KVH Industries, Inc. |
| LeddarTech Holdings Inc. |
| Sentera |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between survey-grade ISO 21384-3 compliant optics and uncertified economy alternatives manifests in both pricing premiums and supply chain sourcing strategies. Premium assemblies draw from Japanese CMOS sensor foundries and German aspherical grinding houses, while economy tiers source from Pearl River Delta contract manufacturers with compressed validation cycles.
Pricing Analysis
Short lead-time premiums of 15-25 percent apply to thermal infrared configurations stocked for Texas and California infrastructure auditors facing emergency substation inspection contracts. The dominant pricing structure stratifies across premium certified, standard commercial, and economy OEM-bundled tiers. Price differentiation centers on ISO 21384-3 compliance documentation and EASA specific category dual-sensor redundancy certification. Cost compression in economy tiers intensifies because DJI's ecosystem lock-in forces third-party mount adapter producers into margin sacrifices. Farming enterprises in Iowa and Illinois exhibit highest price sensitivity, while European cinematography operators under EASA mandates show least sensitivity due to insurance and liability considerations.
Supply Chain Analysis
Returns and refurbishment flows for high-value thermal optics create reverse logistics infrastructure concentrated in Texas, Arizona, and Shenzhen. Optical glass element production concentrates in Germany, Japan, and China. Raw material dependencies include germanium and chalcogenide glass for infrared transmission, rare-earth coating materials, and precision-molded aspherical substrates. Single-source vulnerability sits with Japanese semiconductor foundries controlling high-resolution CMOS sensor output. Distribution runs through direct procurement relationships with large agricultural cooperatives and specialized surveying equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aspherical element engineering talent scarcity props pricing for certified optics as workforce expansion lags demand from precision agriculture and infrastructure inspection verticals.
For Market Incumbents: Anchor ecosystem lock-in through proprietary lens mount communication protocols that fragment interoperability standards and raise switching costs. Defend against Chinese OEM vertical integration by deepening direct procurement relationships with Midwestern farming cooperatives operating fifty-plus airframe fleets. Prioritize certification investment in EASA specific category dual-sensor redundancy to capture European infrastructure inspection contracts. For New Entrants and Emerging Players: The price-point gap between DJI-bundled economy optics and Sony-integrated premium cinematography configurations creates white-space opportunity. Target India's PLI scheme beneficiaries with compact optical modules for price-sensitive surveying segments. Pursue custom spectral filtering contracts with Maharashtra and Gujarat farming enterprises as a go-to-market angle bypassing established distributor channels. For Investors and Strategic Acquirers: Re-rating potential sits with thermal infrared specialists given FAA beyond-visual-line-of-sight waiver expansion for energy inspection operators. Long-term viability favors acquisition targets with integrated stabilization and autofocus machine vision capabilities. Monitor CAAC low-altitude economy policy acceleration in Shenzhen demonstration zones as inflection indicator for domestic Chinese demand scaling.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 21384-3 Certification Investment | Surveying firms in Germany and France differentiate through compliance documentation in public tenders. |
| Backward Integration into CMOS Sensor Supply | Japanese foundry partnerships reduce input bottlenecks for lens-integrated module manufacturers. |
| Direct Procurement Channel Development | Midwestern agricultural cooperatives negotiate custom spectral filtering bypassing distributor margins. |
| Dual-Sensor Redundancy Architecture | EASA specific category mandates drive equipment certification for flights over populated areas. |
| Autofocus Machine Vision Convergence | Phase-detect and ultrasonic modules enable single-pilot commercial deployments reducing labor costs. |
Research Methodology
Trade databases, customs filings, and semiconductor equipment import records formed the secondary backbone for supply-side capacity assessment. Primary interviews with optical design engineers, agricultural cooperative procurement managers, infrastructure audit firm operations directors, and EASA certification consultants combined with secondary validation across FAA waiver documentation, CAAC policy circulars, and ISO standards repositories. Bottom-up triangulation against top-down aerial imaging equipment production estimates anchored market sizing.
Historical trendline analysis of lens assembly shipments, CMOS sensor wafer starts, and drone airframe production established baseline growth trajectories across the projection horizon. The analytical framework modeled product type, technology, application, and end user segments alongside regional regulatory cluster differentiation. CAGRs derived from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs included agricultural drone fleet penetration rates and thermal inspection contract award velocity from Texas and California utilities.
Inputs from EASA certification registries and FAA waiver approval databases were available through the study window; gaps in Chinese CAAC operational permit disclosures introduce uncertainty bands around domestic demand estimates. Forecasts reflect documented assumptions regarding BVLOS authorization timelines and PLI scheme disbursement rates. Practitioners should monitor CAAC low-altitude economy zone expansion and Japanese foundry capacity announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Airborne Digital Battlefield Market
UAV
Drone-In-A-Box Market
UAV
Latin America Small UAV Market
UAV
North America Small UAV Market
UAV
Small UAV Market
UAV
Tactical UAV Market
UAV
North America Fuel Cell UAV Market
UAV
Enterprise Drone Management Solutions Market
UAV
GCC Drone Pilot Training Market
UAV
North America Drones Market
UAV
United States Drone Services Market
UAV
Industrial Drones Market
UAV
Fixed Wing Military Drones Market
UAV
UAV Simulator Market
UAV
Global Multirotor UAV Market
UAV
Electric Glider Market