
 Drone-Based Consulting Services Market | 2026-2036
Drone-Based Consulting Services Market Size, Share, and Industry Trends Forecast 2026-2036
Drone-Based Consulting Services Market Foresight
FAA Part 107 is restructuring the cost-of-entry calculus for commercial drone operators by expanding beyond-visual-line-of-sight waivers and streamlining pilot certification pathways. PrecisionHawk leverages its vertical integration into proprietary flight analytics software to sustain recurring utility contracts across North American transmission corridors. Terra Drone anchors its competitive position through deep regulatory navigation in Asian markets, while Cyberhawk specializes in confined-space industrial inspections for offshore oil and gas facilities.
Drone-based consulting services encompass the professional advisory, data acquisition, and analytical interpretation of unmanned aerial system outputs for commercial decision-making, typically involving flight altitudes below 400 feet with sensor payloads including LiDAR, thermal, and multispectral imagers. These services transform raw aerial captures into actionable intelligence for infrastructure integrity, crop health, or construction progress monitoring. Inspection services currently dominate revenue flows due to mandatory asset integrity cycles in energy and utilities, while LiDAR-enabled mapping commands premium pricing in topographic and corridor planning engagements. Thermal imaging is the fastest-expanding technology segment as insurers and regulators mandate heat-loss and electrical fault detection in commercial building portfolios and solar installations.
The FAA governs airspace access and pilot credentialing in the United States, while EASA's U-space framework and specific category certifications shape European operational parameters, and China's CAAC implements GB standards for civilian unmanned flight below 120 meters. Regulatory fragmentation across these jurisdictions forces service providers to maintain multiple compliance architectures, elevating barriers for pure-software entrants lacking aviation law expertise. Stakeholders must monitor which regulator moves first on fully automated BVLOS frameworks, as this jurisdiction will concentrate early-mover investment and talent migration.
Market Dynamics
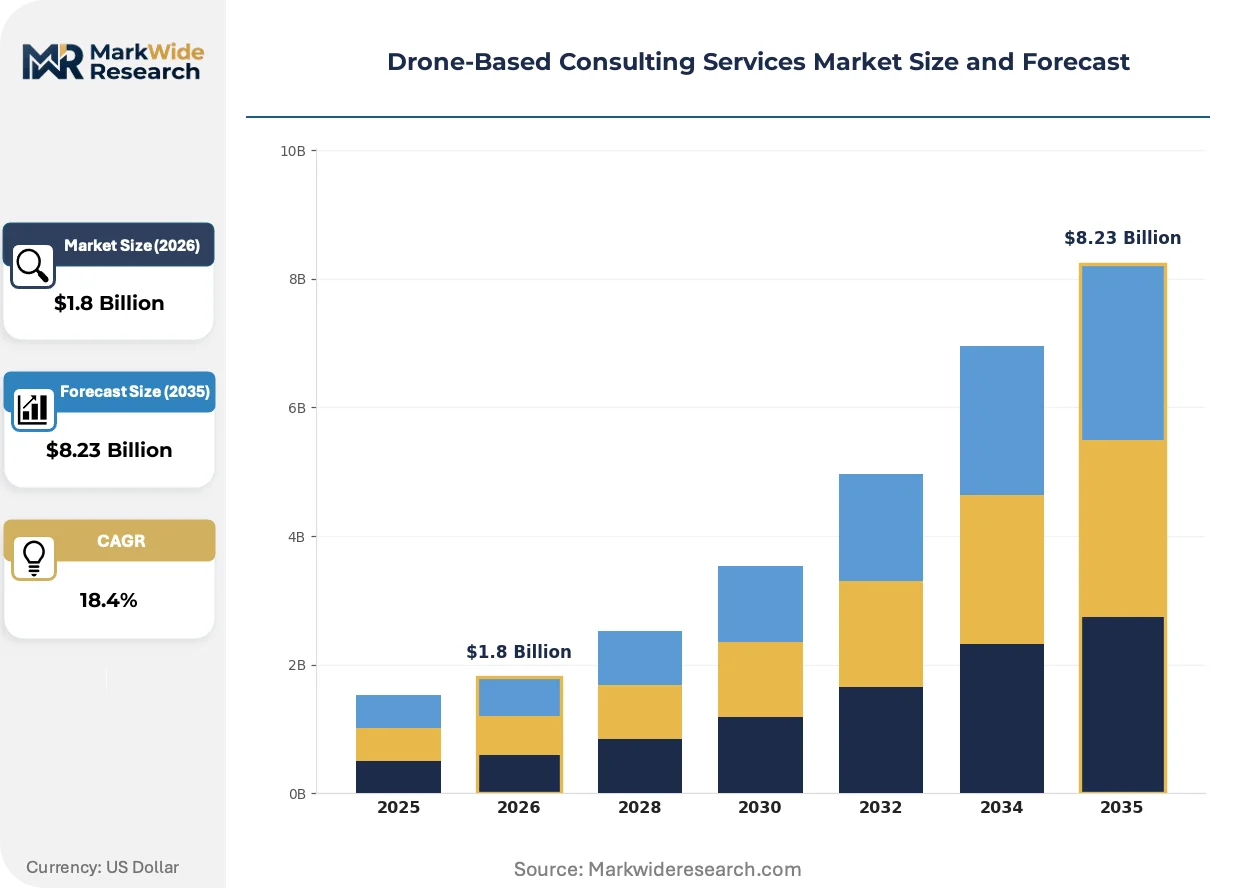
Energy utilities are consolidating inspection procurement around recurring aerial service contracts as FAA Part 107 waivers expand beyond-visual-line-of-sight operations, compressing the cost gap between drone-based and traditional manned aviation for transmission corridor monitoring.
Growth Catalysts
- BVLOS Regulatory Expansion:The FAA's evolving Part 107 waiver framework in the United States is removing altitude and range restrictions for commercial operators, unlocking utility-scale solar and wind farm inspections previously requiring manned helicopters.
- LiDAR Sensor Miniaturization:Advances in solid-state LiDAR are reducing payload weight thresholds, enabling longer flight durations for topographic mapping and corridor planning engagements across North American transmission networks.
- Mandatory Asset Integrity Cycles:FERC inspection mandates for electrical transmission infrastructure and insurer-driven thermal monitoring requirements for commercial building portfolios are institutionalizing recurring drone-based service contracts.
Market Restraints
- Aviation Law Expertise Scarcity:Regulatory fragmentation across FAA, EASA, and CAAC jurisdictions forces service providers to maintain multiple compliance architectures, elevating fixed costs for entrants lacking captive aviation legal capacity.
- Sensor Payload Cost Concentration:Thermal and multispectral imager supply concentrates among Japanese and German component manufacturers, exposing margins to yen and euro exchange volatility.
- Battery Energy Density Ceiling:Lithium-polymer chemistry limitations cap flight endurance below 45 minutes for heavy LiDAR payloads, constraining single-sortie coverage area for corridor-scale engagements.
Strategic Opportunities
- Offshore Oil and Gas Confinement:Confined-space inspection requirements for North Sea and Gulf of Mexico platforms remain underpenetrated by drone-based providers, with helicopter alternatives facing weather downtime constraints.
- EU Green Deal Alignment:CSRD-mandated emissions disclosure and asset-level climate risk reporting are creating audit-grade documentation requirements that drone-based thermal and multispectral capture can satisfy.
- AI-Enabled Defect Recognition:Convergence of edge-computing inference chips with thermal imaging is enabling real-time fault classification during flight, compressing analyst review cycles and expanding addressable inspection volume.
Industry Challenges
- Pilot Certification Bottlenecks:FAA Part 107 remote pilot credentialing timelines and practical examination slot scarcity are constraining workforce scaling for service providers winning multi-site utility contracts.
- Legacy SCADA Integration Friction:Utility clients require drone-derived inspection data to flow into existing asset management databases, forcing custom API development and data format standardization delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drone-Based Consulting Services Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.23 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Surveys, Inspections, Mapping, Monitoring Technology: LiDAR, Imaging, Thermal, Multispectral End User: Agriculture, Construction, Energy, Environmental Application: Data Analysis, Asset Management, Risk Assessment, Compliance |
| Companies Covered | PrecisionHawk, DroneDeploy, Terra Drone, Aerodyne Group, Cyberhawk, Sky-Futures, Measure, Aerialtronics, Delair, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drone-Based Consulting Services Market Shifts & Advancements
Autonomous flight systems and real-time edge analytics are compressing the analyst-in-the-loop requirement, shifting value capture from data collection toward predictive intelligence delivery for infrastructure operators.
Automated defect recognition software is automating thermal anomaly flagging in electrical transmission components. Duke Energy and Southern California Edison are deploying these systems across their respective 32,000-mile and 18,000-mile transmission networks, reducing analyst review time from days to hours. This compression is automating the traditional labor-intensive interpretation layer, enabling service providers to bid lower per-mile rates while defending margin through volume throughput.
EASA's U-space regulatory framework is mandating unmanned traffic management integration for operations above 120 meters in European urban airspace. The industrial consequence is a certification requirement for detect-and-avoid systems that adds hardware cost but creates regulatory moats against non-compliant entrants. German and French utility operators are prioritizing U-space-ready service providers in renewable energy site selection, accelerating vendor consolidation across the EU market.
Subscription-based inspection contracts are displacing project-based procurement for utility-scale solar and wind portfolios. Asset owners in Texas and California are consolidating multi-year service agreements with single providers, replacing fragmented regional vendor relationships. This concentration is most visible in the ERCOT and CAISO grid regions, where renewable deployment scale justifies dedicated flight crews and equipment pools.
Drone-Based Consulting Services Market Segmentation
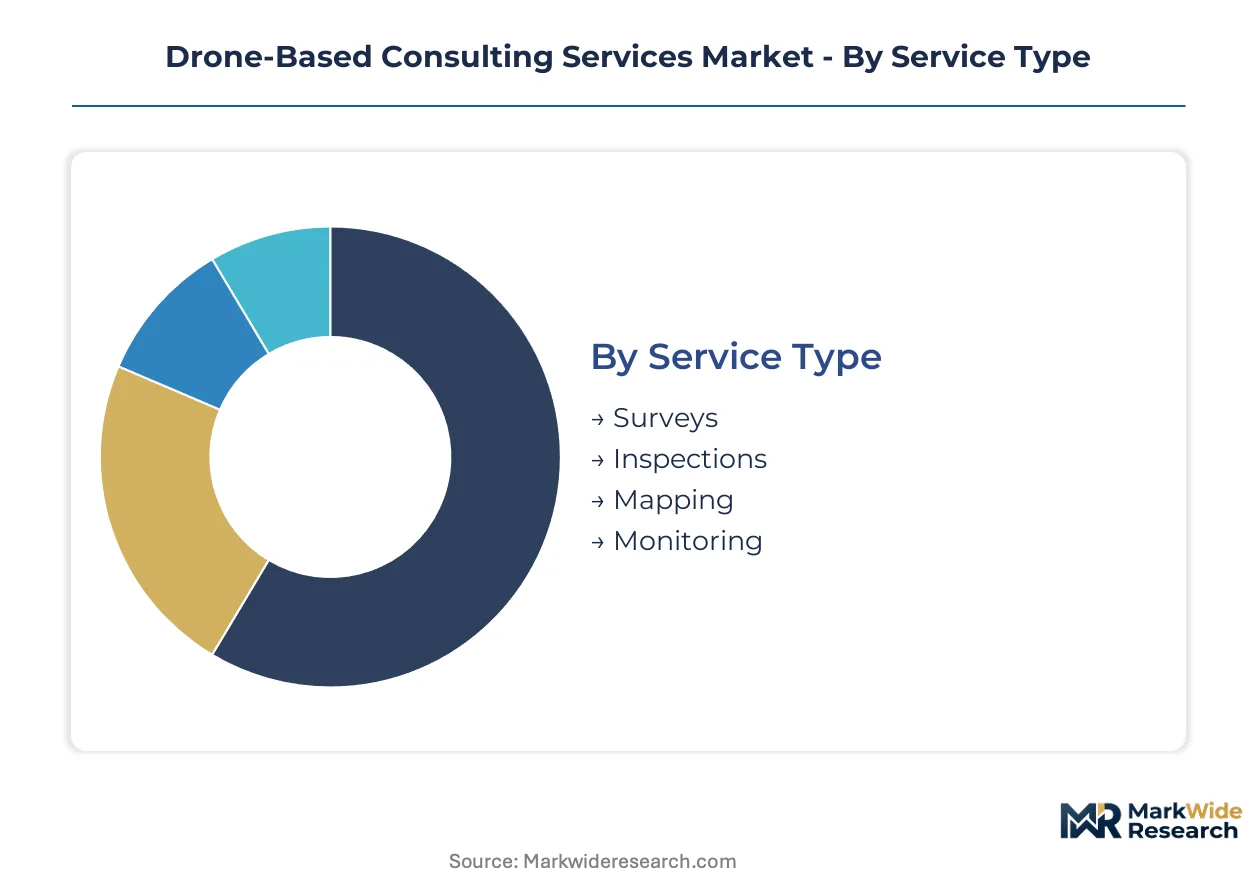
Drone-based consulting services fragment across four distinct dimensions, each with divergent margin profiles and regulatory exposure. Service type and technology selection determine contract value and pilot certification requirements, while end-user verticals dictate seasonal demand patterns and sensor payload specifications.
Service Type:
Supply concentrates among inspection specialists with recurring utility contracts, while project-based mapping providers compete on equipment depreciation cycles.
- Inspections:Recurring transmission corridor and solar farm assessments dominate revenue flows. FERC-mandated electrical infrastructure cycles in Texas and California institutionalize multi-year service agreements with dedicated flight crews.
- Mapping:Topographic and corridor planning engagements command premium pricing through LiDAR payload deployment. Solid-state sensor miniaturization is extending flight duration for North American transmission network coverage.
- Surveys:Pre-construction site assessments for renewable energy developers in the ERCOT and CAISO grid regions.
- Monitoring:Continuous agricultural crop health and construction progress tracking with multispectral imager integration.
Inspections absorb the bulk of installed capacity; monitoring is expanding most quickly through subscription-based agricultural contracts.
Technology:
Cost tiers separate thermal imager deployments from basic RGB photography, with LiDAR systems requiring capital commitments that filter out regional independents.
- Thermal:Heat-loss detection and electrical fault classification for commercial building portfolios and solar installations. Insurer mandates and CSRD-aligned emissions disclosure requirements in Germany and France are accelerating procurement.
- LiDAR:Solid-state laser scanning for millimeter-accurate topographic modeling. Japanese and German component supply concentration exposes margins to yen and euro exchange volatility.
- Imaging:Standard RGB and high-resolution photographic capture for basic documentation and marketing deliverables.
- Multispectral:Agricultural vegetation index mapping with narrow-band spectral filtering for crop stress detection.
Thermal imaging climbs the fastest as regulatory disclosure frameworks mandate audit-grade building envelope documentation; LiDAR retains the highest per-project contract values.
End User:
Application maturity varies sharply across verticals, with energy utilities consolidating procurement around flight-hour guarantees while construction remains fragmented.
- Energy:Transmission corridor monitoring and offshore platform confined-space inspection for Duke Energy and Southern California Edison networks. FAA Part 107 BVLOS waiver expansion is compressing the cost gap against manned helicopter alternatives.
- Agriculture:Precision farming advisory with NDVI-derived irrigation and fertilization recommendations. Subscription models are displacing per-acre project billing in the US Corn Belt.
- Construction:Progress documentation and earthwork volume calculations for commercial development portfolios.
- Environmental:Wetland delineation, wildlife corridor mapping, and post-disaster damage assessment for regulatory compliance filing.
Energy absorbs the bulk of installed capacity; environmental applications are gaining share fastest through disaster response funding cycles.
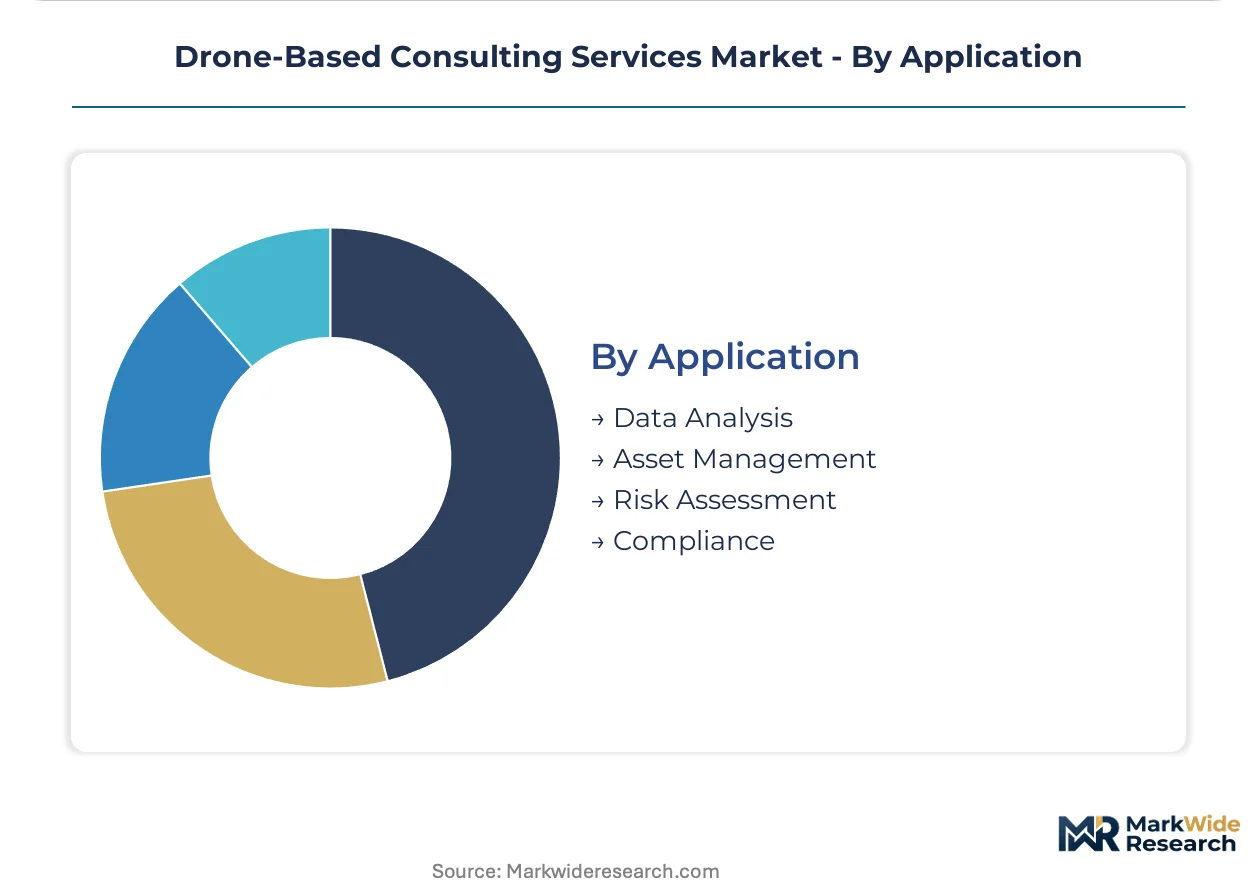
Application:
Customer type stratification separates enterprise asset owners requiring SCADA integration from mid-market operators accepting standardized reporting formats.
- Asset Management:Integration of drone-derived condition data into existing utility databases. Custom API development and legacy SCADA format standardization create friction for service providers winning multi-site contracts.
- Data Analysis:Edge-computing inference chips enabling real-time defect classification during flight. Analyst review cycle compression is expanding addressable inspection volume for transmission network operators.
- Compliance:Audit-grade documentation for EASA U-space certification and FAA waiver renewal submissions.
- Risk Assessment:Pre-acquisition due diligence and insurance underwriting support for commercial property portfolios.
Asset management captures the bulk of contract value; data analysis is scaling fastest through AI-enabled automation of interpretation workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity zones in Texas and California concentrate utility-scale renewable deployments that institutionalize recurring drone service contracts. The FAA's Part 107 waiver framework and EASA's U-space regulations create divergent compliance architectures across North America and Europe. Asian markets navigate CAAC GB standards below 120 meters with distinct certification pathways.
United States
ERCOT and CAISO grid operators mandate recurring transmission corridor inspections that compress the cost gap against manned helicopters. The FAA's evolving BVLOS waiver expansion removes altitude and range restrictions for commercial drone operators. Duke Energy and Southern California Edison anchor demand across 32,000-mile and 18,000-mile transmission networks in Texas and California respectively.
Germany
CSRD-mandated emissions disclosure and asset-level climate risk reporting institutionalize audit-grade thermal documentation requirements. EASA's U-space framework mandates detect-and-avoid system certification for operations above 120 meters in urban airspace. German utility operators in the North Rhine-Westphalia industrial corridor prioritize U-space-ready service providers in renewable energy site selection.
China
Dual carbon goals accelerate utility-scale solar and wind deployments requiring recurring asset monitoring below 120 meters. CAAC implements GB standards for civilian unmanned flight with distinct operational parameters from Western frameworks. Yangtze River Delta renewable clusters in Jiangsu and Zhejiang provinces concentrate procurement for transmission infrastructure inspection.
Japan
Insurer-driven thermal monitoring mandates for commercial building portfolios expand addressable inspection volume. METI standards shape operational parameters for industrial drone deployment in confined-space environments. Osaka-Kansai manufacturing corridors institutionalize recurring service contracts for facility envelope documentation.
United Kingdom
North Sea offshore platform confined-space inspection requirements face weather downtime constraints that favor drone alternatives. EASA-aligned regulatory frameworks post-Brexit maintain U-space trajectory for unmanned traffic management integration. Aberdeen energy clusters and London commercial property portfolios concentrate demand for thermal and multispectral capture services.
Drone-Based Consulting Services Market Competitive Landscape
North American providers anchor one tier with recurring utility contracts; Asian specialists hold regulatory navigation advantages in fragmented compliance environments. The vendor base stratifies across inspection specialists with dedicated flight crews, software-integrated analytics platforms, and regional independents competing on equipment depreciation cycles. Two strategic archetypes dominate: vertically integrated flight-analytics hybrids and regulatory-native specialists with deep jurisdiction-specific certification expertise. Competitive moves concentrate on multi-year service agreement consolidation and detect-and-avoid hardware certification for U-space readiness.
Among North American-integrated providers, PrecisionHawk exemplifies the flight-analytics hybrid archetype with proprietary software sustaining recurring utility relationships. Terra Drone anchors the regulatory-native specialist position through deep navigation of Asian compliance architectures. Cyberhawk occupies a distinct tier specializing in confined-space industrial inspections for offshore oil and gas facilities, representing the vertical-specific depth strategy.
| Leading Market Players |
|---|
| PrecisionHawk |
| DroneDeploy |
| Terra Drone |
| Aerodyne Group |
| Cyberhawk |
| Sky-Futures |
| Measure |
| Aerialtronics |
| Delair |
| Others |
Supply & Pricing Matrix
Captive in-house production of flight analytics software anchors pricing power for vertically integrated providers serving North American utility transmission networks. This backward integration into proprietary data interpretation layers enables recurring subscription premiums while insulating margins from sensor hardware cost volatility.
Pricing Analysis
Short lead-time engagements for emergency storm-damage assessments command premium pricing over standard scheduled inspection cycles. Three-tier pricing structure across premium, standard, and economy levels segments by pilot certification tier and data turnaround speed. Price differentiation hinges on BVLOS waiver status and thermal imager resolution grade. Cost compression in economy-tier RGB photography is intensifying because regional independents compete on equipment depreciation cycles. Mid-market solar developers exhibit highest price sensitivity; integrated utilities with FERC-mandated cycles show lowest.
Supply Chain Analysis
Freight costs for solid-state LiDAR units from Japanese and German component manufacturers expose margins to yen and euro exchange volatility. Manufacturing concentrates in Japan, Germany, and China for thermal imagers, multispectral sensors, and lithium-polymer battery packs. Raw material dependencies span rare-earth magnet supply for brushless motors, gallium arsenide for thermal detector arrays, and cobalt-nickel cathode formulations. Single-source vulnerability in solid-state laser emitter supply creates procurement risk. Distribution runs through direct OEM relationships with service providers and specialized drone equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Drone-based consulting services occupy a technology-transition phase as autonomous edge-computing systems displace analyst-in-the-loop interpretation workflows. Real-time defect classification during flight is compressing review cycles and reshaping value capture toward predictive intelligence delivery.
For Market Incumbents: Lock in multi-year service agreements with ERCOT and CAISO grid operators before FAA BVLOS waiver expansion saturates transmission corridor markets. Invest in detect-and-avoid hardware certification for EASA U-space readiness to defend against European regulatory-native specialists. Prioritize proprietary AI model development for thermal anomaly classification to differentiate from software-only entrants.
For New Entrants and Emerging Players: FAA Part 107 waiver expansion in the United States opens a window for specialized confined-space inspection providers in offshore oil and gas platforms. Target North Sea and Gulf of Mexico facilities where helicopter alternatives face weather downtime constraints. Pursue white-space in CSRD-aligned thermal documentation for German commercial building portfolios. Lead with audit-grade data packages that satisfy emissions disclosure mandates.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by utility-scale infrastructure operators seeking captive aerial monitoring capabilities. Long-term viability favors vertically integrated flight-analytics hybrids with recurring revenue depth over project-based mapping providers. Watch for the first fully automated BVLOS framework from FAA, EASA, or CAAC as inflection signal for talent migration and investment concentration.
| Strategic Initiative | Industry Significance |
|---|---|
| Detect-and-Avoid Hardware Certification | EASA U-space mandates create regulatory moats against non-compliant entrants in European urban airspace. |
| Proprietary AI Model Development | Real-time thermal anomaly classification compresses analyst review cycles for Duke Energy network deployments. |
| Multi-Year Service Agreement Consolidation | ERCOT and CAISO grid operators institutionalize recurring contracts with dedicated flight crews. |
| Offshore Platform Specialization | North Sea confined-space requirements face weather constraints favoring drone alternatives over helicopters. |
| CSRD-Aligned Data Packaging | German emissions disclosure mandates institutionalize audit-grade thermal documentation procurement. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with utility planning officers, drone service provider operations leads, FAA certification consultants, and thermal sensor procurement managers combined with secondary validation. FAA Part 107 waiver databases, EASA U-space implementation documents, FERC transmission inspection mandates, and utility RFP records supplied quantitative anchors. Bottom-up contract value aggregation and top-down market sizing triangulated volume estimates.
Data-stream reconciliation across pilot certification timelines, sensor shipment volumes, and utility procurement databases shaped the analytical framework. Segmentation dimensions span service type, technology payload, end-user vertical, and application function across the projection horizon. CAGRs derived from contract value growth rates and equipment deployment trajectories. Forecast inputs include BVLOS waiver approval velocity and solid-state LiDAR cost curves.
The model assumes a particular technology adoption path; alternative pathways for fully autonomous BVLOS operations would alter the outlook. Forecasts reflect assumptions about regulatory timeline acceleration and sensor miniaturization rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Drone Flight Controller System Market
UAV
Firefighting Drone Market
UAV
Anti-Drone Market
UAV
North America Tactical UAV Market
UAV
Global Drone Software Market
UAV
Stratospheric Flying Drone Market
UAV
Drone-As-A-Service Market
UAV
Drone Camera Market
UAV
North America Drones Market
UAV
Global Drone Inspection and Monitoring Market
UAV
Small UAV Market
UAV
Delivery Drones Market
UAV
Auto-Follow Drone Market
UAV
Drone Roof Inspection Market
UAV
Short-Range Delivery Drone Market
UAV
Global Stratospheric UAV Payload Technology Market