
 Consumer Drone Market | 2026-2036
Consumer Drone Market Size, Share, and Industry Trends Forecast 2026-2036
Consumer Drone Market Analysis
Carbon fiber is expanding its share in consumer drone airframes as manufacturers trade aluminum weight penalties for improved flight endurance and payload capacity. DJI leverages integrated gimbal manufacturing to sustain margin capture across the camera drone tier. Autel Robotics anchors its competitive stance through North American channel control and firmware differentiation. Holy Stone competes aggressively in the toy drone segment through Shenzhen-based production scale and direct-to-consumer pricing.
A consumer drone is an unmanned aerial vehicle weighing under 25 kilograms, typically incorporating brushless motors, lithium-polymer power systems, and multi-rotor configurations for stabilized flight. These devices serve commercial and recreational purposes spanning aerial photography, real estate documentation, agricultural scouting, and pilot training. Camera drones occupy the dominant margin pool as filmmakers and content creators prioritize sensor resolution and gimbal precision over raw flight performance. Racing drones represent the fastest-growing technology tier as First-Person View systems attract younger hobbyists and organized competitive leagues expand. Toy drones function as a mature volume segment where price compression limits profitability but sustains brand awareness for upsell pathways.
The FAA enforces Remote ID compliance and Part 107 certification pathways that shape product design and operator eligibility across the United States. EASA's CE marking requirements under the EU Drone Regulation establish harmonized safety categories that filter non-compliant imports from European retail channels. China's CAAC coordinates with MIIT on frequency allocation and manufacturing quality standards that govern domestic production and export eligibility. Stakeholders must monitor regulatory divergence between transatlantic frameworks as divergence in pilot licensing and airspace classification threatens to fragment product development roadmaps and certification investments.
Market Dynamics
FAA Remote ID mandates and EASA CE marking requirements are compressing demand toward compliant manufacturers while Shenzhen-based supply chains dominate component sourcing and finished-goods assembly.
Growth Catalysts
- Aerial cinematography:Filmmakers now represent the fastest-expanding end-user segment as independent and commercial production standardizes drone-based footage capture.
- First-Person View systems:Racing drones attract younger hobbyists and organized competitive leagues expand across North America and Europe.
- FAA Part 107 certification pathways:Commercial operator eligibility expansion creates structured demand for camera drones in real estate documentation and agricultural scouting.
Market Restraints
- Lithium-polymer battery supply concentration:Shenzhen-based cell manufacturers control pricing volatility for power systems across all weight classes.
- Brushless motor import dependency:Precision motor fabrication concentrates in Guangdong province, exposing non-Chinese assemblers to tariff friction.
- Aluminum airframe displacement cost:Carbon fiber conversion requires retooling that compresses margins for mid-tier manufacturers.
Strategic Opportunities
- Pilot training infrastructure:Unpenetrated flight schools in India and Brazil present channel development potential for simulator-integrated hardware bundles.
- EU Drone Regulation harmonization:CE marking alignment across member states filters non-compliant imports and rewards early certifiers with retail shelf access.
- Sensor-gimbal convergence:Integrated stabilization modules enable entry-tier camera drones to capture footage previously requiring professional-grade equipment.
Industry Challenges
- Frequency allocation coordination:China's MIIT and the FCC maintain divergent spectrum assignments that fragment radio module design and certification timelines.
- Remote ID firmware integration:Real-time location broadcasting requirements compress development cycles and strain engineering resources at smaller manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Consumer Drone Market |
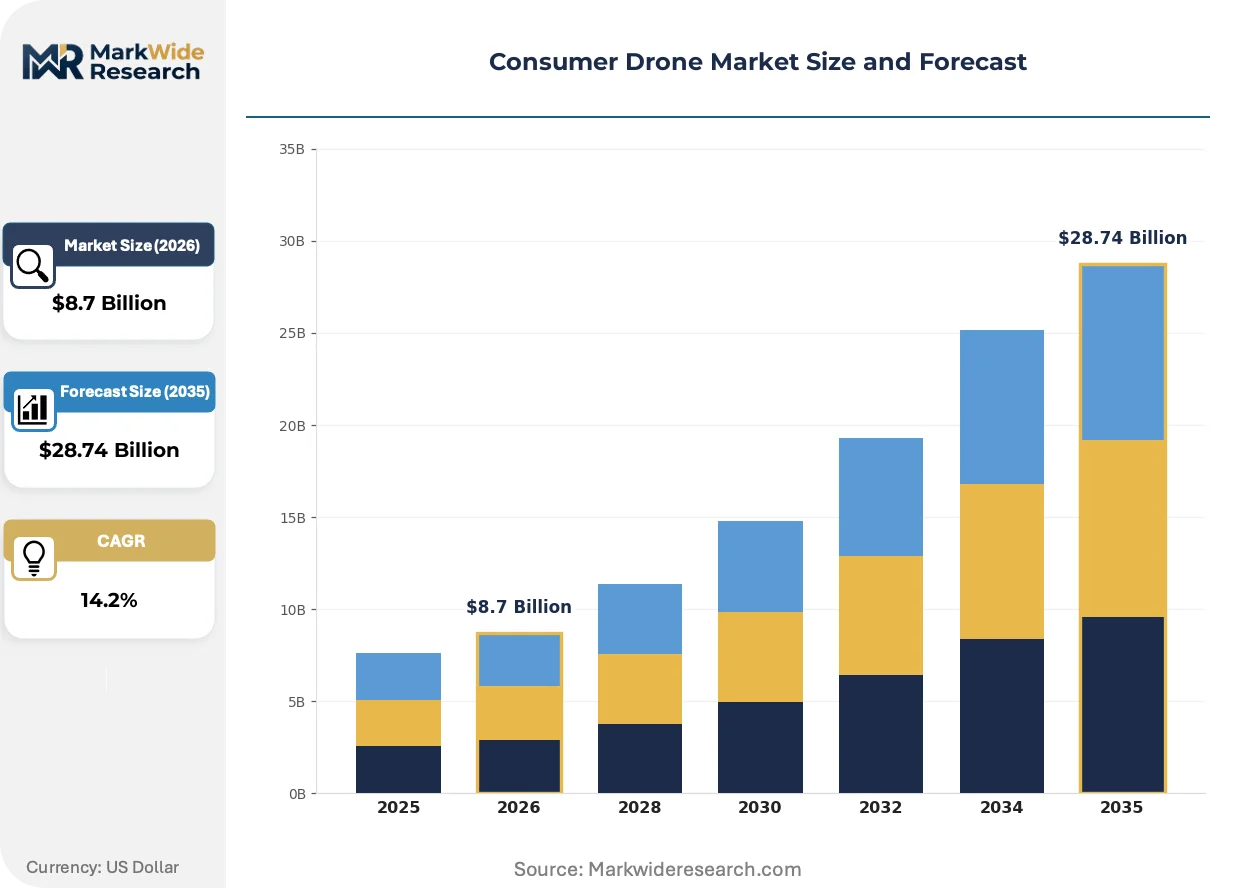
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Camera Drones, Racing Drones, Toy Drones, Photography Drones End User: Hobbyists, Filmmakers, Surveyors, Emergency Services Technology: GPS, First-Person View, Automated Flight, Obstacle Avoidance Distribution Channel: Online Retailers, Electronics Stores, Specialty Shops, Direct Sales |
| Companies Covered | DJI, Autel Robotics, Parrot SA, Skydio, Yuneec International, Holy Stone, Potensic, FIMI, Eachine, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Consumer Drone Market Emerging Trajectories
Active unification of hardware and software layers is compressing development cycles while regulatory frameworks in major markets force product architecture decisions.
Computer vision-based obstacle avoidance is unifying flight safety systems across consumer price tiers. Content creators and recreational pilots now expect autonomous navigation as standard equipment rather than premium add-ons. This capability compression is unifying mid-tier and entry-tier feature sets, eroding traditional price stratification.
EASA's EU Drone Regulation establishes harmonized safety categories that filter non-compliant imports from European retail channels. Manufacturers must redesign airframes and firmware to satisfy CE marking requirements under three operational risk classes. Camera drone tiers face the steepest compliance burden as their higher kinetic energy triggers stricter certification pathways.
Direct-to-consumer channel expansion is displacing traditional electronics retail for toy and racing drone categories. Shenzhen-based manufacturers now bypass distributors entirely, capturing margin through owned e-commerce storefronts and social commerce integration. This pattern concentrates in North American and European markets where logistics infrastructure supports last-mile delivery of sub-250-gram packages.
Consumer Drone Market Segmentation
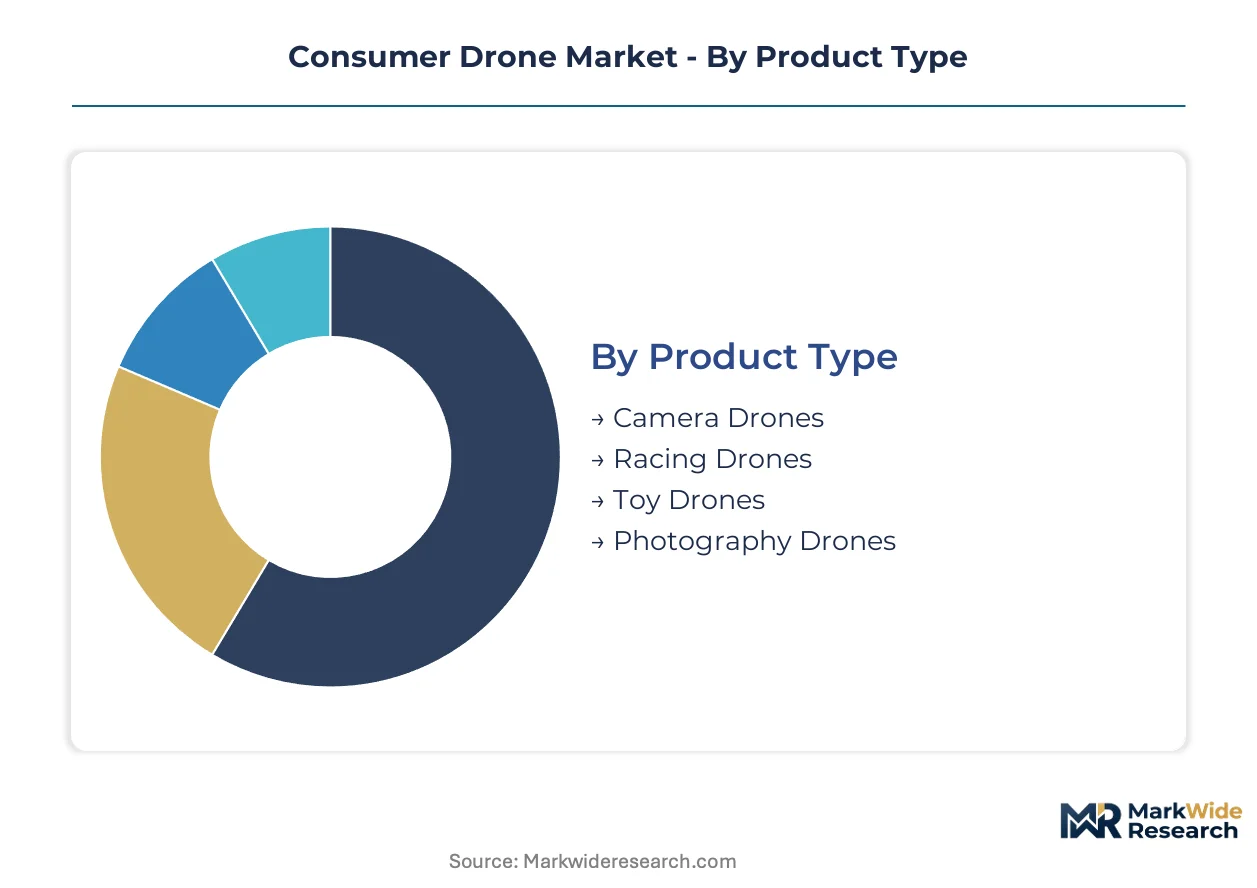
Segmentation in the consumer drone market determines compliance pathways, margin architecture, and channel strategy. Product type dictates certification burden under FAA Remote ID and EASA CE frameworks. End-user concentration shapes firmware differentiation and gimbal specification priorities.
Product Type:
Certification burden escalates with kinetic energy and sensor capability. Camera drones and photography drones trigger stricter EASA operational risk classifications than toy drones. Racing drones occupy a regulatory middle ground where FPV transmission power draws FCC scrutiny.
- Camera Drones:Integrated gimbal-stabilization systems carry sensors exceeding 20 megapixels. Filmmakers in Los Angeles and London concentrate demand here, prioritizing 10-bit color depth and log profiles over raw flight speed. FAA Part 107 commercial certification requirements filter amateur operators from revenue-generating deployment.
- Racing Drones:First-Person View transmission systems dominate the specification sheet. Younger hobbyists across Austin and Manchester drive fastest expansion through organized competitive leagues. Frame durability and repairability outweigh camera quality in purchase decisions.
- Toy Drones:Sub-250-gram designs exploit regulatory thresholds in most jurisdictions. Shenzhen manufacturers control pricing through direct-to-consumer channels.
- Photography Drones:One-inch and larger sensor formats target enthusiast content creators. EASA C2 class compliance adds firmware complexity absent from toy-tier products.
Leading the category by volume: Toy Drones. Growing fastest: Racing Drones.
End User:
Customer type determines pricing tolerance, feature prioritization, and support expectations. Commercial operators accept premium hardware costs for liability protection and warranty coverage. Recreational users sacrifice service infrastructure for upfront savings.
- Filmmakers:Aerial cinematography now standardizes across independent and commercial production workflows. Gimbal precision and codec flexibility command priority over flight time specifications. EASA's harmonized safety categories create certification bottlenecks for non-compliant imports.
- Hobbyists:Recreational pilots span FPV racing, photography, and casual flight. FAA recreational flyer rules limit altitude and airspace access without Part 107 certification.
- Surveyors:Photogrammetry and mapping applications demand RTK-GPS accuracy. Agricultural scouting in Brazil's Mato Grosso and Australia's Queensland drives regional concentration.
- Emergency Services:Search-and-rescue and firefighting deployments require thermal imaging integration. Procurement cycles extend 18-24 months through municipal budget approvals.
Volume leader: Hobbyists. Steepest expansion trajectory: Filmmakers.
Technology:
Technical capability stacks now compress across price tiers as Shenzhen supply chains democratize component access. GPS and obstacle avoidance migrate from premium to standard equipment within single product generations.
- GPS:Multi-constellation receivers integrating GLONASS and BeiDou enable precision hovering and return-to-home functions. Surveyors in India and emergency services in Germany concentrate demand for centimeter-grade accuracy modules.
- Obstacle Avoidance:Computer vision systems using stereo cameras and time-of-flight sensors now equip mid-tier camera drones. Content creators expect autonomous navigation as baseline capability rather than premium add-on.
- First-Person View:Low-latency video transmission systems enable immersive piloting for racing applications. FCC and MIIT maintain divergent spectrum assignments that fragment radio module design.
- Automated Flight:Waypoint programming and subject-tracking algorithms reduce operator skill requirements. Real estate documentation in Florida and Texas absorbs volume through simplified mission planning.
Widest deployment: GPS. Fastest capability compression: Obstacle Avoidance.
Distribution Channel:
Channel selection reflects product complexity, customer support needs, and margin capture strategy. Direct sales bypass distributor markups but absorb logistics and returns costs. Physical retail sustains brand visibility for entry-tier purchases.
- Online Retailers:Amazon and Alibaba aggregate search traffic for toy and racing drone categories. Shenzhen manufacturers bypass intermediaries entirely through owned storefronts and social commerce integration.
- Direct Sales:DJI and Autel Robotics capture margin through proprietary e-commerce platforms. Firmware updates and accessory bundling deepen customer lifetime value.
- Electronics Stores:Best Buy and comparable chains provide hands-on evaluation for first-time buyers. Staff training limitations restrict technical consultation depth.
- Specialty Shops:Hobby retailers and drone-specific outlets service FPV racing communities. Component-level repair and customization support attracts enthusiast loyalty.
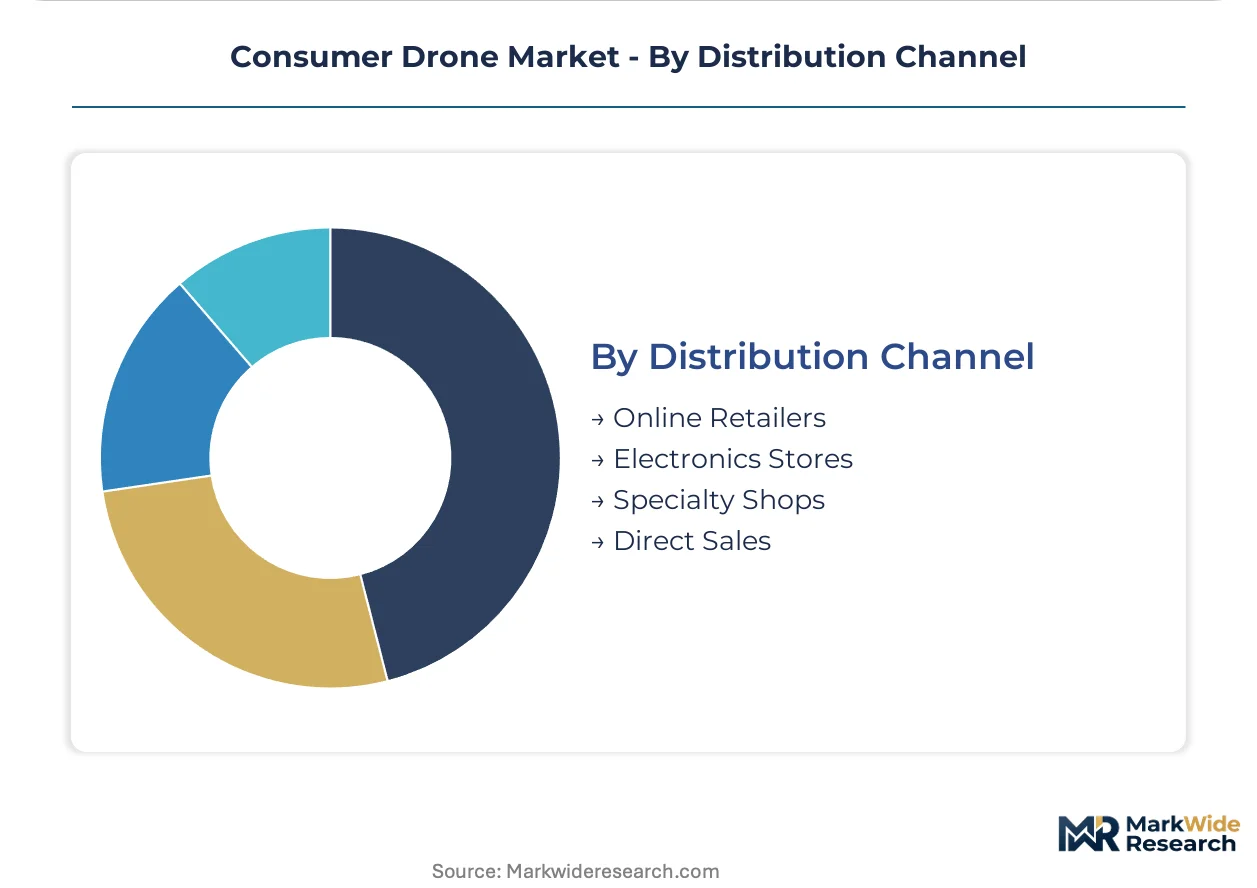
Volume concentration: Online Retailers. Margin protection: Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen's Qianhai Free Trade Zone concentrates component sourcing and finished-goods assembly for the consumer drone industry. Tax incentives and streamlined customs procedures attract manufacturers seeking integrated supply chains. This zone anchors global production capacity for brushless motors, lithium-polymer cells, and carbon fiber airframes.
United States
Commercial operators in Los Angeles and Austin drive demand for camera drones certified under FAA Part 107 pathways. The FAA's Remote ID mandate compresses procurement toward compliant manufacturers with integrated firmware solutions. Texas and California host the densest concentrations of aerial cinematography studios and FPV racing leagues.
China
Guangdong province dominates precision motor fabrication and gimbal assembly for export markets. MIIT coordinates frequency allocation with CAAC on manufacturing quality standards that govern domestic production eligibility. Shenzhen-based supply chains control pricing volatility for power systems across all drone weight classes.
Germany
Surveyors in Bavaria and emergency services in North Rhine-Westphalia concentrate demand for RTK-GPS accuracy modules. EASA's CE marking requirements under the EU Drone Regulation establish harmonized safety categories that filter non-compliant imports. Berlin anchors firmware development clusters serving European certification pathways.
Japan
Content creators in Tokyo and Osaka prioritize sensor resolution and gimbal precision for commercial production workflows. METI oversees JIS standards alignment with international frequency protocols. Nagoya's industrial corridor hosts precision machining facilities for carbon fiber airframe components.
United Kingdom
Independent filmmakers in London and Manchester standardize drone-based footage capture across commercial production. The Civil Aviation Authority enforces operational risk classifications that parallel EASA frameworks. Scotland's Highlands attract agricultural scouting deployments requiring extended flight endurance specifications.
Consumer Drone Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated gimbal producers capturing margin pools in camera drones while Shenzhen-based assemblers dominate toy-tier volume. The market structures around three tiers: premium sensor-gimbal integrators, mid-tier firmware differentiators, and scale-driven direct-to-consumer manufacturers. Competitive moves concentrate on backward integration into component supply and proprietary e-commerce platform development.
Within the premium sensor-gimbal tier, DJI exemplifies integrated manufacturing architecture. Autel Robotics occupies a position emphasizing North American channel control. Shenzhen-based Holy Stone represents scale-driven direct-to-consumer positioning through owned e-commerce storefronts.
| Leading Market Players |
|---|
| DJI |
| Autel Robotics |
| Parrot SA |
| Skydio |
| Yuneec International |
| Holy Stone |
| Potensic |
| FIMI |
| Eachine |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap assemblers in Guangdong province anchor toy-tier production, constraining pricing discipline through Shenzhen-based direct-to-consumer channels while carbon fiber conversion costs compress margins for mid-tier camera drone manufacturers seeking airframe differentiation.
Pricing Analysis
Short lead-time premiums command pricing power for racing drone components serving Austin and Manchester FPV leagues, while spot inventory of lithium-polymer cells from Shenzhen trades at discounts. Three-tier pricing structure across premium, standard, and economy levels separates DJI's integrated gimbal systems from Autel's firmware-differentiated mid-tier and Holy Stone's direct-to-consumer economy tier. Cost compression in the toy segment is intensifying because Shenzhen manufacturers bypass distributor markups entirely. Hobbyists exhibit highest price sensitivity; filmmakers purchasing for Part 107 commercial certification show lowest.
Supply Chain Analysis
Lithium-polymer cell supply rests on Shenzhen-based manufacturers, brushless motor fabrication concentrates in Guangdong province, and carbon fiber airframe machining clusters in Japan's Nagoya corridor. Raw material dependencies span rare-earth magnets for motor assemblies, high-discharge battery chemistry, and aerospace-grade composite prepregs. Single-source vulnerability in Guangdong motor production exposes non-Chinese assemblers to tariff friction. Distribution runs through Amazon and Alibaba aggregation for toy and racing tiers, with DJI and Autel capturing margin through proprietary direct sales platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The consumer drone market sits in a technology-transition phase where computer vision-based obstacle avoidance displaces legacy GPS-only navigation systems, compressing feature differentiation timelines across price tiers.
For Market Incumbents: Acquire specialist computer vision firms to deepen autonomous navigation capabilities before feature parity erodes camera drone premiums. DJI should reinforce North American channel control against Autel's firmware differentiation while accelerating carbon fiber airframe backward integration to offset Guangdong supply risk. Certification investment for EASA C2 compliance creates defendable positioning as CE marking filters non-compliant imports.
For New Entrants and Emerging Players: The mid-tier price-point gap between DJI's premium sensor-gimbal systems and Holy Stone's economy toy drones offers white-space entry for firmware-differentiated camera drones targeting independent filmmakers. Pilot training infrastructure in India and Brazil presents channel development potential for simulator-integrated hardware bundles. Go-to-market should leverage specialty hobby retailers for FPV racing community penetration before scaling through owned e-commerce.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier firmware specialists with EASA pre-certification in Germany's Berlin development corridor. Long-term viability hinges on regulatory compliance architecture rather than raw flight performance specifications. Watch FAA Remote ID enforcement consistency as inflection indicator for compliance-technology acquisition premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Gimbal Manufacturing | DJI sustains margin capture across camera drone tiers through captive stabilization module production. |
| EASA CE Marking Pre-Certification | Early certifiers secure retail shelf access as harmonized safety categories filter non-compliant imports. |
| Direct-to-Consumer Platform Expansion | Shenzhen manufacturers bypass distributor markups through owned storefronts and social commerce integration. |
| Sensor-Gimbal Convergence R&D | Integrated stabilization modules enable entry-tier camera drones to capture professional-grade footage. |
| Pilot Training Infrastructure Partnership | Simulator-integrated hardware bundles penetrate unpenetrated flight schools in India and Brazil. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combined with primary interviews across drone manufacturer executives, FAA Part 107 certification instructors, EASA regulatory affairs leads, and specialty hobby retailer buyers. Secondary sources spanned FAA Remote ID implementation databases, EASA CE marking registries, Shenzhen customs export classifications, and lithium-polymer cell trade flow records. Bottom-up segment sizing triangulated against top-down market reconstruction.
Granularity-level modeling deployed product-type segmentation at the SKU level for camera, racing, toy, and photography drones, with end-user splits across filmmakers, hobbyists, surveyors, and emergency services. Technology capability stacks were modeled for GPS, obstacle avoidance, FPV, and automated flight systems. Distribution channel dynamics captured online retailer, direct sales, electronics store, and specialty shop pathways. CAGRs derived from regression analysis against historical shipment data and regulatory implementation timelines. Forecast inputs incorporated EASA operational risk class adoption curves and FAA commercial certification growth patterns.
Underlying measurement precision varies by segment; toy drone volume through Shenzhen direct channels carries tighter precision than emergency services procurement through municipal budget cycles. Forecasts reflect documented assumptions on regulatory enforcement consistency and supply chain tariff exposure. A small set of triggers warrants ongoing watch: FAA Remote ID firmware integration delays, EASA CE marking harmonization divergence, and Guangdong brushless motor supply disruptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Drone Camera Market
UAV
Tethered Drones Market
UAV
Commercial UAV Market
UAV
UAV Battery Market
UAV
Passenger Drones Market
UAV
Drone Telematics Market
UAV
UAV GNSS Antenna Market
UAV
Autonomous Aircraft Cameras Market
UAV
Drone Identification System Market
UAV
Military Unmanned Aerial Vehicles Market
UAV
Asia-Pacific Drone Light Shows Market
UAV
UAV Navigation Systems Market
UAV
Counter-UAS Market
UAV
Unmanned Aerial Vehicle Fuel Cell Market
UAV
Drone-Based Consulting Services Market
UAV
Autonomous Underwater Gliders (AUG) Market