
 North America Drones Market | 2026-2036
North America Drones Market Size, Share, and Industry Trends Forecast 2026-2036
North America Drones Market Analytics
Energy infrastructure inspection is hardening as the dominant commercial vertical across North America, displacing earlier recreational dominance. Skydio leverages autonomous obstacle-avoidance algorithms to anchor utility-sector contracts in dense transmission corridors. Boeing sustains defense-grade platform development for government ISR programs. Parrot competes through specialized multispectral sensor packages calibrated for agricultural stress-mapping.
North America drones encompass unmanned aerial vehicles spanning fixed-wing, multi-rotor, hybrid, and nano form factors, typically incorporating lithium-polymer power systems, GPS-INS navigation, and payload capacities from sub-500 grams to above 25 kilograms for industrial telemetry, reconnaissance, and cargo transport. Fixed-wing platforms dominate long-range pipeline and border surveillance missions where endurance exceeds four hours, while multi-rotor systems capture the fastest expansion in construction site photogrammetry due to vertical takeoff flexibility in confined airspace. AI-driven navigation technology concentrates margin pools through predictive maintenance integrations and swarm-coordination software licensing.
FAA Remote ID rules and Part 107 recurrent training requirements shape operator density and equipment refresh cycles across the United States, while Transport Canada BVLOS waiver frameworks govern cross-border commercial expansion into Canadian resource territories. The FAA Reauthorization Act provisions for UTM infrastructure deployment and counter-UAS authority allocation will determine which stakeholders secure beyond-visual-line-of-sight operational certificates. Procurement and compliance teams must monitor pending FAA detect-and-avoid rulemakings that will redefine platform certification thresholds.
Market Dynamics
FAA Remote ID mandates and Part 107 certification expansion are compressing operator authorization timelines while forcing equipment refresh cycles across commercial fleets. This regulatory pressure is concentrating operational capability among certified providers who can absorb compliance costs.
Growth Catalysts
- Precision agriculture protocols:Multispectral stress-mapping adoption is hardening across Midwest and Great Plains farm belts. Growers deploy variable-rate input programs calibrated to drone-collected canopy data.
- FAA Part 107 recurrent training:Expanded certification pathways are accelerating commercial operator density in Texas and California energy corridors. Utility inspectors now constitute the fastest-expanding licensee category.
- Last-mile logistics trials:Retail and pharmaceutical distributors are piloting autonomous cargo platforms in Florida urban air mobility zones. These trials validate beyond-visual-line-of-sight operational frameworks.
Market Restraints
- Lithium-polymer supply concentration:Battery cell sourcing depends on Asian cathode material suppliers. Price volatility in cobalt and lithium carbonate inputs compresses hardware margins.
- Detect-and-avoid technical limitations:Onboard sense-and-avoid systems face certification thresholds that delay BVLOS authorization. Current radar and optical fusion packages fail in degraded visual environments.
- FAA waiver processing friction:Operational certificate timelines for night flights and operations over people extend 90-180 days. This regulatory lag constrains service scalability for emergency response applications.
Strategic Opportunities
- Canadian resource territory expansion:Transport Canada BVLOS waiver frameworks enable cross-border pipeline inspection into Alberta oil sands and British Columbia mining districts. Operators with dual certification capture integrated North American contracts.
- UTM infrastructure deployment:FAA Reauthorization Act provisions for unmanned traffic management systems create first-mover advantage for platform-agnostic service providers. Early UTM integrators will anchor corridor access rights.
- AI-navigation and predictive maintenance convergence:Swarm-coordination software licensing is unifying flight control with asset health monitoring. This technology stack enables subscription revenue models displacing hardware-only sales.
Industry Challenges
- Certified pilot skill scarcity:Remote ID compliance and recurrent training requirements outpace FAA-designated examiner capacity. Operator backlogs extend hiring timelines for commercial service fleets.
- Legacy system integration complexity:Enterprise asset management platforms lack native API architecture for drone telemetry ingestion. Custom middleware development consumes 15-25% of deployment budgets.
- Counter-UAS authority fragmentation:Federal, state, and municipal jurisdiction overlaps create legal uncertainty for detection and mitigation system deployment. Critical infrastructure operators delay procurement pending clarity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Drones Market |
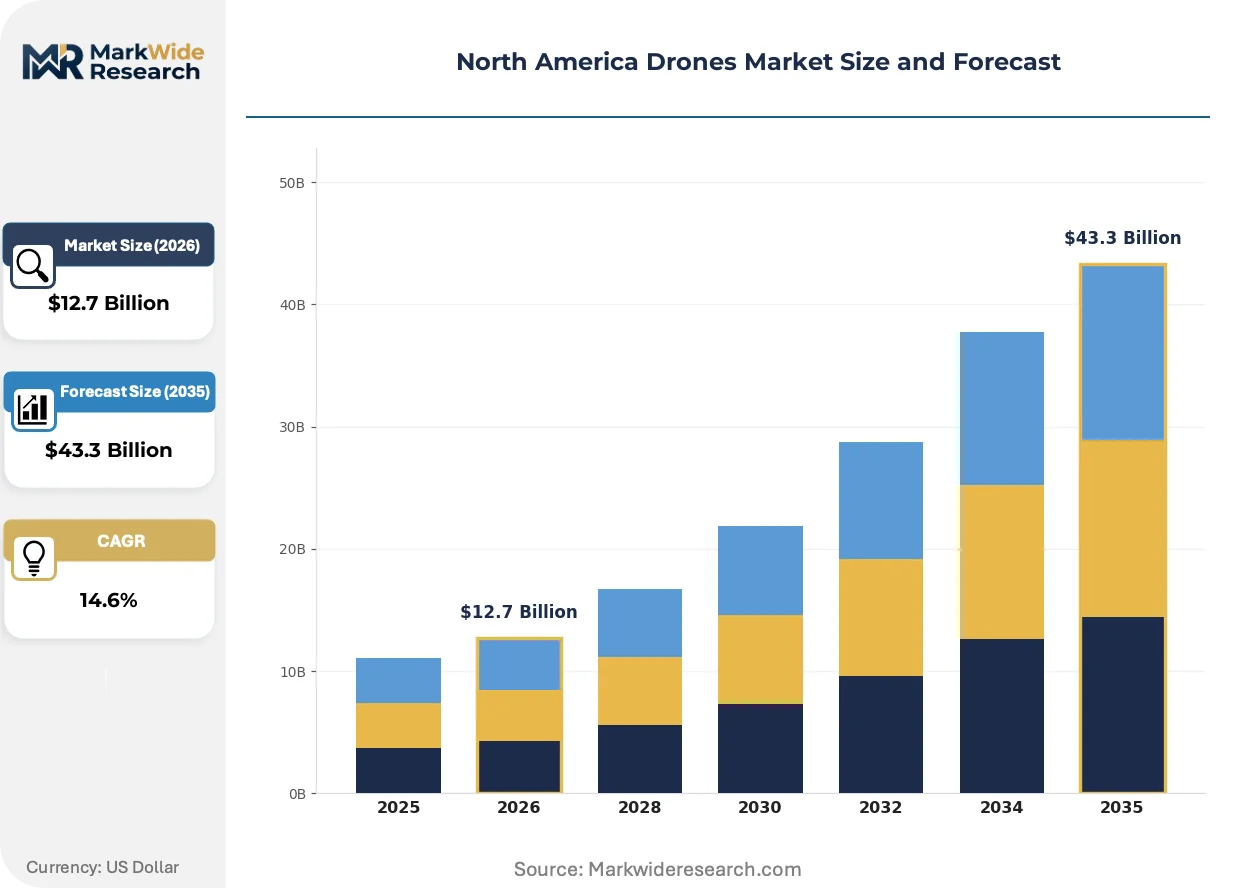
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $43.3 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed-Wing, Multi-Rotor, Hybrid, Nano Application: Agriculture, Surveillance, Delivery, Construction End User: Aerospace, Defense, Commercial, Environmental Technology: Autonomous, Remote-Controlled, AI-Driven, IoT-Enabled |
| Companies Covered | DJI, Boeing, Northrop Grumman, General Dynamics Corporation, Parrot, Draganfly Innovations, Skydio, Autel Robotics, Intel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Drones Market Evolving Landscape
Autonomous navigation architectures and regulatory data infrastructure are converging to compress operational authorization cycles. Platform differentiation is shifting from hardware specifications to software-enabled service integration.
AI-driven flight control systems are unifying predictive obstacle avoidance with real-time mission replanning. Energy utility operators in dense transmission corridors adopt these platforms at the fastest clip. This capability compression is enabling single-pilot oversight of multi-drone inspection swarms, collapsing labor cost structures.
FAA detect-and-avoid rulemakings will redefine platform certification thresholds for beyond-visual-line-of-sight operations. Industrial inspection providers face equipment retrofit mandates or fleet replacement decisions. The Texas-California-Florida corridor clusters are absorbing compliance costs earliest to secure operational certificates.
Service bundling is displacing hardware-centric procurement across enterprise buyer segments. Construction and agriculture end-users now prioritize per-acre or per-mile pricing over capital expenditure ownership. This preference shift is most visible in Midwest farm cooperatives and Permian Basin energy operators.
North America Drones Market Segmentation
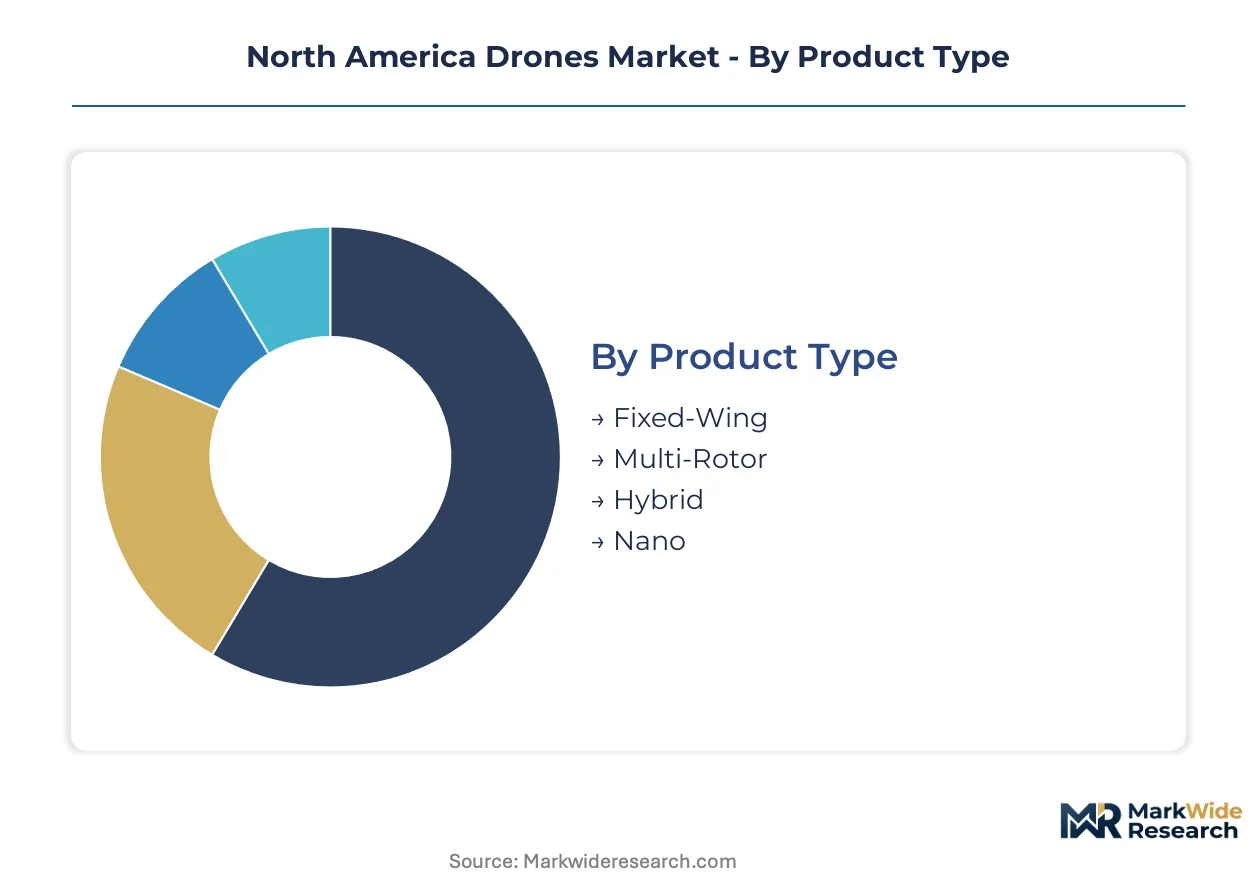
Platform architecture and operational autonomy define competitive positioning across North American commercial fleets. Segmentation reveals where FAA certification requirements and payload specifications concentrate procurement decisions.
Product Type:
Airframe geometry dictates endurance profiles and regulatory compliance pathways across energy corridor deployments.
- Fixed-Wing:Extended endurance platforms exceed four hours on single battery cycles. Pipeline operators across Texas and Alberta oil sands favor these systems for linear infrastructure inspection where landing zones remain sparse.
- Multi-Rotor:Vertical takeoff capability dominates construction site photogrammetry in confined urban airspace. California utility inspectors deploy these platforms for dense transmission corridor work where obstacle density requires hover precision.
- Hybrid:VTOL-fixed-wing fusion architectures optimize range with landing flexibility. Emerging deployments target Canadian mining districts requiring runway-independent operations.
- Nano:Sub-250 gram platforms bypass FAA Remote ID hardware mandates. Recreational and light commercial reconnaissance applications concentrate in Florida urban zones.
Fixed-Wing leads on scale; Multi-Rotor leads on momentum.
Application:
Mission specificity determines sensor payload configurations and software licensing requirements across buyer segments.
- Agriculture:Multispectral stress-mapping protocols calibrate variable-rate input programs. Midwest farm cooperatives in Iowa and Illinois deploy canopy analysis for nitrogen optimization.
- Surveillance:Border security and critical infrastructure monitoring demand encrypted datalinks. Government ISR programs sustain defense-grade platform procurement.
- Delivery:Last-mile pharmaceutical and retail trials validate BVLOS frameworks. Florida urban air mobility corridors host autonomous cargo pilots.
- Construction:Photogrammetry and volumetric survey workflows compress project timelines. Texas Permian Basin operators integrate drone telemetry with enterprise asset management platforms.
Agriculture leads on scale; Delivery leads on momentum.
End User:
Procurement authority and operational risk tolerance segment buyer requirements across certification tiers.
- Aerospace:Airframe manufacturers deploy drones for supply chain inspection and test range monitoring. Internal flight operations teams absorb FAA Part 107 recurrent training costs.
- Defense:Government ISR programs require hardened communication links and counter-UAS integration. Boeing sustains platform development for classified mission profiles.
- Commercial:Energy utilities and logistics providers constitute the fastest-expanding licensee category. Part 107 certification density concentrates in Texas and California corridors.
- Environmental:Conservation agencies and disaster response units prioritize rapid deployment over payload sophistication. Transport Canada BVLOS waivers enable cross-border wildfire monitoring.
Commercial leads on scale; Environmental leads on momentum.
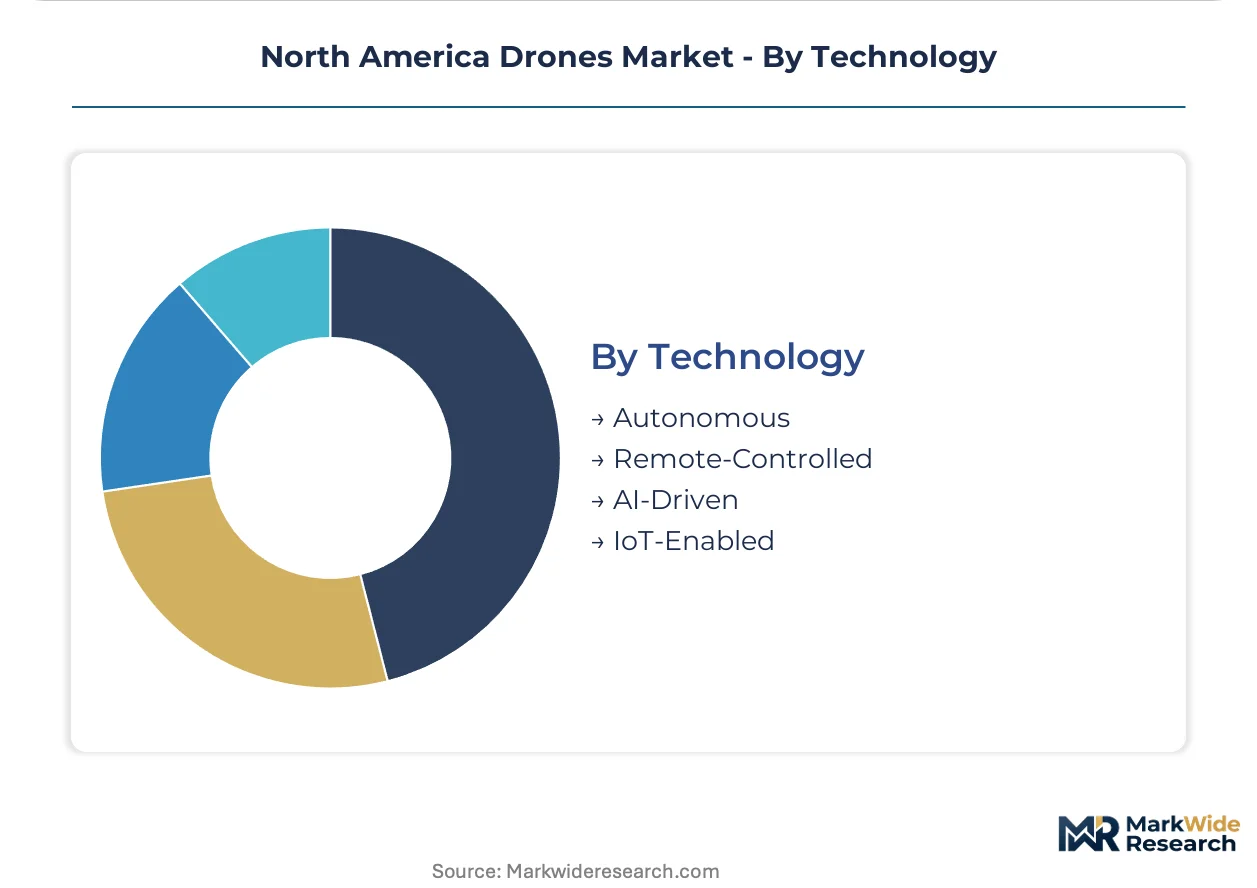
Technology:
Control architecture determines pilot-to-aircraft ratios and subscription revenue potential across service models.
- Autonomous:Pre-programmed waypoint navigation reduces operator workload for repetitive inspection routes. Skydio obstacle-avoidance algorithms anchor utility-sector contracts.
- Remote-Controlled:Manual piloting persists in cinematography and precision agriculture where real-time decision-making outweighs automation efficiency. FAA Part 107 mandates sustain training infrastructure demand.
- AI-Driven:Predictive maintenance integrations and swarm-coordination software unify flight control with asset health monitoring. Single-pilot multi-drone oversight collapses labor cost structures.
- IoT-Enabled:Real-time telemetry ingestion into enterprise platforms requires custom middleware development. Sensor fusion packages feed predictive analytics for infrastructure degradation modeling.
Autonomous leads on scale; AI-Driven leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost-of-compliance gaps between jurisdictions are redirecting operator certification investment and fleet deployment toward corridors with faster waiver processing and clearer beyond-visual-line-of-sight pathways. This arbitrage dynamic concentrates operational capability in sub-regions where FAA and Transport Canada frameworks offer interpretive certainty.
United States
Texas, California, and Florida energy corridors absorb the highest density of Part 107 certified commercial operators. FAA Remote ID mandates and recurrent training requirements compress equipment refresh cycles while accelerating authorization timelines for utility inspectors. The Permian Basin and Gulf Coast transmission networks anchor the dominant cluster for pipeline surveillance missions.
Canada
Alberta oil sands and British Columbia mining districts drive cross-border demand for dual-certified operators with Transport Canada BVLOS waivers. The country's national aviation regulator enables faster operational certificate processing for resource corridor inspection than equivalent US timelines. Calgary and Vancouver serve as certification hubs for integrated North American contract fulfillment.
Mexico
Energy infrastructure monitoring along the Tamaulipas-Veracruz pipeline corridor and agricultural reconnaissance in Sinaloa and Jalisco farm belts concentrate emerging commercial demand. The country's federal civil aviation authority maintains evolving unmanned aircraft regulations that lag US and Canadian standardization. Monterrey and Guadalajara industrial zones host pilot logistics programs for cross-border supply chain visibility.
North America Drones Market Competitive Landscape
Portfolio diversification dominates the current landscape as defense contractors extend platform development into commercial applications while autonomous navigation specialists capture utility-sector contracts. The vendor base organizes around three strategic archetypes: defense-grade system integrators with government ISR relationships, obstacle-avoidance algorithm developers serving energy infrastructure, and sensor package specialists calibrating agricultural payloads. M&A activity and technology licensing partnerships represent the dominant competitive moves as hardware margins compress and software-enabled service models displace equipment sales.
Within the autonomous navigation tier, Skydio exemplifies obstacle-avoidance platform development for dense transmission corridor work. Boeing occupies a position representing defense-grade system integration for classified mission profiles. Parrot sits within the sensor specialization archetype, with multispectral package calibration for agricultural stress-mapping applications.
| Leading Market Players |
|---|
| DJI |
| Boeing |
| Northrop Grumman |
| General Dynamics Corporation |
| Parrot |
| Draganfly Innovations |
| Skydio |
| Autel Robotics |
| Intel Corporation |
| Others |
Value Network & Pricing Analysis
AI-driven navigation technology adoption simultaneously compresses hardware margins and concentrates procurement power among certified fleet operators capable of absorbing compliance costs. FAA Remote ID mandates force equipment refresh cycles that favor subscription-based service models over transactional hardware sales, reshaping how lithium-polymer battery packs and sensor payloads flow through distribution channels.
Pricing Analysis
Distributor margins in commercial drone hardware typically absorb 15-25 percent of end-user pricing, with direct-to-OEM arrangements compressing this layer for volume fleet purchasers. Three-tier pricing structure across premium, standard, and economy levels separates defense-grade platforms with encrypted datalinks from Part 107-compliant commercial units and sub-250 gram recreational units. Pricing pressure stems from Asian battery cell sourcing volatility, with cobalt and lithium carbonate input costs squeezing hardware margins most acutely in the standard tier. Agricultural cooperatives in the Midwest exhibit highest price sensitivity, while defense contractors demonstrate lowest sensitivity due to mission-critical procurement authority.
Supply Chain Analysis
Single-source vulnerability sits with Chinese cathode material suppliers and South Korean battery cell manufacturers, with Japanese sensor component providers adding secondary concentration risk. North American assembly operations draw from these inputs for lithium-polymer power systems, GPS-INS navigation modules, and multispectral imaging arrays. Tariff exposure on Chinese rare earth processing creates supply chain risk for permanent magnet motors in high-performance multi-rotor platforms. Distribution runs through specialized industrial distributors serving energy utilities, direct OEM relationships with defense primes, and online channels for Part 107 training and certification bundles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America drones market functions as a stable compounder, with regulatory infrastructure deepening commercial operator density and recurring certification requirements sustaining replacement demand across the analysis window.
For Market Incumbents: Anticipate margin compression in hardware sales by accelerating software-enabled service bundling for predictive maintenance and swarm-coordination licensing. FAA detect-and-avoid rulemakings threaten fleet obsolescence; defend position by pre-certifying next-generation platforms for BVLOS operations in the Texas-California-Florida corridor. Vertical integration into lithium-polymer pack assembly offers limited relief given cathode material concentration. For New Entrants and Emerging Players: Enter via Canadian resource territory expansion, where Transport Canada BVLOS waiver frameworks enable faster operational certificate processing than FAA timelines. Agricultural stress-mapping in Iowa and Illinois farm cooperatives presents the most penetrable segment, with per-acre pricing models displacing capital expenditure ownership. Target dual-certification service provision for cross-border pipeline operators seeking integrated North American contracts. For Investors and Strategic Acquirers: Valuations sit cheapest among autonomous navigation software specialists with utility-sector revenue visibility and recurring licensing streams. Long-term viability over a 5-10 year horizon rests on UTM infrastructure deployment timing and FAA beyond-visual-line-of-sight authorization velocity. Monitor FAA Reauthorization Act implementation progress as the primary inflection signal for corridor access rights and operational certificate scalability.| Strategic Initiative | Industry Significance |
|---|---|
| UTM Infrastructure Partnership | Early UTM integrators anchor corridor access rights under FAA Reauthorization Act provisions. |
| AI Navigation Platform Licensing | Swarm-coordination software unifies flight control with asset health monitoring for utility contracts. |
| Dual Certification Capability | Transport Canada BVLOS waivers enable integrated North American pipeline inspection contracts. |
| Sensor Package Specialization | Multispectral calibration for agricultural stress-mapping captures Midwest farm cooperative demand. |
| Subscription Service Transition | Per-mile and per-acre pricing models displace hardware-only sales in energy and agriculture segments. |
Research Methodology
Multiple input streams — primary interviews with FAA-designated pilot examiners, utility fleet operations managers, and agricultural cooperative procurement leads; secondary validation through FAA regulatory filings, Transport Canada operational certificate databases, and energy utility capital expenditure disclosures — were reconciled to construct segment-level demand estimates. Bottom-up triangulation across platform shipment data and top-down reconciliation against fleet operator certification density produced volume and value outputs.
Data-stream reconciliation across fixed-wing, multi-rotor, hybrid, and nano platform architectures, combined with segmentation by agriculture, surveillance, delivery, and construction applications, informed growth trajectory modeling over the projection horizon. CAGRs were derived from equipment refresh cycle analysis and Part 107 certification expansion rates. Forecast inputs incorporated lithium-polymer battery cost curves, Remote ID compliance penetration assumptions, and BVLOS waiver processing velocity by jurisdiction.
Inputs from FAA regulatory dockets and Transport Canada operational statistics were available through the study window; gaps in real-time fleet utilization data and proprietary utility contract terms introduce uncertainty bands around service revenue projections. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Drones Market
UAV
Global Smart Commercial Drones Market
UAV
Short-Range Delivery Drone Market
UAV
GCC Drone Pilot Training Market
UAV
UAV Market
UAV
Drone Lens Market
UAV
Autonomous Underwater Gliders (AUG) Market
UAV
North America Small UAV Market
UAV
UAV Battery Market
UAV
Utility Drone Market
UAV
North America Tactical UAV Market
UAV
Drone Tracking Antenna Market
UAV
Europe Commercial Drones Market
UAV
Global Aerial Survey Services Market
UAV
Stratospheric Flying Drone Market
UAV
Latin America Small UAV Market