
 Deoxidant Market | 2026-2036
Deoxidant Market Size, Share, and Industry Trends Forecast 2026-2036
Deoxidant Market Analytics
REACH compliance in Europe is rebalancing the cost-of-entry calculus for non-European suppliers seeking market access. Mitsubishi Gas Chemical Company leverages its integrated gas-chemical platform to sustain leadership in high-purity oxygen scavenger production for electronics-grade applications. BASF SE anchors its position through backward integration into specialty iron powder precursors, while Clariant Ltd. differentiates via controlled-atmosphere packaging solutions tailored to European food safety protocols.
Deoxidants are chemical agents designed to remove or bind dissolved oxygen from enclosed environments, typically formulated as iron powder, ascorbic acid, or enzymatic systems with particle sizes ranging from 50 to 500 microns for optimal surface-area reactivity. Their primary industrial purpose centers on preventing oxidative degradation in packaged foods, sensitive electronic components, and metalworking fluids during storage and transit. Powder formulations command the largest volume share due to blending flexibility across food preservation and industrial materials applications, while liquid deoxidants represent the fastest-expanding category driven by precision dosing requirements in electronics manufacturing and aerospace component protection. The food industry end-user segment generates the deepest margin pools, particularly where multi-use packaged formats align with sustainability mandates from major retail chains.
The European Chemicals Agency (ECHA) enforces REACH registration thresholds that compel reformulation away from certain metal-based scavengers, while the FDA's food-contact notification process in the United States dictates acceptable migration limits for active packaging additives. China's Ministry of Ecology and Environment (MEE) has introduced dual carbon goals that incentivize lower-energy deoxidant production pathways, reshaping supplier qualification criteria for domestic electronics producers. Stakeholders must monitor divergence between regional purity standards and carbon-intensity benchmarks when configuring manufacturing footprints and product portfolios for cross-border deployment.
Market Dynamics
Iron powder purity thresholds under REACH registration are forcing reformulation investments across European supply chains while cold-chain logistics expansion in China pulls volume toward enzymatic and organic scavenger systems.
Growth Catalysts
- Electronics-grade oxygen scavengers:Semiconductor fabrication facilities in Taiwan and South Korea are deploying high-purity iron-based deoxidants for wafer packaging, tightening specifications for particle size distribution below 100 microns.
- REACH compliance deadlines:ECHA registration requirements for metal-based scavengers are accelerating substitution toward ascorbic acid and enzymatic alternatives in food-contact applications across Germany and France.
- Cold-chain infrastructure:Domestic logistics investments in China are expanding deoxidant deployment for temperature-sensitive pharmaceuticals and fresh produce, driving demand for multi-layer active packaging films.
Market Restraints
- Iron ore price volatility:Input cost swings for reduced iron powder precursors compress margins for commodity-grade scavenger manufacturers in India and Brazil.
- Specialty chemical supply concentration:Ascorbic acid production clusters in Shandong province create single-source vulnerability for organic deoxidant formulators.
- Migration limit stringency:FDA food-contact notification rejections for novel iron chelate complexes delay product launches by 18-24 months in United States retail channels.
Strategic Opportunities
- Aerospace component protection:Liquid deoxidant systems for precision-dosed corrosion prevention in aircraft fuel systems and avionics packaging represent an underdeveloped application vertical.
- MEE dual carbon incentives:China's Ministry of Ecology and Environment carbon-intensity benchmarks favor enzymatic scavenger production pathways with lower thermal energy requirements.
- E-commerce direct fulfillment:Single-serve oxygen absorber sachets for meal-kit subscription services are bypassing traditional food packaging distributors in urban United States markets.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in oxygen scavenger kinetics and polymer compatibility commands premium compensation in European and Japanese labor markets.
- Multi-jurisdiction certification timelines:Parallel FDA, EFSA, and NMPA food-contact approvals for active packaging additives extend time-to-revenue by 30-40 months.
- Legacy equipment retrofit costs:Powder-to-liquid formulation transitions require capital-intensive dosing system upgrades at contract packaging facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Deoxidant Market |
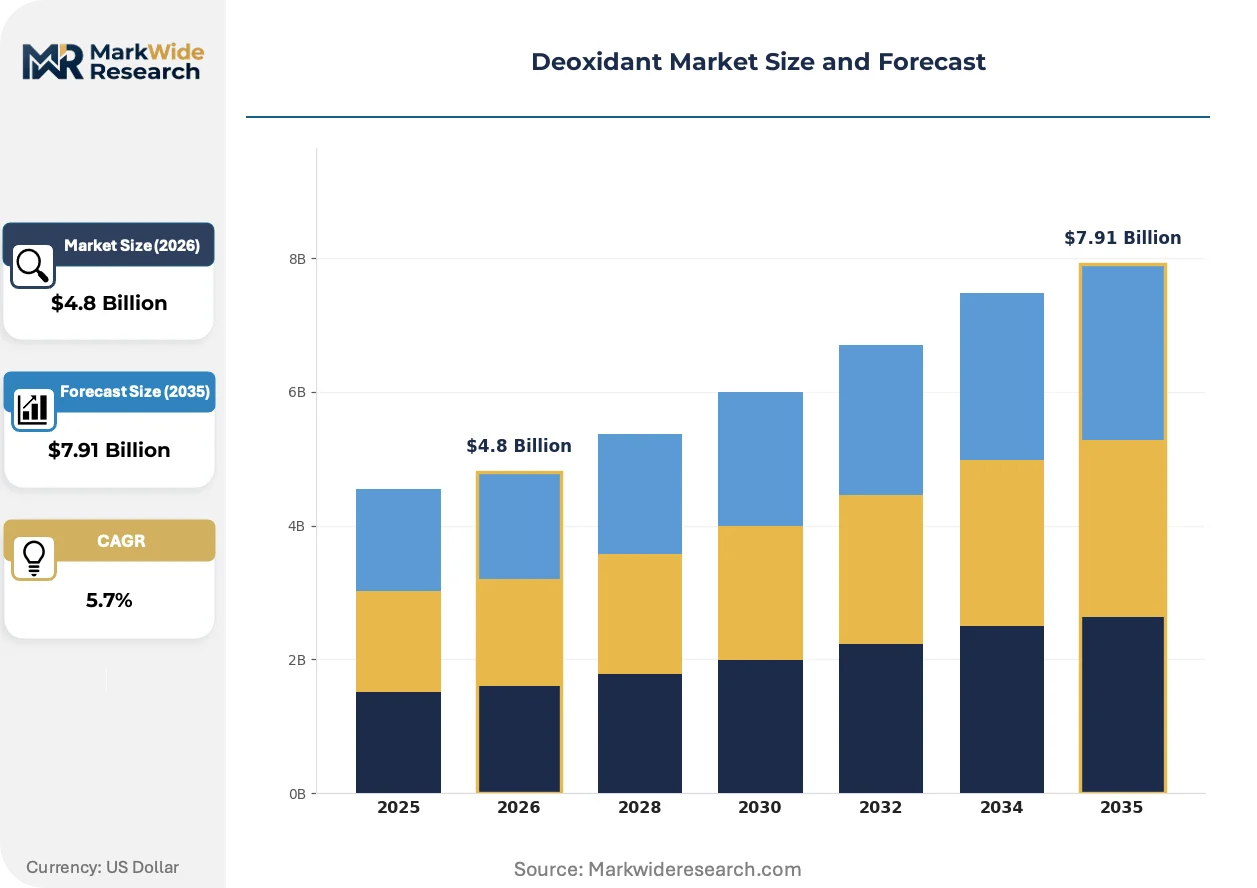
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granules, Tablets, Powder, Liquid Application: Food Preservation, Industrial Materials, Electronics, Aerospace Form: Single-use, Multi-use, Packaged, Bulk End User: Food Industry, Manufacturing Sector, Electronic Producers, Research Labs |
| Companies Covered | Mitsubishi Gas Chemical Company, BASF SE, Ecolab Inc., Clariant Ltd., Kemira OYJ, Arkema Group, Baker Hughes, Sealed Air Corporation, Solenis LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Deoxidant Market Evolving Landscape
Active packaging chemistry is diverging along purity-grade lines, with electronics applications demanding sub-ppm contamination control while food systems prioritize biodegradability and carbon footprint reduction.
Enzymatic glucose oxidase-catalase systems are converging with modified atmosphere packaging films for ready-to-eat protein products. Japanese convenience retail chains are piloting these integrated formats for 14-day shelf life extension. The technology is converging with high-barrier polymer substrates to eliminate separate sachet insertion steps, compressing packaging line capital requirements.
EU F-Gas Regulation phase-down schedules are accelerating hydrofluorocarbon replacement in industrial deoxidant storage and transport systems. Cold-chain operators in Germany and the Netherlands are retrofitting warehouse climate control with CO2-based refrigeration. Pharmaceutical-grade scavenger inventories face temporary supply tightness as logistics providers absorb compliance costs.
Consolidated retail procurement is displacing fragmented distributor networks for oxygen scavenger sourcing. Walmart and Carrefour are mandating direct supplier relationships with deoxidant formulators for private-label active packaging. The shift is most visible in United States and French fresh produce categories, where volume commitments now determine formulation development roadmaps.
Deoxidant Market Segmentation
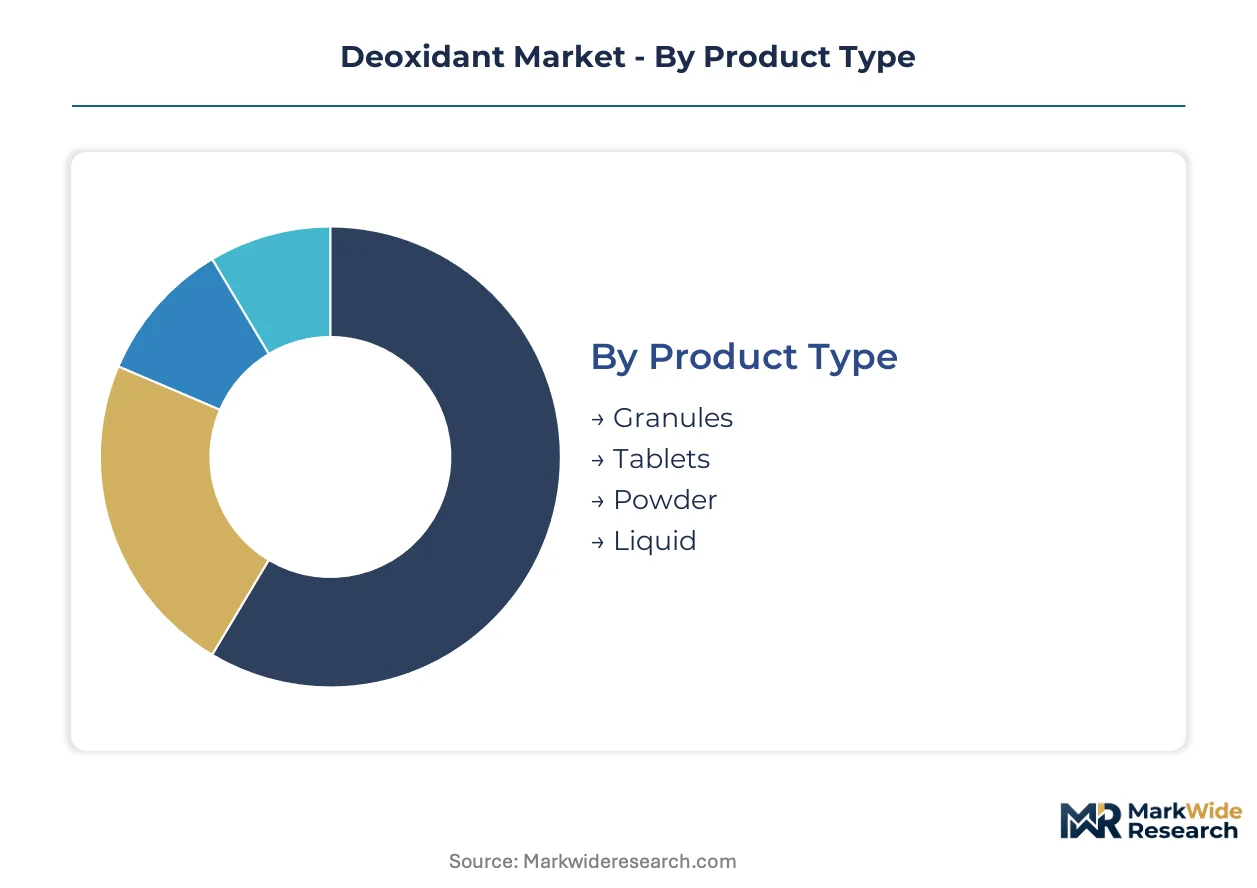
Deoxidant formulation chemistry and delivery format dictate capital deployment patterns across production assets. Segmentation reveals where purity premiums justify specialized equipment investments versus commodity-scale manufacturing.
Product Type:
Granule and tablet production lines demand the heaviest upfront capital for precision compaction and coating systems, while liquid blending requires lower fixed costs but higher ongoing quality control expenditure.
- Granules:Iron-based granules with controlled porosity between 200-400 microns dominate oxygen absorption kinetics for industrial food packaging. Demand concentrates in German meat processing facilities where EFSA migration limits for iron chelates have tightened formulation standards.
- Tablets:Compressed ascorbic acid tablets with disintegration rates under 30 seconds serve pharmaceutical blister packaging. Japanese drug manufacturers are expanding tablet deoxidant procurement for moisture-sensitive biologics storage.
- Powder:Reduced iron powder with 80-150 micron particle distribution offers blending flexibility across sachet and bulk applications.
- Liquid:Precision-dosed enzymatic solutions for electronics manufacturing require cleanroom filling infrastructure.
Powder formulations absorb the bulk of installed capacity; liquid systems are expanding most quickly.
Application:
Electronics and aerospace applications command margin premiums through contamination-grade specifications, while food preservation operates at volume scale with thinner unit economics.
- Food Preservation:Active packaging for ready-to-eat meals and fresh produce employs iron-based sachets and film-integrated scavengers. Walmart's direct supplier mandates for private-label active packaging are reshaping procurement patterns in United States retail channels.
- Industrial Materials:Metalworking fluid stabilization and polymer resin protection utilize bulk powder deoxidants. Brazilian steel processors are expanding scavenger dosing for corrosion prevention in humid coastal storage.
- Electronics:Semiconductor wafer packaging demands sub-ppm iron contamination thresholds. Taiwan fabrication facilities are tightening particle size specifications below 100 microns for high-purity applications.
- Aerospace:Aircraft fuel system corrosion prevention represents an underdeveloped vertical with precision liquid dosing requirements.
Food preservation absorbs the bulk of installed capacity; electronics is climbing the fastest.
Form:
Multi-use and bulk formats reward economies of scale in continuous production, while single-use sachet lines require frequent changeover capabilities and flexible packaging integration.
- Single-use:Individual sachets for meal-kit subscription services bypass traditional distributor networks in urban United States markets. Direct-to-consumer fulfillment models favor compact, pre-measured formats.
- Multi-use:Refillable canister systems for industrial metalworking fluids reduce per-unit packaging waste. German automotive suppliers are piloting returnable deoxidant containers under circular economy mandates.
- Packaged:Pre-sealed pouches for pharmaceutical cold chain integrate with existing packaging line equipment.
- Bulk:Tanker and drum deliveries for large-scale food processing minimize handling labor.
Bulk formats absorb the bulk of installed capacity; single-use is gaining share fastest.
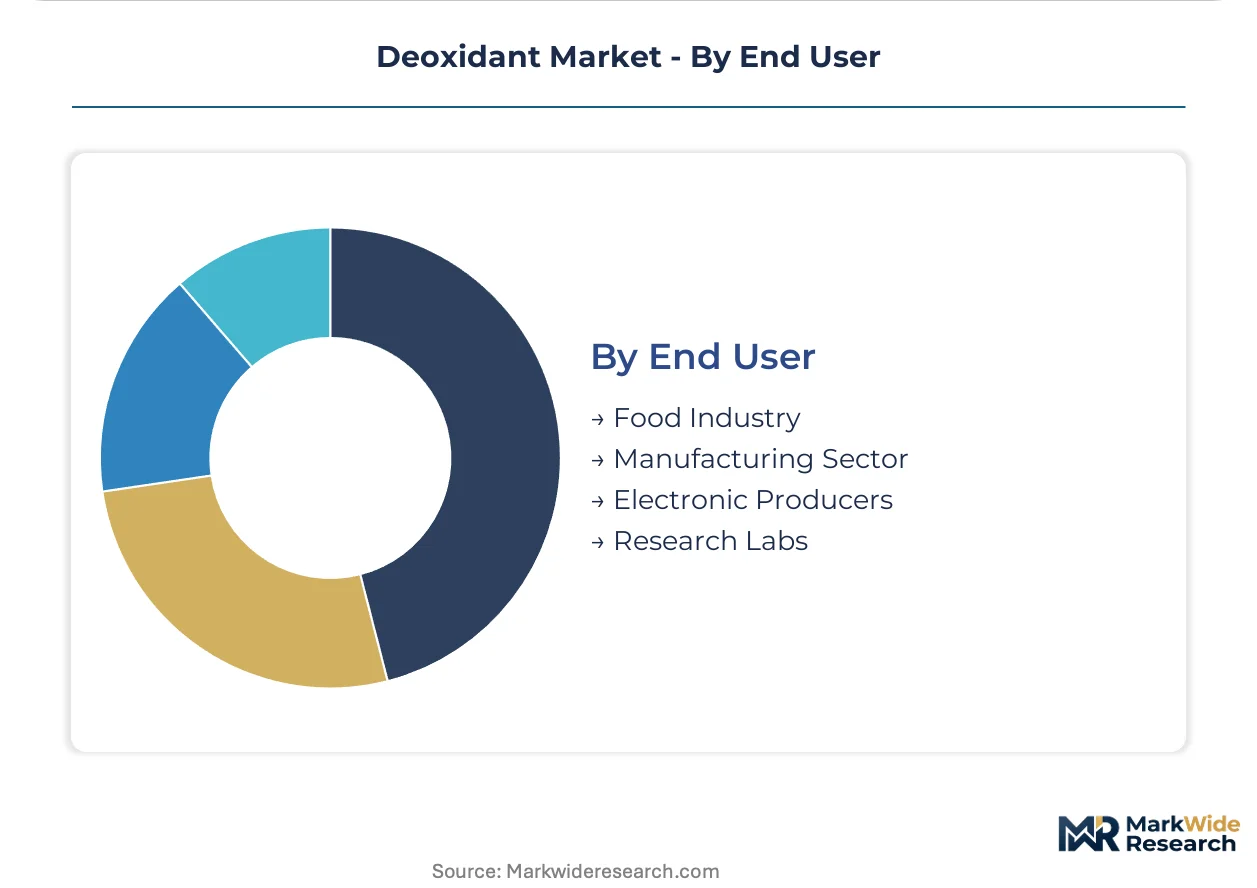
End User:
Electronic producers and research labs impose the most stringent qualification protocols, extending sales cycles but securing multi-year supply agreements with price stability clauses.
- Food Industry:Multi-layer active packaging films for temperature-sensitive pharmaceuticals and fresh produce are expanding with China's cold-chain infrastructure investments. Domestic logistics providers are absorbing EU F-Gas Regulation compliance costs for climate-controlled storage.
- Manufacturing Sector:Metalworking and polymer processing operations utilize commodity-grade iron powder scavengers. Indian steel fabricators face margin compression from iron ore price volatility.
- Electronic Producers:Wafer packaging and component storage require electronics-grade oxygen scavengers with sub-100 micron particle distribution. South Korean semiconductor facilities are tightening supplier qualification criteria.
- Research Labs:Analytical-grade deoxidants for controlled-atmosphere experiments command small-batch premiums.
Food industry absorbs the bulk of installed capacity; electronic producers are on the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China absorbs the largest share of deoxidant consumption, driven by semiconductor fabrication investments and cold-chain logistics expansion. Electronics-grade oxygen scavenger specifications tighten across East Asian fabrication clusters. Regulatory divergence between ECHA REACH thresholds and FDA food-contact rules reshapes supplier qualification requirements.
China
Domestic electronics fabrication and pharmaceutical cold-chain investments accelerate deoxidant deployment across industrial and consumer applications. MEE dual carbon goals incentivize lower-energy enzymatic production pathways for domestic suppliers. Yangtze River Delta fabrication facilities tighten particle size specifications below 100 microns for wafer packaging applications.
United States
Meal-kit subscription services and direct-to-consumer fulfillment models expand single-use oxygen absorber procurement beyond traditional distributor networks. FDA food-contact notification rejections for novel iron chelate complexes delay product launches by 18-24 months in retail channels. Walmart's direct supplier mandates for private-label active packaging reshape procurement patterns in fresh produce categories.
Germany
EFSA migration limits for iron chelates tighten formulation standards in meat processing facilities. EU F-Gas Regulation phase-down schedules accelerate warehouse climate control retrofits with CO2-based refrigeration. Cold-chain operators in the Netherlands absorb compliance costs, creating temporary supply tightness for pharmaceutical-grade scavenger inventories.
Japan
Convenience retail chains pilot enzymatic glucose oxidase-catalase systems integrated with modified atmosphere packaging films for ready-to-eat protein products. METI standards influence regional supplier qualification protocols. Kanto region packaging equipment manufacturers compress line capital requirements by eliminating separate sachet insertion steps.
South Korea
Semiconductor fabrication facilities deploy high-purity iron-based deoxidants for wafer packaging with sub-ppm contamination thresholds. Domestic logistics providers expand temperature-sensitive pharmaceutical protection. Busan-Ulsan industrial clusters tighten supplier qualification criteria for electronics-grade oxygen scavengers.
Deoxidant Market Competitive Landscape
Japanese and German producers anchor one tier; Chinese and American specialists hold differentiated positions in enzymatic and liquid formulation segments. The vendor base concentrates around integrated gas-chemical platforms and specialty iron powder precursor operations. Three archetypes dominate: diversified chemical conglomerates with backward integration into precursors, packaging-focused specialists with film-integration capabilities, and regional formulators serving cold-chain logistics. Capacity expansion and direct retail procurement mandates constitute the dominant competitive moves reshaping distributor relationships.
Among diversified chemical conglomerates, Mitsubishi Gas Chemical Company and BASF SE exemplify integrated platform strategies, while Clariant Ltd. occupies a position within packaging-specialist tier. These three entities represent distinct archetypes: gas-chemical integration, specialty precursor control, and controlled-atmosphere packaging solutions. Their positioning reflects how purity-grade requirements and regulatory compliance capabilities determine competitive boundaries across electronics and food-contact applications.
| Leading Market Players |
|---|
| Mitsubishi Gas Chemical Company |
| BASF SE |
| Ecolab Inc. |
| Clariant Ltd. |
| Kemira OYJ |
| Arkema Group |
| Baker Hughes |
| Sealed Air Corporation |
| Solenis LLC |
| Others |
Value Network & Pricing Analysis
Reduced iron powder spot indices cascade through deoxidant supply chains into three distinct pricing tiers, with electronics-grade specifications commanding substantial premiums over commodity food-packaging grades and cold-chain logistics operators absorbing EU F-Gas compliance costs into landed pricing.
Pricing Analysis
Volume concentrates in commodity iron powder sachets for food preservation where margins compress under Walmart direct-procurement mandates, while electronics-grade scavengers with sub-100 micron particle distribution and sub-ppm contamination thresholds sustain premium pricing. Three-tier pricing structure across premium, standard, and economy levels separates semiconductor wafer packaging specifications from meat-processing migration limits and bulk metalworking fluid applications. Price differentiation hinges on REACH registration status and FDA food-contact notification completion, with uncertified formulators facing 18-24 month launch delays that erode pricing power. Cost compression in standard-grade powder runs through iron ore price volatility and Shandong province ascorbic acid supply concentration, while pharmaceutical and electronics buyers exhibit lowest price sensitivity due to qualification protocol rigidity.
Supply Chain Analysis
China's Ministry of Ecology and Environment dual carbon goals and domestic-content preferences for Yangtze River Delta fabrication facilities are reshaping sourcing patterns toward local enzymatic production pathways with lower thermal energy requirements. Supply concentrates in China for iron powder precursors and enzymatic systems, Germany for REACH-compliant specialty formulations, and Japan for glucose oxidase-catalase film integration. Raw material dependencies draw from Australian iron ore, Shandong province ascorbic acid clusters, and Taiwanese semiconductor-grade packaging substrates. Single-source vulnerability in Shandong organic scavenger feedstocks creates supply chain risk. Distribution runs through consolidated retail procurement channels with Walmart and Carrefour direct-supplier mandates displacing traditional distributor networks in United States and French fresh produce categories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Deoxidant competitive dynamics have become a vertical-integration race, with control over specialty iron powder precursors and cleanroom liquid-dosing infrastructure determining margin capture across electronics and pharmaceutical applications.
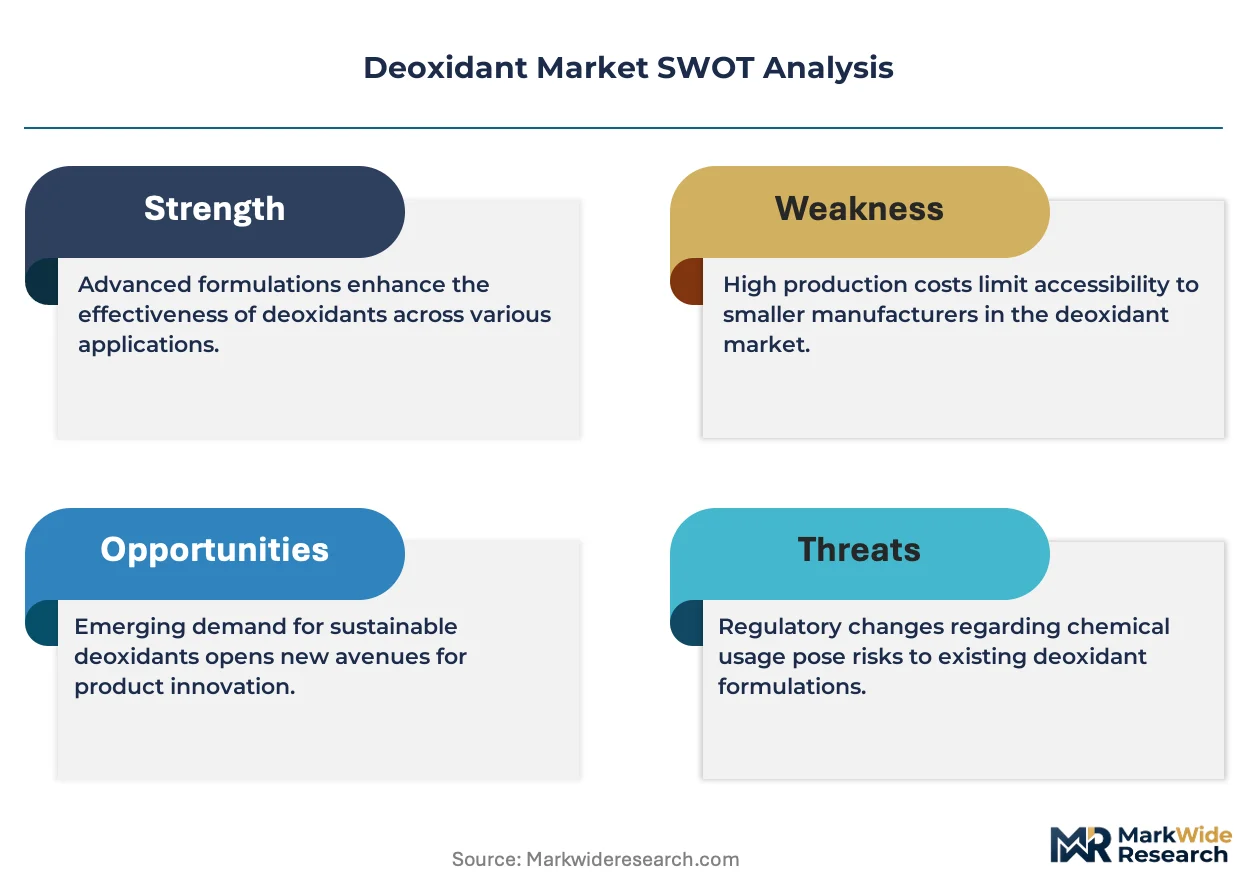
For Market Incumbents: Anticipate regulatory divergence between ECHA REACH thresholds and FDA food-contact rules by securing parallel certification capabilities in both jurisdictions, while deepening backward integration into high-purity iron powder production to defend against commodity-grade margin compression from Indian and Brazilian competitors. Capacity expansion in enzymatic production pathways aligns with China's MEE carbon-intensity benchmarks and secures qualification for domestic electronics fabrication procurement. For New Entrants and Emerging Players: Enter via aerospace component protection for precision liquid-dosed corrosion prevention in aircraft fuel systems, an underdeveloped vertical with limited incumbent specialization and qualification barriers lower than semiconductor-grade specifications. Target meal-kit subscription services in urban United States markets with single-serve sachet formats that bypass entrenched distributor relationships, leveraging direct-to-consumer fulfillment infrastructure and compact pre-measured packaging to establish initial volume positions. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap enzymatic specialists with established cleanroom infrastructure in China's Yangtze River Delta region, where domestic electronics fabrication investments and MEE dual carbon incentives create sustained demand tailwinds. Long-term viability over the projection horizon rests on qualification protocol completion across multiple jurisdictions rather than commodity volume scale. Watch for FDA food-contact notification approval velocity as the inflection indicator signaling which formulation platforms can capture United States retail channel access.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Precursors | Captures margin from iron powder purity premiums demanded by Taiwan semiconductor fabrication facilities. |
| Enzymatic Production Pathway Expansion | Aligns with China's MEE dual carbon goals while qualifying suppliers for domestic electronics procurement. |
| Parallel Multi-Jurisdiction Certification | Reduces time-to-revenue gaps between ECHA REACH compliance and FDA food-contact notification approvals. |
| Direct Retail Procurement Relationships | Bypasses distributor networks as Walmart and Carrefour mandate supplier consolidation in fresh produce. |
| Film-Integrated Scavenger Development | Eliminates separate sachet insertion steps for Japanese convenience retail chains piloting 14-day shelf life extension. |
Research Methodology
Multi-period observation of iron ore price indices, REACH registration completion rates, and FDA food-contact notification approval timelines anchored the trend analysis, supplemented by interviews with plant managers at German meat processing facilities, procurement leads at South Korean semiconductor fabrication sites, distribution channel partners in China's cold-chain logistics sector, and technical R&D directors at Japanese packaging equipment manufacturers. Secondary validation drew from ECHA registration databases, FDA food-contact substance inventories, Chinese customs trade data for iron powder imports, and SEC filings of diversified chemical conglomerates. Bottom-up volume estimates from individual application segments triangulated against top-down market sizing from precursor consumption patterns.
Input-output matrices mapped deoxidant consumption across formulation chemistry, delivery format, end-use industry, and regional production hub dimensions throughout the forecast period. CAGRs derived from segmented volume trajectories weighted by purity-grade pricing differentials and regulatory compliance cost absorption. Industry-specific forecast inputs included semiconductor wafer packaging growth from Taiwanese and South Korean fabrication investments, plus cold-chain logistics expansion metrics from China's pharmaceutical and fresh produce distribution infrastructure buildout.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt iron ore price shocks, ECHA substance restriction amendments, or FDA migration limit stringency increases for novel iron chelate complexes. Forecasts reflect documented assumptions regarding qualification timeline standardization and carbon-intensity benchmark stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Mass Transfer Trays Market
Industrial Chemicals
Global High Throughput Process Development Market
Industrial Chemicals
Beneficiation Reagents Market
Industrial Chemicals
US Anhydrous Hydrogen Fluoride Market
Industrial Chemicals
Global Foundry Chemicals Market
Industrial Chemicals
Explosive Chargers Market
Industrial Chemicals
Permethrin Market
Industrial Chemicals
Reconditioned Drums Market
Industrial Chemicals
Fatty Amines Market
Industrial Chemicals
Europe Hydrocarbon Refrigerants Market
Industrial Chemicals
Rotomolding Powder Market
Industrial Chemicals
Pulp and Paper Enzymes Market
Industrial Chemicals
Hydrogen Silicone Fluid Market
Industrial Chemicals
Liquid Electrolyte Market
Industrial Chemicals
Bio Derived Enzymes for Detergents Market
Industrial Chemicals
Naphthenic Acid Market