
 Iraq Freight and Logistics Market | 2026-2036
Iraq Freight and Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Iraq Freight and Logistics Market Foresight
The gap between premium cold-chain logistics and standard dry-cargo services is recalibrating pricing structures across Iraqi corridors. CMA CGM Group leverages its port infrastructure partnerships to dominate containerized sea freight into Umm Qasr. DHL Group sustains express air freight capacity through Baghdad International Airport operations. Almas Group International Transportation anchors domestic road distribution networks connecting Kurdish autonomous region hubs to southern port zones.
Iraq freight and logistics encompasses the planning, execution, and management of goods movement across multimodal networks including temperature-controlled reefers, flatbed trailers for construction materials, and bulk liquid tankers for petroleum derivatives, with primary commercial purpose of bridging import-dependent consumption centers to global supply sources. Road transport occupies the largest volume share given underdeveloped rail alternatives and fragmented last-mile topography. Contract logistics represents the fastest-expanding service category as multinational manufacturers seek outsourced inventory management rather than owned warehouse operations. Third-party logistics providers capture expanding margin pools by integrating customs brokerage with inland distribution.
Iraq's General Commission for Customs, the Ministry of Transportation, and the Kurdistan Regional Government's investment board collectively shape market access through port concession rules, transit permit allocations, and cross-border tariff harmonization. These frameworks determine which operators qualify for bonded warehouse licenses and priority corridor allocations. Stakeholders must monitor infrastructure tender timelines and customs automation rollout phases to secure operational positioning before competitor network density solidifies.
Market Dynamics
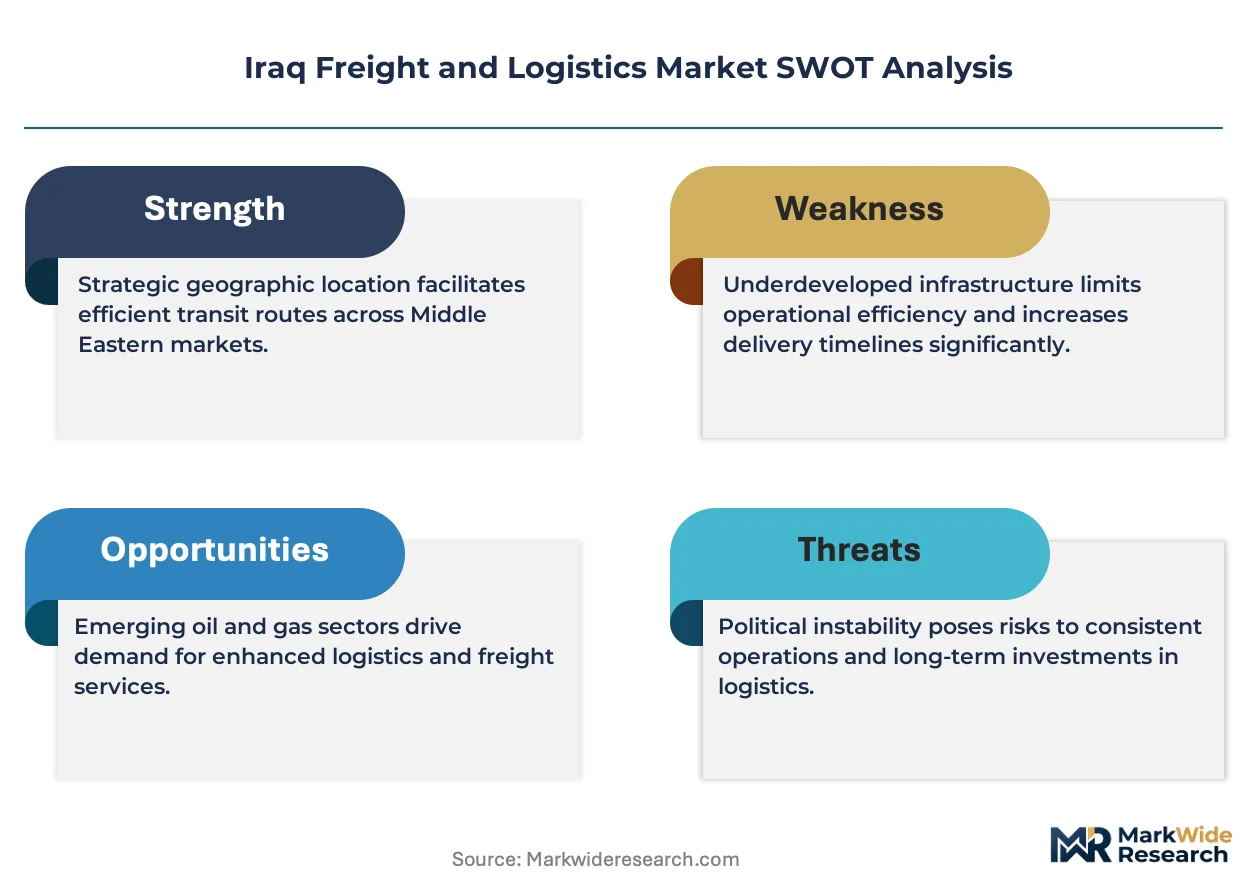
Oil and gas sector procurement cycles are concentrating freight forwarding demand along the Baghdad-Basra corridor, while customs modernization directives from Iraq's General Commission for Customs reconfigure clearance protocols and bonded warehouse licensing.
Growth Catalysts
- Customs Automation Directives:Iraq's General Commission for Customs is digitizing cross-border clearance protocols, reducing dwell times at Umm Qasr port and accelerating bonded warehouse throughput for containerized imports.
- Oil and Gas Procurement Expansion:Upstream capital expenditure from international petroleum operators is generating sustained demand for heavy-lift project cargo and bulk liquid tanker movements.
- Kurdistan Regional Government Investment Board:Priority corridor allocations and transit permit frameworks are channeling warehousing investment toward Erbil-Duhok distribution hubs connecting to southern port zones.
Market Restraints
- Fuel Price Volatility:Diesel cost fluctuations directly compress road freight margins across Iraq's long-haul domestic networks, where diesel-powered flatbed trailers dominate construction material movements.
- Rail Infrastructure Underdevelopment:Fragmented track connectivity between Baghdad and Basra forces cargo onto higher-cost road alternatives, limiting modal choice for bulk commodity shippers.
- Cross-Border Tariff Harmonization Gaps:Discrepancies between federal customs frameworks and Kurdistan Regional Government transit rules create documentation friction at internal checkpoints.
Strategic Opportunities
- Basra Special Economic Zone Development:Port-adjacent free zone expansion is attracting third-party logistics providers seeking integrated customs brokerage with inland distribution capabilities.
- Temperature-Controlled Reefer Services:Pharmaceutical and food importers are driving underpenetrated cold-chain infrastructure investment at Baghdad International Airport cargo terminals.
- Contract Logistics Outsourcing:Multinational manufacturers in automotive and consumer goods verticals are abandoning owned warehouse operations in favor of outsourced inventory management partnerships.
Industry Challenges
- Last-Mile Topography Fragmentation:Informal settlement patterns and inadequate addressing systems in southern Iraqi cities complicate final delivery routing for e-commerce and retail distribution networks.
- Licensed Customs Broker Scarcity:Bonded warehouse operator qualifications require specialized certification timelines that lag behind demand growth, constraining service expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Iraq Freight and Logistics Market |
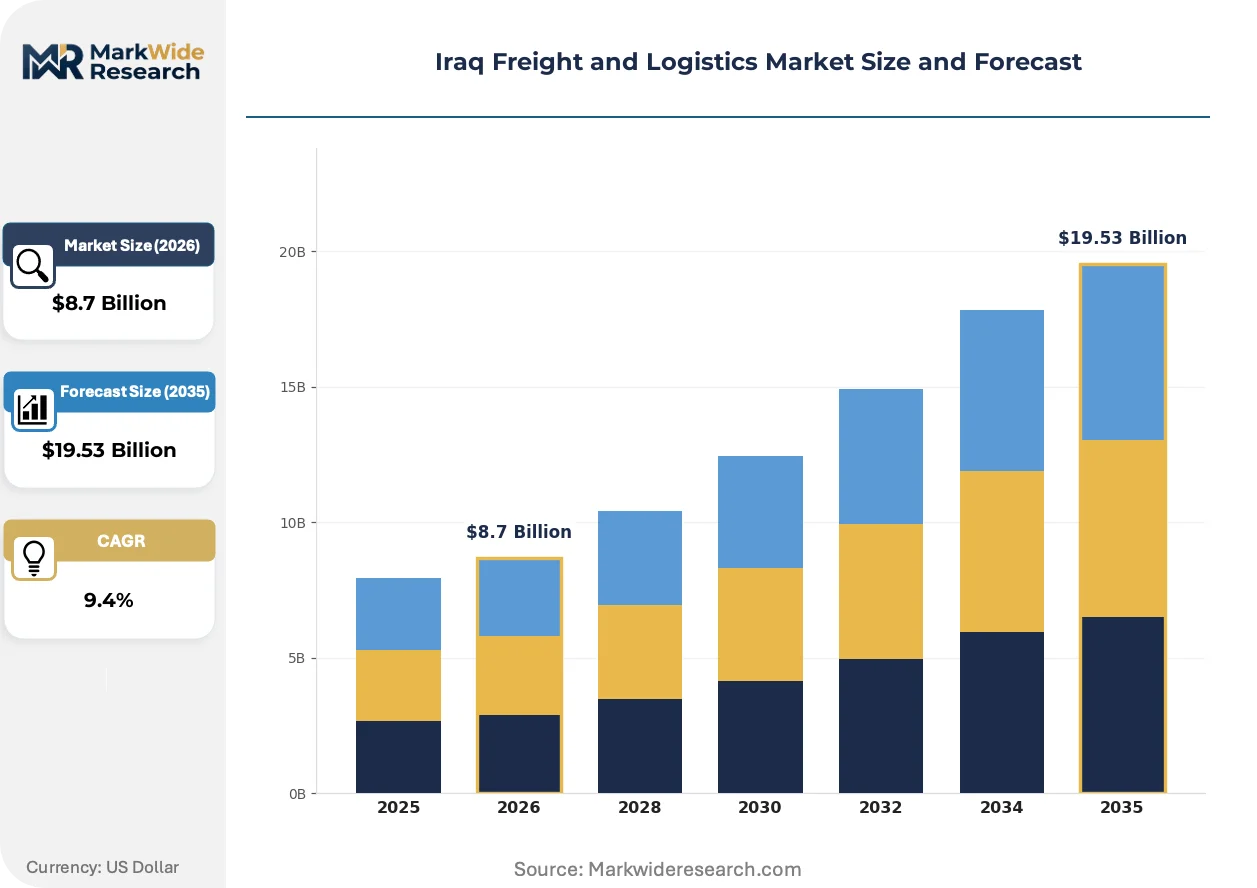
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Logistics Type: Freight Forwarding, Warehousing, Transportation, Supply Chain Management Service Category: Contract Logistics, Third-Party Logistics, Last-Mile Delivery, Freight Brokerage Transport Mode: Road Transport, Rail Transport, Air Freight, Sea Freight Customer Segment: Manufacturers, Retailers, E-commerce, Government |
| Companies Covered | CMA CGM Group, Almas Group International Transportation, DHL Group, DSV Global Transports and Logistics, Mateen Express and Logistics, A.P. Moller – Maersk, Aramex, Nippon Express, GAC Group (Holdings), Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Iraq Freight and Logistics Market Shifts & Advancements
Digital freight platforms and automated customs systems are compressing transaction cycles across Iraqi multimodal networks, while procurement models evolve toward integrated supply chain outsourcing.
Blockchain-enabled cargo documentation is expanding into containerized sea freight operations at Umm Qasr port, where shipping lines and customs brokers are piloting distributed ledger systems for bill-of-lading verification. Major commodity importers are adopting these platforms to reduce documentary fraud exposure. The technology is expanding into cross-border trade finance arrangements, compressing settlement cycles for letters of credit.
Iraq's General Commission for Customs modernization directives are mandating electronic manifest submission and risk-based inspection protocols, eliminating paper-based clearance bottlenecks at primary entry points. Industrial manufacturers importing machinery and production inputs face accelerated release timelines. Temperature-sensitive pharmaceutical cargo at Baghdad International Airport is benefiting most from expedited cold-chain clearance procedures.
Integrated logistics procurement is consolidating previously fragmented forwarding, warehousing, and customs brokerage contracts into single-source arrangements with third-party providers. Multinational industrial and retail buyers are displacing transactional spot-market freight purchases. Basra-based oilfield service companies are demonstrating this consolidation most visibly, bundling project cargo management with inventory holding services.
Iraq Freight and Logistics Market Segmentation
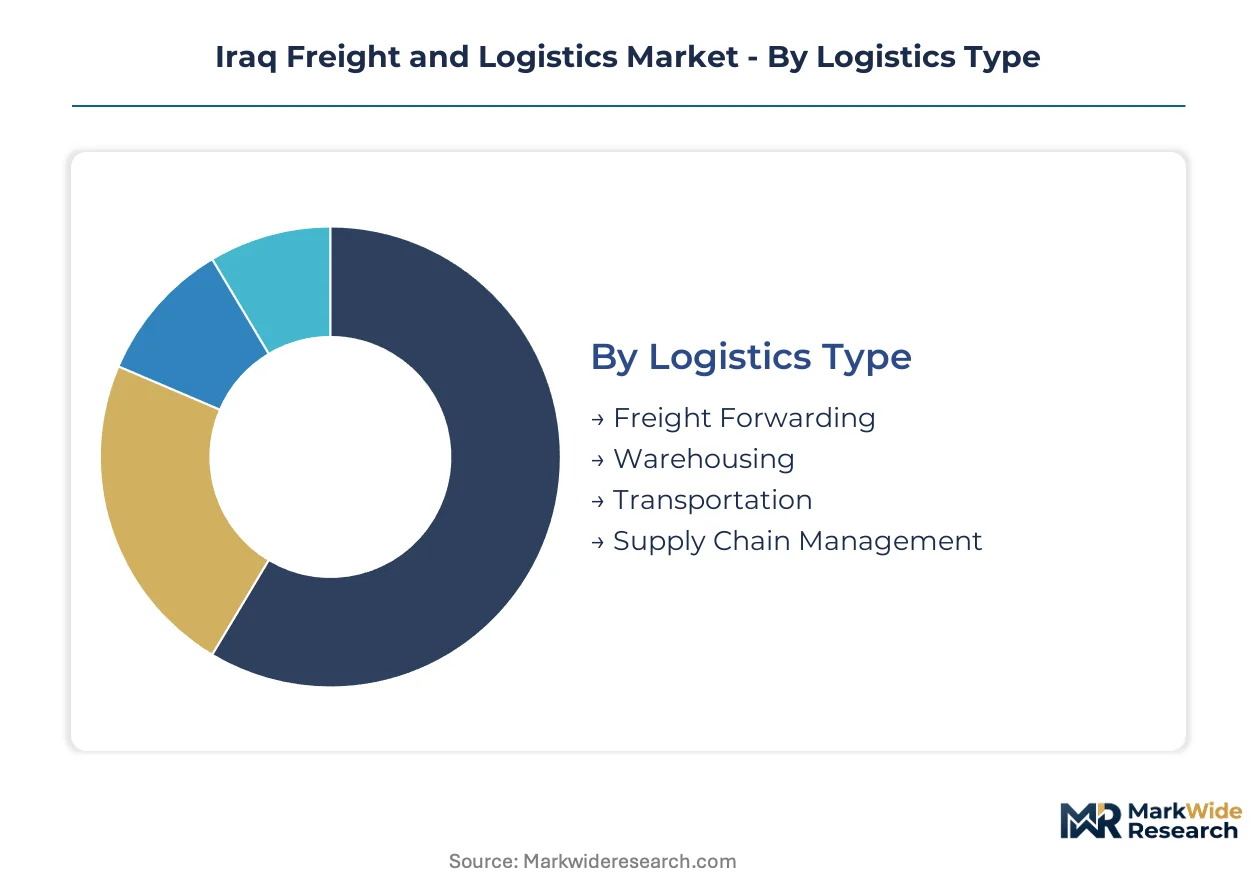
Segmentation reveals how procurement cycles and infrastructure gaps concentrate revenue across distinct service tiers. Operators align capability investments with modal constraints and customer outsourcing maturity.
Logistics Type:
Replacement cycles in logistics assets favor integrated service bundles over standalone functions.
- Freight Forwarding:Consolidation and documentation management for multimodal cargo movements. Oil and gas procurement along the Baghdad-Basra corridor sustains heavy-lift forwarding demand for project cargo and bulk liquid tankers.
- Warehousing:Bonded and non-bonded storage facilities with inventory management systems. Investment concentrates at Umm Qasr-adjacent zones and Erbil distribution hubs serving Kurdish autonomous region trade corridors.
- Transportation:Asset-based and non-asset-based cargo movement execution. Diesel-powered flatbed trailers dominate construction material flows where rail connectivity remains fragmented.
- Supply Chain Management:End-to-end planning and optimization services spanning demand forecasting to distribution network design. Multinational manufacturers adopt these solutions to displace owned logistics infrastructure.
Volume placements concentrate in Freight Forwarding; the faster expansion belongs to Supply Chain Management.
Service Category:
Customer procurement sophistication separates transactional spot purchases from multi-year integrated partnerships.
- Contract Logistics:Long-term outsourced warehouse operations with embedded inventory management. Automotive and consumer goods multinationals are abandoning captive facilities for operator-managed dedicated spaces.
- Third-Party Logistics:Bundled forwarding, customs brokerage, and distribution services. Basra Special Economic Zone development is attracting 3PL providers seeking integrated customs clearance with inland distribution capabilities.
- Last-Mile Delivery:Final distribution to end consumers and retail points. Informal settlement patterns in southern Iraqi cities complicate routing for e-commerce networks.
- Freight Brokerage:Intermediary matching of cargo with available transport capacity. Spot-market price discovery serves shippers with irregular or project-based freight requirements.
Contract Logistics captures the largest revenue pool; Third-Party Logistics is climbing the fastest as procurement consolidates.
Transport Mode:
Infrastructure availability constrains modal choice, forcing cargo onto higher-cost alternatives where networks are underdeveloped.
- Road Transport:Diesel-powered truck and trailer movements across highway and rural networks. Flatbed configurations handle construction materials while tankers move petroleum derivatives; fuel price volatility directly compresses operator margins.
- Rail Transport:Bulk commodity movement on limited track infrastructure. Fragmented connectivity between Baghdad and Basra forces cargo onto road alternatives, constraining modal competition.
- Air Freight:Time-sensitive cargo via Baghdad International Airport and regional airports. Temperature-controlled reefer services for pharmaceutical imports are driving cargo terminal infrastructure investment.
- Sea Freight:Containerized and bulk cargo through Umm Qasr port. CMA CGM Group leverages port infrastructure partnerships to dominate containerized import volumes.
Road Transport holds dominant volume share; Air Freight is gaining share fastest from pharmaceutical and electronics import demand.
Customer Segment:
Outsourcing readiness varies by sector maturity and regulatory procurement requirements.
- Manufacturers:Industrial producers importing machinery and production inputs. Customs automation directives accelerate release timelines for manufacturing supply chains.
- Retailers:Consumer goods distributors requiring inventory holding and replenishment services. Basra-based operators serve retail networks across southern consumption centers.
- E-commerce:Digital commerce platforms requiring fulfillment and last-mile capabilities. Addressing system inadequacies in informal settlements complicate delivery routing.
- Government:Public sector procurement and infrastructure project logistics. Ministry of Transportation and General Commission for Customs frameworks shape operator licensing and corridor access.
Manufacturers anchor current volume; E-commerce shows steepest expansion trajectory from underpenetrated digital retail penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Baghdad-Basra corridor concentrates Iraq's freight and logistics activity, with Umm Qasr port handling the bulk of containerized imports and Erbil anchoring distribution networks for the Kurdish autonomous region.
Baghdad Governorate
Baghdad International Airport cargo terminals are expanding temperature-controlled reefer capacity for pharmaceutical imports. Iraq's General Commission for Customs automation directives are accelerating electronic manifest processing at airport customs facilities. Industrial zones in eastern Baghdad are attracting contract logistics providers serving automotive parts distributors.
Basra Governorate
Oilfield service companies along the Shatt al-Arab waterway are consolidating project cargo and inventory holding services into single-source logistics contracts. Basra Special Economic Zone development is attracting third-party logistics providers seeking bonded warehouse licenses adjacent to Umm Qasr port. Heavy-lift forwarding demand from upstream petroleum operators sustains specialized equipment pools in the port district.
Kurdistan Region
Erbil and Duhok distribution hubs are channeling warehousing investment toward cross-border trade corridors connecting to southern port zones. The Kurdistan Regional Government's investment board prioritizes corridor allocations for operators qualifying for transit permit frameworks. Manufacturing importers in the Sulaymaniyah industrial zone are adopting outsourced inventory management partnerships.
Nineveh and Anbar Governorates
Reconstruction material flows through Mosul and Ramadi are reviving road freight networks damaged during conflict periods. Federal customs frameworks are harmonizing clearance protocols at western border crossings with Jordan and Syria. Construction logistics providers are positioning flatbed trailer fleets to serve cement and steel distribution to rebuilding urban centers.
Iraq Freight and Logistics Market Competitive Landscape
Premium-margin players sit above commodity-margin players across service integration depth, with bundled customs brokerage and inland distribution commanding superior pricing power over standalone forwarding functions. The vendor base fragments between global shipping lines with port infrastructure partnerships, regional express operators with air cargo capacity, and domestic road specialists with last-mile density. Three archetypes dominate: integrated multimodal operators, asset-light freight forwarders, and captive oilfield logistics providers. Capacity expansion at Umm Qasr-adjacent free zones and strategic partnerships for bonded warehouse licensing represent the dominant competitive moves.
Within the integrated multimodal tier, CMA CGM Group and A.P. Moller – Maersk exemplify global shipping lines leveraging port infrastructure partnerships to anchor containerized sea freight volumes. DHL Group occupies a position among express air freight specialists sustaining cargo terminal operations at Baghdad International Airport. Almas Group International Transportation represents domestic road distribution archetypes connecting Kurdish autonomous region hubs to southern port zones through permit-secured corridor allocations.
| Leading Market Players |
|---|
| CMA CGM Group |
| Almas Group International Transportation |
| DHL Group |
| DSV Global Transports and Logistics |
| Mateen Express and Logistics |
| A.P. Moller – Maersk |
| Aramex |
| Nippon Express |
| GAC Group (Holdings), Ltd. |
| Others |
Supply & Pricing Matrix
Iraq's General Commission for Customs modernization directives for electronic manifest submission and risk-based inspection protocols gate qualified supply access and premium-tier pricing power for operators holding bonded warehouse licenses and priority corridor allocations. Compliance investment separates certified providers commanding integrated service premiums from transactional spot-market competitors facing margin compression.
Pricing Analysis
Outcome-based pricing anchored to clearance throughput timelines and inventory velocity dominates contract logistics negotiations with multinational manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates bonded warehouse operators with customs automation integration from basic forwarding services and informal brokerage arrangements. Cost compression in standard-tier road freight is intensifying because diesel price volatility directly erodes flatbed trailer operator margins across long-haul domestic networks. E-commerce platforms and informal retail distributors exhibit highest price sensitivity, while oilfield service companies demonstrate lowest sensitivity due to procurement consolidation into single-source integrated contracts.
Supply Chain Analysis
Regional distribution centers at Umm Qasr-adjacent free zones and Erbil-Duhok hubs anchor hub-and-spoke patterns connecting Kurdish autonomous region trade corridors to southern port zones. Equipment and technology inputs draw from China, Turkey, and the United Arab Emirates for port handling systems and warehouse automation. Diesel fuel and specialized chassis for heavy-lift project cargo represent critical input dependencies tethered to petroleum market fluctuations. Single-source vulnerability concentrates in customs brokerage certification pipelines where licensed operator scarcity lags demand growth. Distribution runs through multimodal corridors integrating sea freight at Umm Qasr with road networks spanning Baghdad-Basra and Erbil-southern linkages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Iraq freight and logistics functions as a consolidation play where customs automation compliance costs and bonded warehouse licensing requirements force undercapitalized spot-market operators toward exit or acquisition.
For Market Incumbents: Cement corridor control by securing transit permit allocations from the Kurdistan Regional Government's investment board before competitor network density solidifies at Erbil distribution hubs. Deepen backward integration into captive customs brokerage certification pipelines to offset licensed broker scarcity constraining service expansion. Defensive positioning requires priority allocation defense against emerging regional 3PL entrants seeking Basra Special Economic Zone free zone expansion slots. For New Entrants and Emerging Players: Temperature-controlled pharmaceutical importers at Baghdad International Airport represent an underserved buyer archetype where cold-chain infrastructure gaps create penetrable white-space. Target contract logistics outsourcing demand from automotive parts distributors in eastern Baghdad industrial zones seeking dedicated inventory management partnerships. Basra-based oilfield service companies demonstrate the most consolidatable procurement pattern for integrated project cargo and warehousing bundles. For Investors and Strategic Acquirers: Accelerated bonded warehouse licensing approvals from Iraq's General Commission for Customs is the leading indicator that regulatory barriers are easing for qualified operators over the five-to-ten year infrastructure modernization horizon. Acquisition targets should display integrated multimodal capability spanning customs brokerage certification with inland distribution density rather than single-function forwarding operations. Monitor customs automation rollout phase completion at Umm Qasr as the signal for operational inflection where compliant operators capture margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Bonded Warehouse Licensing | Priority allocation from Iraq's General Commission for Customs secures premium-tier pricing access for integrated operators. |
| Cold-Chain Infrastructure Investment | Temperature-controlled reefer capacity expansion at Baghdad International Airport cargo terminals captures pharmaceutical import demand. |
| Customs Brokerage Certification | Licensed operator pipeline development addresses scarcity constraining service expansion for third-party logistics providers. |
| Corridor Allocation Securement | Transit permit frameworks from the Kurdistan Regional Government investment board anchor Erbil-Duhok distribution hub control. |
| Contract Logistics Outsourcing Partnerships | Long-term dedicated space arrangements with automotive and consumer goods multinationals displace captive warehouse operations. |
Research Methodology
Multi-period observation of customs automation rollout phases, bonded warehouse licensing timelines, and corridor allocation patterns anchored the trend analysis, supplemented by interviews with freight forwarding executives, bonded warehouse operators, customs brokerage specialists, and procurement managers at multinational manufacturers. Secondary validation drew from Iraq's General Commission for Customs directive publications, Ministry of Transportation infrastructure tender disclosures, Kurdistan Regional Government investment board corridor allocation announcements, and Umm Qasr port throughput statistics. Bottom-up service provider capability mapping and top-down trade flow analysis enabled triangulation across the analysis window.
Input-output matrix framing connected modal capacity expansion, customs processing efficiency gains, and outsourcing adoption curves to segment-level revenue trajectories across logistics type, service category, transport mode, and customer segment dimensions. CAGRs were derived from modeled relationships between infrastructure investment cycles and procurement consolidation patterns, with specific weighting applied to oil and gas capital expenditure cycles, pharmaceutical import growth, and e-commerce penetration trajectories.
Revisions become necessary when customs automation implementation delays, fuel price volatility spikes, or cross-border tariff harmonization gaps between federal and Kurdistan Regional Government frameworks materialize beyond modeled assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Europe Contract Logistics Market
Logistics and Shipping
Inbound Logistics Market
Logistics and Shipping
Australia 3PL Market
Logistics and Shipping
Japan Logistics Market
Logistics and Shipping
South America Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
US Courier, Express, and Parcel Market
Logistics and Shipping
Europe FMCG Logistics Market
Logistics and Shipping
US Event Logistics Market
Logistics and Shipping
India Domestic Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Global Container Terminal Operations Market
Logistics and Shipping
Indonesia Freight and Logistics Market
Logistics and Shipping
Intralogistics Containers Market
Logistics and Shipping
Poland Cold Chain Logistics Market
Logistics and Shipping
Tanker Shipping Market
Logistics and Shipping
Event Logistics Market
Logistics and Shipping
Indonesia Cold Chain Logistics Market