
 Asia Pacific Rett Syndrome Market | 2026-2036
Asia Pacific Rett Syndrome Market Size, Share, and Industry Trends Forecast 2026-2036
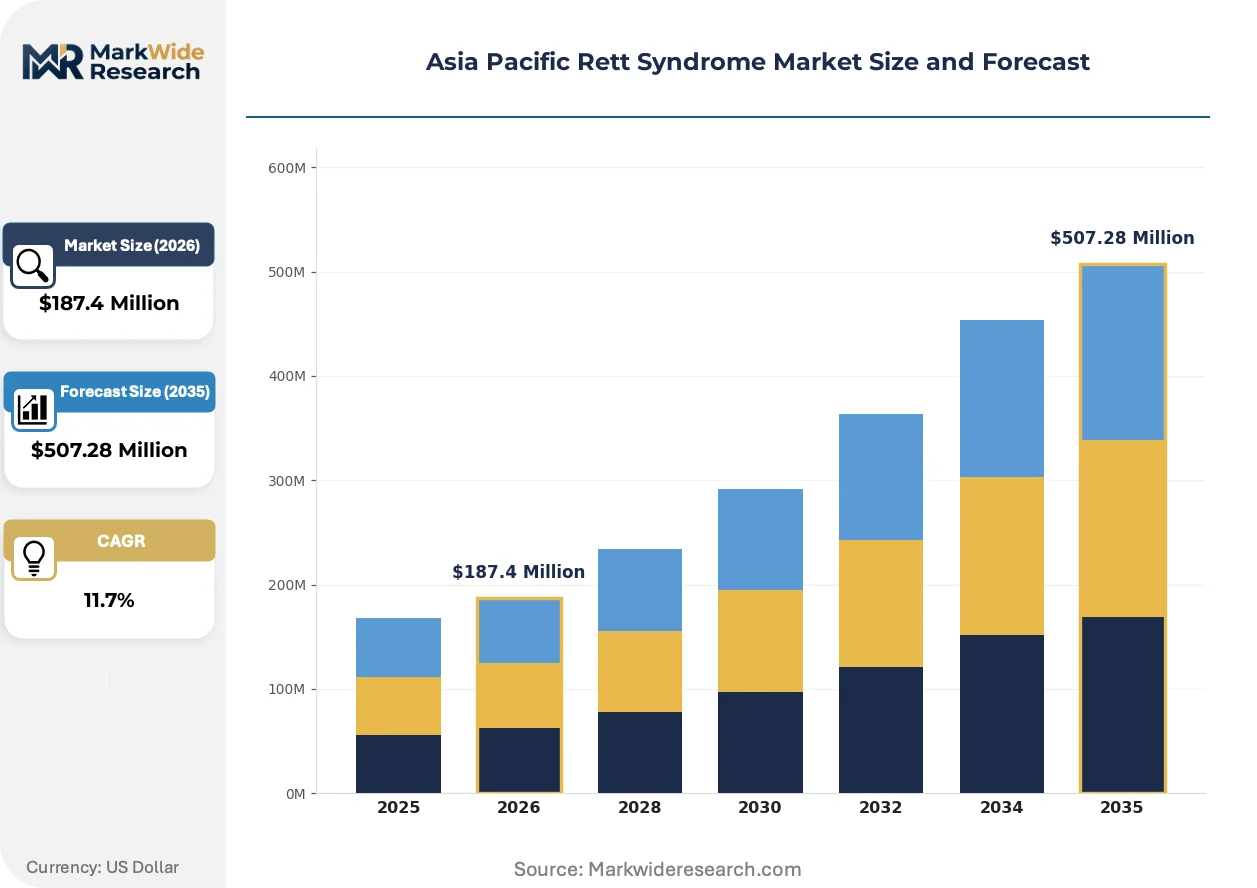
Asia Pacific Rett Syndrome Market Outlook
Australia's pediatric neurology infrastructure is reconfiguring access patterns for Rett syndrome care across the Asia Pacific. Eisai Co., Ltd. leverages its neurology franchise to anchor clinical development efforts in Japan. Neurotech International Ltd. sustains a specialized position through cell therapy research targeting rare neurological disorders. Zydus Cadila competes on cost-accessible manufacturing, extending generic and biosimilar capabilities into orphan indications.
Rett syndrome constitutes a rare neurodevelopmental disorder caused by mutations in the MECP2 gene on the X chromosome, characterized by apparently normal early development followed by loss of purposeful hand skills, gait abnormalities, and severe communication impairment. Therapeutics dominates current value generation, with pharmacological intervention representing the most structurally concentrated margin pool. Diagnostics is gaining share as next-generation sequencing panels and biochemical biomarker assays expand newborn screening protocols. Support services occupy a fragmented but essential layer, bridging hospital discharge and long-term home care management.
Japan's PMDA operates an accelerated approval pathway for regenerative medicines and orphan drugs, compressing development timelines for novel Rett syndrome interventions. Australia's TGA aligns with international ICH standards while maintaining distinct pediatric labeling requirements that influence trial design. India's CDSCO orphan drug provisions, including tax incentives and waived registration fees, are redirecting sponsor investment toward local manufacturing. Stakeholders must weigh Japan's premium reimbursement environment against India's volume-access potential when sequencing market entry decisions.
Market Dynamics
Japan's PMDA regenerative medicine framework and India's CDSCO orphan drug incentives are compressing development timelines while fragmenting sponsor investment across divergent regulatory pathways. This dual-track acceleration is reshaping how cell therapy developers sequence market entry decisions.
Growth Catalysts
- Next-generation sequencing panels:Biochemical biomarker assays and MECP2 mutation screening are expanding newborn protocols across Australian pediatric neurology networks. Diagnostic penetration is deepening in metropolitan hospital clusters.
- CDSCO orphan drug provisions:India's tax incentives and waived registration fees are redirecting manufacturing investment toward local production capacity. Sponsors are reconfiguring supply footprints.
- PMDA accelerated approval:Japan's compressed timelines for regenerative medicines are attracting cell therapy trials. Pediatric labeling requirements are influencing protocol design.
Market Restraints
- Genetic testing cost structure:MECP2 mutation analysis and specialized neurology consultations impose significant out-of-pocket burdens on families. Reimbursement gaps persist in secondary cities.
- Supply concentration in metropolitan hubs:Japan's demand concentrates in Tokyo-Osaka corridors while Australia's specialized rehabilitation centers cluster in Sydney-Melbourne. Rural access remains structurally constrained.
- Technical limitation in female diagnosis:X-chromosome inactivation patterns complicate phenotypic prediction and therapeutic targeting. Variable expressivity challenges clinical trial stratification.
Strategic Opportunities
- Underpenetrated Indian diagnostics:Tier-2 and Tier-3 cities lack MECP2 screening infrastructure. Public-private partnership models could extend newborn testing coverage.
- TGA pediatric labeling alignment:Australia's distinct requirements create trial design expertise that transfers to ASEAN markets. Regulatory consulting services are emerging.
- Home-based rehabilitation technology:Telehealth platforms and remote monitoring tools are bridging gaps between hospital discharge and long-term care management. Family caregiver support systems are digitizing.
Industry Challenges
- Pediatric neurology specialist scarcity:Rett syndrome diagnosis and management require rare expertise concentrated in academic medical centers. Training pipeline expansion lags demand growth.
- Multi-site trial coordination:Cross-border protocol alignment between Japan's PMDA and Australia's TGA creates documentation complexity. Harmonization efforts remain incomplete.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Rett Syndrome Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Therapeutics, Diagnostics, Support Services, Nutritional Products Treatment Approach: Behavioral Therapy, Pharmacological Intervention, Physiotherapy, Occupational Therapy End User: Hospitals, Rehabilitation Centers, Home Care, Research Institutions Distribution Channel: Online Pharmacies, Retail Pharmacies, Direct Sales, Specialty Clinics |
| Companies Covered | Eisai Co., Ltd., Neurotech International Ltd., Zydus Cadila, Viatris Inc., Hikma Pharmaceuticals PLC, LUPIN, Teva Pharmaceutical USA, Dr. Reddy's Laboratories Ltd., Sun Pharmaceutical Industries Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Rett Syndrome Market Strategic Shifts
Gene therapy delivery mechanisms and regulatory pathway convergence are actively restructuring competitive positioning in Asia Pacific rare disease markets. Technology developers are navigating between premium reimbursement environments and volume-access strategies.
Antisense oligonucleotide platforms targeting MECP2 gene regulation are collapsing the traditional small-molecule development timeline. Japanese academic medical centers are adopting these modalities for compassionate use protocols. The compression is enabling first-in-class entrants to establish clinical evidence before large-scale trials conclude.
PMDA's regenerative medicine framework and TGA's alignment with ICH pediatric standards are creating divergent but navigable approval routes. Sponsors are building parallel submission capabilities to exploit Japan's premium pricing against Australia's faster patient access. Cell therapy developers are most affected, with manufacturing scale-up decisions now preceding pivotal trial design.
Family caregiver networks are consolidating purchasing influence through digital platforms and patient advocacy organizations. Hospital discharge planning is shifting toward integrated home care service contracts that bundle equipment, nursing visits, and remote monitoring. This restructuring is most visible in Australia's National Disability Insurance Scheme channels and Japan's long-term care insurance system.
Asia Pacific Rett Syndrome Market Segmentation
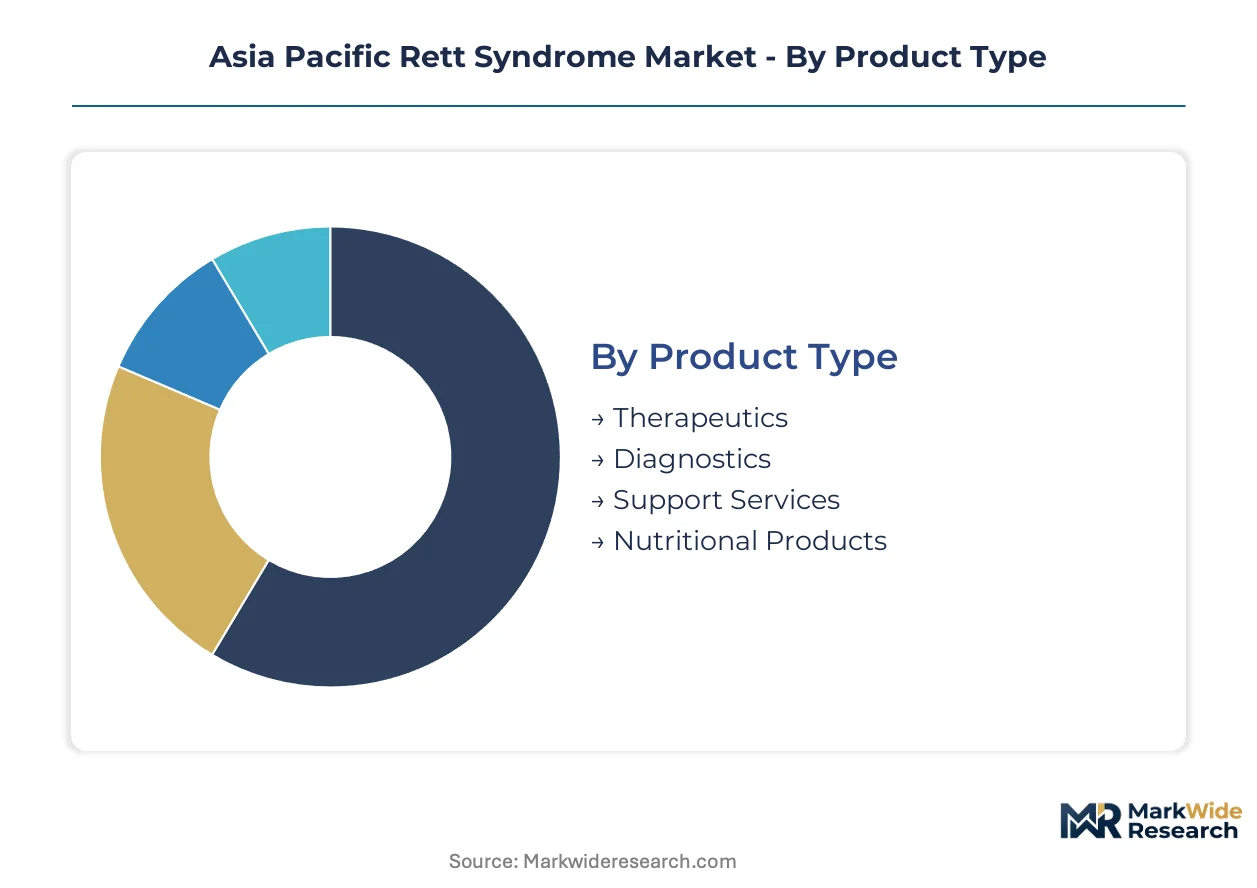
Segmentation in the Asia Pacific Rett syndrome market reveals how value pools concentrate across intervention modalities and care delivery settings. Product type and treatment approach splits expose where margin capture diverges from patient access priorities.
Product Type:
Cost tier stratification across the product mix separates premium-margin biologics from commoditized support offerings.
- Therapeutics:Pharmacological interventions targeting MECP2 pathway modulation command the highest price points. Japan's PMDA accelerated approval pathway draws cell therapy and gene therapy developers to Tokyo-Osaka hospital networks first. Reimbursement negotiations with Japan's long-term care insurance system determine commercial viability.
- Diagnostics:Next-generation sequencing panels and MECP2 mutation assays are penetrating Australian metropolitan pediatric neurology clinics. Newborn screening protocol expansion in New South Wales and Victoria is creating demand concentration. CDSCO orphan drug incentives in India are redirecting manufacturing investment toward local diagnostic production.
- Support Services:Equipment, nursing coordination, and caregiver training bridge hospital discharge and home management.
- Nutritional Products:Specialized feeding formulations address gastroenterological complications common in Rett syndrome progression.
Therapeutics commands the established base. The steepest expansion runs through Diagnostics.
Treatment Approach:
Application focus distinguishes acute symptom management from longitudinal functional preservation strategies.
- Pharmacological Intervention:Small-molecule and biologic therapies target specific symptom clusters including seizures, breathing irregularities, and motor dysfunction. Australia's TGA pediatric labeling requirements influence trial design for compounds seeking early approval. Sydney-Melbourne academic medical centers host the majority of regional interventional studies.
- Behavioral Therapy:Communication rehabilitation and behavioral modification protocols require specialized therapist training. Demand concentrates in Japan's designated child development support centers and Australia's National Disability Insurance Scheme-funded providers. Family caregiver skill transfer limits scalability.
- Physiotherapy:Gait training and musculoskeletal maintenance programs address progressive mobility impairment.
- Occupational Therapy:Adaptive equipment and daily living skill preservation focus on quality-of-life maintenance.
Pharmacological Intervention anchors revenue concentration. Behavioral Therapy is climbing the fastest as reimbursement frameworks mature.
End User:
Customer type fragmentation reflects care continuum handoffs from acute diagnosis through lifetime management.
- Hospitals:Academic medical centers in Japan and Australia concentrate diagnostic expertise and interventional trial access. Pediatric neurology departments at Tokyo Women's Medical University and Royal Children's Hospital Melbourne anchor referral networks. Tertiary capacity constraints create waitlist bottlenecks for initial MECP2 confirmation testing.
- Home Care:Family-directed care models are expanding through Japan's long-term care insurance digitization and Australia's NDIS plan management. Remote monitoring technology adoption is highest in metropolitan corridors with reliable broadband infrastructure. Caregiver burnout drives demand for respite service integration.
- Rehabilitation Centers:Specialized pediatric facilities provide intensive therapy blocks.
- Research Institutions:Academic centers conduct natural history studies and biomarker validation.
Hospitals retain the diagnostic gateway position. Home Care is gaining share fastest as payment systems shift toward community-based management.
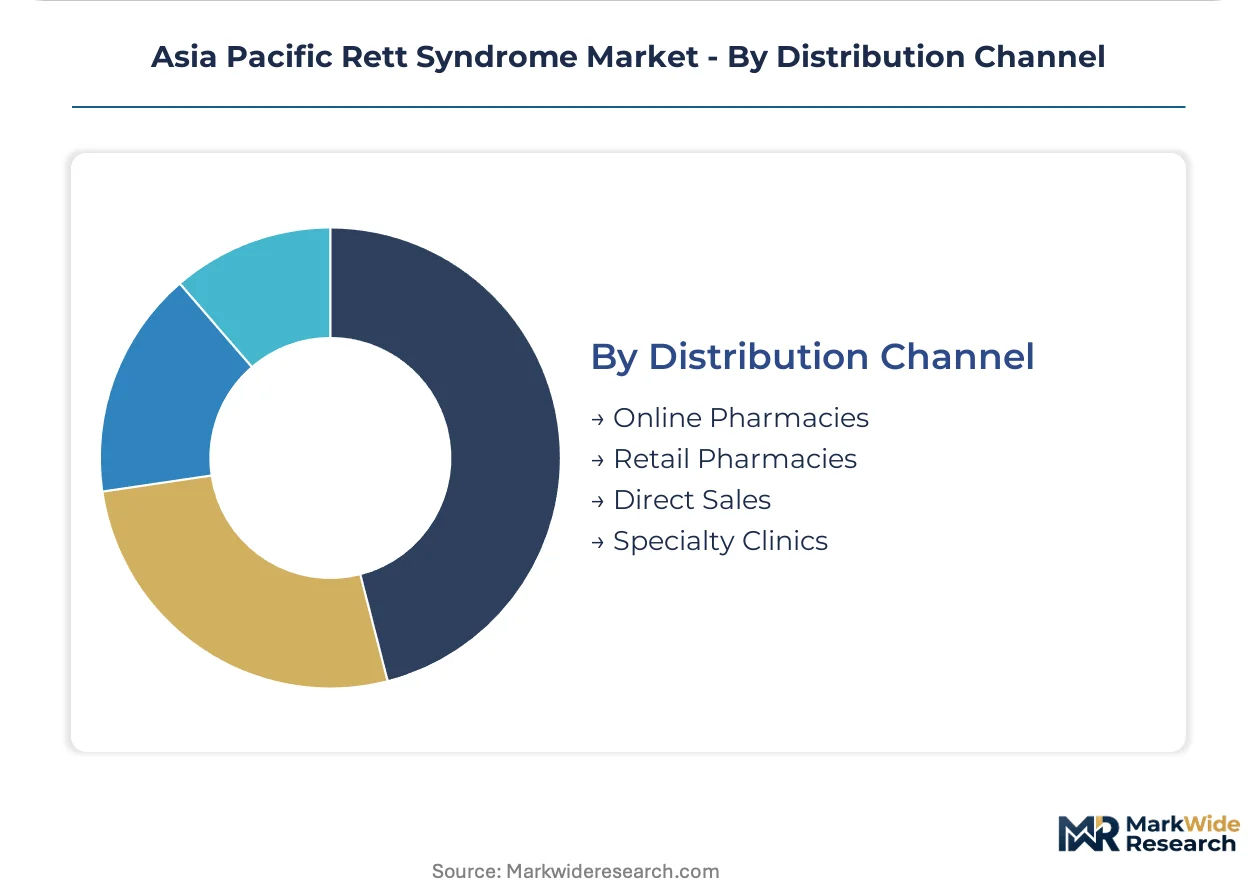
Distribution Channel:
Supply concentration varies by product complexity and regulatory oversight requirements.
- Specialty Clinics:Pediatric neurology and genetics centers control access to orphan therapeutics and advanced diagnostics. Japan's 357 designated rare disease consultation hubs and Australia's state-based metabolic services filter patient flow. Prescription authority and compounding capabilities create channel stickiness.
- Direct Sales:Device manufacturers and nutritional suppliers engage institutional procurement teams. Australia's hospital purchasing consortia and Japan's medical device reimbursement price listings structure negotiation dynamics. Volume commitments determine contract tier placement.
- Online Pharmacies:Digital dispensing platforms extend reach for maintenance medications.
- Retail Pharmacies:Community outlets handle limited supportive care products.
Specialty Clinics dominates high-value product flow. Direct Sales is expanding most quickly as institutional procurement consolidates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pediatric neurology infrastructure concentrates in Japan and Australia's metropolitan hospital networks, while India's diagnostic manufacturing capacity draws sponsor investment toward volume-access strategies. CDSCO orphan drug provisions and PMDA regenerative medicine frameworks fragment regulatory pathways across the region.
Japan
Tokyo-Osaka hospital corridors anchor MECP2 mutation screening and cell therapy trial access. PMDA accelerated approval compresses development timelines for regenerative medicines targeting Rett syndrome. Academic medical centers at Tokyo Women's Medical University host the majority of regional interventional studies.
Australia
Sydney-Melbourne pediatric rehabilitation centers concentrate demand for behavioral therapy and home care transition services. TGA pediatric labeling requirements influence trial design for compounds seeking early approval. New South Wales and Victoria newborn screening protocol expansion deepens diagnostic penetration.
India
Tier-2 and Tier-3 cities present underpenetrated demand for MECP2 screening infrastructure. CDSCO tax incentives and waived registration fees redirect manufacturing investment toward local diagnostic production. Public-private partnership models could extend newborn testing coverage beyond metropolitan hubs.
South Korea
Seoul Capital Area academic medical centers develop gene therapy delivery mechanisms for rare neurological disorders. MFDS orphan drug designation provides expedited review pathways for novel interventions. Busan-Ulsan bioclusters host contract manufacturing capacity for cell therapy scale-up.
Singapore
Specialized pediatric neurology referral networks serve as a regional hub for Southeast Asian Rett syndrome diagnosis. HSA regulatory alignment with ICH standards attracts multi-site trial coordination. Biomedical research institutes validate biomarker assays for newborn screening expansion.
Asia Pacific Rett Syndrome Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in the supply structure. The market fragments across multinational neurology franchises, cell therapy developers, and cost-accessible manufacturers. Three archetypes dominate: Japanese pharmaceutical conglomerates with orphan drug portfolios, Australian biotechnology specialists in regenerative medicine, and Indian generic manufacturers extending into rare disease indications. Competitive moves center on parallel regulatory submission capabilities and manufacturing footprint reconfiguration.
Within the neurology franchise tier, Eisai Co., Ltd. occupies a position exemplifying platform integration across rare disease portfolios. Among cell therapy specialists, Neurotech International Ltd. and Neurotech International Ltd. represent the regenerative medicine archetype targeting neurological indications. Indian manufacturers including Zydus Cadila anchor the cost-accessible production tier, extending generic and biosimilar capabilities into orphan drug categories.
| Leading Market Players |
|---|
| Eisai Co., Ltd. |
| Neurotech International Ltd. |
| Zydus Cadila |
| Viatris Inc. |
| Hikma Pharmaceuticals PLC |
| LUPIN |
| Teva Pharmaceutical USA |
| Dr. Reddy's Laboratories Ltd. |
| Sun Pharmaceutical Industries Ltd. |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in Japanese cell therapy manufacturing capacity is driving sponsor behavior toward premium pricing postures while compressing development timelines. PMDA accelerated approval pathways reward early movers with reimbursement advantages that offset India's volume-access manufacturing economics.
Pricing Analysis
PMDA's regenerative medicine framework dictates the pricing tier structure across the Asia Pacific Rett syndrome landscape. Three-tier pricing separates gene therapy interventions from small-molecule symptom management from generic supportive care. Brand premiums attach to Tokyo-Osaka academic medical center provenance and PMDA orphan drug designation. Cost compression in diagnostic services is intensifying because CDSCO tax incentives are redirecting manufacturing toward Indian generic production. Tier-2 Indian cities exhibit highest price sensitivity; Japanese long-term care insurance beneficiaries show lowest elasticity.
Supply Chain Analysis
Upstream plasmid DNA and viral vector feedstocks draw from contract manufacturing networks concentrated in South Korea, Singapore, and Japan. MECP2 mutation assay components rest on specialized reagent supply chains anchored in the United States and Germany. Single-source vulnerability permeates gene therapy raw material sourcing, with few qualified suppliers for GMP-grade viral vectors. Distribution runs through hospital pharmacy consortia in Japan and Australia's state-based metabolic services procurement frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
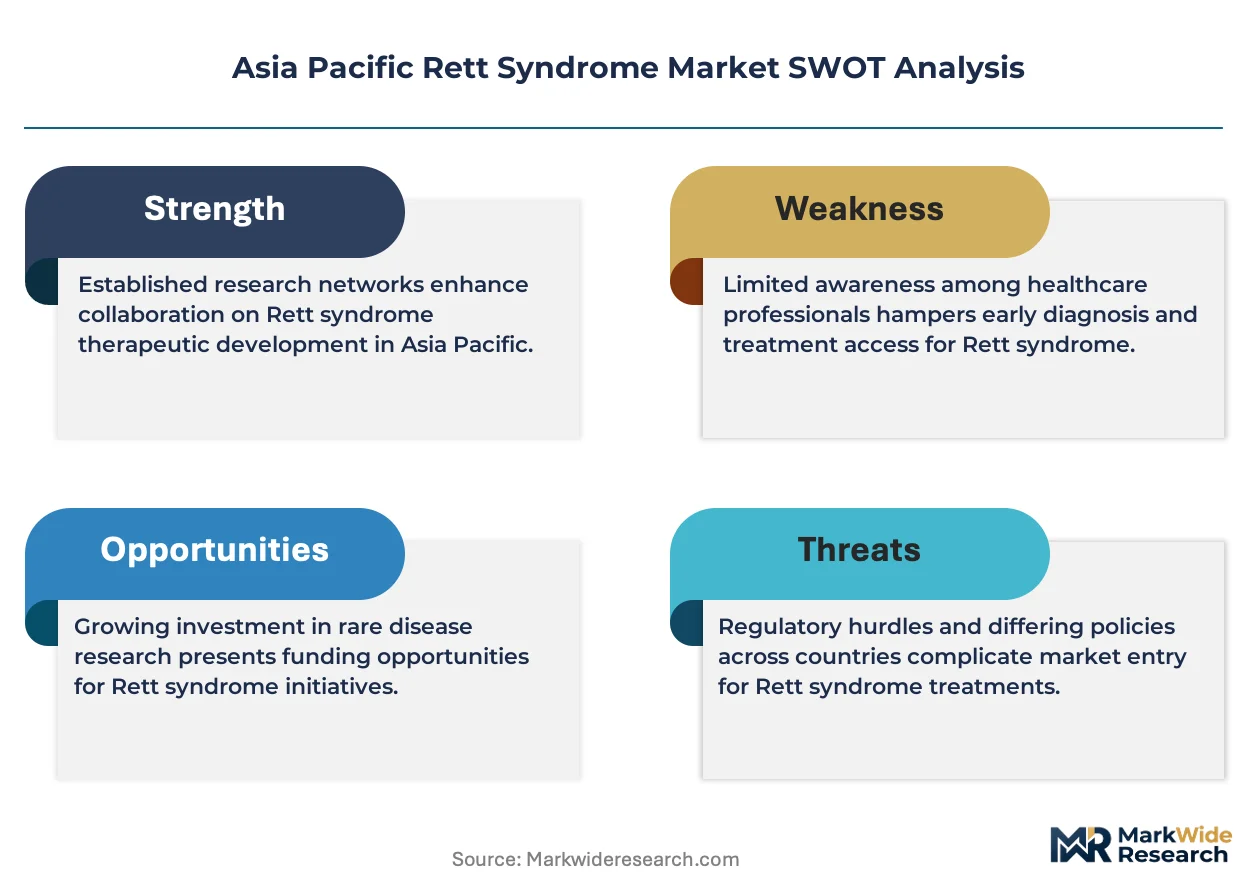
Pediatric neurology specialist scarcity constrains diagnostic throughput and trial enrollment velocity across the region. The gap between Tokyo-Osaka corridor expertise and Tier-2 Indian city access represents the decisive capability bottleneck.
For Market Incumbents: Entrench diagnostic gateway control by embedding MECP2 screening protocols within Japan's 357 designated rare disease consultation hubs. Expand backward integration into viral vector manufacturing to secure supply continuity against Korean biocluster capacity constraints. Cell therapy developers threaten first-mover advantage through PMDA regenerative medicine fast-track exploitation.
For New Entrants and Emerging Players: Tier-2 and Tier-3 Indian cities represent the most penetrable entry point for MECP2 screening infrastructure deployment. Australia's National Disability Insurance Scheme plan management channels offer white-space access for home-based rehabilitation technology platforms. Public-private partnership models with state governments provide the most viable go-to-market angle for diagnostic market development.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among behavioral therapy providers integrated with Japan's long-term care insurance digitization and Australia's NDIS funding streams. Five-to-ten year viability hinges on regulatory submission capabilities spanning PMDA, TGA, and CDSCO pathways. Platform integrators with parallel approval track records represent the preferred acquisition archetype. Cell therapy manufacturing scale-up decisions preceding pivotal trial design serve as the critical inflection signal to monitor.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Parallel Submission Capability | PMDA-TGA-CDSCO alignment compresses time-to-market across divergent approval frameworks. |
| Manufacturing Footprint Reconfiguration | Indian CDSCO incentives redirect diagnostic production toward volume-access cost structures. |
| Home Care Service Integration | NDIS and Japanese long-term care insurance digitization shift payment toward community-based management. |
| Pediatric Neurology Specialist Pipeline Expansion | Academic medical center training partnerships address diagnostic throughput constraints in metropolitan hubs. |
| Biomarker Assay Validation | Singapore HSA-aligned research institutes anchor newborn screening protocol expansion across Southeast Asia. |
Study Parameters
Operator-level perspectives from pediatric neurologists, regulatory affairs leads at orphan drug sponsors, hospital formulary directors, and National Disability Insurance Scheme plan managers anchored the qualitative base. Primary interviews combined with secondary validation from PMDA approval databases, TGA pediatric labeling guidelines, CDSCO orphan drug registration records, and ClinicalTrials.gov interventional study listings. Bottom-up patient flow modeling and top-down reimbursement spend analysis provided triangulation across value estimation approaches.
Scenario-bracketing framed the analytical approach across the projection horizon, with sensitivity testing on regulatory approval timing and manufacturing scale-up velocity. Segmentation dimensions included product type, treatment approach, end user category, and distribution channel structure. CAGRs derived from patient population epidemiology, diagnostic penetration curves, and reimbursement framework evolution. Gene therapy delivery mechanism advancement rates and cell therapy manufacturing cost decline trajectories served as industry-specific forecast inputs.
Practitioners should monitor PMDA regenerative medicine framework revisions and CDSCO tax incentive renewals for early signals of forecast revision. Cross-checking against hospital procurement database benchmarks and GPO contract pricing disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Creutzfeldt-Jakob Disease (CJD) Market
Rare Diseases
Dystrophic Epidermolysis Bullosa Treatment Market
Rare Diseases
Global Neuromyelitis Optica Spectrum Disorder Market
Rare Diseases
Chronic Granulomatous Disease Market
Rare Diseases
Down Syndrome Market
Rare Diseases
Rare Disease Clinical Trials Market
Rare Diseases
Yellow Nail Syndrome Treatment Market
Rare Diseases
Fabry Disease Market
Rare Diseases
Dystrophic Epidermolysis Bullosa Management Market
Rare Diseases
Andersen-Tawil Syndrome Market
Rare Diseases
Middle East and Africa Rett Syndrome Market
Rare Diseases
Global Rare Hemophilia Factors Market
Rare Diseases
Orphan Diseases Market
Rare Diseases
Rare Neurological Disease Treatment Market
Rare Diseases
Global Hemoglobinopathies Market
Rare Diseases
Byler Disease Market