
 Chronic Granulomatous Disease Market | 2026-2036
Chronic Granulomatous Disease Market Size, Share, and Industry Trends Forecast 2026-2036
Chronic Granulomatous Disease Market Intelligence
The shift of complex case management towards specialized Immunology Centers is redrawing the care landscape for chronic granulomatous disease. This trend favors companies with highly targeted therapeutic pipelines. Pfizer Inc. leverages its extensive experience in immunomodulators, while Novartis AG sustains a strong research focus on genetic disorders. Orchard Therapeutics plc specializes in developing advanced gene therapies for rare diseases, positioning itself at the forefront of curative treatments.
Chronic granulomatous disease is a primary immunodeficiency disorder characterized by the inability of phagocytic cells to produce reactive oxygen species. This defect stems from mutations in genes encoding the NADPH oxidase enzyme complex, leading to severe and recurrent infections. While antibiotics and antifungals form the foundational product segment, emerging Gene Therapy options promise curative potential. Consequently, delivery modes are evolving from standard oral medications to complex procedures like bone marrow transplant and ex-vivo gene editing.
Regulatory frameworks from the US FDA and the European Medicines Agency (EMA) heavily influence market entry for new CGD treatments. Orphan drug designations and accelerated approval pathways are essential for commercializing novel therapies. The successful navigation of these regulatory channels determines the viability of next-generation treatments. Stakeholder focus is now on establishing reimbursement strategies that ensure patient access to high-cost curative options.
Market Dynamics
The fundamental dynamic shaping the chronic granulomatous disease market is the clinical and economic tension between lifelong prophylactic management and the advent of high-cost, single-administration curative therapies, a shift heavily influenced by new regulatory pathways for genetic medicines.
Growth Catalysts
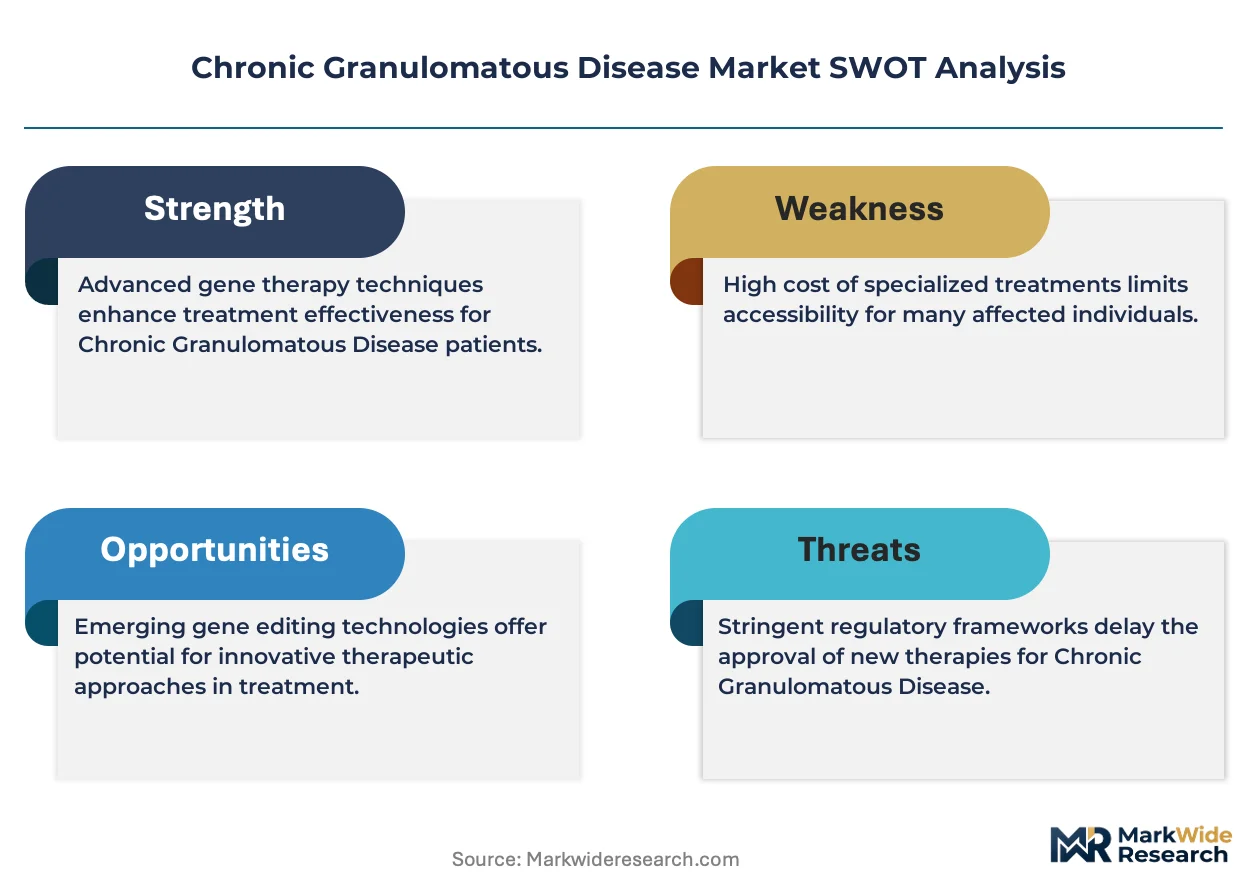
- Advanced Genetic Technologies:The refinement of gene editing tools, including lentiviral vectors for ex-vivo modification of hematopoietic stem cells, provides the foundational technology for developing potentially curative treatments for CGD.
- Favorable Regulatory Frameworks:The FDA's Regenerative Medicine Advanced Therapy (RMAT) designation provides an accelerated pathway for novel cell and gene therapies, encouraging investment and speeding up clinical development timelines for promising candidates.
- Consolidation of Care:The growing trend of managing CGD patients within specialized Immunology Centers improves diagnostic accuracy, standardizes treatment protocols, and creates centralized hubs for advanced therapy administration and clinical trial recruitment.
Market Restraints
- Prohibitive Treatment Costs:The exceptionally high price points associated with gene therapies and hematopoietic stem cell transplantation (HSCT) create significant access barriers, limiting their availability to patients in well-funded healthcare systems.
- Technical Hurdles in Gene Therapy:Challenges remain in ensuring the long-term durability and safety of gene-corrected cells, including risks associated with insertional mutagenesis from viral vectors and the toxicity of pre-transplant conditioning regimens.
- Expertise Concentration:The clinical expertise and infrastructure required to perform complex procedures like ex-vivo gene therapy are concentrated in a very small number of elite academic medical centers, creating a significant bottleneck for patient access.
Strategic Opportunities
- Geographic Expansion of Diagnostics:There is a significant opportunity to improve and expand newborn screening and genetic diagnostic services in developed countries like Italy and Spain, leading to earlier diagnosis and an increased treatable patient pool.
- In-Vivo Gene Editing:The development of next-generation in-vivo gene therapies, which could correct the genetic defect directly within the patient's body, represents a major opportunity to bypass the complexities of ex-vivo cell manufacturing.
- European Regulatory Incentives:Leveraging the EMA's PRIority MEdicines (PRIME) scheme offers enhanced scientific and regulatory support, providing a strategic pathway for developers to accelerate the approval of CGD therapies in Europe.
Industry Challenges
- Specialized Talent Scarcity:A critical shortage of personnel with expertise in GMP-compliant manufacturing of cell and gene therapies, as well as clinicians trained in their administration, constrains the ability to scale up treatment capacity.
- Reimbursement Model Complexity:Developing sustainable payment and reimbursement models for high-cost, one-time curative treatments is a major operational hurdle, requiring extensive negotiation with payers and health technology assessment bodies.
- Lengthy Clinical Validation:The long-term follow-up required by regulators like the FDA and EMA to prove the durability and safety of gene therapies extends clinical trial timelines and delays commercial availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chronic Granulomatous Disease Market |
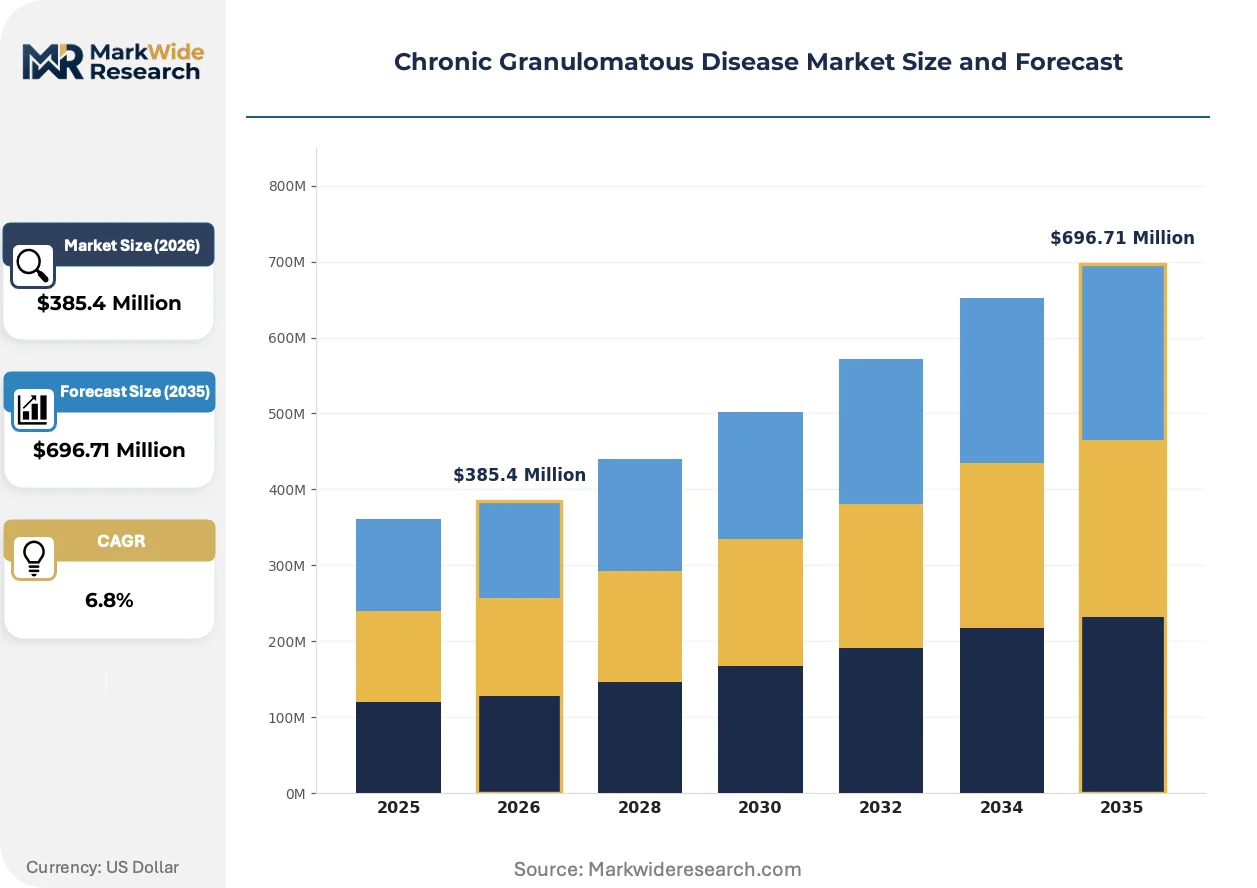
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $696.71 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Therapy Area: Immune Deficiency Disorders, Genetic Disorders, Pediatric Immunology, Rare Diseases Product Type: Antibiotics, Antifungals, Immunomodulators, Gene Therapy, Enzyme Replacement Delivery Mode: Oral Medication, Intravenous Injection, Subcutaneous Injection, Bone Marrow Transplant, Gene Editing End User: Specialty Clinics, Research Laboratories, Academic Hospitals, Immunology Centers |
| Companies Covered | ViroMed Co. Ltd, Pfizer Inc, Clinigen Group plc, Novartis AG, Hoffmann-La Roche Ltd, Orchard Therapeutics plc, Bellicum Pharmaceuticals, Inc, GlaxoSmithKline plc, Horizon Therapeutics plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chronic Granulomatous Disease Market Strategic Shifts & Innovations
The therapeutic paradigm for chronic granulomatous disease is undergoing a fundamental transformation from chronic symptom management to curative intervention. This evolution is driven by breakthroughs in genetic science that are redefining clinical pathways, patient expectations, and the economic structure of treatment.
Ex-vivo autologous gene therapy, a process that corrects the genetic mutation in a patient's own hematopoietic stem cells outside the body, is a key innovation. It is being adopted within advanced clinical trials at specialized immunology centers for patients who do not have a suitable matched donor for a traditional transplant. This personalized methodology is displacing allogeneic bone marrow transplantation for specific patient profiles by mitigating the severe risk of graft-versus-host disease.
Orphan Drug Designation, a policy tool used by the US FDA and the European Medicines Agency, provides powerful incentives for therapeutic development in rare diseases. These designations offer benefits such as market exclusivity periods, tax credits, and reduced regulatory fees, which substantially de-risk the high cost of R&D. The gene therapy product segment is the primary beneficiary, as these incentives are essential for attracting capital to advance novel CGD treatments through expensive clinical trials.
A clear behavioral shift involves the growing preference among patients and clinicians for treatments offering a potential cure over lifelong prophylactic management. This trend is disrupting the established reliance on long-term antibiotic and antifungal drug regimens, with patient advocacy organizations actively promoting access to definitive therapies. This demand is most visible in the United States and Germany, where sophisticated healthcare infrastructure supports the complex delivery and reimbursement of high-value genetic medicines.
Chronic Granulomatous Disease Market Segmentation
Segmentation analysis within the chronic granulomatous disease market provides a detailed understanding of where value is created and captured across various therapeutic approaches and delivery mechanisms. This granular view helps stakeholders identify key growth areas and allocate resources effectively for both established and emerging treatments.
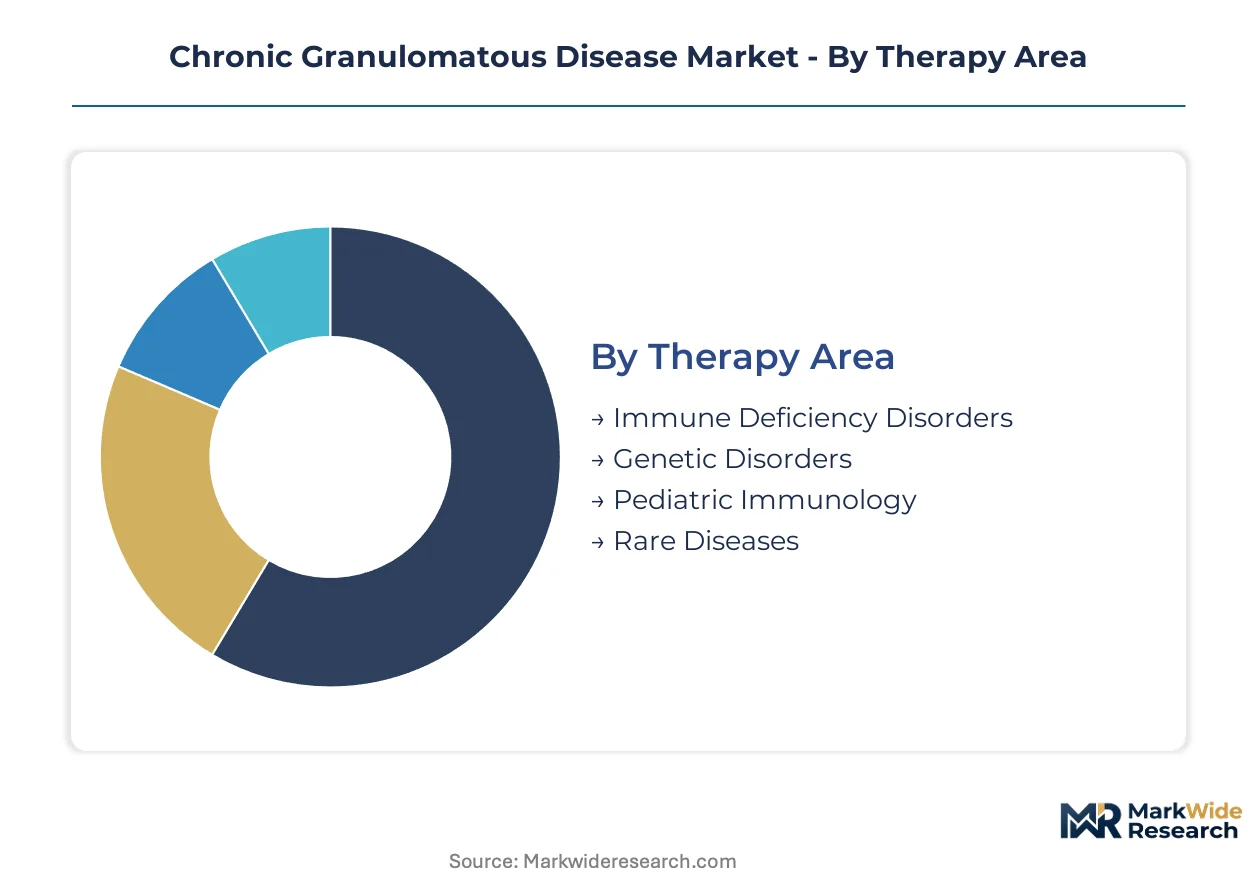
Therapy Area:
Margin pools within the chronic granulomatous disease market's therapy area segmentation are significantly influenced by the complexity and novelty of treatments.
- Gene Therapy:These advanced treatments focus on correcting the underlying genetic defect in CGD patients, often involving ex-vivo modification of hematopoietic stem cells. Demand concentrates in countries with advanced regulatory frameworks like the United States, driven by the potential for a curative outcome.
- Rare Diseases:This segment encompasses therapies developed under orphan drug designations, benefiting from market exclusivity and tax credits provided by regulators like the FDA and EMA. Demand is high in regions like Germany, where patient advocacy supports access to high-cost, specialized treatments.
- Immune Deficiency Disorders:This broad category includes treatments addressing the compromised immune function characteristic of CGD, often involving prophylactic measures.
- Pediatric Immunology:Therapies in this area specifically target younger CGD patients, considering their unique physiological responses and long-term care needs.
Immune Deficiency Disorders holds installed capacity. Gene Therapy is rotating up the share rankings.
Product Type:
Supply concentration for chronic granulomatous disease product types varies significantly, reflecting manufacturing complexity and regulatory pathways.
- Gene Therapy:These products involve complex biological manufacturing processes, often leveraging viral vectors for gene delivery. Demand is high in specialized immunology centers in Japan, driven by the pursuit of curative interventions.
- Immunomodulators:These therapies modulate the immune response to reduce inflammation and infection susceptibility, often requiring precise dosing. Demand is consistent across developed healthcare systems like Canada, supporting long-term patient management.
- Antibiotics:These foundational treatments manage recurrent bacterial infections in CGD patients, forming a critical part of prophylactic care.
- Antifungals:These medications prevent and treat fungal infections, which pose a significant threat to individuals with CGD.
- Enzyme Replacement:This segment includes therapies that aim to replace deficient enzymes, though less prominent for CGD compared to other genetic disorders.
Antibiotics form a foundational segment. Gene Therapy is expanding most quickly.
Delivery Mode:
Application complexity profoundly shapes the market dynamics within the chronic granulomatous disease delivery mode segmentation.
- Gene Editing:This mode involves highly specialized ex-vivo procedures to modify a patient's own hematopoietic stem cells, requiring advanced surgical and laboratory infrastructure. Demand is emerging in elite academic medical centers in France, driven by clinical trial advancements.
- Bone Marrow Transplant:This established curative intervention for CGD involves replacing defective bone marrow with healthy donor cells, a procedure with significant associated risks and recovery periods. Demand remains steady in countries like the United Kingdom, particularly for patients with matched donors.
- Oral Medication:This convenient delivery method includes daily antibiotics and antifungals for long-term prophylactic management of CGD.
- Intravenous Injection:This mode is commonly used for administering certain antibiotics, antifungals, and immunomodulators in hospital or clinic settings.
- Subcutaneous Injection:This less invasive method allows for home administration of some immunomodulators, improving patient convenience and adherence.
Oral Medication remains a primary delivery route. Gene Editing is climbing the fastest.
End User:
Customer type needs dictate the specific infrastructure and service offerings required across the chronic granulomatous disease end user segments.
- Immunology Centers:These specialized facilities provide comprehensive diagnostic, treatment, and long-term management services for complex immune disorders like CGD. Demand for advanced gene therapies is concentrated here, especially in the United States, due to their specialized expertise and infrastructure.
- Academic Hospitals:These institutions combine patient care with medical research and education, often serving as referral centers for rare diseases and conducting clinical trials for novel CGD treatments. Demand for complex procedures like bone marrow transplants is high in major cities across Italy.
- Specialty Clinics:These clinics offer focused care for specific conditions, including aspects of CGD management, often collaborating with larger immunology centers.
- Research Laboratories:These facilities are crucial for developing new diagnostic tools and therapeutic interventions for CGD, contributing to long-term market innovation.
Specialty Clinics provide foundational support. Immunology Centers are on the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer-archetype concentration in the chronic granulomatous disease market centers on highly specialized immunology centers and academic hospitals. These facilities serve as critical hubs for advanced diagnostics and complex treatment administration. Demand for innovative gene therapies drives this geographic consolidation of expertise.
United States
Demand for advanced gene therapies in the United States is strong, driven by a sophisticated healthcare infrastructure. The FDA's Regenerative Medicine Advanced Therapy (RMAT) designation accelerates development for promising candidates. The Boston-Cambridge biotech hub remains a focal point for gene therapy research and clinical trials.
Germany
German patient advocacy groups support access to high-cost, specialized CGD treatments. The European Medicines Agency's (EMA) PRIME scheme offers enhanced scientific support for novel therapies. The Munich region hosts numerous biotech firms and academic medical centers for rare disease research.
Japan
The pursuit of curative interventions drives demand for complex biological products in Japan. The PMDA's accelerated review pathways facilitate the market entry of regenerative medicines. Tokyo's medical innovation districts focus on advanced gene therapy clinical applications.
United Kingdom
Established curative interventions like bone marrow transplants remain steady in the United Kingdom. The Medicines and Healthcare products Regulatory Agency (MHRA) oversees advanced therapy medicinal products. London's biomedical research campuses support specialized transplant centers.
Italy
Improved diagnostics and referral centers for rare diseases are key demand drivers in Italy. The Italian Medicines Agency (AIFA) supports access to orphan drugs. Milan's academic hospitals serve as crucial referral points for CGD patient management.
Chronic Granulomatous Disease Market Key Industry Players
Player mix skews toward established pharmaceutical companies and specialized biotech firms in the chronic granulomatous disease market. The market exhibits a tiered structure, with large diversified players alongside innovative rare disease specialists. Strategic archetypes include R&D-intensive gene therapy developers and broad-portfolio immunomodulator providers. Dominant competitive moves involve strategic partnerships for technology licensing and portfolio diversification into advanced therapies, aiming to capture emerging curative segments.
Within the R&D-intensive segment, Pfizer Inc. and Novartis AG occupy positions as diversified pharmaceutical corporations. Orchard Therapeutics plc exemplifies a specialized biotech firm, focusing on advanced gene therapies for rare diseases. These companies anchor the development of novel treatments, leveraging extensive research capabilities and regulatory expertise for complex biological products. Their strategies often involve navigating complex clinical trials and securing orphan drug designations for high-value therapeutic candidates, ensuring market access for groundbreaking therapies.
| Leading Market Players |
|---|
| ViroMed Co. Ltd |
| Pfizer Inc |
| Clinigen Group plc |
| Novartis AG |
| Hoffmann-La Roche Ltd |
| Orchard Therapeutics plc |
| Bellicum Pharmaceuticals, Inc |
| GlaxoSmithKline plc |
| Horizon Therapeutics plc |
| Others |
Cost & Logistics Intelligence
Contract-based long-term agreements for novel gene therapies lock in both supply access and price visibility for specialized immunology centers. These agreements often involve complex negotiation with payers in advanced healthcare systems like the United States.
Pricing Analysis
Cost-plus pricing, indexed to R&D intensity, dominates the gene therapy segment within the chronic granulomatous disease market. Value-based pricing models are emerging for curative treatments, linking payment to long-term patient outcomes. Price differentiation stems from the curative potential of gene therapies and the specific regulatory designations, such as FDA's RMAT. Pricing pressure arises from the significant reimbursement challenges associated with high-cost single-administration therapies. Payers and national health systems exhibit high price sensitivity, while patient advocacy groups prioritize access regardless of cost.
Supply Chain Analysis
Specialized manufacturing infrastructure for viral vectors, primarily concentrated in the United States and Germany, underwrites the gene therapy supply chain. This chain relies heavily on highly purified plasmids, specialized cell culture media, and GMP-compliant facilities. A significant structural risk involves the scarcity of personnel with expertise in cell and gene therapy manufacturing. Distribution runs through a highly centralized model, leveraging elite academic medical centers and specialized immunology centers for complex ex-vivo procedures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The chronic granulomatous disease market is experiencing high-growth disruption, driven by breakthroughs in gene therapy and the advent of curative interventions.
For Market Incumbents: Fortify existing market positions by deepening R&D investments in next-generation gene editing technologies, particularly in-vivo approaches. This mitigates the threat from specialized biotechs focusing solely on ex-vivo therapies. Leverage extensive regulatory expertise to navigate complex approval pathways for advanced treatments, securing early market access in key regions like the European Union. Invest in specialized manufacturing capabilities for complex biological products.
For New Entrants and Emerging Players: Differentiate on technological novelty by focusing on in-vivo gene editing solutions that bypass ex-vivo manufacturing complexities. Target underpenetrated diagnostic markets in Southern European countries like Italy and Spain, leading to earlier patient identification. Collaborate with patient advocacy organizations to build trust and demonstrate therapy value, facilitating market entry. Develop innovative reimbursement models that align with long-term curative outcomes.
For Investors and Strategic Acquirers: Specialized gene therapy developers with robust clinical pipelines represent compelling acquisition targets over the next five to ten years. These firms possess critical intellectual property and expertise in complex biological manufacturing. A key signal to watch is the successful completion of Phase 3 clinical trials for RMAT-designated candidates, indicating regulatory and clinical validation. Focus on companies with established platforms for rare disease indications.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerates regulatory approval pathways for novel gene therapies in the United States. |
| Manufacturing Scale-Up | Ensures sufficient supply of complex biological products for global patient populations. |
| Strategic Partnership | Leverages established pharmaceutical distribution networks for specialized treatments. |
| Pipeline Diversification | Reduces reliance on single therapeutic modalities by exploring new genetic targets. |
| Regulatory Approval Pathway | Secures market exclusivity and premium pricing for orphan drug designations in Europe. |
Research Approach
A spread of perspectives from drug development executives, regulatory affairs leads, formulary directors, and immunology specialists converged on the working assumptions for the chronic granulomatous disease market. Primary interviews were triangulated with extensive secondary validation from sources including FDA filings, EMA submissions, ClinicalTrials.gov, and peer-reviewed scientific literature. This comprehensive approach ensured a robust bottom-up and top-down understanding of market dynamics.
Market segmentation dimensions modeled included therapy area, product type, delivery mode, end user, and regional regulatory clusters. The analytical framework projected market expansion over the forecast period by integrating historical data with anticipated shifts in treatment paradigms. Compound annual growth rates were derived from a multi-factor analysis considering gene therapy pipeline progression and evolving regulatory approval rates for rare diseases.
Forecasts assume regulatory continuity in the United States and European Union; material policy shifts would require re-modeling market projections. These forecasts reflect assumptions regarding reimbursement policy stability and the long-term safety data for emerging gene therapies. Practitioners should keep alternative scenarios live as clinical trial outcomes and payer acceptance criteria evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Achondrogenesis Market
Rare Diseases
Cowden Syndrome Market
Rare Diseases
Hutchinson Gilford Progeria Syndrome (HGPS) Therapeutics Market
Rare Diseases
Niemann-Pick Disease Type C Therapeutics Market
Rare Diseases
Rare Disease Clinical Trials Market
Rare Diseases
Aarskog Scott Syndrome Treatment Market
Rare Diseases
North America Down Syndrome Market
Rare Diseases
Fragile X Syndrome Market
Rare Diseases
Chronic Granulomatous Disease (CGD) Management Market
Rare Diseases
Krabbe Disease Treatment Market
Rare Diseases
Sanfilippo Syndrome Market
Rare Diseases
Zellweger Spectrum Disorders Market
Rare Diseases
Rosai-Dorfman Disease (RDD) Therapeutics Market
Rare Diseases
Pompe Disease Market
Rare Diseases
Byler Disease Market
Rare Diseases
Congenital Adrenal Hyperplasia Market