
 Global Hemoglobinopathies Market | 2026-2036
Global Hemoglobinopathies Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hemoglobinopathies Market Intelligence
The U.S. Food and Drug Administration's accelerated approval pathway for orphan drugs is expanding the addressable market for novel hemoglobinopathy treatments by reducing development timelines. This regulatory shift benefits companies pioneering curative approaches. Vertex Pharmaceuticals specializes in gene-editing therapies for sickle cell disease and beta-thalassemia. Concurrently, bluebird bio leverages its expertise in lentiviral vector gene addition therapies. CRISPR Therapeutics also competes directly in this space with its own gene-editing platform, creating a dynamic innovation landscape.
Hemoglobinopathies are a group of inherited blood disorders characterized by the abnormal structure or production of the hemoglobin protein, which impairs the blood's ability to transport oxygen. The two most prevalent conditions are sickle cell disease and thalassemia. Within the market's structure, the therapy area segment is dominated by treatments for these two conditions. While established therapeutic agents like hydroxyurea and iron chelators constitute a large part of the product type segment, gene therapy represents the fastest-growing category, promising one-time curative potential.
The regulatory environment is governed by agencies such as the U.S. FDA and the European Medicines Agency (EMA), which set stringent standards for the clinical efficacy and safety of new therapies. These bodies, along with Japan's PMDA, define the evidence required for marketing authorization, directly impacting market access. The primary challenge for developers now shifts to demonstrating long-term value to payers to secure reimbursement for these high-cost, transformative treatments.
Market Dynamics
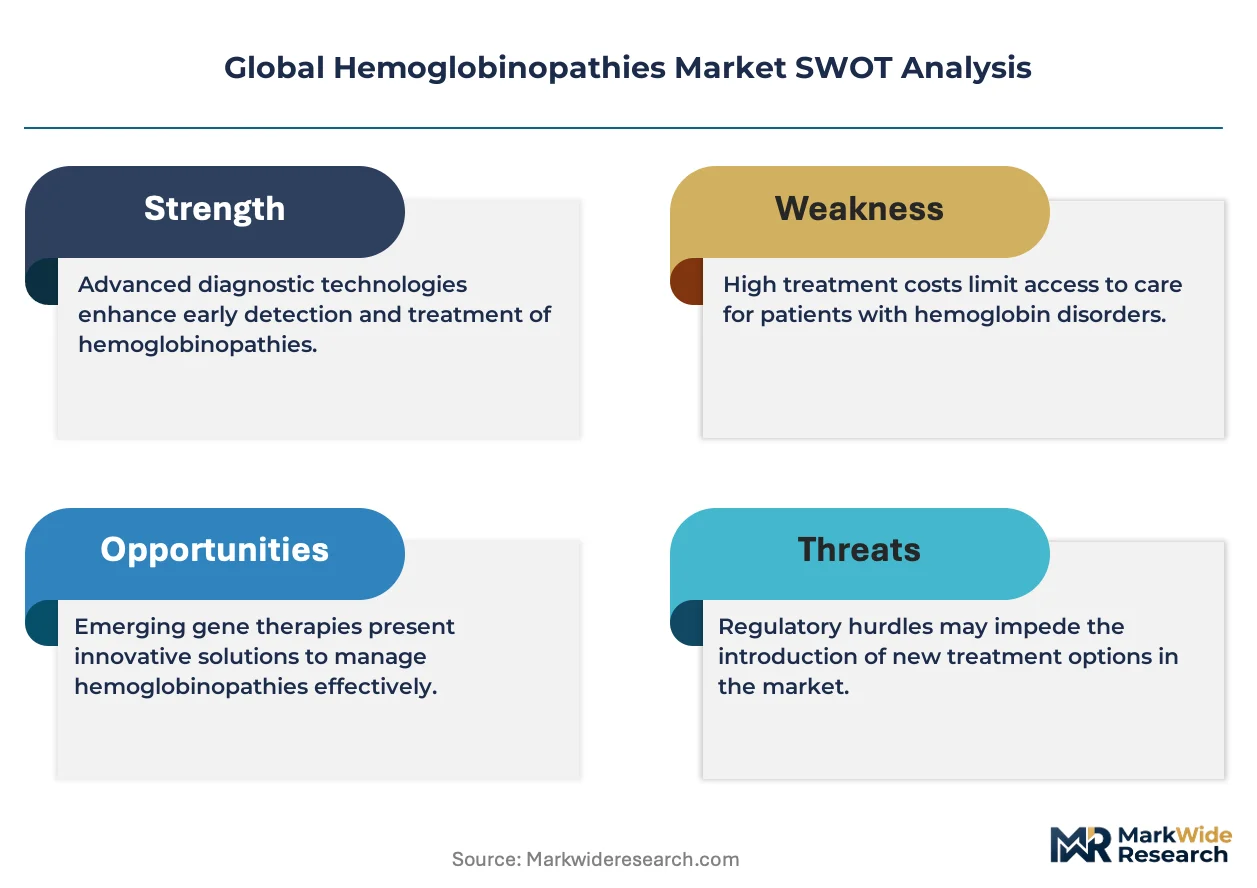
The central dynamic in the hemoglobinopathies market is the tension between the arrival of potentially curative gene therapies and the immense financial and logistical strain these high-cost treatments place on healthcare systems, payers, and patients, forcing a re-evaluation of value and access models.
Growth Catalysts
- Regulatory Pathways:The U.S. FDA's accelerated approval and orphan drug designations are shortening development timelines for novel therapies, encouraging investment in treatments for rare blood disorders.
- Diagnostic Technology:Advances in next-generation sequencing and newborn screening programs enhance early and accurate diagnosis of sickle cell disease and thalassemia, expanding the identifiable patient population for intervention.
- Care Infrastructure:The proliferation of specialized treatment clinics, particularly in North America and Europe, provides the necessary infrastructure for administering complex treatments like gene therapy and managing patient care.
Market Restraints
- Prohibitive Treatment Costs:The multi-million dollar price tags associated with one-time gene therapies create significant affordability and reimbursement hurdles, limiting patient access even in developed markets.
- Manufacturing Complexity:The production of lentiviral vectors for gene addition therapies is a highly specialized, resource-intensive process, leading to supply bottlenecks and high manufacturing costs.
- Long-Term Safety Concerns:Potential long-term risks, including off-target effects from CRISPR-based editing and insertional mutagenesis from viral vectors, necessitate extensive and costly long-term patient follow-up studies.
Strategic Opportunities
- Emerging Markets Access:Developing and deploying affordable diagnostic tools and established therapies like hydroxyurea in high-prevalence, underpenetrated regions such as Sub-Saharan Africa and Southeast Asia presents a major volume opportunity.
- AI in Patient Stratification:The convergence of artificial intelligence with genomic data analysis offers an opportunity to better predict patient response to specific therapies, optimizing clinical trial design and personalizing treatment.
- Alternative Delivery Systems:Research into non-viral delivery methods for gene-editing components, such as lipid nanoparticles, could reduce manufacturing complexity and improve the safety profile of future therapies.
Industry Challenges
- Specialized Talent Scarcity:A shortage of hematologists, genetic counselors, and technicians with expertise in cell and gene therapy protocols hinders the broader rollout of these advanced treatments beyond major academic centers.
- Reimbursement Model Negotiation:Developers face the challenge of creating novel payment models, such as annuity-based or outcome-contingent payments, to persuade public and private payers to cover high-cost curative treatments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hemoglobinopathies Market |
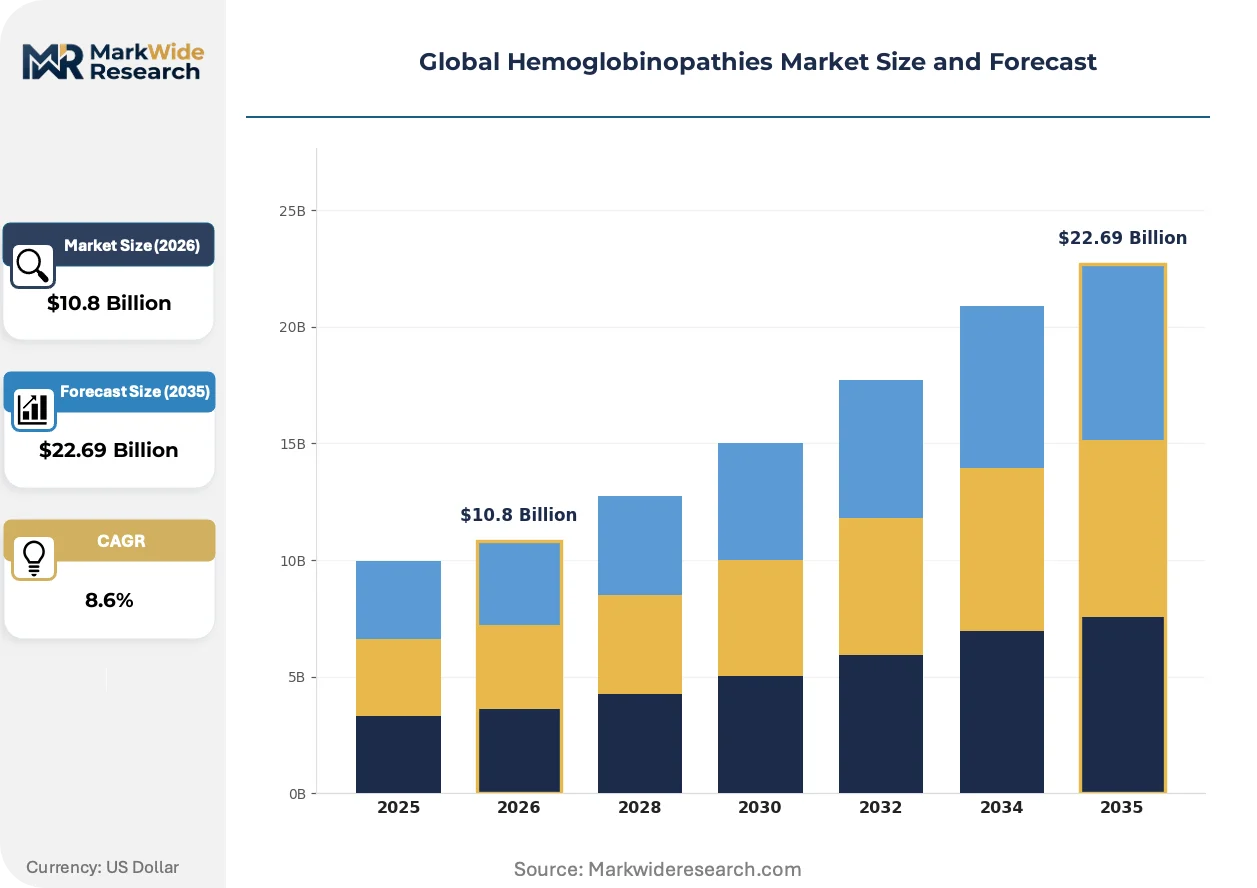
| Market Size in 2026 | $10.8 Billion |
| Market Size in 2035 | $22.69 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Kits, Therapeutic Agents, Gene Therapy, Screening Tools, Monitoring Devices Therapy Area: Sickle Cell Disease, Thalassemia, Hemoglobin C Disease, Hemoglobin E Disease, Hemoglobin D Disease End User: Specialty Clinics, Diagnostic Laboratories, Research Institutes, Blood Banks, Patient Support Centers Delivery Mode: Oral Medication, Intravenous Therapy, Subcutaneous Injection, Gene Editing Platforms, Blood Transfusion |
| Companies Covered | bluebird bio, Inc., Pfizer, Inc., Novartis AG, Vertex Pharmaceuticals, Global Blood Therapeutics, Inc., Emmaus Life Sciences Inc., CRISPR Therapeutics, Sangamo Therapeutics, Inc., Bioverativ Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hemoglobinopathies Market Strategic Shifts & Innovations
The clinical and commercial landscape for hemoglobinopathies is being transformed by the industrialization of curative science. This shift moves treatments from bespoke laboratory procedures toward scalable, regulated medical products, a transition that influences technology, regulation, and patient care delivery models.
CRISPR-based gene-editing systems provide a programmable platform for correcting the specific genetic mutations that cause sickle cell disease and beta-thalassemia. Biopharmaceutical companies are rapidly adopting these toolkits to progress therapies through clinical trials. This development is modularizing the therapeutic design process, enabling researchers to interchange components like guide RNAs and delivery mechanisms to address different genetic variants more efficiently.
The European Medicines Agency's PRIME (PRIority MEdicines) scheme provides early and enhanced scientific and regulatory support for medicines with significant therapeutic potential. This framework facilitates an accelerated assessment of novel hemoglobinopathy treatments that address a high unmet medical need. Consequently, gene therapy developers are most affected, adapting clinical development plans to generate evidence that satisfies the EMA's criteria for early access and ongoing evaluation.
Patient and provider preferences are evolving from a model of chronic disease management toward a demand for one-time, potentially curative interventions. This change disrupts the traditional pharmaceutical business model reliant on long-term medication sales, shifting the point of care to highly specialized hospital-based treatment centers. This trend is most pronounced in the United States, where the first gene therapies have received regulatory approval and are navigating complex reimbursement negotiations.
Global Hemoglobinopathies Market Segmentation
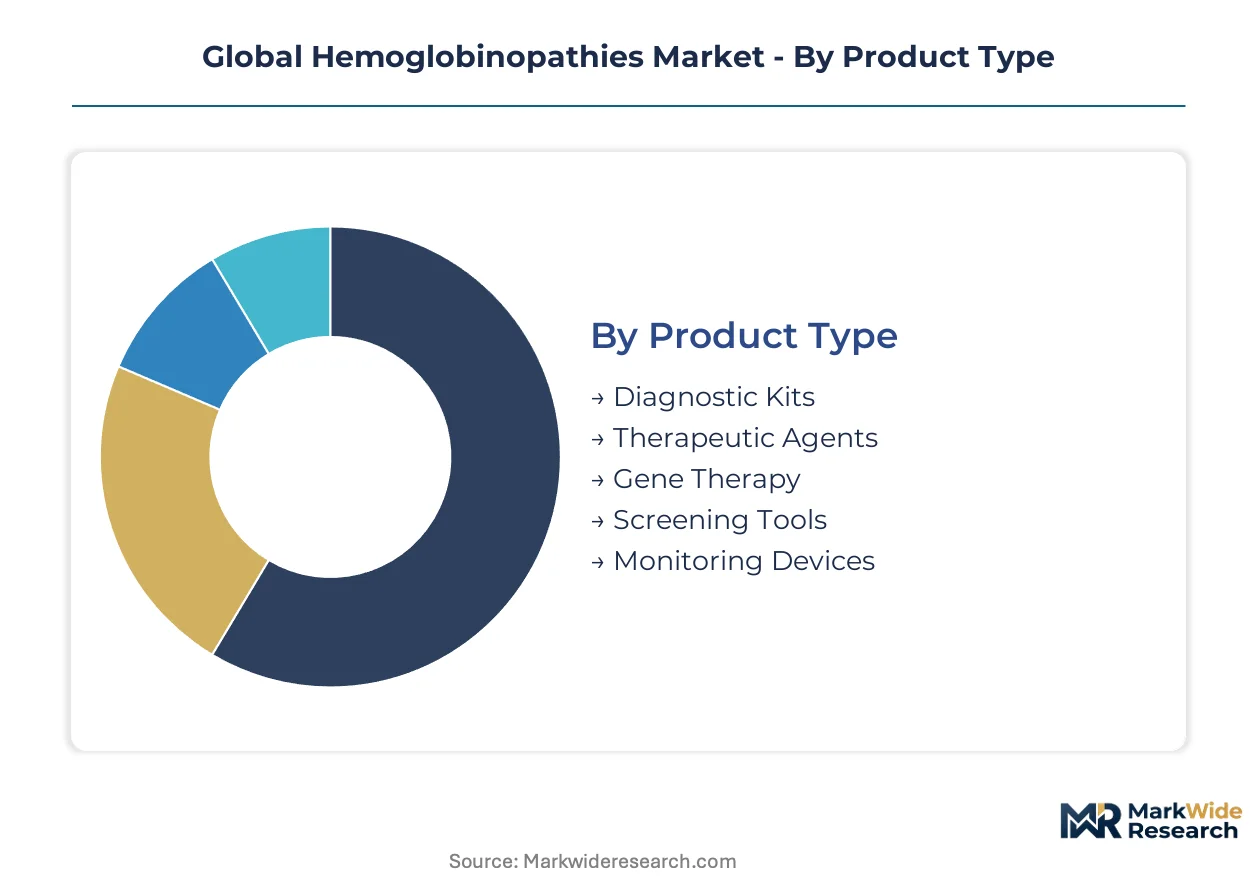
The global hemoglobinopathies market is systematically categorized to reveal distinct patient needs, therapeutic approaches, and delivery mechanisms. This structured view highlights where innovation is most impactful and where resource allocation can optimize patient outcomes across diverse populations.
Product Type:
Differentiation among product types is driven by their intended use, ranging from early detection to long-term curative interventions.
- Gene Therapy:These advanced treatments modify a patient's genetic material to correct the underlying cause of hemoglobin disorders. Demand for gene therapy is concentrating in high-income countries like the United States, driven by robust regulatory pathways and significant investment in research infrastructure.
- Therapeutic Agents:This category encompasses pharmaceutical compounds designed to manage symptoms, reduce disease complications, or improve quality of life for patients. Established agents like hydroxyurea maintain a significant market presence, particularly in regions with limited access to advanced therapies.
- Diagnostic Kits:These kits offer tools for the identification of specific genetic mutations or abnormal hemoglobin variants. Early and accurate diagnosis is critical for effective disease management, especially in newborn screening programs in countries such as Italy and the United Kingdom.
- Screening Tools:These instruments and reagents facilitate population-level screening for hemoglobinopathies, identifying carriers and affected individuals.
- Monitoring Devices:This segment includes equipment used to track disease progression, treatment efficacy, and patient health parameters over time.
Therapeutic Agents lead volumes today; Gene Therapy is gaining share fastest.
Therapy Area:
The market's therapy area segmentation reflects the specific clinical targets and disease prevalence, guiding research and development efforts.
- Sickle Cell Disease:This inherited blood disorder affects red blood cells, causing pain crises, anemia, and organ damage. Significant patient populations exist in Sub-Saharan Africa and India, driving demand for both symptomatic and disease-modifying treatments.
- Thalassemia:Characterized by reduced or absent hemoglobin production, thalassemia often requires lifelong blood transfusions and iron chelation therapy. Countries around the Mediterranean, the Middle East, and Southeast Asia experience high prevalence.
- Hemoglobin C Disease:A milder form of hemoglobinopathy, individuals with Hemoglobin C disease typically experience mild anemia.
- Hemoglobin E Disease:This condition is common in Southeast Asia and can range from asymptomatic to severe, especially when co-inherited with beta-thalassemia.
- Hemoglobin D Disease:This variant is generally asymptomatic unless inherited with another hemoglobinopathy, such as sickle cell trait.
Sickle Cell Disease and Thalassemia collectively dominate the therapy area segment due to their high prevalence and severe clinical manifestations.
End User:
The end-user landscape reflects the specialized infrastructure required for diagnosis, treatment, and long-term management of hemoglobinopathies.
- Specialty Clinics:These dedicated medical centers provide comprehensive care for patients with complex blood disorders, often administering advanced treatments like gene therapy. The proliferation of such clinics in Germany and France facilitates access to cutting-edge interventions.
- Research Institutes:Academic and private research entities drive the discovery and development of novel diagnostic methods and therapeutic agents. Their activities are crucial for expanding the understanding of hemoglobinopathies and translating scientific breakthroughs into clinical practice.
- Diagnostic Laboratories:These facilities perform genetic testing and hemoglobin analysis to confirm diagnoses and identify carriers.
- Blood Banks:Blood banks supply the necessary transfusions for patients with severe anemia, particularly those with thalassemia.
- Patient Support Centers:These organizations offer educational resources, counseling, and advocacy for patients and their families.
Specialty Clinics and Research Institutes represent the primary revenue generators within the end-user segment.
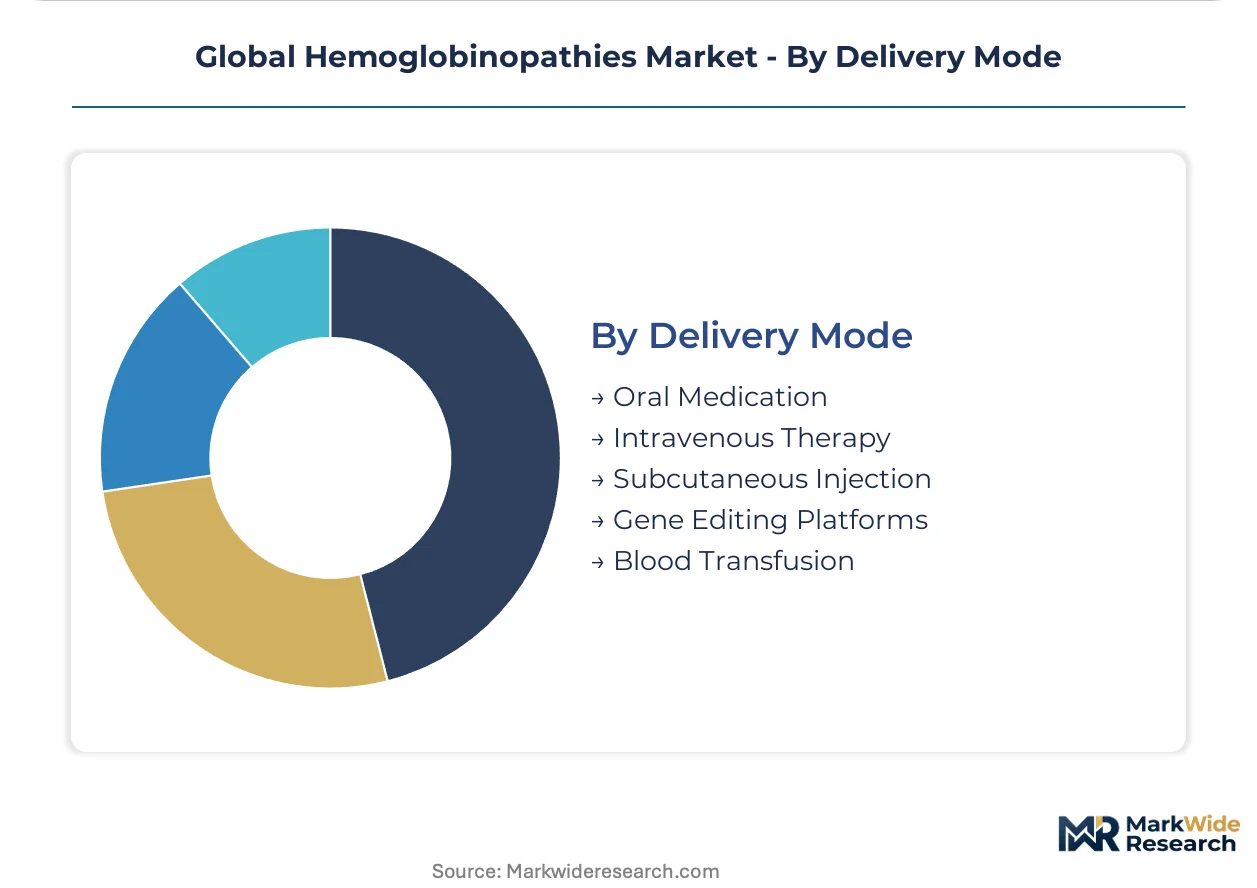
Delivery Mode:
The delivery mode segmentation highlights the diverse methods by which therapies are administered, impacting patient convenience and treatment efficacy.
- Gene Editing Platforms:This mode involves ex vivo or in vivo delivery of genetic material to correct disease-causing mutations. These platforms represent a paradigm shift towards curative therapies, requiring highly specialized infrastructure and expertise.
- Intravenous Therapy:Many established treatments, including blood transfusions and some therapeutic agents, are administered directly into the bloodstream. This method ensures rapid systemic distribution of the therapeutic compound.
- Oral Medication:This convenient delivery method is suitable for long-term management of symptoms or disease modification, such as with hydroxyurea.
- Subcutaneous Injection:This less invasive method allows for self-administration of certain medications, improving patient adherence and reducing clinic visits.
- Blood Transfusion:A cornerstone of thalassemia management, blood transfusions replace deficient red blood cells to alleviate anemia.
Gene Editing Platforms are experiencing the most rapid expansion in terms of technological advancement and investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The specialized talent pool for advanced treatments and robust research infrastructure across several nations anchors demand for hemoglobinopathy therapies. These regions drive innovation and adoption for gene therapies, shaping the market's global trajectory. Early diagnostic programs also expand the identifiable patient population in these key areas.
United States
Demand for novel hemoglobinopathy treatments concentrates heavily in the United States, driven by a robust research infrastructure. The U.S. FDA's accelerated approval pathway for orphan drugs shortens development timelines for novel therapies. Major academic medical centers and biotech hubs in Boston and San Francisco lead clinical trials and commercialization efforts for advanced gene therapies.
Germany
The proliferation of specialized treatment clinics in Germany provides the necessary infrastructure for administering complex treatments like gene therapy. The European Medicines Agency (EMA) sets stringent standards for clinical efficacy and safety, influencing market access for new therapies. Research institutes in cities like Munich and Berlin actively contribute to novel diagnostic methods and therapeutic agents.
Japan
Japan's market for hemoglobinopathy treatments benefits from advanced healthcare infrastructure and a focus on precision medicine. The Pharmaceuticals and Medical Devices Agency (PMDA) defines evidence requirements for marketing authorization, impacting market entry. Major pharmaceutical companies and research institutions in Tokyo and Osaka are investing in gene-editing technologies.
Italy
Early and accurate diagnosis of hemoglobinopathies, particularly thalassemia, expands the identifiable patient population in Italy. Newborn screening programs are critical for effective disease management and early intervention. Specialized hematology centers in Milan and Rome are at the forefront of administering advanced treatments and managing patient care.
Global Hemoglobinopathies Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists, creating a multi-tiered market structure for hemoglobinopathy treatments. The landscape includes established pharmaceutical companies alongside innovative biotechnology firms. Companies pursue strategic partnerships and advanced technology licensing agreements to accelerate pipeline development and market penetration.
Specialists in gene-editing and lentiviral vector gene addition therapies, such as bluebird bio and Vertex Pharmaceuticals, exemplify the innovative edge in this market. CRISPR Therapeutics also occupies a significant position with its proprietary gene-editing platform. These companies are navigating complex reimbursement negotiations to secure access for their high-cost, transformative treatments.
| Leading Market Players |
|---|
| bluebird bio, Inc. |
| Pfizer, Inc. |
| Novartis AG |
| Vertex Pharmaceuticals |
| Global Blood Therapeutics, Inc. |
| Emmaus Life Sciences Inc. |
| CRISPR Therapeutics |
| Sangamo Therapeutics, Inc. |
| Bioverativ Inc. |
| Others |
Cost & Logistics Intelligence
Gene therapy industrialization reshapes cost economics by requiring specialized manufacturing, concentrating supply in advanced biotech hubs. This transition impacts pricing models and accessibility for novel treatments.
Pricing Analysis
Bundled services, encompassing gene therapy administration and long-term patient follow-up, define the pricing structure for novel hemoglobinopathy treatments. Value-based pricing and outcome-contingent payments are emerging for high-cost gene therapies. Efficacy profile and regulatory approval status drive price differentiation, with curative approaches commanding premium pricing. Pricing pressure stems from payer negotiations seeking long-term value for multi-million dollar treatments. Public and private payers exhibit high price sensitivity, while patients, facing life-threatening conditions, prioritize curative potential.
Supply Chain Analysis
Specialized talent availability in manufacturing geographies like the United States and Germany is critical for producing advanced hemoglobinopathy therapies. Production of lentiviral vectors and CRISPR components concentrates in the United States, Germany, and Japan. The supply chain relies on highly specialized viral vectors, gene-editing components, and cell processing reagents. Manufacturing complexity creates supply bottlenecks and single-source vulnerability for critical components. Distribution runs through highly specialized hospital-based treatment centers and specialty clinics equipped for cold chain logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hemoglobinopathies market functions as a stable compounder, driven by the persistent unmet medical need for curative treatments. Regulatory support for orphan drugs further ensures consistent, long-term expansion.
For Market Incumbents: Hedge against the high-cost treatment reimbursement challenge by developing novel payment models, such as outcome-contingent agreements with payers. Invest in manufacturing scale-up for gene therapies to mitigate supply bottlenecks and lower per-unit costs. Expand clinical trial programs to include diverse patient populations in high-prevalence regions like Sub-Saharan Africa. R&D in alternative delivery systems, like lipid nanoparticles, offers a key lever for future cost reduction.
For New Entrants and Emerging Players: Capture market share by focusing on diagnostic technology advancements and affordable screening tools for underpenetrated regions. Target emerging markets in Southeast Asia and India, where high disease prevalence meets a demand for established, cost-effective therapies like hydroxyurea. A go-to-market angle involves strategic partnerships with local healthcare providers and public health initiatives to facilitate early diagnosis. Develop AI-driven patient stratification tools to optimize clinical trial design for specific genetic variants.
For Investors and Strategic Acquirers: Valuations sit cheapest among companies specializing in established therapeutic agents and diagnostic kits, offering stable cash flows over a 5-10 year window. Target innovative biotechnology firms with robust gene-editing platforms and early-stage clinical assets in rare hemoglobinopathies. Long-term viability hinges on successful clinical translation of curative gene therapies and favorable reimbursement negotiations. The signal to watch is successful long-term patient follow-up data for approved gene therapies, validating their curative potential.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | Accelerates market access for novel gene therapies in the United States. |
| Manufacturing Scale-Up | Reduces production costs and increases patient access for lentiviral vectors. |
| Licensing Agreement | Expands technology reach for CRISPR platforms in new geographic markets. |
| Clinical Trial Advancement | Generates long-term safety and efficacy data for curative treatments. |
| Reimbursement Strategy | Secures payer coverage for high-cost interventions in European markets. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region informing the analysis. This involved combining in-depth primary interviews with industry stakeholders and rigorous secondary validation. Stakeholders included gene therapy developers, regulatory affairs leads, specialized hematologists, and hospital procurement managers. Secondary data was drawn from U.S. FDA filings, EMA submissions, ClinicalTrials.gov, and national health registries. A bottom-up and top-down triangulation approach ensured data accuracy and market sizing precision.
Rate-of-change decomposition informed the market forecast across the analysis window, modeling shifts in therapy adoption. The analytical framework considered segmentation dimensions including product type, therapy area, end user, and delivery mode. Compound annual growth rates were derived from historical data trends and projected technological advancements. Key forecast inputs included gene therapy approval timelines and the expansion of newborn screening programs.
Regulatory changes, reimbursement policy shifts, and long-term gene therapy safety data are the dominant revision risks for market projections. Forecasts reflect assumptions regarding clinical trial success rates and manufacturing scalability. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Sarcoidosis Therapeutics Market
Rare Diseases
Spina Bifida Market
Rare Diseases
Asia Pacific Rett Syndrome Market
Rare Diseases
Mucopolysaccharidosis (MPS) Treatment Market
Rare Diseases
Europe Down Syndrome Market
Rare Diseases
Orphan Diseases Market
Rare Diseases
Hutchinson Gilford Progeria Syndrome (HGPS) Therapeutics Market
Rare Diseases
Glanzmann Thrombasthenia Market
Rare Diseases
Chronic Granulomatous Disease (CGD) Management Market
Rare Diseases
Batten Disease Market
Rare Diseases
Leigh Syndrome Treatment Market
Rare Diseases
Dystrophic Epidermolysis Bullosa Market
Rare Diseases
Rare Inflammatory Disease Treatment Market
Rare Diseases
Canavan Disease Treatment Market
Rare Diseases
Turner Syndrome Market
Rare Diseases
Middle East and Africa Down Syndrome Market