
 Fabry Disease Market | 2026-2036
Fabry Disease Market Size, Share, and Industry Trends Forecast 2026-2036
Fabry Disease Market Intelligence
Patient monitoring and adherence subscription services is decoupling therapy delivery from pure drug sales in the Fabry disease landscape. Sanofi Genzyme leverages its established global infusion network to sustain market presence across rare disease centers. Amicus Therapeutics differentiates through oral chaperone therapy, reducing patient dependence on intravenous administration. Protalix Biotherapeutics anchors its position with plant-cell-derived enzyme production technology, competing on manufacturing cost structure.
Fabry disease is an X-linked lysosomal storage disorder caused by alpha-galactosidase A deficiency, leading to globotriaosylceramide accumulation in vascular endothelium, kidneys, heart, and nervous tissue; enzyme replacement therapy supplies recombinant alpha-galactosidase A to catalyze substrate clearance. Intravenous enzyme replacement therapy dominates the product type landscape due to established clinical evidence and payer familiarity, while subcutaneous delivery modes are gaining traction among patients seeking reduced infusion center burden. Chaperone therapy occupies a narrower but strategically significant segment for amenable mutations, with pharmacological agents addressing symptom management in advanced disease stages.
FDA orphan drug designation and EMA priority medicines pathways accelerate Fabry therapy approvals, while national rare disease strategies in Germany and Japan mandate newborn screening expansion. The EU F-Gas Regulation constrains cold-chain logistics for biologics distribution, influencing delivery infrastructure investments. Stakeholders must monitor gene therapy pipeline maturation and payer willingness to fund curative modalities against chronic maintenance paradigms.
Market Dynamics
Gene therapy pipeline maturation is compressing development timelines and forcing established enzyme replacement manufacturers to reposition around curative versus chronic maintenance paradigms before clinical data readouts reshape reimbursement negotiations.
Growth Catalysts
- FDA Orphan Drug Incentives:Tax credits and extended exclusivity periods accelerate Fabry therapy development, drawing venture capital into rare disease biologics manufacturing.
- Enzyme Replacement Therapy:Intravenous infusion protocols with established payer codes sustain treatment adherence and reduce prior authorization friction in US and German rare disease centers.
- Japan Newborn Screening Mandates:METI-coordinated national rare disease strategies expand diagnostic catchment, converting latent prevalence into addressable patients earlier in disease progression.
Market Restraints
- Biologics Cold-Chain Costs:EU F-Gas Regulation constraints on fluorinated refrigerants elevate distribution infrastructure capital requirements for temperature-sensitive enzyme therapies.
- Diagnostic Concentration:Genetic testing capacity clusters in United States, Germany, and Japan, leaving Eastern European and Latin American patients undiagnosed or delayed in treatment initiation.
- Mutation-Amenable Subset Limitation:Chaperone therapy efficacy restricts to specific GLA gene variants, capping addressable population for oral alternatives regardless of patient preference.
Strategic Opportunities
- Subcutaneous Delivery Innovation:Infusion center burden reduction drives patient switching toward home-administration formats, opening channel expansion for specialty pharmacy networks.
- EMA Priority Medicines Pathway:Accelerated assessment timelines compress regulatory lag for gene therapy candidates, enabling first-mover positioning in curative modality reimbursement.
- Plant-Cell Production Platforms:Protalix Biotherapeutics' technology demonstrates cost structure advantages that could displace mammalian-cell manufacturing if scale-up succeeds.
Industry Challenges
- Gene Therapy Manufacturing Talent Scarcity:Viral vector production and quality control expertise concentrates in Boston and Basel clusters, constraining pipeline expansion for second-tier developers.
- Longitudinal Outcome Data Requirements:Payer demands for decade-plus renal and cardiac event data delay formulary placement for novel mechanisms despite accelerated regulatory approval.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fabry Disease Market |
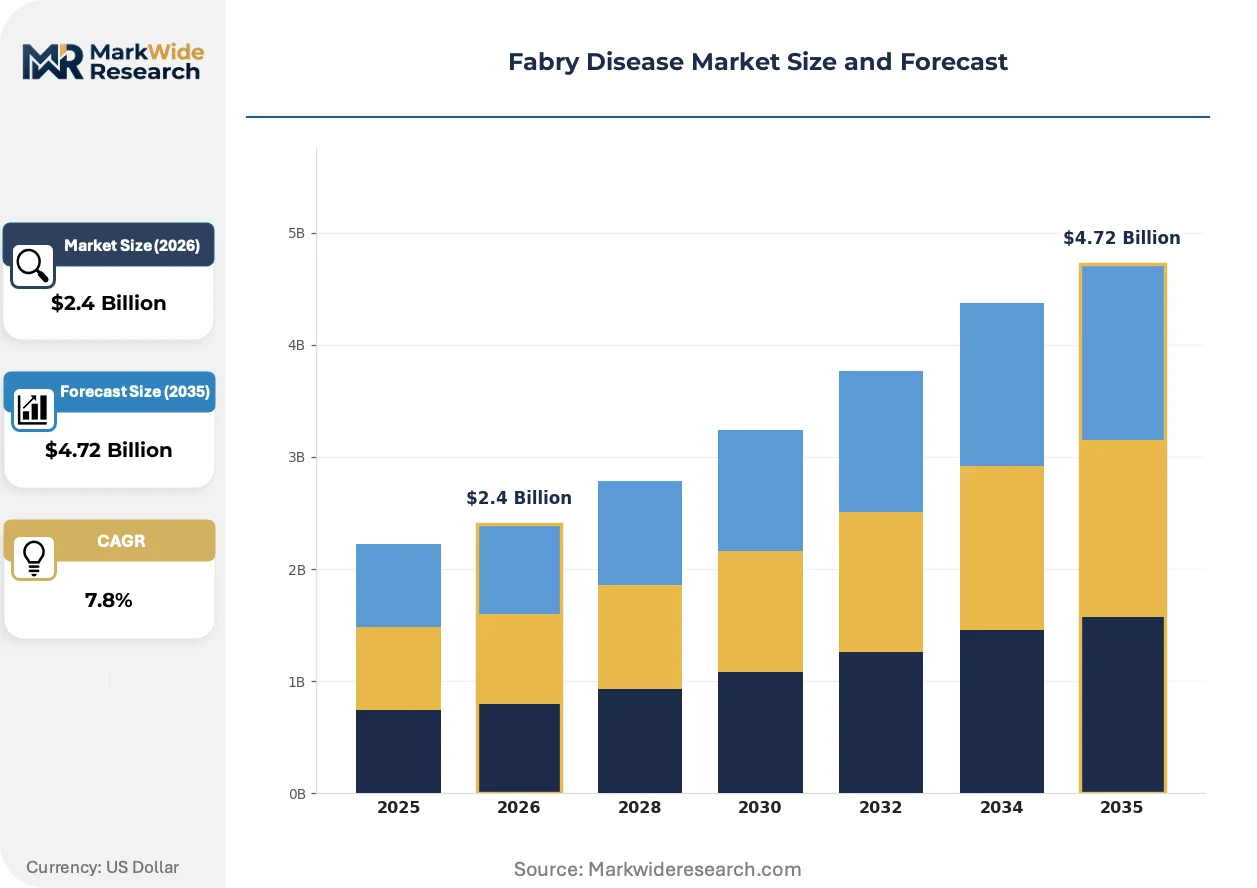
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.72 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enzyme Replacement Therapy, Pharmacological Agents, Chaperone Therapy, Others End User: Hospitals, Clinics, Homecare Settings, Specialty Pharmacies Delivery Mode: Intravenous, Oral, Subcutaneous, Inhalation Application: Chronic Care Management, Palliative Care, Disease Management, Preventive Care |
| Companies Covered | Amicus Therapeutics, Sanofi Genzyme, Takeda Pharmaceuticals, Protalix Biotherapeutics, Chiesi Farmaceutici, Sangamo Therapeutics, Idorsia Pharmaceuticals, ISU Abxis, JCR Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fabry Disease Market Strategic Shifts & Innovations
Digital biomarker integration and patient-reported outcome platforms are restructuring how Fabry disease progression is tracked, shifting value demonstration from surrogate endpoints to functional status metrics that resonate with payers.
Subcutaneous enzyme delivery systems are modularizing treatment administration, enabling patients to self-infuse at home rather than commuting to infusion centers. Adult patients with established venous access fatigue are adopting these devices fastest. Home administration is compressing site-of-care costs and redistributing margin capture toward drug manufacturers and specialty pharmacies.
EMA's F-Gas Regulation is forcing cold-chain logistics reconfiguration across European biologics distribution, requiring investment in alternative refrigeration technologies for enzyme replacement therapies. Manufacturers are responding with regional hub consolidation and temperature-monitoring digitalization. German and French distribution networks face the steepest compliance cost escalation.
Patient advocacy groups are demanding earlier intervention thresholds, pressuring physicians to initiate enzyme replacement before organ damage manifests. This behavioral shift expands treatable population definitions beyond classical phenotype males. United States and Japanese prescriber communities are adjusting practice patterns most rapidly in response to advocacy mobilization.
Fabry Disease Market Segmentation
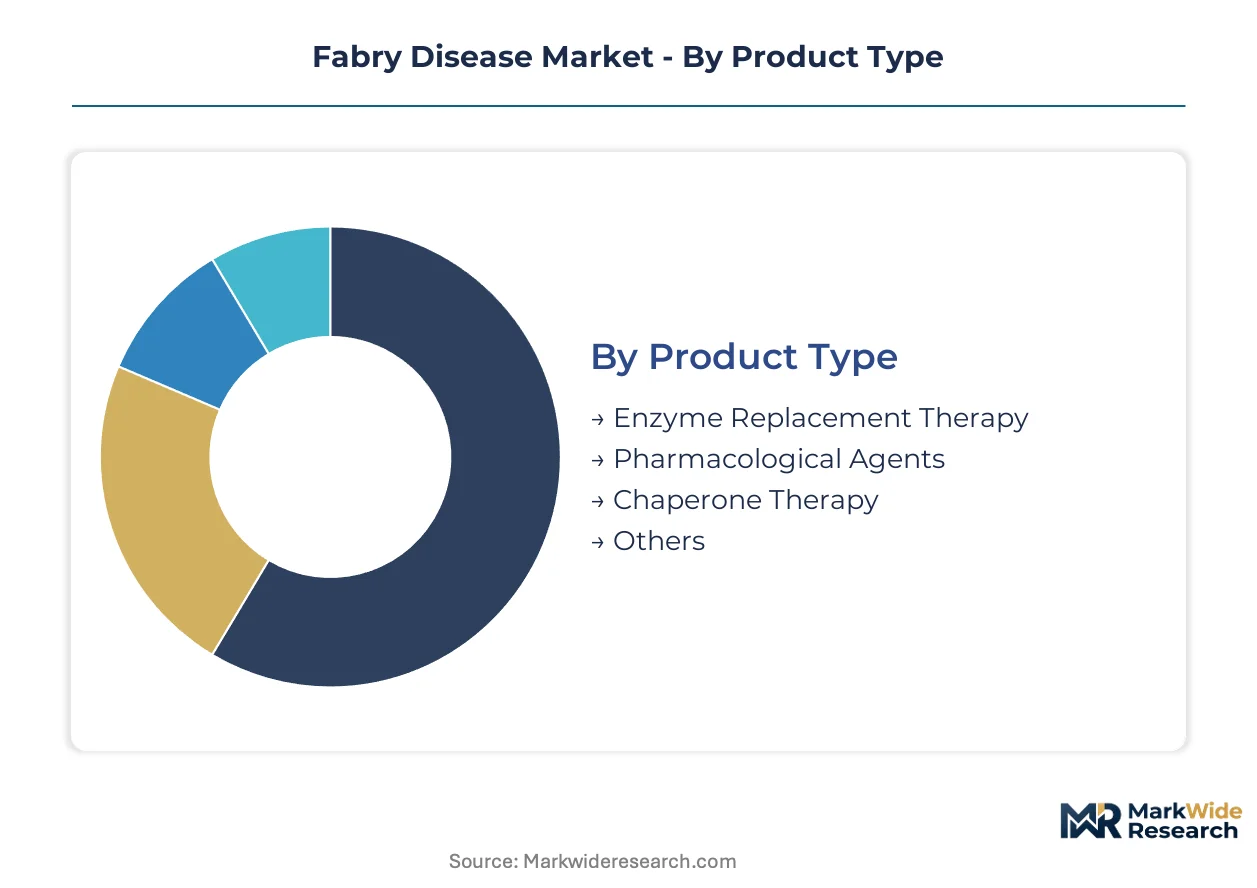
Fabry disease market segmentation reveals how regulatory pathways, site-of-care economics, and patient convenience preferences allocate commercial value across distinct product and service categories. Each dimension carries specific certification burdens that shape competitive entry costs and margin structures.
Product Type:
FDA orphan drug designation and EMA accelerated assessment requirements vary sharply across this category, with recombinant biologics facing the steepest manufacturing validation and lot-release testing protocols.
- Enzyme Replacement Therapy:Intravenous infusion of recombinant alpha-galactosidase A requires cold-chain distribution and specialized infusion center infrastructure. Demand concentrates in United States and German rare disease centers where payer codes for chronic biologic administration are most established; diagnostic expansion in Japan is converting latent prevalence into addressable patients.
- Chaperone Therapy:Oral pharmacological chaperones stabilize mutant enzyme folding for amenable GLA variants, eliminating infusion burden. United States prescribers favor this modality for eligible patients seeking home-based administration; mutation-specific efficacy limits addressable population regardless of patient preference.
- Pharmacological Agents:Symptom management therapies address renal, cardiac, and neuropathic complications in advanced disease stages.
- Others:Emerging modalities including substrate reduction approaches and adjunctive therapies occupy pre-commercial or niche positioning.
Leading the category by volume: Enzyme Replacement Therapy. Growing fastest: Chaperone Therapy.
End User:
Site-of-care economics and reimbursement granularity create distinct margin tiers across delivery settings, with hospital outpatient departments commanding premium pricing versus home administration.
- Hospitals:Academic medical centers and rare disease institutes anchor initial diagnosis and treatment initiation, capturing highest reimbursement for infused biologics under outpatient prospective payment systems. United States hospital networks in Boston and Baltimore maintain the deepest Fabry treatment expertise; German university hospitals coordinate newborn screening follow-up protocols.
- Specialty Pharmacies:Hub-and-spoke distribution models consolidate patient access services, adherence monitoring, and benefits investigation for complex biologics. United States specialty pharmacy networks are expanding home infusion capabilities to capture site-of-care margin migration; Japanese dispensing pharmacies face stricter cold-chain compliance under revised GMP standards.
- Homecare Settings:Self-administration and visiting nurse services reduce patient travel burden for established therapies.
- Clinics:Community-based infusion centers compete on convenience and prior authorization efficiency.
Dominating revenue capture: Hospitals. Expanding most quickly: Specialty Pharmacies.
Delivery Mode:
Route of administration determines cold-chain intensity, patient training requirements, and the balance between clinical supervision and convenience.
- Intravenous:Established enzyme replacement protocols require infusion center attendance every two weeks, with established renal and cardiac outcome data satisfying payer evidence requirements. United States and German payers maintain favorable prior authorization pathways for IV ERT; patient fatigue with venous access drives switching interest toward alternatives.
- Subcutaneous:Enzyme formulations optimized for subcutaneous depot administration enable home-based self-injection with reduced infusion duration. Patient advocacy groups in the United States and Japan are pressing for earlier access to subcutaneous options; specialty pharmacies are investing in nurse training infrastructure to support home initiation.
- Oral:Chaperone and small-molecule therapies eliminate injection burden entirely for eligible patients.
- Inhalation:Investigational delivery routes for pulmonary manifestations remain pre-commercial.
Highest patient volume: Intravenous. Gaining share fastest: Subcutaneous.
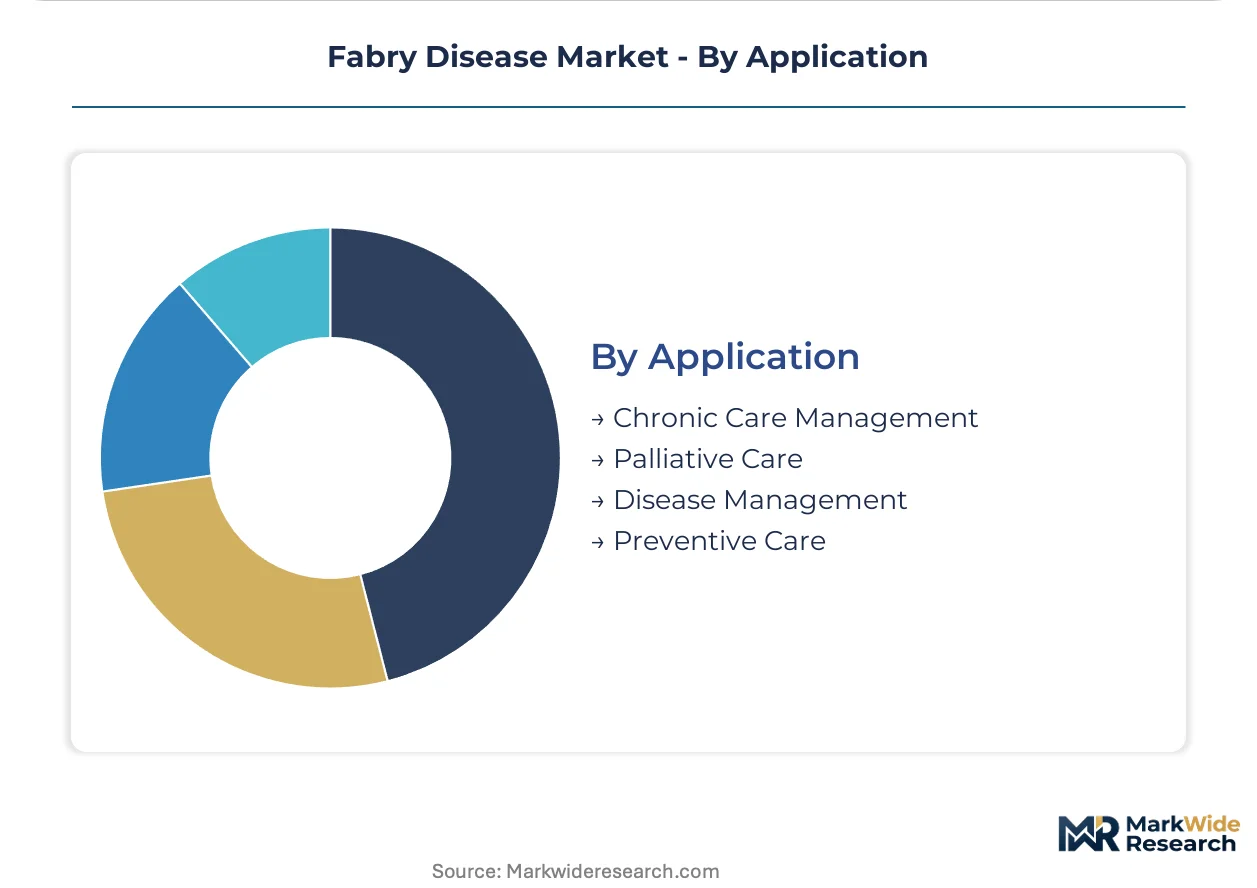
Application:
Clinical intent and disease stage determine treatment intensity, endpoint measurement, and the evidentiary burden for reimbursement.
- Chronic Care Management:Long-term enzyme replacement for classical and non-classical phenotypes requires sustained adherence monitoring and organ function surveillance. United States payers are expanding value-based contracts that tie reimbursement to renal and cardiac event reduction; German disease management programs integrate Fabry care into structured treatment pathways.
- Disease Management:Coordinated multidisciplinary care addresses the multi-organ progression of Fabry pathology.
- Palliative Care:Symptom-focused interventions for advanced organ failure stages.
- Preventive Care:Newborn screening and family cascade testing convert latent prevalence into early intervention candidates.
Capturing majority of treated patients: Chronic Care Management. Showing steepest expansion trajectory: Preventive Care.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diagnostic capacity and reimbursement infrastructure concentrate in the United States, Germany, and Japan, while treatment demand outpaces supply-side investment across Eastern Europe and Latin America. Manufacturing of recombinant enzymes clusters in mammalian-cell facilities near Boston and Basel, with plant-cell alternatives emerging in Israeli biotechnology parks.
United States
FDA orphan drug incentives and established prior authorization pathways sustain enzyme replacement therapy demand across academic medical centers. The national rare disease strategy coordinates newborn screening expansion through HRSA-funded state programs. Boston and Baltimore anchor the deepest Fabry treatment expertise, with specialty pharmacy networks expanding home infusion capabilities to capture site-of-care margin migration.
Germany
EMA accelerated assessment pathways and structured disease management programs integrate Fabry care into statutory health insurance reimbursement. The EU F-Gas Regulation elevates cold-chain compliance costs for biologics distribution across Bavarian and North Rhine-Westphalian pharmacy networks. University hospitals in Munich and Heidelberg coordinate newborn screening follow-up protocols, converting diagnostic catchment into addressable patients earlier in disease progression.
Japan
METI-coordinated national rare disease strategies mandate newborn screening expansion, converting latent prevalence into treatable patients before organ damage manifests. PMDA priority review vouchers accelerate Fabry therapy approvals for domestic and foreign manufacturers. Tokyo and Osaka academic medical centers maintain the highest enzyme replacement therapy penetration rates across Asia-Pacific, with dispensing pharmacies facing stricter GMP standards for cold-chain compliance.
Switzerland
Swissmedic regulatory efficiency and proximity to Basel-based biologics manufacturing attract gene therapy developers seeking accelerated clinical trial initiation. The country's centralized health technology assessment coordinates reimbursement negotiations for curative modalities against chronic maintenance paradigms. Geneva and Zurich rare disease centers participate in multinational outcome registries, generating longitudinal renal and cardiac event data demanded by German and French payers.
United Kingdom
NICE technology appraisals and NHS England specialized commissioning frameworks determine access to high-cost biologics for Fabry patients across England and devolved administrations. The UK rare disease framework mandates improved diagnostic equity, though genetic testing capacity concentrates in London and Cambridge. Scottish and Welsh health boards negotiate managed entry agreements for enzyme replacement therapies, linking reimbursement to real-world outcome data collection.
Fabry Disease Market Key Industry Players
Top-tier vendors anchor the enzyme replacement segment, while mid-tier biotechnology firms compete on manufacturing innovation and delivery mode differentiation. The competitive structure stratifies across three tiers: established biologics manufacturers with global infusion networks, oral therapy specialists targeting mutation-amenable subsets, and gene therapy developers pursuing curative modalities. Consolidation pressure intensifies as subcutaneous delivery innovations and plant-cell production platforms threaten incumbent manufacturing cost structures. M&A activity targets gene therapy pipeline assets, while strategic partnerships secure viral vector manufacturing capacity.
Among established biologics manufacturers, Sanofi Genzyme and Takeda Pharmaceuticals occupy positions defined by global infusion infrastructure and payer relationship depth. Amicus Therapeutics exemplifies the oral therapy archetype, reducing patient dependence on intravenous administration for eligible mutation subsets. Protalix Biotherapeutics anchors the manufacturing innovation tier, with plant-cell-derived enzyme production technology demonstrating cost structure advantages against mammalian-cell alternatives.
| Leading Market Players |
|---|
| Amicus Therapeutics |
| Sanofi Genzyme |
| Takeda Pharmaceuticals |
| Protalix Biotherapeutics |
| Chiesi Farmaceutici |
| Sangamo Therapeutics |
| Idorsia Pharmaceuticals |
| ISU Abxis |
| JCR Pharmaceuticals |
| Others |
Cost & Logistics Intelligence
Viral vector production specialists cluster in Boston and Basel, where labor-cost differentials between mammalian-cell and plant-cell manufacturing platforms widen pricing-tier spreads across enzyme replacement therapies and emerging gene therapy candidates.
Pricing Analysis
Cost-down pressure on intravenous enzyme replacement accelerates because plant-cell production platforms undercut mammalian-cell cost structures. Three-tier pricing structure across premium biologics, standard-of-care infusions, and economy chaperone tiers separates Sanofi Genzyme's established therapies from Protalix Biotherapeutics' cost-advantaged entries. Certification grade and cold-chain compliance burden drive price differentiation, with EMA F-Gas Regulation compliance adding distribution premiums. Payer pharmacy benefit managers exhibit highest price sensitivity, while rare disease centers with dedicated infusion infrastructure remain least sensitive due to bundled reimbursement codes.
Supply Chain Analysis
Reverse-logistics for temperature-deviated biologics returns concentrates cost recovery efforts in German and French distribution hubs, where lot-release failures trigger complex refurbishment protocols. Manufacturing of recombinant enzymes clusters in the United States, Switzerland, and Israel, with plant-cell alternatives emerging in Israeli biotechnology parks. Production draws from Chinese-sourced bioreactor components, German-engineered filtration systems, and US-origin cell culture media. Single-source vulnerability in viral vector manufacturing constrains gene therapy pipeline expansion. Distribution runs through specialty pharmacy hub-and-spoke networks with regional cold-chain consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gene therapy maturation is displacing chronic enzyme replacement paradigms, with curative modalities poised to capture premium reimbursement against maintenance therapy frameworks.
For Market Incumbents: Lock in infusion center relationships through exclusive site-of-care contracts before subcutaneous and oral alternatives erode venous access dependency. Secure backward integration into viral vector manufacturing capacity in Basel or Boston clusters to defend against gene therapy talent scarcity. Expand patient adherence subscription services to decouple revenue from pure drug volume as curative modalities enter reimbursement negotiations.
For New Entrants and Emerging Players: Launch via home-administration subcutaneous formats targeting United States and Japanese patients with established venous access fatigue. White-space opportunities concentrate in Eastern European diagnostic expansion and Latin American newborn screening follow-up protocols. Prioritize EMA Priority Medicines pathway submissions to compress regulatory lag against established enzyme replacement manufacturers.
For Investors and Strategic Acquirers: Re-rating potential sits with plant-cell production platform specialists given manufacturing cost structure advantages against mammalian-cell incumbents. Long-term viability over the next decade hinges on positioning for gene therapy manufacturing scale-up before clinical data readouts reshape competitive dynamics. Monitor PMDA and FDA gene therapy approval timelines as inflection indicators for chronic maintenance paradigm displacement.
| Strategic Initiative | Industry Significance |
|---|---|
| Subcutaneous Delivery Innovation | Reduces infusion center burden and captures site-of-care margin migration toward specialty pharmacies. |
| Plant-Cell Manufacturing Scale-Up | Protalix Biotherapeutics' technology demonstrates cost structure advantages against mammalian-cell alternatives. |
| Gene Therapy Pipeline Advancement | Sangamo Therapeutics and others pursue curative modalities that threaten chronic enzyme replacement frameworks. |
| EMA Priority Medicines Pathway | Accelerated assessment timelines compress regulatory lag for novel mechanisms entering European markets. |
| Newborn Screening Expansion | Japan METI-coordinated strategies convert latent prevalence into addressable patients earlier in disease progression. |
Research Approach
Document review covered FDA orphan drug filings, EMA accelerated assessment decisions, ClinicalTrials.gov gene therapy protocols, and Japanese PMDA priority review vouchers, complemented by interviews with drug development executives at enzyme replacement manufacturers, regulatory affairs leads navigating EMA and FDA pathways, formulary directors at US pharmacy benefit managers, and payer access specialists in German statutory health insurance. Secondary validation drew from SEC 10-K biologics revenue disclosures, EU F-Gas Regulation compliance filings, and METI rare disease strategy documents. Bottom-up patient prevalence estimates and top-down manufacturer revenue analysis were triangulated.
Cross-referencing historical enzyme replacement adoption curves against expert panel input on gene therapy reimbursement willingness shaped the analytical framework across the analysis window. Segmentation dimensions modeled included product type, delivery mode, end-user setting, and regional regulatory cluster. CAGRs were derived from epidemiological expansion, diagnostic rate improvement, and therapy penetration assumptions. Forecast inputs incorporated newborn screening mandate timelines and cold-chain infrastructure investment trajectories.
Gene therapy clinical trial failure, EMA F-Gas Regulation enforcement escalation, and Japanese reimbursement austerity are the dominant revision risks to enzyme replacement demand projections. Forecasts reflect assumptions around curative modality pricing power and chronic therapy persistence rates. Practitioners should monitor PMDA gene therapy approval decisions and German disease management program expansions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Canavan Disease Treatment Market
Rare Diseases
Hutchinson-Gilford Progeria Syndrome Market
Rare Diseases
Rare Inflammatory Disease Treatment Market
Rare Diseases
Skeletal Dysplasia Market
Rare Diseases
Asia-Pacific Down Syndrome Market
Rare Diseases
Aicardi Syndrome Market
Rare Diseases
Gaucher Disease Drugs Market
Rare Diseases
Rosai-Dorfman Disease (RDD) Therapeutics Market
Rare Diseases
Erdheim-Chester Disease Market
Rare Diseases
Lesch-Nyhan Syndrome Market
Rare Diseases
Andersen-Tawil Syndrome Market
Rare Diseases
Byler Disease Market
Rare Diseases
Global Neuromyelitis Optica Spectrum Disorder Market
Rare Diseases
Phelan-Mcdermid Syndrome Market
Rare Diseases
Sarcoidosis Therapeutics Market
Rare Diseases
Leigh Syndrome Treatment Market