
 India Maize Seed Market | 2026-2036
India Maize Seed Market Size, Share, and Industry Trends Forecast 2026-2036
India Maize Seed Market Foresight
Hybrid maize germplasm is decoupling from open-pollinated dependency as trait-stacked varieties reshape farmer economics across India's corn belt. Kaveri Seeds dominates proprietary single-cross hybrids in Telangana and Andhra Pradesh through captive breeding stations and decentralized seed multiplication. Bayer AG leverages molecular marker-assisted selection to accelerate trait integration timelines for drought-tolerant inbreds. Mahyco Seeds Company Ltd anchors its position through deep backward integration into parental line development and licensed Bt trait access.
India maize seed comprises sexually propagated planting material bred for heterotic yield expression, typically delivered as single-cross F1 hybrids with specified germination thresholds above 80 percent and genetic purity standards monitored through grow-out tests. The primary commercial purpose centers on transferring yield stability, pest resistance, and abiotic stress tolerance from proprietary inbred parents to farmer-sown production fields. Hybrid seeds command the dominant value share as farmers in irrained belts abandon retained OPV grain for certified hybrid purchases each season. Animal feed application generates the fastest volume pull as integrated poultry operations in Haryana and Tamil Nadu contract directly for identity-preserved silage and grain maize.
BIS seed certification standards and the Seeds Act enforcement by state agricultural departments govern market access, with mandatory truthful labeling of genetic purity and germination rates creating compliance barriers for uncertified suppliers. The PLI scheme for agriculture and CDSCO-equivalent oversight of biotech trait approvals shape product pipelines and commercialization timelines for stacked-gene varieties. Stakeholders must monitor how state-level seed subsidy allocations and water-use regulations for summer maize interact to determine which germplasm categories gain acreage priority in the coming planting cycles.
Market Dynamics
Hybrid trait stacking is compressing replacement cycles as Deccan Plateau farmers abandon retained OPV grain for certified single-cross purchases each season, while the PLI scheme for agriculture accelerates breeder-to-market linkages.
Growth Catalysts
- PLI scheme for agriculture:Central government production-linked incentives are accelerating domestic breeding infrastructure and reducing import dependency for parental lines.
- Integrated poultry operations:Contract farming arrangements in Haryana and Tamil Nadu are creating identity-preserved demand corridors for silage and feed-grade maize.
- Starch processing expansion:Wet milling capacity additions in Karnataka and Maharashtra are pulling dedicated high-amylose germplasm through direct processor-seed company agreements.
Market Restraints
- Parental line concentration:Proprietary inbred development remains concentrated among three domestic breeders, creating germplasm bottleneck risk.
- BIS certification timelines:Mandatory grow-out tests for genetic purity verification extend commercialization cycles by two full planting seasons.
- Irrigation water scarcity:Depleting groundwater tables in Telangana and Andhra Pradesh are constraining summer maize acreage expansion regardless of seed quality.
Strategic Opportunities
- Rabi maize underpenetration:Bihar and eastern Uttar Pradesh retain 60 percent OPV coverage, creating conversion runway for drought-tolerant hybrids.
- Silage-specific germplasm:Dairy cooperatives in Gujarat and Rajasthan are requesting customized high-moisture harvest varieties with enhanced fiber digestibility.
- Decentralized seed multiplication:Village-level processing units under the Seeds Act are enabling faster last-mile distribution in Madhya Pradesh tribal belts.
Industry Challenges
- Trait licensing complexity:Stacked-gene varieties require parallel CDSCO-equivalent approvals and state seed committee registrations, multiplying compliance touchpoints.
- Skilled breeder scarcity:Molecular marker-assisted selection expertise remains concentrated in Hyderabad and Pune, constraining regional breeding station expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Maize Seed Market |
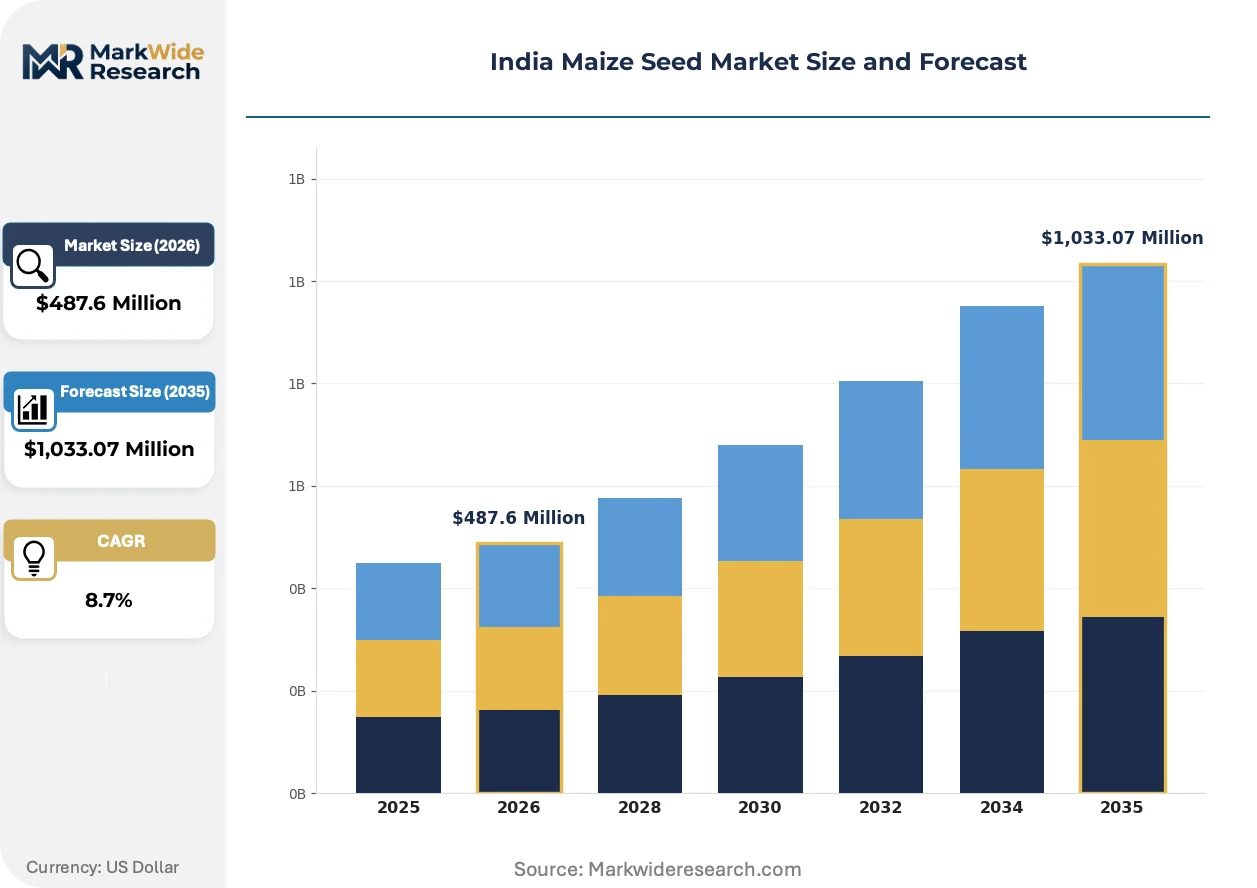
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hybrid Seeds, Open-Pollinated Varieties, Organic Seeds, GM Seeds Distribution Channel: Retail Stores, Online Platforms, Distributors, Cooperatives End User: Farmers, Commercial Growers, Agricultural Organizations, Research Institutions Application: Food Production, Animal Feed, Biofuel, Industrial Uses |
| Companies Covered | Kaveri Seeds, Mahyco Seeds Company Ltd, Bayer AG, Advanta Seeds - UPL, Rasi Seeds Private Limited, Syngenta Group, Nuziveedu Seeds Ltd, JK Agri Genetics, Corteva Agriscience, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Maize Seed Market Shifts & Advancements
Digital phenotyping platforms and decentralized multiplication networks are compressing the traditional breeder-to-farmer pipeline, while regulatory frameworks for gene-edited traits reshape product development priorities.
Marker-assisted selection combined with rapid-cycle winter nurseries is decentralizing hybrid development timelines that previously required six years of conventional backcrossing. Mid-tier seed companies in Madhya Pradesh and Chhattisgarh are adopting these platforms to bypass captive breeding station dependencies. The structural result is fragmenting the historical concentration of proprietary germplasm among Hyderabad-based breeders.
CDSCO-equivalent oversight frameworks for biotech trait approvals are tightening compliance documentation requirements for stacked-gene varieties. Developers must now submit parallel dossiers to central regulators and state seed committees, extending pre-commercialization timelines. Germplasm categories incorporating drought-tolerance traits face the steepest documentation burden, with Maharashtra and Karnataka state committees imposing additional location-specific efficacy trials.
Contract procurement arrangements between integrated poultry operators and commercial growers are displacing spot-market grain purchases in Haryana and Tamil Nadu. These arrangements specify identity-preserved hybrid varieties with documented silage digestibility metrics, shifting farmer seed selection criteria toward processor-validated germplasm lists. The procurement model is most visible in the NCR dairy belt, where feed mills now mandate variety disclosure as a contract condition.
India Maize Seed Market Segmentation
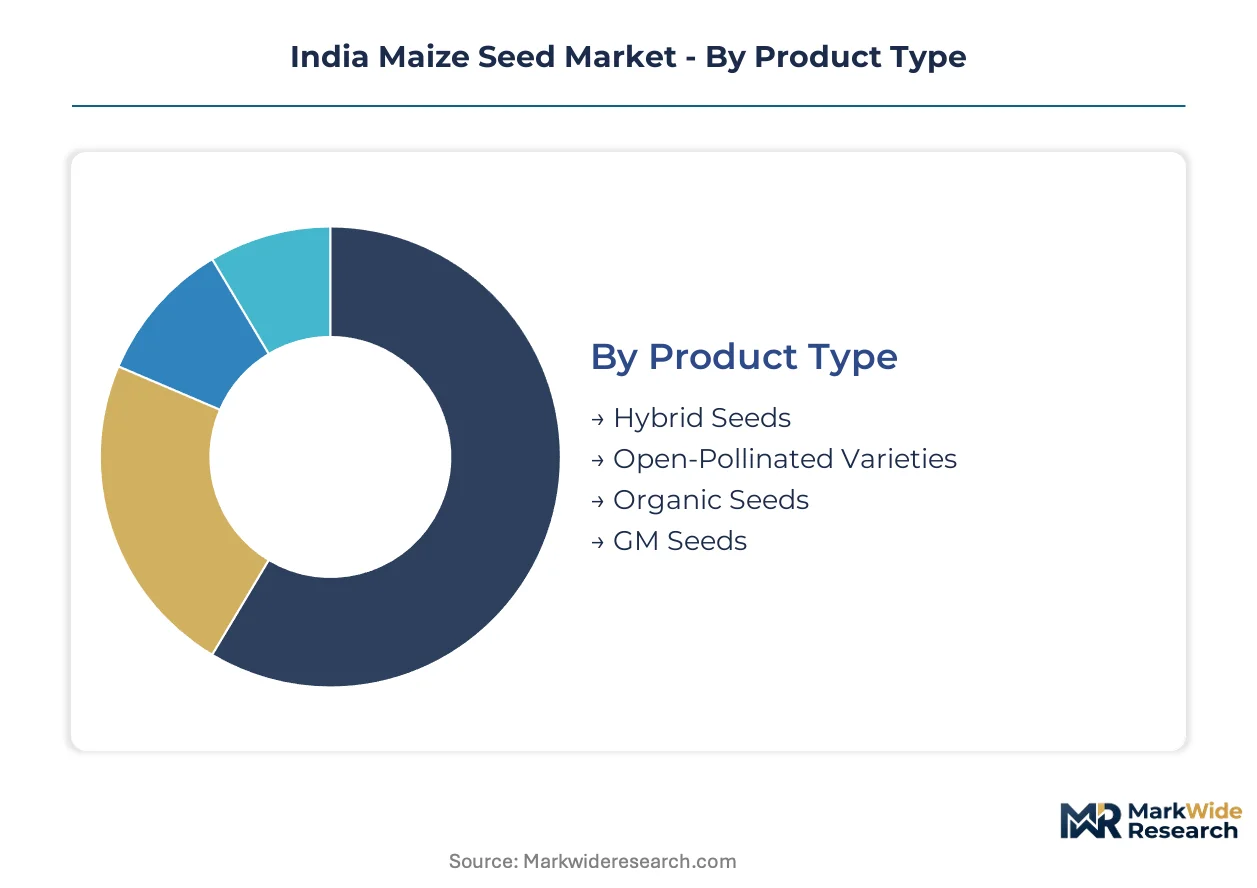
Segmentation in India's maize seed market reveals how germplasm selection criteria diverge across buyer economics, channel access, and end-use specifications. Each dimension captures distinct procurement behaviors that shape breeding priorities and commercialization timelines.
Product Type:
Buyer differentiation hinges on yield stability requirements versus seed cost sensitivity across India's corn belt.
- Hybrid Seeds:Single-cross F1 varieties with specified germination thresholds above 80 percent and genetic purity verified through grow-out tests. Demand concentrates in Karnataka and Maharashtra where commercial growers contract for silage and poultry feed production, driven by processor-validated germplasm lists and identity-preserved procurement arrangements.
- Open-Pollinated Varieties:Farmer-retained grain with lower input costs but declining yield trajectories after multiple generations. Retention persists in Bihar and eastern Uttar Pradesh where 60 percent OPV coverage creates conversion runway, constrained by limited irrigation access and price-sensitive smallholder economics.
- Organic Seeds:Certified chemical-free germplasm meeting FSSAI and NPOP standards for residue-free grain.
- GM Seeds:Stacked-trait varieties incorporating Bt insect resistance requiring CDSCO-equivalent approval and state seed committee registration.
Volume sits with Hybrid Seeds; growth tilts toward GM Seeds as regulatory frameworks mature for stacked-gene commercialization.
Distribution Channel:
Channel selection reflects farmer scale, credit access, and the urgency of varietal replacement cycles.
- Retail Stores:Brick-and-mortar agri-input dealers providing immediate availability and relationship-based credit terms. Penetration dominates in Telangana and Andhra Pradesh where Kaveri Seeds maintains captive distribution through dedicated dealer networks, supported by breeder-to-market linkages accelerated under the PLI scheme for agriculture.
- Online Platforms:E-commerce portals and app-based procurement enabling price transparency and direct-to-farmer breeder access. Adoption concentrates among commercial growers in Haryana and Tamil Nadu integrated with contract farming arrangements, driven by identity-preserved variety documentation requirements and processor-mandated germplasm disclosure.
- Distributors:Wholesale aggregators supplying multi-brand portfolios to retail networks and cooperatives.
- Cooperatives:Member-owned procurement bodies aggregating demand for volume discounts and quality assurance.
Retail Stores capture current volume; Online Platforms are expanding most quickly among contract-integrated commercial operations.
End User:
User category determines germplasm specification depth and the intensity of technical support required.
- Farmers:Individual cultivators ranging from subsistence to semi-commercial scale with varying trait awareness. Demand fragments across India's corn belt with concentration in rainfed Deccan Plateau states, where water scarcity constrains summer maize acreage regardless of seed quality and irrigation access dictates hybrid adoption rates.
- Commercial Growers:Contract-integrated operations cultivating identity-preserved varieties for processor offtake. Scale concentrates in Karnataka and Maharashtra where direct seed company-processor agreements pull dedicated high-amylose germplasm, driven by wet milling capacity expansion and silage digestibility specifications.
- Agricultural Organizations:Extension services and farmer producer organizations facilitating collective procurement and demonstration plots.
- Research Institutions:Public and private breeding stations developing parental lines and conducting location-specific efficacy trials.
Commercial Growers anchor value concentration; Farmers represent the deepest volume pool with steepest expansion trajectory as OPV conversion accelerates.
Application:
End-use specification determines grain quality parameters and the premium commanded over commodity benchmarks.
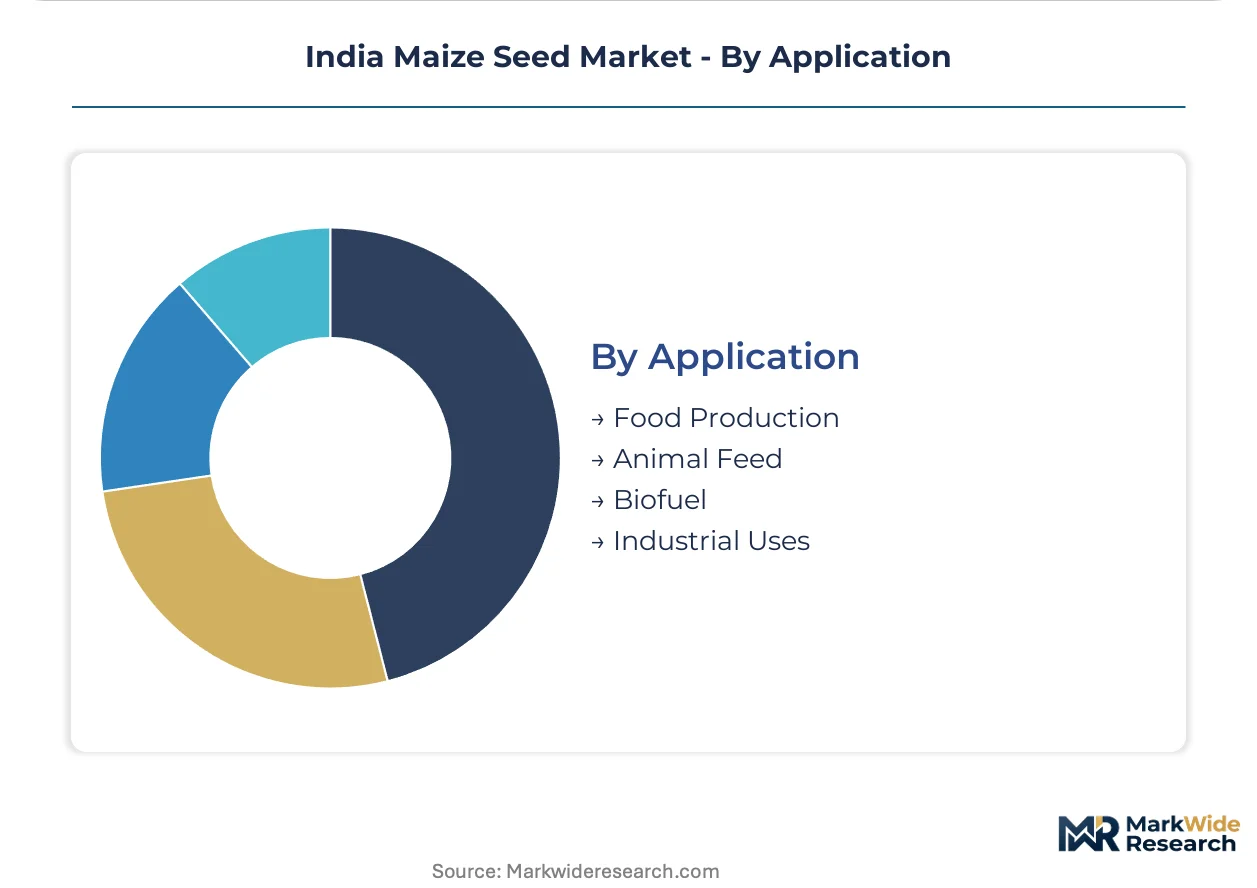
- Animal Feed:Silage and grain production for integrated poultry and dairy operations. Demand pulls fastest in Haryana and Tamil Nadu where feed mills mandate variety disclosure as contract conditions, driven by identity-preserved procurement and documented fiber digestibility metrics for high-moisture harvest varieties.
- Food Production:Direct human consumption and processed food ingredients requiring specific starch profiles and mycotoxin thresholds.
- Biofuel:Ethanol feedstock aligned with national blending mandates and distillery offtake agreements.
- Industrial Uses:Starch extraction, textile sizing, and pharmaceutical applications demanding high-amylose or waxy germplasm.
Animal Feed dominates current volume; Industrial Uses are gaining share fastest through processor-direct breeding partnerships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial maize seed procurement concentrates in the Deccan Plateau states where irrigated acreage for feed and starch processing continues expanding. Karnataka and Maharashtra anchor hybrid adoption through direct processor-seed company agreements. The PLI scheme for agriculture accelerates breeder-to-market linkages across the corn belt.
Karnataka
Wet milling capacity additions pull dedicated high-amylose germplasm through direct agreements between starch processors and seed developers. State agricultural departments enforce BIS seed certification standards through mandatory grow-out tests for genetic purity verification. The Bangalore-Mysore corridor hosts decentralized seed multiplication networks enabling faster last-mile distribution to commercial growers.
Maharashtra
Silage production for integrated poultry operations drives identity-preserved variety adoption among contract-integrated farmers. State seed committees impose additional location-specific efficacy trials for drought-tolerance trait documentation beyond central CDSCO-equivalent requirements. The Pune-Nashik belt concentrates molecular marker-assisted selection expertise among breeding stations developing abiotic stress-tolerant inbreds.
Telangana
Captive breeding stations and dedicated dealer networks dominate proprietary single-cross hybrid distribution through relationship-based retail channels. Groundwater depletion constrains summer maize acreage expansion regardless of seed quality improvements. The Hyderabad seed cluster anchors parental line development for Deccan Plateau germplasm categories.
Haryana
Integrated poultry operations in the NCR dairy belt mandate variety disclosure as a contract condition for silage procurement. Feed mills specify identity-preserved hybrids with documented fiber digestibility metrics for high-moisture harvest varieties. The Karnal-Ambala corridor channels contract farming arrangements displacing spot-market grain purchases.
Tamil Nadu
Commercial growers adopt app-based procurement platforms enabling direct-to-farmer breeder access for processor-validated germplasm lists. State agricultural departments allocate seed subsidies interacting with water-use regulations to determine germplasm category priority in planting cycles. The Coimbatore-Erode belt concentrates poultry feed demand pulling certified hybrid purchases each season.
India Maize Seed Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with proprietary germplasm developers commanding premium positioning in irrigated belts while decentralized multipliers serve price-sensitive retention markets. Three domestic breeders concentrate parental line development, creating germplasm bottleneck risk that mid-tier adopters bypass through marker-assisted selection platforms. Strategic moves center on backward integration into captive breeding stations and licensed trait access for stacked-gene commercialization.
Among Hyderabad-based germplasm specialists, Kaveri Seeds occupies a position exemplifying captive distribution through dedicated dealer networks in Telangana and Andhra Pradesh. Mahyco Seeds Company Ltd represents the backward-integrated archetype with in-house parental line development and licensed Bt trait access. Bayer AG anchors the molecular breeding tier, leveraging marker-assisted selection capabilities to accelerate trait integration timelines for drought-tolerant inbreds.
| Leading Market Players |
|---|
| Kaveri Seeds |
| Mahyco Seeds Company Ltd |
| Bayer AG |
| Advanta Seeds - UPL |
| Rasi Seeds Private Limited |
| Syngenta Group |
| Nuziveedu Seeds Ltd |
| JK Agri Genetics |
| Corteva Agriscience |
| Others |
Supply & Pricing Matrix
Family-owned germplasm specialists with captive breeding stations in Hyderabad and Pune anchor supply-side concentration, translating proprietary parental line control into pricing discipline across certified hybrid tiers while BIS certification mandates enforce quality-based price stratification.
Pricing Analysis
Volume concentrates in standard-tier single-cross hybrids priced for smallholder replacement cycles, while margin capture sits with premium drought-tolerant and silage-specific varieties validated through processor offtake agreements. Price differentiation rests on germplasm certification grade and documented genetic purity thresholds, with BIS grow-out test compliance separating certified premiums from uncertified economy tiers. Pricing pressure intensifies in economy segments as groundwater depletion in Telangana and Andhra Pradesh constrains acreage expansion regardless of seed cost. Commercial growers integrated with poultry operations exhibit lowest price sensitivity due to contract-guaranteed offtake, while rainfed smallholders in Bihar and eastern Uttar Pradesh retain highest sensitivity to per-kilogram seed cost.
Supply Chain Analysis
Molecular marker-assisted selection expertise concentrates in Hyderabad and Pune breeding stations, constraining regional expansion of skilled breeder capacity and concentrating proprietary germplasm development in western and southern India. Parental line development draws from captive inbred programs at Kaveri Seeds and Mahyco, while trait licensing agreements with Bayer and Syngenta tether stacked-gene commercialization to CDSCO-equivalent approval timelines. Single-source vulnerability runs through the three domestic breeders controlling proprietary inbred development, creating germplasm bottleneck risk for mid-tier seed companies without captive breeding infrastructure. Distribution runs through state-mandated dealer networks under the Seeds Act, with village-level processing units in Madhya Pradesh enabling decentralized last-mile multiplication.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where BIS certification standards and CDSCO-equivalent trait approval pathways create barrier-to-entry moats favoring incumbent breeders with established regulatory dossier capabilities and captive testing infrastructure.
For Market Incumbents: Anticipate margin compression from marker-assisted selection platforms enabling mid-tier competitors to bypass captive breeding station dependencies, and respond by deepening backward integration into parental line development while accelerating drought-tolerance trait stacking for water-scarce Deccan Plateau acreage. Prioritize licensing negotiations for Bt and stacked-gene trait access before CDSCO-equivalent approval backlogs extend commercialization timelines further. For New Entrants and Emerging Players: The 40-60 percent price-point gap between premium processor-validated hybrids and retained OPV grain in Bihar and eastern Uttar Pradesh creates conversion runway for drought-tolerant standard-tier offerings. Target rabi maize underpenetration through decentralized seed multiplication partnerships under the Seeds Act, leveraging village-level processing units to bypass established dealer network gatekeeping in Madhya Pradesh tribal belts. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier seed companies with marker-assisted selection adoption and regional distribution licenses in Maharashtra and Karnataka, where wet milling expansion and silage procurement growth concentrate demand pull. Long-term viability hinges on regulatory navigation capabilities across central and state seed committees. Watch state-level groundwater regulation enforcement as the inflection indicator determining which germplasm categories gain acreage priority.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Parental Line Development | Captive inbred programs reduce licensing dependency and accelerate trait integration timelines for Deccan Plateau germplasm. |
| CDSCO-Equivalent Trait Approval Dossier Investment | Parallel central and state committee registrations enable stacked-gene commercialization before competitors clear compliance backlogs. |
| Decentralized Seed Multiplication Network Expansion | Village-level processing units under the Seeds Act compress last-mile distribution cycles in Madhya Pradesh and Chhattisgarh. |
| Processor-Direct Breeding Partnerships | High-amylose and silage-digestibility specifications align germplasm pipelines with Karnataka starch milling and Haryana poultry feed demand. |
| Digital Phenotyping Platform Adoption | Rapid-cycle winter nurseries compress conventional backcrossing timelines that previously required six years of development. |
Research Methodology
Central Seed Committee filings, state agricultural department subsidy allocation records, and BIS certification databases formed the secondary backbone, cross-referenced with primary interviews involving hybrid seed breeders, state seed certification officers, poultry feed procurement managers, and starch processor agronomists. Bottom-up acreage estimates by state and germplasm category were triangulated against top-down value projections from seed company revenue disclosures and processor contract volume data.
Top-down macro assumptions on irrigation expansion and PLI scheme disbursement trajectories anchored the analytical lens, while bottom-up segmentation across hybrid versus OPV coverage, distribution channel penetration, and end-use application splits refined volume allocations. CAGRs were derived from regression fits to historical acreage and pricing data across the projection horizon, with specific weighting for drought-tolerance trait adoption curves and groundwater depletion constraints in Telangana and Andhra Pradesh.
Inputs from state seed committees and central regulator disclosure databases were available through the study window; gaps in real-time groundwater table monitoring and informal OPV retention estimates introduce uncertainty bands around conversion rate assumptions. Forecasts reflect documented assumptions on PLI scheme continuity and BIS certification timeline stability. A small set of triggers—state-level water-use regulation enforcement, CDSCO-equivalent approval backlog resolution, and processor contract specification shifts—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Global Sunflower Seed (Seed for Sowing) Market
Seeds
Punnet Market
Seeds
Africa Chia Seeds Market
Seeds
North America Quinoa Seeds Market
Seeds
Americas Seeds Market
Seeds
Citrus Seeds Market
Seeds
Chamomile Seeds Market
Seeds
Fruit Seed Waste Market
Seeds
Pigeon Pea Market
Seeds
South Africa Seed Market
Seeds
Global Wheat Seed Market
Seeds
Sweet Corn Seeds Market
Seeds
Ghana Seed Extract Market
Seeds
United States Garden Seeds Market
Seeds
North America Cannabis Seeds Market
Seeds
Asia-Pacific Cannabis Seeds Market