
 Organic Quinoa Market | 2026-2036
Organic Quinoa Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Quinoa Market Analytics
The price gap between certified organic quinoa and conventional commodity grain is hardening as supply chain traceability costs diverge. Andean Naturals leverages direct farmer partnerships across the Altiplano to sustain volume consistency for North American buyers. Alter Eco competes through Fairtrade-certified sourcing that anchors premium shelf positioning in European retail channels. Ancient Harvest dominates the private-label and branded ingredient space with manufacturing scale that extends into gluten-free flour blends.
Organic quinoa denotes Chenopodium quinoa seed cultivated without synthetic pesticides or fertilizers, processed to retain intact saponin-free perisperm with protein content typically exceeding 14% and full essential amino acid profile. The grain serves commercial food manufacturers seeking clean-label binding and texturing in plant-based formulations. White quinoa occupies the mainstream volume tier due to neutral flavor and shorter cook time, while black quinoa commands the fastest expansion in nutraceutical applications where anthocyanin content drives functional positioning. Retail packs generate concentrated margin pools compared to bulk channels, though food service procurement through specialty distributors sustains steady institutional uptake.
USDA Organic certification governs domestic market access and label claims within the United States, while EU Organic Regulation 2018/848 mandates third-country equivalency for Andean imports into Europe. Peru's national organic program and Bolivia's SENASAG oversight enforce origin-level compliance that shapes exporter eligibility. Stakeholders must monitor evolving equivalency negotiations between major import jurisdictions and Andean producer states.
Market Dynamics
EU Organic Regulation 2018/848 is tightening third-country equivalency requirements, forcing Andean exporters to rebuild traceability infrastructure while North American buyers absorb elevated compliance costs through long-term contracting.
Growth Catalysts
- Clean-label plant protein demand:Food manufacturers reformulate meat alternatives using quinoa protein isolates to meet consumer rejection of methylcellulose and synthetic binders.
- USDA Organic certification expansion:The standard governs shelf placement in US natural retail channels and unlocks access to institutional procurement programs requiring certified ingredient streams.
- Andean production clustering:Peru and Bolivia concentrate 80% of organic quinoa volume, creating scale economies in organic certification auditing and export logistics.
Market Restraints
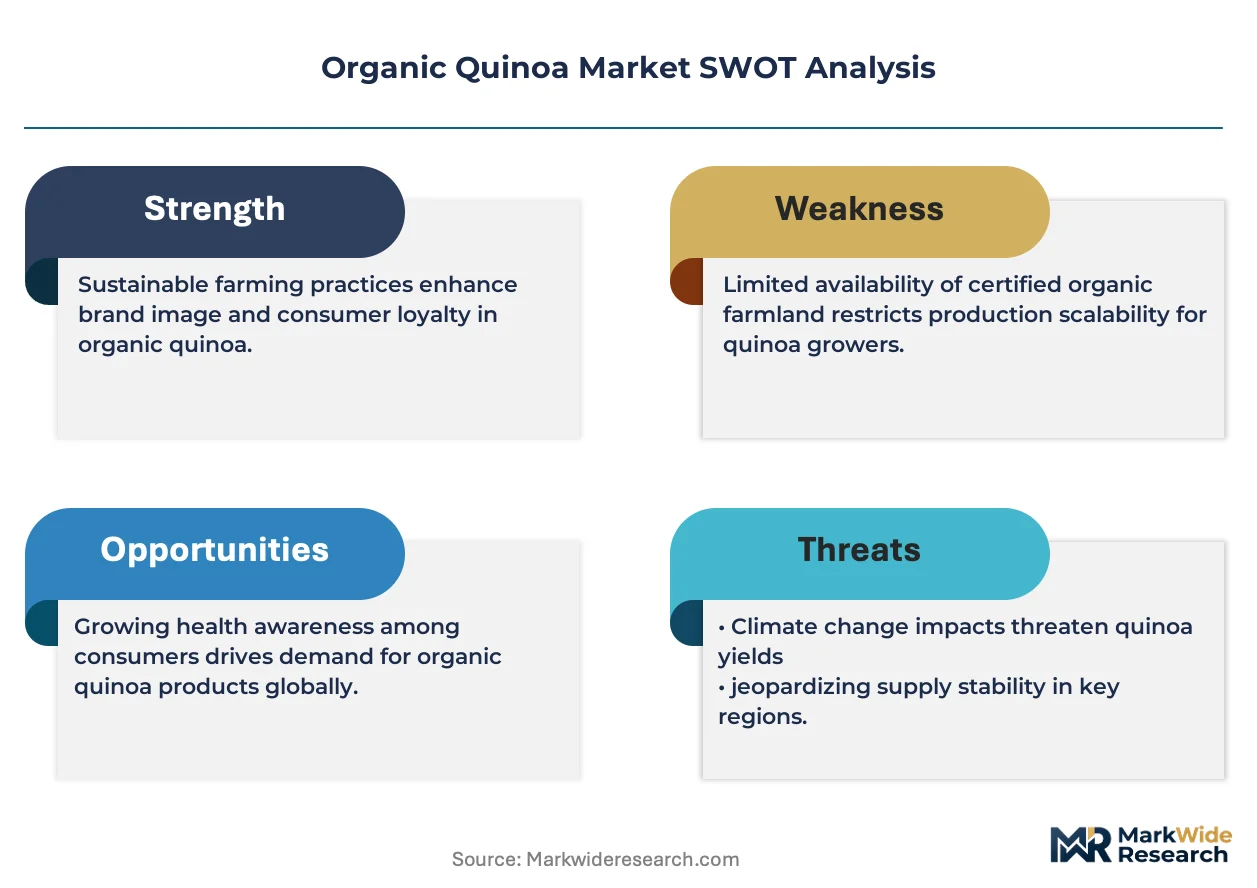
- Input cost volatility:Organic guano and biological pest control inputs face price instability from marine ecosystem fluctuations and climate-driven harvest failures.
- Geographic supply concentration:Altiplano drought cycles in Bolivia and Peru create systemic yield risk without geographic diversification buffers.
- Technical limitation:Saponin removal without water-intensive processing remains commercially unproven at scale, constraining water-stressed origin expansion.
Strategic Opportunities
- Ecuador emergence:The country's underdeveloped organic quinoa sector offers first-mover advantages in establishing certified supply chains before competitor saturation.
- Nutraceutical anthocyanin extraction:Black quinoa varieties enable functional ingredient positioning in supplement formulations targeting antioxidant claims.
- EU Green Deal alignment:Carbon footprint labeling requirements favor Andean low-input organic production against European domestic grain alternatives.
Industry Challenges
- Certification timeline compression:EU Organic Regulation equivalency renegotiations demand 36-month compliance overhauls for existing exporters.
- Traceability system integration:Blockchain and GPS-enabled farm mapping must interface with legacy paper-based cooperative record systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Quinoa Market |
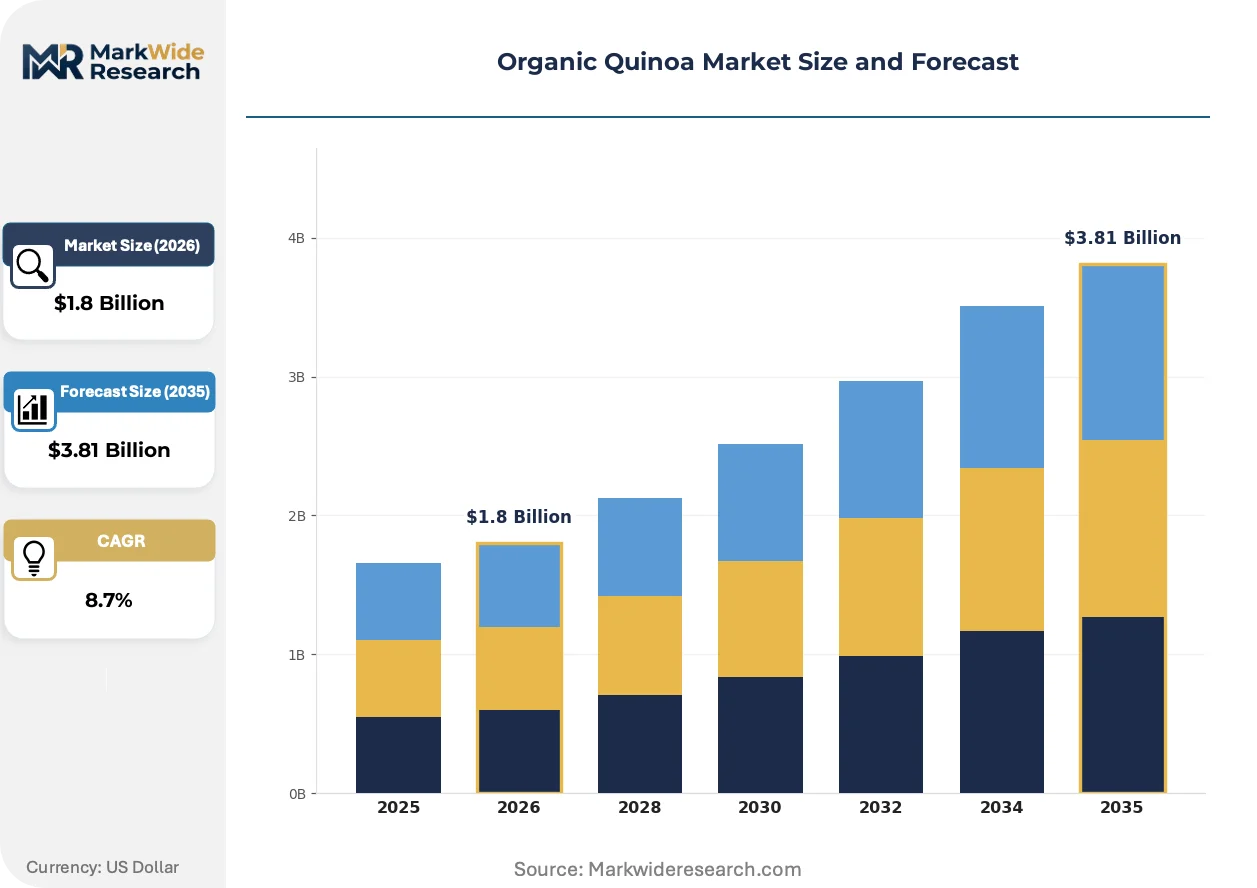
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: White Quinoa, Red Quinoa, Black Quinoa, Tri-Color Quinoa End User: Household, Food Service, Retailers, Nutraceuticals Distribution Channel: Online, Supermarkets, Health Food Stores, Specialty Shops Packaging Type: Bulk, Retail Packs, Pouches, Sachets |
| Companies Covered | Andean Naturals, Alter Eco, Quinoa Foods Company, Northern Quinoa Production Corporation, The British Quinoa Company, Inca Organics, Ancient Harvest, Irupana Andean Organic Food, Above Food Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Quinoa Market Evolving Landscape
Processing technology and regulatory architecture are restructuring competitive advantage around verified origin claims rather than commodity scale. The sector is pivoting toward ingredient-grade specialization and direct-farmer data capture.
Mechanical saponin abrasion systems are consolidating market share against traditional water-washing methods. Equipment suppliers in Germany and the Netherlands deploy abrasive hulling lines that cut water use by 70% while preserving germ integrity. Food ingredient buyers in the Netherlands and Germany now specify dry-processed quinoa to meet Scope 3 water targets, compressing margins for exporters without capital access.
EU Organic Regulation 2018/848 mandates third-country equivalency audits every two years with unannounced inspections. Andean exporters must maintain dual certification stacks to serve US and European markets simultaneously. Smallholder cooperatives in Bolivia face consolidation pressure as audit costs per farmer exceed individual revenue contributions.
Direct-origin procurement contracts are displacing spot-market purchasing among North American ingredient buyers. Brands now require farm-level GPS coordinates and harvest-date documentation for ESG reporting. This pattern concentrates sourcing relationships with vertically integrated exporters capable of field-to-fork data capture, marginalizing traditional commodity traders.
Organic Quinoa Market Segmentation
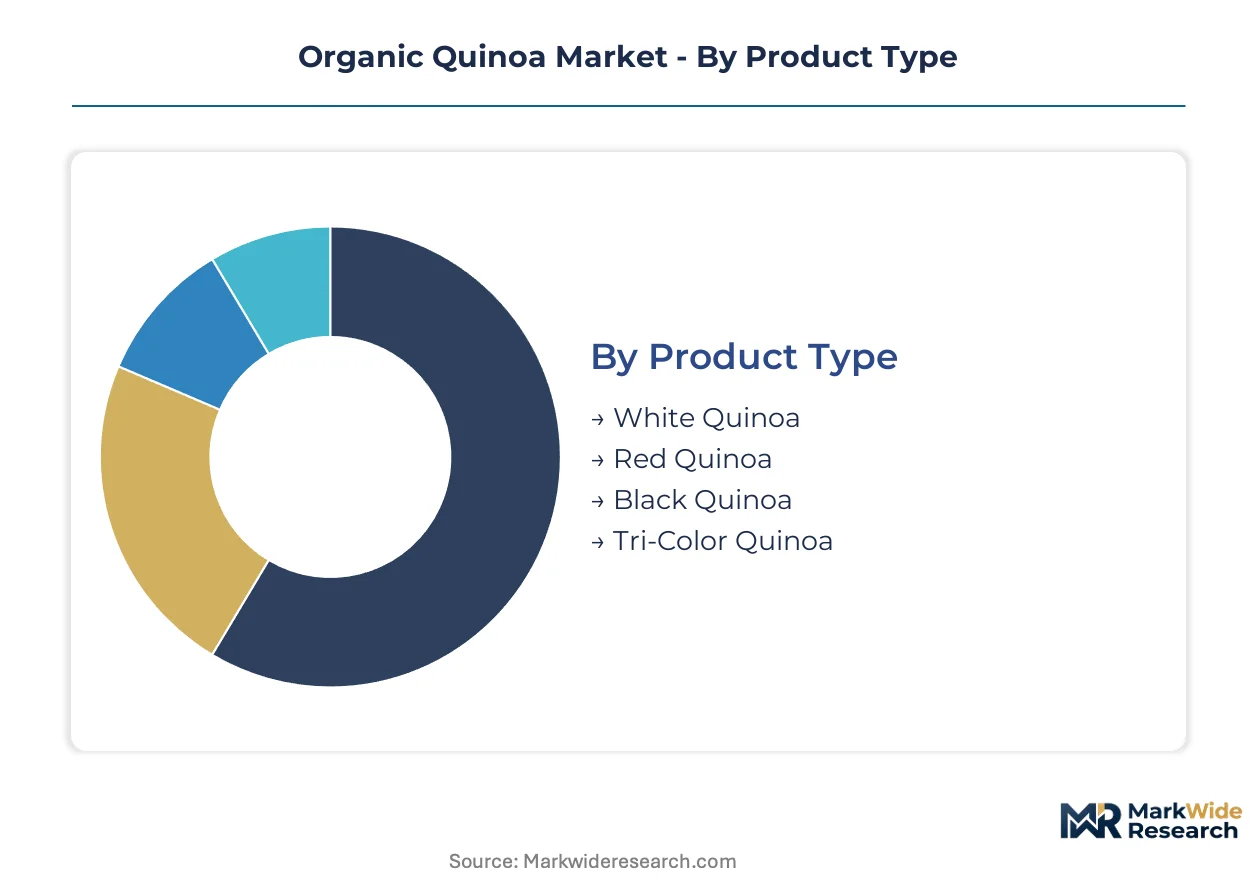
Organic quinoa buyers upgrade procurement specifications based on functional protein content, color-derived nutraceutical value, and shelf-positioning requirements. Segment boundaries harden as food manufacturers demand ingredient-grade certifications distinct from retail-ready packaging formats.
Product Type:
Buyers cycle through quinoa varieties based on formulation compatibility and premium positioning needs rather than price sensitivity alone.
- White Quinoa:Neutral flavor profile and sub-20-minute cook time make this variety the default choice for gluten-free flour blends and mainstream retail SKUs. North American private-label manufacturers concentrate procurement here to minimize recipe adjustment costs across plant-based product lines.
- Black Quinoa:Anthocyanin concentrations exceeding conventional grain varieties position this segment for nutraceutical extraction and antioxidant marketing claims. European supplement formulators in Germany and the Netherlands are expanding offtake agreements for certified organic black quinoa isolates.
- Red Quinoa:Firmer texture retention after cooking serves food service applications requiring visual plate differentiation.
- Tri-Color Quinoa:Premium retail merchandising drives demand for blended SKUs targeting gift and specialty food channels.
White quinoa sits at the top of the volume ranking, with black quinoa climbing the fastest.
End User:
Customer procurement sophistication varies sharply across consumption contexts, from traceability-demanding manufacturers to price-sensitive institutional buyers.
- Food Service:Contract food management companies specify organic certification for institutional accounts while accepting conventional quinoa for cost-driven segments. Aramark and Compass Group procurement frameworks in the United States now require third-party organic verification for healthcare and education sector contracts.
- Nutraceuticals:Protein isolate buyers demand 14%+ protein content with complete amino acid profiles and heavy metal testing documentation. EU-based supplement manufacturers face EU Green Deal pressure to source low-carbon-footprint Andean supply.
- Household:Direct-to-consumer retail purchases concentrate in natural channel shoppers with sustained organic basket loyalty.
- Retailers:Private-label development teams balance margin targets against clean-label positioning requirements.
Food service generates the largest absolute tonnage, while nutraceuticals is gaining share fastest.
Distribution Channel:
Channel selection determines margin capture and brand control intensity for organic quinoa suppliers.
- Health Food Stores:Staff-trained recommendation environments sustain premium pricing for certified organic and Fairtrade-labeled SKUs. Whole Foods Market and Sprouts Farmers Market in the United States anchor volume through dedicated bulk and packaged quinoa sets.
- Online:Direct-to-consumer subscriptions and marketplace fulfillment are expanding fastest among urban consumers seeking subscription convenience. Amazon and Thrive Market capture disproportionate growth in organic pantry staple replenishment.
- Supermarkets:Mainstream grocers compress shelf space for specialty grains against private-label expansion.
- Specialty Shops:Gourmet and ethnic food retailers serve niche demand for heirloom varieties and small-batch sourcing stories.
Health food stores retain the highest margin per pound, with online channels showing the steepest expansion trajectory.
Packaging Type:
Format economics separate ingredient buyers from retail-ready suppliers with divergent capital requirements.
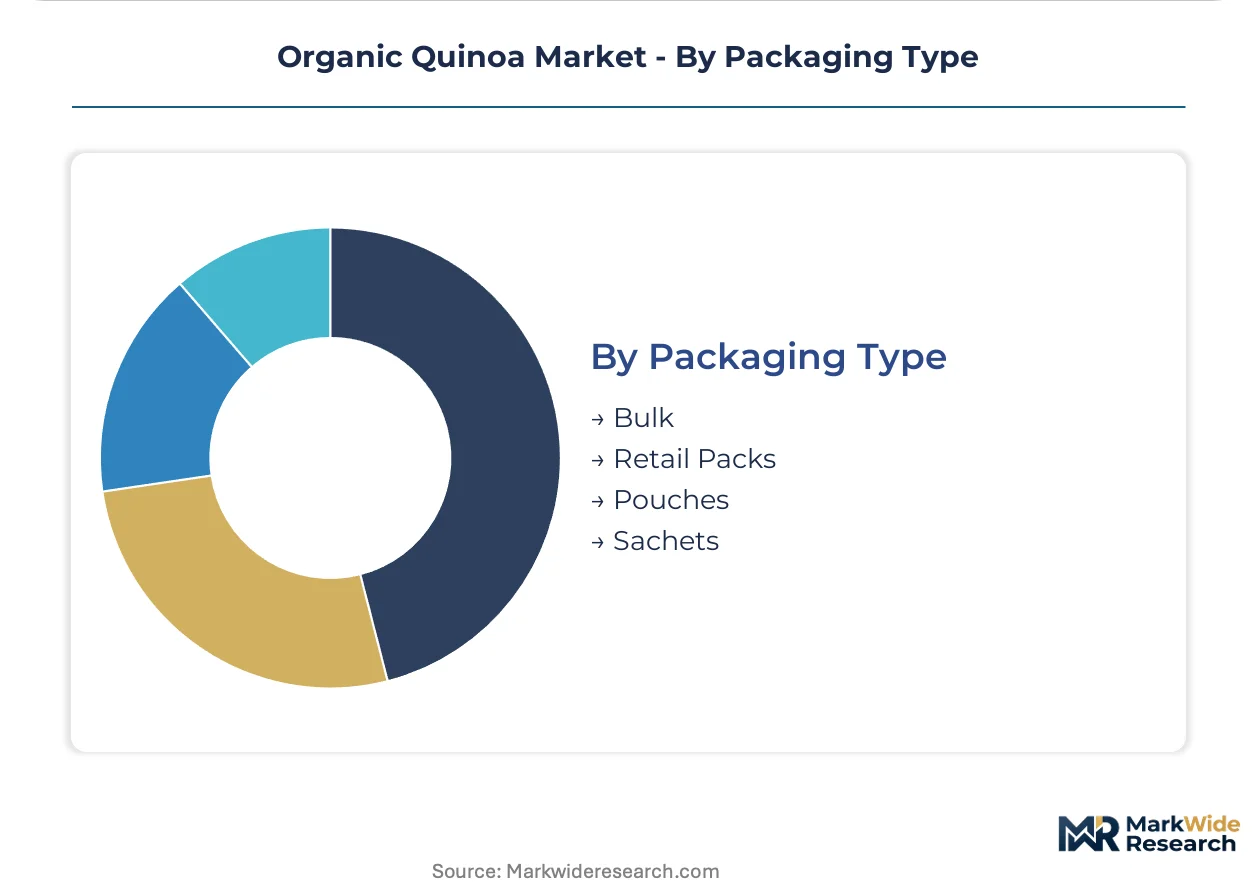
- Bulk:Food manufacturers and food service distributors purchase 25kg to 1-tonne sacks for in-house processing or institutional kitchen preparation. This format minimizes per-unit packaging cost but demands customer-side handling infrastructure.
- Retail Packs:12-16 ounce stand-up pouches with reseal features dominate supermarket and natural channel shelf sets. Graphics-intensive packaging supports brand storytelling and certification badge visibility.
- Pouches:Single-serve and family-size flexible formats serve convenience-oriented household segments.
- Sachets:Portion-controlled samples and trial sizes support new product introduction and on-the-go consumption occasions.
Bulk commands the highest total volume, with retail packs delivering the strongest margin contribution per kilogram.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Andean agronomists and organic certification specialists anchor production concentration across the Altiplano plateau, while European regulatory expertise and North American procurement sophistication shape demand geography.
Peru
USDA Organic certification compliance drives exporter eligibility for North American buyers. The country's national organic program enforces origin-level standards that SENASA administers through field inspections. Puno and Cusco departments concentrate smallholder cooperatives supplying Andean Naturals with direct-farm traceability data.
Bolivia
Altiplano drought cycles create systemic yield risk for Oruro and Potosí growers. SENASAG oversight mandates third-country equivalency documentation for EU market access. The Uyuni salt flat periphery hosts emerging mechanical saponin abrasion facilities reducing water intensity.
Germany
EU Organic Regulation 2018/848 enforcement tightens third-country audit protocols for Andean imports. The EFSA evaluates heavy metal testing documentation from quinoa protein isolate suppliers. Hamburg port logistics clusters handle bulk ingredient redistribution to Netherlands and French processors.
United States
Natural channel retail expansion at Whole Foods Market and Sprouts Farmers Market concentrates procurement through certified ingredient brokers. The USDA National Organic Program governs shelf placement claims and institutional procurement eligibility. Boulder, Colorado hosts Ancient Harvest's gluten-free flour blend manufacturing.
Netherlands
Scope 3 water footprint targets drive specification of dry-processed quinoa among ingredient buyers. Rotterdam port infrastructure handles EU redistribution with carbon footprint labeling alignment to EU Green Deal requirements. Amsterdam-based trading houses coordinate Fairtrade-certified sourcing for Alter Eco's European retail positioning.
Organic Quinoa Market Competitive Landscape
Top-tier vendors anchor direct-origin procurement with field-to-fork data capture, while commodity traders face margin compression from traceability demands. The vendor base stratifies across vertically integrated Andean exporters, North American ingredient manufacturers, and European Fairtrade specialists. Strategic archetypes include certified-volume aggregators, nutraceutical-grade isolators, and private-label blenders. Competitive moves concentrate on long-term contracting structures and mechanical processing technology licensing.
Within the Andean-origin tier, Andean Naturals and Irupana Andean Organic Food represent certified-volume aggregators leveraging Altiplano cooperative networks. Alter Eco occupies a position exemplifying European Fairtrade positioning through premium retail channel access. Ancient Harvest anchors the North American ingredient manufacturing archetype with gluten-free flour blend capabilities.
| Leading Market Players |
|---|
| Andean Naturals |
| Alter Eco |
| Quinoa Foods Company |
| Northern Quinoa Production Corporation |
| The British Quinoa Company |
| Inca Organics |
| Ancient Harvest |
| Irupana Andean Organic Food |
| Above Food Inc. |
| Others |
Value Network & Pricing Analysis
Organic guano and biological pest control inputs trace divergent cost paths through Peru and Bolivia's Altiplano cooperatives into premium-certified and conventional-grade pricing tiers. North American buyers absorb elevated traceability infrastructure costs through multi-year contracting while European importers face compressed margins from EU Organic Regulation 2018/848 compliance overhauls.
Pricing Analysis
Certification-bundled versus unbundled service splits separate premium organic quinoa from conventional commodity grain. Three-tier pricing structure across premium, standard, and economy levels stratifies by USDA Organic or EU Organic Regulation tier, with brand premiums attaching to Fairtrade-labeled SKUs. Price differentiation stems from traceability documentation intensity and volume scale, with cost compression in mid-tier white quinoa intensifying because mechanical saponin abrasion technology licensing concentrates among German and Dutch equipment suppliers. Food service procurement teams exhibit highest price sensitivity, while nutraceutical isolate buyers show least sensitivity due to functional protein content specifications.
Supply Chain Analysis
Direct-to-manufacturer channels handle hyperscale ingredient buyer demand for quinoa protein isolates and gluten-free flour blends. Geographic supply concentrates in Peru, Bolivia, and emerging Ecuador, with raw material dependencies on organic guano, biological pest control agents, and water resources for traditional saponin removal. Distribution runs through Rotterdam and Hamburg port logistics clusters for EU redistribution, with single-source vulnerability from Altiplano drought cycles creating systemic yield risk without geographic diversification buffers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential in organic quinoa rests on mechanical processing technology cost-down curves and nutraceutical-grade anthocyanin extraction premiums displacing commodity grain positioning.
For Market Incumbents: Cement direct-farmer data capture capabilities through GPS-enabled farm mapping and blockchain traceability integration before EU Organic Regulation equivalency renegotiations compress competitor timelines. Defend against emerging Ecuador-based first-movers by locking long-term offtake agreements with Puno and Cusco cooperatives, using certification investment as the anchor lever for dual US-European market access. For New Entrants and Emerging Players: The premium-economy price-point gap in black quinoa nutraceutical applications offers white-space entry before incumbent isolate suppliers saturate German and Netherlands supplement formulator relationships. Target Ecuador's underdeveloped organic sector for certified supply chain establishment ahead of competitor saturation, deploying Fairtrade-certified positioning as the go-to-market angle for European retail channel access. For Investors and Strategic Acquirers: Consolidation pressure builds where audit costs per farmer exceed individual revenue contributions among Bolivia's smallholder cooperatives. Long-term viability favors vertically integrated exporters with field-to-fork data capture capabilities over commodity traders facing traceability-driven margin compression. Watch for mechanical saponin abrasion facility licensing announcements as inflection indicators for water-stressed origin expansion potential.| Strategic Initiative | Industry Significance |
|---|---|
| Mechanical Saponin Abrasion Licensing | German and Dutch equipment deployment cuts water use 70% for EU Green Deal alignment. |
| Direct-Origin Procurement Contracts | Farm-level GPS documentation satisfies ESG reporting for North American ingredient buyers. |
| Dual Certification Stack Maintenance | USDA Organic plus EU Organic Regulation compliance secures simultaneous Atlantic market access. |
| Nutraceutical-Grade Isolate Capacity | 14%+ protein content with heavy metal testing documentation unlocks supplement formulation partnerships. |
| Ecuador Supply Chain Establishment | First-mover certified production before competitor saturation captures emerging origin premiums. |
Research Methodology
Bottom-up nutraceutical and food service demand modeling reconciled against top-down Andean production tracking forms the analytical core. Primary interviews with organic certification auditors, Altiplano cooperative managers, ingredient procurement directors at North American manufacturers, and EU-based supplement formulators combined with secondary validation from SENASA and SENASAG export documentation, EU Organic Regulation 2018/848 equivalency filings, and USDA National Organic Program certification records. Triangulation across these sources anchors volume and value estimates.
Historical trendline analysis of certified organic grain pricing and production volumes established baseline growth patterns across the projection horizon. Segmentation dimensions modeled include quinoa variety, end-use application, distribution channel, and packaging format, with CAGRs derived from regression analysis of supply expansion constraints and demand pull from clean-label plant protein reformulation. Forecast inputs incorporate Altiplano drought frequency data and mechanical processing technology adoption curves.
Caveats apply where EU Organic Regulation equivalency renegotiations or Altiplano climate volatility could materially shift the outlook. Forecasts reflect assumptions around certification timeline compression and traceability system integration feasibility. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Coir Market
Agriculture and Agri Products
South America Poultry Feed Market
Agriculture and Agri Products
E-Commerce of Agricultural Products Market
Agriculture and Agri Products
Algae-Based Animal Feed Market
Agriculture and Agri Products
Ethiopia Agriculture Sector Market
Agriculture and Agri Products
Tunisia Agriculture Market
Agriculture and Agri Products
Sophora Japonica Market
Agriculture and Agri Products
Cassava Starch Market
Agriculture and Agri Products
Asia-Pacific Chaga Mushroom Market
Agriculture and Agri Products
Boswellia Market
Agriculture and Agri Products
Compound Horse Feedstuff Market
Agriculture and Agri Products
Sugar Cane Market
Agriculture and Agri Products
Spain Alfalfa Hay Market
Agriculture and Agri Products
North America Animal Protein Market
Agriculture and Agri Products
Kuwait Poultry Meat Market
Agriculture and Agri Products
Organic Feed Market