
 Perilla Seed Oil Market | 2026-2036
Perilla Seed Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Perilla Seed Oil Market Insights
Multi-source procurement is restructuring supply security across the perilla seed oil value chain. Hubei Shizhen anchors upstream cultivation networks across central China. Gustav Heess competes through cold-pressing specialization for European cosmetic grade demand. Sanmark leverages organic certification to differentiate within nutraceutical channels.
Perilla seed oil is an edible vegetable oil extracted from Perilla frutescens seeds, containing alpha-linolenic acid concentrations exceeding sixty percent in cold-pressed grades, primarily serving functional food and cosmetic applications requiring high omega-3 stability. Cold-pressed oil commands premium positioning due to retained phytosterol and polyphenol profiles, while refined grades dominate food flavoring volumes where thermal stability matters. Nutraceutical applications represent the fastest-expanding segment as dietary supplement producers seek plant-derived ALA alternatives to fish oil.
China's SAMR enforces GB standards for edible oil purity and labeling, directly shaping export eligibility for domestic crushers. Japan's MHLW through PMDA-aligned specifications governs pharmaceutical-grade perilla oil used in approved supplement formulations. Korea's MFDS maintains residual solvent limits that filter low-cost refined imports. Stakeholders must monitor evolving ALA content disclosure requirements as regulatory bodies tighten substantiation standards for omega-3 health claims.
Market Dynamics
Omega-3 ALA sourcing strategies are restructuring competitive positioning across the perilla seed oil value chain. Nutraceutical formulators now prioritize cold-pressed grades with verified phytosterol retention, forcing crushers to recalibrate extraction protocols and certification investments.
Growth Catalysts
- Japan's MHLW supplement approval pathways:Pharmaceutical-grade perilla oil gains formal recognition in approved omega-3 formulations, expanding institutional procurement channels.
- Plant-based omega-3 substitution:Dietary supplement producers actively reformulate away from marine sources to address vegan demographic expansion and supply volatility concerns.
- Shandong-Hunan crushing clusters:Integrated cultivation-processing operations achieve cost efficiencies through captive seed supply and reduced logistics overhead.
Market Restraints
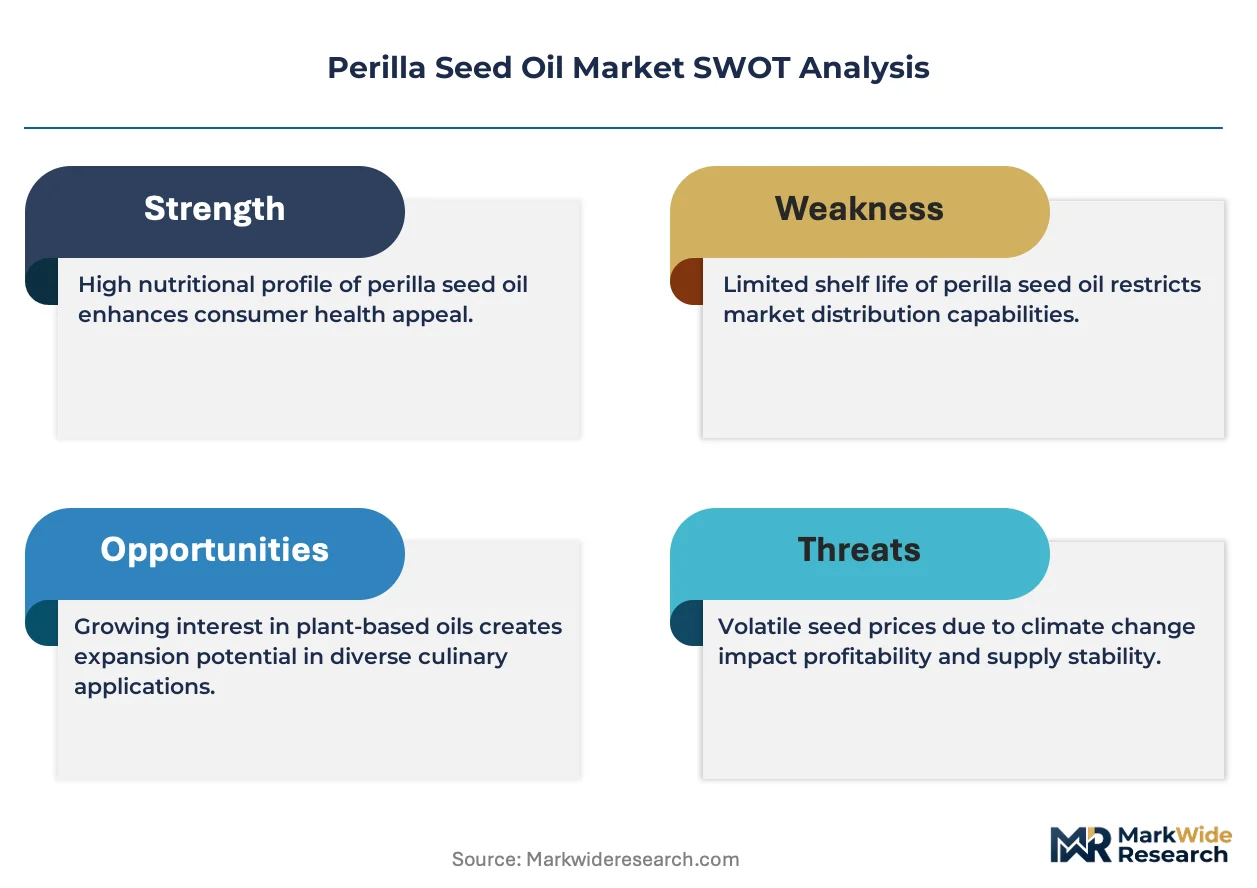
- Perilla seed price volatility:Weather-dependent annual harvests in central Chinese provinces create input cost instability for non-integrated processors.
- Residual solvent thresholds:Korea's MFDS maintains strict hexane limits that disqualify conventional refined imports from mass-market positioning.
- Fish oil ALA bioavailability perception:Marine-derived omega-3 retains clinical validation advantages in physician-directed supplement recommendations.
Strategic Opportunities
- EU cosmetic grade expansion:Cold-pressed organic grades with ECHA-compliant contaminant profiles access premium skincare formulation channels.
- Carbon-neutral extraction certification:Dual carbon goals under China's MEE create compliance-linked procurement preferences for low-emission crushing operations.
- Direct-to-practitioner distribution:Functional medicine networks bypass conventional retail markup structures for clinical-grade ALA supplements.
Industry Challenges
- Organic certification timeline compression:Three-year transition periods for cultivation land lock out rapid supply scaling during demand surges.
- ALA oxidation stability protocols:Packaging and storage infrastructure requires nitrogen-flushing capabilities that strain mid-scale processor capital allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Perilla Seed Oil Market |
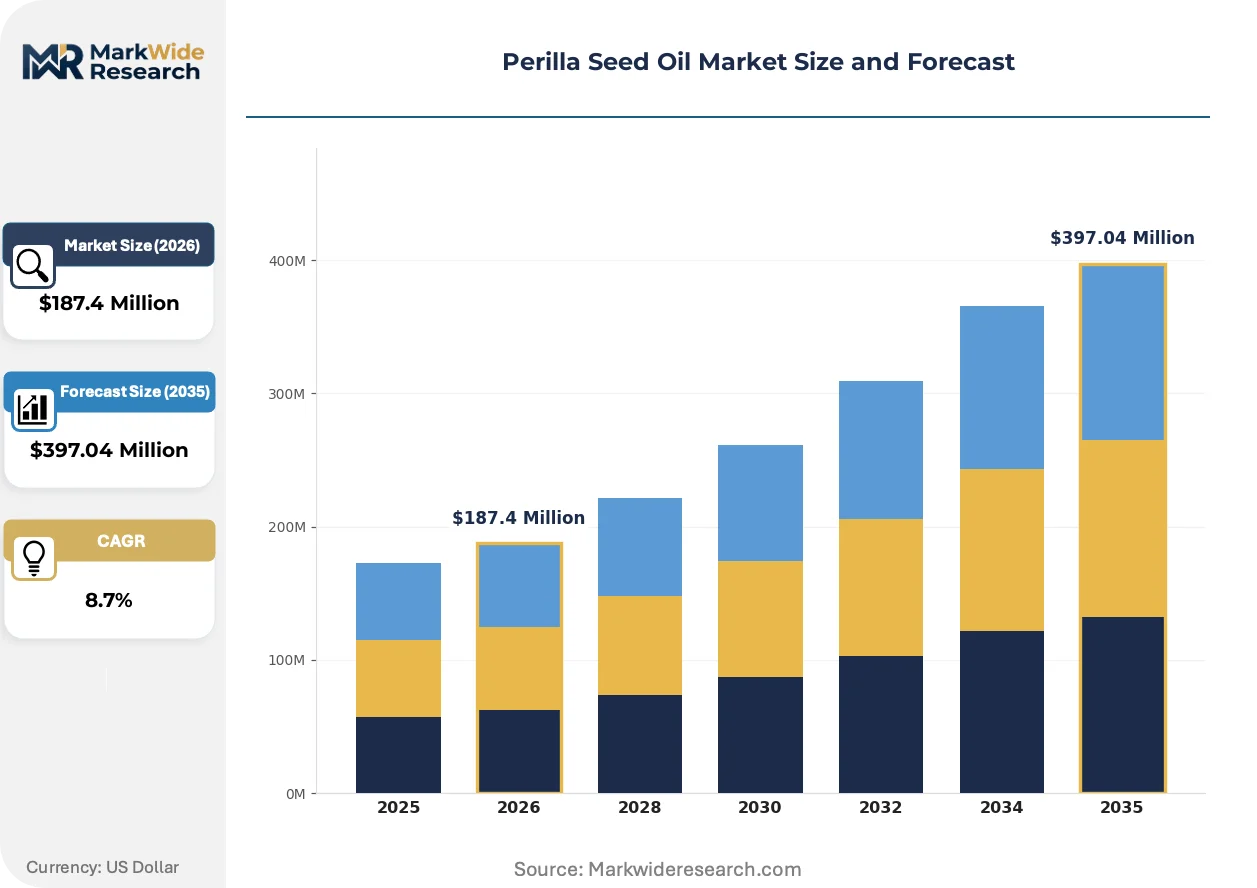
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cold-Pressed, Refined, Organic, Blended Application: Food Flavoring, Nutraceuticals, Cosmetics, Pharmaceutical Supplements, Animal Feed End User: Food Manufacturers, Dietary Supplement Producers, Personal Care Brands, Animal Husbandry Operators Packaging Type: Glass Bottles, PET Bottles, Sachets, Bulk Containers |
| Companies Covered | Hubei Shizhen, Hebei Jiafeng Plant Oil, Hunan Yamei Biotechnology, Sanmark, San Sheng Nong Lin, Huanan Nongsheng, Zonghoo Jianyuan Biotech, Komega, Gustav Heess, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Perilla Seed Oil Market Trends and Innovations
Extraction technology convergence and regulatory disclosure mandates are compressing traditional grade differentiation in perilla seed oil. Stakeholders now compete on traceability infrastructure and real-time quality verification rather than conventional cold-versus-refined positioning.
Supercritical CO2 extraction systems are unifying cosmetic and nutraceutical grade specifications through solvent-free processing. European botanical extractors adopt these units to satisfy EFSA contaminant thresholds without sacrificing phytosterol yields. The technology is unifying previously separate premium tiers into single-stream certification pathways.
REACH-aligned substance registration requirements in Europe now govern perilla oil imports as cosmetic ingredients. ECHA dossier obligations force non-EU crushers to invest in third-party toxicological testing and exposure scenario documentation. Small-scale Asian suppliers face exclusion from EU cosmetic channels without dedicated regulatory affairs capacity.
Buyer consolidation among contract supplement manufacturers is shortening supplier qualification cycles. Large nutraceutical formulators now mandate blockchain-tracked seed-to-oil documentation, displacing traditional certificate-of-analysis relationships. This pattern concentrates procurement authority with vertically integrated Chinese and Japanese processors possessing captive cultivation networks.
Perilla Seed Oil Market Segmentation
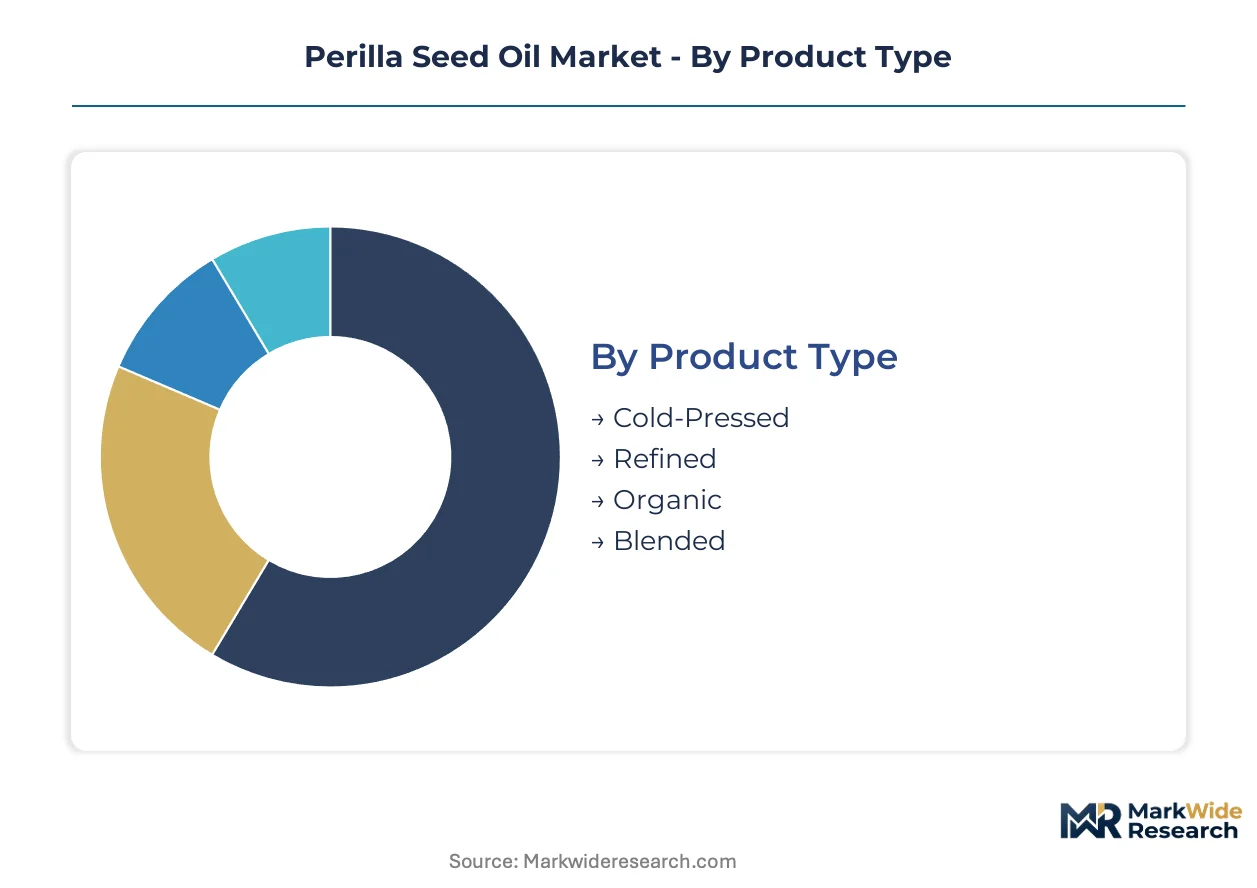
Perilla seed oil segmentation reflects divergent technical requirements across extraction methods and end-use specifications. Grade differentiation determines regulatory pathways, shelf-life protocols, and pricing tiers that shape procurement decisions.
Product Type:
Cold-pressed grades serve standalone nutraceutical applications with minimal processing, while refined and blended variants embed into formulated food systems requiring thermal stability.
- Cold-Pressed:Mechanical extraction at temperatures below 40°C preserves alpha-linolenic acid concentrations exceeding sixty percent alongside intact phytosterol and polyphenol profiles. Dietary supplement producers in Japan's PMDA-aligned procurement channels specify this grade for omega-3 encapsulation.
- Refined:Degumming, neutralization, and deodorization strips free fatty acids and peroxides to extend fry-life stability for commercial food manufacturing. China's GB standards govern permissible residual contaminant levels for domestic retail distribution.
- Organic:Three-year cultivation transition periods and certifier-audited crushing operations access premium cosmetic and supplement positioning in EU REACH-registered channels.
- Blended:Formulations with rice bran or camellia oil adjust smoke points and cost structures for mass-market food service applications.
Volume placements concentrate in refined grades for food manufacturing; the faster expansion belongs to cold-pressed organic certification tiers.
Application:
Application segmentation tracks divergent stability requirements, from ambient retail shelf life to clinical-grade oxidation control protocols.
- Food Flavoring:Refined perilla oil imparts distinct nutty-herbal notes to Korean banchan and Chinese cold dishes where thermal degradation is minimal. Restaurant chains in Shandong province specify bulk refined deliveries for standardized flavor profiles.
- Nutraceuticals:Softgel encapsulation demands peroxide values below 5 meq/kg and verified ALA retention through nitrogen-flushed packaging. Japan's MHLW supplement approval pathways now recognize pharmaceutical-grade perilla oil in approved omega-3 formulations.
- Cosmetics:ECHA-compliant contaminant profiles and supercritical CO2 extraction satisfy EU skincare formulator requirements for solvent-free botanical actives.
- Pharmaceutical Supplements:Clinical-grade specifications require batch-level ALA assay documentation and stability testing under ICH guidelines for practitioner-directed distribution.
- Animal Feed:Omega-3 enrichment of poultry and aquaculture feed utilizes lower-grade press cake extracts with reduced fatty acid purity thresholds.
Cosmetic and nutraceutical applications are gaining share fastest; food flavoring retains the largest shipment volumes.
End User:
End user segmentation distinguishes between formulation integration depth and regulatory compliance burden.
- Food Manufacturers:Industrial buyers procure refined grades in bulk containers for sauce, dressing, and prepared meal applications where cost efficiency dominates specification.
- Dietary Supplement Producers:Contract manufacturers mandate blockchain-tracked seed-to-oil documentation and third-party ALA assay verification for retail shelf placement.
- Personal Care Brands:European botanical extractors require EFSA-aligned toxicological dossiers and REACH registration for cosmetic ingredient imports.
- Animal Husbandry Operators:Feed compounders source solvent-extracted press cake derivatives for omega-3 enriched egg and fish production.
Dietary supplement producers command premium pricing; food manufacturers drive aggregate tonnage.
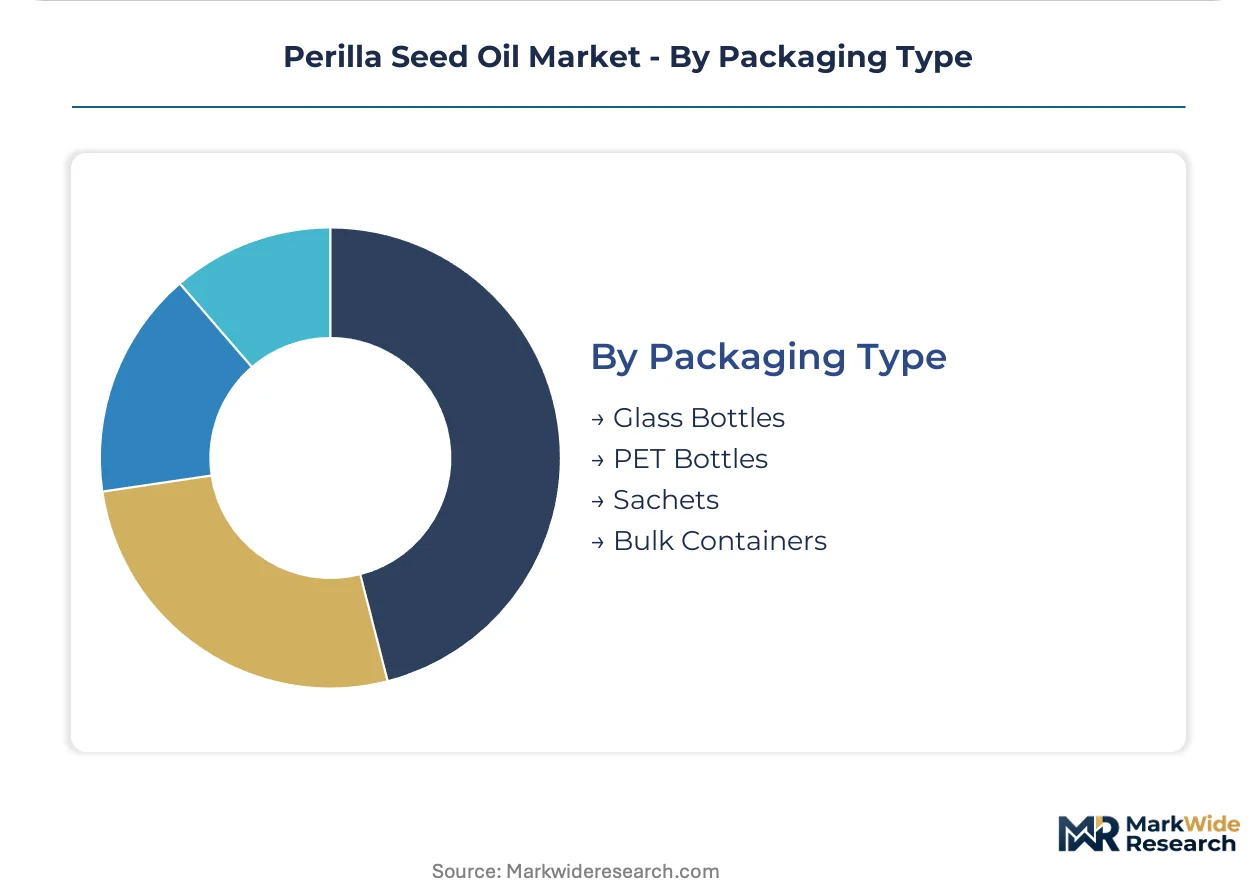
Packaging Type:
Packaging segmentation aligns oxidation protection requirements with distribution channel economics.
- Glass Bottles:Amber and cobalt glass with nitrogen flushing preserves cold-pressed oil integrity for premium retail and cosmetic ingredient channels. Higher unit costs restrict deployment to low-volume, high-margin segments.
- PET Bottles:Lightweight, shatter-resistant containers serve mass-market food retail with oxygen barrier multilayer constructions. China's SAMR enforces migration testing for plastic contact with edible oils.
- Sachets:Single-serve foil laminates support food service portion control and sample distribution for supplement marketing campaigns.
- Bulk Containers:Stainless steel totes and flexitanks minimize per-unit logistics costs for integrated crushers supplying downstream formulators directly.
Bulk containers dominate inter-processor transfers; sachet formats are climbing fastest for direct-to-consumer trial programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Central Chinese provinces anchor perilla seed cultivation, with Shandong and Hunan crushing clusters processing the majority of global feedstock. Regulatory divergence across East Asian markets shapes export eligibility and grade specifications. Procurement patterns concentrate around integrated cultivation-processing operations with captive seed supply.
China
Shandong and Hunan provinces host the densest concentration of perilla cultivation and integrated crushing infrastructure. SAMR enforces GB standards for edible oil purity, contaminant thresholds, and labeling requirements that directly govern domestic retail distribution and export eligibility. Hubei Shizhen anchors upstream networks across central China, linking provincial agricultural cooperatives to industrial-scale oil extraction.
Japan
Pharmaceutical-grade perilla oil demand concentrates in supplement formulations seeking PMDA-aligned approval pathways. MHLW recognition of plant-derived omega-3 in approved formulations expands institutional procurement channels beyond conventional retail. Komega and domestic formulators source cold-pressed grades with verified ALA retention for softgel encapsulation.
South Korea
MFDS residual solvent limits filter low-cost refined imports, creating regulatory preference for cold-pressed or supercritical CO2-extracted grades. Domestic supplement manufacturers reformulate toward plant-based ALA alternatives to marine sources. Seoul-based distributors consolidate procurement authority through direct relationships with Chinese crushing clusters.
Germany
REACH-aligned substance registration governs perilla oil imports as cosmetic ingredients, forcing toxicological dossier investment from non-EU suppliers. ECHA contaminant thresholds and EFSA-aligned specifications shape premium skincare formulation demand. Gustav Heess competes through cold-pressing specialization for European cosmetic grade channels.
United States
FDA dietary supplement regulations govern ALA content disclosure and health claim substantiation for perilla-derived omega-3 products. Functional medicine networks bypass conventional retail markup structures for clinical-grade distribution. West Coast formulators source organic-certified cold-pressed grades with blockchain-tracked seed-to-oil documentation.
Perilla Seed Oil Market Competitive Landscape
Capacity expansion dominates the current landscape as integrated Chinese processors scale crushing operations to capture nutraceutical demand growth. The vendor base clusters around three strategic tiers: provincial agricultural conglomerates with captive cultivation networks, specialized cold-pressing operators serving premium cosmetic channels, and certified organic suppliers accessing EU and North American premium segments. Competitive intensity concentrates on extraction technology differentiation and regulatory certification speed rather than price alone. Geographic expansion through direct-to-practitioner distribution and backward integration into seed supply chains represent the dominant competitive moves.
Among Chinese provincial specialists, Hubei Shizhen, Hebei Jiafeng Plant Oil, and Hunan Yamei Biotechnology exemplify the agricultural conglomerate archetype with integrated cultivation-processing footprints. Sanmark occupies a position within the certified organic tier, leveraging third-party verification to differentiate within nutraceutical channels. Gustav Heess anchors the European cold-pressing specialization vector, serving cosmetic formulators with ECHA-compliant contaminant profiles. These three archetypes—provincial integrators, organic certifiers, and European specialists—collectively represent the competitive structure's dominant positioning vectors.
| Leading Market Players |
|---|
| Hubei Shizhen |
| Hebei Jiafeng Plant Oil |
| Hunan Yamei Biotechnology |
| Sanmark |
| San Sheng Nong Lin |
| Huanan Nongsheng |
| Zonghoo Jianyuan Biotech |
| Komega |
| Gustav Heess |
| Others |
Pricing and Supply Chain Analysis
Blockchain-tracked seed-to-oil documentation mandates from large nutraceutical formulators are forcing mid-scale processors to invest in traceability infrastructure or exit premium channels, compressing margins for non-compliant suppliers while concentrating pricing power with integrated operators. This procurement shift feeds directly into extraction technology decisions and certification timelines that reshape cost structures across the value chain.
Pricing Analysis
Certification-bundled service packages separate compliant suppliers from commodity traders, with organic verification and third-party ALA assay documentation commanding substantial premiums over certificate-of-analysis-only relationships. Price differentiation hinges on cold-pressing grade purity and ECHA-compliant contaminant profiles for EU cosmetic channels. Cost compression in refined food-grade tiers is intensifying because restaurant chains and industrial buyers prioritize volume scale over phytosterol retention. Dietary supplement producers show least price sensitivity; mass-market food manufacturers drive aggregate tonnage at thin margins.
Supply Chain Analysis
China's dual carbon goals under MEE are reshaping sourcing preferences toward low-emission crushing operations with captive renewable energy supply. Feedstock concentration centers on Shandong and Hunan provinces, with secondary processing clusters in Hebei and Hubei. Raw material dependencies include perilla seed harvests from central Chinese agricultural cooperatives, hexane for conventional refined extraction, and nitrogen gas for oxidation-protective packaging. Single-source vulnerability runs through weather-dependent annual harvests in drought-prone provinces. Distribution runs through stainless steel totes for inter-processor transfers and amber glass bottles for premium retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance arena where Japan's PMDA-aligned supplement approval pathways erect formidable barriers to entry, rewarding players with existing regulatory dossiers and toxicological testing infrastructure while excluding capital-constrained challengers from institutional procurement channels.
For Market Incumbents: Deploy supercritical CO2 extraction capacity to unify cosmetic and nutraceutical grade specifications, eliminating solvent-residue compliance risks from Korea's MFDS thresholds. Expand backward integration into seed supply chains across Hunan and Shandong to buffer input cost volatility from weather-dependent harvests. Consolidate procurement relationships with Seoul-based distributors before emerging Chinese provincial specialists achieve comparable certification breadth. For New Entrants and Emerging Players: Functional medicine practitioners represent an underserved buyer archetype bypassing conventional retail markup structures for clinical-grade ALA supplements with ICH-aligned stability documentation. Direct-to-practitioner distribution offers the most penetrable channel given established players' concentration on mass-market supplement manufacturers. Pursue carbon-neutral extraction certification under China's MEE framework to access compliance-linked procurement preferences from sustainability-focused formulators. For Investors and Strategic Acquirers: Re-rating potential sits with certified organic suppliers possessing REACH-registered EU cosmetic channels given ECHA dossier obligations forcing toxicological testing investment from non-EU crushers. Long-term viability favors operators with three-year cultivation transition periods already completed and blockchain-tracked seed-to-oil infrastructure operational. Watch ALA oxidation stability protocol adoption rates among mid-scale processors as the inflection indicator for certification-tier consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Extraction Deployment | Solvent-free processing satisfies ECHA contaminant thresholds while preserving phytosterol yields for premium tiers. |
| Backward Integration into Seed Supply | Captive cultivation networks in Shandong and Hunan buffer weather-driven input cost volatility for integrated crushers. |
| Carbon-Neutral Certification Program | Dual carbon compliance under China's MEE creates procurement preference moats against conventional hexane-based competitors. |
| Direct-to-Practitioner Distribution Launch | Functional medicine networks bypass retail markup structures for clinical-grade ALA supplements with ICH stability documentation. |
| REACH Registration Completion | ECHA dossier obligations force toxicological testing investment that excludes small-scale Asian suppliers from EU cosmetic channels. |
Research Methodology
Document review covered regulatory filings from Japan's PMDA and Korea's MFDS, complemented by interviews with crushing plant managers in Shandong, procurement leads at dietary supplement contract manufacturers, organic certification auditors, and EU cosmetic formulators. Secondary validation drew from SAMR GB standards documentation, ECHA REACH registration databases, customs trade records for perilla seed oil shipments, and SEC filings from listed nutraceutical companies. Bottom-up volume estimates from processor capacity utilization were cross-referenced against top-down demand calculations from end-use consumption patterns.
Historical extraction technology adoption curves were cross-referenced against expert panel input from supercritical CO2 equipment suppliers and cold-pressing specialists. The analytical framework modeled grade tier, application segment, packaging format, and regional regulatory cluster across the projection horizon. CAGRs were derived from segment-level growth rate reconciliation with aggregate market expansion. Industry-specific forecast inputs included organic certification transition timelines and nitrogen-flushing packaging infrastructure deployment rates.
Revisions become necessary when PMDA approval pathway modifications, MFDS residual solvent threshold adjustments, or MEE carbon intensity recalibrations materialize beyond current regulatory trajectories. Forecasts reflect documented assumptions regarding seed yield stability and ALA retention through alternative extraction methods. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Global Seed Market
Seeds
Crambe Abyssinica Seed Oil Market
Seeds
Europe Sesame Seed Market
Seeds
North America Chia Seeds Market
Seeds
Buckwheat Market
Seeds
Vietnam Seed Market
Seeds
North America Vegetable Seed Market
Seeds
Chamomile Seeds Market
Seeds
Southeast Asia Vegetable Seed Market
Seeds
China Rice Seed Market
Seeds
Watermelon Seeds Market
Seeds
Agricultural Seeder Market
Seeds
Field Crop Seeds Market
Seeds
Grass Seed Market
Seeds
Global Sunflower Market
Seeds
Flax Crop Market