
 Flooring Adhesive Market | 2026-2036
Flooring Adhesive Market Size, Share, and Industry Trends Forecast 2026-2036
Flooring Adhesive Market Intelligence
The capital-intensity divergence in automated batch processing for reactive adhesives is collapsing, enabling smaller specialists to challenge incumbents. Sika AG leverages its global manufacturing footprint to achieve economies of scale in polyurethane production. H.B. Fuller Company differentiates through specialized hot melt adhesive formulations for niche flooring applications, while Arkema competes on the strength of its advanced acrylic polymer chemistry. Henkel AG & Co. KGaA sustains its market position through extensive distribution networks targeting both professional contractors and DIY enthusiasts.
Flooring adhesives are chemical formulations designed to bond floor coverings like tile, carpet, and vinyl to a subfloor. These products must achieve specific shear strength and flexibility while managing cure times during installation. Water-based adhesives dominate the residential segment due to ease of use and low VOC content. In contrast, high-performance epoxy and polyurethane systems command premium pricing in demanding commercial and industrial applications where durability and chemical resistance are critical performance factors.
Product formulations are governed by environmental and safety standards, including the US EPA's rules on VOCs and the EU's REACH regulation. In China, national GB standards dictate performance and safety criteria for construction materials, influencing market access. Navigating these divergent regional standards while developing sustainable, bio-based adhesive alternatives presents a central strategic challenge for all suppliers seeking to expand their geographic reach and product portfolios.
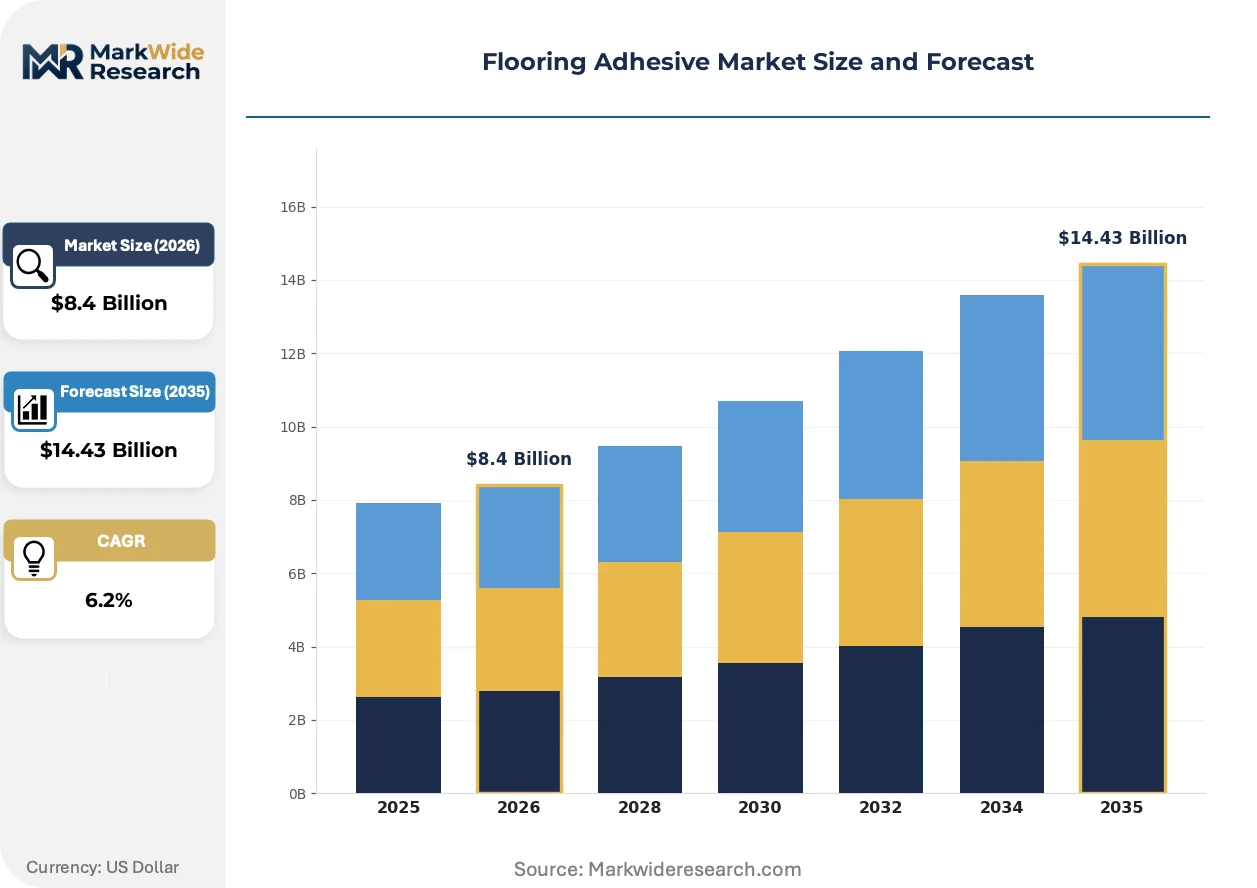
Market Dynamics
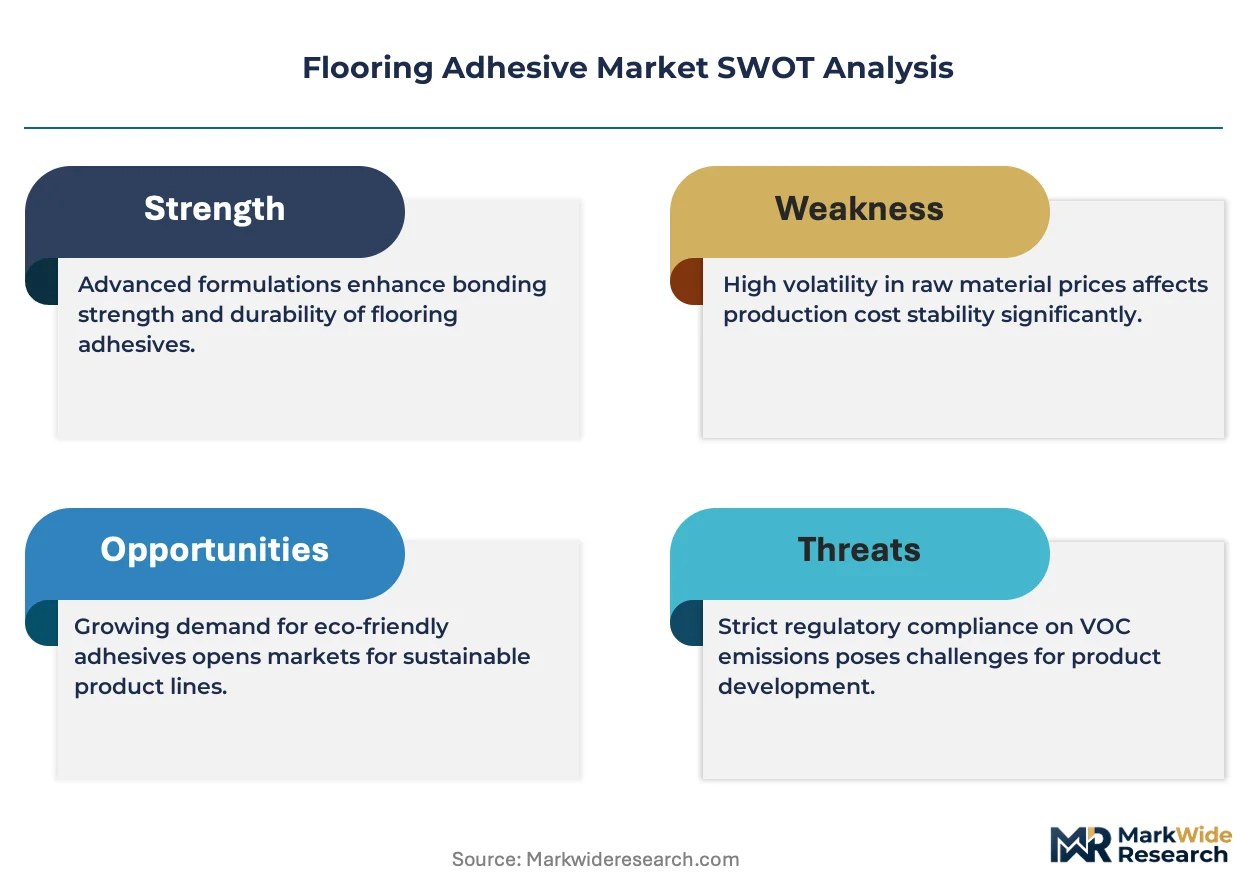
The flooring adhesive market is defined by the tension between stringent environmental regulations demanding low-VOC formulations and the high-performance requirements of commercial construction. This dynamic accelerates innovation in water-based, polyurethane, and bio-based adhesive chemistries, forcing a re-evaluation of product portfolios across all suppliers.
Growth Catalysts
- Regulatory Compliance:The EU's REACH regulation and US EPA rules on VOCs create demand for compliant adhesives, particularly in public-sector renovations.
- Infrastructure Expansion:Transportation and commercial projects in Asia and Latin America stimulate consumption of high-strength epoxy and polyurethane systems.
- Specialty Flooring Materials:Adoption of luxury vinyl tile (LVT) requires specifically formulated adhesives to manage cure times and ensure dimensional stability.
Market Restraints
- Raw Material Volatility:Price fluctuations for feedstocks like acrylic monomers and isocyanates, sourced from concentrated chemical suppliers, compress manufacturer margins.
- Long Cure Times:Certain two-component epoxy systems require extended curing, creating installation bottlenecks on projects with accelerated construction schedules.
- Substitution from Floating Floors:The adoption of click-lock floating floor systems in the residential sector for laminate and LVT eliminates the need for adhesives.
Strategic Opportunities
- Bio-Based Formulations:Adhesives from renewable feedstocks like plant starches can meet demand from green building certifications such as LEED and BREEAM.
- Middle East Markets:Commercial construction in Saudi Arabia and the UAE creates demand for specialized adhesives formulated for high heat and humidity.
- Heated Flooring Compatibility:A market exists for adhesives that maintain bond integrity with radiant floor heating systems, withstanding repeated thermal cycling.
Industry Challenges
- Regulatory Fragmentation:Navigating divergent regional standards, including China's GB standards and Europe's CE marking, increases product testing costs and complicates global supply chain management.
- Installer Skill Gap:A shortage of contractors trained in the correct application of advanced, two-component reactive adhesive systems can lead to installation failures and costly warranty claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flooring Adhesive Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $14.43 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based, Solvent-Based, Hot Melt, Reactive Material: Polyurethane, Epoxy, Acrylic, Silicone Application: Residential, Commercial, Industrial, Healthcare End User: Contractors, DIY Enthusiasts, Distributors, Manufacturers |
| Companies Covered | MAPEI S.p.A., Dow, Sika AG, Lanxess, Arkema, Henkel AG & Co. KGaA, Bostik, Pidilite Industries Ltd., H.B. Fuller Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flooring Adhesive Market Strategic Shifts & Innovations
A dual focus on sustainability and application efficiency is defining product development. Manufacturers are reformulating products to meet stringent environmental mandates while also addressing contractor demands for faster, more reliable installation methods on job sites.
Hybrid polymer adhesives merge the flexibility of silicones with the strength of polyurethanes. Commercial contractors are adopting these for installing engineered wood and LVT over difficult subfloors, such as concrete with residual moisture. The availability of these versatile, all-in-one products is fragmenting the traditional market segmentation between specialized moisture barriers and dedicated adhesives.
China’s national GB 18583 standard imposes strict limits on hazardous substances within adhesives for construction. This regulation compels manufacturers to shift production away from solvent-based formulations toward compliant water-based systems for the Chinese market. The residential flooring segment is most affected, as compliance is a prerequisite for market access and a key brand differentiator.
Specifiers are increasingly demanding complete, warranted flooring systems from a single source instead of purchasing components like adhesives separately. This behavior disrupts the traditional channel where contractors buy from general building material distributors, favoring manufacturers offering integrated warranties. The shift is most visible in large healthcare and education projects across Europe and North America where performance guarantees are critical.
Flooring Adhesive Market Segmentation
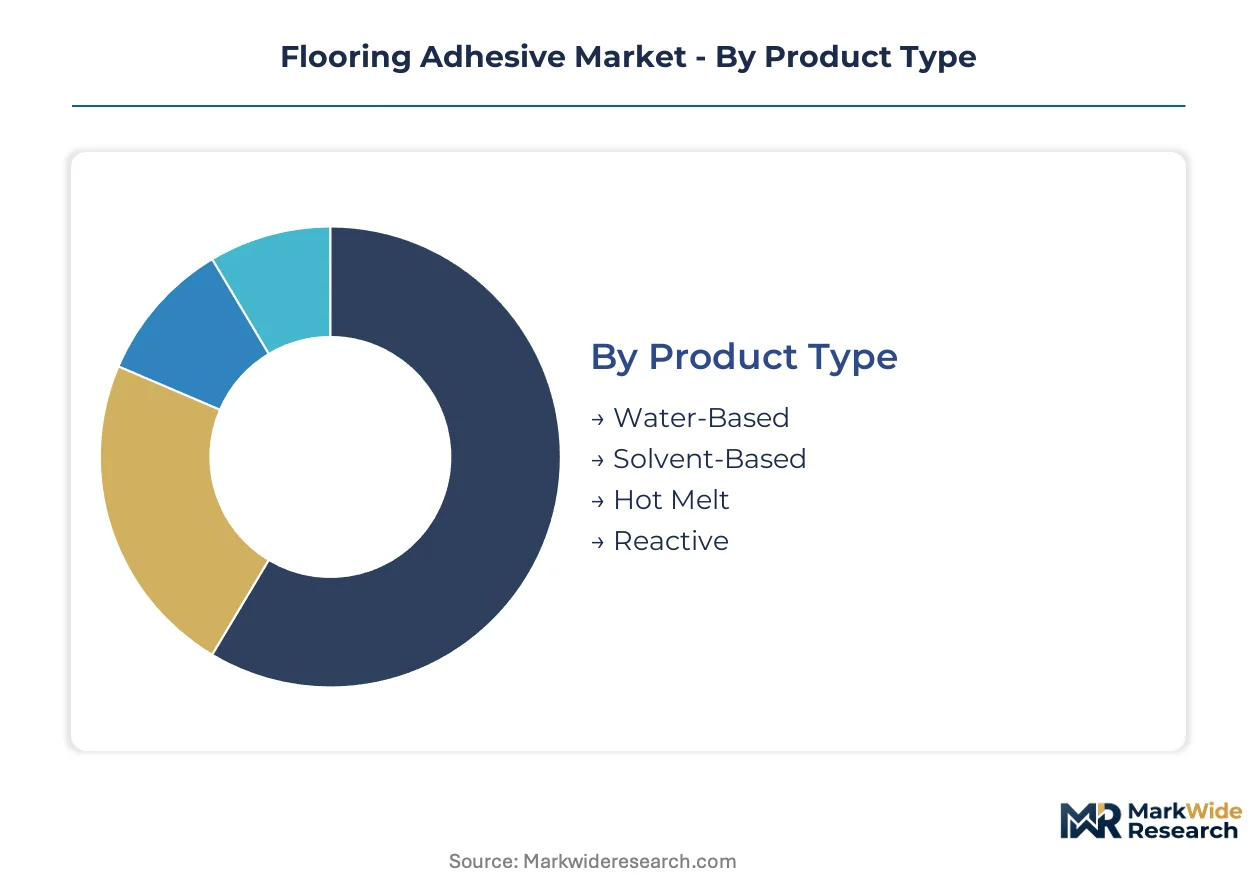
The flooring adhesive market's structure reflects diverse product performance requirements and end-user preferences. Understanding these segments is crucial for manufacturers to align product development with specific application demands and regulatory shifts. This segmentation analysis dissects the market's core constituents.
Product Type:
Substitution pressure is most pronounced for solvent-based adhesives, which face displacement by low-VOC alternatives across multiple geographies. Water-based formulations also see substitution from mechanical fastening systems in residential applications.
- Reactive:These multi-component systems, often epoxy or polyurethane, cure chemically for exceptional bond strength and chemical resistance. Demand concentrates in industrial and commercial construction in Germany and the United States.
- Water-Based:Formulated with polymers in water, these offer low VOCs and easy cleanup, suitable for residential use. Demand is strong in public-sector renovations across the European Union and Canada.
- Solvent-Based:These adhesives use organic solvents, offering strong initial tack but facing severe regulatory restrictions due to high VOCs.
- Hot Melt:Applied molten, these thermoplastic adhesives cool to form a bond, prized for fast setting times in specialized flooring.
Water-Based retains volume leadership; Reactive holds the steepest expansion curve.
Material:
The cost tiering of flooring adhesive materials reflects performance capabilities, with high-performance epoxy and polyurethane systems commanding premium pricing. Acrylic formulations offer a mid-range cost solution.
- Polyurethane:These versatile polymers offer excellent flexibility, adhesion, and moisture resistance, ideal for bonding engineered wood and LVT. Demand is significant in commercial projects across Brazil and India.
- Epoxy:Known for superior strength, chemical resistance, and rigidity, epoxy adhesives are two-part systems for demanding industrial and commercial environments. Critical for healthcare facilities and manufacturing plants in Saudi Arabia and Australia.
- Acrylic:These polymer-based adhesives provide good tack and flexibility, commonly used in water-based formulations for residential applications.
- Silicone:Offering high elasticity and moisture resistance, silicone adhesives are used for specialized applications like perimeter sealing and expansion joints.
Polyurethane formulations lead in versatility, while epoxy systems define the high-performance niche.
Application:
Volume consumption patterns for flooring adhesives are heavily influenced by construction cycles, with residential applications driving broad market demand. Commercial and industrial segments dictate premium product uptake.
- Commercial:This segment includes offices, retail spaces, and public buildings, where adhesives must withstand heavy foot traffic and provide long-term durability. Demand is strong in urban development projects across China and the United Kingdom.
- Residential:Encompassing single-family homes and multi-unit dwellings, this application prioritizes ease of use, low VOCs, and cost-effectiveness. The United States and Germany represent significant residential volumes.
- Industrial:Demanding extreme durability and chemical resistance, industrial applications include factories and warehouses, often requiring specialized epoxy or polyurethane systems.
- Healthcare:Hospitals, clinics, and laboratories require adhesives supporting sterile environments, ease of cleaning, and resistance to disinfectants, driving demand for high-performance products.
Residential applications account for the largest share, but commercial projects drive innovation in high-performance formulations.
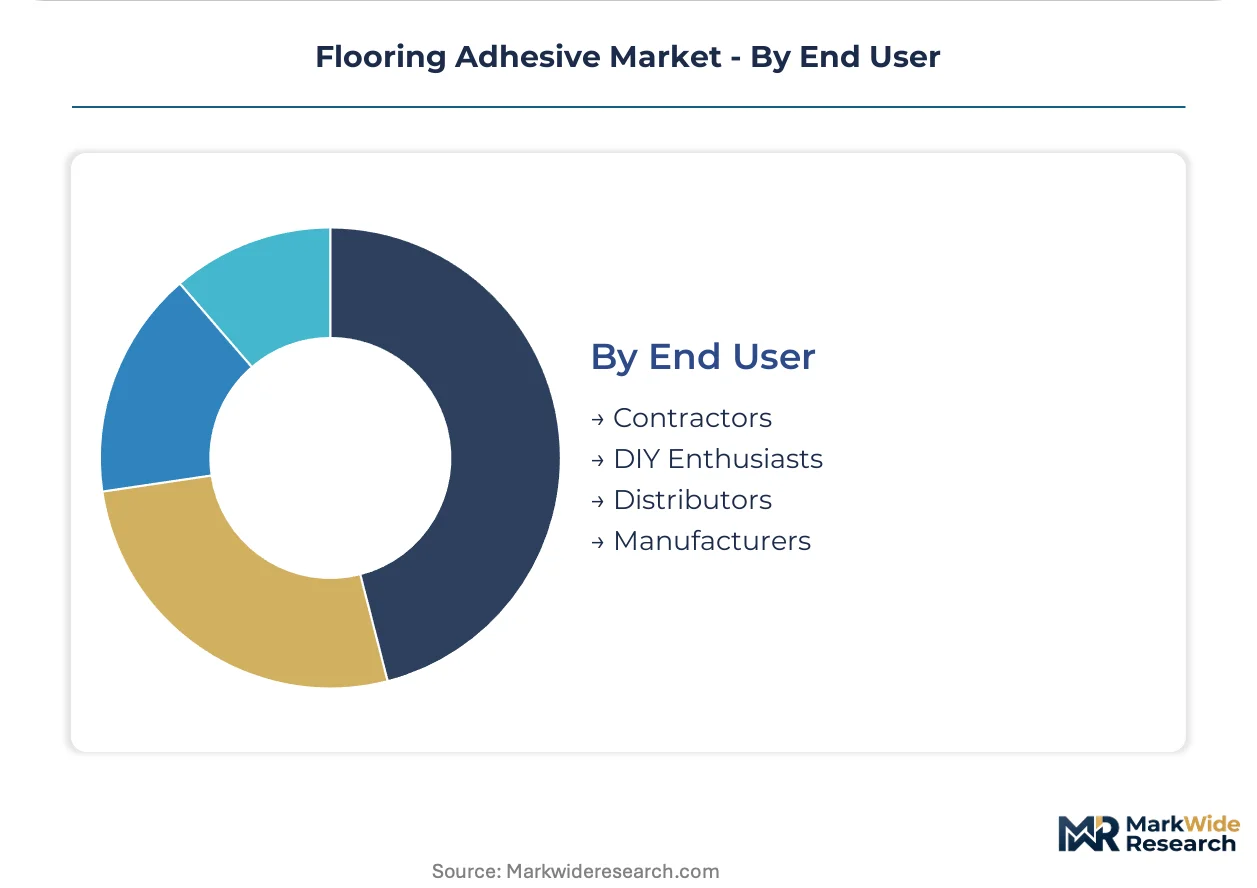
End User:
The diverse end-user landscape ranges from professional installers to individual consumers, each with distinct purchasing criteria. Professional contractors prioritize performance and efficiency, while DIY enthusiasts focus on ease of application.
- Contractors:Professional installers and construction firms represent the largest end-user segment, demanding reliable, high-performance adhesives that meet project specifications. Procurement is critical for large-scale commercial and industrial projects across France and Japan.
- Distributors:These entities serve as intermediaries, stocking a wide range of adhesive products and providing logistical support to contractors and retailers. Their role is vital in ensuring market access and product availability across Indonesia and Mexico.
- DIY Enthusiasts:Individual consumers undertaking home renovation projects seek user-friendly, low-VOC adhesives, often water-based, available through retail channels.
- Manufacturers:Flooring manufacturers integrate adhesives into their production processes for pre-finished flooring components, requiring consistent quality and supply.
Contractors remain the primary decision-makers, with distributors facilitating broad market reach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global flooring adhesive market exhibits a complex interplay between domestic consumption and international trade flows, particularly for specialized formulations. Major production hubs in Europe and North America often serve as net exporters of high-performance epoxy and polyurethane systems. Conversely, developing economies in Asia and Latin America represent significant net importers, driving demand through extensive infrastructure development.
United States
Residential and commercial construction drive significant adhesive consumption across the United States. US EPA rules on VOCs mandate the use of low-emission formulations, particularly in public and commercial projects. In urban centers like New York City, renovation projects increasingly specify water-based adhesives for multi-story buildings.
China
Infrastructure expansion and urban development projects fuel demand for high-strength flooring adhesives in China. China's national GB standards dictate performance and safety criteria for construction materials, influencing market access for all suppliers. The Yangtze River Delta region, with its dense manufacturing and construction activity, represents a major consumption area.
Germany
The country's robust commercial and residential sectors maintain a steady demand for durable flooring solutions. The European Union's REACH regulation promotes the adoption of low-VOC and bio-based adhesive alternatives across the construction industry. Munich and Berlin, with their ongoing public-sector renovations, are significant markets for compliant water-based systems.
India
Rapid urbanization and large-scale commercial projects in India stimulate consumption of specialized epoxy and polyurethane systems. The national government's "Housing for All" initiative boosts residential construction, indirectly influencing demand for cost-effective, easy-to-use adhesives. Major metropolitan areas such as Mumbai and Delhi drive demand for both residential and commercial applications.
Brazil
Commercial construction and infrastructure improvements across Brazil create a substantial need for versatile polyurethane formulations. ANVISA, the national health surveillance agency, influences product safety standards for construction materials, including adhesives. The São Paulo metropolitan region leads in commercial project development, requiring high-performance bonding solutions.
Flooring Adhesive Market Key Industry Players
Concentration sits with a few global chemical giants leveraging extensive R&D and manufacturing capabilities. The market structure is characterized by a tiered landscape, where large diversified players coexist with specialized formulators and regional niche providers. Global diversified chemical manufacturers, specialized hot melt adhesive experts, and advanced acrylic polymer specialists represent distinct strategic archetypes. Dominant competitive moves include geographic expansion into developing markets and continuous product portfolio diversification to meet evolving regulatory standards.
Within the global diversified chemical manufacturer archetype, Swiss-based Sika AG exemplifies a strategy of leveraging a broad product range and global manufacturing footprint across various construction segments. H.B. Fuller Company represents a specialized formulation expert, differentiating through niche hot melt adhesive applications for specific flooring types and industrial uses. French-based Arkema, with its focus on advanced acrylic polymer chemistry, occupies a position emphasizing material science innovation for developing sustainable and high-performance solutions for the construction sector.
| Leading Market Players |
|---|
| MAPEI S.p.A. |
| Dow |
| Sika AG |
| Lanxess |
| Arkema |
| Henkel AG & Co. KGaA |
| Bostik |
| Pidilite Industries Ltd. |
| H.B. Fuller Company |
| Others |
Cost & Logistics Intelligence
Project-based supply agreements for commercial and industrial applications lock in both supply access and price visibility for specialized flooring adhesives. This structure helps manage the inherent volatility of chemical feedstocks, providing stability for large-scale construction projects.
Pricing Analysis
Professional contractors anchor tiered pricing structures, reflecting performance capabilities and regulatory compliance. Price differentiation stems from product quality grade, such as shear strength and cure time, and specific certifications like low-VOC content for public-sector projects. Pricing pressure stems from raw material volatility for acrylic monomers and isocyanates, compressing manufacturer margins. DIY enthusiasts represent the most price-sensitive segment, while commercial and industrial buyers prioritize performance over cost.
Supply Chain Analysis
Inventory management for flooring adhesives balances long lead times for specialized raw materials with regional demand fluctuations. Geographic supply concentration for key chemical feedstocks like isocyanates and acrylic monomers centers in Germany and China. The supply chain relies heavily on petroleum-derived inputs, making it vulnerable to commodity price volatility. Distribution runs through a network of specialized building material distributors and direct channels to large commercial contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The flooring adhesive market is experiencing a buyer-power shift as specifiers increasingly demand complete, warranted flooring systems from single sources.
For Market Incumbents: Compound investment in advanced R&D for low-VOC and bio-based formulations to counter regulatory fragmentation and substitution from floating floors. Expand global manufacturing footprints to achieve economies of scale in polyurethane production, mitigating raw material cost pressures. Invest in installer training programs to close the skill gap for advanced reactive adhesive systems, enhancing application reliability and reducing warranty claims.
For New Entrants and Emerging Players: Specialized installer training and technical support represent a service-layer gap where incumbents under-serve the market for advanced reactive adhesive systems. Target niche applications requiring specific performance attributes, such as adhesives for heated flooring systems or specialized formulations for luxury vinyl tile. Focus initial market entry on developing economies in Asia and Latin America where infrastructure expansion drives demand for high-strength epoxy systems.
For Investors and Strategic Acquirers: Capital is best deployed toward specialized formulators with proven intellectual property in bio-based or hybrid polymer chemistries. Long-term viability depends on capabilities to navigate divergent regional standards and produce sustainable, high-performance solutions. Target companies with strong distribution networks in high-growth regions like the Middle East or those with expertise in application-specific product development. The signal to watch is the accelerating adoption rate of green building certifications in commercial construction.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Manufacturing Transition | Ensures compliance with EU REACH and US EPA regulations, supporting market access. |
| Long-term Supply Agreement | Secures feedstock for polyurethane and acrylic formulations, mitigating raw material volatility. |
| Product Launch (Hybrid Adhesives) | Addresses demand for versatile solutions for LVT and engineered wood over challenging subfloors. |
| Geographic Expansion (Middle East) | Captures growth from commercial construction in Saudi Arabia and the UAE, adapting to high heat. |
| Certification Investment (LEED/BREEAM) | Meets specifier requirements for sustainable building projects, enhancing market differentiation. |
Research Approach
Desk research of industry association reports and government construction statistics preceded structured interviews with R&D directors, procurement leads, and regulatory compliance officers. This primary research was triangulated with secondary data from company financial filings and patent databases. The approach combined bottom-up market sizing with top-down validation, ensuring comprehensive data coverage.
Variance decomposition across the projection horizon disaggregated market growth drivers, quantifying their individual contributions to the overall forecast. The analytical framework modeled market segmentation by product type, material, application, end-user, and regional regulatory frameworks. Compound Annual Growth Rates (CAGRs) were derived from historical trends and future demand drivers, including construction spending forecasts and VOC emissions regulations.
Underlying assumptions cover stable geopolitical conditions and consistent regulatory enforcement, with deviation risk concentrated in raw material price volatility and unforeseen technological disruptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
India Adhesives Market
Adhesives & Sealants
North America Laminating Adhesives Market
Adhesives & Sealants
North America Adhesives Market
Adhesives & Sealants
Global Automotive Adhesive Market
Adhesives & Sealants
Global Footwear Adhesives Market
Adhesives & Sealants
North America Electronics Adhesives Market
Adhesives & Sealants
Italy Sealants Market
Adhesives & Sealants
Middle-East and Africa Acrylic Adhesives Market
Adhesives & Sealants
Mexico Adhesives Market
Adhesives & Sealants
Fuel Resistant Sealant Market
Adhesives & Sealants
Asia-Pacific Epoxy Curing Agents Market
Adhesives & Sealants
UV Cured Adhesives Market
Adhesives & Sealants
Adhesive Primer Market
Adhesives & Sealants
Metal Glue Market
Adhesives & Sealants
Global Adhesion Promoter Market
Adhesives & Sealants
Removable Adhesive Market