
 Feed Antioxidants Market | 2026-2036
Feed Antioxidants Market Size, Share, and Industry Trends Forecast 2026-2036
Feed Antioxidants Market Intelligence
Producers of synthetic antioxidants in China and India are expanding their manufacturing capacity for Butylated Hydroxytoluene (BHT) and other core compounds to serve export markets. This supply-side development influences global pricing and availability for livestock operations. In this environment, Kemin Industries, Inc. specializes in both natural and synthetic antioxidant solutions, offering a diversified portfolio. BASF SE leverages its extensive chemical production scale to compete on cost for high-volume synthetic products. Meanwhile, Cargill, Inc. integrates antioxidants into its broader animal nutrition and premix offerings.
Feed antioxidants are chemical compounds added to animal diets to inhibit the oxidative degradation of lipids, vitamins, and pigments. These additives function by neutralizing free radicals, thereby preserving the nutritional value, palatability, and shelf life of formulated feeds. The market's product landscape shows that synthetic types like BHT and Ethoxyquin hold significant volume share due to their cost-effectiveness and proven efficacy. However, natural antioxidants, particularly Mixed Tocopherols, are gaining traction, driven by demand in the premium pet feed and aquaculture animal type segments for clean-label ingredients.
The regulatory environment is a critical factor shaping product formulation and market access. In Europe, the European Food Safety Authority (EFSA) sets stringent approval processes and maximum inclusion levels for all feed additives. Similarly, the U.S. Food and Drug Administration (FDA) regulates antioxidants under its Generally Recognized as Safe (GRAS) framework. These regulations are forcing a re-evaluation of certain synthetic compounds, pushing manufacturers toward developing and validating novel natural alternatives. The key decision for feed producers now revolves around balancing the cost-performance of synthetics with the regulatory and consumer pressures favoring natural sources.
Market Dynamics
The central dynamic in the feed antioxidants market is the structural tension between the cost-efficiency of established synthetic compounds and intensifying regulatory pressure from bodies like EFSA, which is accelerating the validation and adoption of natural alternatives.
Growth Catalysts
- Regulatory Scrutiny:Stricter European Food Safety Authority (EFSA) regulations on synthetic additives are compelling feed producers to seek and validate natural antioxidant alternatives to maintain market access in Europe.
- Aquaculture Expansion:The need to preserve high-fat fishmeal and aquafeed in the expanding global aquaculture industry drives demand for effective antioxidants to extend shelf life and protect nutritional value.
- Industrial Livestock Production:Large-scale poultry and swine operations, particularly in China and Brazil, require antioxidants to maintain feed quality and consistency in intensive farming systems.
Market Restraints
- Input Cost Volatility:The price of synthetic antioxidants like BHT is tied to the fluctuating costs of petrochemical precursors such as toluene, creating margin uncertainty for both producers and end-users.
- Efficacy Gaps:Many natural antioxidants exhibit lower potency or require higher inclusion rates to match the performance of cost-effective synthetics, posing a technical barrier to direct substitution for some applications.
- Regulatory Re-evaluation:Ongoing safety reviews of established synthetics, such as Ethoxyquin by EFSA, create market uncertainty and risk of delisting, disrupting long-standing formulation practices for feed mills.
Strategic Opportunities
- Synergistic Blends:Developing proprietary blends of different natural antioxidants, such as tocopherols with rosemary extracts, creates formulations with enhanced efficacy that can compete with single-ingredient synthetics.
- Premium Pet Food:The demand for "clean-label" and natural ingredients in the premium pet food segment offers a high-margin opportunity for suppliers of tocopherols and other plant-derived antioxidants.
- Aquaculture in Southeast Asia:Expanding into developing aquaculture markets in countries like Vietnam and Indonesia presents an opportunity to introduce antioxidant solutions tailored for tropical fish and shrimp species.
Industry Challenges
- Supply Chain Validation:Shifting from chemically consistent synthetic sources to variable natural ones requires significant investment in qualifying new suppliers and ensuring batch-to-batch consistency and traceability.
- Standardization of Efficacy:A lack of industry-wide, standardized protocols for measuring the in-vivo efficacy of natural antioxidants makes it difficult for feed producers to compare products and justify switching from synthetics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Feed Antioxidants Market |
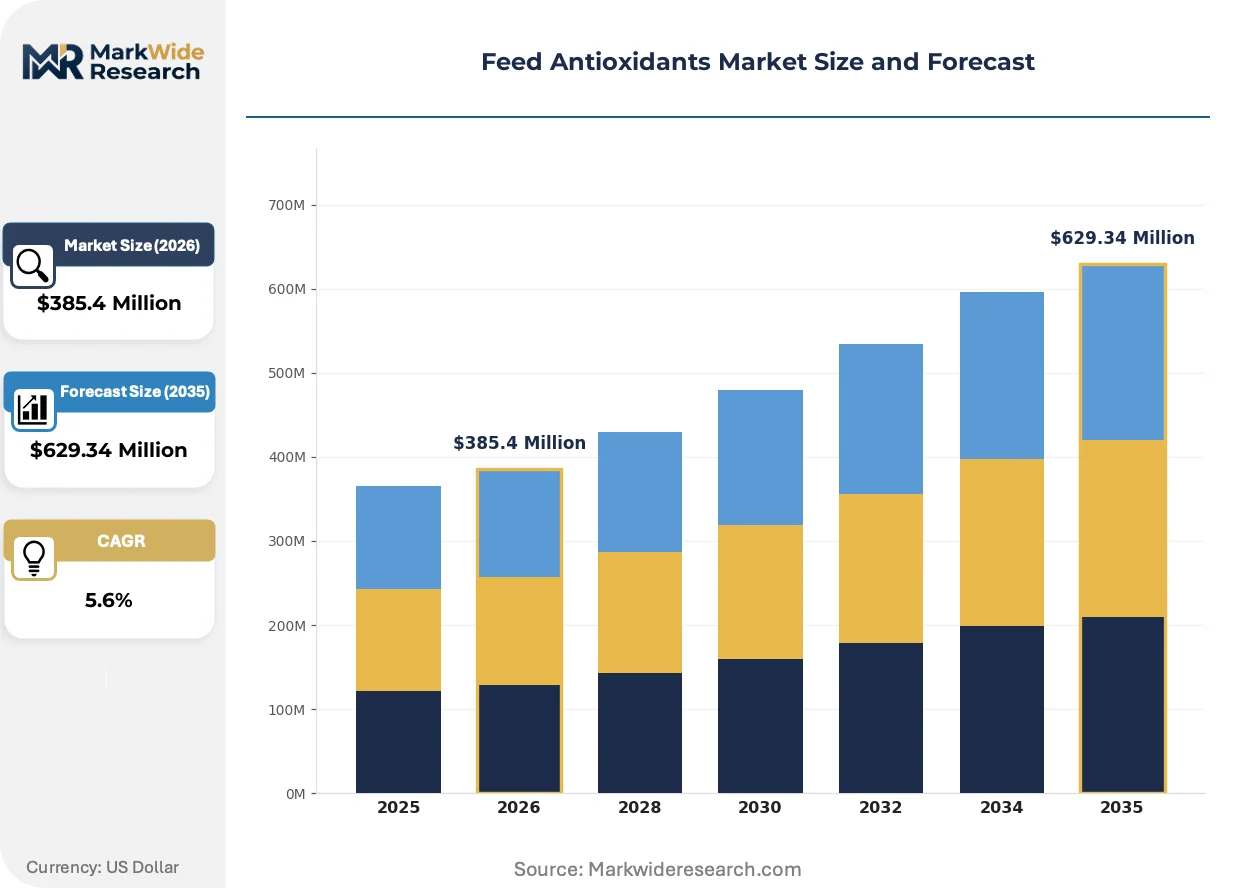
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $629.34 Million |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Ethoxyquin, Butylated Hydroxyanisole, Butylated Hydroxytoluene, Propyl Gallate, Mixed Tocopherols Animal Type: Poultry, Aquaculture, Swine, Ruminants, Pet Feed Form: Liquid, Powder, Granule, Pellets Application: Growth Promotion, Immune Enhancement, Feed Preservation, Meat Quality Improvement |
| Companies Covered | Cargill, Inc., DSM-Firmenich AG, BASF SE, Archer Daniels Midland Company, Kemin Industries, Inc., Bluestar Adisseo Company, Novus International, Alltech, Inc., Nutreco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Feed Antioxidants Market Strategic Shifts & Innovations
A primary shift involves the industrial-scale refinement of natural antioxidant sources to achieve performance and stability metrics previously exclusive to synthetic compounds. This pursuit reshapes supplier capabilities and formulation strategies across the feed industry.
Synergistic antioxidant blends combine natural compounds like tocopherols and polyphenols to deliver broad-spectrum oxidative protection. Premium feed formulators in the aquaculture and specialty pet food sectors are the primary adopters. This development is rewriting the traditional cost-performance calculus, making natural alternatives increasingly viable for mainstream feed applications beyond niche markets.
The European Food Safety Authority's (EFSA) ongoing re-evaluation of synthetic antioxidants is a significant regulatory driver. This process results in stricter maximum inclusion levels and potential phase-outs for compounds like Ethoxyquin. Consequently, European poultry and aquaculture feed producers are most impacted, accelerating their R&D into validated natural substitutes.
A clear behavioral change is the move by large feed manufacturers from purchasing based on pure cost-per-kilogram to a total value calculation. This model disrupts the reliance on single-compound synthetics, favoring suppliers with diverse portfolios and technical support. This shift is most prominent within the North American and European markets for premium livestock and companion animal diets.
Feed Antioxidants Market Segmentation
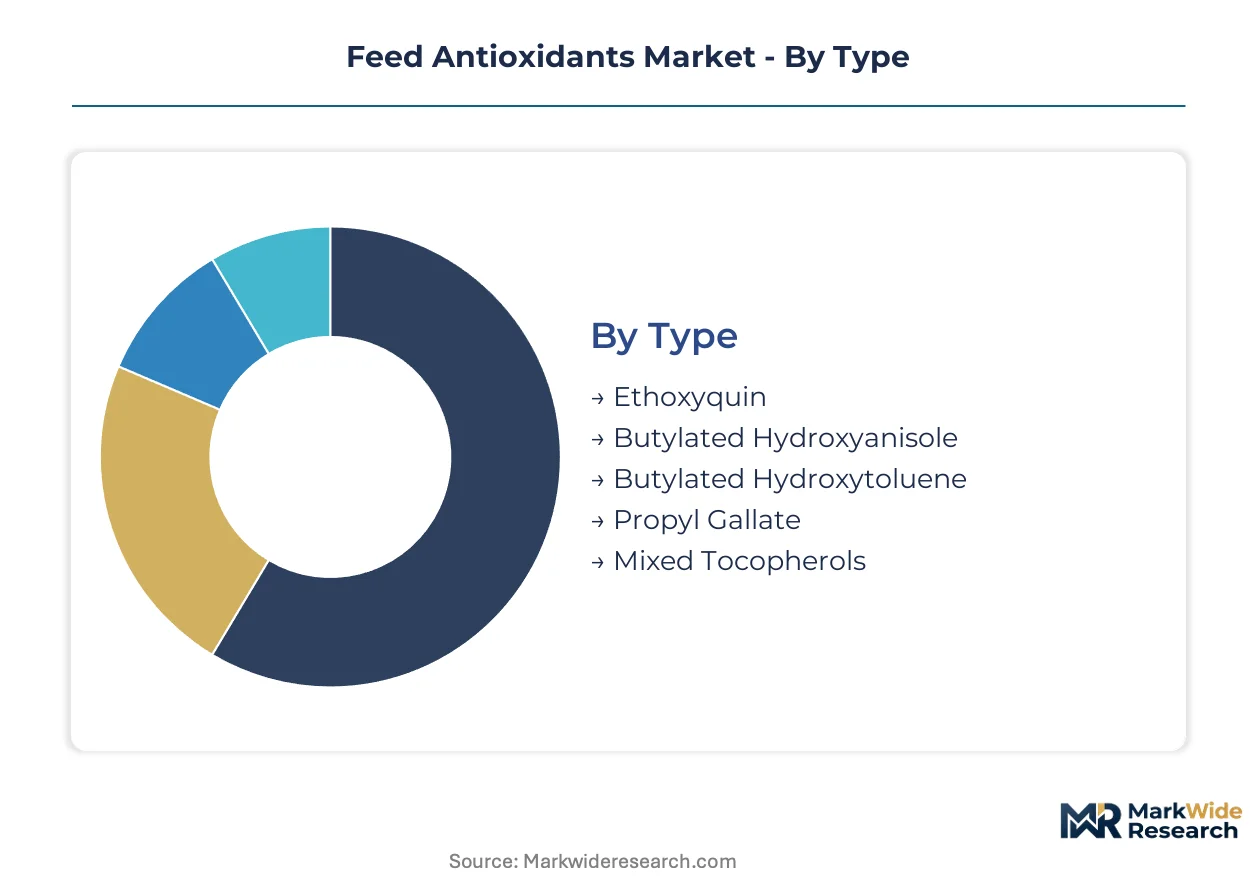
The feed antioxidants market differentiates products to meet diverse animal nutrition needs and regulatory landscapes. Understanding these segments helps producers align their portfolios with specific industry demands, from large-scale livestock operations to niche premium pet food markets.
Type:
The type segmentation highlights the customization-versus-standardization spectrum in feed antioxidant formulations. Producers balance the proven efficacy and cost-effectiveness of synthetic compounds against the clean-label demand for natural alternatives.
- Butylated Hydroxytoluene:This synthetic antioxidant is widely used for its high efficacy in preventing lipid oxidation in animal feeds and raw materials. Demand concentrates in industrial poultry and swine operations, driven by cost-effectiveness and stability in feed processing.
- Mixed Tocopherols:These natural compounds, derived from vegetable oils, provide antioxidant benefits and are gaining traction in premium pet feed and aquaculture. Demand is increasing in European and North American markets due to clean-label ingredient preferences.
- Ethoxyquin:A synthetic antioxidant primarily employed in fishmeal and poultry feed to prevent fat degradation.
- Butylated Hydroxyanisole:This synthetic compound offers antioxidant properties and is commonly used in animal fats and oils.
- Propyl Gallate:A synthetic antioxidant that inhibits rancidity in fats and oils, often used in combination with other antioxidants.
Most installed capacity flows through Butylated Hydroxytoluene. Expansion is steepest in Mixed Tocopherols.
Animal Type:
This category reflects the cost-tier and nutritional requirements across different animal diets, influencing antioxidant selection and inclusion rates.
- Aquaculture:This segment requires specialized antioxidants to preserve high-fat fishmeal and aquafeed, critical for maintaining nutritional value and extending shelf life. Demand is particularly strong in Southeast Asia and South America, supporting rapid growth in fish and shrimp farming.
- Pet Feed:The pet feed sector demands high-quality, often natural, antioxidants to ensure product freshness and meet consumer preferences for clean-label ingredients. This segment sees significant adoption in North America and Europe for premium and specialty pet diets.
- Poultry:Large-scale poultry operations utilize antioxidants to maintain feed quality and prevent oxidative damage in high-fat diets.
- Swine:Swine diets incorporate antioxidants for feed preservation, supporting growth and health in intensive farming systems.
- Ruminants:Antioxidants are used in ruminant feeds to protect nutrients and support animal health, particularly in dairy and beef production.
The largest share of demand comes from Poultry, while Aquaculture is experiencing the most dynamic growth.
Form:
The form category addresses the volume and handling efficiency required for integration into diverse feed manufacturing processes.
- Powder:Powdered antioxidants offer ease of blending and uniform distribution within dry feed mixes, making them suitable for large-scale feed mill operations. This form is widely adopted across industrial livestock production in China and Brazil.
- Liquid:Liquid formulations provide flexibility for precise dosing and application, especially in spray-on coatings or specific feed processing stages. This form is increasingly preferred for specialized applications in aquaculture and pet food manufacturing.
- Granule:Granular forms offer reduced dust and improved flowability compared to powders, aiding in handling and minimizing loss.
- Pellets:Antioxidants in pellet form are typically incorporated into complete pelleted feeds, ensuring consistent intake by animals.
Powder dominates for ease of handling, with Liquid gaining traction for specialized applications.
Application:
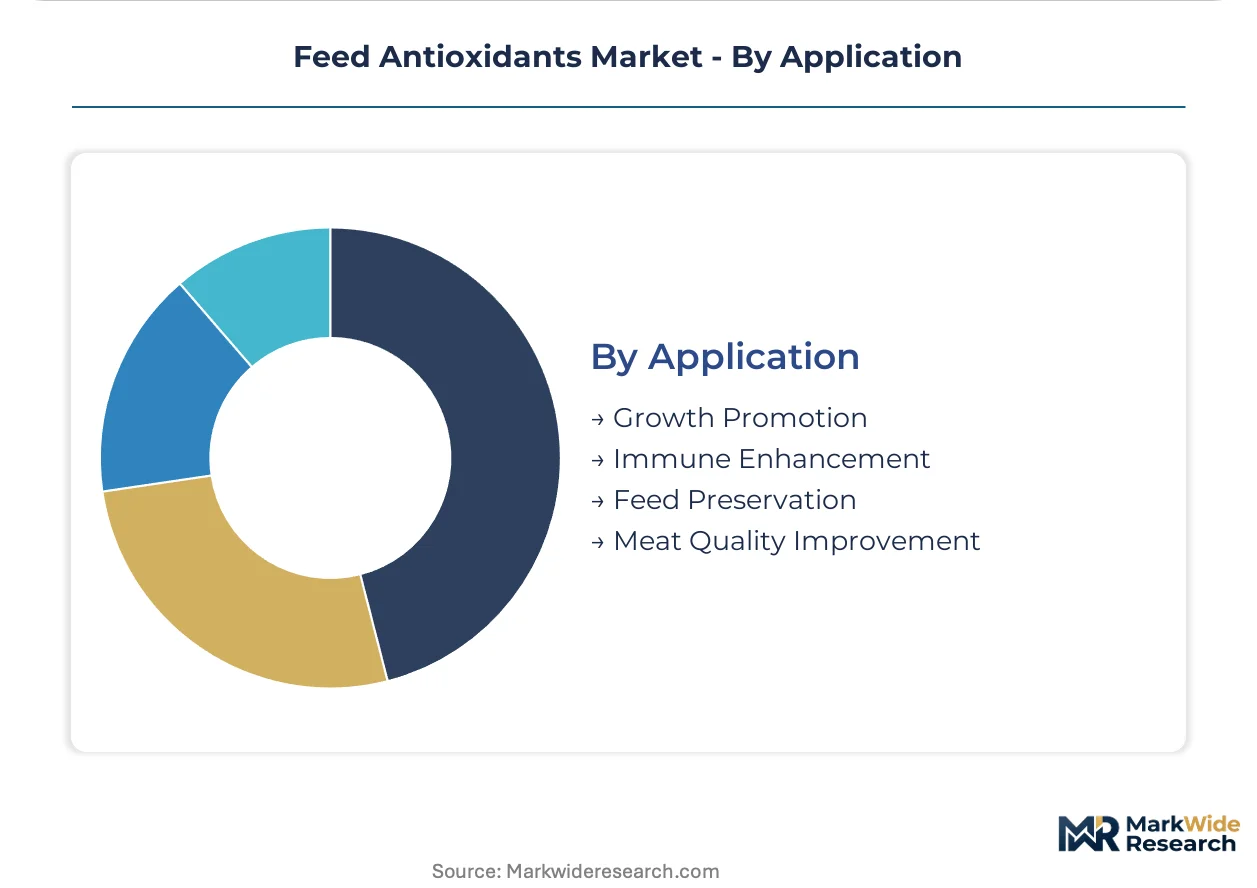
This segmentation highlights the customer type and specific performance benefits sought by feed producers, from basic preservation to advanced animal health outcomes.
- Feed Preservation:This application focuses on inhibiting the oxidative degradation of lipids, vitamins, and pigments within animal feeds, thereby preserving nutritional value and shelf life. This is a fundamental requirement across all animal feed sectors, especially for high-fat formulations.
- Growth Promotion:Antioxidants contribute to growth promotion by reducing oxidative stress in animals, allowing for more efficient nutrient utilization and improved overall health. This application is crucial for poultry and swine operations aiming for optimal production yields.
- Immune Enhancement:Antioxidants support the immune system by neutralizing free radicals, reducing cellular damage and improving an animal's resilience to disease.
- Meat Quality Improvement:Certain antioxidants can enhance the quality of meat by reducing lipid oxidation in animal tissues, leading to better color stability and extended freshness.
Core demand centers on Feed Preservation, but investment is increasing in Immune Enhancement capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The regulatory landscape significantly influences feed antioxidant production and consumption patterns, creating distinct regional dynamics. Stricter environmental and food safety regulations in some regions encourage production shifts to areas with more lenient or developing frameworks. This regulatory arbitrage impacts global supply chains and product availability for livestock operations.
China
Large-scale poultry and swine production drives significant demand for feed antioxidants to maintain feed quality. China's GB standards for feed additives influence product formulation and market entry. Industrial livestock hubs in provinces like Shandong and Henan concentrate antioxidant consumption for intensive farming.
Brazil
Industrial livestock production, particularly for poultry and swine, creates substantial demand for feed preservation solutions. ANVISA regulates feed additives, ensuring safety and efficacy for domestic animal diets. The agricultural heartland in states like Mato Grosso and Goiás sees high antioxidant usage in feed mills.
United States
The premium pet feed segment and large-scale aquaculture operations drive demand for both natural and synthetic antioxidants. The U.S. Food and Drug Administration (FDA) regulates antioxidants under its GRAS framework, impacting product approvals. Major feed manufacturing centers in the Midwest, such as Iowa, integrate antioxidants into diverse animal nutrition products.
Germany
European Food Safety Authority (EFSA) regulations on synthetic additives accelerate the shift towards natural antioxidant sources in animal diets. EFSA's stringent approval processes influence product availability across the European Union. Animal nutrition companies in regions like Lower Saxony and Bavaria focus on developing and validating novel natural alternatives.
India
Expanding industrial livestock and aquaculture sectors require feed antioxidants to support growth and feed stability. FSSAI guidelines for feed ingredients influence the formulation and marketing of antioxidant products. Major poultry and aquafeed producers in states like Andhra Pradesh and Tamil Nadu are increasing antioxidant incorporation.
Feed Antioxidants Market Key Industry Players
Established producers occupy the standard tier, focusing on cost-effective synthetic compounds; emerging entrants pursue natural ingredient solutions and specialized blends. The market exhibits a tiered structure, with large chemical companies competing on scale and specialized nutrition firms innovating in natural alternatives. Key strategic archetypes include global chemical giants, animal nutrition specialists, and ingredient suppliers. Capacity expansion in synthetic production and portfolio diversification into natural sources are dominant competitive moves.
Global chemical producers like BASF SE leverage extensive production capabilities, anchoring the supply of high-volume synthetic products. Animal nutrition specialists such as Kemin Industries, Inc. exemplify diversified portfolios, offering both natural and synthetic antioxidant solutions to meet varied industry demands. Cargill, Inc. further integrates antioxidants into its broader animal nutrition and premix offerings, reflecting a comprehensive approach to feed formulation and market penetration. These prominent entities collectively shape the supply dynamics and innovation trajectory within the feed antioxidants market, influencing pricing and availability for livestock operations worldwide.
| Leading Market Players |
|---|
| Cargill, Inc. |
| DSM-Firmenich AG |
| BASF SE |
| Archer Daniels Midland Company |
| Kemin Industries, Inc. |
| Bluestar Adisseo Company |
| Novus International |
| Alltech, Inc. |
| Nutreco |
| Others |
Cost & Logistics Intelligence
Stricter European Food Safety Authority regulations on synthetic feed additives are compelling feed producers to validate natural alternatives, fundamentally altering supply dynamics and pricing structures for antioxidant solutions.
Pricing Analysis
Distributor margins for synthetic feed antioxidants remain compressed due to high-volume, contract-based long-term offtake agreements. Pricing stratifies across premium, standard, and economy tiers, driven by volume scale for synthetics like BHT and certification levels for natural mixed tocopherols. Regulatory re-evaluation of established synthetics creates pricing softness in that segment. Industrial poultry and swine operations exhibit high price sensitivity, while premium pet food and aquaculture segments prioritize efficacy and clean-label attributes.
Supply Chain Analysis
Regional distribution centers facilitate the movement of high-volume synthetic antioxidants to industrial livestock operations. Supply concentration for synthetic compounds like BHT centers in China and India, while natural tocopherols are sourced globally from vegetable oil processors. Raw material dependencies include petrochemical precursors for synthetics and agricultural outputs for natural alternatives. Commodity price volatility for petrochemicals poses a structural risk. Downstream distribution runs through direct sales channels to large feed manufacturers, with specialized ingredient distributors serving premium segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The feed antioxidants market is evolving into a late-cycle quality story, driven by consumer and regulatory demand for premium, clean-label ingredients in animal nutrition.
For Market Incumbents: Anticipate continued regulatory pressure on synthetic compounds by accelerating portfolio diversification into validated natural antioxidant solutions. Invest in R&D for synergistic natural blends to match synthetic efficacy, mitigating the threat of regulatory phase-outs for compounds like Ethoxyquin. Secure certification investments for clean-label ingredients, appealing to premium pet food and aquaculture segments. Enhance technical support for feed formulators transitioning from traditional synthetics.
For New Entrants and Emerging Players: European Food Safety Authority regulations in Europe open a window for novel natural antioxidant suppliers to gain market share. Target white-space opportunities in premium pet food and specialized aquaculture, particularly within European markets for clean-label ingredients. The most penetrable segment remains European premium pet food, driven by consumer preferences. Focus go-to-market strategies on robust efficacy validation and clear traceability for plant-derived compounds.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized ingredient suppliers possessing proprietary natural antioxidant blends and validated performance data. The market demonstrates long-term viability given the essential role of feed preservation in animal nutrition. Target acquisition profiles include mid-cap specialists with strong R&D pipelines for natural compounds and established supply chain validation. The signal to watch is the adoption of industry-wide efficacy standardization protocols for natural antioxidants.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for BHT | Global chemical producers reinforce supply of cost-effective synthetic compounds for industrial livestock. |
| Portfolio Diversification into Mixed Tocopherols | Animal nutrition specialists meet rising demand for natural, clean-label solutions in premium feed segments. |
| R&D into Synergistic Natural Blends | Manufacturers develop enhanced formulations to compete with synthetic performance and address regulatory shifts. |
| Investment in Clean-Label Certifications | Suppliers capture high-margin opportunities in European and North American premium pet food markets. |
| Market Entry in Southeast Asian Aquaculture | Companies introduce tailored antioxidant solutions for rapidly expanding fish and shrimp farming operations. |
Research Approach
Direct dialogue with feed mill managers, animal nutritionists, regulatory affairs specialists, and ingredient procurement leads formed the primary research foundation. This qualitative grounding was validated against secondary sources including EFSA reports, FDA GRAS notifications, industry association publications, and global trade statistics. A robust bottom-up and top-down triangulation approach ensured data consistency and market sizing accuracy.
A bottom-up approach for volume estimation, combined with a top-down validation for market value, structured the forecast framework. Segmentation across type, animal type, form, application, and regional regulatory frameworks informed the model. Compound Annual Growth Rates were derived from historical trend analysis and future projections of livestock production growth rates. Regulatory approval timelines for novel natural additives served as a critical forecast input across the analysis window.
Revisions become necessary when unforeseen regulatory shifts, particularly from bodies like EFSA, or significant raw material supply disruptions materialize. Forecasts reflect assumptions regarding technological advancements and market adoption rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Asia-Pacific Feed Minerals Market
Agricultural Chemicals
Global Cattle Feed and Feed Additives Market
Agricultural Chemicals
Asia-Pacific Feed Antioxidants Market
Agricultural Chemicals
Mexico Feed Additives Market
Agricultural Chemicals
North America Feed Pigments Market
Agricultural Chemicals
North America Fungicide Market
Agricultural Chemicals
US Home and Garden Fungicides Market
Agricultural Chemicals
Agricultural Grade Zinc Chemicals Market
Agricultural Chemicals
Soil Treatment Market
Agricultural Chemicals
US Fungicide Market
Agricultural Chemicals
Foliar Spray Market
Agricultural Chemicals
Global Feed Palatability Enhancers Market
Agricultural Chemicals
Europe Feed Enzymes Market
Agricultural Chemicals
Feed Mycotoxin Detoxifiers Market
Agricultural Chemicals
GCC Feed Premix Market
Agricultural Chemicals
Feed Preservatives Market