
 Europe Feed Acidifiers Market | 2026-2036
Europe Feed Acidifiers Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Feed Acidifiers Market Foresight
Specialty compound feed manufacturers is bifurcating from commodity premix buyers as gut-health premiums widen across European livestock operations. BASF SE leverages its propionic acid fermentation capacity to anchor supply contracts with Nordic salmon feed producers. Kemin Industries differentiates through buffered acid blends that sustain activity across pelleting temperatures above 80°C.
Feed acidifiers are organic and inorganic acids added to animal feed typically at inclusion rates of 0.5% to 3.0% by weight to suppress pathogenic bacterial growth and improve nutrient digestibility in monogastric and ruminant systems. The organic acids segment dominates value generation due to higher unit economics and established efficacy data in poultry and swine diets. Powder formulations lead volume throughput across European toll milling networks, while liquid acidifier blends represent the fastest-growing form category as automated dosing systems penetrate larger dairy and piglet operations.
EFSA evaluates acidifier safety and efficacy claims under feed additive authorization procedures, while REACH governs chemical substance registration and hazard communication for imported acidifier precursors. The EU Green Deal's Farm to Fork strategy tightens antimicrobial reduction targets, directly expanding the addressable market for acidifiers as zootechnical alternatives. Stakeholders must monitor ECHA's ongoing substance evaluations for formic and lactic acid reclassifications that could reshape formulation costs and import sourcing patterns.
Market Dynamics
EU veterinary medicinal product regulations phasing out zinc oxide across piglet weaning operations force immediate reformulation toward organic acid alternatives, restructuring procurement relationships between compound feed mills and acidifier suppliers.
Growth Catalysts
- EU Green Deal Farm to Fork targets:Mandatory antimicrobial reduction timelines accelerate acidifier adoption as zootechnical alternatives across Spanish and Dutch pork operations.
- Automated liquid dosing systems:Precision delivery infrastructure in Danish and German dairy barns enables higher inclusion rates with labor efficiency gains.
- Formic acid fermentation capacity:Nordic salmon feed producers secure long-term supply contracts as aquaculture gut-health protocols tighten.
Market Restraints
- Propionic acid feedstock volatility:Crude oil derivative pricing swings compress blender margins during energy market dislocations.
- REACH substance evaluation timelines:ECHA's ongoing formic and lactic acid reclassification reviews create formulation uncertainty and import sourcing disruption.
- Copper sulfate substitution:High-dose mineral alternatives retain cost advantage in price-sensitive Southern European premix channels.
Strategic Opportunities
- Poland and Romania expansion:Underpenetrated piglet operations in Eastern Europe offer first-mover positioning as EU regulations harmonize.
- Buffered acid thermal stability:Pelleting temperature tolerance above 80°C opens compound feed manufacturing partnerships previously blocked by activity loss.
- EFSA feed additive authorization pathways:Streamlined efficacy claim approvals reduce time-to-market for novel acidifier blends targeting ruminant applications.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in acid-pH buffering interactions limits R&D throughput for mid-tier manufacturers.
- Multi-jurisdiction compliance synchronization:Divergent national implementation of EU feed additive rules across member states fragments product registration investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Feed Acidifiers Market |
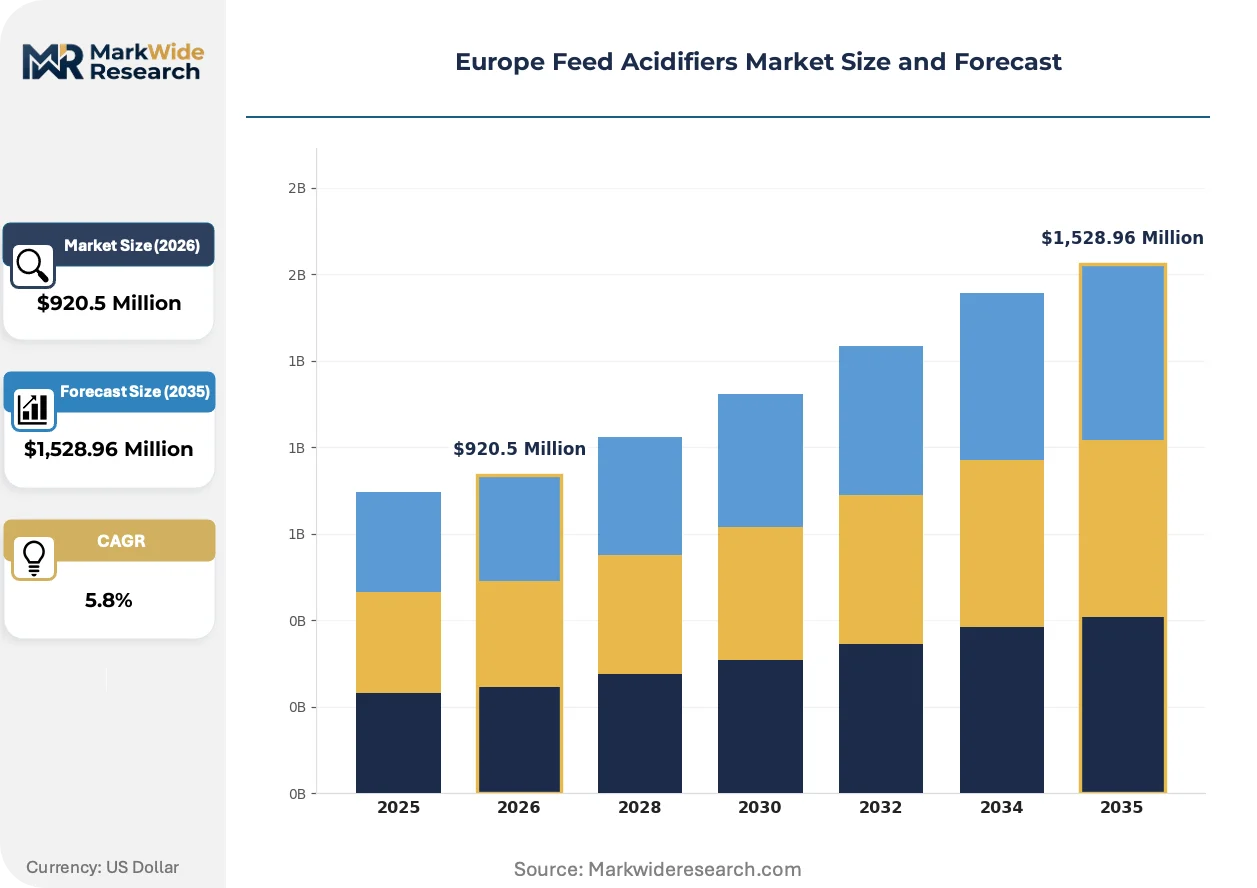
| Market Size in 2026 | $920.5 Million |
| Market Size in 2035 | $1,528.96 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Acids, Inorganic Acids, Propionic Acid, Lactic Acid End User: Poultry, Swine, Ruminants, Aquaculture Application: Feed Preservation, Gut Health Improvement, Nutritional Enhancement, Performance Optimization Form: Liquid, Powder, Granular, Blends |
| Companies Covered | BASF SE, Cargill, Incorporated, Nutreco N.V., Adisseo, Kemin Industries, Evonik Industries AG, Perstorp Holding AB, Biomin Holding GmbH, Novus International, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Feed Acidifiers Market Shifts & Advancements
Feed acidifier technology is pivoting from commodity organic acid sales toward precision delivery systems and thermal-stable formulations that survive industrial pelleting processes.
Encapsulated acidifier technology is decomposing traditional powder formulation dominance. German and Dutch toll millers adopt lipid-coated citric and fumaric acid variants to protect acid activity through extrusion temperatures exceeding 85°C. This thermal protection is decomposing the historical trade-off between pelleting convenience and gut-health efficacy, enabling premium pricing for compound feed manufacturers serving integrator contracts.
EFSA's 2023 updated guidance on feed additive environmental risk assessments tightens residue monitoring obligations. Aquaculture and ruminant acidifier authorizations now require expanded ecotoxicology dossiers, extending registration timelines by 12-18 months. Salmon feed producers in Norway and Scotland accelerate pre-submission toxicology investments to secure market access before competitor products face renewal cliffs.
Integrated pork processors in the Netherlands and Denmark consolidate acidifier procurement through single-source technical service agreements. These contracts bundle formulation support, on-farm dosing equipment, and performance benchmarking, displacing traditional distributor relationships. Spanish cooperatives pilot similar consolidated purchasing models, compressing supplier margins while locking in volume commitments.
Europe Feed Acidifiers Market Segmentation
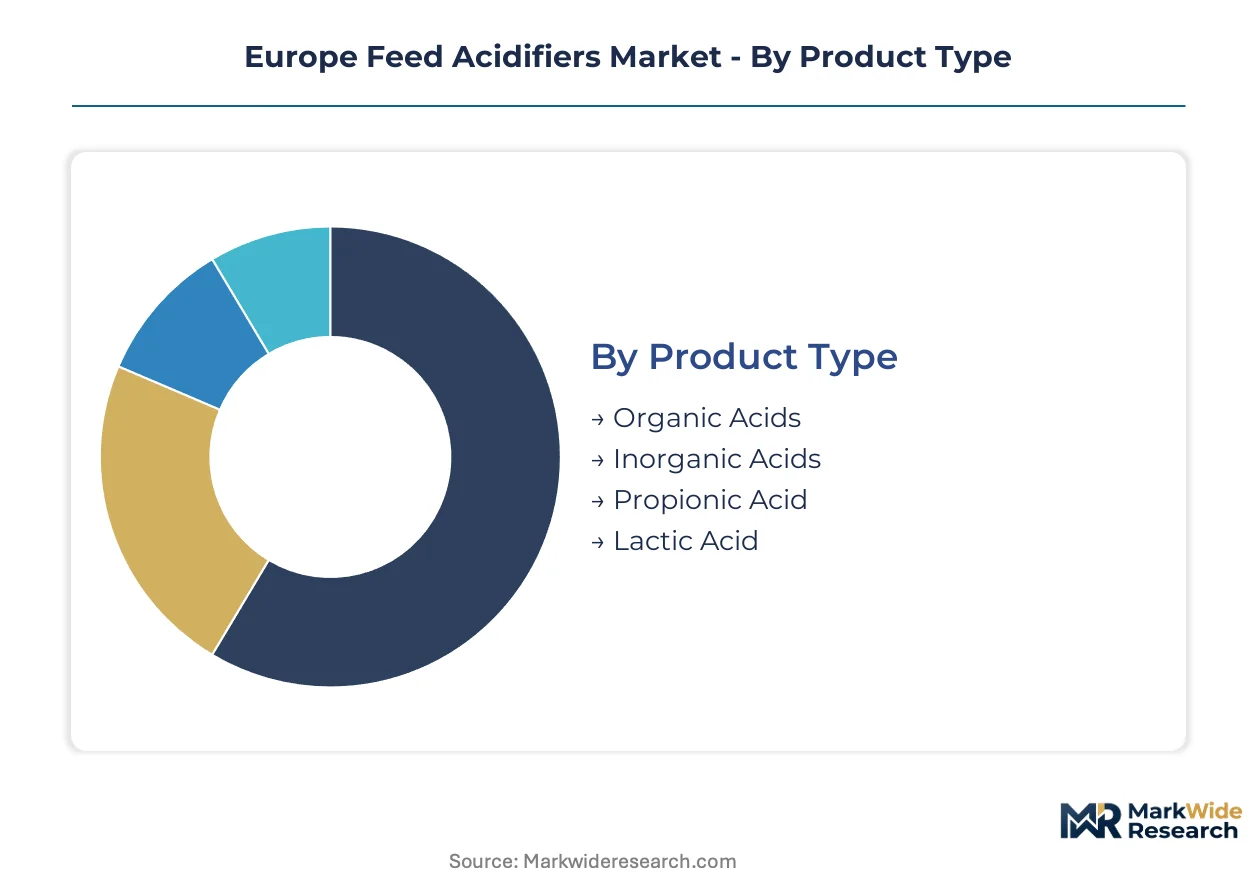
Feed acidifier purchasing patterns diverge sharply across European livestock sectors. Dutch integrators demand precision-dosed liquid systems while Spanish cooperatives favor powder formulations for toll milling flexibility.
Product Type:
Channel flow splits between commodity organic acids moving through distributor networks and specialty acids locked in direct mill contracts.
- Organic Acids:Formic, citric, and fumaric acid blends dominate compound feed manufacturing due to established efficacy data in poultry and swine diets. Spanish piglet weaning operations are expanding inclusion rates as zinc oxide phases out under EU veterinary medicinal product regulations.
- Propionic Acid:Fermentation-derived grades anchor supply contracts with Nordic salmon feed producers requiring consistent mycotoxin inhibition. BASF SE leverages captive fermentation capacity to secure long-term agreements bypassing spot market volatility.
- Inorganic Acids:Phosphoric and hydrochloric acid variants serve mineral premix channels where cost sensitivity overrides organic acid premiums.
- Lactic Acid:Buffered derivatives from corn fermentation penetrate dairy calf starter feeds across German and Danish operations.
By volume, Organic Acids leads. By growth pace, Propionic Acid is ahead.
End User:
Margin structures vary: aquaculture commands formulation premiums while ruminant applications fight mineral substitute competition.
- Swine:Post-weaning diarrhea prevention drives acidifier adoption across Netherlands and Spain as zinc oxide withdrawal deadlines approach. Integrated pork processors enforce stricter enteric health protocols than independent finishers.
- Poultry:Broiler integrators in Poland and Romania adopt acidifiers for clostridium control and nutrient digestibility gains. Automated drinking water systems enable precise organic acid dosing in grow-out houses.
- Aquaculture:Norwegian and Scottish salmon feed producers secure propionic acid supply contracts as gut-health protocols tighten. EFSA environmental risk assessments now require expanded ecotoxicology dossiers extending registration timelines.
- Ruminants:Dairy calf starter applications in Germany and Denmark show growth while adult cattle supplementation faces copper sulfate cost competition.
Swine generates the highest revenue per ton formulated. Aquaculture is expanding most quickly.
Application:
Customer maturity separates preservation buyers seeking commodity pricing from performance optimizers paying technical service premiums.
- Gut Health Improvement:Pathogen suppression in piglet weaning and poultry brooding commands premium pricing due to measurable mortality reduction. Dutch toll millers specify buffered acid blends sustaining activity above 80°C pelleting temperatures.
- Feed Preservation:Mycotoxin inhibition and mold control in stored grain represents volume base but faces price pressure from propionic acid feedstock volatility linked to crude oil derivative swings.
- Nutritional Enhancement:Acidifiers improve phosphorus and protein digestibility in monogastric diets, particularly relevant for Polish and Romanian operations optimizing feed conversion ratios.
- Performance Optimization:Growth promotion claims require EFSA feed additive authorization, favoring established suppliers with regulatory dossier capabilities over new entrants.
Gut Health Improvement captures margin premiums. Feed Preservation moves the most volume.
Form:
Supply concentration differs: powder flows through fragmented toll milling networks while liquid requires integrated dosing equipment partnerships.
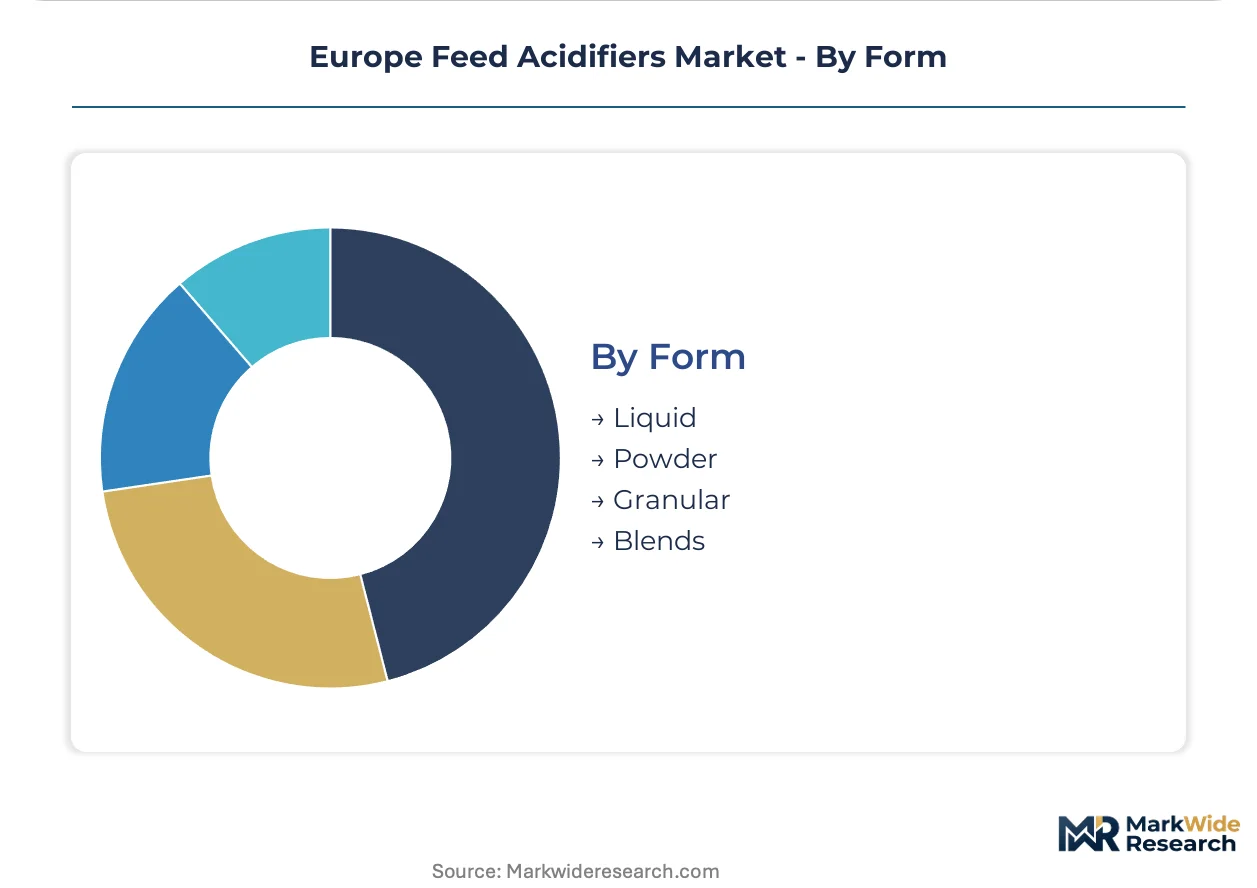
- Liquid:Automated dosing systems in Danish and German dairy barns enable precise inclusion rate control and labor efficiency. Blended organic acid solutions represent the steepest expansion trajectory as integrators consolidate procurement through technical service agreements.
- Powder:Citric and fumaric acid variants dominate European toll milling networks due to handling convenience and pelleting compatibility. German and Dutch millers adopt lipid-coated versions protecting acid activity through extrusion above 85°C.
- Granular:Slow-release formulations target ruminant applications requiring sustained acidification in the rumen environment.
- Blends:Multi-acid combinations with pH buffering optimize cost-performance ratios for mid-tier compound feed manufacturers.
Powder leads volume throughput. Liquid is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's chemical handling infrastructure underwrites the Netherlands' central role in European acidifier distribution, connecting BASF SE's Ludwigshafen production complex to Nordic aquaculture and continental livestock operations.
Netherlands
Integrated pork processors in North Brabant enforce stricter enteric health protocols than independent finishers, driving formic acid blend procurement. REACH substance evaluations through ECHA create formulation uncertainty for imported precursors. The Eindhoven-Rotterdam corridor hosts automated liquid dosing system manufacturers serving Danish and German dairy barns.
Spain
Piglet weaning operations in Catalonia and Aragon are expanding acidifier inclusion rates as producers phase out zinc oxide under EU veterinary medicinal product regulations. EFSA feed additive authorization procedures govern safety and efficacy claims for new formulations. Spanish cooperatives in the Ebro Valley pilot consolidated purchasing models similar to Dutch integrators.
Germany
Dairy calf starter applications across Lower Saxony and Bavaria show sustained demand for buffered lactic acid derivatives. The EU Green Deal's Farm to Fork strategy tightens antimicrobial reduction targets, expanding acidifier adoption as zootechnical alternatives. Toll millers in the Rhine-Ruhr region adopt lipid-coated citric and fumaric acid variants protecting activity through extrusion above 85°C.
Denmark
Automated liquid dosing systems in Jutland dairy barns enable precise organic acid inclusion with labor efficiency gains. National implementation of EU feed additive rules proceeds ahead of member state averages, streamlining product registration. Copenhagen-based technical service providers bundle formulation support with on-farm equipment for integrated pork processors.
Poland
Broiler integrators in Greater Poland and Lower Silesia adopt acidifiers for clostridium control and nutrient digestibility gains. Underpenetrated piglet operations offer first-mover positioning as EU regulations harmonize across Eastern Europe. Poznań and Wrocław host emerging compound feed manufacturing clusters previously served by mineral premix channels.
Europe Feed Acidifiers Market Competitive Landscape
Concentration sits with diversified chemical conglomerates possessing captive fermentation capacity and regulatory dossier capabilities. The vendor base stratifies across three tiers: integrated multinationals with REACH-registered substance portfolios, regional blenders serving toll milling networks, and specialist innovators targeting thermal-stable formulations. Strategic moves center on securing long-term supply contracts with Nordic salmon feed producers and consolidating procurement relationships through bundled technical service agreements.
Among Germany-based chemical conglomerates, BASF SE and Evonik Industries AG exemplify the integrated multinational archetype, leveraging propionic acid fermentation capacity to anchor supply agreements bypassing spot market volatility. Kemin Industries represents the specialist innovator tier, occupying a position defined by buffered acid blends that sustain activity across pelleting temperatures above 80°C. Perstorp Holding AB anchors the Nordic regional vector, sitting within the aquaculture-focused supply chain serving Norwegian and Scottish salmon feed producers.
| Leading Market Players |
|---|
| BASF SE |
| Cargill, Incorporated |
| Nutreco N.V. |
| Adisseo |
| Kemin Industries |
| Evonik Industries AG |
| Perstorp Holding AB |
| Biomin Holding GmbH |
| Novus International |
| Others |
Supply & Pricing Matrix
Zinc oxide withdrawal from piglet weaning formulations is simultaneously redrawing raw material sourcing maps and compressing margin structures across European compound feed channels. This substitution dynamic concentrates pricing power with fermentation-derived organic acid producers while fragmenting bargaining leverage among toll millers locked into mineral premix legacy contracts.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates EFSA-authorized performance claims from commodity preservation grades and unregistered mineral substitutes. Price differentiation hinges on thermal stability certification and bundled technical service depth. Pricing pressure stems from propionic acid feedstock volatility linked to crude oil derivative swings. Spanish cooperatives exhibit highest price sensitivity; Nordic salmon feed producers show lowest, accepting long-term offtake premiums for supply security.
Supply Chain Analysis
The Port of Rotterdam's chemical handling infrastructure underwrites European acidifier distribution, connecting BASF SE's Ludwigshafen fermentation complex to Nordic aquaculture and continental livestock operations. Manufacturing concentrates in Germany, the Netherlands, and Belgium. Raw material flows draw from crude oil derivatives for synthetic acids and corn fermentation streams for lactic acid grades. Single-source vulnerability sits with REACH-registered propionic acid precursors. Distribution runs through integrated processor technical service agreements displacing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized formulation chemistry expertise in acid-pH buffering interactions has become the binding constraint on R&D throughput, privileging incumbents with captive technical talent and excluding mid-tier manufacturers from premium contract tiers.
For Market Incumbents: Secure long-term supply contracts with Nordic salmon feed producers before EFSA environmental risk assessment timelines extend registration cliffs for competitor products. Deepen backward integration into fermentation capacity to bypass propionic acid spot market volatility. Lock in exclusive technical service agreements with Dutch and Danish integrators to forestall distributor margin compression. For New Entrants and Emerging Players: Differentiate on thermal-stable buffered formulations sustaining activity above 80°C pelleting temperatures, opening partnerships with German and Dutch toll millers previously blocked by activity loss. Target underpenetrated piglet operations in Poland and Romania as EU regulations harmonize across Eastern Europe. Lead with automated liquid dosing system bundling to bypass established powder formulation channels. For Investors and Strategic Acquirers: EFSA's 2023 updated environmental risk assessment guidance reshapes the acquisition landscape by extending registration timelines and elevating toxicology dossier capabilities to primary valuation factors. Viable targets combine REACH-registered substance portfolios with aquaculture or ruminant authorization pathways. Monitor ECHA's ongoing formic and lactic acid reclassification reviews as signal for formulation cost inflection and import sourcing disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | BASF SE's captive propionic acid production anchors supply security bypassing crude oil derivative volatility. |
| Thermal-Stable Formulation Development | Kemin Industries' buffered acid blends above 80°C tolerance unlock compound feed manufacturing partnerships. |
| Long-term Supply Agreement with Aquaculture | Nordic salmon feed producers secure propionic acid contracts as EFSA gut-health protocols tighten. |
| Automated Dosing System Bundling | Danish and German dairy barns consolidate procurement through technical service agreements displacing distributors. |
| EFSA Feed Additive Authorization Investment | Streamlined efficacy claim pathways reduce time-to-market for novel ruminant-targeted acidifier blends. |
Research Methodology
A spread of perspectives from compound feed mill procurement directors, formulation chemists at acidifier manufacturers, EFSA regulatory affairs specialists, and Nordic aquaculture nutritionists converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through EFSA feed additive authorization databases, REACH substance registration records, EU customs trade data, and Cefic chemical industry reports. Bottom-up volume estimates from toll milling networks triangulated against top-down market sizing from fermentation capacity disclosures.
Segmentation dimensions modeled span organic versus inorganic acid chemistry, powder versus liquid versus encapsulated form factors, swine versus poultry versus aquaculture versus ruminant end-use sectors, and gut health improvement versus feed preservation versus nutritional enhancement application claims. CAGRs derived from regression analysis of historical inclusion rate trajectories against regulatory phase-out timelines and automated dosing system penetration curves. Forecast inputs incorporated EU Green Deal Farm to Fork antimicrobial reduction targets and ECHA substance evaluation pipeline status.
Material uncertainties — ECHA reclassification outcomes for formic and lactic acid, propionic acid feedstock price dislocations, and divergent national implementation of EU feed additive rules — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory timeline adherence and technology adoption rates. Practitioners should keep alternative scenarios live as REACH substance evaluation conclusions and zinc oxide withdrawal compliance deadlines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Europe Silage Additives Market
Agricultural Chemicals
Pesticide Adjuvant Market
Agricultural Chemicals
Asia-Pacific Feed Minerals Market
Agricultural Chemicals
Middle East and Africa Agricultural Pheromones Market
Agricultural Chemicals
Global Cattle Feed and Feed Additives Market
Agricultural Chemicals
Agricultural Miticides Market
Agricultural Chemicals
Asia-Pacific Feed Additives Market
Agricultural Chemicals
South America Feed Antioxidants Market
Agricultural Chemicals
US Fungicide Market
Agricultural Chemicals
Agricultural Surfactants Market
Agricultural Chemicals
South America Plant Growth Regulators Market
Agricultural Chemicals
North America Feed Phytogenics Market
Agricultural Chemicals
Africa Feed Antioxidants Market
Agricultural Chemicals
Lawn Care Chemicals Market
Agricultural Chemicals
South America Feed Acidifiers Market
Agricultural Chemicals
US Home and Garden Fungicides Market