
 Global Agricultural Micronutrients Market | 2026-2036
Global Agricultural Micronutrients Market Size, Share, and Industry Trends Forecast 2026-2036
Global Agricultural Micronutrients Market Analysis
Consolidation among large-scale commercial farming operations in North America and Brazil is realigning procurement patterns toward bulk micronutrient contracts with technical support bundled in. The Mosaic Company leverages its integrated phosphate and micronutrient portfolio to anchor supply relationships with these consolidated buyers. Yara International competes through controlled-release technology and digital farming platforms that extend its advisory reach beyond product sales. Nutrien Ltd. dominates North American distribution through its retail network while sustaining agronomic service intensity at the farm gate.
Agricultural micronutrients are essential mineral elements—primarily zinc, iron, boron, and manganese—required by plants in trace quantities, typically applied at rates below one kilogram per hectare for optimal enzymatic function and metabolic regulation. These elements correct soil deficiencies that macronutrient fertilizers cannot address, directly influencing crop yield stability and nutritional quality in food systems. Zinc applications lead product type demand due to widespread deficiency in calcareous soils across South Asia and the Sahel, while foliar delivery methods are expanding fastest as farmers seek rapid correction during critical growth stages. The farmer segment anchors end-user volume, though agricultural cooperatives in Europe are capturing margin pools through collective bargaining and shared precision application equipment.
The EPA regulates micronutrient labeling and environmental release thresholds in the United States, while REACH and the EU F-Gas Regulation govern chemical composition and emissions profiles for products entering European markets. India's FSSAI and CEA coordinate with state agriculture departments to enforce quality standards under the national soil health card scheme, which mandates micronutrient testing. Stakeholders must monitor how carbon accounting frameworks and nutrient use efficiency metrics reshape product certification requirements and market access conditions.
Market Dynamics
Precision agriculture platforms are compressing application windows and forcing micronutrient suppliers to bundle real-time soil sensing with product formulations, collapsing the traditional separation between hardware vendors and input manufacturers.
Growth Catalysts
- India's Soil Health Card Scheme:State agriculture departments mandate micronutrient testing for subsidized fertilizer access, accelerating farmer education on zinc and boron deficiencies in calcareous soils.
- Foliar delivery systems:Specialty crop producers in Brazil deploy drone-mounted sprayers for rapid zinc correction during soybean reproductive stages, bypassing soil fixation limitations.
- EU F-Gas Regulation:Tightening emissions standards for fertilizer production equipment push manufacturers toward closed-loop nutrient recovery systems that recapture micronutrient byproducts.
Market Restraints
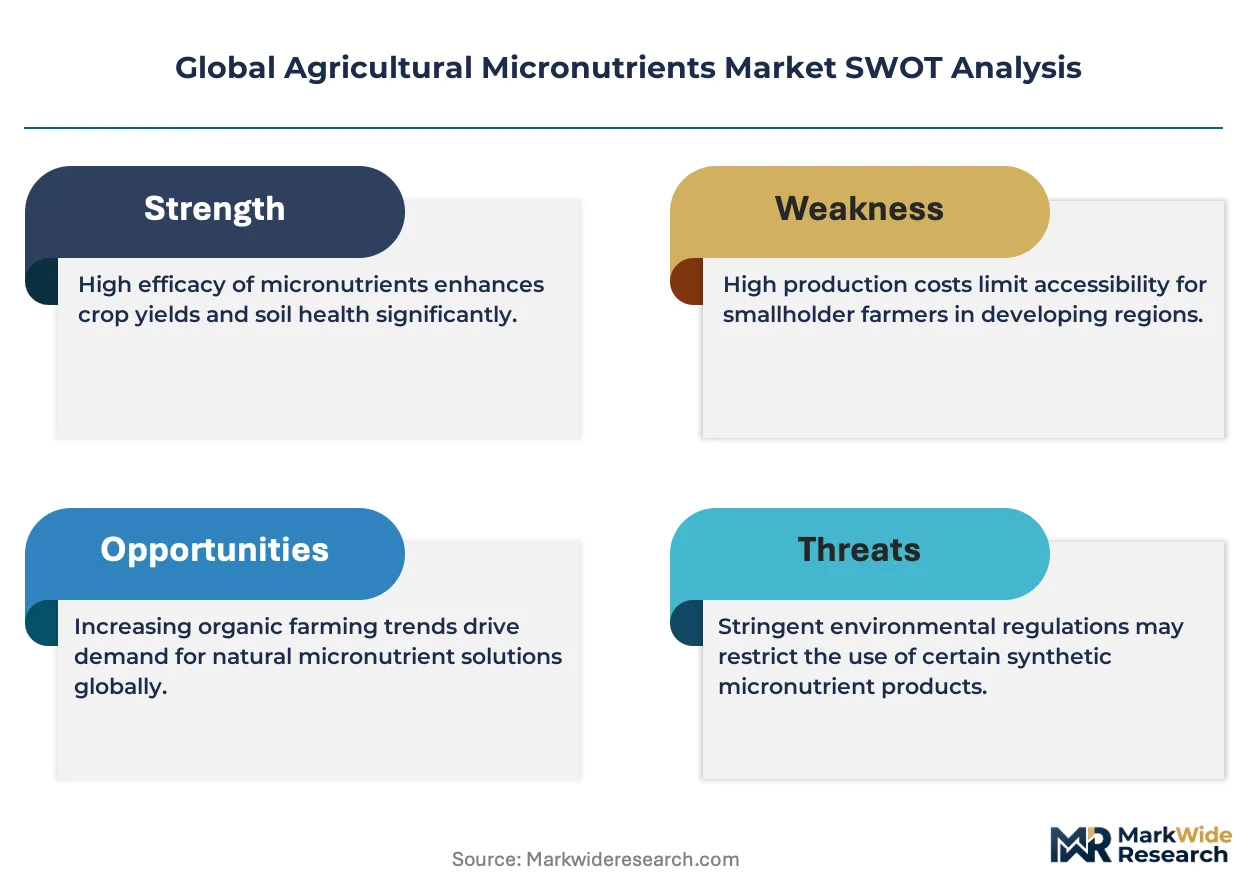
- Sulfuric acid price volatility:Processing of zinc sulfate and copper sulfate faces margin compression when sulfur feedstock costs spike, particularly affecting Brazilian blenders dependent on imported acid.
- Chinese processing concentration:Over half of refined boron and manganese sulfate originates from Shandong and Hunan provinces, exposing buyers to concentrated supply disruption risks.
- Soil fixation chemistry:High-pH calcareous soils across South Asia and the Sahel bind applied zinc into unavailable forms, limiting efficacy of conventional soil-applied products without chelation.
Strategic Opportunities
- Ethiopian highland agriculture:Teff and wheat rotations in the Ethiopian Highlands exhibit severe zinc deficiency with minimal historical micronutrient use, presenting first-mover expansion potential for foliar specialists.
- Controlled-release polymer coatings:Convergence of nanostructured encapsulation with precision irrigation enables synchronized nutrient release matching crop phenological demand curves.
- EU Carbon Border Adjustment Mechanism:Impending carbon intensity reporting requirements for imported fertilizers create advantage for European producers with verified low-emission micronutrient production pathways.
Industry Challenges
- Agronomic data integration:Farm management software platforms lack standardized APIs for micronutrient recommendation engines, forcing suppliers to maintain parallel technical support infrastructures.
- Organic certification timelines:OMRI and EU organic input approvals for novel chelated micronutrients require 18-24 month evaluation cycles, delaying market entry for reformulated products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Agricultural Micronutrients Market |
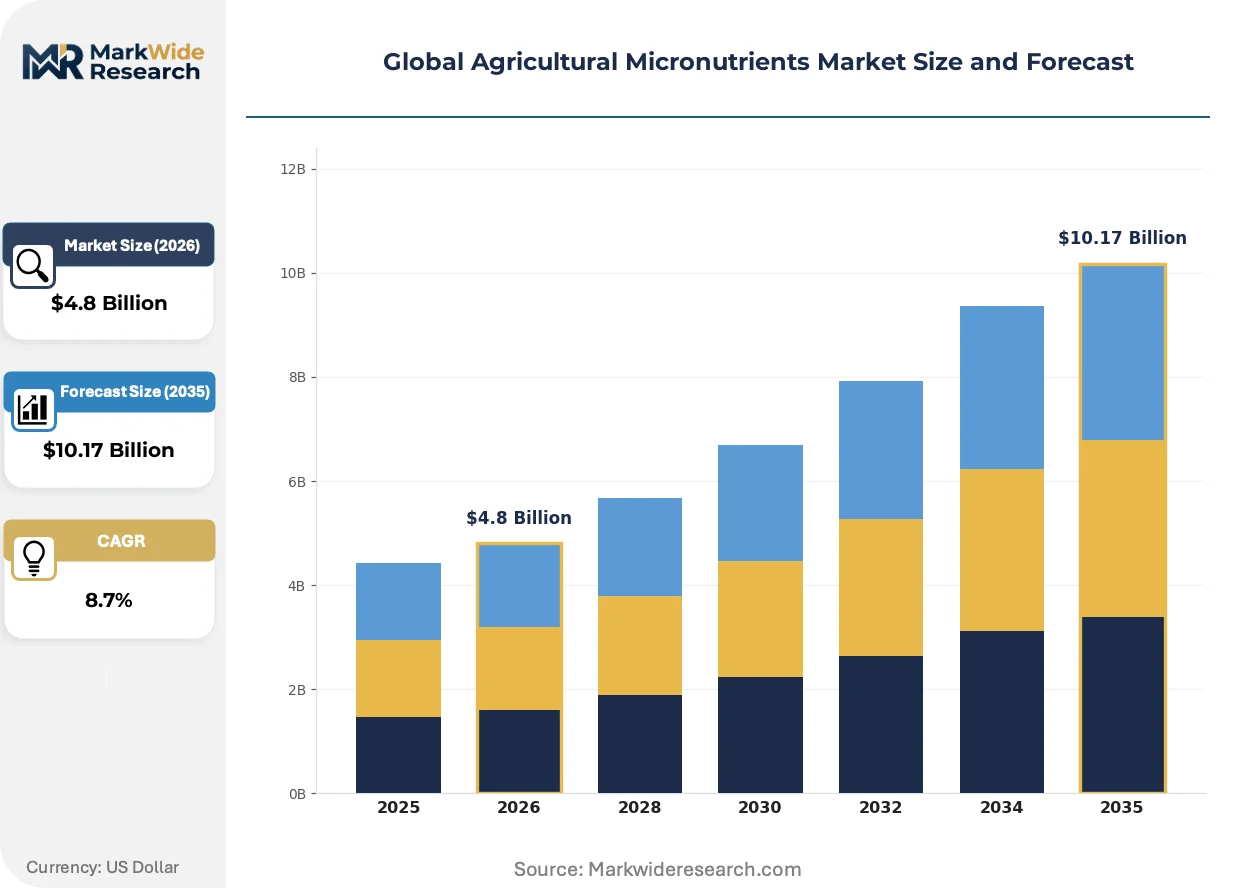
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Zinc, Iron, Boron, Manganese Application: Crops, Soils, Fertilizers, Foliar End User: Farmers, Agricultural Cooperatives, Distributors, Retailers Distribution Channel: Online, Offline, Direct Sales, Wholesale |
| Companies Covered | The Mosaic Company, Yara International, Haifa Group, Nutrien Ltd., ICL Specialty Fertilizers, Koch Agronomic Services, Tessenderlo Kerley, BASF, Nouryon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Agricultural Micronutrients Market Emerging Trajectories
Digital soil mapping and variable-rate application hardware are dissolving the boundaries between micronutrient supply and agronomic advisory, repositioning product vendors as data-integrated service providers.
Micro-encapsulated nutrient delivery is modularizing how specialty crop managers sequence interventions. California almond and pistachio growers now layer zinc, boron, and manganese releases through irrigation injection systems calibrated to phenological stages. This approach compresses the number of field passes while maintaining tissue concentration targets, enabling input suppliers to sell integrated season-long programs rather than discrete product units.
REACH authorization requirements for boron compounds are tightening compositional disclosure standards for micronutrient blends entering European markets. Manufacturers must now document full substance dossiers including co-formulant impurities, raising compliance costs for smaller blenders. German and Dutch agricultural cooperatives are responding by consolidating procurement through distributors with dedicated regulatory affairs capacity, filtering market access for direct-import suppliers.
Cooperative purchasing collectives are displacing individual farm gate transactions across European arable regions. French and Polish farmer-owned buying groups now negotiate micronutrient contracts covering multiple growing seasons, bundling volume commitments with shared precision application equipment. This concentration shifts bargaining power toward buyers capable of guaranteeing off-take minimums, pressuring suppliers to absorb price volatility through indexed contract structures rather than spot market exposure.
Global Agricultural Micronutrients Market Segmentation
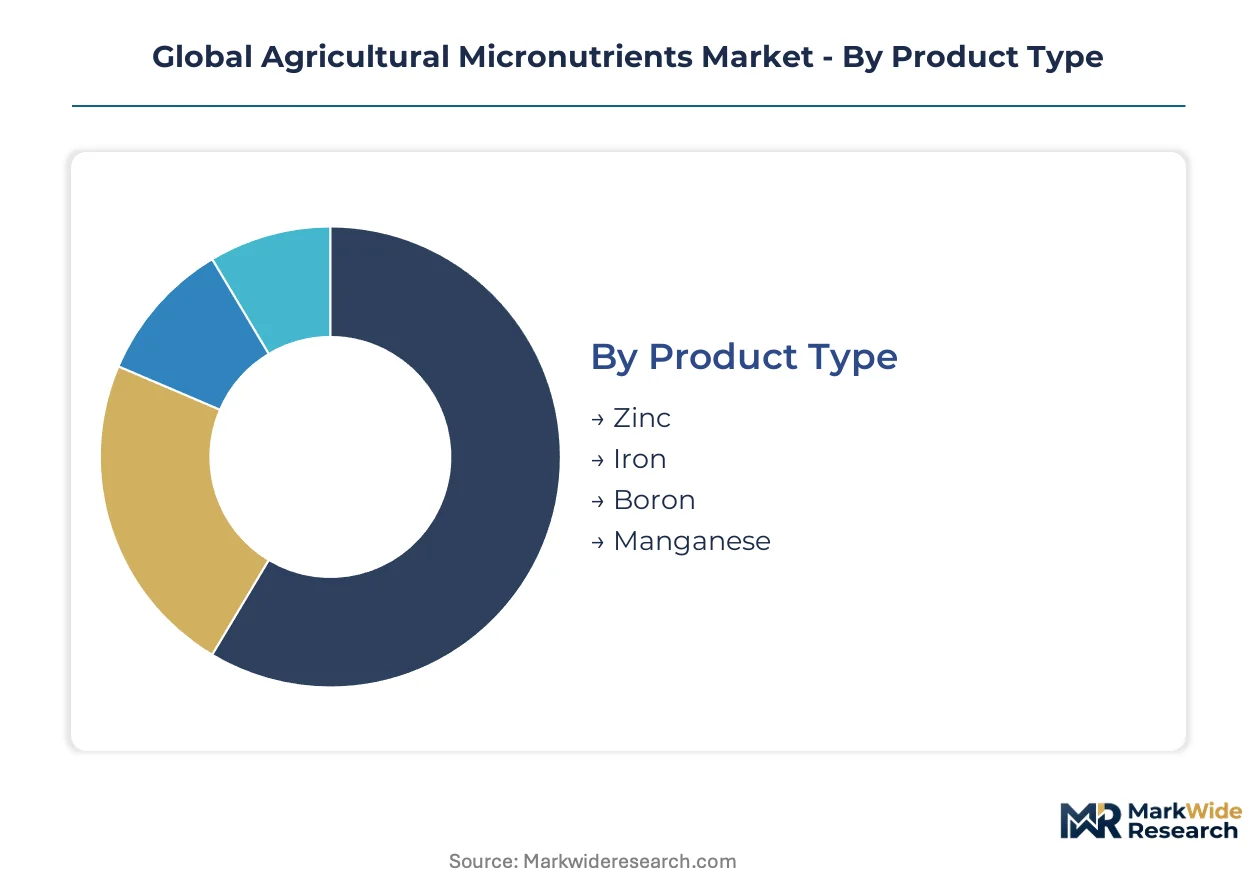
Micronutrient purchasing behavior fragments sharply across buyer sophistication levels, application timing constraints, and supply chain proximity requirements. Understanding these fault lines reveals where formulation premiums command pricing power versus where commodity logistics dominate procurement decisions.
Product Type:
Cost tier differentiation separates commodity sulfate salts from chelated premium formulations and determines margin capture potential across soil chemistry conditions.
- Zinc:Zinc sulfate and chelated forms correct widespread deficiency in calcareous soils, with demand concentrating in India where the Soil Health Card Scheme mandates testing for subsidized fertilizer access. High-pH fixation chemistry limits efficacy of conventional applications without EDTA or lignosulfonate chelation, driving premium formulation uptake.
- Iron:Ferrous sulfate and Fe-EDDHA address chlorosis in alkaline soils, with Brazilian soybean producers expanding foliar correction during reproductive stages as a rapid intervention bypassing soil fixation. Drone-mounted application systems compress treatment windows to critical growth phases.
- Boron:Boric acid and borate compounds regulate cell wall formation and reproductive development; REACH authorization requirements tighten compositional disclosure standards for European market entry.
- Manganese:Manganese sulfate supports photosynthetic enzyme function; Chinese processing concentration in Shandong and Hunan provinces exposes buyers to supply disruption risks.
Zinc leads volumes today; foliar-specialized manganese formulations are gaining share fastest.
Application:
Application method selection hinges on soil chemistry constraints, crop value density, and labor availability during narrow agronomic windows.
- Crops:Direct crop-specific formulations target high-value specialty production; California almond and pistachio growers layer zinc, boron, and manganese releases through irrigation injection systems calibrated to phenological stages.
- Soils:Broadcast and banded applications dominate broadacre grain systems; fixation chemistry in South Asian calcareous soils limits efficacy without chelation amendments.
- Fertilizers:Bulk blending with NPK carriers achieves scale economics; sulfuric acid price volatility compresses margins for zinc and copper sulfate processing.
- Foliar:Rapid tissue correction during critical growth stages; Brazilian specialty crop producers deploy drone-mounted sprayers for zinc intervention during soybean reproductive phases.
Soil applications retain volume dominance; foliar delivery is climbing the fastest as precision agriculture platforms compress treatment windows.
End User:
Customer scale and technical sophistication determine whether procurement optimizes for unit price or integrated agronomic support.
- Farmers:Individual operations anchor end-user volume with fragmented purchasing patterns; Indian government subsidized distribution accelerates uptake through state agriculture department networks.
- Agricultural Cooperatives:French and Polish farmer-owned buying groups negotiate multi-season contracts bundling volume commitments with shared precision application equipment.
- Distributors:Regional logistics networks consolidate procurement for smaller farm gate customers; Nutrien's North American retail network exemplifies service intensity at point of delivery.
- Retailers:Final-mile agronomic advice and product bundling; consolidation among large-scale commercial farming operations in Brazil and North America realigns patterns toward bulk contracts with technical support.
Farmers drive absolute volumes; agricultural cooperatives are capturing margin pools through collective bargaining leverage.
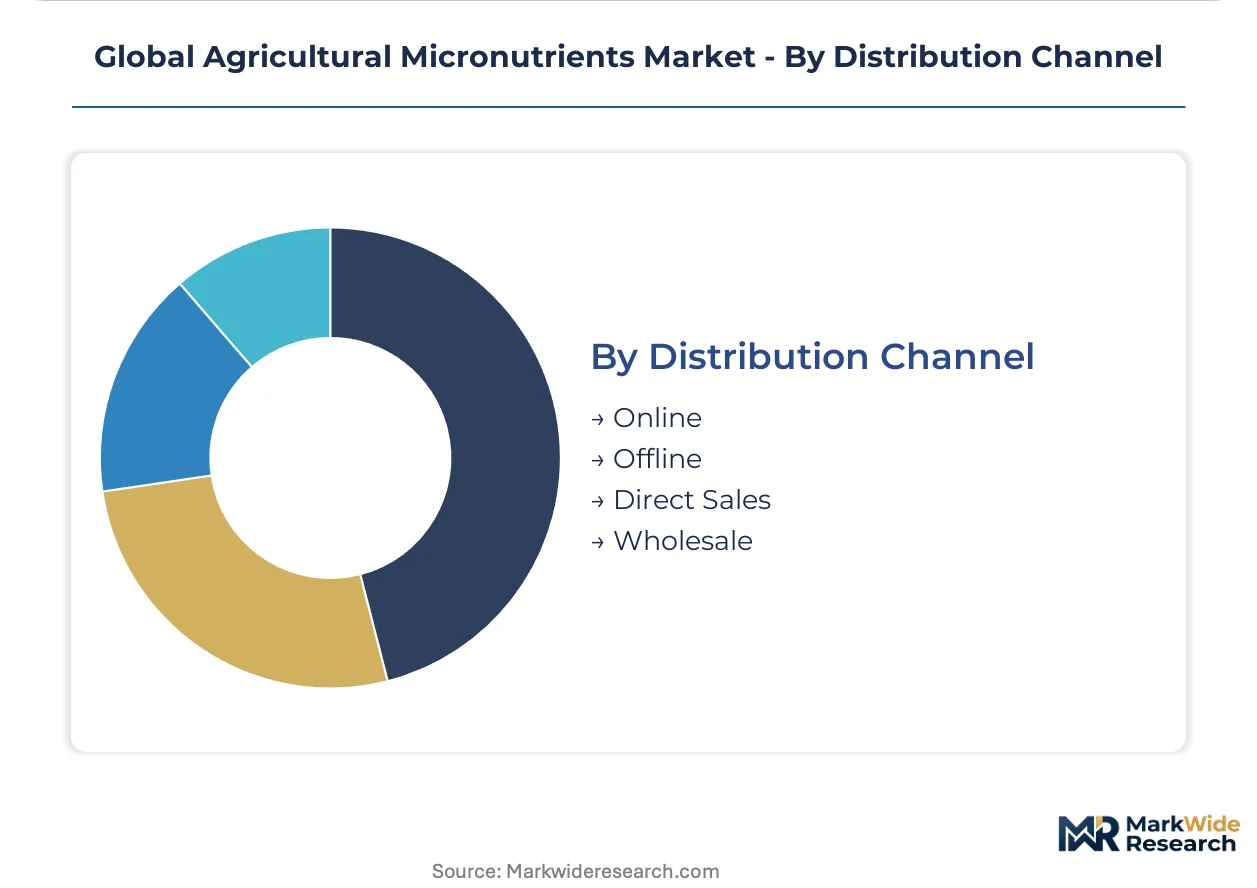
Distribution Channel:
Channel selection reflects order scale, technical support requirements, and geographic distance from manufacturing origin.
- Online:Digital platforms enable price transparency and specification comparison; farm management software integration remains constrained by lack of standardized APIs for micronutrient recommendation engines.
- Offline:Traditional agronomy retailer relationships persist where soil testing and prescription services bundle with product supply; German and Dutch cooperatives consolidate procurement through distributors with dedicated regulatory affairs capacity.
- Direct Sales:Large-scale consolidated farming operations negotiate bulk contracts with manufacturers; The Mosaic Company anchors supply relationships through integrated phosphate and micronutrient portfolio bundling.
- Wholesale:Volume aggregation for regional redistribution; indexed contract structures absorb price volatility for buyers guaranteeing off-take minimums.
Offline channels retain volume leadership; direct sales to consolidated farm operations are expanding most quickly as procurement scale concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized agronomic talent pools in Brazil, India, and the United States anchor the geographic concentration of micronutrient formulation expertise and precision application technology deployment.
Brazil
Soybean-corn rotation expansion in Mato Grosso and Paraná drives zinc and boron demand for soil deficiency correction. ANVISA coordinates with state agriculture departments to enforce fertilizer quality standards under federal micronutrient labeling requirements. Campo Grande-based cooperatives deploy drone-mounted foliar systems for rapid reproductive-stage intervention.
India
The Soil Health Card Scheme mandates micronutrient testing for subsidized fertilizer access across Punjab and Haryana wheat belts. FSSAI and CEA enforce quality standards for zinc sulfate and chelated formulations distributed through state agriculture networks. Gujarat and Maharashtra processing clusters supply blended micronutrient carriers to cooperative procurement channels.
United States
Consolidated commercial farming operations in Iowa and Illinois realign procurement toward bulk contracts with bundled technical support. EPA regulates micronutrient labeling and environmental release thresholds for products entering interstate commerce. California's Central Valley specialty crop districts layer zinc, boron, and manganese through precision irrigation injection systems.
Germany
Agricultural cooperatives in Lower Saxony and Bavaria consolidate procurement through distributors with dedicated regulatory affairs capacity. REACH authorization requirements tighten compositional disclosure standards for boron compounds entering European markets. Kiel and Hamburg logistics clusters coordinate multi-season indexed contracts for farmer-owned buying groups.
China
Shandong and Hunan provinces concentrate refined boron and manganese sulfate processing capacity serving export markets. The country's national chemical regulator encloses fertilizer production within emissions monitoring frameworks aligned with dual carbon goals. Qingdao port infrastructure handles bulk micronutrient salt shipments to South Asian and African agricultural importers.
Global Agricultural Micronutrients Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation tiers, creating a bifurcated structure where scale-driven phosphate majors anchor supply relationships while regional blenders capture service-intensive niches. The vendor base organizes around three strategic archetypes: integrated nutrient portfolio holders, controlled-release technology specialists, and precision application service integrators. Dominant competitive moves include backward integration into sulfuric acid and phosphate rock sourcing to secure processing margins, and partnerships with digital farming platforms to embed micronutrient recommendations within farm management software.
Within the integrated portfolio tier, The Mosaic Company exemplifies the phosphate-micronutrient bundling archetype through its combined mining and formulation assets. Yara International occupies a position among controlled-release technology specialists, while Nutrien Ltd. anchors the North American retail distribution vector with farm gate service intensity. These three entities represent distinct strategic postures without implying specific market share positions or operational claims.
| Leading Market Players |
|---|
| The Mosaic Company |
| Yara International |
| Haifa Group |
| Nutrien Ltd. |
| ICL Specialty Fertilizers |
| Koch Agronomic Services |
| Tessenderlo Kerley |
| BASF |
| Nouryon |
| Others |
Supply Flow & Price Mechanics
Sulfuric acid feedstock costs cascade through zinc and copper sulfate processing tiers, compressing margins for Brazilian blenders dependent on imported acid while rewarding European producers with captive sulfur recovery from phosphate operations. This input-cost geography splits pricing power between integrated phosphate majors and regional toll processors.
Pricing Analysis
Bundled technical support separates contract structures for consolidated commercial farming operations from spot-market commodity transactions. Three-tier pricing structure across premium, standard, and economy levels reflects chelation chemistry grade and volume commitment scale. Pricing pressure stems from sulfuric acid volatility and Chinese processing concentration, with Indian state-subsidized distribution channels exhibiting highest price sensitivity and California specialty crop growers showing lowest sensitivity due to yield-risk premiums.
Supply Chain Analysis
REACH authorization and FSSAI quality standards gate market entry for boron compounds and zinc formulations, filtering smaller blenders from European and Indian distribution. Supply concentrates in China for refined boron and manganese sulfate, India for blended micronutrient carriers, and Brazil for regional toll processing. Raw material dependencies include sulfur feedstock, phosphate rock, and lignosulfonate chelating agents. Single-source vulnerability in Shandong and Hunan processing clusters exposes buyers to disruption. Distribution runs through agricultural cooperatives in Europe, state agriculture departments in India, and integrated retail networks in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Agricultural Micronutrients Market functions as a regulatory compounder where India's Soil Health Card Scheme and EU F-Gas Regulation tighten compliance thresholds that accelerate premium formulation demand.
For Market Incumbents: Extend controlled-release technology portfolios into precision irrigation synchronization to defend against drone-mounted foliar specialists capturing Brazilian soybean reproductive-stage interventions. Backward integration into sulfuric acid sourcing secures processing margins against feedstock volatility. Investment in regulatory affairs capacity filters market access for smaller competitors under REACH authorization timelines. For New Entrants and Emerging Players: The premium-economy price-point gap in Ethiopian highland teff and wheat rotations offers first-mover expansion potential with minimal historical micronutrient penetration. Foliar-specialized manganese formulations targeting calcareous soil fixation chemistry represent the most penetrable product tier. Go-to-market through development finance institution partnerships bypasses fragmented farm-gate distribution. For Investors and Strategic Acquirers: Roll-up economics work for regional precision application service integrators because cooperative purchasing collectives concentrate buyer power and demand bundled technical support. Five-to-ten year viability hinges on carbon intensity verification pathways under impending EU Carbon Border Adjustment Mechanism reporting requirements. Watch for OMRI and EU organic certification timeline compression as inflection signal for novel chelated formulation market entry.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sulfur Recovery | Captive acid supply shields Brazilian processors from import price spikes and margin compression. |
| Controlled-Release Polymer Coating Development | Nanostructured encapsulation enables synchronized nutrient release matching crop phenological demand curves. |
| Precision Agriculture Platform Partnership | Digital farming integration embeds micronutrient recommendations within farm management software workflows. |
| Regulatory Affairs Capacity Buildout | Dedicated compliance teams filter market access under REACH and FSSAI quality standard enforcement. |
| Multi-Season Indexed Contract Structuring | Volume commitment guarantees absorb price volatility for European cooperative procurement channels. |
Methodological Framework
Direct dialogue with micronutrient formulation chemists, agricultural cooperative procurement managers, state agriculture department officials, and precision application equipment distributors grounded qualitative findings in operational reality. Secondary validation drew from customs trade databases, EPA and ECHA regulatory filings, state fertilizer subsidy disbursement records, and agricultural cooperative annual reports. Bottom-up farmer adoption modeling and top-down nutrient demand projection triangulated volume estimates across the analysis window.
Bottom-up segmentation by product type, application method, and end-user archetype intersected with top-down macroeconomic drivers and regulatory milestone tracking throughout the forecast period. CAGRs derived from fitted growth curves against historical adoption patterns in comparable soil health intervention programs. Industry-specific forecast inputs included sulfuric acid price indices, drone-mounted sprayer deployment rates, and organic certification approval cycle durations.
Caveats apply where sulfur feedstock cost spikes, Chinese processing disruption, or carbon accounting framework revisions could materially shift the outlook. Forecasts reflect assumptions on subsidy continuity, regulatory enforcement intensity, and precision agriculture hardware penetration trajectories. A model refresh is warranted upon material change in EU Carbon Border Adjustment Mechanism implementation timelines or Indian Soil Health Card Scheme expansion rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Mexico Feed Additives Market
Agricultural Chemicals
North America Castor Oil Market
Agricultural Chemicals
Asia-Pacific Feed Binders Market
Agricultural Chemicals
Glyphosate Herbicide Market
Agricultural Chemicals
Europe Feed Pelletizing Agents Market
Agricultural Chemicals
Asia-Pacific Plant Growth Regulators Market
Agricultural Chemicals
China Castor Oil Market
Agricultural Chemicals
Artificial Humus Market
Agricultural Chemicals
Berry Greenhouse Premium Micronutrient Package Market
Agricultural Chemicals
Global Feed Palatability Enhancers Market
Agricultural Chemicals
North America Feed Pigments Market
Agricultural Chemicals
Feed Antibiotics Market
Agricultural Chemicals
India Phosphate Rich Organic Manure (PROM) Market
Agricultural Chemicals
Feed Preservatives Market
Agricultural Chemicals
South America Agricultural Disinfectants Market
Agricultural Chemicals
Amino Acid for Agriculture Market