
 South America Feed Enzymes Market | 2026-2036
South America Feed Enzymes Market Size, Share, and Industry Trends Forecast 2026-2036
South America Feed Enzymes Market Analytics
Broiler poultry operations is recalibrating enzyme procurement priorities across South America as producers seek alternatives to antibiotic growth promoters. Novonesis A/S leverages its fermentation technology leadership to supply phytase concentrates optimized for tropical feed formulations. Cargill Incorporated anchors regional distribution through its integrated animal nutrition network spanning Brazil and Argentina. BASF SE differentiates via enzyme stability engineering for high-temperature pelleting conditions common in South American feed mills.
Feed enzymes comprise biocatalytic proteins—primarily amylase, protease, cellulase, and phytase—produced through submerged fermentation or solid-state fermentation of microbial strains, then stabilized for thermal tolerance during feed processing. These additives degrade anti-nutritional factors, liberate bound phosphorus, and improve amino acid digestibility in cereal-soybean diets fed to monogastric and ruminant livestock. Phytase dominates value contribution due to its direct replacement of inorganic phosphate supplements and associated cost savings for compound feed manufacturers. Protease exhibits the fastest structural expansion as soybean meal price volatility drives formulators toward alternative protein sources with higher indigestible fractions. Liquid delivery mode leads in large-scale mill integration for dosing accuracy, though powder formats sustain penetration among smaller regional blenders lacking liquid handling infrastructure.
Brazil's MAPA and Argentina's SENASA enforce residue monitoring and antibiotic reduction mandates that directly expand enzyme eligibility in official feed formulations. ANVISA pharmaceutical oversight and Mercosur harmonization protocols shape cross-border product registration timelines and label claim standards for imported enzyme preparations. Stakeholders must monitor evolving national implementation timelines for Mercosur's unified feed additive registry, as asynchronous adoption between Brazil and Argentina could fragment procurement strategies across integrated livestock operations.
Market Dynamics
Brazil's MAPA enforcement of antibiotic-free growth promoter regulations is compressing enzyme adoption timelines across the southern livestock corridor, forcing compound feed manufacturers to reconfigure formulation protocols around phytase and protease substitution.
Growth Catalysts
- ANVISA pharmaceutical oversight:Residue monitoring mandates eliminate antibiotic growth promoters from broiler rations, creating immediate eligibility expansion for exogenous enzymes in official feed formulations.
- Soybean meal price volatility:Protease demand accelerates as formulators pivot toward alternative protein sources with higher indigestible fractions requiring enzymatic pre-processing.
- Paraná-Santa Catarina corridor concentration:Integrated poultry operations achieve scale economies in liquid enzyme dosing infrastructure that smaller regional blenders cannot replicate.
Market Restraints
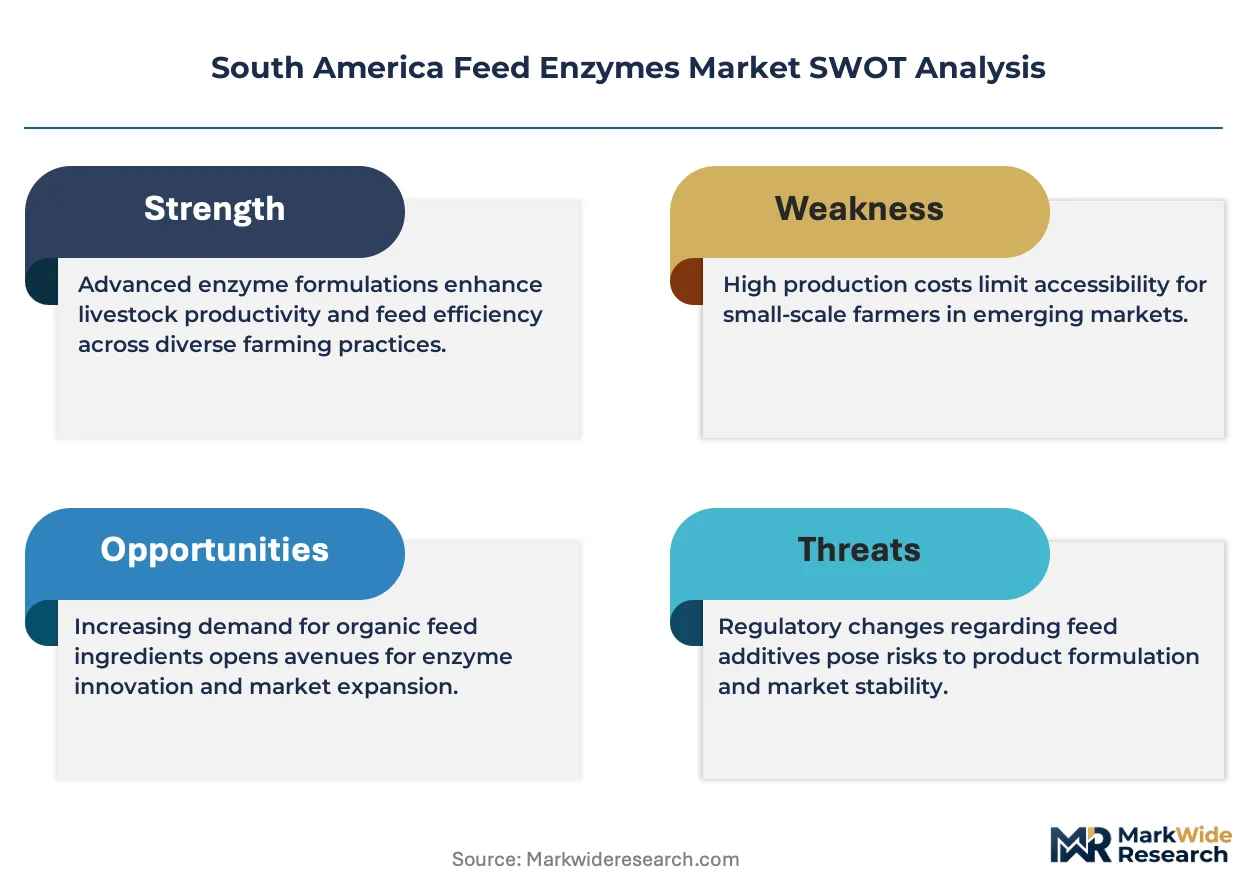
- Fermentation input cost volatility:Submerged fermentation substrate prices fluctuate with Brazilian corn and sugarcane molasses markets, compressing phytase concentrate margins.
- Mercosur harmonization delays:Asynchronous adoption between Brazil and Argentina fragments procurement strategies for cross-border integrated livestock operations.
- Thermal stability limitations:High-temperature pelleting conditions common in South American feed mills degrade unprotected enzyme activity, requiring costly stabilization engineering.
Strategic Opportunities
- Rio Grande do Sul dairy expansion:Ruminant enzyme penetration remains underdeveloped relative to monogastric applications, offering white space for cellulase and amylase formulations.
- SENASA antibiotic reduction mandates:Argentina's regulatory alignment with Brazilian standards creates synchronized demand pull across the Mercosur bloc.
- Powder-to-liquid conversion:Regional blenders lacking liquid handling infrastructure represent captive upgrade demand for engineered dry thermostable concentrates.
Industry Challenges
- Cross-border registration complexity:Mercosur's unified feed additive registry remains unimplemented, forcing duplicate dossier submissions to MAPA and SENASA with divergent label claim standards.
- Fermentation strain optimization:Tropical feed formulation requirements demand specialized microbial strain development that regional R&D infrastructure struggles to support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Feed Enzymes Market |
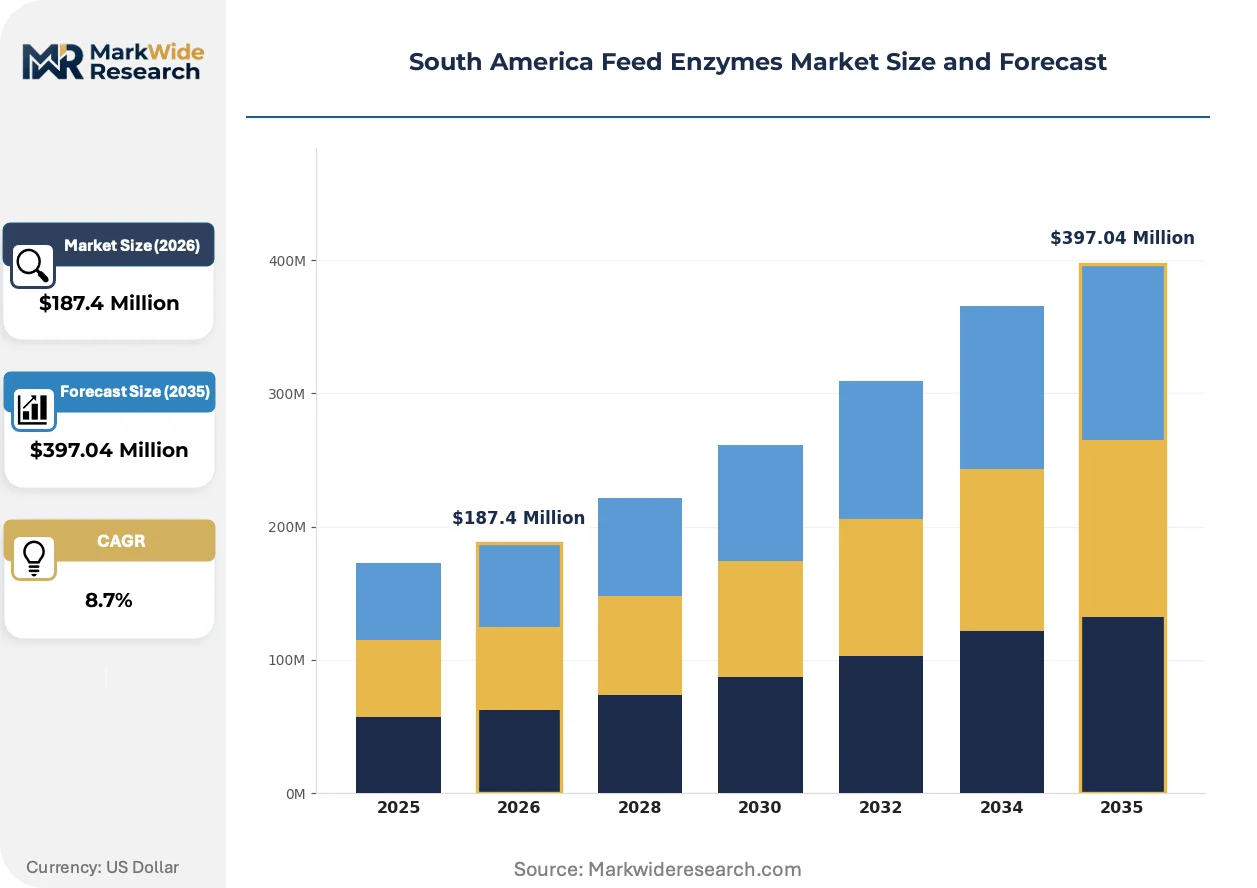
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Amylase, Protease, Cellulase, Phytase Application: Poultry, Swine, Ruminants, Aquaculture Delivery Mode: Liquid, Powder, Granular, Concentrated End User: Feed Manufacturers, Livestock Farms, Aquaculture Operators, Animal Nutritionists |
| Companies Covered | Novonesis A/S, Brenntag SE, Kerry Group Plc, Elanco Animal Health Inc., Archer Daniels Midland Company, BASF SE, Evonik Industries AG, DSM Nutritional Products, Cargill Incorporated, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Feed Enzymes Market Evolving Landscape
Enzyme engineering priorities across South America center on thermal tolerance and tropical formulation compatibility, with manufacturers racing to match pelleting conditions and substrate variability that characterize regional feed mill operations.
Granular thermostable phytase concentrates are absorbing the capital deployment focus of large-scale compound feed manufacturers. Novonesis A/S and Cargill Incorporated anchor supply of engineered variants that withstand 85°C pelleting temperatures common in Brazilian operations. This absorption is compressing demand for standard-grade powder formats among integrated poultry producers while fragmenting procurement tiers between multinational mills and regional blenders.
MAPA's antibiotic growth promoter phase-out timeline is accelerating protease adoption in broiler starter diets. The regulation forces reformulation of corn-soybean rations around digestibility enhancement rather than growth promotion. Poultry integrators in Paraná and Santa Catarina are responding with dedicated enzyme procurement committees that bypass traditional additive distributors.
Integrated livestock operations are consolidating enzyme sourcing decisions at headquarters level, displacing decentralized mill-level procurement. Large poultry and swine producers in Brazil's southern corridor now negotiate multi-year enzyme supply agreements directly with fermentation specialists. This concentration is most visible among vertically integrated broiler operations that internalize feed manufacturing across 15-20 owned mills.
South America Feed Enzymes Market Segmentation
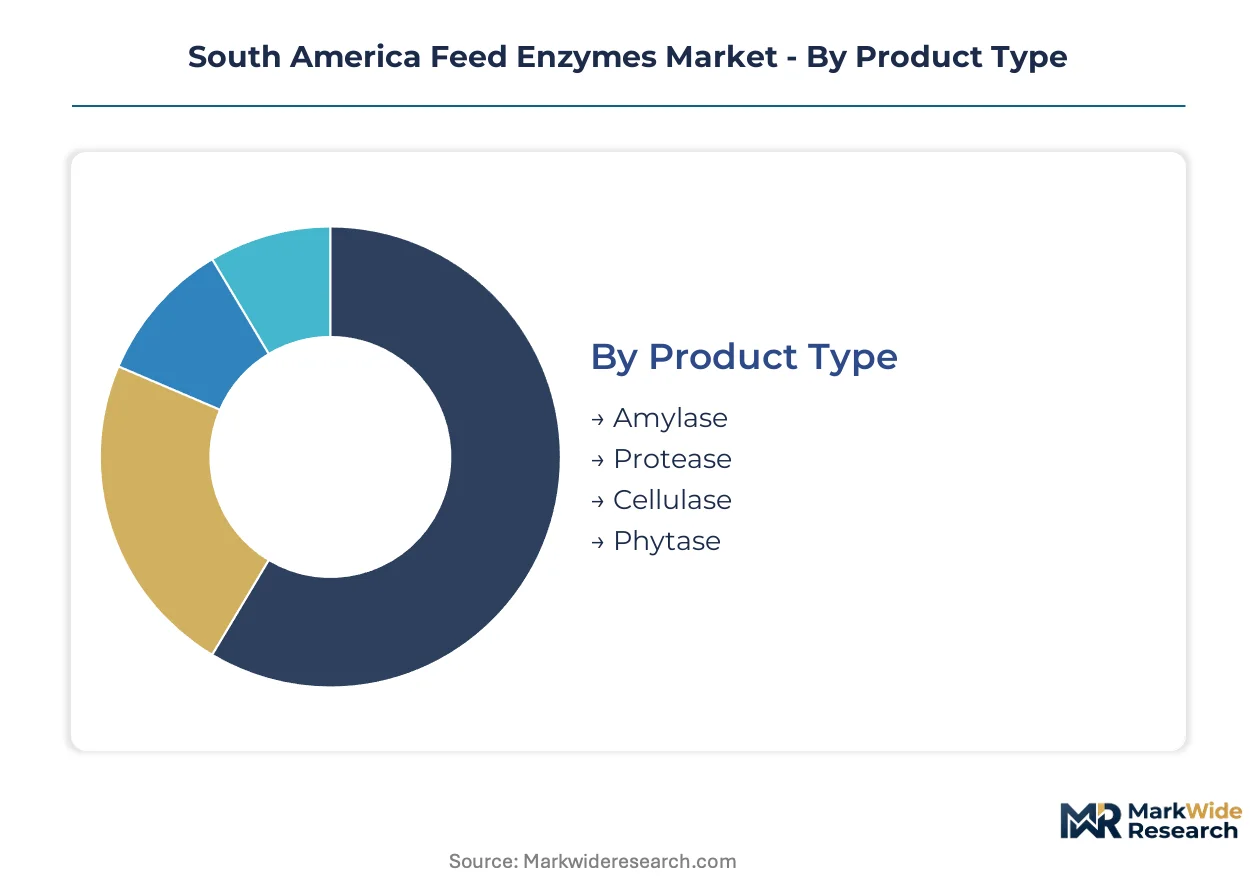
Feed enzyme segmentation in South America reflects divergent regulatory burdens across product categories, with phytase and protease preparations facing distinct MAPA registration pathways compared to cellulase variants. Procurement patterns fragment between large compound feed manufacturers demanding liquid dosing systems and regional blenders constrained by powder handling infrastructure.
Product Type:
MAPA's feed additive registry applies differential documentation requirements across enzyme classes, with phytase concentrates requiring phosphorus-release efficacy studies while protease submissions demand amino acid digestibility trials under tropical conditions.
- Phytase:Fermentation-derived biocatalysts hydrolyzing phytic acid to liberate bound phosphorus in corn-soybean diets. Demand concentrates in Brazil's southern poultry corridor where MAPA's antibiotic growth promoter ban forces phosphate substitution economics. Registration dossiers must demonstrate thermal stability through 85°C pelleting simulations.
- Protease:Endo- and exopeptidase complexes degrading protein anti-nutritional factors and improving amino acid availability. Santa Catarina broiler integrators are expanding procurement as soybean meal price volatility drives alternative protein sourcing with higher indigestible fractions. ANVISA residue monitoring protocols accelerate substitution timelines.
- Amylase:Starch-hydrolyzing enzymes targeting cereal-based energy release in monogastric rations.
- Cellulase:Fiber-degrading complexes for ruminant and high-fiber diet applications, currently underpenetrated relative to monogastric enzymes.
Leading the category by volume: Phytase. Growing fastest: Protease.
Application:
End-use concentration varies sharply across livestock sectors, with poultry operations achieving scale economies in enzyme dosing infrastructure that ruminant and aquaculture systems have yet to replicate.
- Poultry:Broiler and layer operations dominate enzyme consumption through integrated feed manufacturing across Paraná, Santa Catarina, and Rio Grande do Sul. MAPA's enforcement of antibiotic-free growth promoter regulations has compressed adoption timelines, with phytase and protease now standard in starter and grower rations. Vertically integrated producers internalize formulation decisions across 15-20 owned mills.
- Swine:Sow and finishing diet applications expanding as SENASA in Argentina aligns residue standards with Brazilian protocols, creating synchronized Mercosur demand.
- Ruminants:Dairy and beef cattle enzyme penetration remains underdeveloped, offering white space for cellulase and amylase formulations in Rio Grande do Sul's expanding dairy sector.
- Aquaculture:Shrimp and finfish feed applications constrained by specialized formulation requirements and limited regional production infrastructure.
Poultry commands the volume base. Swine exhibits the steepest expansion trajectory as Argentine regulatory alignment proceeds.
Delivery Mode:
Physical format selection directly correlates with mill infrastructure investment, fragmenting procurement tiers between multinational compounders and regional blenders lacking liquid handling systems.
- Liquid:Aqueous enzyme suspensions enabling precision dosing through automated injection systems. Large-scale mill integration dominates in Brazil's southern corridor where integrated poultry operations achieve dosing accuracy impossible with dry formats. MAPA stability testing requirements for liquid concentrates are less stringent than for thermostable granules.
- Powder:Spray-dried preparations for smaller regional blenders lacking liquid infrastructure. Santa Catarina and Paraná mid-tier compounders sustain this segment despite handling losses and dosing variability.
- Granular:Thermostable concentrates engineered for high-temperature pelleting common in South American feed mills.
- Concentrated:High-activity formulations reducing transport and storage costs for remote livestock operations.
Liquid formats lead in value contribution. Powder-to-liquid conversion represents the captive upgrade pathway for infrastructure-constrained blenders.
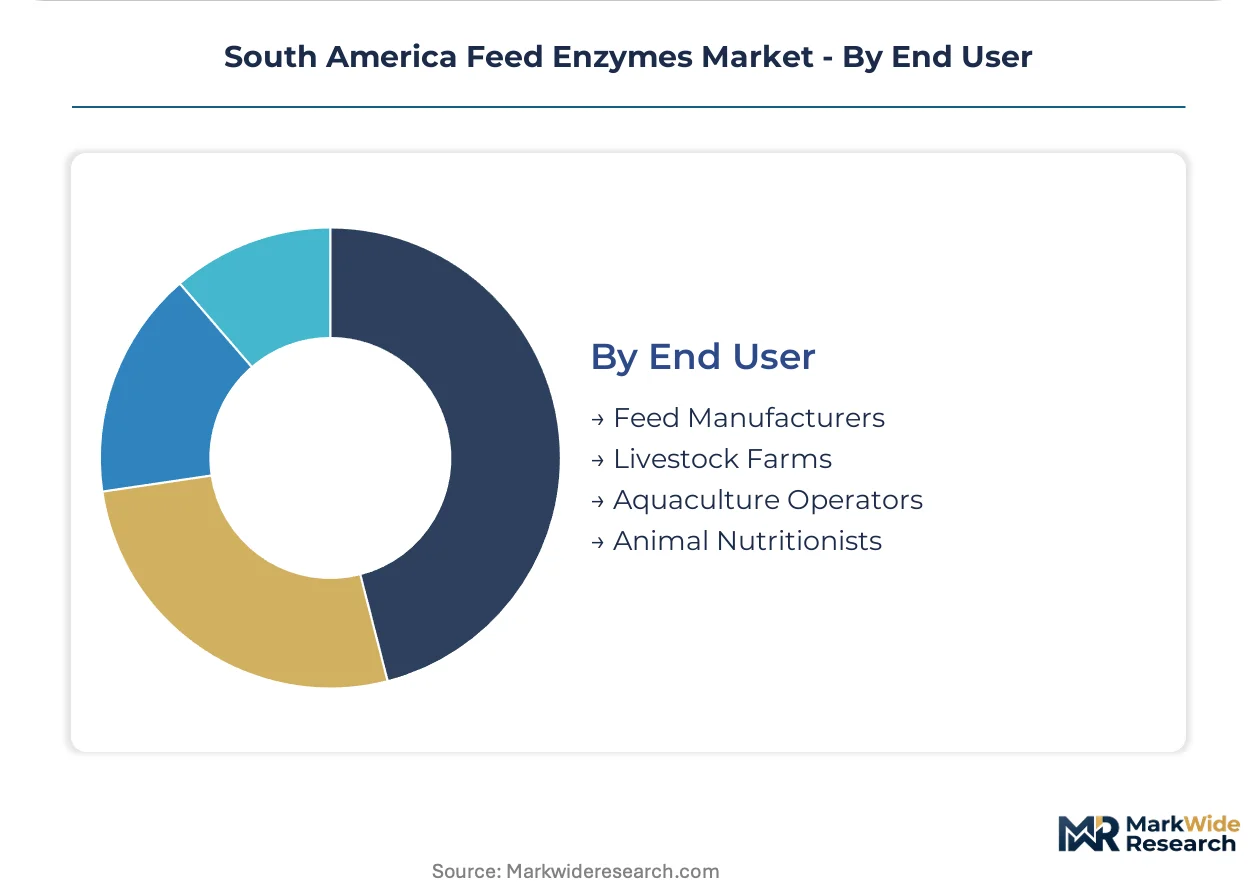
End User:
Procurement authority is consolidating at headquarters level among integrated operations, displacing decentralized mill-level purchasing that previously characterized regional enzyme distribution.
- Feed Manufacturers:Compound feed producers ranging from multinational integrated operations to regional blenders. Brazil's southern corridor concentration enables direct negotiation with fermentation specialists, bypassing traditional additive distributors. MAPA registration holders must maintain separate dossiers for each manufacturing site.
- Livestock Farms:Vertically integrated poultry and swine operations internalizing feed manufacturing. Rio Grande do Sul dairy expansion is creating new on-farm formulation demand for ruminant-specific enzymes.
- Aquaculture Operators:Shrimp and fish farm feed mills with specialized enzyme stability requirements.
- Animal Nutritionists:Formulation consultants influencing enzyme specification in independent feed mill contracts.
Feed manufacturers absorb the procurement volume. Livestock farms are gaining share fastest as vertical integration deepens across Brazil and Argentina.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's Zona Franca de Manaus and Argentina's Tierra del Fuego free-trade zones concentrate enzyme import infrastructure, creating tax-advantaged entry points for fermentation-derived feed additives across the southern livestock corridor.
Brazil
Broiler integrators in Paraná and Santa Catarina are expanding phytase procurement as MAPA enforces antibiotic-free growth promoter regulations. ANVISA residue monitoring protocols eliminate traditional growth promoters from official feed formulations. The southern livestock corridor spanning Curitiba to Florianópolis now hosts dedicated enzyme procurement committees that bypass traditional additive distributors.
Argentina
Santa Fe and Córdoba feed manufacturers are accelerating protease adoption amid soybean meal price volatility and alternative protein sourcing. SENASA antibiotic reduction mandates align with Brazilian MAPA standards, creating synchronized Mercosur demand. Rosario's grain-export hub anchors regional distribution networks for thermostable enzyme concentrates.
Chile
Salmon aquaculture operators in Los Lagos Region are testing cellulase and amylase formulations for high-fiber diet applications. The country's national pharmaceutical regulator enforces strict residue monitoring that expands enzyme eligibility in finfish rations. Puerto Montt's aquafeed manufacturing cluster drives specialized stability requirements for cold-water species.
Colombia
Antioquia and Cundinamarca poultry producers are adopting liquid enzyme dosing systems as vertical integration deepens across the Andean region. The national agricultural institute promotes antibiotic reduction programs that accelerate exogenous enzyme substitution. Bogotá's compound feed manufacturing belt concentrates procurement decisions at headquarters level.
Uruguay
Dairy operations in Colonia and San José are emerging as ruminant enzyme testing grounds for cellulase fiber-degrading applications. Mercosur harmonization protocols streamline cross-border product registration with Brazilian MAPA standards. Montevideo's port infrastructure supports enzyme concentrate imports for pasture-based livestock systems.
South America Feed Enzymes Market Competitive Landscape
Top-tier vendors anchor supply of thermostable phytase concentrates, while mid-tier regional blenders sustain powder-format demand through infrastructure constraints. The market exhibits tiered consolidation around fermentation technology leadership and distribution network scale. Three archetypes dominate: multinational nutrition integrators with captive enzyme supply, specialized fermentation houses with tropical formulation expertise, and regional distributors bridging import logistics. Competitive moves concentrate on backward integration into strain development and geographic expansion through Mercosur registration harmonization.
Within the fermentation-specialist tier, Novonesis A/S and BASF SE exemplify thermal stability engineering capabilities for high-temperature pelleting conditions. Among nutrition-integrated distributors, Cargill Incorporated occupies a position linking Brazilian and Argentine feed manufacturing networks. These three anchors represent distinct competitive vectors: microbial strain optimization, industrial process engineering, and supply chain integration across the southern livestock corridor.
| Leading Market Players |
|---|
| Novonesis A/S |
| Brenntag SE |
| Kerry Group Plc |
| Elanco Animal Health Inc. |
| Archer Daniels Midland Company |
| BASF SE |
| Evonik Industries AG |
| DSM Nutritional Products |
| Cargill Incorporated |
| Others |
Value Network & Pricing Analysis
Captive supply of fermentation-derived phytase concentrates anchors pricing power for integrated compound feed manufacturers across Brazil's southern corridor. MAPA's antibiotic growth promoter ban forces procurement committees to absorb cost premiums for thermostable granules, while regional blenders lacking liquid infrastructure face persistent powder-format penalties.
Pricing Analysis
Short lead-time premiums dominate enzyme concentrate transactions, with Brazilian poultry integrators paying markups for MAPA-registered thermostable phytase delivered within 48 hours. Three-tier pricing structure across premium thermostable granules, standard liquid concentrates, and economy powder formats reflects certification grade and volume scale differentials. Cost compression in standard-grade powder tiers is intensifying because regional blenders face dosing accuracy penalties that erode effective value. Mid-tier compounders in Santa Catarina exhibit highest price sensitivity, while vertically integrated broiler operations show least elasticity due to captive formulation economics.
Supply Chain Analysis
MAPA's domestic-content documentation requirements for feed additive registration are reshaping sourcing toward Brazilian fermentation capacity and Argentine toll-manufacturing partnerships. Supply concentrates in Brazil, Denmark, and Germany for phytase and protease concentrates, with Brazilian corn and sugarcane molasses feeding submerged fermentation substrates. Raw material dependencies include microbial strain banks, pharmaceutical-grade nitrogen sources, and specialized stabilizer chemistries. Single-source vulnerability runs through Novonesis A/S and BASF SE for thermostable granule engineering. Distribution runs through Cargill Incorporated's integrated nutrition network spanning Paraná to Buenos Aires.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's MAPA enforcement of antibiotic-free growth promoter regulations erects a compliance moat that favors registered enzyme suppliers with thermal stability dossiers. ANVISA residue monitoring protocols compound documentation burdens, fragmenting procurement authority toward headquarters-level fermentation specialists.
For Market Incumbents: Extend thermostable strain development pipelines toward 90°C pelleting tolerance to capture MAPA-registered premium positioning. Defend against Argentine SENASA alignment by pre-positioning dual-registered dossiers before Mercosur harmonization completes. Capacity addition in Rio Grande do Sul dairy corridor anchors ruminant enzyme white-space capture before regional blenders consolidate.
For New Entrants and Emerging Players: Capture powder-to-liquid conversion demand among Paraná mid-tier compounders lacking automated dosing infrastructure. Target Santa Catarina regional blenders with engineered dry thermostable concentrates as an upgrade pathway bypassing capital-intensive liquid system installation. Partner with Rosario grain-export hub distributors for Argentine market entry under SENASA accelerated registration timelines.
For Investors and Strategic Acquirers: Exit pathways concentrate in fermentation-specialist acquisition by nutrition-integrated multinationals seeking tropical formulation capabilities. Long-term viability favors players with backward integration into microbial strain development and cross-border Mercosur registration infrastructure. Monitor SENASA-MAPA regulatory synchronization as the inflection signal for synchronized demand pull across the southern livestock corridor.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Strain Development | Captive microbial optimization for tropical feed formulations reduces dependency on external fermentation houses. |
| Mercosur Registration Harmonization | Unified MAPA-SENASA dossier standards compress cross-border procurement fragmentation for integrated livestock operations. |
| Thermal Stability Engineering Investment | 85°C pelleting tolerance unlocks premium positioning in Brazilian compound feed manufacturing corridor. |
| Powder-to-Liquid Infrastructure Conversion | Automated dosing system deployment captures mid-tier blender upgrade demand in Paraná and Santa Catarina. |
| Ruminant Enzyme Formulation Expansion | Cellulase and amylase development targets underpenetrated Rio Grande do Sul dairy sector applications. |
Research Methodology
Multi-period observation of MAPA registration timelines, ANVISA residue monitoring enforcement, and SENASA antibiotic reduction mandates anchored the trend analysis, supplemented by interviews with compound feed procurement directors, fermentation plant managers, MAPA regulatory affairs specialists, and SENASA compliance officers. Secondary validation drew from MAPA feed additive registry filings, ANVISA pharmaceutical oversight bulletins, Mercosur harmonization protocol documents, and Brazilian customs trade data. Bottom-up volume triangulation across phytase, protease, cellulase, and amylase segments reconciled against top-down livestock feed production estimates.
Input-output matrix modeling connected fermentation substrate costs, thermal stability engineering premiums, and regulatory compliance burdens to enzyme concentrate pricing tiers across the projection horizon. Segmentation dimensions included product type, livestock application, delivery mode, and end-user procurement authority. CAGRs were derived from trend extrapolation of MAPA enforcement intensity and soybean meal price volatility impacts on protease substitution economics. Industry-specific forecast inputs incorporated pelleting temperature distribution across Brazilian feed mills and Mercosur registration harmonization probability scenarios.
The model holds under sustained MAPA enforcement of antibiotic growth promoter bans and stable Mercosur trade integration; deviation in SENASA regulatory alignment delays or fermentation input cost spikes would shift volume trajectories. Forecasts reflect assumptions about thermal stability technology diffusion and vertical integration patterns among poultry integrators. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Fish Feed and Shrimp Feed and Additives Market
Agricultural Chemicals
Middle East Feed Binders Market
Agricultural Chemicals
Asia-Pacific Plant Growth Regulators Market
Agricultural Chemicals
China Feed Amino Acids Market
Agricultural Chemicals
Global Carbofuran Market
Agricultural Chemicals
Seed Binders Market
Agricultural Chemicals
Feed Binders Market
Agricultural Chemicals
Triazole Fungicides Market
Agricultural Chemicals
Global Crop Oil Concentrates Market
Agricultural Chemicals
CBD Plant Nutrients Market
Agricultural Chemicals
Feed Antioxidants Market
Agricultural Chemicals
Global Agricultural Disinfectant Market
Agricultural Chemicals
Feed Pigments Market
Agricultural Chemicals
Asia Pacific Fungicide Market
Agricultural Chemicals
Agricultural Grade Zinc Chemicals Market
Agricultural Chemicals
Vietnam Feed Additives Market