
 Powder Packing Machine Market | 2026-2036
Powder Packing Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Powder Packing Machine Market Outlook
Aftermarket service revenue is reconfiguring margin capture across the powder packing machine value chain. Syntegon leverages its global installed base to sustain long-term service contracts. Paxiom Group anchors North American specialty packaging with customized auger-based systems.
A powder packing machine is an industrial filling system engineered to dispense dry particulate materials into pre-formed containers with dosing accuracy typically measured in grams; auger, volumetric, and weighing filler technologies govern dispensation precision for applications spanning food, pharmaceutical, and chemical processing. Fully automatic machines command the dominant share of capital expenditure as labor costs escalate across manufacturing economies. Weighing filler technology leads pharmaceutical applications where milligram-level accuracy determines batch compliance and regulatory acceptance.
FDA validation requirements and EMA Good Manufacturing Practice standards shape machine specifications, forcing manufacturers to integrate audit trails and contamination control into base platform designs. The EU Machinery Directive and CE marking govern European market access, compelling design modifications for cross-border equipment sales. Stakeholders must monitor evolving serialization mandates and sustainability packaging regulations as these frameworks increasingly dictate retrofit cycles and replacement demand.
Market Dynamics
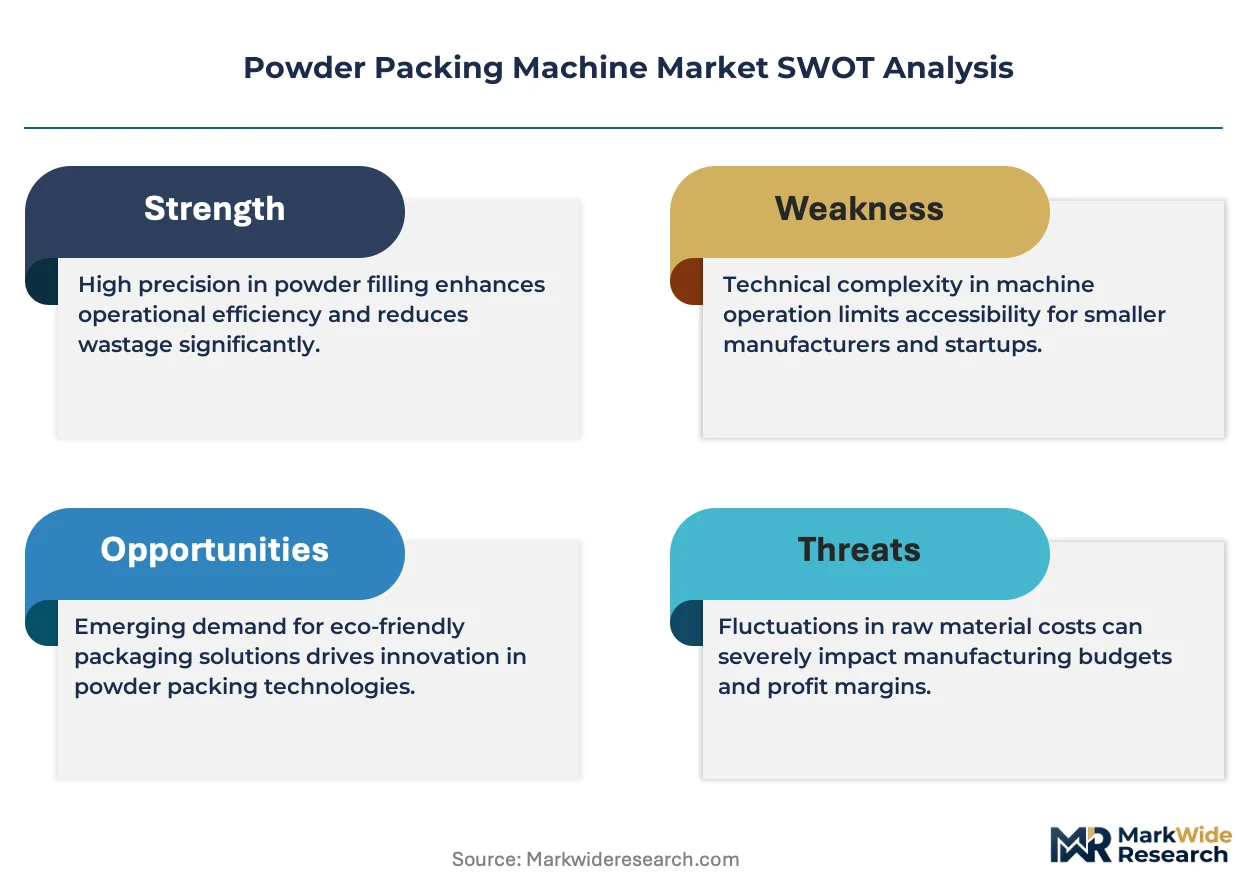
Pharmaceutical serialization mandates and contamination control protocols are forcing machine architecture redesigns across the powder packing value chain. Manufacturers now embed audit trails and closed-loop containment as baseline specifications rather than premium upgrades.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic records and signature requirements drive pharmaceutical manufacturers toward validated filling systems with built-in compliance documentation. Generic drug producers in India and China upgrade legacy lines to meet export standards.
- Aseptic powder processing:Biologics and high-potency APIs demand isolator-integrated packing machines with gloveless robotic interfaces. Contract manufacturers invest in containment-capable platforms to capture CDMO business.
- India PLI scheme:Production-linked incentives for pharmaceutical manufacturing expand domestic machine demand as local generic producers scale capacity for regulated markets.
Market Restraints
- Stainless steel price volatility:Grade 316L sheet and pharmaceutical-grade tubing constitute 35-40% of machine material costs. Mills in China and Indonesia control global supply, creating margin compression for European fabricators.
- Validation timeline friction:EMA Good Manufacturing Practice compliance requires 12-18 month qualification cycles for new installations. Capital deployment delays stretch customer payback periods beyond internal hurdle rates.
- Pre-filled syringe substitution:Liquid dose forms displace powder presentations in vaccine and biologic delivery. Packaging lines for lyophilized powders face demand erosion in high-value therapeutic categories.
Strategic Opportunities
- Saudi Arabia localization:SFDA import substitution policies and domestic pharmaceutical manufacturing targets create demand for compliant powder packing capacity. Joint ventures with local distributors bypass tariff barriers.
- Continuous manufacturing integration:Direct compression-to-packing workflows eliminate intermediate handling. Machine builders partner with process equipment suppliers to offer unified powder-to-package lines.
- EU Green Deal alignment:Sustainable packaging mandates favor recyclable mono-material containers. Auger fillers with quick-change tooling adapt to biodegradable film structures without performance degradation.
Industry Challenges
- Mechatronics talent scarcity:Servo-driven dosing systems and real-time weighing algorithms require cross-trained engineers. Machine builders compete with automotive and semiconductor sectors for control systems specialists.
- Legacy MES integration:Decades-old pharmaceutical manufacturing execution systems lack API compatibility with modern packing machine data architectures. Custom middleware development extends commissioning schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Powder Packing Machine Market |
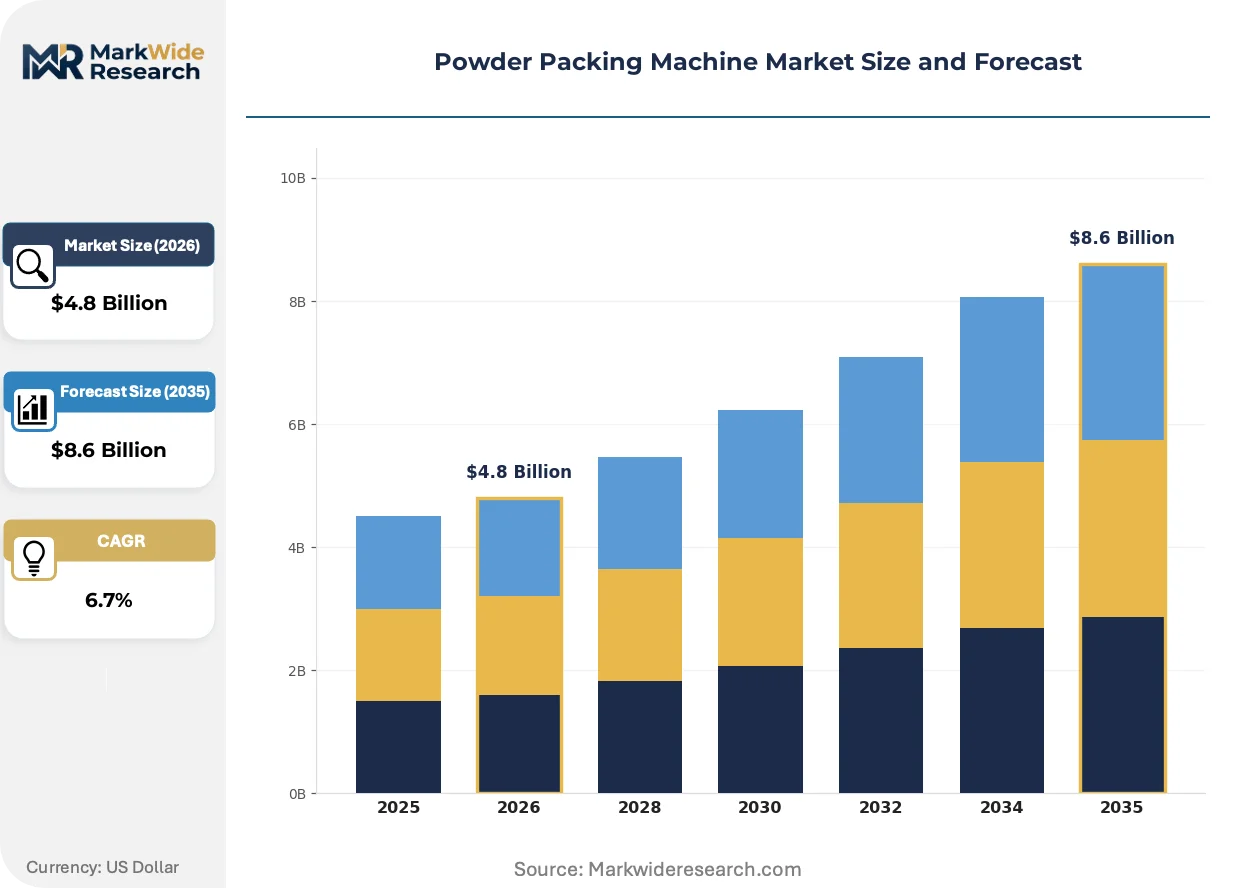
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical Machines, Horizontal Machines, Semi-Automatic Machines, Fully Automatic Machines Technology: Auger Filler, Volumetric Filler, Weighing Filler, Vacuum Filler End User: Food Industry, Pharmaceutical Industry, Chemical Industry, Cosmetics Industry Packaging Type: Bags, Pouches, Boxes, Containers |
| Companies Covered | Syntegon, Rovema, Paxiom Group, Viking Masek, ALLPACK, nVenia, Concetti, Matcon, All-Fill, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Powder Packing Machine Market Strategic Shifts
Machine intelligence and modular platform architectures are compressing development cycles and enabling mass customization at pharmaceutical production scales. Three interconnected developments define current competitive positioning.
Artificial vision systems with deep-learning defect detection are collapsing the trade-off between inspection throughput and false-reject rates. High-speed powder filling lines in oral solid dose manufacturing now operate at 400+ containers per minute with sub-milligram weight verification. Pharmaceutical contract packagers adopt these platforms to reduce manual check-weighing labor and satisfy FDA process analytical technology guidelines.
EMA Medical Device Regulation reclassification of certain drug-device combination products tightens quality management system requirements for packing equipment suppliers. Machine builders must now maintain technical documentation and post-market surveillance comparable to device manufacturers. European pharmaceutical companies prioritize vendors with notified body-certified quality systems, shifting procurement criteria toward regulatory infrastructure rather than unit economics alone.
Aftermarket service unbundling from equipment sales transforms vendor-customer relationships in pharmaceutical packaging. Large generic manufacturers in India negotiate performance-based maintenance contracts with guaranteed uptime thresholds. Service revenue streams now determine long-term account profitability, prompting machine builders to invest in remote diagnostics infrastructure and regional spare parts depots.
Powder Packing Machine Market Segmentation
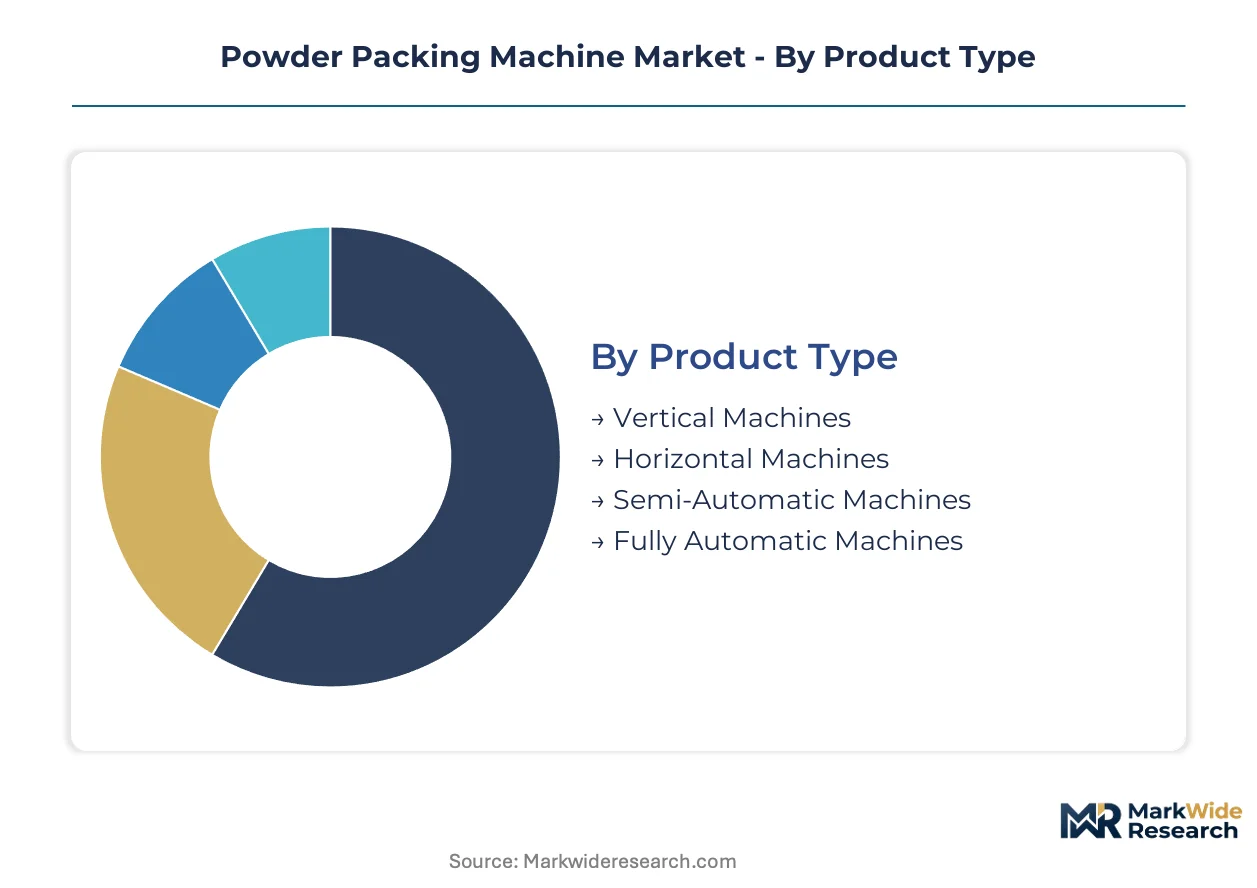
Powder packing machine segmentation reveals how dosing precision requirements, containment standards, and throughput demands fragment procurement patterns across industries. Manufacturers configure platform architectures around specific material characteristics and regulatory exposure rather than pursuing universal designs.
Product Type:
Vertical and horizontal configurations address fundamentally different facility constraints and material flow requirements across food, pharmaceutical, and chemical processing environments.
- Fully Automatic Machines:Integrated servo-driven dosing systems with programmable logic controllers manage 400+ containers per minute with real-time weight feedback. Pharmaceutical contract manufacturers in India deploy these platforms to satisfy FDA validation requirements for generic drug export lines.
- Vertical Machines:Gravity-fed product streams drop through forming collars into continuous film webs, optimizing floor space in high-volume snack and instant beverage packaging. Indian food processors favor these systems for spice and milk powder operations where upstream blending integrates directly with packing.
- Horizontal Machines:Linear indexing conveyors handle pre-formed rigid containers through multiple dosing stations, suiting pharmaceutical vial and jar applications requiring intermittent motion precision.
- Semi-Automatic Machines:Operator-fed container handling with automated dosing heads serves low-volume specialty chemical and cosmetics producers in Germany and Switzerland where batch sizes fluctuate seasonally.
The dominant share belongs to Fully Automatic Machines, while Vertical Machines are closing the gap fastest in emerging market food processing expansions.
Technology:
Cost tier differentiation separates premium precision applications from commodity powder handling where gram-level variance tolerance permits simpler mechanical systems.
- Weighing Filler:Load cell-based gravimetric verification achieves milligram-level accuracy through loss-in-weight or net-weigh architectures. Biologics manufacturers in Switzerland and Massachusetts specify these systems for high-potency API containment where dose deviation triggers batch rejection.
- Auger Filler:Rotating helical screws meter free-flowing and non-free-flowing powders through variable pitch and diameter configurations. Chinese dairy processors deploy auger systems for infant formula packing where density variation demands constant fill volume compensation.
- Volumetric Filler:Piston or cup-based displacement suits coarse granular materials with consistent bulk density, dominating agricultural chemical and detergent powder applications.
- Vacuum Filler:Negative pressure transfer systems handle fragile or aerated powders without compaction, serving specialty food and cosmetic applications where particle integrity determines product quality.
Weighing Filler commands premium positioning in regulated pharmaceutical segments, though Auger Filler is expanding most quickly into mid-tier food and chemical markets seeking precision without gravimetric cost premiums.
End User:
Customer type determines validation burden, containment specification, and aftermarket service intensity across the installed base.
- Pharmaceutical Industry:Isolator-integrated machines with gloveless robotic interfaces satisfy EMA and FDA containment requirements for cytotoxic and hormonal compounds. CDMOs in India and China invest in these platforms to capture outsourced packaging of regulated-market generics.
- Food Industry:Stainless steel construction with IP65 washdown ratings handles dairy, spice, and nutritional powder packing where FSSAI and FDA food safety protocols apply. Indian spice exporters upgrade lines to meet EU allergen labeling and contamination standards.
- Chemical Industry:Explosion-proof electrical enclosures and grounding systems address solvent-laden powder environments, with demand concentrating in German and Chinese specialty chemical manufacturing clusters.
- Cosmetics Industry:Compact tabletop and floor-standing units serve batch production of talc, pigment, and powder foundation products where frequent changeovers demand quick-release tooling.
Pharmaceutical Industry retains the highest equipment value per installed unit, while Food Industry is gaining share fastest through capacity expansions in India and Southeast Asia.
Packaging Type:
Volume and margin profiles vary dramatically across flexible and rigid container formats, with sustainability mandates reshaping material selection criteria.
- Pouches:Form-fill-seal integration with flexible film structures dominates single-serve and retail powder presentations. Indian instant beverage and spice markets drive demand for recyclable mono-material pouches aligned with EU Green Deal packaging requirements.
- Bags:Valve and open-mouth bagging systems handle industrial-scale chemical and food ingredient bulk distribution, with German chemical processors specifying FIBC filling stations for export logistics.
- Containers:Rigid plastic and glass jar filling serves premium cosmetic and pharmaceutical presentations where shelf stability and resealability matter.
- Boxes:Cartoning integration with powder sachet collation addresses pharmaceutical and food variety packs, requiring synchronized line control between primary and secondary packaging.
Pouches command the dominant share in consumer-facing applications, though Bags are climbing the fastest in industrial chemical distribution channel expansions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment fabricators cluster in Germany, China, and the United States where precision engineering capabilities and pharmaceutical manufacturing density create captive demand. Stainless steel supply chains and validation expertise reinforce these concentrations.
United States
Biologics manufacturers in Massachusetts and North Carolina drive isolator-integrated machine procurement for high-potency API containment. FDA 21 CFR Part 11 enforcement tightens electronic records requirements for generic drug exporters. Boston-area CDMOs upgrade legacy filling lines to capture contract packaging of lyophilized biologics.
Germany
Specialty chemical and pharmaceutical producers in Baden-Württemberg specify explosion-proof auger systems for solvent-laden powder environments. EU Machinery Directive compliance costs shape cross-border equipment specifications for export-oriented fabricators. Stuttgart-based machine builders integrate CE-marked control architectures for Middle Eastern pharmaceutical joint ventures.
China
Domestic generic drug scaling under the NMPA regulatory framework accelerates fully automatic line deployment in Jiangsu and Zhejiang provinces. Grade 316L stainless steel price volatility from Indonesian and domestic mills compresses fabricator margins. Yangtze River Delta pharmaceutical clusters demand validated weighing filler systems for regulated-market export compliance.
India
PLI scheme incentives expand domestic machine demand as Mumbai and Hyderabad generic producers scale capacity for US and EU exports. CDSCO validation protocols align with FDA standards for contract packaging lines. Ahmedabad-based equipment distributors partner with European builders for localized assembly and service coverage.
Switzerland
High-potency biologics manufacturing in Basel demands gloveless robotic interfaces with milligram-level dosing precision. Swissmedic quality system requirements exceed EMA baselines for drug-device combination products. Swiss contract manufacturers specify notified body-certified machine builders to satisfy MDR technical documentation mandates.
Powder Packing Machine Market Competitive Environment
Global diversified suppliers and regional specialists split the market across validation-intensive pharmaceutical segments and price-sensitive food processing tiers. Consolidation pressure concentrates among mid-scale European fabricators facing Chinese cost competition. Three archetypes dominate: full-line system integrators with regulatory infrastructure, component specialists with quick-change tooling expertise, and emerging Asian builders with localized service networks. Capacity expansion and strategic partnerships with CDMOs represent the dominant competitive vectors.
Among diversified system integrators, Syntegon anchors the premium tier with global installed base leverage for long-term service contracts. Rovema and Paxiom Group exemplify regional specialization strategies—German precision engineering for European pharmaceutical exports and North American customized auger systems for specialty food applications respectively. These three occupy positions that reflect divergent bets on regulatory complexity versus customization agility.
| Leading Market Players |
|---|
| Syntegon |
| Rovema |
| Paxiom Group |
| Viking Masek |
| ALLPACK |
| nVenia |
| Concetti |
| Matcon |
| All-Fill |
| Others |
Value Chain & Pricing Dynamics
Yangtze River Delta fabricators in Jiangsu and Zhejiang provinces dictate stainless steel input costs for European and Indian machine builders, translating mill pricing power into compressed downstream margins for validated pharmaceutical equipment.
Pricing Analysis
Aftermarket service contracts now generate the majority of lifetime customer value across the powder packing machine installed base. Three-tier pricing structure across premium isolator-integrated, standard automatic, and economy semi-automatic levels separates CDMO-grade containment specifications from food-processing commodity tiers. Cost compression in mid-tier auger systems intensifies because Chinese domestic producers scale validated line output for export markets. Generic drug manufacturers in India exhibit the highest price sensitivity, while Swiss biologics producers prioritize milligram-precision specifications over unit economics.
Supply Chain Analysis
Dual-use technology export controls on precision servo systems and real-time weighing algorithms limit component flows from German and Japanese suppliers to Chinese fabricators. Grade 316L stainless steel sheet, pharmaceutical-grade tubing, and servo-driven dosing modules anchor machine production in Germany, China, and Italy. Single-source vulnerability concentrates in Indonesian nickel supply for corrosion-resistant alloys. Distribution runs through regional equipment distributors with localized validation support capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cross-trained mechatronics engineers capable of integrating servo control with FDA-compliant data architectures remain scarce relative to expanding pharmaceutical automation demand, constraining machine builder expansion velocity.
For Market Incumbents: Insulate service revenue streams by embedding remote diagnostics infrastructure and guaranteed uptime contracts into every new installation. Backward integration into stainless steel component machining reduces exposure to Yangtze River Delta mill pricing volatility. Prioritize CE marking and notified body certification investments to satisfy EMA Medical Device Regulation requirements for drug-device combination products. For New Entrants and Emerging Players: Establish a beachhead in Indian food processing automation where FSSAI compliance requirements lag pharmaceutical validation burdens but capacity expansion accelerates. Target spice and dairy powder segments in Gujarat and Punjab where European equipment costs exceed local budget thresholds. Pursue joint venture structures with Ahmedabad-based distributors for localized assembly and commissioning capabilities. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underoptimized pharmaceutical packaging divisions lacking standalone regulatory infrastructure. Five-to-ten year viability hinges on aftermarket service attach rates rather than equipment shipment volumes. Monitor India PLI scheme disbursement velocity as inflection indicator for domestic capacity expansion demand.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Certification Investment | EMA notified body quality system certification opens European CDMO procurement pipelines. |
| Aftermarket Service Infrastructure Buildout | Regional spare parts depots in Mumbai and Hyderabad capture long-term maintenance contracts. |
| Continuous Manufacturing Partnership | Integration with direct compression process equipment suppliers creates unified powder-to-package offerings. |
| Localization Joint Venture | Saudi SFDA import substitution policies favor domestic assembly partnerships over direct equipment exports. |
| Sustainable Packaging Adaptation | Quick-change auger tooling for recyclable mono-material films aligns with EU Green Deal mandates. |
Study Parameters
A standing panel of pharmaceutical packaging line engineers, CDMO operations directors, stainless steel procurement managers, and aftermarket service heads provided ongoing calibration across primary interview rounds. Secondary validation drew from FDA 483 inspection observations, EMA GMP inspection reports, CDSCO manufacturing license databases, and customs trade flow records for powder processing equipment. Bottom-up equipment shipment tallies and top-down pharmaceutical capital expenditure estimates underwent iterative reconciliation.
Scenario bracketing around regulatory enforcement intensity and stainless steel price volatility shaped demand projections across the analysis window. Segmentation modeling incorporated machine automation level, dosing technology precision tier, end-use industry regulatory exposure, and geographic manufacturing cluster validation requirements. CAGRs derived from equipment replacement cycle analysis and greenfield capacity addition pipelines, with specific inputs from serialization mandate implementation timelines and PLI scheme disbursement schedules.
Sensitivities concentrate around FDA 21 CFR Part 11 enforcement consistency, EMA MDR reclassification scope expansion, and Indonesian nickel export policy shifts. Forecasts reflect documented assumptions regarding generic drug export growth trajectories and contract manufacturing outsourcing rates. Material shifts in biologics dose form preferences toward liquid presentations would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Global Wrapping Machine Market
Packaging Machinery
Multi-Head Filling Machines Market
Packaging Machinery
Plastic Extrusion Equipment Market
Packaging Machinery
Oil Packing Machine Market
Packaging Machinery
Orbital Wrapping Machine Market
Packaging Machinery
Box Filling Machine Market
Packaging Machinery
Wicketed Bagging Machines Market
Packaging Machinery
Plastic Vacuum Forming Machinery Market
Packaging Machinery
Paper Napkins Converting Machines Market
Packaging Machinery
Folder Gluer Machines Market
Packaging Machinery
Poly Bagging Machines Market
Packaging Machinery
Thermal Film Laminating Machines Market
Packaging Machinery
Shrink Label Machine Market
Packaging Machinery
Lipstick Molding Machines Market
Packaging Machinery
Pouch Sealing Machine Market
Packaging Machinery
Wraparound Case Packers Market