
 Tray and Sleeve Packing Machines Market | 2026-2036
Tray and Sleeve Packing Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Tray and Sleeve Packing Machines Market Analytics
Buyer concentration among multinational food processors is rebalancing toward mid-sized regional co-packers seeking flexible automation. Massman Automation Designs LLC leverages its engineering heritage in custom robotic integration to serve this expanding tier. Robert Bosch GmbH sustains broad geographic coverage through its established packaging technology division. Marchesini Group S.p.A. specializes in pharmaceutical-grade sleeve systems that command premium positioning.
Tray and sleeve packing machines mechanically erect corrugated or paperboard sleeves around pre-formed trays, then seal the assembly through hot-melt adhesive, tape, or interlocking tab closure at speeds typically ranging from 30 to 150 cycles per minute for rotary systems. These machines serve primary and secondary packaging functions across food, pharmaceutical, and consumer goods distribution chains. Automatic machines dominate installed base value due to their integration with upstream filling and downstream palletizing lines, while specialty machines capture disproportionate margin pools in pharmaceutical serialization applications. Cardboard packaging material segments benefit from sustainability-driven substitution away from plastic shrink wrapping in European and North American retail supply chains.
The EU F-Gas Regulation and REACH framework constrain adhesive chemistries and pneumatic component specifications, pushing OEMs toward electric servo drives and bio-based hot-melt formulations. FDA cGMP guidelines for pharmaceutical packaging equipment validation shape machine design priorities in US-regulated export markets. Germany's KBA and machinery safety standards influence CE marking pathways that determine market access across European economic area jurisdictions. Stakeholders must weigh capital deployment timing against evolving Extended Producer Responsibility schemes that will alter total cost of ownership calculations for packaging line investments.
Market Dynamics
EU Packaging and Packaging Waste Regulation mandates are compressing plastic-to-paperboard substitution timelines, forcing machinery OEMs to accelerate servo-electric platform development ahead of mechanical pneumatic obsolescence.
Growth Catalysts
- REACH adhesive reformulation:Bio-based hot-melt chemistries are qualifying for CE marking pathways, expanding machine deployability across European economic area jurisdictions.
- Pharmaceutical serialization:Track-and-trace mandates from FDA cGMP and EMA MDR are requiring sleeve systems with integrated vision verification and reject stations.
- German machinery clusters:Stuttgart and Bavaria engineering networks are exporting turnkey lines to Poland and Czech Republic food processors seeking throughput parity with Western European standards.
Market Restraints
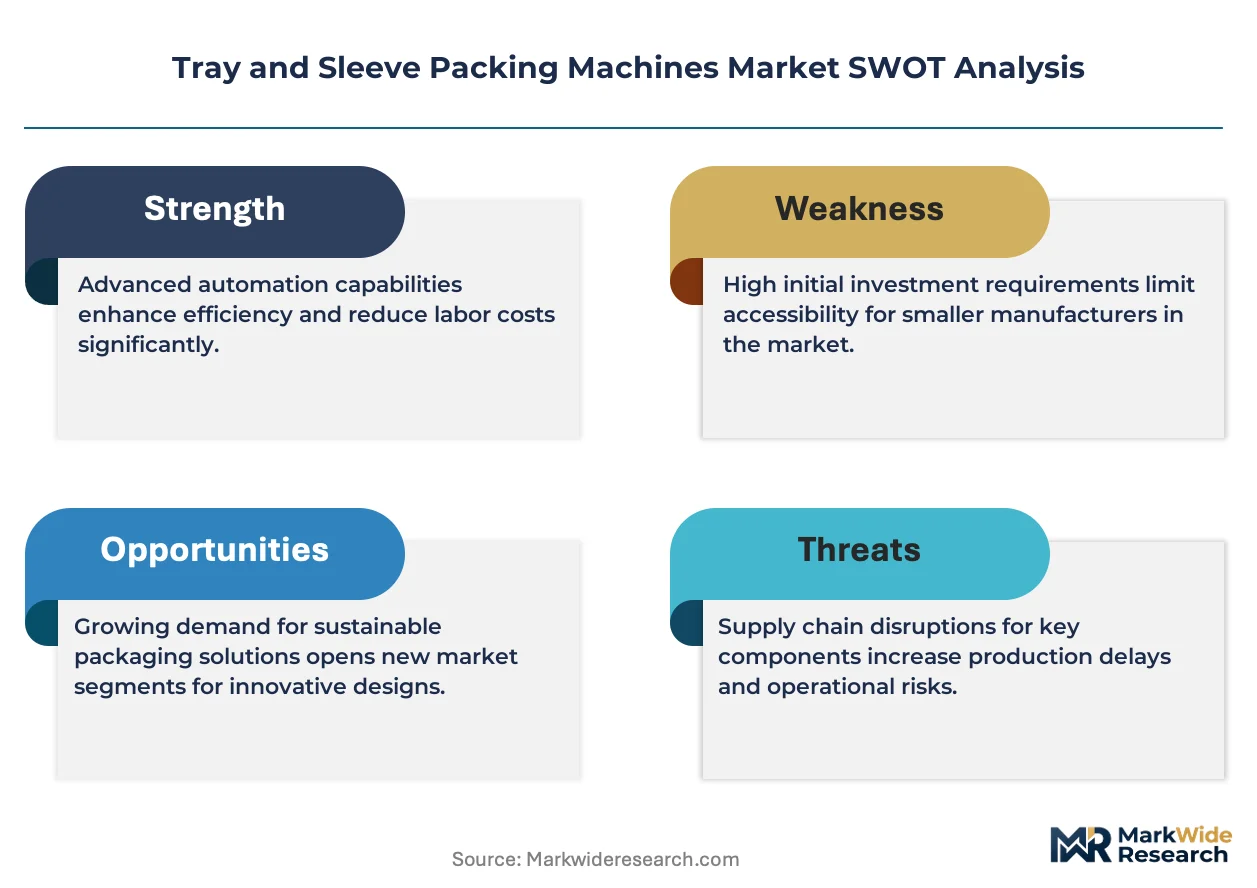
- Stainless steel input volatility:Pharmaceutical-grade 316L enclosures face price swings tied to nickel futures, compressing margin on validated equipment builds.
- Linear actuator supply concentration:Precision ball screw assemblies concentrate among Japanese and German component houses, exposing lead time risk for North American OEMs.
- Shrink film residual demand:High-speed flow wrapping retains cost advantage for moisture-sensitive confectionery, slowing complete sleeve substitution in tropical distribution corridors.
Strategic Opportunities
- Modular retrofit kits:Electric servo drive conversion packages are capturing installed base upgrade spend from mid-sized co-packers avoiding full line replacement.
- India FSSAI compliance windows:Domestic food processors are importing European-designed sleeve systems ahead of anticipated packaging waste rule harmonization.
- Vision-robotics convergence:Collaborative pick-and-place modules integrated with sleeve erectors are enabling mixed-SKU tray loading without mechanical changeover.
Industry Challenges
- Servo tuning expertise gap:Field service organizations struggle to recruit motion control engineers capable of optimizing multi-axis synchronization in rotary sleeve systems.
- Legacy PLC integration friction:Brownfield packaging halls running Siemens S7-300 architectures face protocol translation costs when connecting to modern safety-rated servo drives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tray and Sleeve Packing Machines Market |
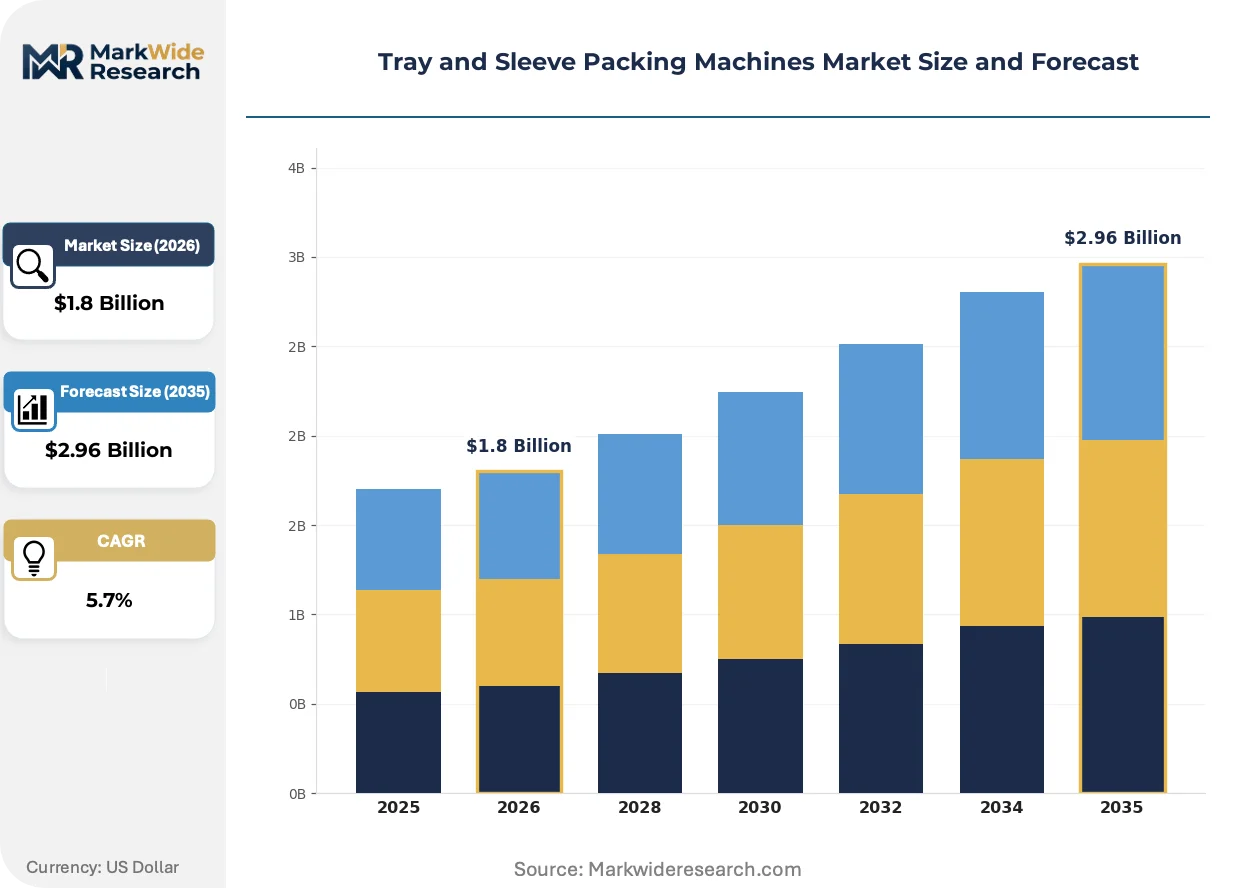
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Machines, Semi-Automatic Machines, Manual Machines, Specialty Machines End User: Food & Beverage, Pharmaceuticals, Consumer Goods, Electronics Packaging Material: Plastic, Cardboard, Composite, Foam Production Capacity: Low Capacity, Medium Capacity, High Capacity, Variable Capacity |
| Companies Covered | BVM Brunner GmbH u. Co. KG, Eastey Enterprises, Massman Automation Designs LLC, A.B. Sealer, Inc., WexxarBel, Robert Bosch GmbH, IMA Group, Marchesini Group S.p.A., Engage Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tray and Sleeve Packing Machines Market Evolving Landscape
Servo-electric actuation is displacing pneumatic power trains across high-speed rotary platforms, compressing energy consumption and maintenance intervals while enabling precise position feedback for quality verification.
Paperboard sleeve forming technology is absorbing advanced creasing and scoring algorithms from folding carton machinery, enabling thinner caliper materials to maintain structural integrity at elevated line speeds. European dairy and ready-meal processors are piloting these systems to meet retailer plastic reduction commitments. The technology is absorbing margin pressure from substrate suppliers by reducing grammage requirements per sleeve.
EU F-Gas Regulation phase-down schedules are accelerating heat pump integration into hot-melt adhesive delivery systems, replacing compressed air heating methods with closed-loop thermal management. German OEMs are certifying these configurations under KBA machinery safety standards for pharmaceutical export eligibility. Cold chain food distributors represent the fastest adoption segment as adhesive open times tighten.
Regional co-packers are consolidating procurement authority previously dispersed across plant engineering teams, centralizing capital equipment decisions with specialized packaging technology buyers. This concentration is compressing vendor evaluation cycles and elevating total cost of ownership analytics over upfront capital metrics. The shift is most visible in Benelux and Nordics markets where private label manufacturing scales dominate.
Tray and Sleeve Packing Machines Market Segmentation
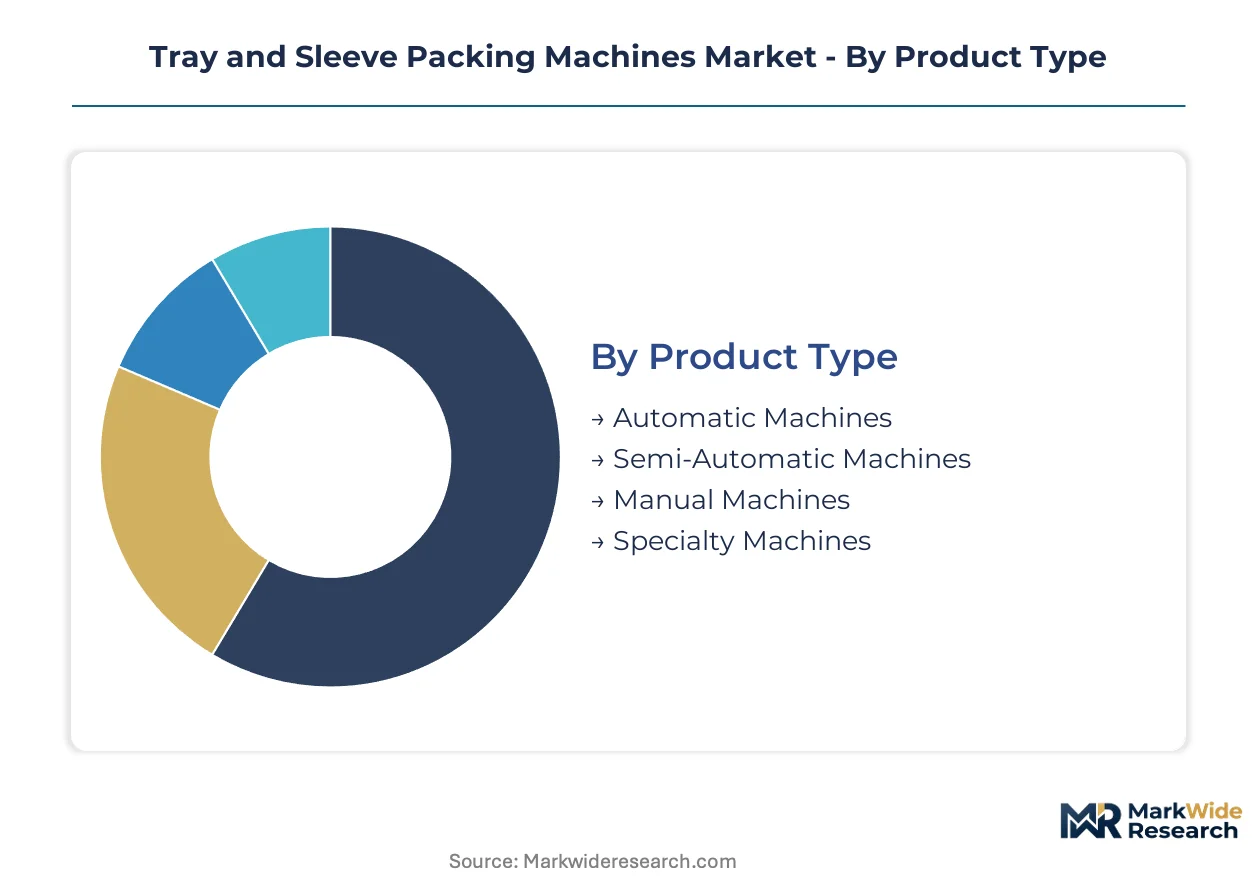
Segmentation reveals how machinery OEMs allocate R&D and field service resources across divergent customer requirements. Equipment specifications vary dramatically between pharmaceutical validation protocols and food-grade washdown environments, creating distinct margin pools and aftermarket revenue streams.
Product Type:
Supply concentration in precision motion control components favors OEMs with captive servo drive engineering capabilities over pneumatic-dependent assemblers.
- Automatic Machines:These systems integrate with upstream filling and downstream palletizing lines through standardized communication protocols. Demand concentrates among German dairy processors expanding into Polish and Czech Republic markets to achieve throughput parity with Western European standards. The EU F-Gas Regulation accelerates servo-electric platform development ahead of pneumatic obsolescence.
- Specialty Machines:Pharmaceutical-grade configurations incorporate vision verification, reject stations, and serialization databases for FDA cGMP and EMA MDR compliance. German OEMs certify these under KBA machinery safety standards for export eligibility to US-regulated markets. Track-and-trace mandates expand the addressable market for validated equipment builds.
- Semi-Automatic Machines:Mid-sized regional co-packers in Benelux and Nordics markets deploy these for flexible SKU handling without full automation capital commitment.
- Manual Machines:Small-batch craft food producers and startup confectionery operations utilize these for low-volume seasonal production runs.
Today's leader: Automatic Machines. Tomorrow's challenger: Specialty Machines.
End User:
Cost tier stratification separates premium-validated pharmaceutical builds from standard food-grade configurations with divergent stainless steel specifications and documentation requirements.
- Food & Beverage:European dairy and ready-meal processors pilot paperboard sleeve systems to meet retailer plastic reduction commitments. Stuttgart and Bavaria engineering networks export turnkey lines to Poland and Czech Republic processors seeking throughput parity with Western European standards. Bio-based hot-melt chemistries qualify for CE marking pathways across European economic area jurisdictions.
- Pharmaceuticals:FDA cGMP guidelines for packaging equipment validation shape machine design priorities in US-regulated export markets. EMA MDR track-and-trace mandates require integrated vision verification and reject stations. Stainless steel 316L enclosures face price volatility tied to nickel futures, compressing margins on validated builds.
- Consumer Goods:Private label manufacturers in Benelux and Nordics markets consolidate procurement authority with specialized packaging technology buyers.
- Electronics:ESD-sensitive component packaging drives demand for ionized air systems and conductive material handling.
Food & Beverage commands current volume. Pharmaceuticals delivers the steepest expansion trajectory.
Packaging Material:
Volume concentration in cardboard applications is accelerating as EU Packaging and Packaging Waste Regulation mandates compress plastic-to-paperboard substitution timelines.
- Cardboard:Advanced creasing and scoring algorithms from folding carton machinery enable thinner caliper materials to maintain structural integrity at elevated line speeds. European dairy and ready-meal processors pilot these systems to meet retailer plastic reduction commitments. Reduced grammage requirements per sleeve absorb margin pressure from substrate suppliers.
- Plastic:Shrink film retains cost advantage for moisture-sensitive confectionery in tropical distribution corridors, slowing complete substitution despite regulatory pressure.
- Composite:Multi-layer barrier structures serve modified atmosphere packaging for premium ready-meal applications requiring extended shelf life.
- Foam:Protective cushioning applications concentrate in electronics and fragile consumer goods distribution.
Cardboard dominates new line investments. Composite materials gain share in premium applications.
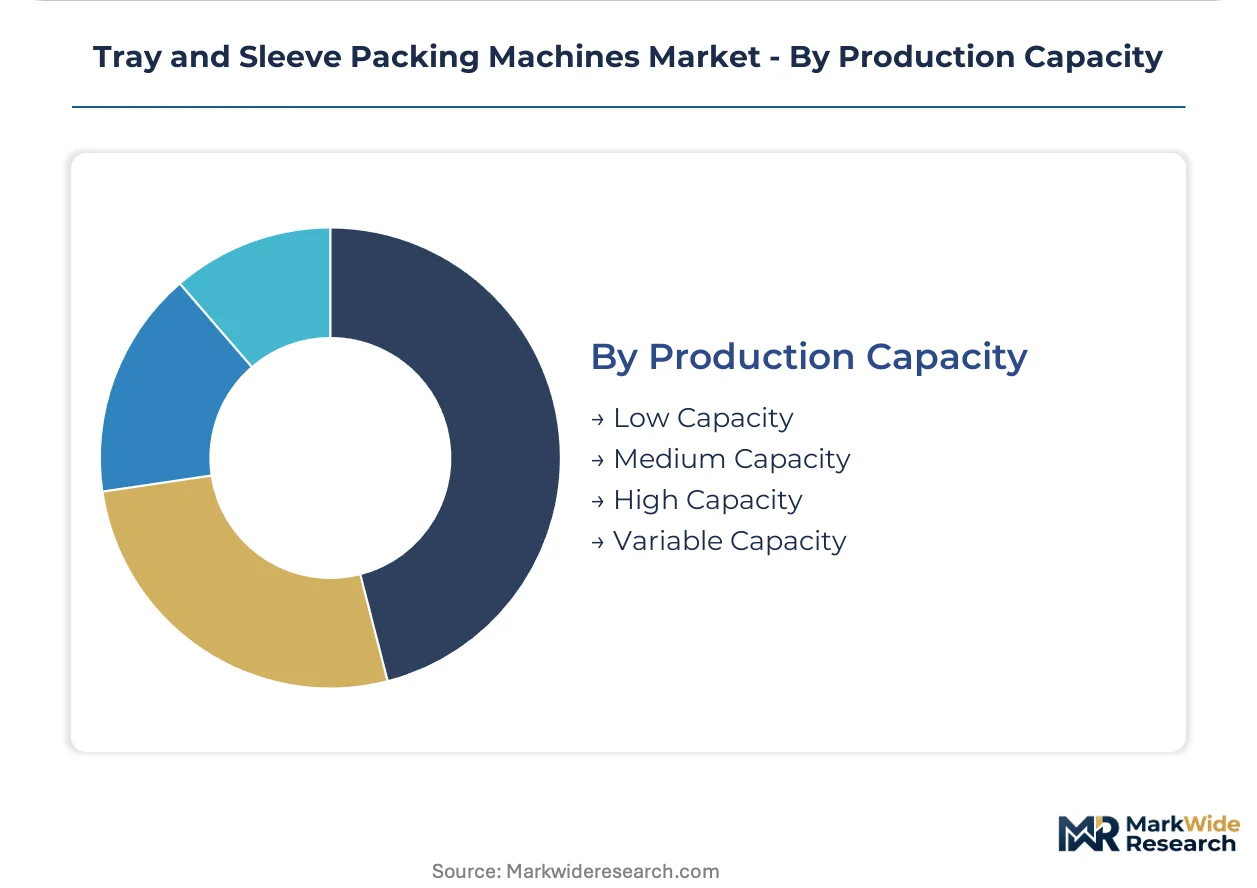
Production Capacity:
Customer type concentration among multinational food processors is rebalancing toward mid-sized regional co-packers seeking flexible automation with modular upgrade paths.
- High Capacity:Rotary systems operating at 30 to 150 cycles per minute serve primary and secondary packaging functions across large-scale food distribution chains. German machinery clusters export these configurations to Poland and Czech Republic processors. Servo-electric actuation displaces pneumatic power trains, compressing energy consumption and maintenance intervals.
- Variable Capacity:Modular retrofit kits with electric servo drive conversion packages capture installed base upgrade spend from mid-sized co-packers avoiding full line replacement. Field service organizations struggle to recruit motion control engineers capable of optimizing multi-axis synchronization.
- Medium Capacity:Regional co-packers in Benelux and Nordics markets standardize on these for private label manufacturing scale.
- Low Capacity:Artisan producers and test market launches utilize these for limited production runs before scale-up commitment.
High Capacity systems anchor current revenue. Variable Capacity configurations are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent clusters in Stuttgart and Bavaria anchor European machinery development, while regional co-packer consolidation in Benelux and Nordics redirects procurement authority toward specialized packaging technology buyers.
Germany
Stuttgart and Bavaria engineering networks export turnkey tray and sleeve packing lines to Poland and Czech Republic food processors seeking throughput parity with Western European standards. KBA machinery safety standards influence CE marking pathways that determine market access across European economic area jurisdictions. German OEMs certify servo-electric configurations with heat pump-integrated adhesive systems for pharmaceutical export eligibility.
United States
FDA cGMP guidelines for pharmaceutical packaging equipment validation shape machine design priorities in US-regulated export markets. Track-and-trace mandates from FDA cGMP require sleeve systems with integrated vision verification and reject stations. Regional co-packer consolidation concentrates procurement authority with specialized packaging technology buyers in Midwest dairy processing corridors.
India
Domestic food processors import European-designed sleeve systems ahead of anticipated packaging waste rule harmonization under FSSAI compliance windows. The country's national food safety regulator is tightening packaging material recovery requirements that will alter total cost of ownership calculations for packaging line investments. Engineering talent shortages in motion control specialization constrain field service deployment for multi-axis rotary systems.
Poland
Food and beverage processors expand automated packaging lines to meet throughput targets aligned with Western European retail supply chain standards. EU Packaging and Packaging Waste Regulation mandates compress plastic-to-paperboard substitution timelines for dairy and ready-meal exporters. German machinery clusters serve Polish processors through turnkey line integration with upstream filling and downstream palletizing systems.
China
Domestic packaging machinery fabricators absorb advanced creasing and scoring algorithms from European folding carton technology to enable thinner caliper materials at elevated line speeds. The country's national standards administration is tightening machinery safety specifications that influence export eligibility for pharmaceutical-grade configurations. Yangtze River Delta manufacturing bases concentrate servo drive component assembly for regional OEM supply chains.
Tray and Sleeve Packing Machines Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Consolidation pressures concentrate among mid-sized regional co-packers consolidating procurement authority previously dispersed across plant engineering teams. Three strategic archetypes dominate: diversified industrial technology groups with captive packaging divisions, pure-play automation specialists with custom robotic integration heritage, and pharmaceutical-grade system validators with serialization compliance expertise. Competitive moves center on modular retrofit kit development for installed base upgrades and geographic expansion through German engineering cluster networks into Central European food processing markets.
Among Germany-based diversified industrial groups, Robert Bosch GmbH occupies a position exemplifying broad geographic coverage through established packaging technology divisions. Massman Automation Designs LLC represents the pure-play specialist archetype, leveraging engineering heritage in custom robotic integration to serve expanding mid-sized co-packer tiers. Marchesini Group S.p.A. anchors the pharmaceutical-grade validator segment, commanding premium positioning through specialized sleeve systems with integrated compliance architectures.
| Leading Market Players |
|---|
| BVM Brunner GmbH u. Co. KG |
| Eastey Enterprises |
| Massman Automation Designs LLC |
| A.B. Sealer, Inc. |
| WexxarBel |
| Robert Bosch GmbH |
| IMA Group |
| Marchesini Group S.p.A. |
| Engage Technologies |
| Others |
Value Network & Pricing Analysis
Stainless steel 316L input costs cascade from nickel futures volatility through pharmaceutical-grade machine enclosures, compressing margins on validated builds while forcing tiered pricing stratification between food-grade and pharmaceutical configurations.
Pricing Analysis
Equipment-plus-service bundling separates premium pharmaceutical validators from unbundled food-grade vendors. Pricing stratifies across premium, standard, and economy tiers based on FDA cGMP certification level and after-sales field service coverage. Cost compression in standard food-grade segments intensifies because mid-sized co-packers centralize procurement authority and elevate total cost of ownership analytics. Regional co-packers in Benelux and Nordics markets exhibit highest price sensitivity; pharmaceutical exporters to US-regulated markets demonstrate lowest sensitivity due to compliance-driven specification rigidity.
Supply Chain Analysis
CE marking and KBA machinery safety certification requirements gate component sourcing for European economic area market access. Precision ball screw assemblies concentrate among Japanese and German component houses, while servo drive engineering capabilities anchor in Stuttgart and Bavaria clusters. Raw material dependencies span nickel for stainless steel enclosures, bio-based hot-melt adhesive formulations, and specialized corrugated substrates. Single-source vulnerability in linear actuator supply exposes North American OEMs to lead time risk. Distribution runs through German engineering networks exporting turnkey lines to Poland and Czech Republic processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Pharmaceutical serialization mandates and EU F-Gas Regulation compliance windows are concentrating procurement authority with buyers seeking validated, servo-electric platforms over pneumatic legacy systems.
For Market Incumbents: Acquire motion control engineering talent pools to address field service recruitment gaps. Incumbents should deepen backward integration into servo drive component supply and expand pharmaceutical-grade certification capacity ahead of EMA MDR enforcement waves. These moves counter emerging pure-play automation specialists capturing mid-sized co-packer upgrade spend through modular retrofit kits.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in pharmaceutical-grade sleeve systems offers white-space entry. New entrants should target India's FSSAI compliance window ahead of packaging waste rule harmonization, deploying European-designed sleeve systems through local integration partnerships. A rental-plus-service subscription model reduces capital barrier for domestic food processors.
For Investors and Strategic Acquirers: Consolidation pressure builds where mid-sized regional co-packers centralize procurement authority previously dispersed across plant engineering teams. The five-to-ten year viability window favors pure-play automation specialists with captive robotic integration capabilities over diversified conglomerates with packaging divisions. Watch for inflection when German machinery clusters report order book acceleration into Polish and Czech Republic markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Servo-Electric Platform Migration | F-Gas Regulation compliance secures CE marking pathways across European economic area jurisdictions. |
| Pharmaceutical Serialization Integration | FDA cGMP and EMA MDR track-and-trace mandates expand validated equipment addressable market. |
| Modular Retrofit Kit Development | Electric servo conversion packages capture installed base upgrade spend from co-packers avoiding full replacement. |
| German Engineering Cluster Expansion | Stuttgart and Bavaria networks export turnkey lines to Poland and Czech Republic food processors. |
| Bio-Based Hot-Melt Formulation Partnership | REACH-compliant adhesive chemistries qualify machines for EU market deployability. |
Research Methodology
Multiple input streams — machinery OEM technical documentation, regulatory filing databases, and trade flow records — were reconciled across primary interviews with packaging line engineers, aftermarket service directors, and pharmaceutical validation specialists. Secondary validation drew from KBA machinery safety standards documentation, EU F-Gas Regulation implementation guidance, FDA cGMP equipment validation guidelines, and SEC filings of diversified industrial technology groups. Bottom-up equipment shipment analysis and top-down end-use demand modeling were triangulated to establish market sizing.
Data-stream reconciliation anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include machine automation level, end-use industry vertical, packaging material substrate, and production capacity tier. CAGRs were derived from regression analysis of historical equipment replacement cycles and forward projection of regulatory compliance windows. Industry-specific forecast inputs incorporated nickel futures price trajectory impacts on stainless steel enclosure costs and pharmaceutical serialization mandate implementation timelines.
The model assumes a particular technology adoption path; alternative pathways for pneumatic-to-servo-electric conversion speed would alter the outlook. Forecasts reflect assumptions regarding EU Packaging and Packaging Waste Regulation enforcement consistency and REACH adhesive reformulation qualification rates. A model refresh is warranted upon material change in German machinery cluster export order trends or FSSAI packaging waste rule harmonization announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Cosmetic Packaging Machinery Market
Packaging Machinery
Puffer Machines Market
Packaging Machinery
Air Cushion Machine Market
Packaging Machinery
Paper Embossing Machine Market
Packaging Machinery
Corrugated Paper Machine Market
Packaging Machinery
Folding Gluing Machines Market
Packaging Machinery
Plastic Blow Molding Machine Market
Packaging Machinery
Carton Erecting Machinery Market
Packaging Machinery
Oral Dosage Powder Packaging Machines Market
Packaging Machinery
Flow Pack Machine Market
Packaging Machinery
Hardgel Liquid Capsule Filling Machines Market
Packaging Machinery
Package Closing Machines Market
Packaging Machinery
Palletizing Machines Market
Packaging Machinery
Multi-Head Filling Machines Market
Packaging Machinery
Straw Machine Market
Packaging Machinery
Blind Box Machine Market