
 Tray Former Machines Market | 2026-2036
Tray Former Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Tray Former Machines Market Outlook
China is tilting its packaging machinery output toward higher-speed tray forming systems for export markets. Wayne Automation leverages its North American installed base to sustain aftermarket service revenue across beverage and food accounts. Wexxar Packaging anchors its position through specialized corrugated tray handling expertise in the Pacific Northwest manufacturing corridor. Bosch Packaging Technology competes on servo-driven precision across pharmaceutical clean-room specifications.
Tray former machines are electromechanical systems that erect flat corrugated or paperboard blanks into rigid trays through sequential folding, gluing, or locking operations, typically operating at speeds from 15 to 60 trays per minute depending on blank complexity and automation level. These systems serve primary and secondary packaging lines where product containment, shelf-ready display, and supply chain stacking strength are required. Fully automatic configurations dominate volume deployments in high-throughput food packaging plants where labor minimization drives capital allocation, while electric servo technology captures margin pools through precision motion control and reduced compressed air dependency. Compact machine footprints are gaining traction in electronics contract manufacturing where cleanroom floor space commands premium lease rates.
The FDA enforces sanitary design standards for tray forming equipment deployed in food contact zones, while OSHA machine guarding regulations govern operator access points on automatic lines. The EU Machinery Directive and CE marking requirements shape export compliance costs for North American and Asian OEMs selling into European food packaging networks. Stakeholders must weigh servo electrification investments against pneumatic infrastructure sunk costs as energy pricing volatility redraws total cost of ownership curves.
Market Dynamics
Electric servo electrification is compressing total cost of ownership curves against legacy pneumatic infrastructure, forcing capital allocation decisions across food packaging networks as energy pricing volatility redraws operating economics.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:The directive mandates reduced energy intensity in converting operations, pushing machinery buyers toward electric servo tray formers that eliminate compressed air dependency and cut power consumption.
- Food packaging automation:North American processors are expanding automated tray forming lines to minimize labor exposure in high-throughput environments where wage pressure and workforce availability constrain manual operations.
- German industrial automation clustering:Machinery OEM concentration around Stuttgart and Munich industrial corridors creates supplier density that accelerates R&D spillover and shortens equipment commissioning cycles.
Market Restraints
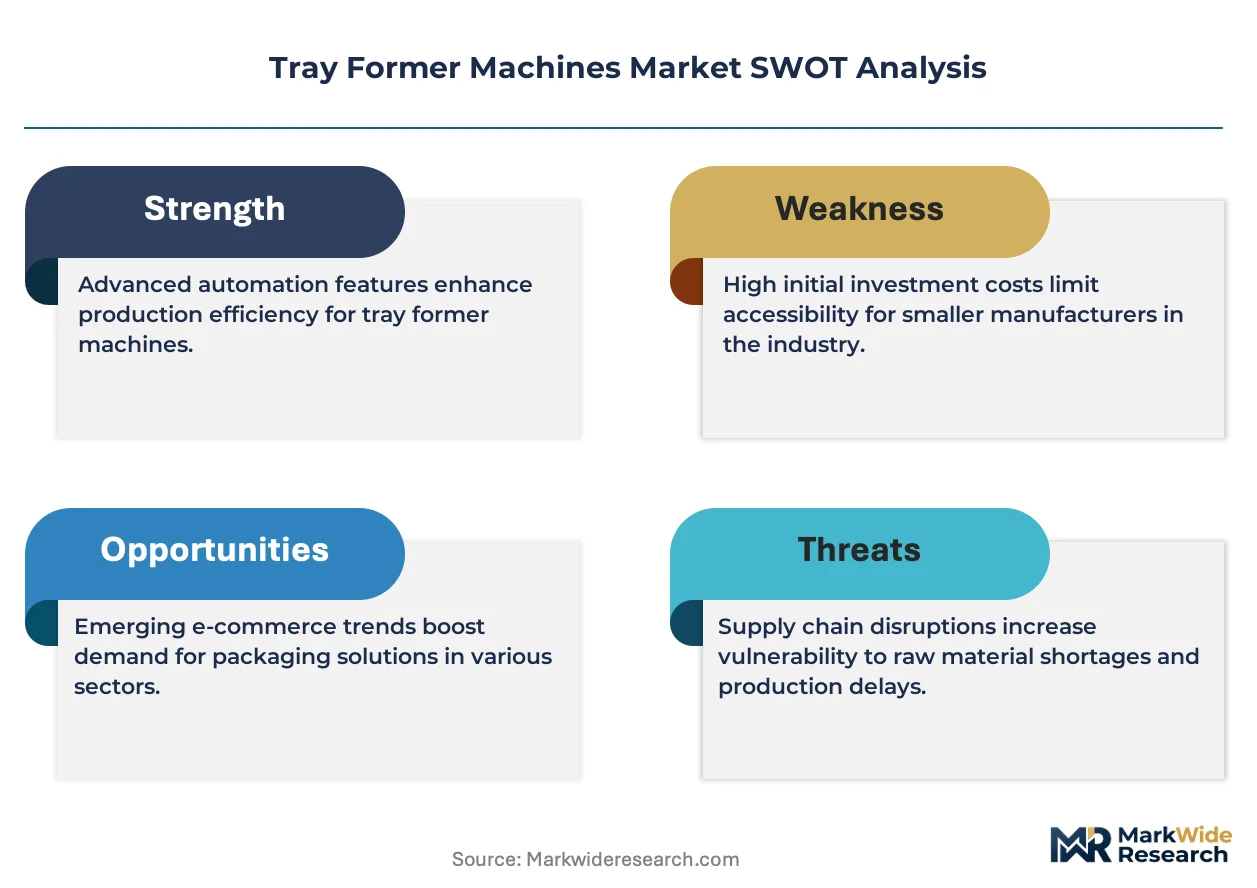
- Pneumatic infrastructure sunk costs:Plants with existing compressed air systems face stranded asset risk when evaluating servo electrification, creating retrofit friction that slows replacement cycles.
- Steel and aluminum input volatility:Frame fabrication and precision motion components depend on commodity metals whose price swings compress OEM margins and destabilize project quoting.
- Corrugated substrate specification fragmentation:Regional variations in flute profiles and recycled content ratios force machine builders to maintain multiple tooling configurations, inflating engineering overhead.
Strategic Opportunities
- Electronics contract manufacturing cleanrooms:Compact footprint tray formers address premium floor space constraints in semiconductor and consumer electronics packaging operations where lease rates per square meter exceed food plant benchmarks.
- Pharmaceutical serialization integration:Converging track-and-trace requirements with tray forming operations creates demand for servo-precision systems that maintain registration accuracy through variable-speed production.
- India food processing modernization:Cold chain expansion and organized retail growth in processed foods generates first-time automation demand where semi-automatic tray formers bridge manual and fully automatic configurations.
Industry Challenges
- Motion control engineering scarcity:Servo system programming and tuning expertise concentrates among automation specialists, forcing machinery OEMs to compete for talent against robotics and semiconductor equipment sectors.
- FDA sanitary design validation timelines:Food contact zone equipment must demonstrate cleanability under 21 CFR standards, extending certification cycles and delaying revenue recognition on custom builds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tray Former Machines Market |
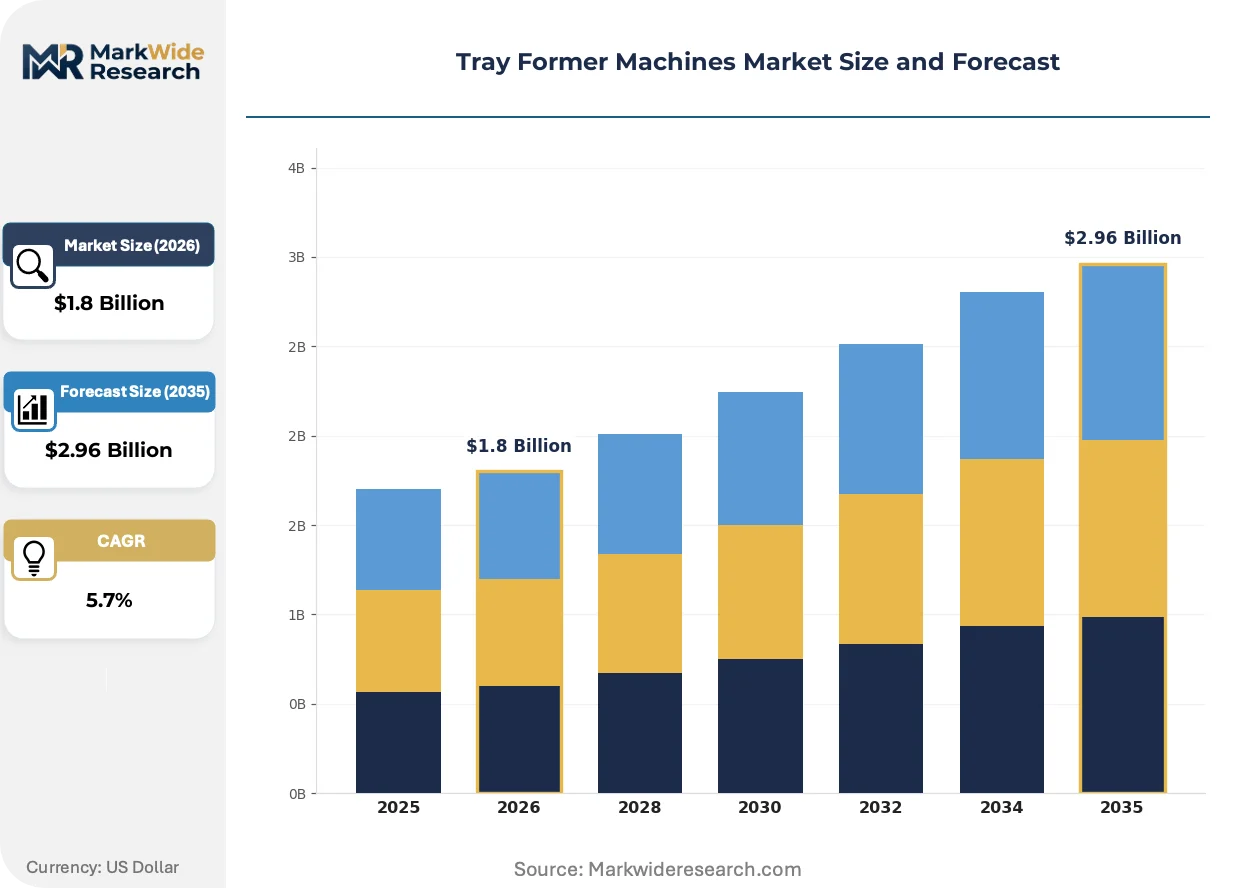
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fully Automatic, Semi-Automatic, Manual, Customizable Technology: Pneumatic, Hydraulic, Electric, Servo End User: Food Packaging, Electronics, Cosmetics, Pharmaceuticals Size: Compact, Standard, Large, Industrial |
| Companies Covered | Wayne Automation, Wexxar Packaging, AFA Systems, ADCO Manufacturing, Combi Packaging Systems, DS Smith, Bosch Packaging Technology, Douglas Machine, Boix Maquinaria, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tray Former Machines Market Strategic Shifts
Digital thread integration across design, production, and service phases is compressing equipment lifecycle economics and reshaping how tray former performance is contracted and measured.
Industrial IoT sensor arrays embedded in forming heads and glue stations are digitizing predictive maintenance workflows. Pharmaceutical packaging operations in Switzerland and Germany are deploying these systems fastest, using vibration and temperature telemetry to schedule interventions before registration drift degrades output quality.
The EU Machinery Directive's updated safety integrity requirements are mandating redundant guarding and programmable safety controllers on automatic lines. Exporters from China and North America face elevated compliance engineering costs to achieve CE marking, with smaller OEMs outsourcing certification to specialized notified bodies in Italy and the Netherlands.
Buyer preference is migrating toward performance-based service agreements where uptime guarantees replace traditional break-fix contracts. Beverage bottlers in the US Pacific Northwest are leading this shift, unbundling aftermarket service from initial capital procurement and paying per thousand trays formed rather than per maintenance visit.
Tray Former Machines Market Segmentation
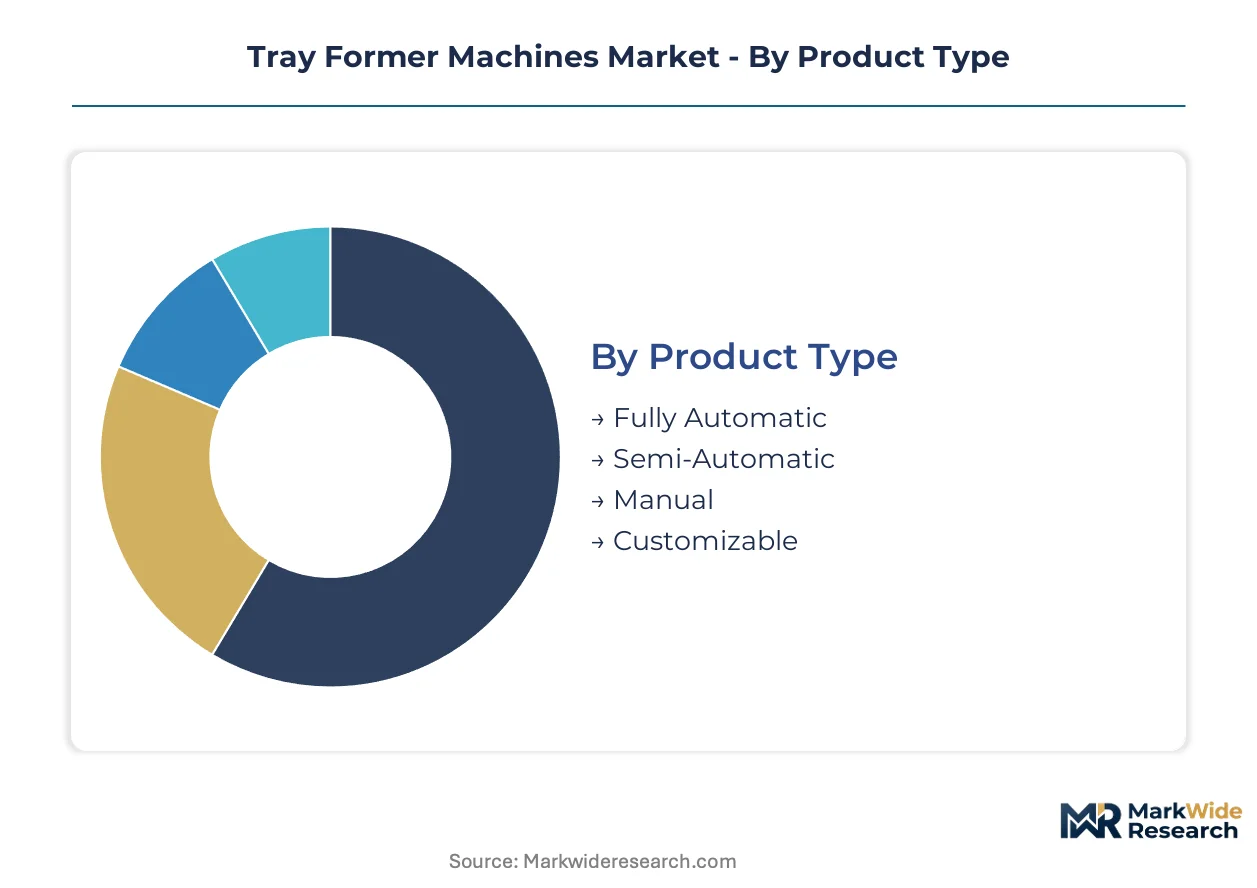
Tray former machine segmentation reflects divergent capital deployment strategies across food packaging networks, electronics contract manufacturers, and pharmaceutical cleanrooms. Equipment specification varies sharply by automation level, energy infrastructure, and floor space economics, creating distinct margin pools for OEMs.
Product Type:
Automation intensity separates volume deployments from specialized configurations, with labor cost arithmetic and throughput requirements driving capital allocation decisions.
- Fully Automatic:These systems execute blank feeding, erecting, and discharge without operator intervention, typically achieving 45-60 trays per minute on standard corrugated formats. Demand concentrates in US Midwest dairy and protein processing plants where OSHA machine guarding regulations and wage pressure accelerate replacement of semi-automatic lines.
- Semi-Automatic:Operator-fed configurations bridge manual and automatic operations at 15-30 trays per minute, requiring periodic loading of blank magazines. Electronics contract manufacturers in Mexico's Baja California corridor deploy these for pilot production runs where volume uncertainty delays full automation commitments.
- Manual:Foot-pedal or hand-lever actuated units serve micro-breweries and artisan food producers with batch sizes below 500 units daily. German craft bakery cooperatives maintain this installed base where product variety exceeds mechanical changeover feasibility.
- Customizable:Modular frame architectures accommodate non-standard tray dimensions, multi-material blanks, and integrated labeling stations. Swiss pharmaceutical packaging specialists specify these for serialization-ready configurations that merge tray forming with track-and-trace compliance.
Fully automatic systems hold installed capacity. Customizable configurations are rotating up the share rankings.
Technology:
Actuation method determines energy intensity, precision tolerances, and total cost of ownership curves across regulatory jurisdictions with divergent electricity and compressed air pricing.
- Electric:Motor-driven cam and linkage mechanisms eliminate pneumatic infrastructure dependency, reducing energy consumption. India's Food Safety and Standards Authority of India (FSSAI) sanitary design mandates are pushing domestic dairy processors toward electric actuation to simplify clean-in-place protocols.
- Servo:Closed-loop motion control enables programmable acceleration curves and registration accuracy within ±0.5mm, critical for pharmaceutical serialization integration. EU Packaging and Packaging Waste Regulation compliance costs are accelerating servo adoption in German and French converting operations where energy audits factor into capital approval workflows.
- Pneumatic:Compressed air cylinders and rotary actuators dominate legacy installed bases, particularly in US Southeast poultry processing plants with existing compressor infrastructure. Stranded asset risk slows replacement cycles despite servo electrification economics.
- Hydraulic:High-force actuation for heavy-gauge corrugated and triple-wall applications in industrial appliance packaging. Japanese automotive parts logistics hubs in Aichi Prefecture specify hydraulic forming heads for returnable tray systems handling powertrain components.
Pneumatic systems retain legacy share dominance. Servo technology is climbing the fastest as energy pricing volatility redraws operating economics.
End User:
Application-specific requirements for sanitary design, cleanroom compatibility, and serialization integration fragment demand patterns across verticals.
- Food Packaging:FDA 21 CFR compliant stainless steel construction, sloped surfaces for drainage, and tool-free disassembly for allergen changeovers. US Pacific Northwest seafood processors specify washdown-rated enclosures for brine exposure environments.
- Electronics:ESD-safe materials, compact footprints for premium cleanroom lease rates, and vibration isolation for semiconductor wafer tray handling. South Korea's Gyeonggi-do semiconductor packaging cluster drives specification for sub-2-meter machine widths.
- Pharmaceuticals:cGMP validation documentation, redundant safety controllers for CE marking under EU Machinery Directive, and integration with aggregation stations for serial number hierarchy. Swissmedic inspection protocols shape equipment qualification timelines for Basel-area packaging operations.
- Cosmetics:Premium finish requirements, quick-change tooling for seasonal SKU proliferation, and shelf-ready display tray formats. French luxury goods contract manufacturers in Normandy prioritize changeover speed over absolute throughput.
Food packaging anchors volume demand. Electronics applications are gaining share fastest as contract manufacturing cleanroom expansion accelerates.
Size:
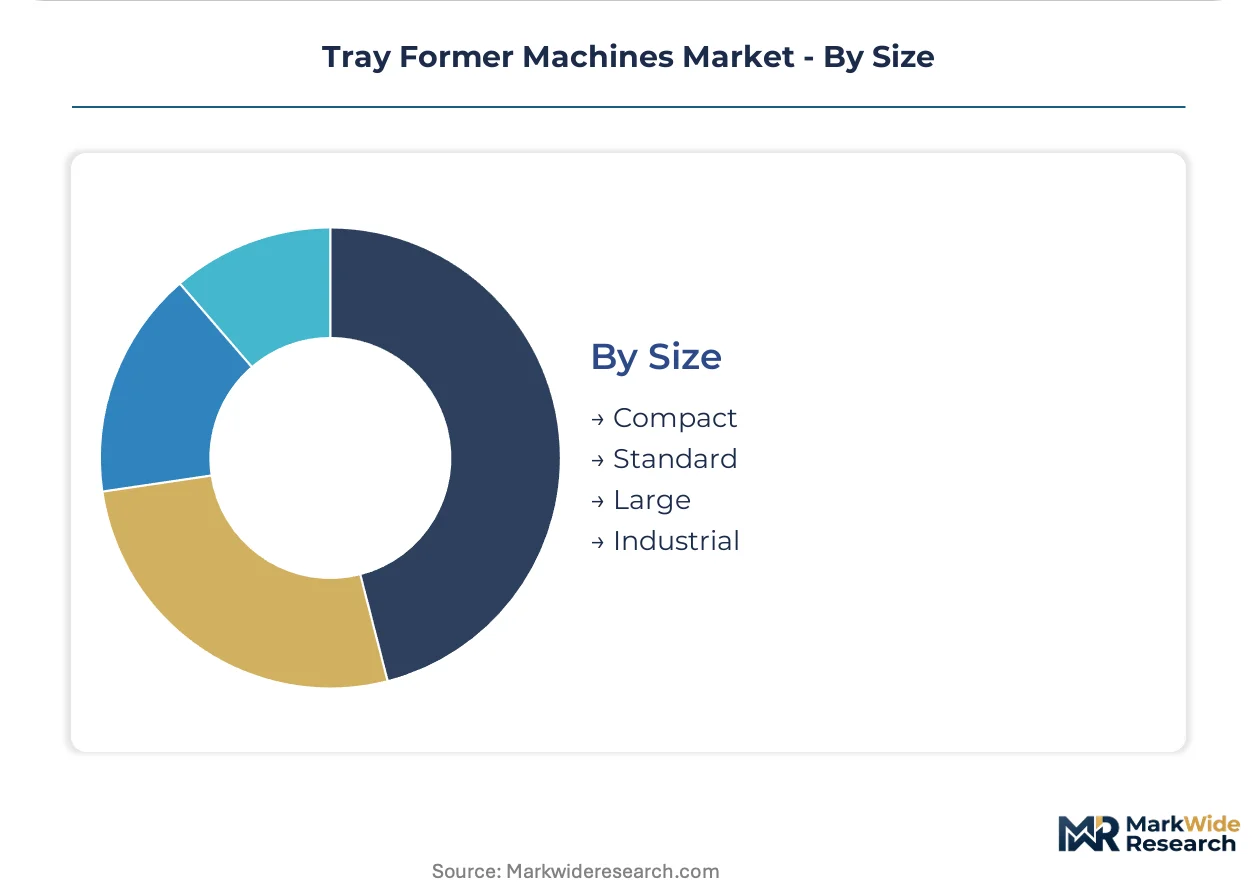
Footprint constraints and throughput requirements create distinct specification bands from benchtop units to integrated production line centers.
- Compact:Sub-1.5 meter widths for electronics cleanrooms and urban food production facilities where lease rates per square meter exceed industrial park benchmarks. Singapore precision engineering parks specify these for vertical integration of packaging operations within multi-story manufacturing facilities.
- Standard:Mid-range footprints accommodating 20-40 tray per minute outputs on single-operator supervision. Brazilian meatpacking operations in São Paulo state deploy these for export carton preparation where labor availability constrains fully automatic deployment.
- Large:Extended magazine capacities and dual forming stations for 24-hour continuous operation in high-volume beverage distribution. Australian wine export consolidation facilities in Adelaide specify these for mixed-SKU palletization upstream of container loading.
- Industrial:Integrated line centers merging tray forming, loading, and palletizing with centralized HMI control. German automotive battery gigafactories in Thuringia deploy these for heavy-format EV module shipping containers.
Standard sizes hold installed capacity. Compact configurations are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA sanitary design standards anchor machinery procurement in the United States, while EU Machinery Directive compliance costs reshape competitive positioning across European converting operations. Regional demand patterns diverge sharply based on energy infrastructure, labor economics, and regulatory enforcement intensity.
United States
OSHA machine guarding regulations and wage pressure in Midwest dairy processing drive replacement of semi-automatic lines with fully automatic configurations. The FDA enforces 21 CFR cleanability standards for food contact zone equipment, extending validation timelines for custom builds. Pacific Northwest seafood processors around Seattle specify washdown-rated enclosures for brine exposure environments.
Germany
The EU Packaging and Packaging Waste Regulation accelerates electric servo adoption by mandating reduced energy intensity in converting operations. Machinery OEM concentration around Stuttgart and Munich industrial corridors creates supplier density that shortens equipment commissioning cycles. Bavarian automotive battery gigafactories deploy industrial-scale integrated line centers for heavy-format EV module shipping containers.
China
GB standards and MIIT industrial automation directives tilt domestic packaging machinery output toward higher-speed tray forming systems for export markets. Yangtze River Delta manufacturers cluster around Shanghai to serve electronics contract manufacturing cleanroom expansion. Zhejiang and Jiangsu provinces concentrate servo motion control R&D spillover from adjacent robotics sectors.
India
FSSAI sanitary design mandates push domestic dairy processors toward electric actuation to simplify clean-in-place protocols. Cold chain expansion and organized retail growth in processed foods generates first-time automation demand where semi-automatic configurations bridge manual operations. Maharashtra and Gujarat food processing corridors drive specification for compact footprint equipment in premium urban lease environments.
Japan
METI energy efficiency guidelines and JIS standards shape precision motion control requirements for pharmaceutical serialization integration. Aichi Prefecture automotive parts logistics hubs specify hydraulic forming heads for returnable tray systems handling powertrain components. Kansai region semiconductor packaging operations demand sub-2-meter machine widths for cleanroom floor space optimization.
Tray Former Machines Market Competitive Environment
Full-line automation specialists and regional fabrication houses split the market into technology-tiered competitive bands. Consolidation pressure concentrates among mid-scale OEMs facing servo engineering talent scarcity and certification cost inflation. Three archetypes dominate: North American aftermarket-anchored incumbents, European precision-motion engineering houses, and Asia-Pacific volume-export fabricators. Dominant competitive moves include geographic expansion through distributor partnerships and portfolio diversification into adjacent case packing equipment.
Within the North American installed-base tier, Wayne Automation and Wexxar Packaging occupy positions sustained by aftermarket service revenue concentration across beverage and food accounts. Bosch Packaging Technology exemplifies the European precision-motion archetype, competing on servo-driven registration accuracy for pharmaceutical clean-room specifications. These three companies represent the strategic positioning spectrum from regional service density to cross-sector technology licensing.
| Leading Market Players |
|---|
| Wayne Automation |
| Wexxar Packaging |
| AFA Systems |
| ADCO Manufacturing |
| Combi Packaging Systems |
| DS Smith |
| Bosch Packaging Technology |
| Douglas Machine |
| Boix Maquinaria |
| Others |
Value Chain & Pricing Dynamics
Tariff exposure on Chinese servo drives and motion controllers determines both pricing tier spreads and supply chain shape across tray former OEM portfolios, compressing margins on economy configurations while forcing premium-tier buyers toward European-sourced electromechanical components.
Pricing Analysis
Price spreads between German-engineered servo systems and Chinese pneumatic alternatives exceed three-to-one across comparable throughput specifications. Pricing stratifies across premium, standard, and economy tiers based on CE marking validation depth and aftermarket service bundling intensity. Cost compression in economy pneumatic configurations is intensifying because Southeast Asian fabricators are flooding export markets with stripped-down electromechanical alternatives. Food packaging conglomerates exhibit lowest price sensitivity due to FDA validation timelines that lock in supplier relationships, while electronics contract manufacturers in Mexico's Baja California corridor negotiate aggressively on capital equipment leases.
Supply Chain Analysis
Steel and aluminum feedstock sourcing concentrates in China, Germany, and Japan for precision-machined frame components and servo motor housings. Motion control electronics draw from Taiwan semiconductor foundries and South Korean memory suppliers, creating single-source vulnerability on encoder chips and drive controllers. Distribution runs through authorized OEM service networks in food processing corridors rather than third-party industrial distributors, preserving margin capture on spare parts and commissioning support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aftermarket service contracts and predictive maintenance telemetry subscriptions are expanding faster than hardware shipments, converting capital equipment vendors into recurring-revenue platforms anchored by uptime guarantee pricing.
For Market Incumbents: Harden installed-base retention through captive spare parts logistics and remote diagnostics infrastructure that raises switching costs for food packaging accounts facing FDA revalidation friction. Consolidate regional service density in US Midwest dairy corridors where Wayne Automation and Wexxar Packaging already anchor maintenance relationships, blocking emerging entrants from securing initial reference installations. For New Entrants and Emerging Players: Establish a beachhead in India's semi-automatic tray former segment where FSSAI sanitary design mandates are displacing manual operations but domestic OEMs lack servo engineering depth. Target electronics contract manufacturers in Vietnam and Indonesia with compact footprint configurations optimized for premium cleanroom lease rates, bypassing entrenched competition in saturated North American food packaging networks. For Investors and Strategic Acquirers: EU Machinery Directive safety integrity upgrades reshape the acquisition landscape by elevating compliance engineering costs that strain mid-scale regional fabricators. Mid-cap specialists with validated CE marking dossiers and existing pharmaceutical cleanroom installations represent consolidation targets with defensive moats against Asian volume exporters. Monitor German automotive battery gigafactory procurement pipelines as an inflection signal for industrial-scale integrated line center demand.| Strategic Initiative | Industry Significance |
|---|---|
| Servitization Transition | Performance-based contracts with uptime guarantees displace break-fix revenue in US beverage bottling networks. |
| Backward Integration into Motion Control | In-house servo drive production insulates margins from Taiwanese semiconductor supply volatility. |
| CE Marking Acceleration | Early compliance with EU Machinery Directive safety integrity requirements unlocks German automotive battery procurement channels. |
| Cleanroom Footprint Miniaturization | Sub-2-meter machine widths capture electronics contract manufacturing expansion in South Korea's Gyeonggi-do cluster. |
| Pharmaceutical Serialization Integration | Registration accuracy within ±0.5mm positions systems for Swissmedic-tracked packaging operations in Basel. |
Study Parameters
Cross-validation between machinery OEM technical documentation and food processor capital expenditure records anchors the qualitative findings on servo electrification adoption trajectories. Primary interviews with plant engineers, aftermarket service directors, OEM procurement teams, and regulatory compliance officers across North American dairy processing and European pharmaceutical packaging networks combined with secondary validation from SEC equipment supplier filings, EU Machinery Directive implementation guidance, and FDA 21 CFR sanitary design standards. Bottom-up unit shipment estimates triangulate against top-down capital investment flows reported in food industry trade associations.
Calibration against historical replacement cycle data and energy price elasticity assumptions shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include automation intensity, actuation technology, end-use vertical, and machine footprint category, with regional regulatory enforcement intensity treated as a cross-cutting variable. CAGRs derive from equipment lifecycle depreciation schedules and capacity expansion announcements by major food packaging conglomerates, with servo motor cost curves and compressed air pricing volatility as industry-specific forecast inputs.
Sensitivities concentrate around EU energy tariff trajectories, Chinese steel export duty fluctuations, and FDA validation timeline extensions for custom sanitary designs. Forecasts reflect documented assumptions on replacement cycle acceleration and technology substitution elasticities. Cross-checking against machinery import statistics from Germany's Federal Statistical Office and US Census Bureau capital goods trade data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Banding Machine Market
Packaging Machinery
Flow Wrapper Market
Packaging Machinery
Lidding Machines Market
Packaging Machinery
Heavy Duty Band Sealer Machine Market
Packaging Machinery
Asia-Pacific Pharmaceutical Packaging Machinery Market
Packaging Machinery
Box Sealing Machines Market
Packaging Machinery
Corrugated Box Printer Slotter Machine Market
Packaging Machinery
Liquid Pouch Filling and Sealing Machine Market
Packaging Machinery
CCL Laminating Machine Market
Packaging Machinery
Extrusion Press Market
Packaging Machinery
Thermal Film Laminating Machines Market
Packaging Machinery
Capsule Filling Machines Market
Packaging Machinery
Horizontal Flow Wrapping Machines Market
Packaging Machinery
Meter-Mix Dispensing Machine Market
Packaging Machinery
Powder Packing Machine Market
Packaging Machinery
Lipstick Molding Machines Market