
 Vial Capping Machines Market | 2026-2036
Vial Capping Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Vial Capping Machines Market Analytics
Aluminum-plastic composite seals is pivoting toward all-aluminum designs to improve tamper-evidence and recyclability in pharmaceutical packaging. Syntegon leverages its integrated processing portfolio to dominate high-throughput vaccine lines across European manufacturing hubs. Cozzoli Machine Company anchors its position through precision-engineered semi-automatic systems serving mid-scale biotechnology producers in North America. Krones differentiates via modular platform architectures that accommodate rapid format changeovers for multi-product contract manufacturers.
Vial capping machines apply calibrated torque to secure elastomeric stoppers and aluminum seals onto glass or polymer vials, typically operating at speeds from 60 to 600 units per minute with torque accuracy within ±5 percent to maintain container closure integrity. These systems serve critical functions in sterile drug product finishing, where improper seal compression risks contamination or oxidation that compromises shelf-stable biologics. Automatic capping equipment leads unit shipments due to throughput requirements in commercial pharmaceutical fill-finish operations, while laboratory-scale manual systems command premium pricing from research institutions running small-batch clinical trials. Servo technology represents the fastest-expanding category as direct-drive motors deliver precise torque profiling without compressed air infrastructure, though pneumatic systems retain installed-base dominance in emerging manufacturing economies.
FDA current Good Manufacturing Practice regulations and EMA Annex 1 sterile manufacturing guidelines mandate validated capping processes with documented torque monitoring and seal integrity testing for commercial drug products. ISO 15378 primary packaging materials standards and USP Chapter 1207 container closure integrity requirements further constrain equipment design, compelling manufacturers to integrate in-line check-weighing and vision inspection modules. Stakeholders must weigh total cost of ownership against regulatory audit readiness when selecting between established pneumatic platforms and emerging servo architectures for facility expansions.
Market Dynamics
Servo-driven torque control is compressing cycle times and eliminating compressed air infrastructure from vaccine fill-finish lines, forcing incumbent pneumatic suppliers to accelerate retrofit programs or cede high-throughput installations.
Growth Catalysts
- FDA serialization mandates:Track-and-trace requirements for commercial drug products are compelling contract manufacturers to upgrade from semi-automatic to fully validated automatic capping systems with integrated vision inspection.
- Cell and gene therapy expansion:Personalized medicine manufacturing in Switzerland and the United States requires flexible, small-batch capping equipment that maintains sterile isolator compatibility.
- Aluminum seal recyclability:Pharmaceutical packaging sustainability targets in Germany are accelerating displacement of aluminum-plastic composite seals with mono-material designs compatible with standard capping heads.
Market Restraints
- Stainless steel input volatility:Grade 316L pharmaceutical-grade steel price fluctuations compress margins for European equipment fabricators serving mid-scale biotechnology producers.
- Precision servo motor supply concentration:High-torque direct-drive motor manufacturing concentrates in Japan and Germany, exposing capping system OEMs to extended lead times during capacity constraints.
- Legacy pneumatic installed base:Emerging manufacturing economies in Southeast Asia face capital constraints that prolong dependence on compressed-air systems despite higher operating costs.
Strategic Opportunities
- Indian biopharmaceutical contract manufacturing:CDMO capacity expansion under the PLI scheme creates demand for modular capping platforms with rapid format changeover capabilities.
- Continuous manufacturing integration:Convergence of real-time release testing and servo-driven capping enables elimination of batch-wise quality verification in advanced therapy production.
- EMA Annex 1 revision:Updated sterile manufacturing guidelines create compliance-driven replacement cycles for pre-2023 capping equipment lacking documented torque monitoring.
Industry Challenges
- Mechatronics technician scarcity:Servo system commissioning and predictive maintenance require specialized skills that outpace vocational training output in Midwestern United States manufacturing hubs.
- IQ/OQ/PQ validation timelines:FDA current Good Manufacturing Practice documentation requirements extend equipment qualification periods, delaying revenue recognition for fill-finish line expansions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vial Capping Machines Market |
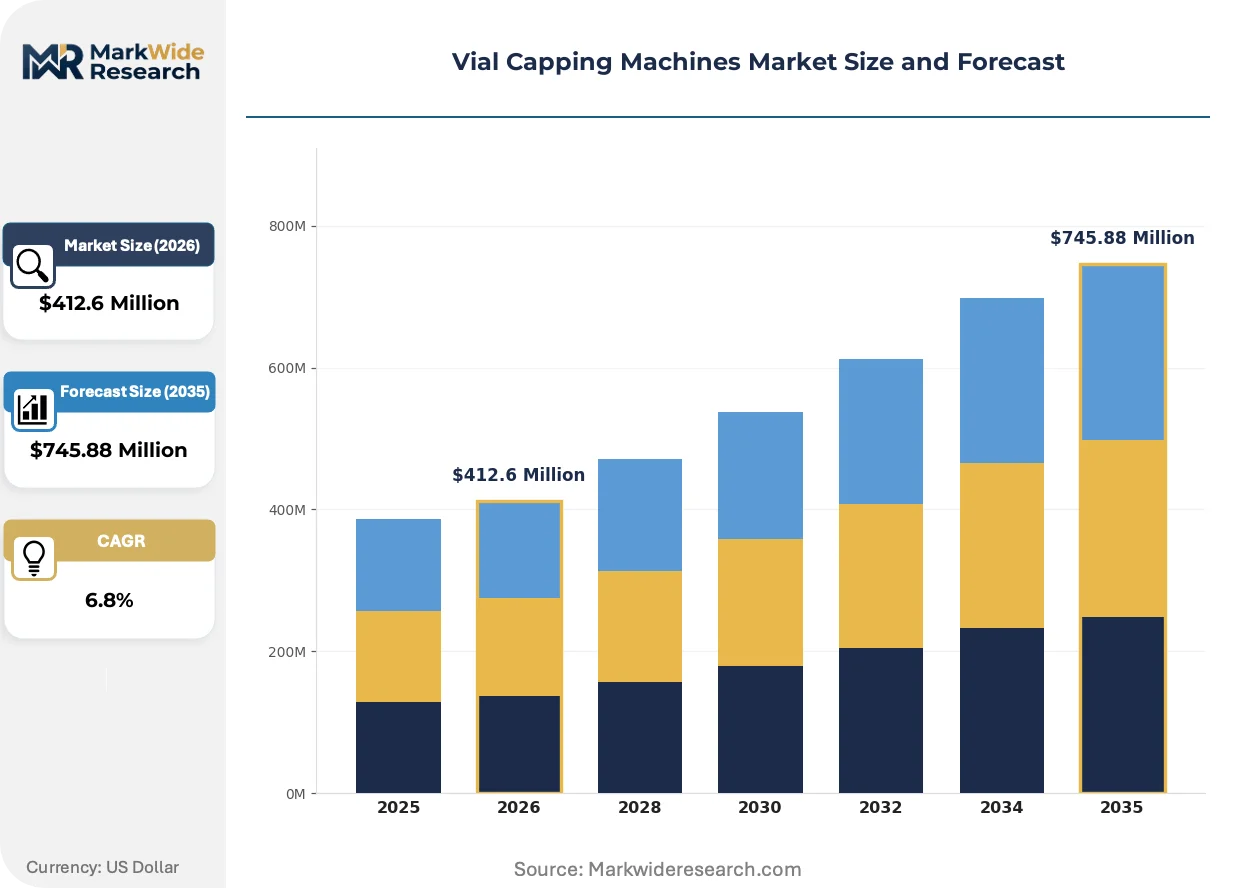
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Semi-Automatic, Manual, Laboratory Technology: Pneumatic, Servo, Electromechanical, Hydraulic Application: Pharmaceuticals, Biotechnology, Cosmetics, Food & Beverage End User: OEMs, Contract Manufacturers, Research Institutions, Laboratories |
| Companies Covered | Syntegon, Cozzoli Machine Company, Closure Systems International, Accutek Packaging Equipment, IMA Group, Krones, Capmatic, Groninger & Co. GmbH, Filamatic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vial Capping Machines Market Evolving Landscape
Servo-electronic torque profiling is collapsing the performance gap between laboratory-scale precision and commercial throughput, enabling single-platform architectures that span clinical trial to commercial launch without equipment replacement.
Direct-drive servo motors with integrated torque transducers are decentralizing capping control from centralized pneumatic manifolds to individual spindle-level feedback loops. Vaccine manufacturers in the United States and Switzerland are adopting these architectures for 400+ units per minute lines. This shift is decentralizing maintenance expertise requirements from facility-wide compressed air engineers to spindle-level diagnostics technicians.
EMA Annex 1 sterile manufacturing guidelines now mandate continuous process verification for commercial drug products, compelling equipment suppliers to embed in-line check-weighing and seal integrity testing within capping modules. European fill-finish operators are redesigning isolator layouts to accommodate these integrated inspection stations. High-value biologics manufacturing in Germany and Ireland faces the most intensive compliance retrofit requirements.
Biotechnology procurement teams are unbundling equipment purchase from validation service contracts, treating capping system vendors as component suppliers while engaging specialized third-party firms for IQ/OQ/PQ execution. This disintermediation compresses vendor margins and extends sales cycles. The pattern is most pronounced among mid-scale North American CDMOs seeking to diversify supplier risk across multiple equipment and service providers.
Vial Capping Machines Market Segmentation
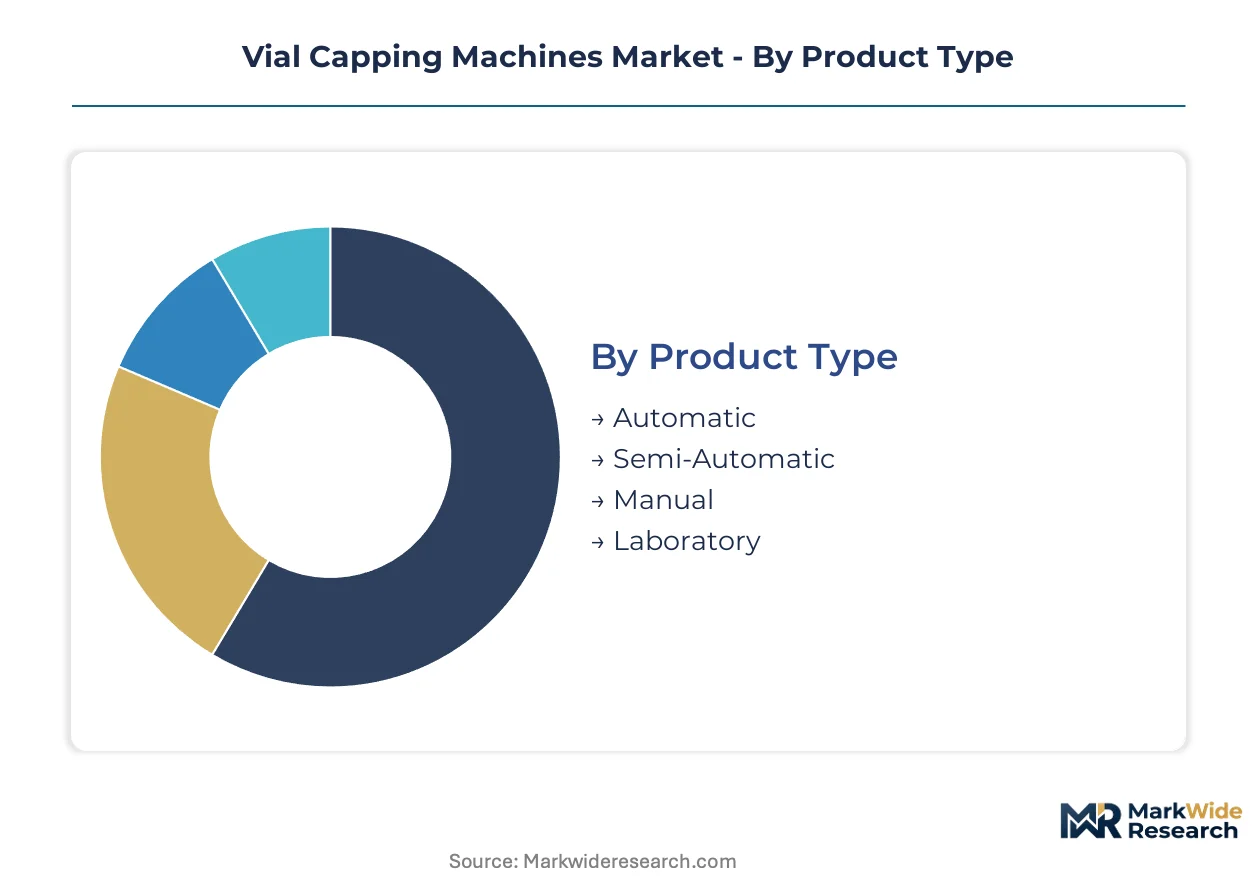
Segmentation in vial capping machines reflects divergent operational requirements across sterile drug manufacturing, from high-throughput commercial fill-finish to precision laboratory applications. Equipment specifications vary dramatically by torque accuracy demands, batch size flexibility, and regulatory validation intensity.
Product Type:
Automatic systems dominate commercial volume while manual and laboratory configurations command substantial price premiums per unit.
- Automatic:These systems deliver 200 to 600 units per minute with integrated vision inspection and torque feedback loops. Demand concentrates in vaccine manufacturing facilities across the United States and Switzerland where FDA and Swissmedic mandates for serialization drive replacement of legacy equipment.
- Semi-Automatic:Units process 60 to 150 units per minute with operator-assisted vial handling. Contract manufacturers in India under CDSCO oversight favor these platforms for mid-scale biologics production where batch flexibility outweighs absolute throughput.
- Manual:Benchtop devices serve small-batch clinical trial material preparation with torque accuracy within ±3 percent.
- Laboratory:Precision-engineered systems accommodate research-scale sterile filling in isolator environments.
Mature deployment sits with Automatic systems in commercial pharmaceutical operations. Newer deployment is concentrated in Laboratory configurations serving cell and gene therapy manufacturing.
Technology:
Drive mechanism selection determines capital expenditure profiles, operating cost structures, and maintenance expertise requirements across facility types.
- Servo:Direct-drive motors with integrated torque transducers eliminate compressed air infrastructure and enable spindle-level feedback control. Biotechnology manufacturers in Germany and Ireland are adopting these architectures fastest under EMA Annex 1 pressure for continuous process verification.
- Pneumatic:Compressed-air systems retain installed-base dominance in Southeast Asian manufacturing economies where capital constraints prolong dependence despite higher energy consumption.
- Electromechanical:Hybrid architectures combine electric actuation with mechanical torque limiting for mid-speed applications.
- Hydraulic:High-force systems serve specialty pharmaceutical packaging with unusual container geometries.
Procurement patterns favor Servo technology for new greenfield installations. Pneumatic retention is strongest in brownfield expansions with existing compressed air infrastructure.
Application:
End-use sector dictates sterility assurance levels, validation documentation intensity, and equipment changeover frequency requirements.
- Pharmaceuticals:Commercial drug product finishing demands validated capping with documented torque monitoring under FDA current Good Manufacturing Practice. Fill-finish operators in the United States and Germany face the most intensive compliance retrofit cycles.
- Biotechnology:Cell and gene therapy manufacturing requires flexible equipment compatible with isolator environments and rapid format changeovers. Swiss and United States facilities lead adoption of single-platform architectures spanning clinical to commercial scale.
- Cosmetics:Lower sterility requirements permit simpler pneumatic systems with reduced validation burden.
- Food & Beverage:Aseptic packaging applications borrow pharmaceutical-grade technology for extended shelf-life products.
Revenue concentration rests with Pharmaceuticals. Biotechnology represents the steepest expansion trajectory as personalized medicine manufacturing scales.
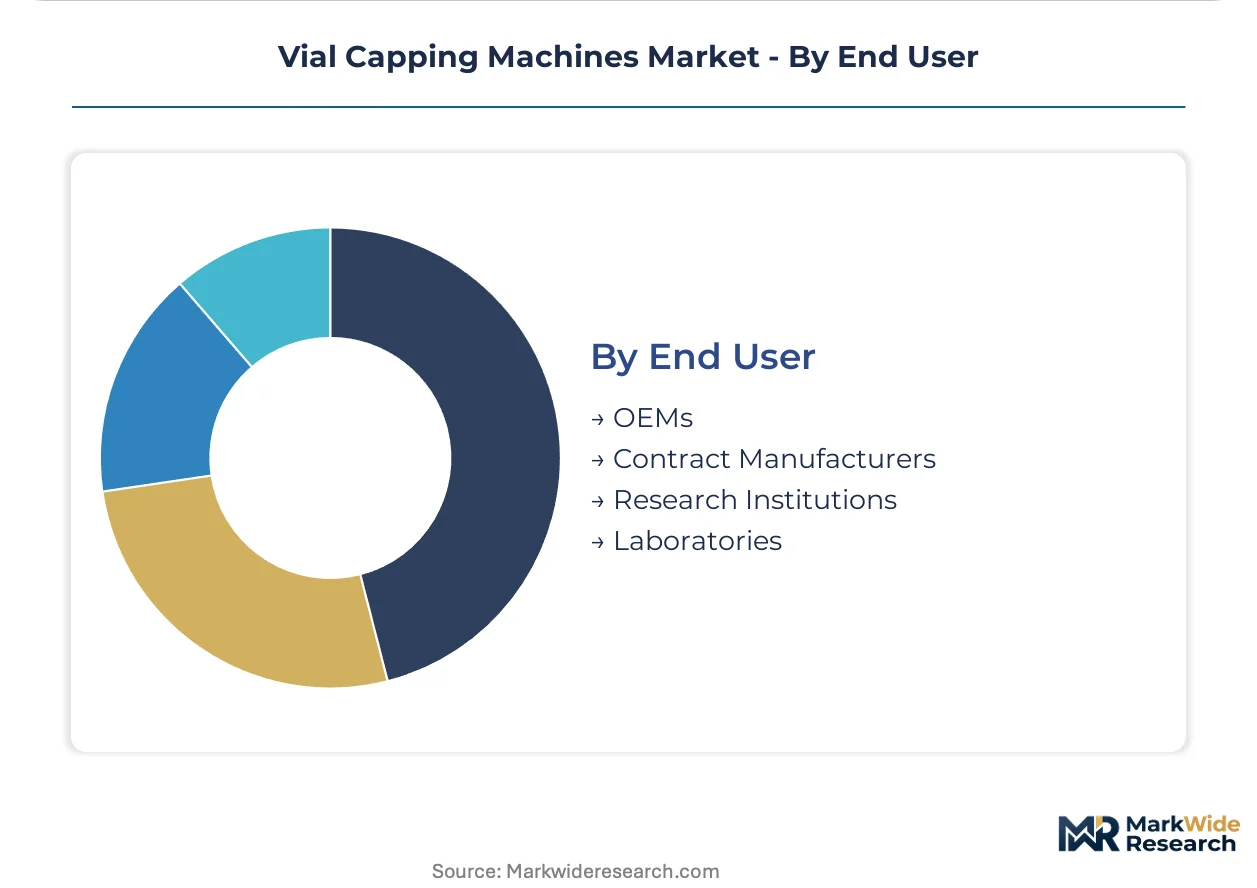
End User:
Customer type determines procurement sophistication, service contract structures, and validation responsibility allocation.
- Contract Manufacturers:CDMOs in India and Germany are expanding automated filling lines to serve multiple pharmaceutical clients under divergent regulatory requirements. The PLI scheme in India accelerates capacity additions with modular platform preferences.
- OEMs:Integrated fill-finish line builders specify capping modules as subsystems within larger processing portfolios.
- Research Institutions:Academic and government laboratories prioritize precision over speed for small-batch clinical trial material.
- Laboratories:Quality control and analytical testing facilities require validated equipment for container closure integrity studies.
Contract Manufacturers drive volume procurement with standardized platform specifications. Research Institutions sustain premium pricing through specialized torque profiling requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biopharmaceutical manufacturing clusters in the United States, Germany, Switzerland, India, and China concentrate demand for validated capping equipment. FDA and EMA serialization mandates drive replacement cycles across these jurisdictions. Contract manufacturers in India and Germany are expanding automated filling lines fastest.
United States
Vaccine manufacturers in Massachusetts and North Carolina are retrofitting fill-finish lines with servo-driven torque control systems. FDA current Good Manufacturing Practice regulations mandate documented torque monitoring for commercial drug products. Boston-Cambridge biotech clusters lead adoption of single-platform architectures spanning clinical to commercial scale.
Germany
EMA Annex 1 sterile manufacturing guidelines are compelling equipment replacement cycles for pre-2023 capping systems lacking continuous process verification. The country's national pharmaceutical regulator enforces strict container closure integrity documentation. Rhine-Ruhr manufacturing hubs host the densest concentration of modular capping platform deployments serving multi-product CDMOs.
Switzerland
Cell and gene therapy manufacturing in Basel and Zurich requires flexible capping equipment compatible with isolator environments. Swissmedic mandates for personalized medicine production drive demand for rapid format changeover capabilities. The Basel-Land industrial corridor anchors high-value biologics finishing operations with intensive compliance requirements.
India
Biopharmaceutical contract manufacturers in Maharashtra and Telangana are expanding capacity under the PLI scheme with modular platform preferences. CDSCO oversight requires validated automatic systems with integrated vision inspection for export-oriented production. Hyderabad-Pune pharmaceutical corridors concentrate the fastest greenfield installation rates for servo technology.
China
Vaccine fill-finish operators in Jiangsu and Zhejiang provinces are adopting high-speed automated lines to meet NMPA serialization requirements. The national medical products administration mandates track-and-trace compliance for commercial drug products. Yangtze River Delta manufacturing clusters lead domestic adoption of servo-electronic torque profiling systems.
Vial Capping Machines Market Competitive Landscape
Portfolio diversification dominates the current landscape as equipment suppliers unbundle hardware from validation services to capture recurring revenue streams. The vendor base organizes around three strategic archetypes: integrated processing portfolio holders, precision-engineered specialists, and modular platform architects. M&A activity and technology licensing agreements represent the primary competitive vectors as incumbents seek servo-electronic capabilities and regional service networks.
Among European integrated processing portfolio holders, Syntegon and Krones occupy positions spanning high-throughput vaccine lines to modular contract manufacturing platforms. German precision-engineered specialists Groninger & Co. GmbH exemplify the mid-scale biotechnology focus with isolator-compatible architectures. North American precision fabricators Cozzoli Machine Company and Accutek Packaging Equipment represent the semi-automatic and laboratory-scale segments serving research institutions and emerging CDMOs.
| Leading Market Players |
|---|
| Syntegon |
| Cozzoli Machine Company |
| Closure Systems International |
| Accutek Packaging Equipment |
| IMA Group |
| Krones |
| Capmatic |
| Groninger & Co. GmbH |
| Filamatic |
| Others |
Value Network & Pricing Analysis
EMA Annex 1 sterile manufacturing guidelines gate qualified supply and premium-tier pricing access by mandating documented torque monitoring and continuous process verification for commercial drug products. Contract manufacturers in Germany and the United States absorb validation service unbundling costs while biotechnology procurement teams compress vendor margins through third-party IQ/OQ/PQ execution.
Pricing Analysis
Volume concentrates in automatic systems serving vaccine manufacturers while margins concentrate in laboratory-scale configurations for cell and gene therapy applications. Three-tier pricing structure across premium, standard, and economy levels separates servo-driven platforms with integrated vision inspection from pneumatic retrofit units and basic semi-automatic systems. Price differentiation hinges on torque accuracy certification and after-sales validation support bundling. Pricing pressure stems from stainless steel input volatility compressing European fabricator margins. Emerging manufacturing economies in Southeast Asia exhibit highest price sensitivity due to capital constraints prolonging pneumatic dependence.
Supply Chain Analysis
High-torque direct-drive motor supply rests on Japanese and German specialty manufacturers, exposing capping system OEMs to extended lead times during capacity constraints. Grade 316L pharmaceutical-grade stainless steel draws from German, Japanese, and South Korean metallurgical producers. Aluminum seal stock feeds from Chinese and German rolling mills. Single-source vulnerability concentrates in precision servo motor manufacturing. Distribution runs through integrated processing portfolio holders and specialized equipment fabricators serving regional fill-finish clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vial capping machines market is consolidating around servo-electronic capabilities as EMA Annex 1 compliance costs force pneumatic specialists into distressed asset sales or technology licensing arrangements.
For Market Incumbents: Deepen backward integration into precision servo motor supply relationships to insulate against Japanese and German capacity constraints. Anchor service revenue through captive validation offerings that counter third-party IQ/OQ/PQ disintermediation threatening hardware margins. Prioritize modular platform architectures for Indian CDMOs expanding under PLI scheme incentives. For New Entrants and Emerging Players: The gap between premium servo systems and economy pneumatic units creates entry space for electromechanical hybrid architectures serving mid-scale biotechnology producers in North America. Target laboratory-scale configurations for Swiss and United States cell and gene therapy manufacturing where isolator compatibility commands pricing power. Lead with rapid format changeover capabilities as the primary go-to-market wedge against integrated portfolio incumbents. For Investors and Strategic Acquirers: EMA Annex 1 revision implementation is the leading indicator that compliance-driven replacement cycles will concentrate market share among validated platform suppliers. The five-to-ten year viability window favors acquisition of precision-engineered specialists with isolator-compatible architectures and established regulatory documentation libraries. Watch for distressed pneumatic equipment vendors seeking servo technology licensing partnerships as the primary inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Servo-Electronic Platform Migration | FDA and EMA serialization mandates accelerate displacement of pneumatic installed base in vaccine manufacturing. |
| Validation Service Integration | Captive IQ/OQ/PQ offerings counter third-party disintermediation compressing hardware margins at Syntegon and Krones. |
| Indian Manufacturing Footprint Expansion | PLI scheme incentives attract modular platform deployments serving CDMO capacity additions in Maharashtra and Telangana. |
| Continuous Process Verification Embedding | In-line check-weighing and seal integrity testing integration meets EMA Annex 1 sterile manufacturing guideline requirements. |
| Precision Servo Motor Supply Agreement | Long-term contracts with Japanese and German motor manufacturers mitigate lead time exposure during capacity constraints. |
Research Methodology
Document review covered FDA 483 inspection observations, EMA GMP inspection deficiency reports, and ISO 15378 primary packaging materials standards, complemented by interviews with fill-finish operations directors, pharmaceutical quality assurance managers, CDMO procurement leads, and servo system commissioning technicians. Secondary validation drew from USP Chapter 1207 container closure integrity documentation, SEC 10-K filings of integrated processing portfolio holders, and Swissmedic personalized medicine manufacturing guidelines. Bottom-up equipment shipment estimates triangulated against top-down pharmaceutical fill-finish capacity expansion announcements.
Segment-level value outputs were constructed across product type, drive technology, application sector, and end-user archetype dimensions throughout the forecast period. CAGRs were derived from installed base replacement cycles, greenfield facility commissioning timelines, and regulatory compliance deadline clustering. Industry-specific forecast inputs incorporated servo motor lead time volatility, Grade 316L stainless steel price indexing, and EMA Annex 1 revision implementation schedules across European manufacturing hubs.
Inputs from FDA warning letter databases and EMA inspection outcome registers were available through the study window; gaps in real-time CDSCO enforcement data and NMPA serialization compliance tracking introduce uncertainty bands around Indian and Chinese market penetration assumptions. Forecasts reflect documented regulatory deadline clustering and announced capacity expansion commitments. Servo technology adoption velocity, stainless steel input price trajectories, and mechatronics technician training pipeline adequacy represent primary revision risks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Automatic Filling Machine Market
Packaging Machinery
Poly Bagging Machines Market
Packaging Machinery
Induction Sealing Machine Market
Packaging Machinery
Meter-Mix Dispensing Machine Market
Packaging Machinery
Sleeve Wrapping Machine Market
Packaging Machinery
Envelope Sealing Machines Market
Packaging Machinery
Vertical Strapping Machines Market
Packaging Machinery
Heavy Duty Band Sealer Machine Market
Packaging Machinery
Case Packaging Machinery Market
Packaging Machinery
Toilet Roll Converting Lines Market
Packaging Machinery
Paper Napkins Converting Machines Market
Packaging Machinery
Box Filling Machine Market
Packaging Machinery
Liquid Filling Machines Market
Packaging Machinery
Aerosol Filling Machines Market
Packaging Machinery
Glazing Machine Market
Packaging Machinery
Triangle Tea Bag Packaging Machinery Market