
 Asia-Pacific Pharmaceutical Glycerin Based Products Market | 2026-2036
Asia-Pacific Pharmaceutical Glycerin Based Products Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Pharmaceutical Glycerin Based Products Market Analytics
India's glycerin refining corridor is narrowing the gap between technical-grade output and pharmaceutical-grade supply. KLK OLEO leverages its Malaysian oleochemical complex to sustain high-purity glycerin flows into Indian formulation plants. IOI Oleochemical anchors its Asia-Pacific position through backward integration into palm oil refining. P&G Chemicals competes on USP-grade consistency across multiple production sites.
Pharmaceutical glycerin based products comprise refined glycerol formulations meeting USP or EP monograph specifications, typically achieving purity above 99.5% through ion exchange or distillation processes, serving as osmotic agents, humectants, and excipient stabilizers in drug delivery systems. Liquid glycerin dominates volume throughput due to its versatility across oral, topical, and parenteral applications, while glycerin suppositories retain stable demand in pediatric and geriatric constipation management. Glycerin tablets occupy a mature niche with limited formulation innovation, whereas glycerin creams capture expanding margin pools in dermatological cosmeceuticals.
India's CDSCO mandates excipient-grade traceability under revised drug master file protocols, while China's NMPA enforces pharmacopoeial alignment with ChP standards for glycerin used in domestically manufactured generics. Japan's PMDA maintains stringent residual solvent limits that filter out non-pharmaceutical glycerin streams. Stakeholders must monitor evolving pharmacopoeial harmonization between national regulators and assess captive refining investments versus merchant supply dependence.
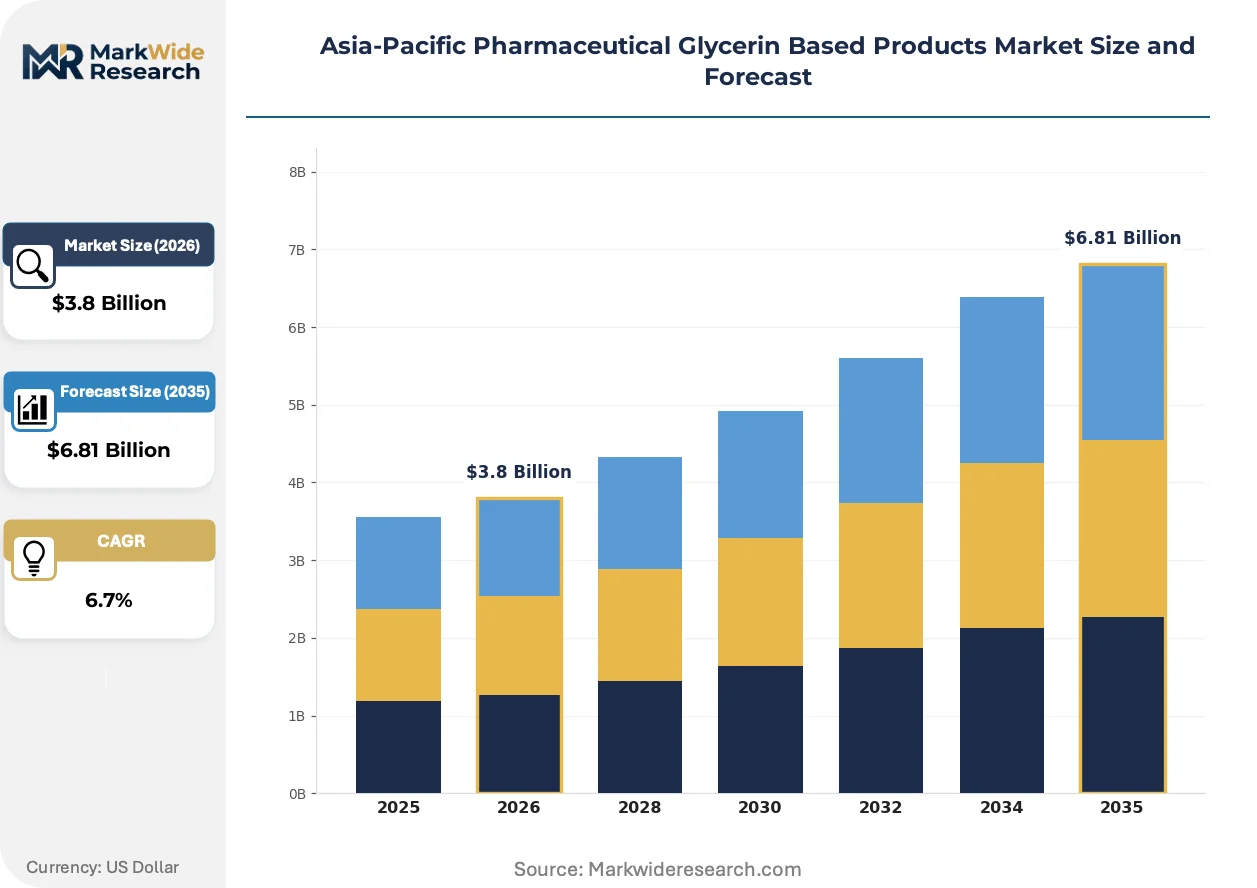
Market Dynamics
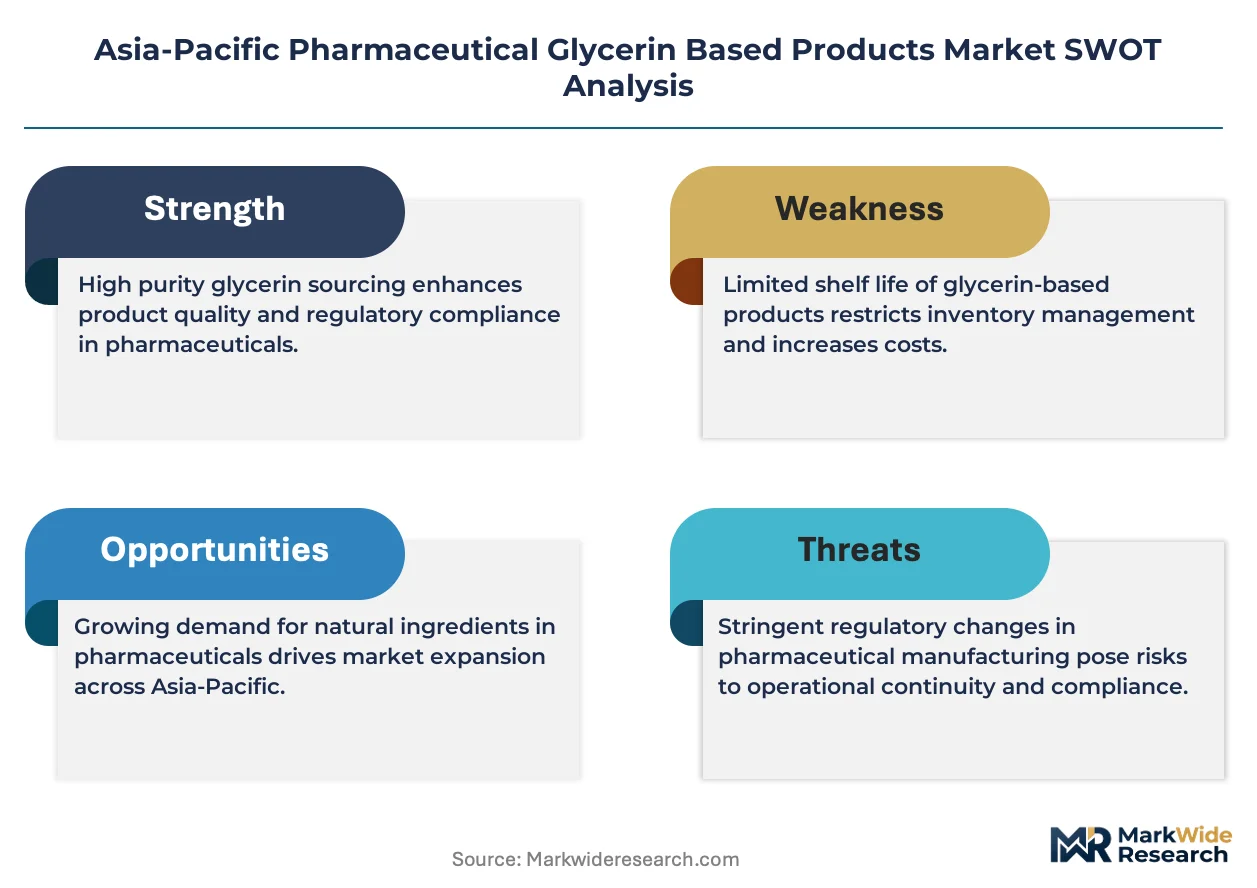
Pharmaceutical-grade glycerin supply in Asia-Pacific is tightening around captive oleochemical refining complexes, as merchant market liquidity shrinks under pharmacopoeial purity mandates from CDSCO, NMPA, and PMDA.
Growth Catalysts
- CDSCO Excipient Traceability Mandate:India's revised drug master file protocols force formulation plants to source USP-certified glycerin, pulling technical-grade refiners up the value chain.
- Pediatric Laxative Demand:Glycerin suppositories retain stable prescription volumes across Japan's aging prefectures and India's pediatric care networks.
- Dual Carbon Goals:China's MEE incentives for bio-based feedstock utilization accelerate epichlorohydrin-to-glycerin process conversions at domestic API hubs.
Market Restraints
- Palm Oil Price Volatility:Crude palm oil futures transmit directly to glycerin spot markets, compressing margin predictability for non-integrated formulators.
- Malaysian Supply Concentration:Klang Valley oleochemical complexes control the majority of Asia-Pacific pharmaceutical-grade export volumes, creating single-geography dependency.
- Residual Solvent Limits:PMDA's stringent methanol and diethylene glycol thresholds filter out non-pharmaceutical glycerin streams from Japan-bound shipments.
Strategic Opportunities
- Vietnam Formulation Manufacturing:Greenfield pharmaceutical plants in Binh Duong province seek captive glycerin supply partnerships to serve ASEAN export markets.
- Dermatological Cosmeceuticals:Humectant-grade glycerin creams capture expanding margin pools in South Korean and Australian aesthetic medicine channels.
- PLI Scheme Alignment:India's production-linked incentive schemes for active pharmaceutical ingredients subsidize backward integration into glycerin refining.
Industry Challenges
- Pharmacopoeial Harmonization Lag:Misalignment between USP, EP, and ChP monograph specifications forces dual-certification inventories and extended batch release timelines.
- Ion Exchange Resin Sourcing:Specialized purification media for glycerin distillation face extended procurement lead times from European specialty chemical suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Pharmaceutical Glycerin Based Products Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Glycerin, Glycerin Suppositories, Glycerin Tablets, Glycerin Creams End User: Hospitals, Pharmacies, Clinics, Homecare Settings Application: Laxatives, Emollients, Humectants, Antiseptics Distribution Channel: Online Retail, Wholesalers, Direct Sales, Pharmacy Chains |
| Companies Covered | Hunan Er-Kang Pharmaceutical, IOI Oleochemical, KLK OLEO, Kao Corporation, Emery Oleochemicals, P&G Chemicals, Wilmar International Ltd., Oleon NV, Hangzhou Oleochemicals, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Pharmaceutical Glycerin Based Products Market Evolving Landscape
Membrane filtration and molecular distillation technologies are compressing the capital intensity gap between technical-grade and pharmaceutical-grade glycerin output, enabling mid-scale refiners to enter certified supply chains.
Hybrid purification architecture is hybridizing ion exchange columns with thin-film evaporators to achieve 99.7% purity thresholds without multi-pass distillation. Indian contract manufacturers are piloting these systems to meet CDSCO's tightened excipient documentation requirements. The technology is compressing capital barriers for regional refiners seeking USP certification.
REACH-aligned substance registration is forcing Asian glycerin exporters to submit extended safety data sheets for EU-bound pharmaceutical shipments. NMPA's 2025 pharmacopoeial revision cycle is incorporating analogous disclosure requirements for domestic generics manufacturers. Formulators in Zhejiang and Jiangsu provinces are consolidating supplier bases to reduce compliance documentation fragmentation.
Buyers are consolidating glycerin procurement under long-term offtake agreements with oleochemical producers, displacing spot-market purchasing for critical excipient volumes. Japanese pharmaceutical distributors are negotiating three-year supply contracts directly with Malaysian refining complexes. The shift is most visible in parenteral-grade glycerin, where batch consistency requirements override price elasticity.
Asia-Pacific Pharmaceutical Glycerin Based Products Market Segmentation
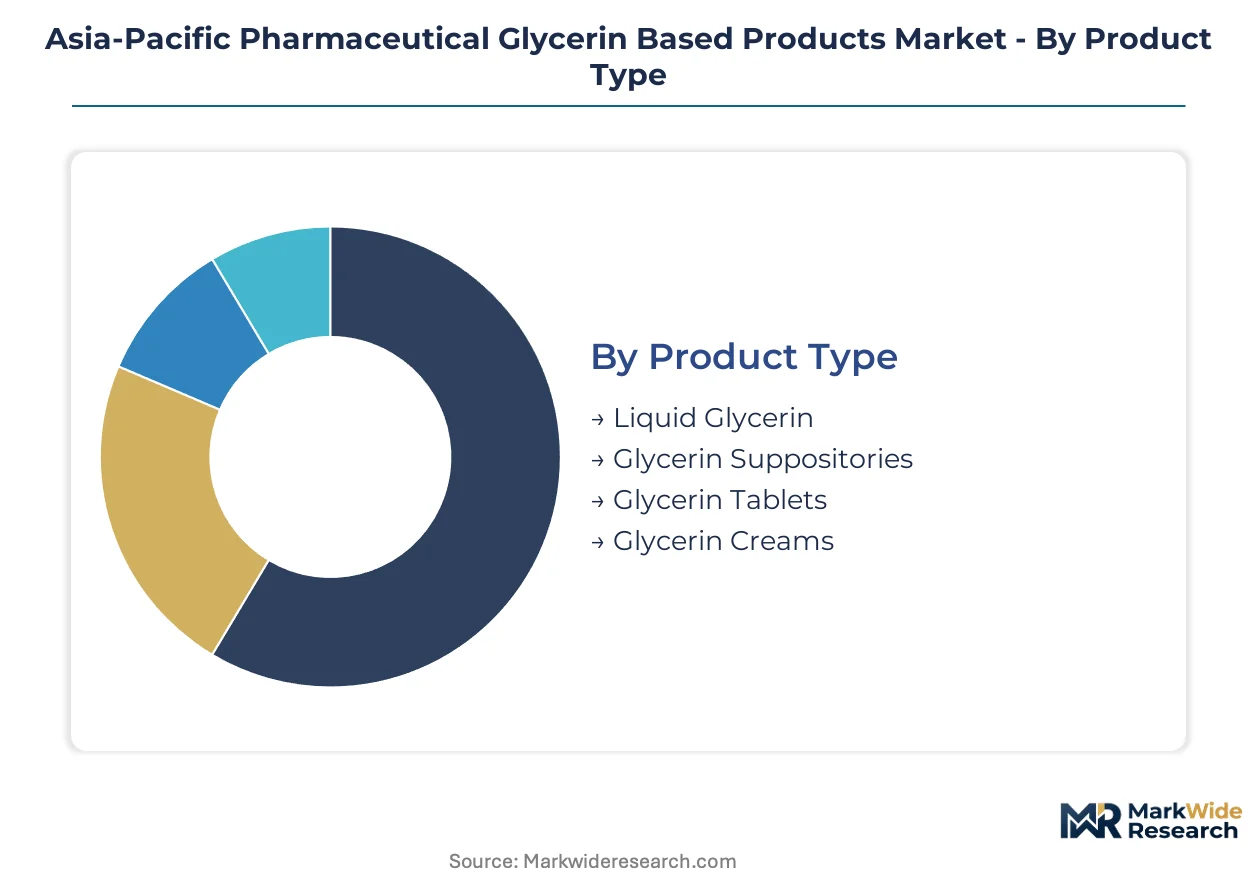
Pharmaceutical glycerin products traverse distinct demand cycles across formulation types, end-use settings, and procurement channels. Segment-level analysis reveals where inventory velocity compresses lead times and where pharmacopoeial certification extends batch release timelines.
Product Type:
Liquid glycerin turns inventory fastest through oral and parenteral formulation plants, while suppository manufacturing cycles stretch longer due to mold-release and stability testing protocols.
- Liquid Glycerin:Refined glycerol achieving 99.5%+ purity through ion exchange or molecular distillation serves as the universal excipient backbone. Demand concentrates in China's Zhejiang and Jiangsu API corridors where domestic producers secure captive supply to feed generic injectable lines under NMPA pharmacopoeial alignment.
- Glycerin Suppositories:Molded polyethylene glycol-glycerin matrices designed for pediatric and geriatric rectal administration carry extended stability protocols. Japan's PMDA residual solvent limits filter out non-pharmaceutical glycerin streams, concentrating prescription volumes in Tokyo and Osaka prefectures facing acute aging demographics.
- Glycerin Tablets:Compressed formulations occupy mature constipation management with limited formulation innovation.
- Glycerin Creams:Humectant-grade emulsions capture expanding margin pools in South Korean dermatological cosmeceuticals.
Liquid glycerin dominates installed base. Glycerin creams are where expansion concentrates.
End User:
Procurement scale and pharmacovigilance intensity separate high-volume institutional buyers from fragmented retail channels.
- Hospitals:Centralized pharmacy committees negotiate multi-year glycerin excipient contracts under stringent USP documentation. India's CDSCO drug master file protocols force tertiary care networks in Maharashtra and Karnataka to consolidate supplier bases toward certified refiners.
- Pharmacies:Community dispensaries across Australia's TGA-regulated states move glycerin-based OTC laxatives through rapid-turnover shelf cycles.
- Clinics:Outpatient facilities in Vietnam's Binh Duong province source suppository volumes for pediatric constipation protocols.
- Homecare Settings:Direct-to-patient channels expand through online retail integration for chronic constipation management.
Hospitals anchor procurement volume. Homecare settings are climbing the fastest.
Application:
Functional differentiation across osmotic, emollient, and antimicrobial properties determines glycerin grade specifications and pricing tiers.
- Laxatives:Hyperosmotic glycerol formulations draw water into intestinal lumen through colon-retained administration. Pediatric networks across India's government health schemes and Japan's geriatric care infrastructure sustain stable prescription volumes for suppository and enema delivery.
- Emollients:Skin-conditioning glycerin creams penetrate stratum corneum through hygroscopic moisture retention. South Korean aesthetic medicine channels and Australian dermatology clinics drive humectant-grade demand.
- Humectants:Moisture-stabilizing excipients in oral solid dosage forms require USP-grade certification under tightened CDSCO traceability mandates.
- Antiseptics:Glycerin-preserved topical preparations face formulation competition from alternative polyol stabilizers.
Laxatives command the largest application footprint. Emollients show the steepest expansion trajectory.
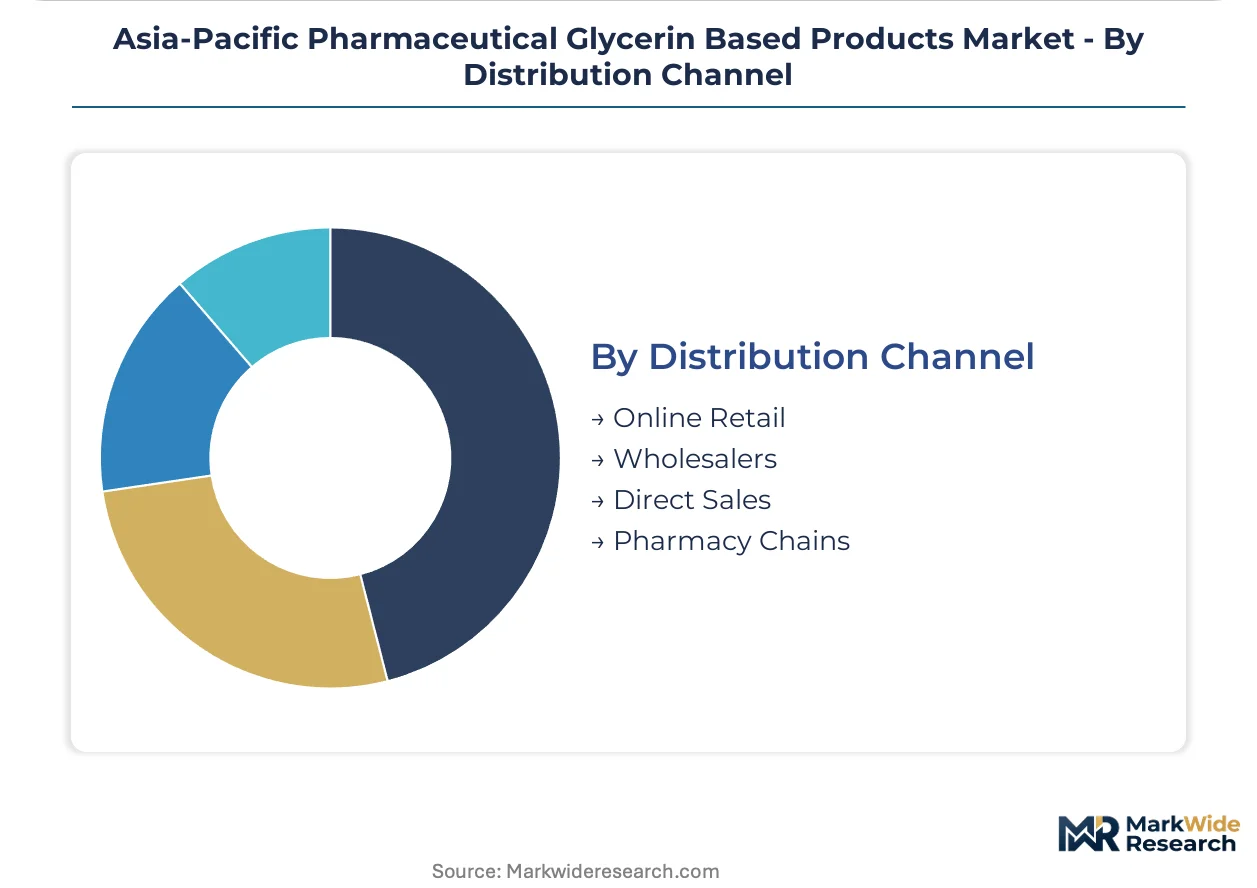
Distribution Channel:
Channel selection reflects batch size requirements, documentation burdens, and geographic reach to formulation plants.
- Online Retail:E-procurement platforms aggregate fragmented glycerin tablet and cream demand from smaller Indian formulation plants seeking CDSCO-compliant excipient documentation without direct refiner relationships.
- Wholesalers:Regional distributors in Malaysia's Klang Valley oleochemical corridor buffer pharmaceutical-grade inventory for ASEAN export markets.
- Direct Sales:Captive supply agreements between Malaysian refining complexes and Japanese pharmaceutical distributors displace spot-market purchasing for parenteral-grade volumes.
- Pharmacy Chains:Consolidated retail networks in Australia's eastern states move OTC glycerin laxatives through high-velocity replenishment cycles.
Direct sales lock in premium-grade volume. Online retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NMPA's pharmacopoeial alignment mandates anchor China's dominance in pharmaceutical-grade glycerin demand. CDSCO's excipient traceability protocols reshape procurement patterns across Indian formulation corridors. PMDA's residual solvent thresholds filter supply streams reaching Japanese pharmaceutical distributors.
China
Zhejiang and Jiangsu API producers secure captive glycerin supply to feed generic injectable lines under NMPA pharmacopoeial alignment. MEE incentives for bio-based feedstock utilization accelerate epichlorohydrin-to-glycerin process conversions at domestic API hubs. Ningbo and Taizhou refining clusters expand pharmaceutical-grade capacity to serve domestic generics manufacturers.
India
Maharashtra and Karnataka tertiary care networks consolidate supplier bases toward certified refiners under CDSCO drug master file protocols. PLI schemes for active pharmaceutical ingredients subsidize backward integration into glycerin refining. Gujarat's Kandla and Mundra port corridors narrow the gap between technical-grade output and pharmaceutical-grade supply.
Japan
Tokyo and Osaka prefectures sustain stable prescription volumes for glycerin suppositories amid acute aging demographics. PMDA's stringent methanol and diethylene glycol thresholds filter out non-pharmaceutical glycerin streams from Japan-bound shipments. Kanto region pharmaceutical distributors negotiate three-year supply contracts directly with Malaysian refining complexes.
South Korea
Seoul Capital Area aesthetic medicine channels drive humectant-grade glycerin cream demand through dermatological cosmeceuticals. MFDS maintains pharmacopoeial standards aligned with USP and EP specifications for excipient-grade imports. Busan-Ulsan chemical complexes evaluate captive glycerin refining investments to reduce merchant supply dependence.
Vietnam
Binh Duong province greenfield pharmaceutical plants seek captive glycerin supply partnerships to serve ASEAN export markets. Outpatient facilities source suppository volumes for pediatric constipation protocols through regional distribution networks. Ho Chi Minh City formulation corridors attract Malaysian oleochemical suppliers establishing localized inventory buffers.
Asia-Pacific Pharmaceutical Glycerin Based Products Market Competitive Landscape
Integrated oleochemical majors and merchant refiners split the market between captive supply security and spot-market flexibility. Klang Valley refining complexes control the majority of pharmaceutical-grade export volumes, creating single-geography dependency for non-integrated formulators. Three archetypes dominate: Malaysian palm oil backward-integrated producers, Indian contract manufacturers piloting hybrid purification systems, and European specialty chemical suppliers of ion exchange media. Competitive moves concentrate on long-term offtake agreements displacing spot purchasing and membrane filtration technology licensing compressing certification barriers.
Within the integrated oleochemical tier, KLK OLEO and IOI Oleochemical exemplify Malaysian producers leveraging Klang Valley refining infrastructure to sustain high-purity glycerin flows. P&G Chemicals occupies a position exemplifying USP-grade consistency across multiple production sites. These three anchors represent the spectrum from palm oil backward integration to multi-site pharmaceutical certification, with each archetype responding differently to CDSCO, NMPA, and PMDA pharmacopoeial mandates.
| Leading Market Players |
|---|
| Hunan Er-Kang Pharmaceutical |
| IOI Oleochemical |
| KLK OLEO |
| Kao Corporation |
| Emery Oleochemicals |
| P&G Chemicals |
| Wilmar International Ltd. |
| Oleon NV |
| Hangzhou Oleochemicals |
| Others |
Value Network & Pricing Analysis
Klang Valley oleochemical complexes in Malaysia anchor Asia-Pacific pharmaceutical-grade glycerin capacity, translating upstream palm oil refining dominance into downstream pricing leverage over Indian and Japanese formulators. CDSCO's USP certification mandates and PMDA's residual solvent thresholds compress merchant market liquidity, concentrating price-setting power among backward-integrated producers.
Pricing Analysis
Malaysian spot glycerin quotes trade at sustained premiums to Indian technical-grade benchmarks, reflecting the cost of ion exchange resin purification and dual pharmacopoeial certification. Three-tier pricing structure separates USP-grade parenteral volumes from EP-grade oral excipients and technical-grade industrial supply. Pricing pressure stems from crude palm oil futures volatility transmitting directly to glycerin contract negotiations. Hospital procurement committees in Maharashtra and Karnataka exhibit lowest price sensitivity due to CDSCO-mandated traceability requirements, while smaller Indian formulation plants sourcing through online retail channels face acute cost compression.
Supply Chain Analysis
Indian contract manufacturers in Gujarat and Maharashtra hold growing purification capacity through hybrid ion exchange-membrane filtration systems. Malaysia, Indonesia, and India constitute the geographic supply triangle, with Klang Valley refiners feeding captive demand at Zhejiang API hubs and spot purchases across ASEAN. Raw material flows rest on crude palm oil from Indonesian estates, specialized ion exchange resins from European specialty chemical suppliers, and polyethylene glycol for suppository matrices. Single-source vulnerability concentrates around Malaysian export dominance, with typhoon disruptions to Klang port logistics threatening regional inventory buffers. Distribution runs through direct long-term offtake agreements displacing spot-market purchasing, particularly for parenteral-grade volumes bound for Japanese pharmaceutical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated hospital pharmacy committees and API producers securing captive glycerin supply, fragmenting merchant refiner pricing leverage across Asia-Pacific formulation corridors.
For Market Incumbents: Entrench USP-grade certification moats through backward integration into palm oil refining or captive ion exchange resin recycling capabilities. KLK OLEO and IOI Oleochemical demonstrate how Klang Valley infrastructure investments filter out technical-grade competitors under CDSCO's tightened drug master file protocols. Defensive capacity addition in Gujarat's Kandla corridor counters Indian PLI-scheme subsidized entrants. For New Entrants and Emerging Players: Pursue Vietnam's Binh Duong province greenfield pharmaceutical plants as the most penetrable demand node, where ASEAN export-oriented formulators seek localized glycerin partnerships absent established refiner relationships. Target humectant-grade glycerin cream supply to South Korean aesthetic medicine channels as a margin-accretive entry vector. Go-to-market leverage rests on membrane filtration technology licensing to compress USP certification timelines for mid-scale Indian refiners. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-complexity arbitrage play because pharmacopoeial harmonization lag between USP, EP, ChP, and PMDA standards perpetuates dual-certification inventory inefficiencies. Acquisition targets include Indian contract manufacturers piloting hybrid purification systems and Malaysian oleochemical assets with proven parenteral-grade batch consistency. The signal to watch is NMPA's incorporation of REACH-aligned substance disclosure requirements, which would accelerate supplier base consolidation among Zhejiang and Jiangsu generics producers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Palm Oil Refining | Captive feedstock control insulates Klang Valley producers from crude palm oil futures volatility. |
| Hybrid Purification Technology Licensing | Membrane filtration-molecular distillation systems enable Indian mid-scale refiners to achieve USP certification. |
| Long-term Supply Agreement with Japanese Distributors | Three-year parenteral-grade contracts displace spot purchasing under PMDA batch consistency requirements. |
| Capacity Expansion in Gujarat Corridor | Kandla and Mundra port infrastructure narrows technical-grade to pharmaceutical-grade supply gaps for CDSCO compliance. |
| Green Manufacturing Transition | MEE bio-based feedstock incentives accelerate epichlorohydrin-to-glycerin conversions at Chinese API hubs. |
Research Methodology
Desk research of pharmacopoeial monograph databases, customs trade flows, and SEC filings from listed oleochemical producers preceded structured interviews with refinery operations managers, pharmaceutical excipient procurement leads, CDSCO regulatory affairs specialists, and hospital pharmacy committee directors. Primary fieldwork across Malaysia's Klang Valley, India's Gujarat and Maharashtra corridors, and China's Zhejiang province validated secondary data on capacity utilization and certification timelines. Bottom-up triangulation of refinery output data with top-down formulation plant demand estimates anchored volume projections.
Assumptions held fixed include current USP, EP, ChP, and PMDA pharmacopoeial specifications without anticipating harmonization, prevailing crude palm oil price volatility bands, and sustained CDSCO drug master file traceability mandates. Segmentation modeling spanned product grade tier, end-use application, distribution channel structure, and regional regulatory cluster. CAGRs derived from slope analysis of historical excipient demand elasticity against pharmaceutical output growth across the analysis window. Industry-specific forecast inputs incorporated NMPA pharmacopoeial revision timelines and PLI scheme subsidy disbursement patterns.
Macroeconomic conditions sit as an overlay; deviation in crude palm oil futures, rupee-ringgit exchange rates, or Chinese API export tax incentives would shift the trajectory. Forecasts reflect these assumptions without claiming predictive certainty. Quarterly review of CDSCO certification audit backlogs, Malaysian port logistics indices, and NMPA pharmacopoeial draft revisions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Global Sugar-Based Excipients Market
Pharmaceutical Ingredients
Small-Molecule Injectable Market
Pharmaceutical Ingredients
Co-Crystal Ingredient Market
Pharmaceutical Ingredients
Global Granisetron Market
Pharmaceutical Ingredients
Pharmaceutical Suspension Market
Pharmaceutical Ingredients
Calcium Folinate for Injection Market
Pharmaceutical Ingredients
Synthetic Small Molecule API Market
Pharmaceutical Ingredients
Scopolamine Market
Pharmaceutical Ingredients
Pharmaceutical Thermal Analysis Market
Pharmaceutical Ingredients
North America Active Pharmaceutical Ingredients Market
Pharmaceutical Ingredients
Diclofenac Sodium API Market
Pharmaceutical Ingredients
Fixed-Dose Combination Drugs Market
Pharmaceutical Ingredients
Asia-Pacific Dipeptide Peptidase 4 (DPP-4) Inhibitors Market
Pharmaceutical Ingredients
Antibiotics API Market
Pharmaceutical Ingredients
Folinic Acid Market
Pharmaceutical Ingredients
France Active Pharmaceutical Ingredients (API) Market