
 Pharmaceutical Glycerin Based Products Market | 2026-2036
Pharmaceutical Glycerin Based Products Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmaceutical Glycerin Based Products Market Analysis
Market Context
USP-grade glycerin specification tiers is collapsing into fewer supplier relationships as pharmaceutical buyers consolidate vendor lists. Croda International Plc leverages its oleochemical backbone to secure multi-year glycerin supply contracts with European formulators. Abbott Laboratories anchors its excipient sourcing through backward integration into refined vegetable oil streams. Emery Oleochemicals specializes in high-purity glycerin fractions for parenteral applications, occupying a defensible niche against commodity producers.
Technical Definition and Segment Structure
Pharmaceutical glycerin based products encompass formulations where glycerol serves as an active pharmaceutical ingredient, excipient, or carrier, typically meeting purity thresholds of 99.5% or higher with controlled diethylene glycol limits to prevent toxicity incidents. These products function primarily as osmotic laxatives, demulcents in cough preparations, moisture-retention agents in topical delivery systems, and stabilizers in liquid dosage forms. Glycerin oral solutions lead volume consumption due to established pediatric and geriatric prescribing patterns, while glycerin coatings command premium margins as functional film-forming layers for extended-release tablets. The homecare settings channel is expanding fastest as self-administration protocols and mail-order pharmacy networks reduce hospital dependency for chronic condition management.
Regulatory Environment and Outlook
The US FDA enforces glycerin diethylene glycol contamination limits through import alerts and testing mandates, while the EMA's excipient risk assessment guidelines require documented supply chain qualification for glycerin sourced outside the European Economic Area. India's CDSCO aligns with ICH Q3D elemental impurity standards, compelling domestic refiners to upgrade purification infrastructure or exit pharmaceutical-grade supply. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and IP monographs to anticipate specification divergence that could fragment sourcing strategies.
Market Dynamics
FDA's tightened diethylene glycol limits are forcing pharmaceutical buyers to consolidate supplier relationships around qualified refiners with documented chain-of-custody systems, collapsing the vendor base from commodity traders to certified oleochemical specialists.
Growth Catalysts
- PLI scheme expansion:India's production-linked incentive program for active pharmaceutical ingredients is scaling domestic glycerin consumption as formulation manufacturing concentrates in Gujarat and Hyderabad clusters.
- Parenteral-grade purification:Advancements in molecular distillation and activated carbon filtration are opening injectable applications previously blocked by endotoxin contamination risks.
- EMA excipient risk assessment:European guidelines requiring documented supply chain qualification for imported glycerin are accelerating substitution of Chinese-origin material with EP-certified European production.
Market Restraints
- Palm oil price volatility:Crude glycerin feedstock costs swing with Malaysian and Indonesian biodiesel policy shifts, compressing margin predictability for USP-grade refiners.
- Supplier concentration:Southeast Asian oleochemical complexes control over 60% of refined pharmaceutical-grade output, creating single-source vulnerability for European formulators.
- Diethylene glycol detection limits:FDA's 0.1% contamination ceiling requires gas chromatography-mass spectrometry testing infrastructure that smaller compounders cannot afford.
Strategic Opportunities
- Brazilian ANVISA alignment:Mercosur pharmacopeial harmonization with USP standards is opening export pathways for North American refiners into Latin American generics manufacturing.
- Continuous processing adoption:Integration of real-time release testing with glycerin refining lines enables just-in-time delivery contracts with hospital compounding pharmacies.
- Biobased certification premiums:USDA BioPreferred and EU Green Deal procurement mandates create price premiums for vegetable-derived glycerin over petrochemical alternatives in institutional purchasing.
Industry Challenges
- Analytical chemistry talent scarcity:Qualified chromatography technicians for diethylene glycol and elemental impurity testing command salaries exceeding regional norms in Indian refining hubs.
- Multi-pharmacopeial compliance:Simultaneous USP, EP, and IP certification requires separate validation batches and documentation systems that extend new product introduction timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceutical Glycerin Based Products Market |
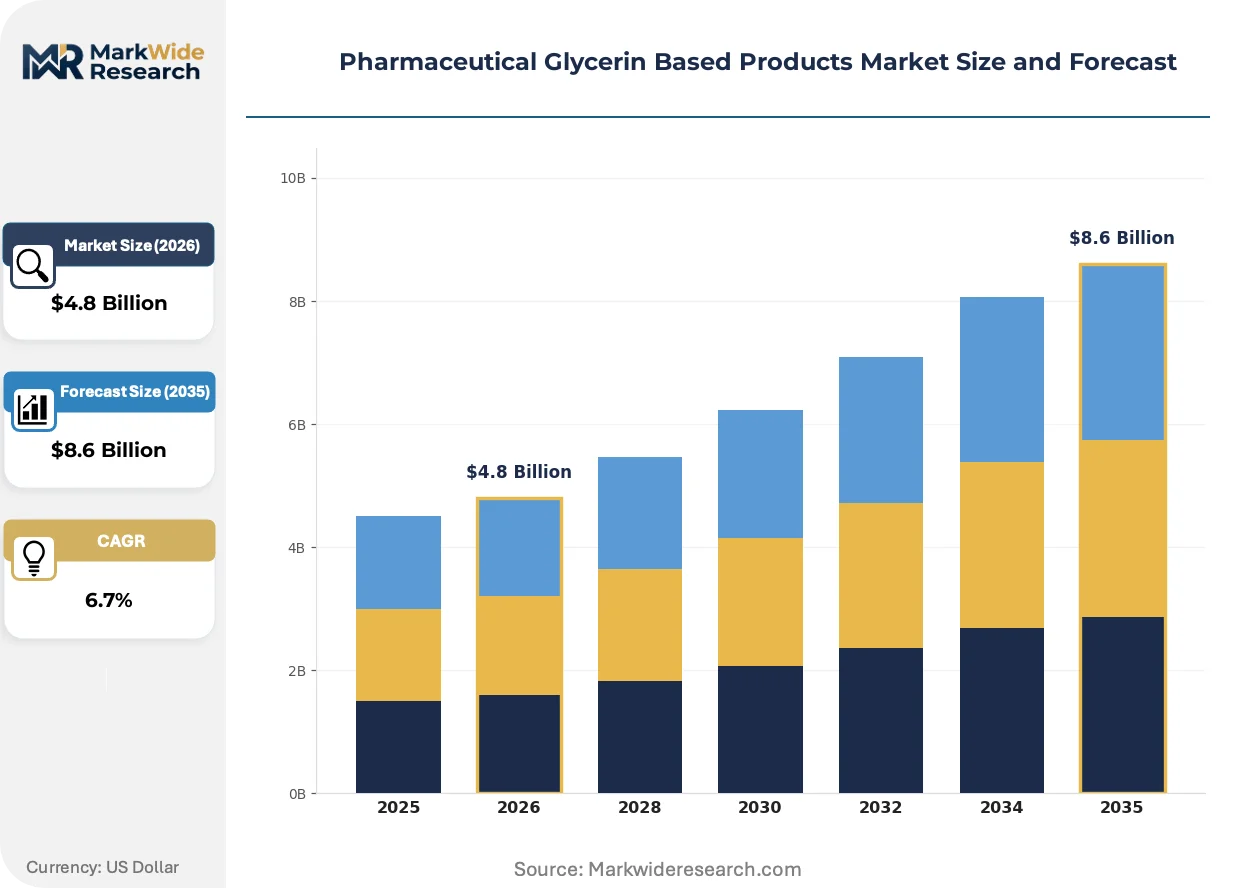
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glycerin Oral Solutions, Glycerin Suppositories, Glycerin Inhalation Solutions, Glycerin Coatings End User: Hospitals, Pharmacies, Clinics, Homecare Settings Formulation: Liquid, Semi-solid, Solid, Gel Packaging Type: Bottles, Blisters, Tubes, Jars |
| Companies Covered | Johnson & Johnson, Abbott Laboratories, AbbVie Inc, Bausch Health Companies Inc, Takeda Pharmaceutical Company, Croda International Plc, Emery Oleochemicals, Dow Inc, Lonza, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceutical Glycerin Based Products Market Emerging Trajectories
Membrane filtration and simulated moving bed chromatography are reshaping purification economics, enabling smaller-batch pharmaceutical-grade production that challenges the scale advantages of traditional oleochemical giants.
Supercritical fluid extraction is supplanting conventional vacuum distillation for high-purity glycerin fractions used in parenteral applications. European injectable manufacturers are adopting this technology to meet endotoxin specifications without multiple reprocessing stages. The shift is compressing capital requirements for entry into pharmaceutical-grade supply, enabling regional refiners to challenge Southeast Asian volume leaders.
REACH authorization requirements for glycerin derivatives are compelling European formulators to document substance volume tracking and safe-use scenarios across extended supply chains. The regulation is accelerating substitution of multi-source commodity purchasing with single-source contractual relationships backed by audit rights. Small molecule generic houses in Eastern Europe are most affected, consolidating around German and Dutch refiners with pre-submitted dossiers.
Hospital procurement departments are unbundling excipient sourcing from finished dosage contracts, creating direct purchasing relationships with glycerin refiners. Mail-order pharmacy networks and central fill operations are displacing traditional wholesale distribution for chronic care formulations. This pattern is most visible in United States integrated delivery networks seeking to capture margin previously retained by contract manufacturers.
Pharmaceutical Glycerin Based Products Market Segmentation
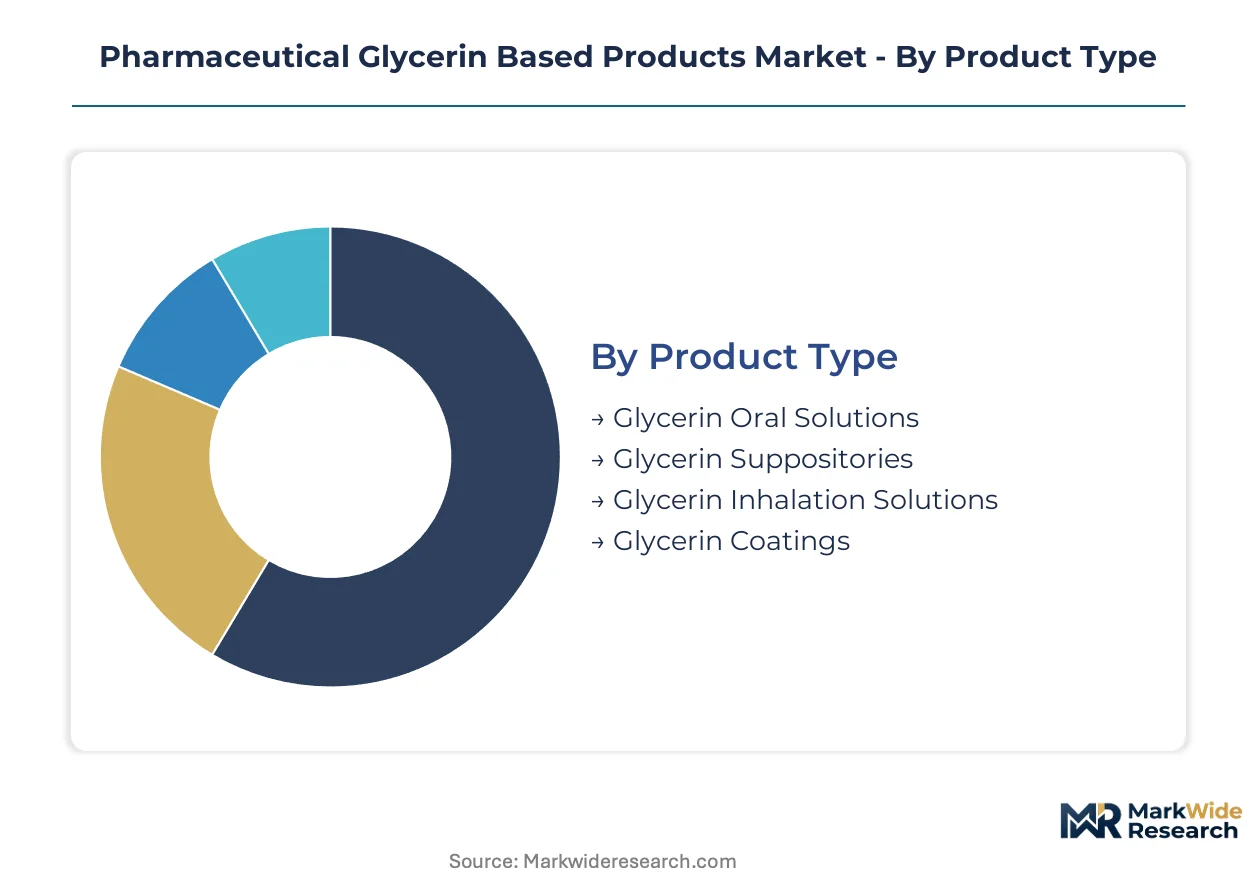
Segmentation in pharmaceutical glycerin markets reveals how purity specifications, distribution channels, and patient administration settings fragment procurement patterns. Each dimension carries distinct regulatory burdens and margin structures that shape supplier qualification strategies.
Product Type:
Domestic consumption concentrates in oral and topical formats, while export-led demand flows toward specialized coatings and inhalation grades requiring advanced purification infrastructure.
- Glycerin Oral Solutions:Pediatric laxative formulations dominate hospital formularies, with USP-grade specifications mandating sub-0.1% diethylene glycol thresholds. Demand clusters in Indian generic houses supplying government procurement contracts under the PLI scheme, constrained by CDSCO batch-release timelines.
- Glycerin Coatings:Functional film-forming layers for extended-release tablets command premium positioning through molecular weight control and viscosity standardization. European formulators in Germany and the Netherlands drive specification tightening as EMA excipient risk assessments mandate documented chain-of-custody.
- Glycerin Suppositories:Rectal delivery systems for constipation management carry localized manufacturing requirements due to temperature-sensitive base compositions.
- Glycerin Inhalation Solutions:Nebulizer-compatible grades require endotoxin limits below 10 EU/g, restricting supply to parenteral-certified refiners with dedicated cleanroom filling lines.
Glycerin oral solutions command the established base. The steepest expansion runs through glycerin coatings.
End User:
Cost tier stratification separates institutional purchasers with direct refiner contracts from retail channels absorbing distributor markups.
- Hospitals:Integrated delivery networks in the United States unbundle excipient sourcing from finished dosage agreements, establishing direct procurement relationships with qualified glycerin refiners. Central fill operations and 503B compounding pharmacies concentrate volume in multi-year supply contracts.
- Homecare Settings:Self-administration protocols for chronic constipation and cough management displace institutional dependency. Mail-order pharmacy networks in North America and Europe capture margin previously retained by wholesale distributors, demanding unit-dose packaging formats.
- Pharmacies:Community retail channels face margin compression from generic substitution policies and reimbursement clawbacks.
- Clinics:Outpatient facilities represent fragmented, low-volume procurement with limited supplier negotiation leverage.
Hospitals anchor volume concentration. Homecare settings are climbing the fastest as patient self-management protocols expand.
Formulation:
Application-driven selection matches glycerin's humectant and solvent properties to route-of-administration requirements and stability profiles.
- Liquid:Oral solutions and syrups leverage glycerin's viscosity-modifying and sweetening characteristics. Indian formulation clusters in Hyderabad and Gujarat scale production under PLI scheme incentives, exporting to African and Latin American markets.
- Semi-solid:Creams and ointments for dermatological applications require compendial-grade glycerin with controlled water content to prevent microbial proliferation.
- Solid:Direct compression tablet formulations utilize spray-dried glycerin derivatives as binders and disintegrants.
- Gel:Mucoadhesive delivery systems for buccal and ophthalmic routes demand ultrapure grades with documented elemental impurity profiles per ICH Q3D.
Liquid formulations hold the volume base. Gel applications show the steepest specification escalation as mucoadhesive platforms proliferate.
Packaging Type:
Customer type and volume scale determine primary versus secondary packaging selection, with institutional buyers favoring bulk formats and retail channels requiring unit-dose compliance.
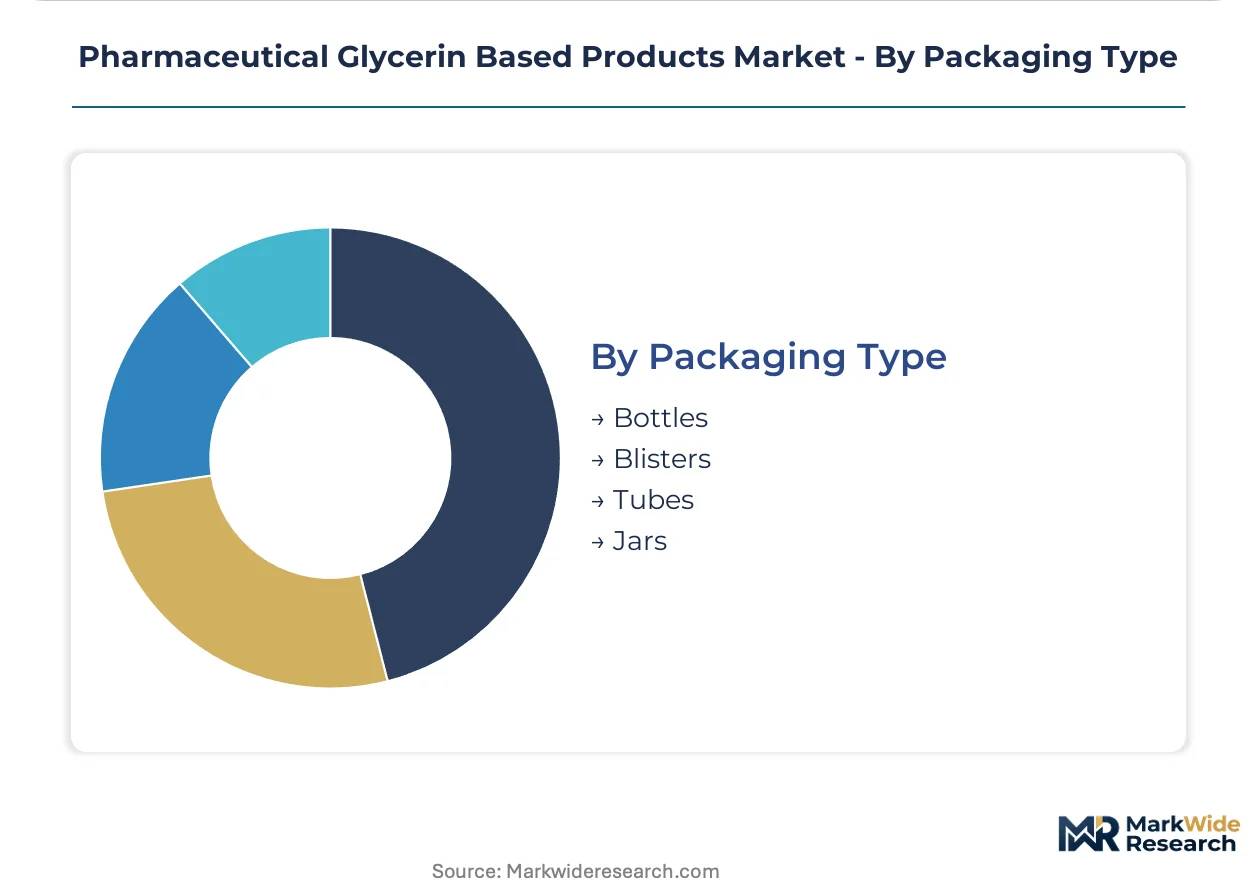
- Bottles:Multi-dose oral solutions for hospital and homecare channels utilize amber glass or HDPE containers with child-resistant closures. German and Dutch refiners supply blow-fill-seal formats for European parenteral applications.
- Blisters:Unit-dose suppositories and solid dosage forms align with compliance packaging mandates in North American institutional purchasing.
- Tubes:Semi-solid topical formulations require laminate or aluminum constructions with oxygen barrier properties.
- Jars:Bulk compounding supply for 503B pharmacies and hospital satellite operations favors wide-mouth containers with nitrogen headspace.
Bottles dominate institutional procurement. Blisters are gaining share fastest as compliance packaging penetrates retail pharmacy networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in pharmaceutical-grade glycerin track divergent regulatory stringency, with surplus jurisdictions exporting into deficit markets where domestic refining capacity lags pharmacopeial compliance requirements. Import dependency concentrates in regions lacking oleochemical infrastructure.
United States
Hospital compounding pharmacies and 503B facilities drive procurement volumes as integrated delivery networks unbundle excipient sourcing from finished dosage contracts. FDA import alerts on diethylene glycol contamination reshape supplier qualification, favoring domestic refiners with documented chain-of-custody systems. New Jersey and North Carolina formulation clusters absorb growing volumes for parenteral applications.
Germany
EMA excipient risk assessment guidelines accelerate substitution of Asian-origin material with EP-certified European production. REACH authorization requirements for glycerin derivatives compel formulators to document substance volume tracking across extended supply chains. The Rhineland refining corridor consolidates around audited single-source relationships with pre-submitted dossiers.
India
CDSCO alignment with ICH Q3D elemental impurity standards forces domestic refiners to upgrade purification infrastructure or exit pharmaceutical-grade supply. PLI scheme incentives for active pharmaceutical ingredients scale glycerin consumption as formulation manufacturing concentrates in Gujarat and Hyderabad clusters. Export volumes to African and Latin American markets expand under government procurement contracts.
Brazil
ANVISA pharmacopeial harmonization with USP standards opens export pathways for North American refiners into Latin American generics manufacturing. Domestic biodiesel policy shifts generate crude glycerin feedstock volatility, compressing margin predictability for local USP-grade refiners. São Paulo state anchors formulation production for Mercosur distribution.
China
NMPA enforcement of glycerin purity specifications tightens alongside national pharmacopeial revisions, though export-oriented production still faces EMA and FDA qualification barriers. Yangtze River Delta oleochemical complexes control refined output volumes, creating sourcing vulnerability for European formulators dependent on imported material. Shandong Province refiners invest in molecular distillation capacity for parenteral-grade fractions.
Pharmaceutical Glycerin Based Products Market Vendor Landscape
Listed leaders compete with private specialists across certification tiers, with publicly traded oleochemical conglomerates commanding scale advantages in multi-pharmacopeial compliance while family-owned refiners defend niche positions in parenteral-grade purification. The vendor base collapses around qualified suppliers as pharmaceutical buyers consolidate vendor lists under tightened FDA diethylene glycol limits. Three archetypes dominate: backward-integrated pharmaceutical conglomerates with captive glycerin supply, independent oleochemical specialists with dedicated pharmaceutical-grade lines, and regional refiners leveraging proximity to formulation clusters. Competitive moves center on multi-year supply contracts with audit rights and continuous processing adoption for just-in-time hospital delivery.
Among diversified healthcare conglomerates, Johnson & Johnson and Abbott Laboratories exemplify backward-integrated positioning through controlled supply chains into refined vegetable oil streams. Croda International Plc occupies the specialist tier, leveraging oleochemical backbone capabilities to secure contractual relationships with European formulators requiring documented chain-of-custody. These three entities represent distinct strategic postures: conglomerate captive supply, independent specialist certification depth, and regional proximity advantage.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Abbott Laboratories |
| AbbVie Inc |
| Bausch Health Companies Inc |
| Takeda Pharmaceutical Company |
| Croda International Plc |
| Emery Oleochemicals |
| Dow Inc |
| Lonza |
| Others |
Supply Flow & Price Mechanics
Substitution of Chinese-origin glycerin with EP-certified European production simultaneously redraws procurement geography and compresses margin spreads for commodity traders lacking certification depth. Pharmaceutical buyers now pay proximity premiums for documented chain-of-custody while penalizing unqualified Asian supply.
Pricing Analysis
Hospital compounding pharmacies anchor contract-based long-term offtake structures for USP-grade material. Price differentiation separates parenteral-certified fractions from oral-grade supply through endotoxin testing infrastructure and molecular distillation investment. Cost compression in standard oral solutions intensifies as Indian PLI scheme participants scale generic output. Retail pharmacy channels exhibit highest price sensitivity due to reimbursement clawbacks, while parenteral manufacturers accept premium positioning for liability protection.
Supply Chain Analysis
Malaysia and Indonesia anchor crude glycerin output through biodiesel policy-linked oleochemical complexes. Refined pharmaceutical-grade production draws from Malaysian palm oil derivatives, Indonesian fatty acid streams, and European rapeseed processing. Single-source vulnerability concentrates in Southeast Asian refining hubs controlling over sixty percent of USP-grade capacity. Distribution runs through direct refiner relationships with hospital integrated delivery networks and 503B compounding facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmaceutical glycerin procurement is shifting toward platform-economy dynamics where EMA-qualified suppliers function as interoperability nodes connecting formulation manufacturers to audit-ready documentation systems.
For Market Incumbents: Secure multi-year supply contracts with audit rights and continuous processing adoption to defend against regional refiners leveraging membrane filtration cost advantages. Backward integration into refined vegetable oil streams anchors supply certainty as FDA diethylene glycol limits tighten. Certification investment in simultaneous USP-EP-IP compliance extends new product introduction timelines but collapses competitor access to multinational formulator vendor lists. For New Entrants and Emerging Players: CDSCO fast-track alignment with ICH Q3D standards opens penetration pathways into Indian generic houses supplying government procurement contracts. Target parenteral-grade purification as the most penetrable tier, where molecular distillation and supercritical fluid extraction compress capital requirements against incumbent scale advantages. Go-to-market positioning centers on just-in-time delivery contracts with hospital compounding pharmacies unbundling excipient sourcing from finished dosage agreements. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European oleochemical specialists holding pre-submitted REACH dossiers and established EMA audit relationships. Five-to-ten year viability hinges on regulatory qualification moats deepening faster than continuous processing technology democratizes entry. Watch FDA import alert expansion on diethylene glycol contamination as the signal indicating vendor base collapse acceleration and acquisition multiple compression for unqualified traders.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Pharmacopeial Certification Investment | Simultaneous USP-EP-IP compliance opens access to multinational formulator vendor lists. |
| Continuous Processing Adoption | Real-time release testing enables just-in-time delivery contracts with hospital compounding pharmacies. |
| Backward Integration into Vegetable Oil Refining | Captive glycerin supply secures margin retention against palm oil price volatility. |
| Parenteral-Grade Purification Infrastructure | Molecular distillation capacity captures premium positioning in injectable applications. |
| Direct Hospital Procurement Relationships | Unbundling excipient sourcing from finished dosage contracts captures distributor margin. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA import alert databases, EMA excipient risk assessment guidelines, and CDSCO batch release records. Interviews with pharmaceutical procurement managers, compounding pharmacy directors, oleochemical plant engineers, and regulatory affairs specialists informed supply chain qualification dynamics. Customs trade data, SEC 10-K filings from listed refiners, and pharmacopeial monograph revisions provided secondary validation. Bottom-up volume modeling from formulation manufacturing clusters triangulated against top-down market sizing from excipient consumption patterns.
Segmentation dimensions modeled include product type, end user channel, formulation route, packaging format, and regional regulatory cluster across the projection horizon. CAGRs derive from weighted average growth across purity tiers with hospital compounding volume trajectories and PLI scheme incentive absorption curves as primary pharmaceutical-grade demand inputs.
The analysis sits within stated boundaries; outcomes outside sustained FDA enforcement intensity, palm oil price stability, or ICH Q3D harmonization progress would require recalibration. Forecasts assume documented supply chain qualification remains the dominant procurement filter. Recalibration cycles align with material shifts in pharmacopeial specification divergence or biodiesel policy reconfiguration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Growth Hormone Inhibiting Hormone Drugs Market
Pharmaceutical Ingredients
Lipids Active Pharmaceutical Ingredient Market
Pharmaceutical Ingredients
Albumin (As Excipient) Market
Pharmaceutical Ingredients
Pharmaceuticals Grade Sodium Bicarbonate Market
Pharmaceutical Ingredients
Active Pharmaceutical Ingredient for Cancer Market
Pharmaceutical Ingredients
Pharmaceutical Desiccants Market
Pharmaceutical Ingredients
Encapsulated Salicylic Acid Market
Pharmaceutical Ingredients
Piperacillin Sodium API Market
Pharmaceutical Ingredients
Pharmaceutical Grade Hyaluronic Acid Market
Pharmaceutical Ingredients
China Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Pharmaceutical Indicator Strips Market
Pharmaceutical Ingredients
Scopolamine Market
Pharmaceutical Ingredients
Pharmaceutical Lactose Market
Pharmaceutical Ingredients
Topical Drugs Market
Pharmaceutical Ingredients
Penciclovir API Market
Pharmaceutical Ingredients
Global Dexamethasone Market