
 North America Cosmeceuticals Market | 2026-2036
North America Cosmeceuticals Market Size, Share, and Industry Trends Forecast 2026-2036
North America Cosmeceuticals Market Insights
ISO 22716 Good Manufacturing Practices certification is bifurcating the competitive landscape into compliant manufacturers and excluded challengers. L'Oréal S.A. leverages its integrated R&D pipeline across dermatological science and consumer marketing to sustain premium positioning. The Estée Lauder Companies Inc. anchors its North American operations through specialty retail partnerships and professional channel control. Johnson & Johnson competes via its heritage in clinical skincare and pharmacy distribution reach.
Cosmeceuticals denote topical preparations containing biologically active ingredients at concentrations sufficient to exert measurable physiological effects on skin structure or function, typically formulated with retinoids, alpha-hydroxy acids, or peptide complexes at pH ranges optimized for epidermal penetration. Skin Care dominates product type revenue due to sustained professional channel demand for anti-aging and corrective treatments, while Peptide-based ingredient formulations represent the fastest-expanding segment as dermatologists validate collagen-stimulating efficacy in clinical settings. Online Retail distribution is displacing department store counter models as telemedicine and subscription-based skincare protocols normalize direct-to-consumer diagnostic tools.
FDA's Over-the-Counter Drug Monograph system and Health Canada's Natural and Non-prescription Health Products Directorate govern ingredient safety thresholds, labeling claims, and pre-market notification requirements across the United States and Canada. State-level board regulations in California and New York further restrict who may administer professional-strength formulations in clinical environments. Stakeholders must monitor evolving classification boundaries between cosmetics and drugs as peptide concentrations and delivery system claims trigger heightened regulatory scrutiny.
Market Dynamics
ISO 22716 Good Manufacturing Practices certification is bifurcating the North American cosmeceuticals competitive landscape, creating compliance moats that exclude challenger manufacturers from professional channel access while concentrating procurement power among certified producers serving dermatology clinics and medical spas.
Growth Catalysts
- FDA Over-the-Counter Drug Monograph alignment:Clarified classification pathways for retinoid and peptide formulations are accelerating professional-grade product development timelines across US dermatology practices.
- Telemedicine subscription protocols:Remote diagnostic platforms in California and New York are normalizing direct-to-consumer prescription skincare, bypassing traditional department store distribution.
- Collagen-stimulating peptide validation:Clinical efficacy data from US and Canadian dermatology settings is expanding reimbursable treatment indications for medical spa channels.
Market Restraints
- Active ingredient supply concentration:Pharmaceutical-grade retinoid and peptide precursor manufacturing concentrates among a limited supplier base in Switzerland and Germany, exposing formulators to input cost volatility.
- Health Canada Natural Health Product notification timelines:Pre-market assessment requirements for novel delivery systems extend product launch windows by 12-18 months versus US FDA pathways.
- Professional administration licensing restrictions:State medical board regulations in California and New York limit high-concentration acid and retinoid application to licensed practitioners, constraining addressable service volume.
Strategic Opportunities
- Underpenetrated Canadian medical spa expansion:Toronto and Vancouver aesthetic medicine clusters show lower professional channel density per capita than comparable US metropolitan markets.
- Biometric-integrated home diagnostic devices:Convergence of spectroscopic skin analysis hardware with AI-powered formulation matching is enabling personalized subscription protocols outside clinical settings.
- Inflation Reduction Act clean manufacturing incentives:US biotechnology production tax credits are reducing capital barriers for domestic peptide synthesis and sustainable packaging investments.
Industry Challenges
- ISO 22716 certification resource intensity:Small and mid-size manufacturers face 18-24 month compliance timelines and six-figure audit costs to access professional distribution channels.
- Peptide concentration claim substantiation:FDA and Health Canada evidentiary standards for structure-function claims require clinical trial investment that strains R&D budgets outside large integrated players.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Cosmeceuticals Market |
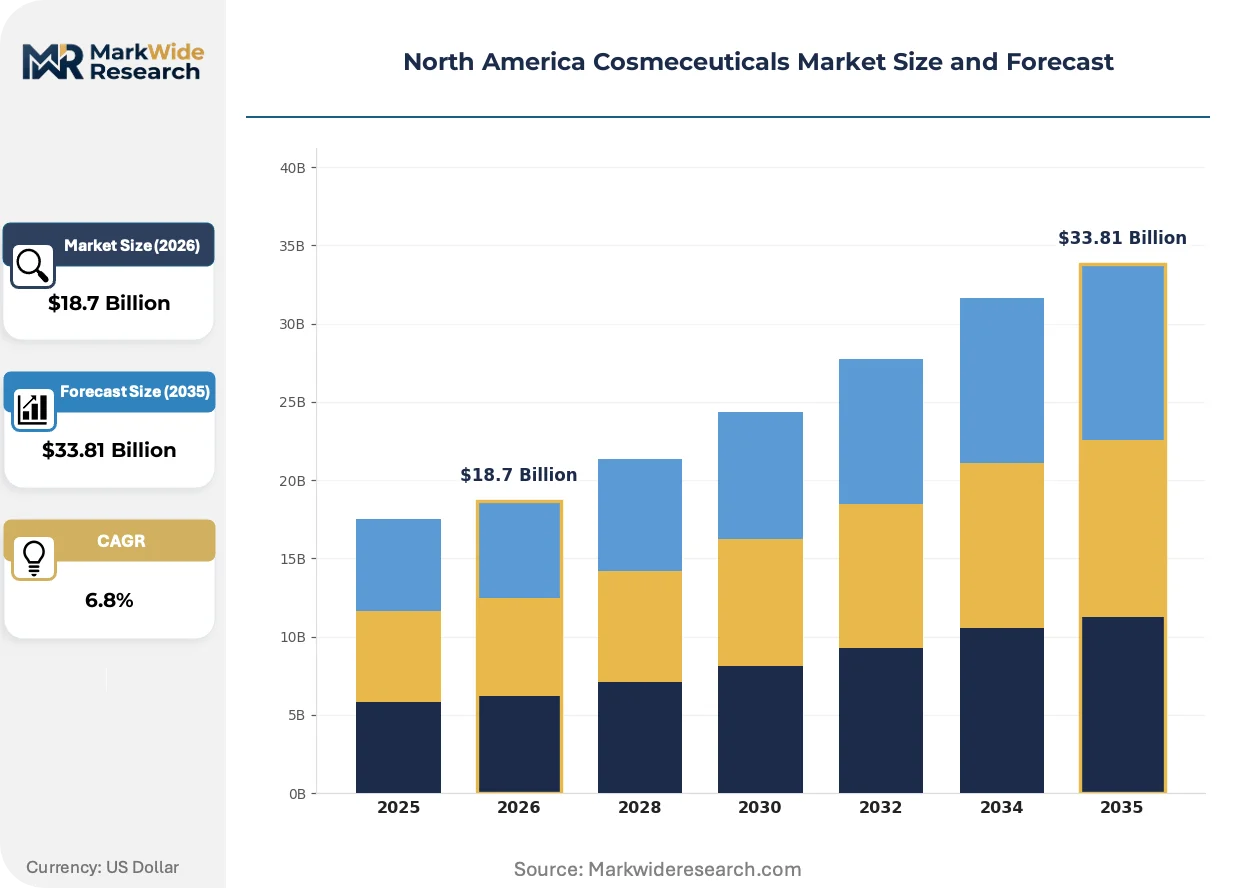
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skin Care, Hair Care, Makeup, Nail Care Ingredient Type: Botanical Extracts, Peptides, Hyaluronic Acid, Retinol Distribution Channel: Online Retail, Specialty Stores, Pharmacies, Department Stores End User: Adults, Seniors, Teenagers, Professionals |
| Companies Covered | L'Oréal S.A., The Estée Lauder Companies Inc., Procter & Gamble Company, Unilever PLC, Shiseido Company, Limited, Johnson & Johnson, Coty Inc., Beiersdorf AG, Kenvue Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Cosmeceuticals Market Trends and Innovations
Microbiome-targeted formulations and biometric personalization are converging to reshape product development priorities across North American cosmeceuticals, shifting competitive advantage from mass-market branding toward clinically validated, data-driven skin health protocols.
Biomimetic peptide complexes engineered for targeted collagen synthesis signaling are supplanting traditional retinoid-first protocols in premium anti-aging formulations. Dermatology clinics in Los Angeles and New York are adopting these actives at accelerating rates for patients with retinoid intolerance. The shift is compressing market share for legacy vitamin-A derivative suppliers while elevating contract manufacturers with peptide synthesis capabilities.
Health Canada's tightened Natural and Non-prescription Health Products Directorate evidentiary requirements for topical drug-cosmetic hybrids are extending pre-market notification assessment periods. Canadian manufacturers are reallocating regulatory affairs resources toward US FDA monograph alignment to maintain competitive launch parity. Professional channel distributors are prioritizing dual-registered inventory to avoid cross-border fulfillment delays.
Subscription-based diagnostic platforms paired with algorithmic formulation customization are disrupting department store counter models. California and New York telemedicine-integrated skincare services are capturing patient cohorts previously served by aesthetic medicine practices. The behavioral pivot is most visible among millennial and Gen-X consumers seeking clinical outcomes without in-clinic visit burdens.
North America Cosmeceuticals Market Segmentation
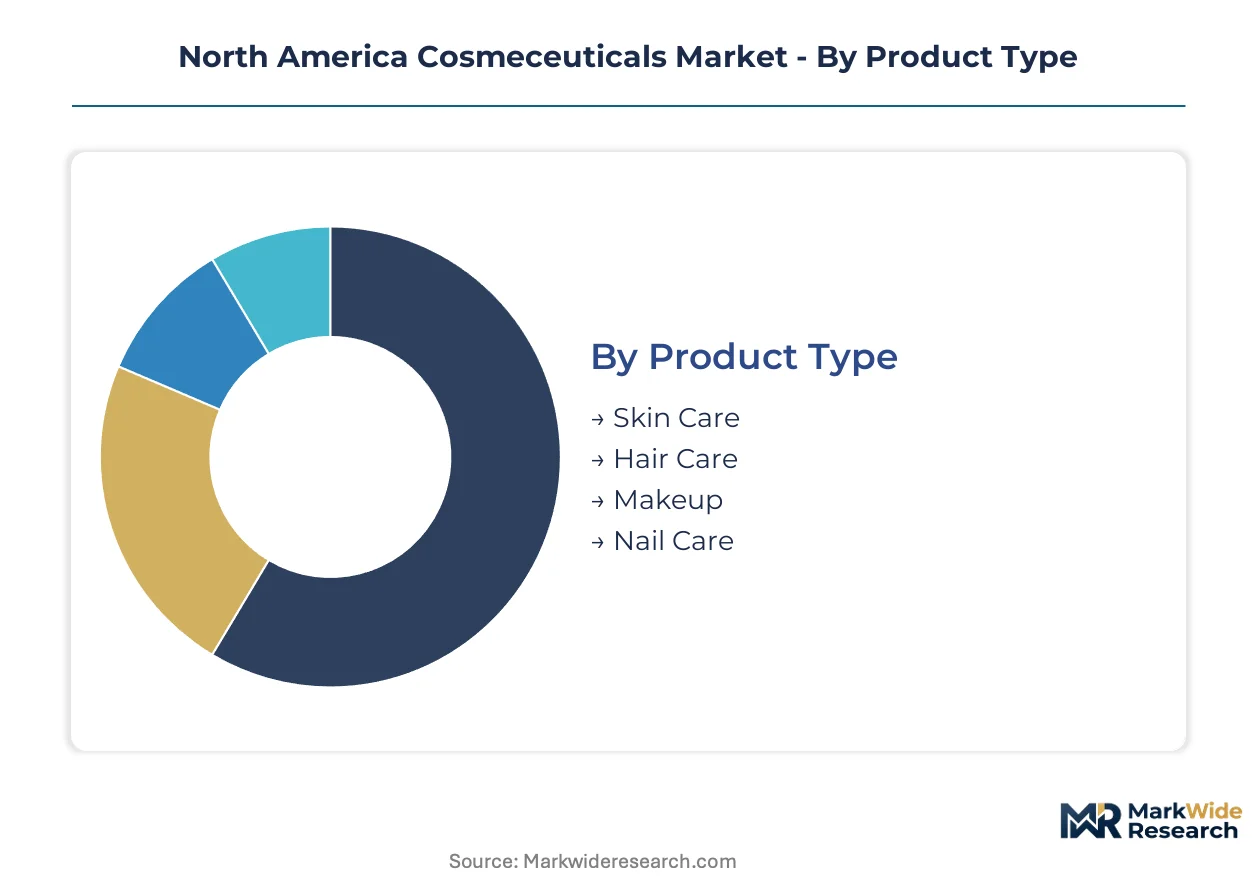
Channel access determines competitive positioning across North American cosmeceuticals, with professional-grade formulations flowing through dermatology clinics while mass-market variants dominate retail shelves. Segmentation clarity reveals where procurement power concentrates and which ingredient technologies command premium positioning.
Product Type:
Skin Care and Hair Care formulations move predominantly through medical spas and specialty retail, while Makeup and Nail Care concentrate in department store and online channels with lower regulatory barriers.
- Skin Care:Topical preparations containing biologically active ingredients at concentrations sufficient to exert measurable physiological effects on skin structure or function. Demand concentrates in California's Los Angeles-San Francisco corridor and New York City's metropolitan aesthetic medicine cluster, driven by dermatology clinic protocols for anti-aging and corrective treatments.
- Hair Care:Scalp-focused cosmeceutical formulations addressing follicular health and density concerns through peptide and botanical delivery systems. Medical spas in Toronto and Vancouver are expanding professional hair restoration protocols faster than comparable US markets, creating channel expansion opportunities.
- Makeup:Hybrid cosmetic-therapeutic products with SPF or skin-conditioning claims regulated under FDA Over-the-Counter Drug Monograph thresholds.
- Nail Care:Cuticle and nail bed treatments incorporating keratin-strengthening peptides and fortifying botanical extracts.
By volume, Skin Care leads. By growth pace, Hair Care is climbing the fastest.
Ingredient Type:
Cost tier stratification separates pharmaceutical-grade synthetics from commodity botanical sourcing, with peptide synthesis commanding premium R&D investment and retinol production benefiting from scale economies.
- Peptides:Biomimetic complexes engineered for targeted collagen synthesis signaling, supplanting traditional retinoid-first protocols in premium anti-aging formulations. Dermatology clinics in Los Angeles and New York are adopting these actives at accelerating rates for patients with retinoid intolerance.
- Retinol:Vitamin A derivatives formulated at pH ranges optimized for epidermal penetration, with concentrations triggering FDA drug classification scrutiny above cosmetic thresholds. Supply concentrates among Swiss and German pharmaceutical-grade manufacturers, exposing formulators to input cost volatility.
- Hyaluronic Acid:Humectant molecules with molecular weight variants determining dermal penetration depth and hydration mechanism.
- Botanical Extracts:Plant-derived actives subject to Health Canada Natural Health Product notification timelines extending launch windows versus US pathways.
By volume, Retinol maintains dominance. By margin capture, Peptides are gaining share fastest.
Distribution Channel:
Customer type segmentation reveals telemedicine platforms capturing patient cohorts previously served by aesthetic medicine practices, while traditional retail loses ground to algorithmic personalization.
- Online Retail:Subscription-based diagnostic platforms paired with algorithmic formulation customization, disrupting department store counter models. California and New York telemedicine-integrated skincare services normalize direct-to-consumer prescription skincare without in-clinic visit burdens.
- Specialty Stores:Professional channel control through dermatology clinic and medical spa procurement, requiring ISO 22716 Good Manufacturing Practices certification for vendor qualification.
- Pharmacies:Clinical skincare distribution leveraging heritage pharmacy networks for over-the-counter drug-cosmetic hybrids.
- Department Stores:Legacy counter models facing displacement as millennial and Gen-X consumers seek clinical outcomes through remote channels.
By transaction volume, Specialty Stores lead. By expansion trajectory, Online Retail is ahead.
End User:
Application maturity varies sharply across demographic cohorts, with professional channel density highest among aging populations seeking corrective interventions and preventive protocols accelerating among younger segments.
- Adults:Core demographic for subscription-based diagnostic platforms and algorithmic formulation customization, concentrated in California and New York metropolitan markets.
- Seniors:Medical spa channel dependence for high-concentration acid and retinoid applications restricted to licensed practitioners under state board regulations.
- Teenagers:Acne-focused cosmeceutical demand flowing through dermatology practices with telemedicine onboarding.
- Professionals:Time-constrained cohort prioritizing clinical outcomes without in-clinic visit burdens, driving biometric-integrated home diagnostic device adoption.
By current spending, Adults dominate. By protocol adoption velocity, Professionals are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA's Over-the-Counter Drug Monograph alignment and Health Canada's Natural Health Product notification pathways are diverging regulatory timelines across North American markets. The Inflation Reduction Act's clean manufacturing incentives are reshaping domestic production economics for peptide synthesis and sustainable packaging investments.
United States
California's Los Angeles-San Francisco corridor and New York City's metropolitan aesthetic medicine cluster concentrate dermatology clinic demand for professional-grade formulations. FDA oversight of retinoid and peptide concentrations above cosmetic thresholds triggers drug classification scrutiny, compressing product development timelines for compliant manufacturers. Telemedicine subscription protocols in these coastal markets normalize direct-to-consumer prescription skincare, bypassing traditional department store distribution channels.
Canada
Toronto and Vancouver aesthetic medicine clusters show lower professional channel density per capita than comparable US metropolitan markets, creating expansion opportunities for medical spa protocols. Health Canada's Natural and Non-prescription Health Products Directorate evidentiary requirements extend pre-market notification assessment periods by 12-18 months versus US pathways. Canadian manufacturers are reallocating regulatory affairs resources toward FDA monograph alignment to maintain competitive launch parity with American counterparts.
Mexico
Mexico City Metro and Nuevo León industrial corridors are emerging as contract manufacturing hubs for US-bound cosmeceutical packaging and formulation assembly. COFEPRIS regulatory convergence with FDA standards is accelerating cross-border supply chain integration for professional-grade skincare brands. Guadalajara's pharmaceutical manufacturing cluster is attracting peptide precursor toll manufacturing investments from North American formulators seeking tariff-advantaged production.
North America Cosmeceuticals Market Competitive Landscape
Player mix skews toward integrated beauty conglomerates with dermatological science capabilities and heritage clinical skincare specialists with pharmacy distribution reach. Market structure concentrates procurement power among ISO 22716-certified manufacturers serving professional channels, while mass-market retail faces displacement from telemedicine-integrated platforms. Three archetypes dominate: R&D-integrated multinationals with dual dermatology-consumer pipelines, clinical heritage players leveraging pharmacy networks, and contract manufacturers with peptide synthesis capabilities. Competitive moves center on specialty retail partnership consolidation and biometric-integrated home diagnostic device development.
Within the R&D-integrated tier, L'Oréal S.A. and The Estée Lauder Companies Inc. exemplify archetypes combining dermatological science investment with consumer marketing infrastructure. Johnson & Johnson occupies a position bridging clinical heritage and mass-market accessibility through its pharmacy distribution foundation. These three anchors represent contrasting pathways to professional channel control: integrated pipeline ownership, specialty retail anchoring, and clinical credibility transfer.
| Leading Market Players |
|---|
| L'Oréal S.A. |
| The Estée Lauder Companies Inc. |
| Procter & Gamble Company |
| Unilever PLC |
| Shiseido Company, Limited |
| Johnson & Johnson |
| Coty Inc. |
| Beiersdorf AG |
| Kenvue Inc. |
| Others |
Pricing and Supply Chain Analysis
ISO 22716 Good Manufacturing Practices certification gates both supplier qualification and price tiering simultaneously, bifurcating North American cosmeceuticals into certified premium channels and excluded mass-market tiers. Professional dermatology clinics and medical spas concentrate procurement power among ISO-compliant manufacturers, while uncertified formulators compete on price in retail channels with compressed margins.
Pricing Analysis
Certification level creates the primary spread between premium professional-grade and economy retail formulations. Pricing stratifies across pharmaceutical-grade peptide concentrations, ISO 22716-certified manufacturing, and commodity botanical sourcing. Cost compression in retail tiers is intensifying because telemedicine platforms bypass traditional markup structures. Dermatology clinics show least price sensitivity due to reimbursable treatment protocols, while mass-market consumers drive hard bargains through algorithmic price comparison.
Supply Chain Analysis
Switzerland and Germany anchor pharmaceutical-grade retinoid and peptide precursor manufacturing, concentrating upstream supply among Swiss specialty chemical houses and German pharmaceutical ingredient specialists. Formulators draw from these sources for active ingredients, while packaging components feed from Mexico's Nuevo León and Guadalajara industrial corridors. Single-source vulnerability runs through Swiss peptide synthesis capabilities. Distribution runs through professional channel distributors requiring dual FDA-Health Canada registration to avoid cross-border fulfillment delays.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward telemedicine-integrated platforms and medical spa chains, fragmenting demand concentration that previously favored department store counters and legacy pharmacy networks.
For Market Incumbents: Secure ISO 22716 certification moats through accelerated audit investment before regulatory disclosure requirements tighten further. Defend professional channel relationships against telemedicine platform disintermediation by embedding diagnostic hardware into clinic protocols. Capacity addition in California and New York medical spa corridors anchors procurement loyalty. For New Entrants and Emerging Players: Lead with biometric-integrated home diagnostic devices to capture millennial and Gen-X professionals seeking clinical outcomes without visit burdens. Toronto and Vancouver medical spa markets show underpenetrated density per capita versus comparable US metros. Direct-to-consumer subscription protocols with AI-powered formulation matching bypass incumbent retail shelf access requirements. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across peptide synthesis and sustainable packaging investments as the Inflation Reduction Act biotechnology production tax credits reduce domestic production barriers. Long-term viability favors contract manufacturers with captive peptide engineering capabilities and dual-jurisdiction regulatory affairs infrastructure. Watch Health Canada notification timeline convergence with FDA pathways as inflection indicator for Canadian manufacturing competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 22716 Certification Acceleration | Professional channel access gates procurement relationships with Los Angeles and New York dermatology clinic networks. |
| Peptide Synthesis Capacity Buildout | Domestic production captures Inflation Reduction Act clean manufacturing incentives while reducing Swiss supplier dependency. |
| Telemedicine Platform Integration | Remote diagnostic protocols bypass department store counter models and capture subscription-based patient cohorts. |
| Dual-Jurisdiction Regulatory Registration | FDA-Health Canada alignment eliminates 12-18 month Canadian launch delays versus US market entry. |
| Biometric Hardware Development | Spectroscopic skin analysis devices enable algorithmic personalization outside clinical settings. |
Research Methodology
A standing panel of dermatology clinic procurement managers, medical spa operations directors, peptide synthesis chemists, and Health Canada regulatory affairs specialists provided ongoing calibration throughout data collection. Primary interviews with these stakeholders combined with secondary validation from FDA Over-the-Counter Drug Monograph filings, Health Canada Natural and Non-prescription Health Products Directorate notification databases, and dermatology clinical trial registries. Bottom-up volume estimates triangulated against top-down market sizing across ingredient type and distribution channel dimensions.
Consistency checks validated volume and value outputs against external benchmarks including customs trade data for peptide precursor imports and professional channel distributor shipment records. The analytical framework modeled product type, ingredient technology, distribution channel, and end-user demographic segments across the projection horizon. CAGRs derived from segment-level growth trajectory analysis incorporating telemedicine adoption curves and medical spa expansion rates. Forecast inputs included regulatory approval timeline assumptions and professional licensing restriction scenarios.
Forecasts assume regulatory continuity in FDA Over-the-Counter Drug Monograph and Health Canada Natural Health Product regimes; material policy shifts would require re-modeling structure-function claim evidentiary standards or peptide concentration classification thresholds. Specific risks include active ingredient supply disruption from Swiss or German manufacturing constraints and state-level medical board licensing restriction expansion. Recalibration cycles align with material shifts in telemedicine reimbursement policy and ISO certification audit requirement updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Chemicals
Anti-Aging and Anti-Wrinkle Products Market
Cosmetic Chemicals
Cosmetic Cetearyl Alcohol Ingredients Market
Cosmetic Chemicals
North America Jojoba Oil Market
Cosmetic Chemicals
Global Argireline Market
Cosmetic Chemicals
Lip Powder Market
Cosmetic Chemicals
Cosmetic UV Absorbers Market
Cosmetic Chemicals
Cosmetic Ingredients Polymers Market
Cosmetic Chemicals
Premium Tattoo Ink Market
Cosmetic Chemicals
Fractionated Shea Butter in Cosmetics and Personal Care Market
Cosmetic Chemicals
Xerosis Market
Cosmetic Chemicals
Herbal Mascara Market
Cosmetic Chemicals
Asia Pacific Cosmetic Preservatives Market
Cosmetic Chemicals
Cosmetic Chemicals Market
Cosmetic Chemicals
Cosmetic Kaolin Powder Market
Cosmetic Chemicals
Gemstone Cosmetics Powder Market
Cosmetic Chemicals
UV Nail Gel Polish Market