
 Fixed-Dose Combination Drugs Market | 2026-2036
Fixed-Dose Combination Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Fixed-Dose Combination Drugs Market Foresight
Multi-source API procurement is hardening as a dominant supply strategy across the fixed-dose combination drugs sector. Pfizer Inc anchors its manufacturing network through captive active pharmaceutical ingredient production in select geographies. Novartis AG differentiates via sustained investment in complex formulation science for antiretroviral combinations. Sanofi S.A. competes by leveraging its established hospital channel relationships across European and Latin American markets.
Fixed-dose combination drugs co-formulate two or more active pharmaceutical ingredients into a single dosage unit, typically manufactured through wet granulation or direct compression to ensure uniform content distribution and bioequivalence. These formulations primarily serve chronic disease management by improving patient adherence and simplifying therapeutic regimens. Tablet formulations occupy the largest volume share due to manufacturing scalability and patient familiarity, while injection formats represent the fastest-growing delivery category driven by biologic-antibiotic combinations. Antiretroviral therapy areas sustain premium pricing power amid ongoing HIV program scale-up, whereas cardiovascular combinations dominate total prescription volume across hospital and clinic settings.
FDA review standards for bioequivalence and therapeutic equivalence shape product development timelines and portfolio prioritization for manufacturers targeting the United States. EMA guidelines on fixed-dose combination quality and clinical requirements influence formulation strategies for European market access, while WHO prequalification programs steer procurement decisions in low- and middle-income countries. Stakeholders must monitor evolving pharmacovigilance obligations and interchangeability designations as these regulatory levers increasingly determine commercial viability and reimbursement positioning.
Market Dynamics
Hospital procurement consolidation is compressing vendor margins while simultaneously demanding broader therapeutic portfolios from fixed-dose combination suppliers. This buyer-side concentration forces manufacturers to reconfigure formulation pipelines around large-volume contract specifications rather than individual product differentiation.
Growth Catalysts
- WHO Prequalification Programs:Low- and middle-income country procurement decisions increasingly favor WHO-prequalified fixed-dose combinations, creating volume commitments that stabilize manufacturing capacity utilization.
- India's Chronic Disease Management Scale-Up:CDSCO streamlining of combination therapy approvals under national non-communicable disease programs accelerates patient access to cardiovascular and diabetes co-formulations.
- Biologic-Antibiotic Synergies:Advances in compatible stabilization chemistry enable novel injectable combinations previously prevented by protein-small molecule incompatibility.
Market Restraints
- API Supply Concentration:Captive production of key antiretroviral actives in China and India creates single-source vulnerability for Western formulation facilities.
- Bioequivalence Study Costs:FDA requirements for multiple-dose pharmacokinetic comparisons between combination and reference products inflate development budgets for complex formulations.
- Generics Substitution Pressure:Pharmacy-level therapeutic substitution protocols in Germany and the United States erode brand loyalty for established combination therapies.
Strategic Opportunities
- Sub-Saharan Africa HIV Program Expansion:PEPFAR and Global Fund procurement volumes for first-line antiretroviral combinations outpace mature market growth rates.
- EMA Adaptive Pathways:Conditional marketing authorization for combinations addressing unmet antimicrobial resistance needs compresses time-to-revenue for novel formulations.
- Direct-to-Clinic Distribution:Bypassing wholesale intermediaries through hospital system direct contracts captures margin previously lost to channel intermediaries.
Industry Challenges
- Formulation Scientist Scarcity:Complex combination development requires expertise in excipient compatibility and dissolution kinetics that outstrips current training program output.
- Legacy Equipment Retrofitting:Existing tablet presses and coating systems require capital-intensive modification to handle multi-layer combination architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fixed-Dose Combination Drugs Market |
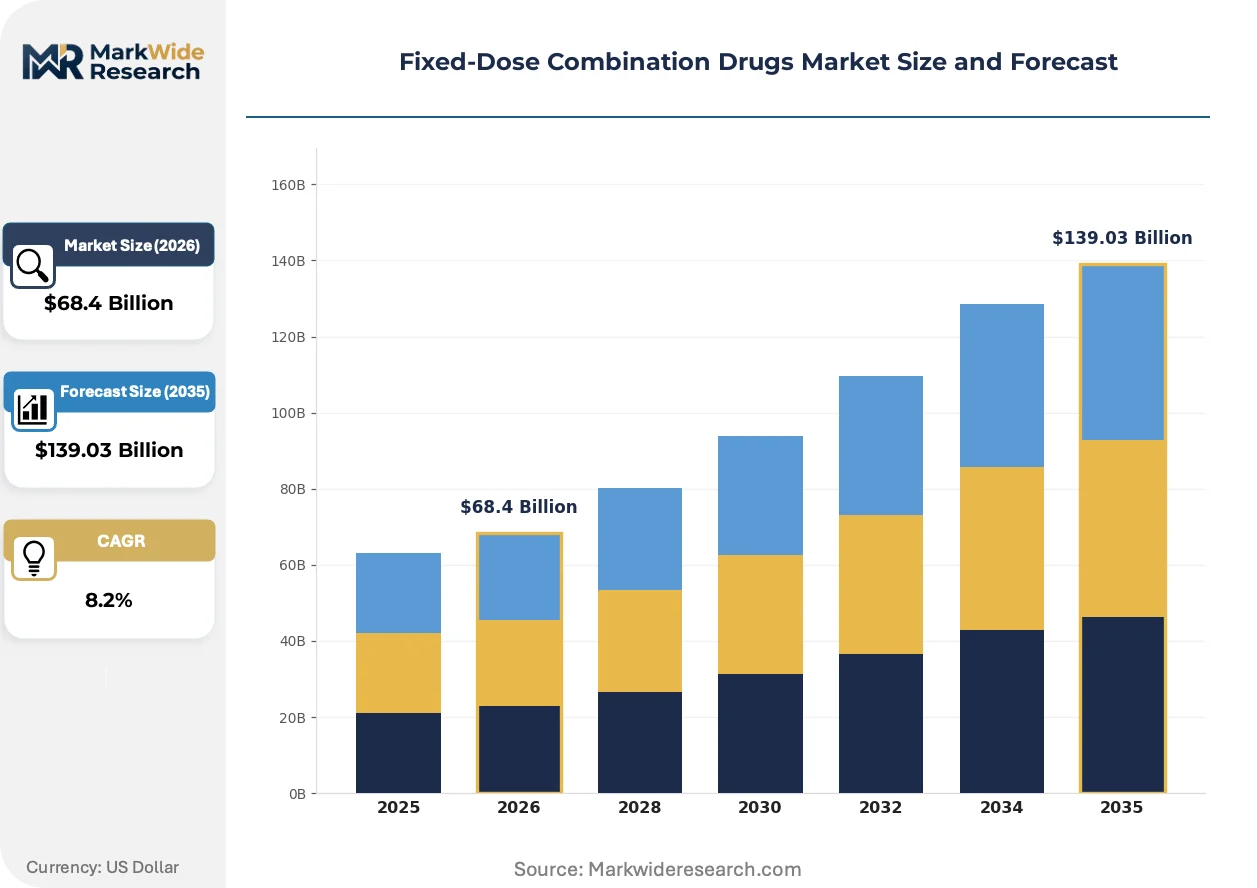
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $139.03 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablet, Capsule, Injection, Syrup, Patch Therapy Area: Cardiovascular, Antiretroviral, Antidiabetic, Respiratory, Gastrointestinal End User: Hospitals, Clinics, Diagnostic Laboratories, Homecare Providers, Specialty Centers Delivery Mode: Oral, Parenteral, Transdermal, Inhalation, Sublingual |
| Companies Covered | Bristol-Myers Squibb Company, AstraZeneca PLC, Pfizer Inc, Johnson & Johnson, Merck & Co., Inc., Novartis AG, Sanofi S.A., AbbVie Inc, GlaxoSmithKline plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fixed-Dose Combination Drugs Market Shifts & Advancements
Continuous manufacturing platforms are displacing batch processing as the dominant production paradigm, enabling real-time release testing and reducing in-process inventory. This shift compresses quality assurance timelines while demanding new skill sets across technical operations.
Hot-melt extrusion technology is consolidating control over poorly soluble active pharmaceutical ingredient distribution within combination matrices. Specialty contract manufacturers in Switzerland and the United States are retrofitting facilities to accommodate this thermal processing approach. The technology is consolidating competitive advantage around firms with demonstrated scale-up capabilities for thermally labile combinations.
EMA's revised guideline on clinical development of fixed-dose combinations mandates earlier demonstration of contribution of each component to overall efficacy. Formulation teams must now design parallel clinical arms rather than sequential add-on studies. Oncology combinations face the steepest compliance burden under this framework, with several sponsors withdrawing development programs rather than expanding trial size.
Hospital pharmacy committees are consolidating formularies around single-source combination contracts rather than maintaining multiple therapeutic alternatives. This concentration transfers pricing leverage from manufacturers to procurement coalitions. The United States and Germany exhibit the most pronounced committee consolidation, with three-hospital systems now representing purchasing volumes previously fragmented across fifteen independent facilities.
Fixed-Dose Combination Drugs Market Segmentation
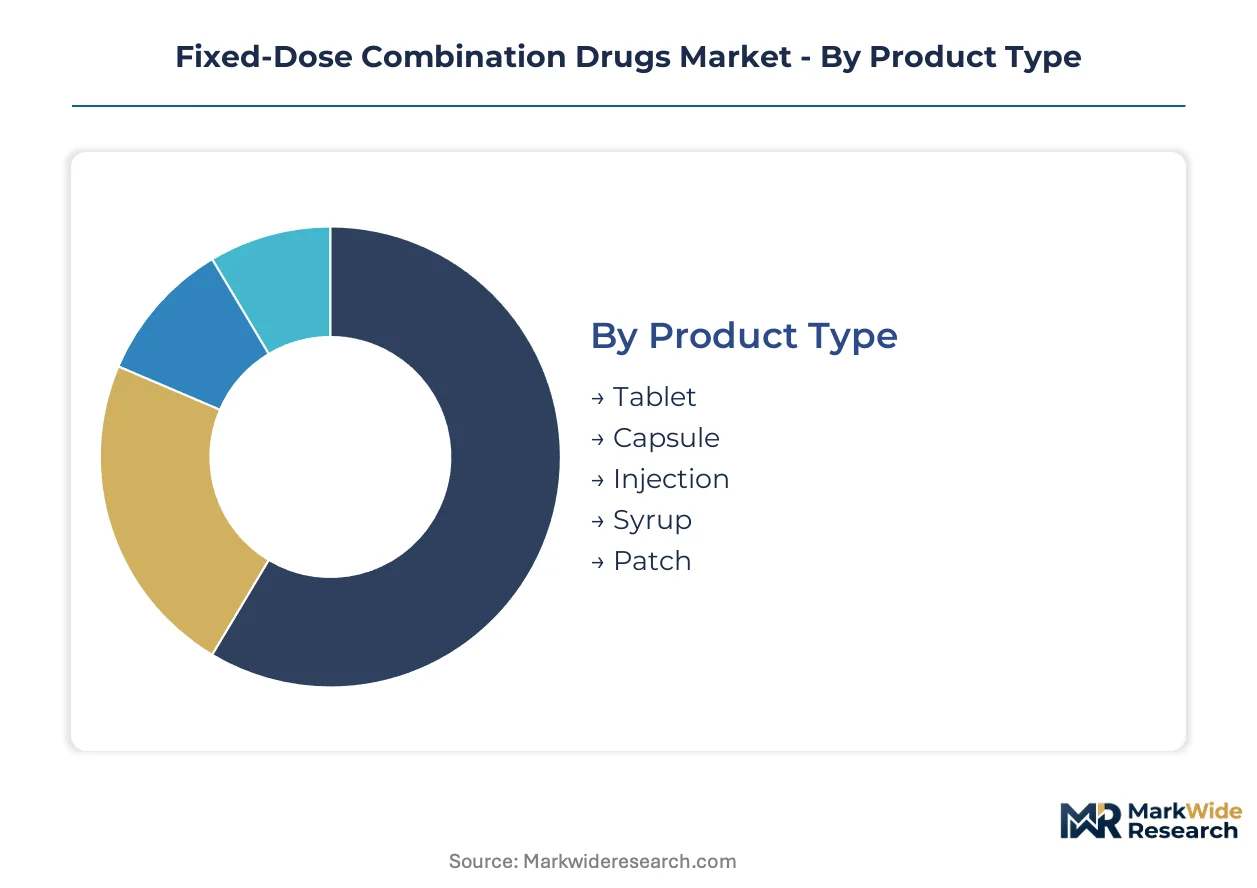
Fixed-dose combination drugs fragment across multiple dimensions that dictate manufacturing investment priorities and regulatory pathway selection. Each segmentation axis reveals distinct margin structures and volume concentration patterns that shape portfolio strategy.
Product Type:
Upgrade cycles in manufacturing equipment favor formats with scalable continuous processing capabilities over legacy batch-dependent architectures.
- Tablet:Wet granulation and direct compression dominate production, with multi-layer architectures enabling incompatible active pharmaceutical ingredient separation. Hospital and clinic procurement in the United States and Germany concentrates volume here due to patient familiarity and reimbursement simplicity. Equipment retrofitting costs for complex geometries constrain mid-tier manufacturer participation.
- Injection:Biologic-antibiotic combinations drive demand as stabilization chemistry advances resolve protein-small molecule incompatibility. Specialty centers and hospital infusion suites in India and Germany adopt these formats for acute care protocols. Cold chain requirements and aseptic fill-finish capacity limit supplier base expansion.
- Capsule:Pellet-based combinations suit gastric pH-sensitive actives through enteric coating flexibility.
- Syrup:Pediatric and geriatric adherence applications favor liquid co-formulations with taste-masking excipients.
- Patch:Transdermal delivery of cardiovascular combinations gains traction in homecare settings with compliance monitoring requirements.
Tablet sits at the top of the volume ranking, with Injection climbing the fastest.
Therapy Area:
Cost tier stratification separates premium-priced antiretroviral programs from high-volume, margin-compressed cardiovascular portfolios.
- Cardiovascular:Hypertension and dyslipidemia combinations command the largest prescription volumes across hospital formularies and retail pharmacy networks. CDSCO streamlining under India's national non-communicable disease program accelerates patient access. Procurement consolidation in German hospital systems compresses vendor margins while demanding broader therapeutic portfolios.
- Antiretroviral:HIV first-line regimens sustain premium pricing through PEPFAR and Global Fund procurement commitments. WHO prequalification requirements filter supplier participation toward manufacturers with demonstrated bioequivalence documentation. Sub-Saharan Africa program expansion outpaces mature market growth rates for volume commitment stability.
- Antidiabetic:Metformin-based combinations face therapeutic substitution pressure in United States pharmacy benefit management protocols.
- Respiratory:Inhaled corticosteroid-long-acting beta agonist pairs require complex device-formulation integration.
- Gastrointestinal:Proton pump inhibitor-antibiotic combinations for Helicobacter pylori eradication follow shorter regulatory review timelines.
Cardiovascular dominates total prescription volume, with Antiretroviral expanding most quickly in value terms.
End User:
Customer type concentration shifts pricing leverage toward procurement coalitions with formulary consolidation authority.
- Hospitals:Pharmacy committee consolidation around single-source combination contracts transfers negotiating power from manufacturers to buyer coalitions. Three-hospital systems in the United States now represent purchasing volumes previously fragmented across fifteen independent facilities. EMA adaptive pathways for antimicrobial resistance combinations target this channel for conditional marketing authorization.
- Clinics:Outpatient chronic disease management programs in India and Germany drive cardiovascular and diabetes co-formulation demand. Direct-to-clinic distribution models bypass wholesale intermediaries to recover margin previously lost to channel intermediaries.
- Diagnostic Laboratories:Companion diagnostic-linked prescribing influences combination therapy selection for targeted populations.
- Homecare Providers:Long-acting injectable and transdermal formats suit adherence monitoring in decentralized care models.
- Specialty Centers:Oncology and infectious disease focused facilities adopt novel combinations under EMA's revised contribution-of-components framework.
Hospitals anchor procurement volume concentration, with Clinics gaining share fastest through chronic disease program scale-up.
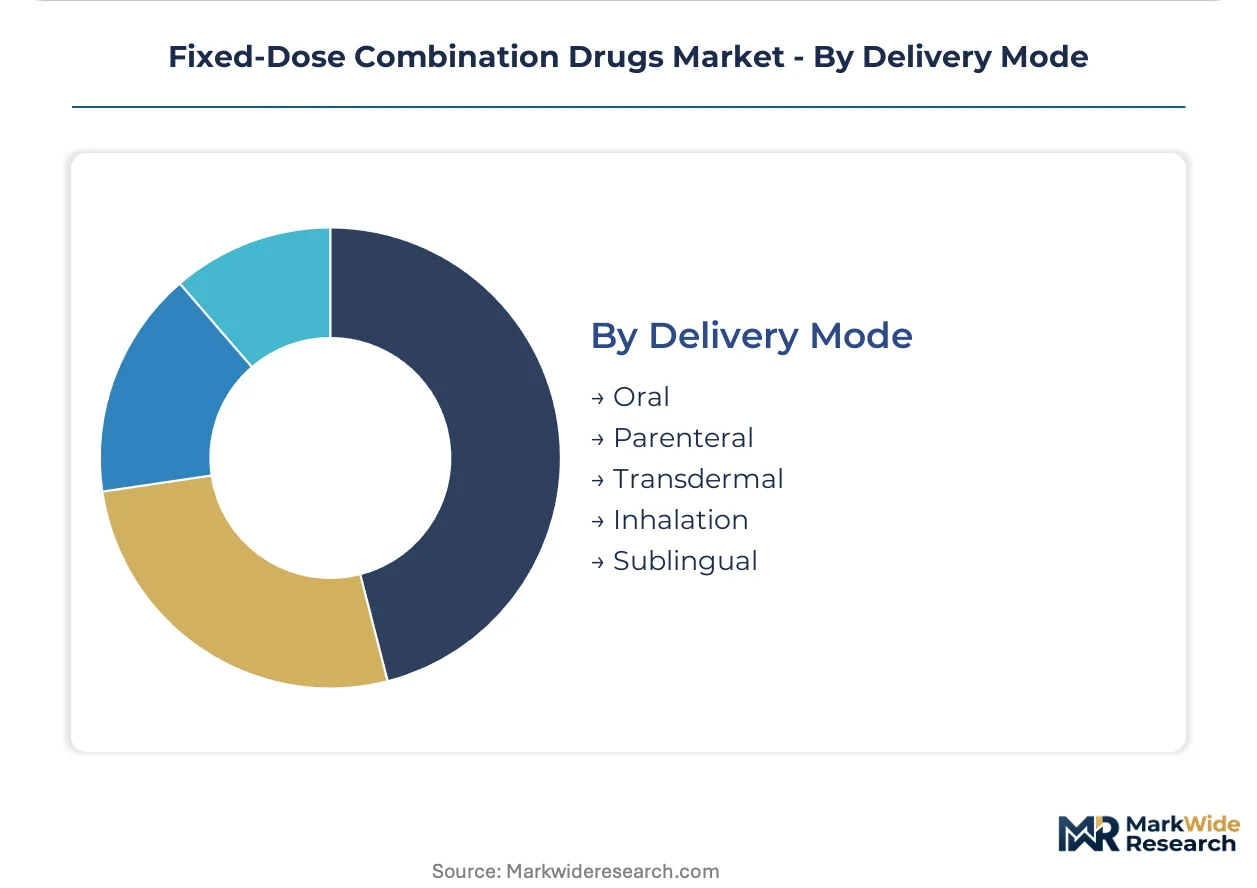
Delivery Mode:
Maturity gradients separate established oral formats from emerging parenteral and transdermal platforms requiring new manufacturing competencies.
- Oral:Tablet and capsule combinations occupy the largest installed base of production equipment and quality control protocols. FDA bioequivalence requirements for multiple-dose pharmacokinetic comparisons between combination and reference products inflate development budgets. Hot-melt extrusion technology retrofits in Switzerland and United States contract facilities address poorly soluble active distribution challenges.
- Parenteral:Injectable combinations gain traction as compatible stabilization chemistry enables previously prevented protein-small molecule formulations. Aseptic processing capacity constraints and formulation scientist scarcity in excipient compatibility and dissolution kinetics limit supplier expansion.
- Transdermal:Patch-based cardiovascular combinations require adhesive matrix expertise and skin permeation modeling capabilities.
- Inhalation:Device-formulation integration complexity and lung deposition studies extend development timelines for respiratory combinations.
- Sublingual:Rapid-onset antiretroviral and cardiovascular formats suit emergency and non-compliant patient scenarios with bypassed first-pass metabolism.
Oral maintains volume leadership, with Parenteral showing the steepest expansion trajectory on biologic-antibiotic synergies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting fixed-dose combination manufacturing toward jurisdictions where bioequivalence study costs and FDA filing fees compress margins less severely. Formulation facilities migrate to India and Eastern Europe while commercial headquarters remain clustered in the United States and Germany.
United States
Hospital pharmacy committee consolidation concentrates procurement leverage among three-hospital systems representing volumes previously fragmented across fifteen independent facilities. FDA streamlined review pathways for certain co-formulated products accelerate commercialization timelines for sponsors with established bioequivalence documentation. The Greater Boston and New Jersey corridors anchor formulation development clusters where contract research organizations support multi-dose pharmacokinetic studies.
India
CDSCO streamlining of combination therapy approvals under the national non-communicable disease program accelerates patient access to cardiovascular and diabetes co-formulations. The country's national pharmaceutical regulator maintains alignment with WHO prequalification standards to secure PEPFAR and Global Fund procurement commitments. Hyderabad and Ahmedabad manufacturing zones expand wet granulation capacity for antiretroviral combinations destined for Sub-Saharan Africa.
Germany
Procurement consolidation across hospital systems compresses vendor margins while demanding broader therapeutic portfolios from fixed-dose combination suppliers. EMA adaptive pathways for antimicrobial resistance combinations enable conditional marketing authorization that compresses time-to-revenue for novel formulations. The Rhine-Main and Bavarian pharmaceutical clusters specialize in complex multi-layer tablet architectures and continuous manufacturing retrofits.
Switzerland
Specialty contract manufacturers retrofit facilities for hot-melt extrusion technology addressing poorly soluble active pharmaceutical ingredient distribution challenges. Swissmedic maintains stringent quality standards that command premium pricing for thermally labile combination exports. The Basel and Zurich regions concentrate formulation science expertise in excipient compatibility and dissolution kinetics.
Brazil
ANVISA harmonization with FDA bioequivalence standards facilitates parallel filing strategies for sponsors targeting Latin American and United States markets simultaneously. Federal chronic disease management program scale-up drives prescription volume for hypertension and dyslipidemia combinations. The São Paulo and Rio de Janeiro metropolitan areas anchor distribution networks serving hospital and clinic procurement coalitions across Mercosur.
Fixed-Dose Combination Drugs Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue complex formulation science and continuous manufacturing capabilities as differentiation vectors. The competitive structure stratifies across three maturity tiers: integrated pharmaceutical conglomerates with captive API production, mid-scale specialists in therapeutic-area combinations, and contract development organizations offering integrated formulation-to-commercial services. Dominant competitive moves include backward integration into active pharmaceutical ingredient supply and strategic partnerships with hospital procurement coalitions for direct-to-clinic distribution.
Within the integrated pharmaceutical tier, Pfizer Inc, Novartis AG, and Sanofi S.A. exemplify divergent strategic positioning. Pfizer anchors manufacturing networks through captive active pharmaceutical ingredient production in select geographies. Novartis occupies a position defined by sustained investment in complex formulation science for antiretroviral combinations. Sanofi sits within the competitive landscape by leveraging established hospital channel relationships across European and Latin American markets.
| Leading Market Players |
|---|
| Bristol-Myers Squibb Company |
| AstraZeneca PLC |
| Pfizer Inc |
| Johnson & Johnson |
| Merck & Co., Inc. |
| Novartis AG |
| Sanofi S.A. |
| AbbVie Inc |
| GlaxoSmithKline plc |
| Others |
Supply & Pricing Matrix
Active pharmaceutical ingredient procurement costs cascade through fixed-dose combination manufacturing tiers, with captive production in India and China anchoring standard-tier pricing while Western contract facilities command premiums for thermally labile formulations requiring Swiss hot-melt extrusion capabilities.
Pricing Analysis
Input-cost pass-through from API concentration in Asian manufacturing zones stratifies pricing across three tiers: WHO-prequalified antiretroviral combinations for Sub-Saharan Africa procurement, standard cardiovascular formulations for hospital formulary contracts, and premium complex multi-layer tablets for European specialty centers. Price differentiation hinges on bioequivalence documentation depth and cold-chain handling requirements. Pricing pressure intensifies in the standard tier as German and United States hospital procurement consolidation squeezes vendor margins. Clinic buyers in India exhibit highest price sensitivity due to national non-communicable disease program budget constraints, while Swiss specialty manufacturers serving oncology combinations face least sensitivity.
Supply Chain Analysis
Reverse-logistics flows for temperature-deviated biologic-antibiotic combinations remain underdeveloped, with most injectable returns diverted to destruction rather than refurbishment due to sterility assurance complexity. API supply concentrates in India, China, and Switzerland for formulation-stage processing. Raw material dependencies center on antiretroviral actives, cardiovascular beta-blockers, and diabetes metformin derivatives. Single-source vulnerability in Chinese captive production of key HIV APIs threatens Western formulation continuity. Distribution runs through hospital procurement coalitions in the United States and Germany, with direct-to-clinic models gaining traction in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fixed-dose combination manufacturing rewards geographic arbitrage between FDA filing-fee jurisdictions and CDSCO-aligned Indian production zones, where bioequivalence study costs compress development budgets by regulatory differential.
For Market Incumbents: Anticipate formulary consolidation pressure in German hospital systems by securing backward integration into Indian API supply and accelerating continuous manufacturing retrofits in Rhine-Main facilities. Defensive positioning requires preemptive WHO prequalification for antiretroviral portfolios before PEPFAR procurement windows narrow. Channel control through direct-to-clinic contracts recovers margin lost to wholesale intermediaries. For New Entrants and Emerging Players: Enter via biologic-antibiotic injectable combinations where formulation scientist scarcity has frozen incumbent capacity expansion. Sub-Saharan Africa HIV program procurement offers the most penetrable geography, with PEPFAR volumes outpacing mature market growth. A go-to-market angle through EMA adaptive pathways for antimicrobial resistance combinations compresses time-to-revenue against traditional regulatory timelines. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-scale specialists lack captive API production and continuous manufacturing capabilities. Five-to-ten-year viability favors targets with demonstrated hot-melt extrusion scale-up and WHO prequalification track records. Acquisition target archetype: Indian manufacturers with CDSCO-aligned cardiovascular portfolios seeking European market access. Monitor EMA contribution-of-components guideline enforcement as inflection signal for oncology combination program withdrawals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into API Production | Captive supply of antiretroviral actives insulates against Chinese single-source vulnerability for Western formulation facilities. |
| Continuous Manufacturing Retrofit | Real-time release testing adoption in Rhine-Main and Bavarian clusters compresses quality assurance timelines for multi-layer tablets. |
| WHO Prequalification Pursuit | PEPFAR and Global Fund procurement commitments stabilize capacity utilization for Hyderabad and Ahmedabad manufacturers. |
| Direct-to-Clinic Distribution | Bypassing wholesale intermediaries through hospital system contracts recovers margin previously lost to channel intermediaries. |
| EMA Adaptive Pathway Navigation | Conditional marketing authorization for antimicrobial resistance combinations targets German hospital pharmacy committees for accelerated access. |
Research Methodology
Direct dialogue with drug development executives, regulatory affairs leads, hospital procurement managers, and formulary directors grounded qualitative insights in operational reality. Secondary validation drew from FDA bioequivalence filings, EMA fixed-dose combination guidelines, WHO prequalification records, and ClinicalTrials.gov protocol registries. Bottom-up prescription volume modeling and top-down therapeutic-area expenditure analysis were triangulated against manufacturing capacity disclosures.
Bottom-up segmentation across product type, therapy area, end user, and delivery mode dimensions fed volume and value projections across the analysis window. CAGRs were derived from fitted growth curves against historical procurement data and regulatory approval velocity. Forecast inputs included CDSCO approval streamlining timelines, PEPFAR procurement commitment trajectories, and EMA guideline revision implementation rates.
Inputs from FDA, EMA, and WHO regulatory databases were available through the study window; gaps in real-time hospital formulary contract terms introduce uncertainty bands around vendor margin estimates. Forecasts reflect assumptions about procurement coalition consolidation velocity and bioequivalence study cost inflation. Practitioners should monitor EMA contribution-of-components enforcement actions and Indian PLI scheme API manufacturing incentives for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Scopolamine Market
Pharmaceutical Ingredients
Glycylglycine Market
Pharmaceutical Ingredients
Calcium Folinate for Injection Market
Pharmaceutical Ingredients
Global Small Molecule API Market
Pharmaceutical Ingredients
Hyaluronic Acid Raw Material Market
Pharmaceutical Ingredients
Global Glycine Supplement Market
Pharmaceutical Ingredients
Active Pharmaceutical Ingredient for Cancer Market
Pharmaceutical Ingredients
Global High Potency Active Pharmaceutical Ingredient (HPAPI) Market
Pharmaceutical Ingredients
Oral Doxycycline Hyclate Market
Pharmaceutical Ingredients
Pemetrexed Market
Pharmaceutical Ingredients
Nuclear Export Inhibitor Drugs Market
Pharmaceutical Ingredients
Fipronil Market
Pharmaceutical Ingredients
Mrna Synthesis Raw Materials Market
Pharmaceutical Ingredients
Pharmaceutical Lactose Market
Pharmaceutical Ingredients
Calcium Gluconate Market
Pharmaceutical Ingredients
Pharmaceutical Grade Magnesium Hydroxide Market