
 Synthetic Small Molecule API Market | 2026-2036
Synthetic Small Molecule API Market Size, Share, and Industry Trends Forecast 2026-2036
Synthetic Small Molecule API Market Intelligence
Indian contract manufacturers is realigning global supply chains for generic APIs after pandemic-era shortages exposed geographic vulnerabilities. Lonza leverages its Swiss-based continuous manufacturing platforms to command premium pricing for complex oncology intermediates. Pfizer sustains vertical control over high-potency compound development through captive facilities in Ireland and Singapore. Teva Pharmaceuticals anchors its competitive stance on cost-optimized fermentation-to-synthesis integration across Eastern European sites.
Synthetic small molecule APIs constitute chemically synthesized, low-molecular-weight organic compounds—typically below 900 Daltons—engineered to modulate specific biological targets through defined pharmacokinetic profiles. These entities serve as the therapeutic backbone of oral solid dosage forms, with purity specifications often exceeding 99.5% and impurity profiles governed by ICH Q3A/Q3B thresholds. Active pharmaceutical ingredients dominate value capture, though intermediates are gaining structural importance as sponsors fragment synthesis across multiple contract partners to protect intellectual property. Oncology commands the steepest investment intensity within therapy areas, driven by cytotoxic and targeted small-molecule portfolios, while cardiovascular applications maintain volume leadership amid statin and antihypertensive commoditization. Contract manufacturers occupy the fastest-expanding end-user channel as biotech firms without captive chemistry capabilities outsource development-to-commercial pathways.
FDA cGMP inspections, EMA REACH compliance for solvent residuals, and ICH M7 mutagenic impurity guidelines collectively elevate barrier costs for market entry while favoring incumbents with dedicated regulatory affairs infrastructure. The EU AI Act's emerging transparency requirements for algorithmic process control may soon extend to AI-driven reaction optimization platforms, adding a compliance layer to digital chemistry investments. Stakeholders must monitor how CDMO consolidation affects pricing leverage and whether India's PLI scheme for active pharmaceutical ingredients reshapes regional competitive dynamics.
Market Dynamics
Patent cliffs across oncology portfolios are compressing sponsor timelines and fragmenting synthesis steps across multiple contract partners to protect intellectual property.
Growth Catalysts
- EMA's tightened impurity guidelines:Manufacturers must retool analytical capabilities, creating upgrade demand for advanced chromatography and mass spectrometry systems.
- Oncology drug developers:Biotech firms without captive chemistry capabilities are outsourcing development-to-commercial pathways at accelerating rates.
- Continuous manufacturing platforms:Swiss and Irish facilities deploy flow chemistry to reduce solvent volumes and accelerate batch release timelines.
Market Restraints
- Starting material concentration:KSM supply for complex heterocycles concentrates among Chinese intermediates specialists, exposing sponsors to single-source risk.
- FDA cGMP inspection backlog:Delayed site approvals extend commercialization timelines for new molecular entities by 8-14 months.
- High-potency compound containment:Isolator technology and dedicated HVAC infrastructure require capital outlays that exclude mid-tier entrants.
Strategic Opportunities
- India's PLI scheme for APIs:Dedicated small-molecule campuses in Hyderabad and Ahmedabad attract Western sponsors seeking supply chain redundancy.
- AI-driven reaction optimization:Machine learning platforms predict yield and selectivity, compressing route scouting from months to weeks.
- Biotech CDMO partnerships:Virtual pharma sponsors seek integrated CMC packages spanning synthesis, formulation, and regulatory filing.
Industry Challenges
- Process analytical technology integration:Legacy batch systems resist retrofit for real-time release testing, forcing greenfield investments.
- Mutagenic impurity assessment:ICH M7 guideline compliance demands specialized toxicology expertise scarce among mid-size CROs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Synthetic Small Molecule API Market |
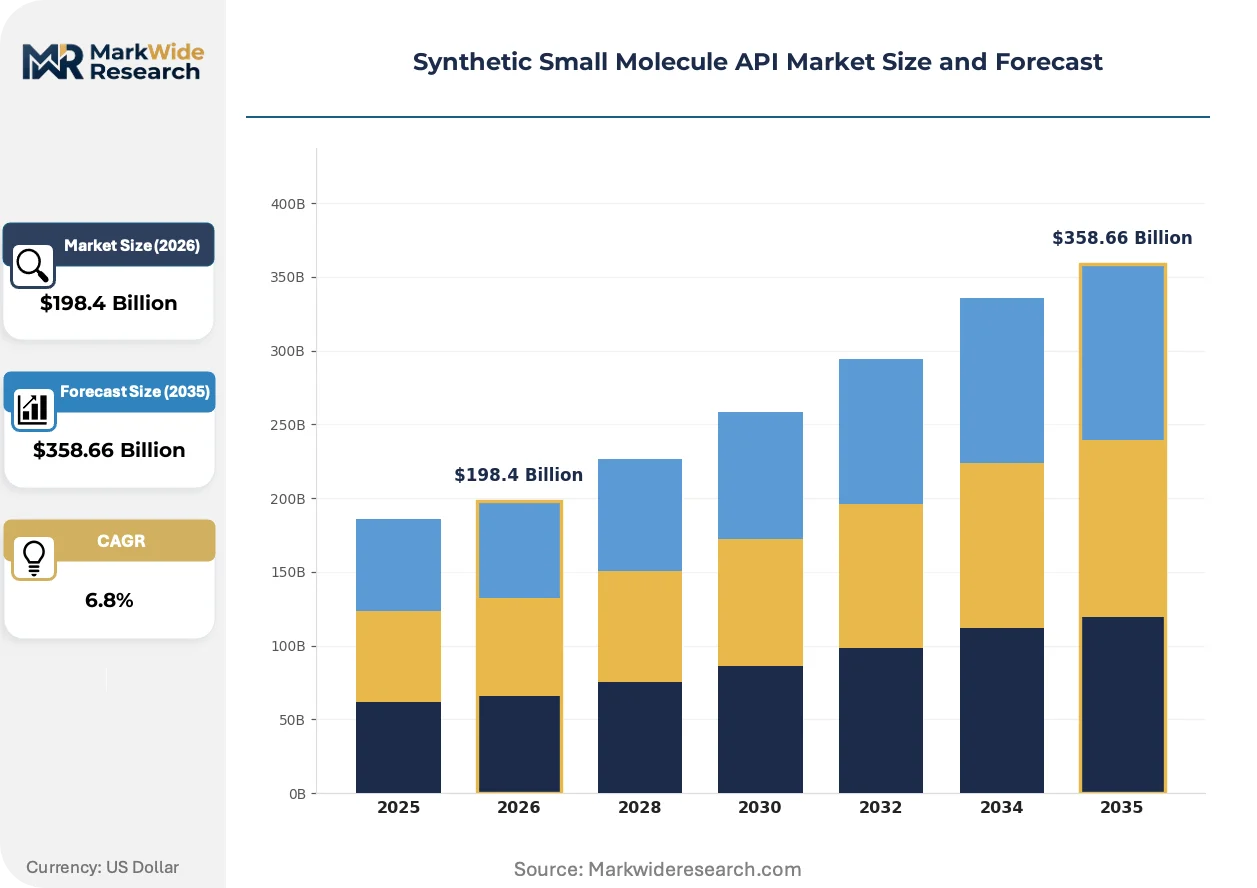
| Market Size in 2026 | $198.4 Billion |
| Market Size in 2035 | $358.66 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Pharmaceutical Ingredients, Intermediates, Excipients, Prodrugs Manufacturing Stage: Development, Commercial Production, Scale-Up, Validation Therapy Area: Oncology, Cardiovascular, Neurology, Infectious Diseases End User: Pharmaceutical Companies, Biotech Firms, Contract Manufacturers, Research Institutions |
| Companies Covered | Lonza, Cambrex Corporation, Pfizer, EUROAPI, Biocon, Teva Pharmaceuticals, Thermo Fisher Scientific (Patheon), Catalent, Sun Pharmaceutical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Synthetic Small Molecule API Market Strategic Shifts & Innovations
Digital chemistry platforms and modular manufacturing architectures are compressing development cycles while regulatory frameworks adapt to algorithmic process control.
Flow chemistry is integrating continuous processing into multi-step syntheses previously executed in batch reactors. Mid-size CDMOs in Switzerland and Singapore adopt skid-mounted units to reduce solvent consumption and improve heat transfer for exothermic reactions. This integration is enabling real-time parameter adjustment that compresses tech transfer timelines between development and commercial sites.
REACH compliance for solvent residuals is forcing manufacturers to substitute classical chlorinated solvents with 2-MeTHF and cyclopentyl methyl ether. ECHA's updated authorization lists elevate barrier costs for legacy processes while favoring entrants with green chemistry capabilities. Generics producers in Eastern Europe respond by retrofitting recovery systems to close solvent loops and reduce virgin material intensity.
Virtual pharma sponsors are consolidating vendor relationships from fragmented CRO-CMO networks toward integrated CDMO partnerships. Biotech firms without internal chemistry functions now seek single-source accountability for IND-enabling through commercial supply. This concentration is most visible in the Boston-San Diego corridor where sponsors prioritize regulatory track record over unit cost in supplier selection.
Synthetic Small Molecule API Market Segmentation
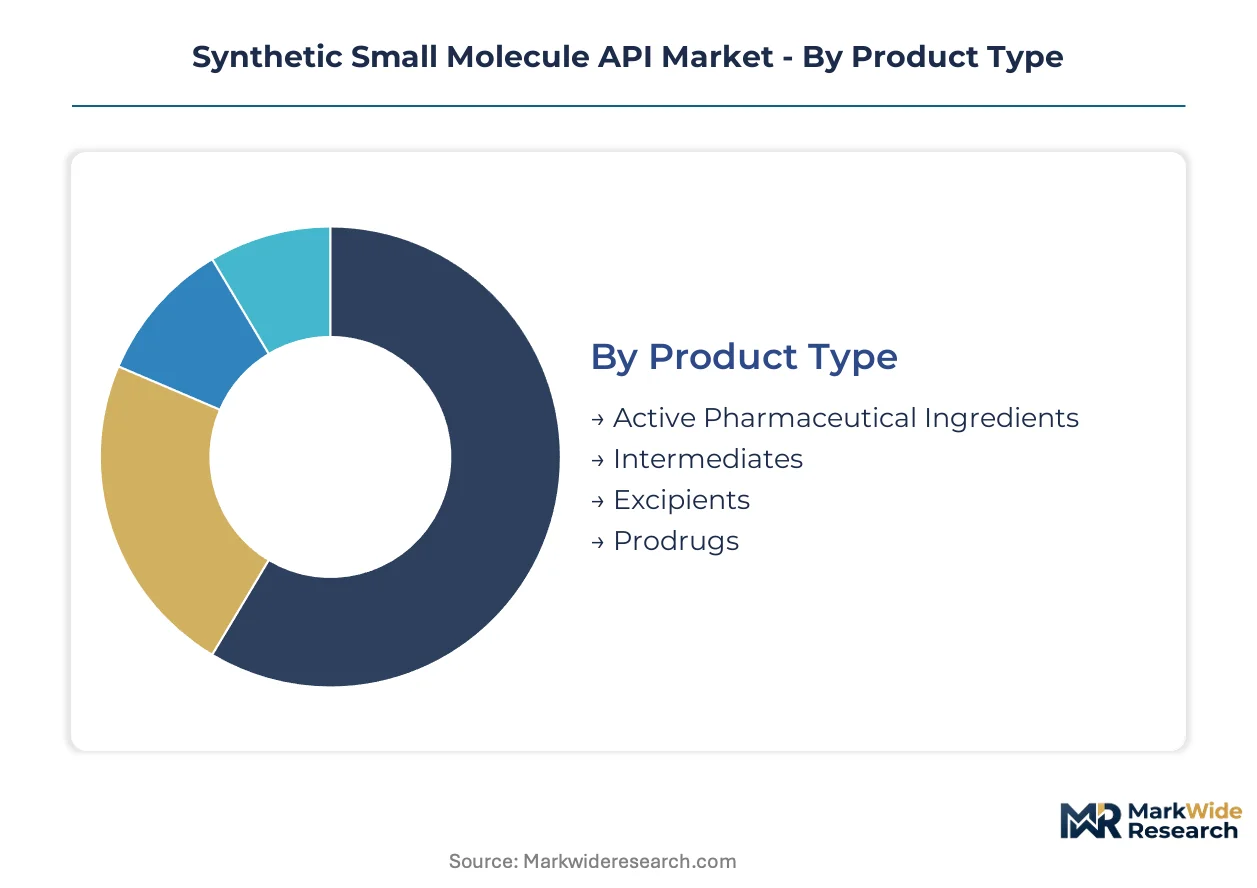
Synthetic small molecule APIs fragment across four critical dimensions that determine capital deployment, regulatory exposure, and margin capture. Product type and manufacturing stage govern fixed asset intensity, while therapy area and end-user channel shape pricing power and contract structure.
Product Type:
Capital intensity peaks with high-potency active pharmaceutical ingredients requiring isolator suites and dedicated HVAC infrastructure, while intermediates demand less containment but greater IP fragmentation across contract networks.
- Active Pharmaceutical Ingredients:Chemically synthesized organic compounds below 900 Daltons with purity specifications exceeding 99.5%. Demand concentrates in oncology applications where Swiss and Irish facilities command premium pricing for cytotoxic compounds under FDA cGMP and EMA REACH oversight.
- Intermediates:Synthetic precursors and key starting materials fragmented across multiple contract partners to protect intellectual property. Indian CROs in Hyderabad and Ahmedabad capture expanding Western sponsor volumes as patent cliffs compress internal capacity.
- Excipients:Pharmacologically inactive formulation components enabling drug delivery and stability.
- Prodrugs:Biologically inactive compounds metabolized to active therapeutic moieties.
Most installed capacity flows through Active Pharmaceutical Ingredients. Expansion is steepest in Intermediates.
Manufacturing Stage:
Cost tier stratification separates development-phase flexibility from commercial-scale validation burdens, with scale-up representing the critical margin compression zone.
- Commercial Production:Validated batch or continuous manufacturing under FDA cGMP and EMA quality guidelines. Lonza's Swiss continuous platforms and Pfizer's Irish captive facilities anchor supply for high-volume oncology portfolios.
- Development:Route scouting and early-phase synthesis requiring rapid iteration without full validation. Biotech firms without captive chemistry outsource these functions to CDMOs offering integrated CMC packages.
- Scale-Up:Technology transfer from lab to pilot to commercial volumes.
- Validation:Process qualification and regulatory filing preparation.
Commercial Production absorbs the majority of fixed asset depreciation. Development is gaining share fastest among virtual pharma sponsors.
Therapy Area:
Application-driven volume concentration in cardiovascular statins contrasts with oncology's investment intensity and pricing power.
- Oncology:Cytotoxic and targeted small-molecule portfolios commanding the steepest investment intensity. FDA cGMP inspections and EMA tightened impurity guidelines force retooling of analytical capabilities for mutagenic impurity assessment under ICH M7.
- Cardiovascular:Statins and antihypertensives maintaining volume leadership amid commoditization. Eastern European generics producers leverage cost-optimized fermentation-to-synthesis integration.
- Neurology:CNS-penetrant compounds requiring specialized formulation expertise.
- Infectious Diseases:Antiviral and antibacterial APIs facing procurement pressure.
Cardiovascular commands the greatest production volume. Oncology shows the steepest expansion trajectory.
End User:
Customer type determines contract structure, with biotech firms seeking integrated partnerships and Big Pharma retaining high-potency captive capacity.
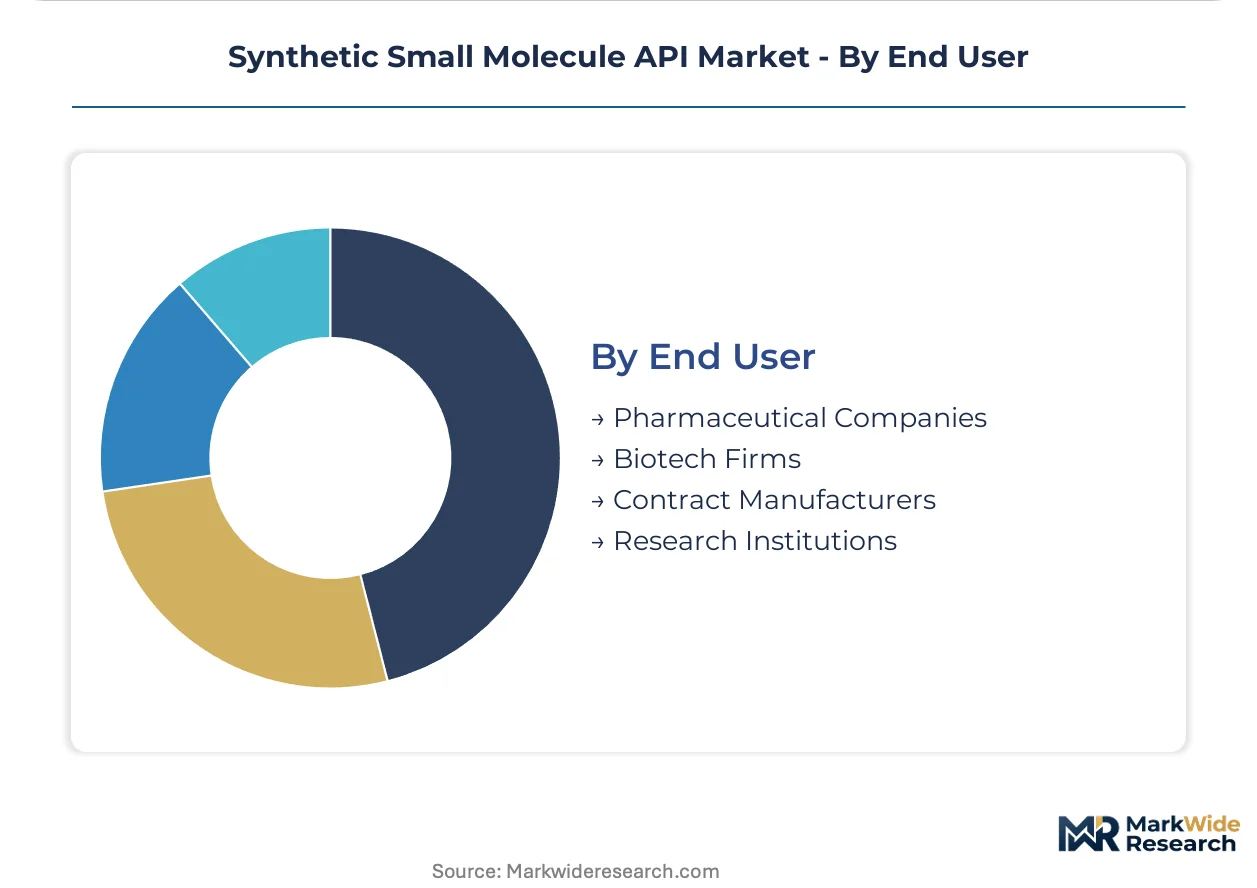
- Contract Manufacturers:CDMOs occupying the fastest-expanding channel as biotech firms fragment synthesis steps across multiple partners. Indian PLI scheme beneficiaries in Hyderabad and Ahmedabad build dedicated small-molecule campuses for Western sponsors.
- Pharmaceutical Companies:Vertically integrated sponsors retaining captive facilities for high-potency compounds and complex oncology intermediates, particularly in Ireland and Singapore.
- Biotech Firms:Virtual pharma sponsors consolidating vendor relationships toward single-source CDMO accountability.
- Research Institutions:Academic and government laboratories conducting early discovery chemistry.
Pharmaceutical Companies deploy the largest absolute capital. Contract Manufacturers are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redistributing synthetic small molecule API production toward jurisdictions with lower cost-of-compliance structures. Swiss and Irish facilities absorb premium oncology volumes under FDA and EMA oversight. Indian contract manufacturers capture generics migration through PLI scheme subsidies.
United States
FDA cGMP inspection backlogs and oncology pipeline acceleration drive sponsor reliance on domestic CDMO capacity. The Inflation Reduction Act's drug pricing provisions compress commercial timelines for small-molecule sponsors. Greater Boston and San Diego biotech clusters outsource development-phase synthesis to specialized contract manufacturers.
Switzerland
Swissmedic oversight and continuous manufacturing expertise anchor premium pricing for high-potency cytotoxic compounds. Basel and Visp industrial corridors concentrate flow chemistry platforms serving Western oncology portfolios. Lonza commands specialized isolator infrastructure for containment-grade APIs.
India
CDSCO regulatory alignment with ICH guidelines and PLI scheme capital subsidies attract Western sponsor investment. Hyderabad and Ahmedabad dedicated small-molecule campuses fragment synthesis steps across contract partners. Biocon and Sun Pharmaceutical anchor fermentation-to-synthesis integration for cost-optimized statin production.
Ireland
IDA Ireland tax incentives and FDA-EMA dual regulatory recognition sustain captive pharmaceutical investment. Cork and Dublin facilities retain high-potency compound development under vertical sponsor control. Pfizer maintains isolator suites for cytotoxic API commercial supply.
Germany
ECHA REACH solvent residual mandates and EU AI Act transparency requirements elevate compliance costs for legacy batch processes. Frankfurt-Rhine-Main chemical corridors retrofit recovery systems for green solvent substitution. EUROAPI represents mid-tier CDMO consolidation responding to regulatory barrier inflation.
Synthetic Small Molecule API Market Key Industry Players
Swiss and Irish producers anchor the premium tier; Indian specialists hold cost-optimized volume positions. Market structure concentrates around three strategic archetypes: continuous manufacturing platform operators, fermentation-integrated generics producers, and virtual pharma service integrators. Dominant competitive moves include CDMO consolidation for regulatory track record acquisition and dedicated campus construction for supply chain redundancy.
Among Swiss-based platform operators, Lonza exemplifies premium-tier positioning through specialized containment infrastructure. Indian PLI beneficiaries including Biocon and Sun Pharmaceutical occupy cost-optimized scale positions. These three entities represent divergent strategic responses to regulatory fragmentation—premium specialization, integrated fermentation, and generics volume leadership respectively.
| Leading Market Players |
|---|
| Lonza |
| Cambrex Corporation |
| Pfizer |
| EUROAPI |
| Biocon |
| Teva Pharmaceuticals |
| Thermo Fisher Scientific (Patheon) |
| Catalent |
| Sun Pharmaceutical |
| Others |
Cost & Logistics Intelligence
Analytical chemist concentrations in Basel and Hyderabad generate labor-cost spreads that stratify pricing tiers across the synthetic small molecule API market. CDMOs in Switzerland command containment-grade premiums while Indian fermentation specialists capture volume-driven generics contracts.
Pricing Analysis
Direct-to-sponsor contracting eliminates distributor markups for commercial-stage APIs, though development-phase intermediates retain broker-mediated pricing. Three-tier pricing structure across premium, standard, and economy levels separates Swiss continuous-manufacturing platforms from Eastern European batch facilities and Indian PLI-subsidized campuses. Cost compression in oncology generics is intensifying because patent cliffs are eroding originator pricing power. Virtual biotech sponsors show highest price sensitivity, while Big Pharma captive buyers prioritize regulatory track record over unit economics.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Singapore anchor hub-and-spoke patterns for time-sensitive high-potency compounds. Manufacturing concentrates in India, Switzerland, and Ireland, with Chinese KSM specialists feeding upstream synthesis steps. Supply chains draw from heterocyclic precursors, noble metal catalysts, and specialized chromatography resins. Single-source vulnerability in key starting material provision exposes sponsors to geographic concentration risk. Distribution runs through integrated CDMO partnerships rather than fragmented CRO-CMO networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The synthetic small molecule API market functions as a stable compounder, with oncology pipeline expansion and outsourcing acceleration providing durable demand foundations.
For Market Incumbents: Anticipate margin compression from Indian PLI-subsidized entrants by deepening isolator infrastructure investments in Switzerland and Ireland. Regulatory track record acquisition through CDMO consolidation offers defensive positioning against FDA inspection backlog delays. Prioritize backward integration into key starting material supply to reduce Chinese intermediate dependency. For New Entrants and Emerging Players: AI-driven reaction optimization platforms present technology-first wedge opportunities against legacy batch-process incumbents. White-space targets include mid-tier oncology CDMO services for Boston-San Diego biotech clusters and green-solvent substitution consulting for REACH-compliant German manufacturers. Go-to-market positioning should emphasize integrated CMC packages spanning synthesis through regulatory filing. For Investors and Strategic Acquirers: CDMO consolidators represent the most active acquirer in this space, seeking regulatory affairs infrastructure and containment-capable facilities. Long-term viability favors platform operators with continuous manufacturing expertise and dual FDA-EMA site approvals. Monitor ICH M7 guideline enforcement intensity as inflection indicator for toxicology-specialist acquisition premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Track Record Acquisition | CDMO consolidation accelerates FDA cGMP site approval timelines for oncology sponsors. |
| Continuous Manufacturing Scale-Up | Swiss flow-chemistry platforms reduce solvent volumes and compress batch release cycles. |
| Backward Integration into KSM Supply | Captive intermediate production mitigates Chinese single-source concentration risk. |
| Green Solvent Substitution | 2-MeTHF adoption satisfies ECHA REACH mandates and lowers authorization costs. |
| Integrated CMC Partnership Models | Single-source accountability spans IND-enabling through commercial supply for virtual pharma. |
Research Approach
Direct dialogue with drug development executives, regulatory affairs leads, contract manufacturing procurement managers, and CDMO operations directors grounded qualitative findings. Secondary validation drew from FDA cGMP inspection databases, EMA quality guideline publications, ClinicalTrials.gov oncology pipeline tracking, and CDSCO PLI scheme disclosures. Bottom-up and top-down triangulation reconciled facility capacity assessments with sponsor outsourcing survey data.
Bottom-up modeling segmented volume and value across product type, manufacturing stage, therapy area, and end-user channel dimensions. Top-down cross-checks incorporated customs trade flows for API imports and pharmaceutical company R&D outsourcing ratios. CAGRs were derived from sponsor pipeline acceleration rates and CDMO capacity expansion announcements. Forecast inputs included patent cliff timing profiles and ICH M7 guideline implementation trajectories across regulatory jurisdictions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA inspection backlog resolution, EMA impurity threshold revisions, and Indian PLI scheme extension decisions. Outputs reflect documented assumptions regarding oncology pipeline conversion rates and sponsor outsourcing elasticity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Duloxetine API Market
Pharmaceutical Ingredients
Pharmaceutical Grade Magnesium Hydroxide Market
Pharmaceutical Ingredients
Global Pharmaceutical Grade Silica Gel Market
Pharmaceutical Ingredients
Pharmaceutical Thermal Analysis Market
Pharmaceutical Ingredients
Pharma-Grade Magnesium Trisilicate Market
Pharmaceutical Ingredients
Oxycodone Drugs Market
Pharmaceutical Ingredients
Histamine H2-Receptor Antagonists Market
Pharmaceutical Ingredients
Non-Steroidal Anti-Inflammatory Drugs (Nsaids) Market
Pharmaceutical Ingredients
Antibiotics Active Pharmaceutical Ingredient (API) Market
Pharmaceutical Ingredients
Pharmaceutical Desiccants Market
Pharmaceutical Ingredients
Asia-Pacific Pharmaceutical Glycerine Market
Pharmaceutical Ingredients
Casein and Casein Derivatives Market
Pharmaceutical Ingredients
Cetrorelix Acetate API Market
Pharmaceutical Ingredients
Hyaluronic Acid Raw Material Market
Pharmaceutical Ingredients
Global Ibuprofen Market
Pharmaceutical Ingredients
Saudi Arabia Active Pharmaceutical Ingredients (API) Market