
 Global Sugar-Based Excipients Market | 2026-2036
Global Sugar-Based Excipients Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sugar-Based Excipients Market Foresight
Specialty biopharmaceutical contract manufacturers are bifurcating demand away from traditional generic tablet producers as complex biologic formulations require higher-grade excipient performance. Roquette Group leverages its pea-starch and polyol portfolio to anchor supply relationships with European biotech firms. BASF SE competes through pharmaceutical-grade mannitol and sorbitol lines that meet USP-NF and EP compendial standards. Ashland Inc. differentiates via its controlled-release polymer and excipient binding technologies for modified-release oral dosages.
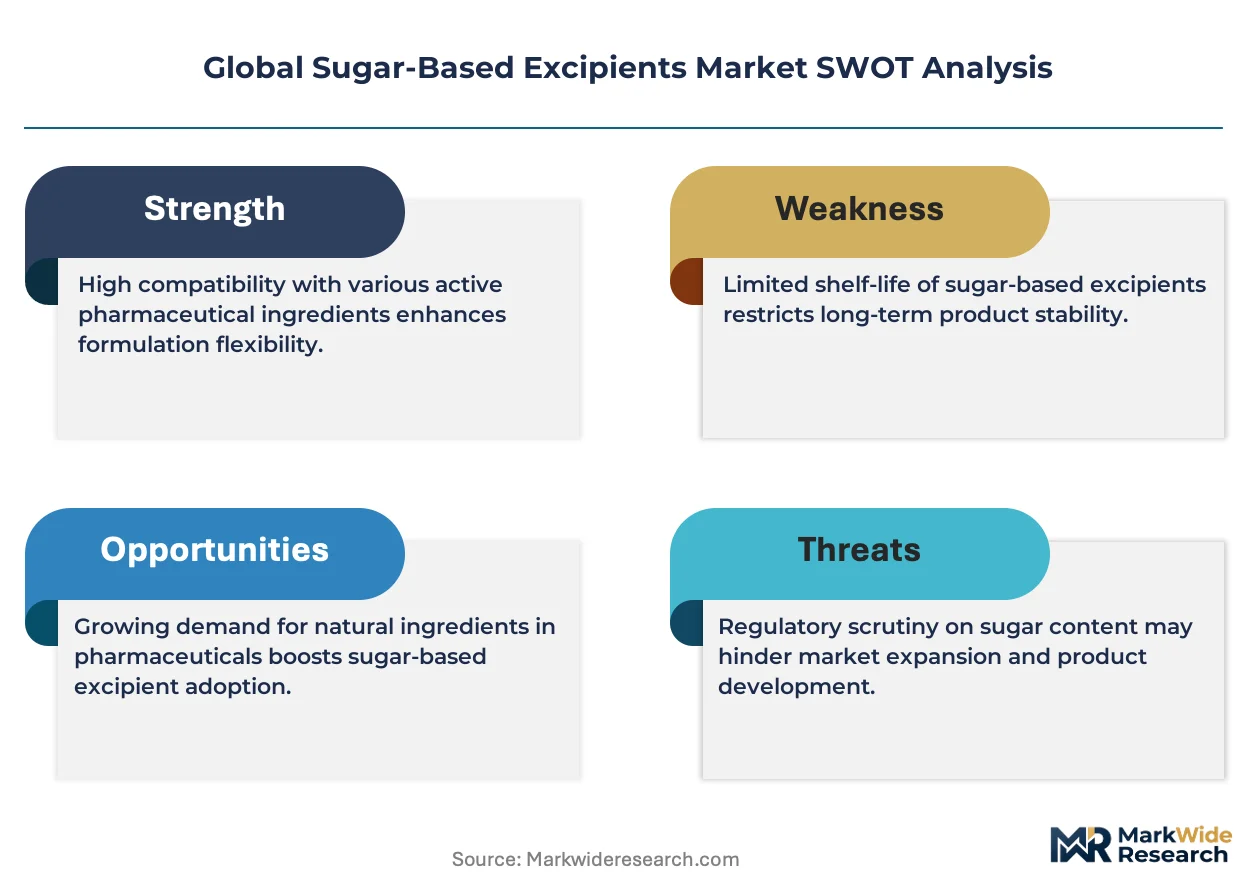
Sugar-based excipients comprise purified carbohydrates and polyols engineered as inactive pharmaceutical ingredients to enhance drug stability, compressibility, and patient palatability in finished dosage forms. These materials typically achieve pharmacopeial purity grades exceeding 99.5% with specified particle size distributions between 50 and 500 micrometers for direct compression tableting. Lactose dominates tablet binding applications due to its established compressibility profile and cost-efficient supply chain, while mannitol captures expanding share in lyophilization and chewable formulations where hygroscopic stability and cooling sensory properties command premium positioning. Maltodextrin sustains growth in granulation and capsule filling as nutraceutical producers seek bland-tasting, rapidly dissolving carriers for botanical and mineral actives.
FDA excipient qualification guidelines, EMA quality guidelines for drug-device combinations, and India's CDSCO excipient registration requirements collectively elevate compliance burdens for cross-border suppliers seeking multi-regional market access. These frameworks compel manufacturers to invest in dedicated pharmaceutical-grade production lines and documentary traceability systems that generic chemical producers cannot readily replicate. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and JP standards to anticipate specification drift that could invalidate existing supplier qualifications or create first-mover advantages for compliant producers.
Market Dynamics
Biopharmaceutical manufacturers are demanding higher-purity sugar-based stabilizers as lyophilized protein formulations displace traditional small-molecule tablets, forcing excipient suppliers to reconfigure production lines around pharmacopeial-grade certification.
Growth Catalysts
- India's PLI scheme:Domestic pharmaceutical production subsidies under India's Production Linked Incentive scheme are accelerating local excipient manufacturing capacity and reducing import dependency for oral solid dosage form producers.
- FDA excipient qualification updates:Tightened purity benchmarks for oral solid dosage applications are compelling manufacturers to upgrade to dedicated pharmaceutical-grade production lines, advantaging certified suppliers.
- Lyophilization technology:Expanding biologic pipelines require mannitol and trehalose stabilizers that maintain protein integrity through freeze-dry cycles, creating specialized demand pull from contract manufacturing organizations.
Market Restraints
- Pharmacopeial-grade corn starch volatility:Input costs for purified carbohydrate feedstocks fluctuate with agricultural commodity markets, compressing margins for excipient producers locked into annual supply contracts.
- European supply concentration:Three specialized polyol manufacturers control the majority of pharmaceutical-grade mannitol capacity, creating single-source risk for biopharmaceutical formulators.
- Cellulose derivative substitution:Microcrystalline cellulose and hydroxypropyl methylcellulose are displacing lactose in direct compression applications where moisture sensitivity or vegan labeling requirements dominate formulation decisions.
Strategic Opportunities
- Brazil's ANVISA excipient registration pathway:Simplified technical dossier requirements for established USP-NF materials create first-mover positioning for suppliers seeking Latin American market expansion.
- Continuous manufacturing integration:Excipient producers developing real-time release testing capabilities can capture preferred supplier status with pharmaceutical companies adopting FDA-promoted continuous processing lines.
- Orally disintegrating tablet formats:Pediatric and geriatric dosage forms requiring rapid dissolution are driving demand for spray-dried mannitol with engineered particle morphology.
Industry Challenges
- Pharmacopeial harmonization gaps:Divergent heavy metal limits between USP, EP, and JP specifications force manufacturers to maintain multiple product grades, complicating inventory management and qualification documentation.
- Bioburden control capex:FDA's tightened microbial quality expectations for non-sterile excipients require investment in isolator technology and environmental monitoring systems that smaller chemical producers cannot fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sugar-Based Excipients Market |
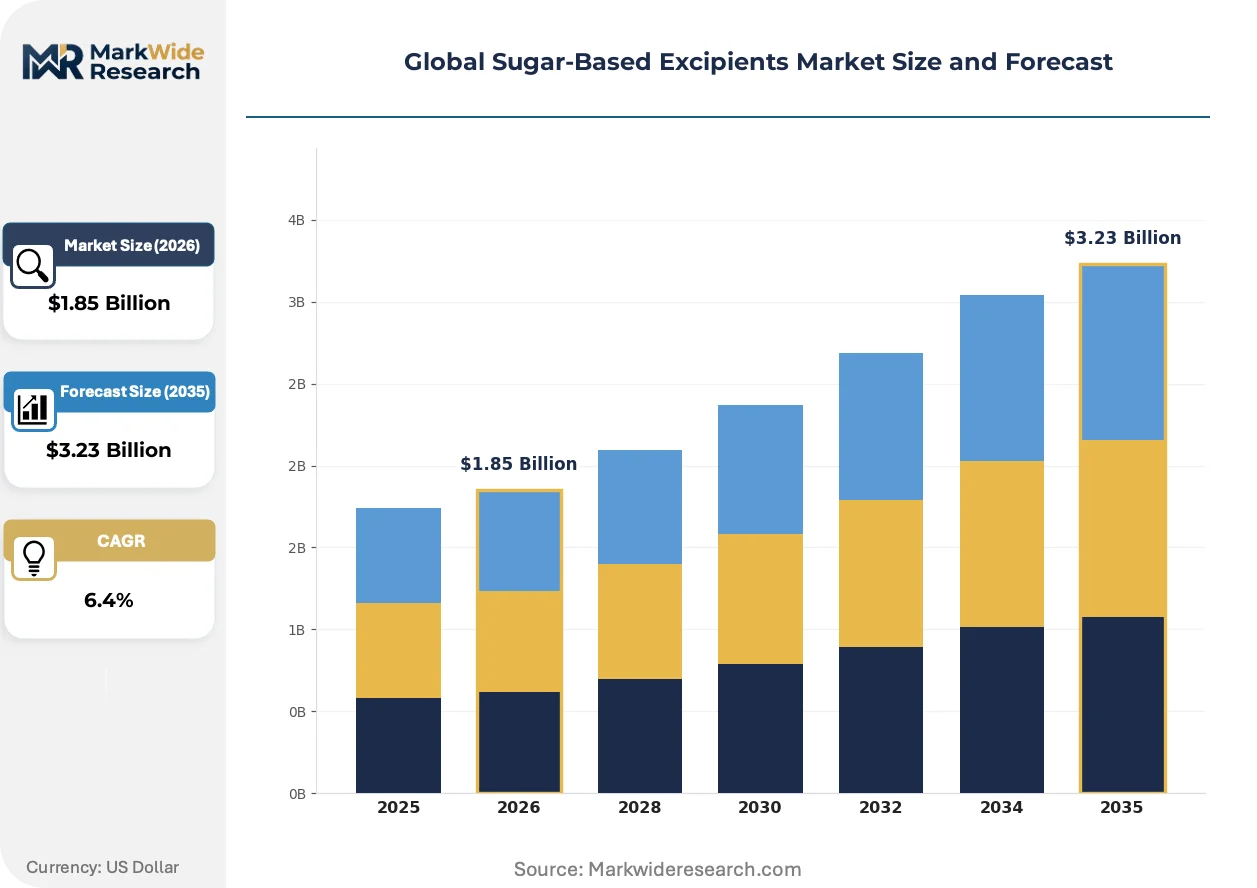
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
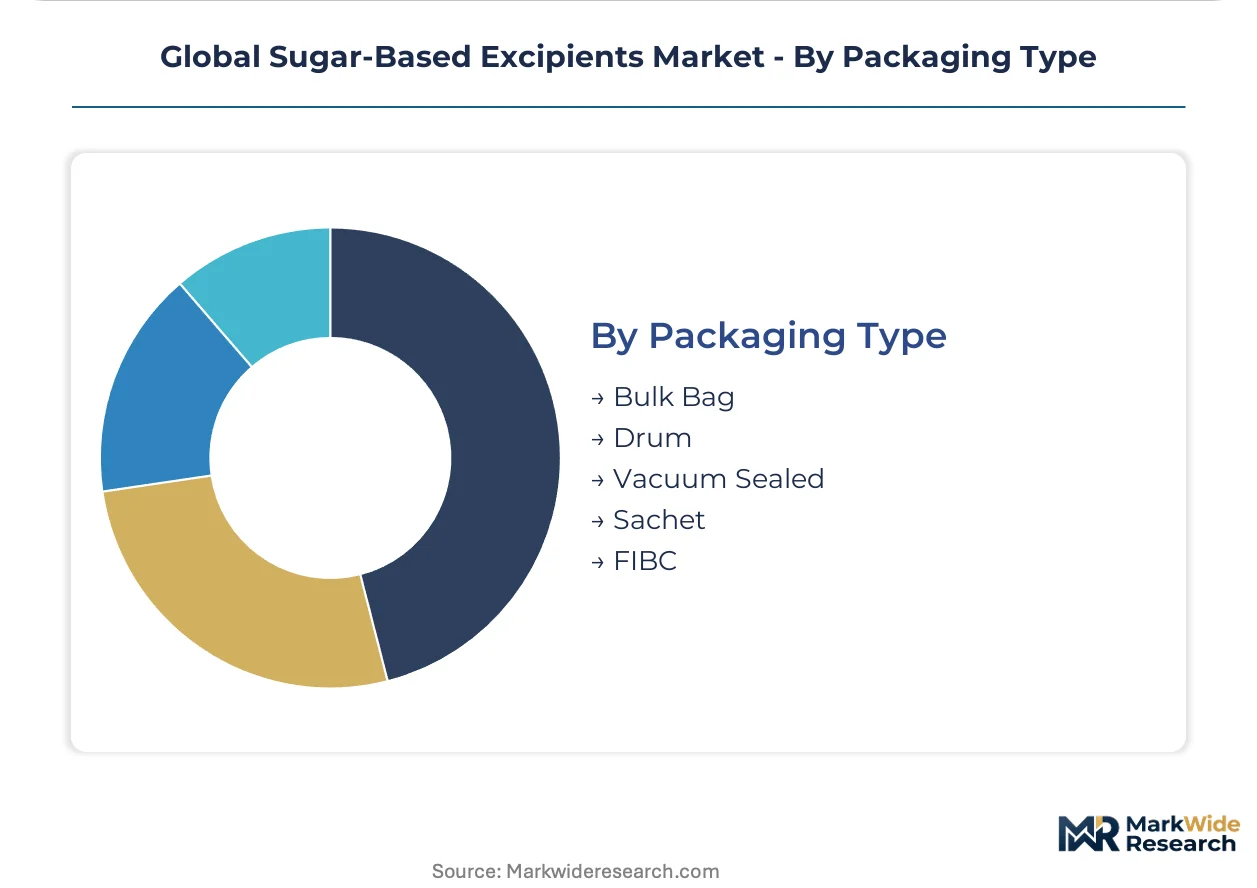
| Segmentation | Product Type: Lactose, Sorbitol, Mannitol, Maltodextrin, Xylitol Application: Tablet Binding, Capsule Filling, Coating Agents, Granulation, Lyophilization End User Industry: Pharmaceutical Manufacturers, Nutraceutical Producers, Veterinary Medicine, Biotechnology Firms Packaging Type: Bulk Bag, Drum, Vacuum Sealed, Sachet, FIBC |
| Companies Covered | Roquette Group, BASF SE, Ashland Inc., DFE Pharma, Archer Daniels Midland Company, Cargill, Inc., Colorcon, Inc., MEGGLE AG, The Lubrizol Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sugar-Based Excipients Market Shifts & Advancements
Excipient functionality is separating into distinct performance tiers as biopharmaceutical complexity demands material properties that commodity carbohydrate suppliers cannot engineer.
Engineered particle mannitol with controlled crystalline structure is bifurcating the lyophilization excipient market. Biologic drug manufacturers are specifying mannitol grades with defined polymorphic stability and reconstitution profiles for protein formulations. This technology compression is marginalizing generic polyol suppliers who lack spray-drying and crystallization control capabilities.
EMA's updated quality guidelines for drug-device combinations are redefining excipient documentation requirements. Manufacturers must now demonstrate leachable and extractable profiles for materials contacting delivery mechanisms. Inhalation and auto-injector developers are responding by sourcing excipients with pre-validated extractables data packages.
Contract development and manufacturing organizations are consolidating excipient procurement around qualified supplier lists with dedicated quality agreements. Large pharmaceutical sponsors are replacing spot-market purchasing with multi-year supply contracts that bundle technical support and regulatory documentation. This concentration pattern is most pronounced in Switzerland and Germany, where biotech clusters maintain stringent vendor qualification standards.
Global Sugar-Based Excipients Market Segmentation
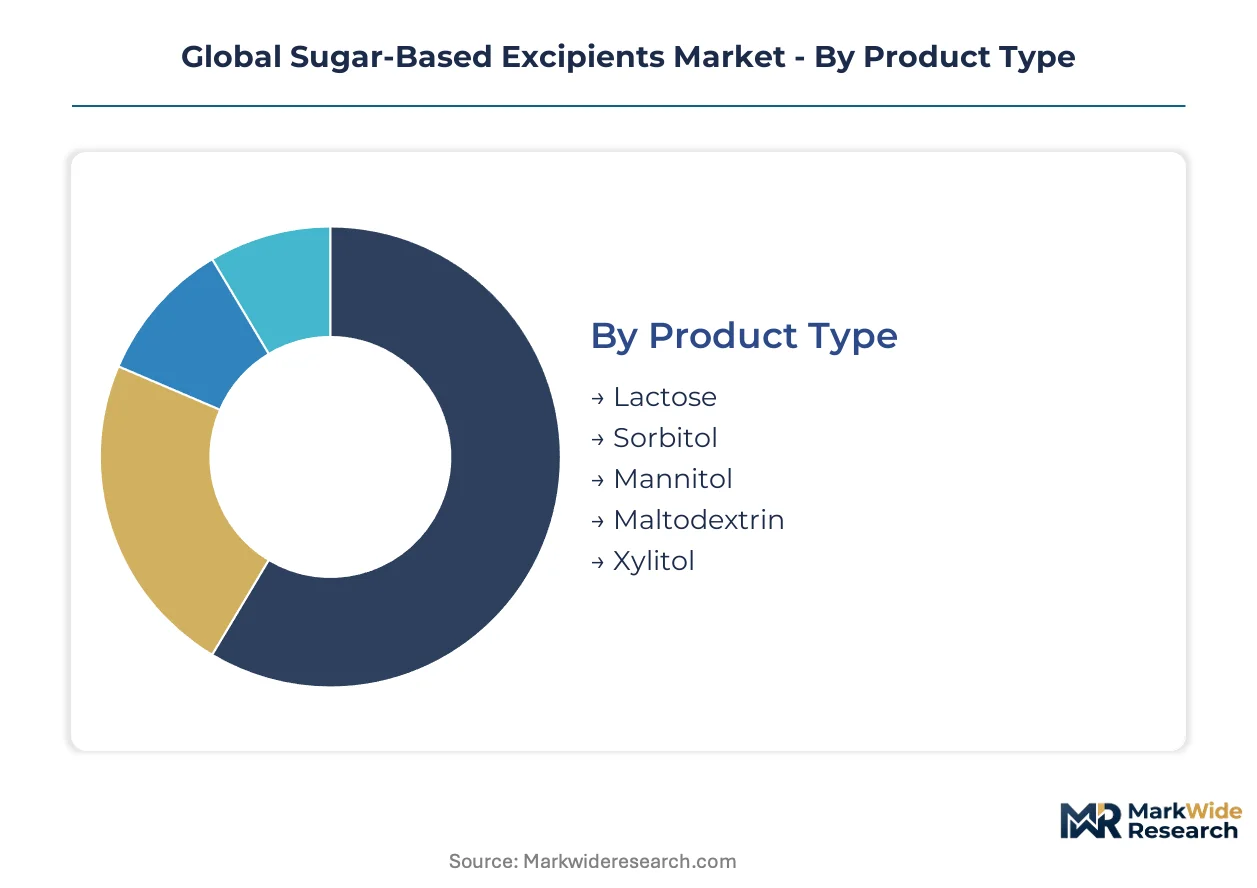
Sugar-based excipients segment across functional chemistry, dosage form application, and supply chain configuration. Channel strategies diverge sharply between commodity lactose distributors and specialty mannitol suppliers serving lyophilization contractors.
Product Type:
Pharmaceutical procurement channels bifurcate between direct compression tablet binders flowing through regional chemical distributors and lyophilization-grade polyols sourced through qualified supplier programs with dedicated quality agreements.
- Lactose:Anhydrous and monohydrate grades dominate direct compression tableting with established compressibility profiles and cost-efficient supply chains. Pharmaceutical manufacturers in India source lactose through domestic distributors under PLI scheme procurement mandates, though USP-NF grade imports still anchor quality-sensitive formulations.
- Mannitol:Spray-dried and crystalline grades engineered with defined polymorphic stability command premium positioning in protein lyophilization. Biologic drug manufacturers in Switzerland and Germany specify mannitol with validated reconstitution profiles, creating specialized demand pull from contract manufacturing organizations that generic polyol suppliers cannot satisfy.
- Sorbitol:Pharmaceutical-grade sorbitol serves wet granulation and liquid dosage applications with hygroscopic stability requirements.
- Maltodextrin:Low-dextrose-equivalent grades function as bland-tasting carriers for nutraceutical capsule filling and botanical actives.
- Xylitol:Cooling sensory properties and dental health positioning drive chewable tablet and orodispersible format adoption.
Lactose dominates installed base across oral solid dosage manufacturing. Mannitol is where expansion concentrates as biologic pipelines displace small-molecule portfolios.
Application:
Cost tier stratification separates commodity tablet binding from premium lyophilization services, with coating agents occupying a mid-tier position sensitive to batch consistency requirements.
- Tablet Binding:Direct compression and wet granulation applications consume the highest excipient volumes, with lactose and microcrystalline cellulose competing for share in moisture-sensitive formulations. Generic pharmaceutical producers in India prioritize cost-optimized binding grades, while European manufacturers specify particle size distributions for high-speed rotary press compatibility.
- Lyophilization:Freeze-dry stabilizers require mannitol and trehalose grades with validated crystalline structure and protein integrity preservation through thermal cycling. Biopharmaceutical contract manufacturers in Germany and Switzerland source these materials through audited supplier lists with documentary traceability systems that commodity distributors cannot replicate.
- Capsule Filling:Flow properties and lubricity requirements drive maltodextrin and starch selection for hard gelatin and vegetable capsule formulations.
- Coating Agents:Sugar-based film coatings and subcoating materials demand consistent viscosity and adhesion profiles across humidity-variable manufacturing environments.
- Granulation:Binder solutions and dry binders enable particle size enlargement for improved flow and compression characteristics in high-dose formulations.
Tablet binding anchors volume consumption across generic pharmaceutical manufacturing. Lyophilization is climbing the fastest as biologic pipelines expand and small-molecule portfolios contract.
End User Industry:
Customer type determines specification intensity, with biotechnology firms demanding pharmacopeial-grade certification and documentary packages that nutraceutical producers rarely require.
- Pharmaceutical Manufacturers:Oral solid dosage form producers drive bulk lactose and sorbitol consumption, with FDA and EMA compliance requirements forcing supplier qualification investments. India's domestic pharmaceutical production scaling under CDSCO registration requirements is accelerating local excipient manufacturing capacity to reduce import dependency.
- Biotechnology Firms:Protein formulation developers specify engineered particle mannitol with controlled crystalline structure for lyophilized biologics. These end users source through multi-year supply contracts bundling technical support and regulatory documentation, replacing spot-market purchasing patterns.
- Nutraceutical Producers:Botanical and mineral actives drive maltodextrin demand for bland-tasting, rapidly dissolving carriers in capsule and tablet formats.
- Veterinary Medicine:Palatability enhancement and stable dosing of active pharmaceutical ingredients in animal health products creates specialized formulation requirements.
Pharmaceutical manufacturers dominate installed excipient consumption. Biotechnology firms represent the steepest expansion trajectory as biologic pipelines displace traditional small-molecule development.
Packaging Type:
Supply concentration in pharmaceutical-grade polyol manufacturing shapes packaging configurations, with bulk formats serving high-volume tablet producers and specialized containment addressing hygroscopic stability requirements.
- Bulk Bag:Intermediate bulk containers serve high-volume lactose and maltodextrin shipments to tablet manufacturing facilities with integrated material handling systems.
- Drum:Steel and fiber drums remain standard for pharmaceutical-grade mannitol and sorbitol requiring protection from moisture ingress during storage and transport.
- Vacuum Sealed:Heat-sealed pouches and foil laminates preserve hygroscopic excipient stability for lyophilization-grade materials with stringent moisture specifications.
- Sachet:Pre-weighed unit doses support research and development formulation work and clinical trial material preparation.
- FIBC:Flexible intermediate bulk containers with liner systems enable efficient handling of non-hygroscopic excipients in continuous manufacturing environments.
Drum packaging dominates pharmaceutical-grade material distribution. Vacuum sealed formats are gaining share fastest as hygroscopic stability requirements tighten for biologic formulation applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biopharmaceutical contract manufacturers cluster in Switzerland and Germany, while oral solid dosage producers concentrate in India and the United States. Excipient procurement patterns diverge sharply between these buyer archetypes, with quality agreements replacing spot purchasing in biotech hubs.
United States
FDA's updated excipient qualification guidelines are tightening purity benchmarks for oral solid dosage applications. Biopharmaceutical manufacturers in Greater Boston and the San Francisco Bay Area specify engineered particle mannitol for lyophilized protein formulations. These firms source through multi-year supply contracts bundling regulatory documentation and technical support.
Germany
EMA quality guidelines for drug-device combinations are redefining documentation requirements for leachable and extractables profiles. The Rhine-Main biotech cluster around Frankfurt maintains stringent vendor qualification standards for inhalation and auto-injector developers. Contract manufacturing organizations here consolidate procurement around audited supplier lists with dedicated quality agreements.
India
Domestic pharmaceutical production is scaling rapidly under the PLI scheme, accelerating local excipient manufacturing capacity. CDSCO excipient registration requirements are elevating compliance burdens for cross-border suppliers. Maharashtra and Gujarat host expanding oral solid dosage facilities that source lactose through domestic distributors under procurement mandates.
Switzerland
Swissmedic maintains exacting pharmacopeial standards that biotech clusters in Basel and Zurich translate into supplier qualification investments. Protein formulation developers specify mannitol grades with validated reconstitution profiles. These end users have replaced spot-market purchasing with contracted supply relationships bundling documentary traceability.
Brazil
ANVISA's simplified excipient registration pathway for established USP-NF materials creates first-mover positioning opportunities. São Paulo's pharmaceutical manufacturing base is expanding oral solid dosage capacity for Latin American distribution. Local producers seek qualified suppliers with pre-validated documentation packages to accelerate market entry.
Global Sugar-Based Excipients Market Competitive Landscape
Player mix skews toward diversified chemical conglomerates with pharmaceutical-grade certification capabilities. Three specialized polyol manufacturers control the majority of pharmaceutical-grade mannitol capacity, creating tiered supply concentration. Strategic archetypes include: European pea-starch and polyol specialists; German chemical conglomerates with USP-NF and EP compendial lines; and US-based controlled-release polymer developers. Dominant competitive moves center on pharmacopeial-grade production line upgrades and multi-year supply contract bundling of technical support with regulatory documentation.
Within the European specialist tier, Roquette Group and MEGGLE AG represent archetypes of regional feedstock-integrated suppliers. BASF SE exemplifies the diversified chemical conglomerate model with dedicated pharmaceutical-grade mannitol and sorbitol lines. Ashland Inc. occupies a position among US-based developers of modified-release technologies for oral dosage applications.
| Leading Market Players |
|---|
| Roquette Group |
| BASF SE |
| Ashland Inc. |
| DFE Pharma |
| Archer Daniels Midland Company |
| Cargill, Inc. |
| Colorcon, Inc. |
| MEGGLE AG |
| The Lubrizol Corporation |
| Others |
Supply & Pricing Matrix
Cellulose derivative substitution for lactose in moisture-sensitive tablet formulations is simultaneously shifting procurement geography toward Asian microcrystalline cellulose producers and compressing pricing power for traditional sugar-based binder suppliers locked into annual supply contracts.
Pricing Analysis
Three-generation pricing stratification separates spray-dried mannitol with engineered polymorphic stability from standard crystalline grades and commodity polyol feedstocks. Certification tier and validated reconstitution profiles command substantial premia from biopharmaceutical contract manufacturers, while generic tablet producers in India prioritize volume-scale procurement of standard lactose grades. Cost compression in standard-grade lactose is intensifying because domestic Indian production under PLI scheme subsidies is displacing import volumes. Biotechnology firms demonstrate lowest price sensitivity due to protein integrity requirements; generic oral solid dosage manufacturers exhibit highest sensitivity.
Supply Chain Analysis
Strategic stockpiling of pharmaceutical-grade mannitol dominates procurement behavior among German and Swiss biopharmaceutical contract manufacturers, while Indian generic producers favor just-in-time lactose deliveries through domestic distributor networks. Manufacturing concentrates in Germany, Switzerland, and India, with three specialized European polyol producers controlling majority lyophilization-grade mannitol capacity. Feedstock dependencies include pharmacopeial-grade corn starch, crystalline sucrose, and hydrogenated starch hydrolysates. Single-source vulnerability concentrates in pharmaceutical-grade mannitol where European capacity constraints create allocation risk during demand surges. Distribution runs through qualified supplier programs with dedicated quality agreements for biopharmaceutical segments and regional chemical distributors for commodity tablet applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment story where pharmacopeial-grade certification barriers and multi-year supplier qualification timelines create structural switching costs that protect incumbent positions.
For Market Incumbents: Secure pharmacopeial harmonization compliance across USP-NF, EP, and JP specifications to preempt specification drift that could invalidate competitor qualifications. Invest in isolator technology and environmental monitoring systems to meet FDA's tightened microbial quality expectations for non-sterile excipients, creating separation from smaller chemical producers unable to fund comparable bioburden control capex. For New Entrants and Emerging Players: Differentiate on real-time release testing capabilities for continuous manufacturing integration, capturing preferred supplier status with pharmaceutical companies adopting FDA-promoted processing lines. Target Brazil's ANVISA simplified excipient registration pathway for established USP-NF materials, where pre-validated documentation packages accelerate market entry ahead of slower-moving incumbents. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors feedstock-integrated specialists with pharmaceutical-grade certification capabilities. Long-term viability rests on backward integration into agricultural carbohydrate supply and captive spray-drying technology. Acquisition targets should display established qualified supplier relationships with audited biopharmaceutical contract manufacturers. Watch for pharmacopeial harmonization announcements between USP, EP, and JP as inflection indicators that could invalidate existing supplier qualifications or create first-mover advantages.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmacopeial-Grade Production Line Upgrade | Enables compliance with FDA's tightened purity benchmarks for oral solid dosage applications. |
| Backward Integration into Pea-Starch Feedstock | Secures supply continuity for European biotech firm relationships through captive raw material sourcing. |
| Long-Term Supply Contract with Quality Agreement Bundling | Replaces spot-market purchasing patterns among Swiss and German biopharmaceutical contract manufacturers. |
| Spray-Drying Capacity Expansion for Engineered Particle Mannitol | Addresses specialized demand pull from protein lyophilization formulations requiring defined polymorphic stability. |
| Continuous Manufacturing Integration Partnership | Captures preferred supplier status through real-time release testing capabilities aligned with FDA processing initiatives. |
Research Methodology
Cross-validation between primary interviews with excipient procurement managers, quality assurance directors, and regulatory affairs leads at biopharmaceutical contract manufacturers and secondary validation through FDA guidance documents, EMA quality guidelines, and CDSCO registration requirements anchors the qualitative findings. Bottom-up triangulation incorporates customs data on pharmaceutical-grade carbohydrate imports, USP-NF and EP compendial specification filings, and SEC disclosures from diversified chemical conglomerates with pharmaceutical-grade lines.
Sensitivity analysis across multiple scenario assumptions informs the projection framework. The analytical framework segments by product chemistry, dosage form application, end-user industry archetype, and regional regulatory cluster throughout the forecast period. CAGRs derive from modeled volume-demand trajectories for lyophilization-grade polyols versus direct compression tablet binders, incorporating biologic pipeline expansion rates and small-molecule portfolio contraction patterns as key forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained biopharmaceutical capital allocation to lyophilization capacity or abrupt pharmacopeial specification divergence would require recalibration. Forecasts reflect assumptions regarding PLI scheme continuation in India and EMA drug-device combination guideline stability. Revision becomes warranted when agricultural commodity price volatility for corn starch feedstocks crosses thresholds that compress excipient producer margins beyond contract renegotiation capacity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Global Cephalosporin Drugs Market
Pharmaceutical Ingredients
Heparin Sodium API Market
Pharmaceutical Ingredients
Mitotic Inhibitors Market
Pharmaceutical Ingredients
Originator Small Molecule Drug Market
Pharmaceutical Ingredients
Fixed-Dose Combination Drugs Market
Pharmaceutical Ingredients
Piperacillin Sodium API Market
Pharmaceutical Ingredients
Kitasamycin Market
Pharmaceutical Ingredients
Large Molecule Drug Substance CDMO Market
Pharmaceutical Ingredients
Synthetic Small Molecule API Market
Pharmaceutical Ingredients
Pharmaceutical Grade Magnesium Hydroxide Market
Pharmaceutical Ingredients
Rizatriptan Market
Pharmaceutical Ingredients
Alpha Lipoic Acid API Market
Pharmaceutical Ingredients
Global Fibrate Drugs Market
Pharmaceutical Ingredients
Pharmaceutical Grade Amino Acid Market
Pharmaceutical Ingredients
Pharmaceutical Grade Sodium Carbonate Market
Pharmaceutical Ingredients
MEK Inhibitors Market