
 Asia-Pacific Paint Spray Guns Market | 2026-2036
Asia-Pacific Paint Spray Guns Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Paint Spray Guns Market Analytics
Aluminum alloy components are hardening their position over traditional brass and zinc castings in premium spray gun bodies, cutting raw material costs while improving corrosion resistance. Anest Iwata leverages its Japanese manufacturing heritage to dominate precision-engineered HVLP systems across East Asian automotive markets. Zhejiang Rongpeng Air Tools anchors its competitive stance through aggressive pricing and captive supply of pneumatic components from its Zhejiang base. Graco Inc. extends its technical leadership into electrostatic and airless platforms for industrial coating lines throughout the region.
Paint spray guns are precision fluid-delivery instruments that atomize coatings through controlled air pressure or hydraulic force, typically operating at pressures between 1,500 and 3,000 PSI for airless systems and 10 PSI or below for HVLP configurations, designed to deposit uniform films on automotive bodies, furniture substrates, and architectural surfaces. HVLP spray guns lead the product type hierarchy in Japan and South Korea due to stringent transfer-efficiency mandates, while airless systems capture the fastest expansion in China's architectural painting sector where high-volume commercial projects demand speed over material conservation. Industrial coating applications concentrate the thickest margin pools, as Japanese and South Korean electronics manufacturers specify electrostatic systems with programmable pattern controls for consistent deposition on complex geometries.
China's SAMR enforces GB standards on spray equipment safety and electromagnetic compatibility, while India's BIS mandates product certification for imported pneumatic tools under its Compulsory Registration Scheme, effectively filtering low-cost entrants from unbranded supply chains. Japan's METI promotes energy-efficiency benchmarks that favor HVLP adoption in regulated industries, creating tiered market access conditions across the region. Stakeholders must monitor divergence between national certification regimes, as harmonized testing protocols remain absent and dual compliance costs threaten margin structures for manufacturers serving multiple Asia-Pacific jurisdictions.
Market Dynamics
Waterborne coating mandates across China's industrial manufacturing corridors are forcing synchronous equipment upgrades across OEM coating lines and aftermarket repair networks, compressing replacement cycles for conventional solvent-compatible spray guns.
Growth Catalysts
- China's GB Standards:SAMR-enforced safety and electromagnetic compatibility requirements on spray equipment are filtering unbranded supply chains and creating certified product demand.
- Automotive Refinishing:Southeast Asian collision repair networks are expanding tool procurement as vehicle parc growth outpaces existing coating capacity.
- HVLP Transfer Efficiency:Japan's METI energy-efficiency benchmarks favor high-volume low-pressure systems in regulated industries, accelerating technology substitution.
Market Restraints
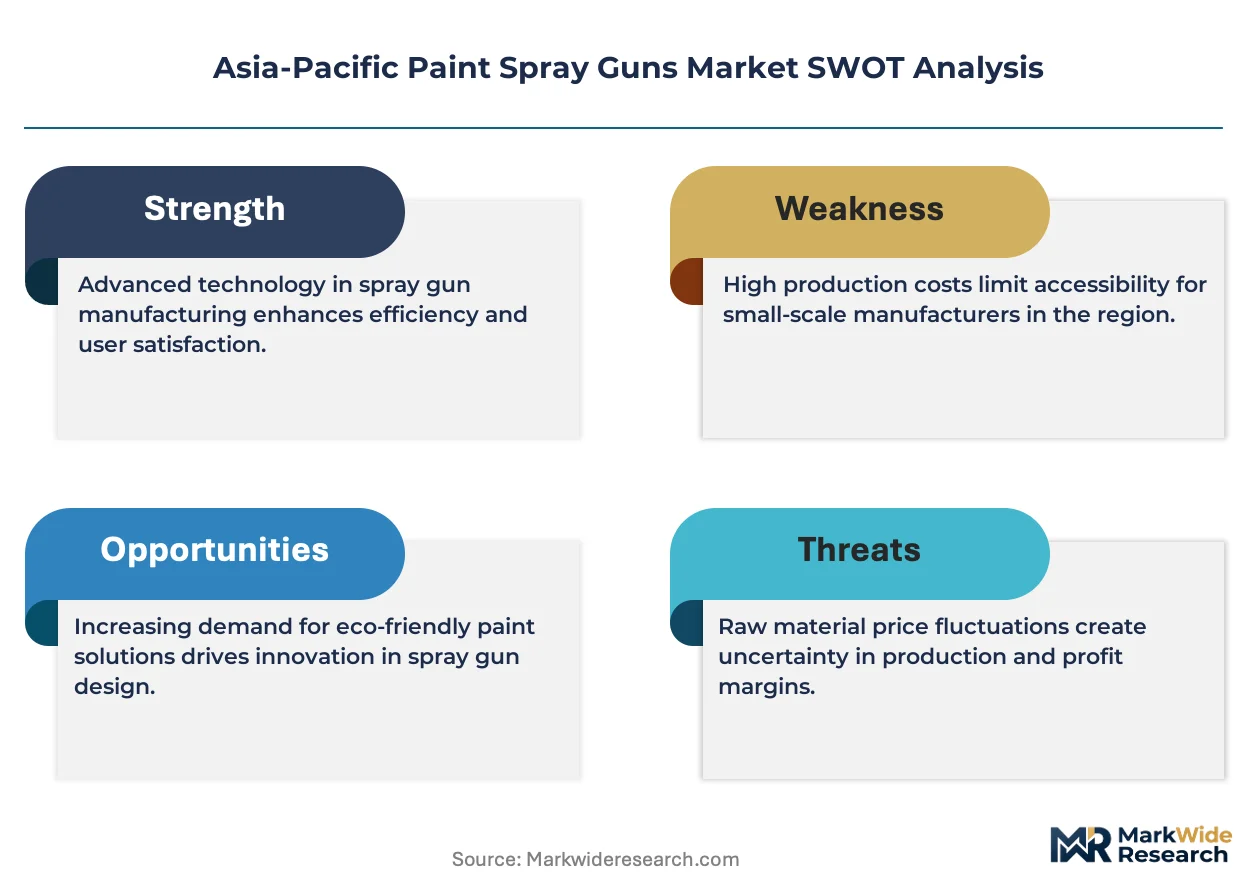
- Aluminum Alloy Volatility:Raw material cost swings for spray gun bodies compress margin structures for manufacturers locked into fixed-price distribution contracts.
- Dual Compliance Costs:Absence of harmonized testing protocols between China's GB standards and India's BIS Compulsory Registration Scheme fragments certification investments.
- Electrostatic System Complexity:Programmable pattern controls for Japanese electronics manufacturers require specialized technical support infrastructure unavailable across secondary cities.
Strategic Opportunities
- India's BIS Certification Gap:Compulsory Registration Scheme enforcement creates white space for compliant pneumatic tool suppliers against unbranded import competition.
- Architectural Airless Expansion:China's commercial painting sector demands speed-optimized equipment for high-volume infrastructure projects.
- Electronics Manufacturing Convergence:South Korean and Japanese semiconductor fabrication facilities are specifying precision electrostatic systems for conformal coating applications.
Industry Challenges
- Skilled Operator Scarcity:HVLP and electrostatic system calibration demands trained technicians, constraining deployment velocity in Indonesia and Vietnam repair networks.
- Legacy Equipment Integration:Pneumatic infrastructure incompatibility with newer low-pressure systems forces parallel maintenance capabilities in multi-brand service centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Paint Spray Guns Market |
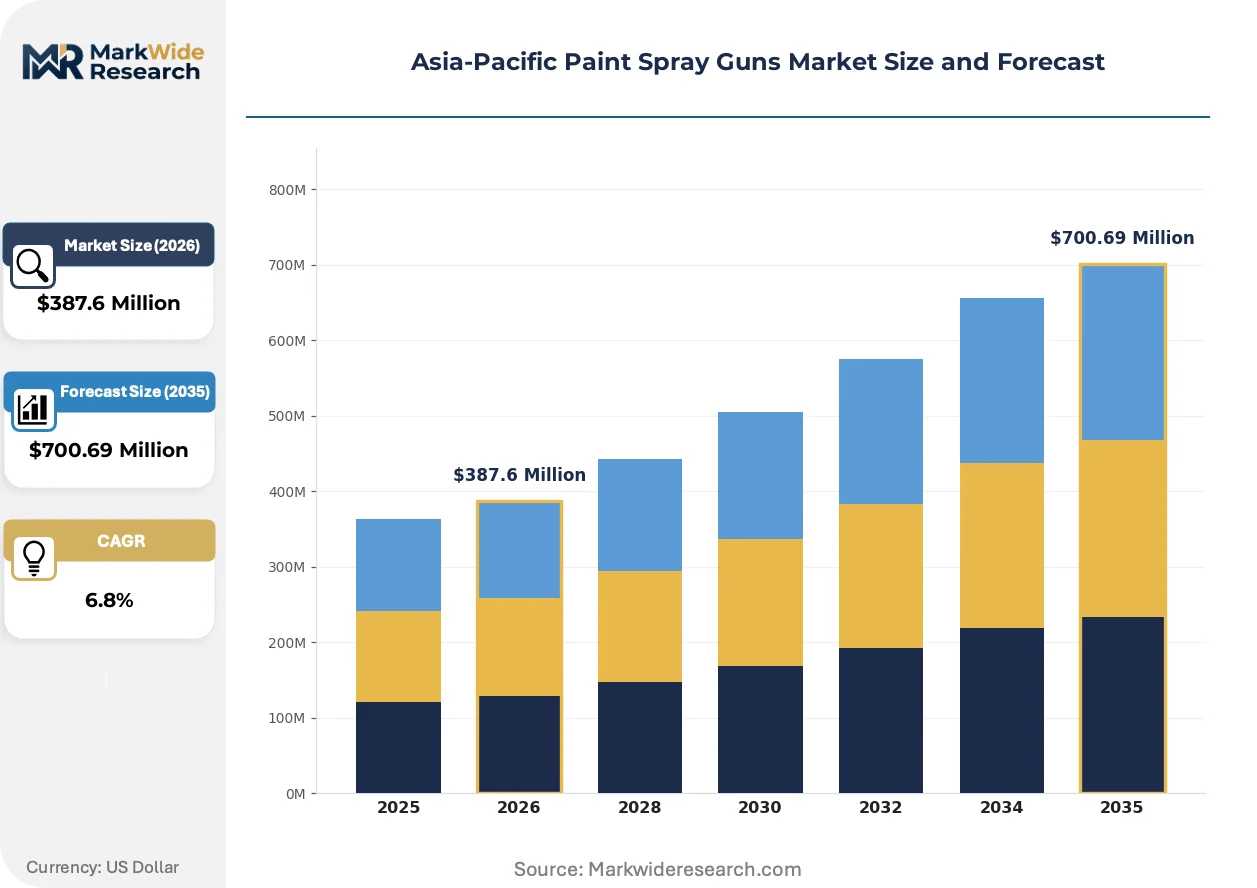
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Airless Spray Guns, HVLP Spray Guns, Conventional Spray Guns, Electrostatic Spray Guns Application: Automotive Refinishing, Furniture Coating, Industrial Coating, Architectural Painting End User: Contractors, DIY Enthusiasts, Industrial Manufacturers, Vehicle Repair Shops Delivery Mode: Online Retail, Offline Retail, Direct Sales, Distribution Partnerships |
| Companies Covered | Anest Iwata, Asahi Sunac, Fuji Spray, Sata GmbH & Co. KG, Zhejiang Rongpeng Air Tools, Ningbo Lis Industrial, Graco Inc., 3M, J. Wagner, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Paint Spray Guns Market Evolving Landscape
Equipment functionality is fragmenting along application-specific optimization paths, with manufacturers abandoning universal-platform strategies in favor of dedicated architectures for automotive refinishing, industrial coating, and architectural painting segments.
Smart spray gun technology is converging with IoT-enabled flow monitoring and real-time pressure adjustment systems. Japanese automotive OEMs are piloting connected HVLP units that feed deposition data directly into quality management systems. This convergence is compressing the service interval prediction market and enabling predictive maintenance revenue models for equipment suppliers.
India's BIS Compulsory Registration Scheme is tightening import filtration for pneumatic tools, mandating laboratory testing at designated facilities before market entry. The industrial consequence is extended product launch timelines for non-compliant suppliers. Aftermarket repair networks in Maharashtra and Tamil Nadu are consolidating procurement around pre-certified equipment to avoid customs detention risks.
Buying patterns are rotating toward specification-driven procurement where coating contractors pre-qualify equipment based on transfer efficiency documentation rather than brand preference. Distributor inventories in China's Pearl River Delta are thinning as direct manufacturer relationships replace multi-brand wholesale channels. This rotation is most visible in Guangdong province architectural painting contracts where project owners now mandate equipment traceability for warranty compliance.
Asia-Pacific Paint Spray Guns Market Segmentation
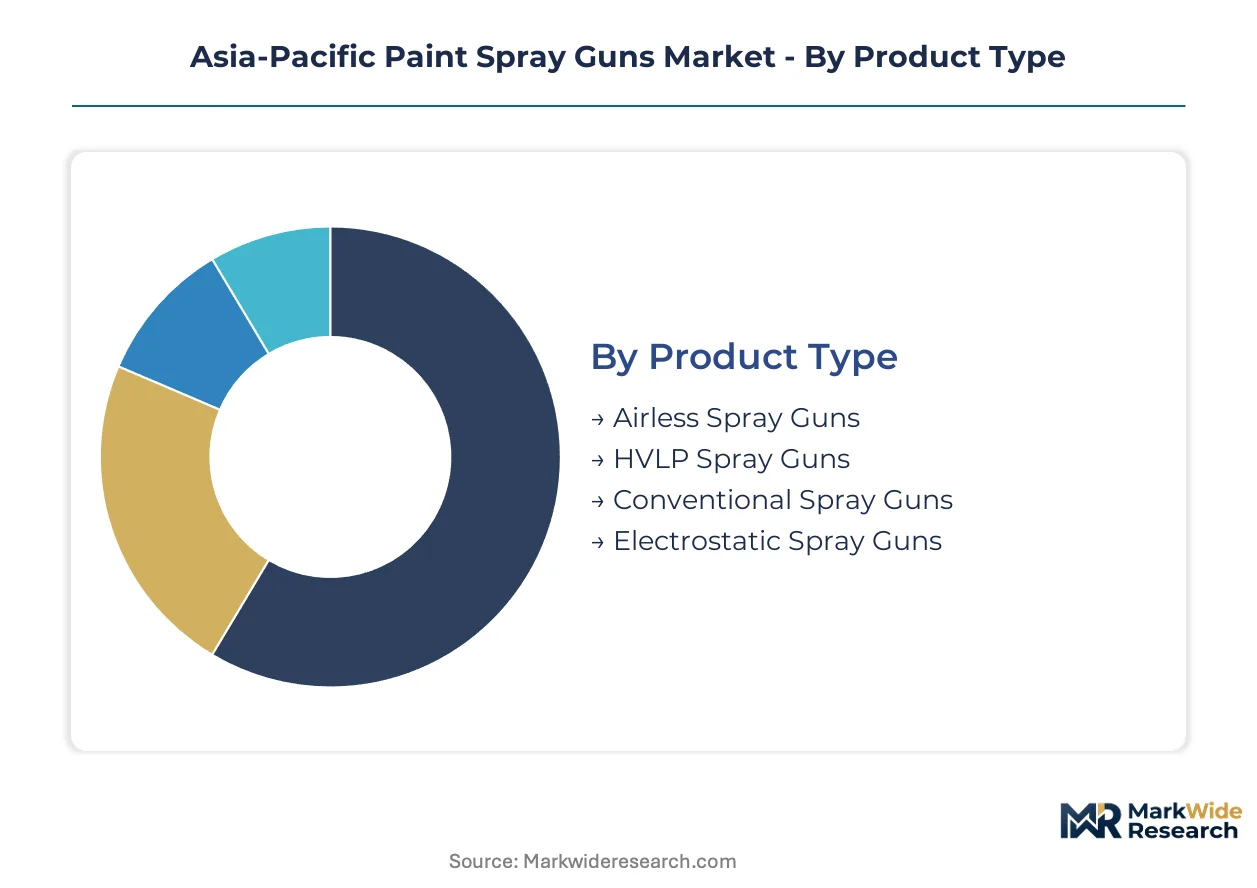
Equipment replacement cycles across Asia-Pacific paint spray guns market fragment sharply by application environment and regulatory exposure. Upgrade decisions hinge on coating chemistry transitions, transfer efficiency mandates, and supply chain certification requirements rather than uniform depreciation schedules.
Product Type:
Upgrade cycles diverge dramatically between high-pressure industrial systems and precision low-pressure units, with replacement timing driven by coating formulation shifts rather than mechanical wear.
- HVLP Spray Guns:High-volume low-pressure systems atomize coatings through reduced air velocity, achieving transfer efficiency above 65 percent. Japanese automotive refinishing shops and South Korean electronics manufacturers specify these units under METI energy benchmarks and corporate sustainability protocols, forcing synchronous fleet replacements when waterborne formulations displace solvent-based chemistries.
- Airless Spray Guns:Hydraulic pressure systems operating between 1,500 and 3,000 PSI deliver high-speed coating deposition for large surface areas. China's architectural painting contractors in Guangdong and Jiangsu provinces deploy these units for infrastructure scale, prioritizing throughput over material conservation as commercial project timelines compress.
- Electrostatic Spray Guns:Charged particle systems dominate Japanese semiconductor fabrication and South Korean electronics manufacturing for conformal coating precision.
- Conventional Spray Guns:Legacy compressed-air systems persist in Vietnam and Indonesia aftermarket repair networks where capital constraints delay HVLP conversion.
Volume placements concentrate in HVLP configurations; the faster expansion belongs to electrostatic systems serving precision manufacturing.
Application:
Margin structures stratify by coating complexity and specification intensity, with industrial applications commanding premium pricing against commoditized architectural segments.
- Industrial Coating:OEM production lines and heavy equipment manufacturing specify programmable electrostatic systems with real-time pattern control. Japanese electronics manufacturers and Chinese industrial machinery producers drive specification intensity, requiring documented transfer efficiency and traceable calibration records for warranty compliance.
- Automotive Refinishing:Collision repair networks across Thailand, Malaysia, and Indonesia expand equipment procurement as vehicle parc growth outpaces existing coating capacity. China's GB standards on spray equipment safety filter unbranded supply chains, redirecting procurement toward certified HVLP systems.
- Architectural Painting:China's commercial infrastructure projects favor airless speed optimization over material efficiency.
- Furniture Coating:Vietnamese and Malaysian wood product manufacturers balance finish quality against compressed margins in export markets.
Revenue concentration pools in industrial coating; architectural painting gains share fastest on infrastructure investment cycles.
End User:
Procurement authority separates specification-driven industrial buyers from price-sensitive fragmented demand in residential and small-commercial segments.
- Industrial Manufacturers:Japanese automotive OEMs and Chinese industrial machinery producers mandate equipment traceability and predictive maintenance capability. These buyers specify connected HVLP units with IoT-enabled flow monitoring, compressing service intervals and shifting supplier relationships toward direct manufacturer partnerships.
- Vehicle Repair Shops:Southeast Asian collision repair networks consolidate procurement around pre-certified equipment to avoid India's BIS customs detention risks and China's SAMR enforcement actions. Maharashtra and Tamil Nadu repair chains increasingly demand documented compliance before purchase authorization.
- Contractors:China's Pearl River Delta architectural painting contractors rotate toward direct manufacturer relationships, thinning distributor inventories.
- DIY Enthusiasts:Price-sensitive demand concentrates in conventional spray gun categories through online retail channels.
Specification intensity peaks with industrial manufacturers; vehicle repair shops expand procurement most rapidly on regulatory filtration.
Delivery Mode:
Channel structure fragments between certification-heavy direct relationships and volume-driven retail intermediation, with divergence accelerating across national regulatory boundaries.
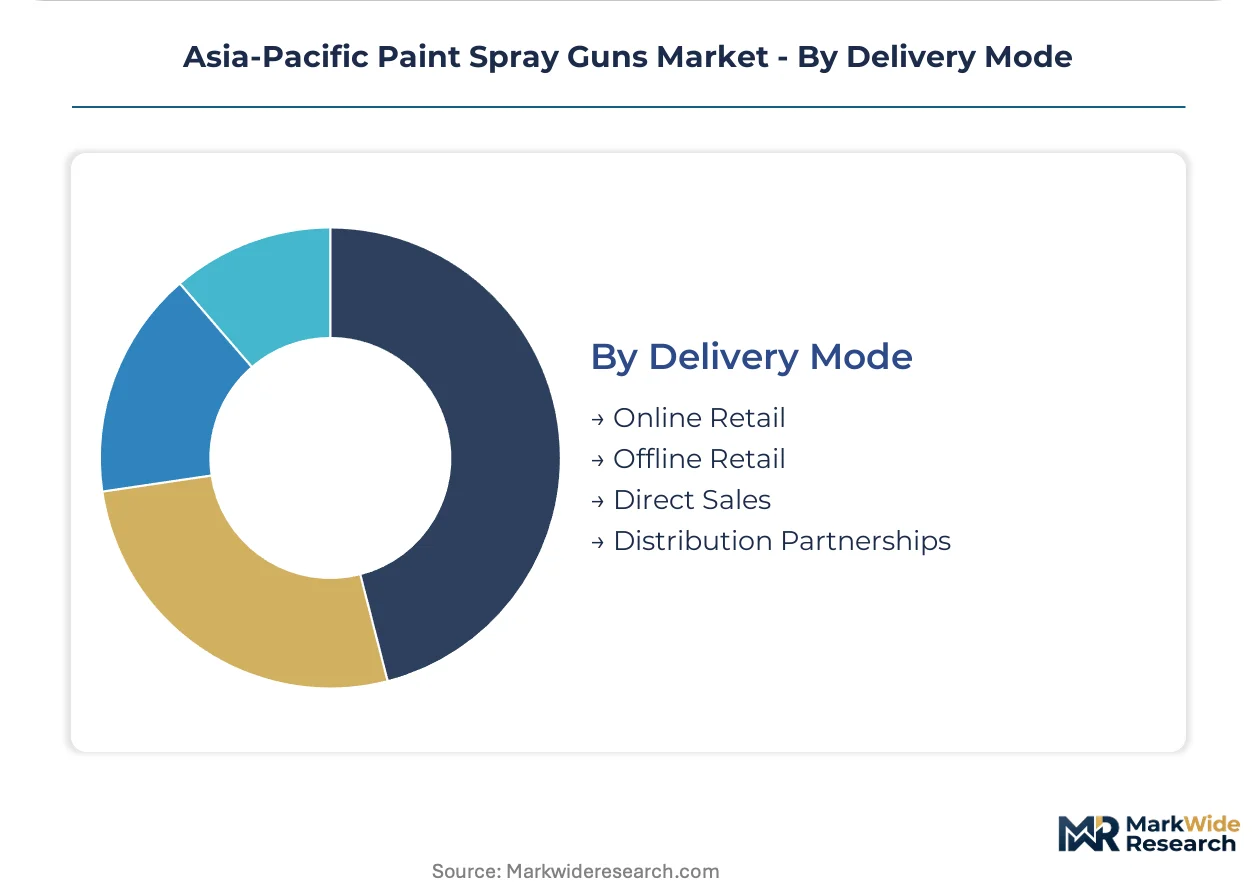
- Direct Sales:Japanese automotive OEMs and South Korean electronics manufacturers bypass distribution layers for electrostatic and connected HVLP systems. These relationships embed technical support and calibration services, capturing margin pools unavailable through wholesale channels.
- Distribution Partnerships:Offline networks in Indonesia and Vietnam remain essential for pneumatic infrastructure compatibility and operator training, constraining pure digital displacement despite regulatory documentation requirements.
- Online Retail:DIY and small-contractor demand migrates toward platform purchasing for conventional spray gun categories.
- Offline Retail:Physical stocking points retain relevance where immediate replacement needs and technical consultation overlap.
Transaction volume concentrates in distribution partnerships; direct sales climbs fastest on specification intensity in precision manufacturing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates the thickest demand pools across OEM coating lines and aftermarket repair networks, while Japan and South Korea anchor precision manufacturing specifications. India's regulatory filtration is redirecting procurement toward certified suppliers, and Southeast Asian collision repair networks are expanding equipment procurement on vehicle parc growth.
China
Industrial manufacturing corridors in Guangdong and Jiangsu provinces are upgrading spray equipment simultaneously as waterborne coating formulations gain traction under SAMR-enforced GB standards. SAMR mandates safety and electromagnetic compatibility certification, filtering unbranded supply chains from Pearl River Delta distribution channels. Guangdong province architectural painting contractors now mandate equipment traceability for warranty compliance, thinning distributor inventories in favor of direct manufacturer relationships.
Japan
Automotive OEMs and semiconductor fabricators specify precision electrostatic systems with programmable pattern controls for conformal coating applications. METI promotes energy-efficiency benchmarks that favor HVLP adoption in regulated industries, creating tiered market access conditions. Kanto region automotive refinishing shops and Chubu industrial zones are piloting connected HVLP units that feed deposition data directly into quality management systems.
India
Collision repair networks in Maharashtra and Tamil Nadu are consolidating procurement around pre-certified equipment to avoid BIS Compulsory Registration Scheme customs detention risks. BIS mandates laboratory testing at designated facilities before market entry, extending product launch timelines for non-compliant suppliers. Tamil Nadu and Maharashtra repair chains increasingly demand documented compliance before purchase authorization, redirecting demand toward certified pneumatic tool suppliers.
South Korea
Electronics manufacturers and semiconductor fabrication facilities are specifying precision electrostatic systems for consistent deposition on complex geometries. Corporate sustainability protocols and METI-aligned energy benchmarks accelerate HVLP fleet replacements when waterborne formulations displace solvent-based chemistries. Busan-Ulsan industrial corridors and Seoul Capital Area coating lines are driving specification intensity for documented transfer efficiency and traceable calibration records.
Thailand
Collision repair networks are expanding tool procurement as vehicle parc growth outpaces existing coating capacity, particularly around Bangkok metropolitan manufacturing zones. Regulatory alignment with neighboring certification schemes creates procurement uncertainty, favoring suppliers with multi-jurisdiction compliance documentation. Bangkok and Eastern Economic Corridor repair chains are balancing capital constraints against pressure to upgrade from legacy compressed-air systems.
Asia-Pacific Paint Spray Guns Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with precision-engineered systems consolidating around heritage Japanese manufacturers while price-sensitive architectural demand fragments toward Zhejiang-based pneumatic suppliers. The vendor base organizes into three strategic archetypes: precision-engineered HVLP specialists serving automotive OEMs, scale-driven airless manufacturers capturing infrastructure projects, and vertically integrated pneumatic component suppliers leveraging captive supply chains. Dominant competitive moves include backward integration into aluminum alloy component production and direct manufacturer partnerships replacing multi-brand wholesale channels.
Within the heritage precision tier, Anest Iwata and Asahi Sunac exemplify Japanese manufacturing positioning in high-transfer-efficiency systems. Zhejiang Rongpeng Air Tools anchors the scale-driven pneumatic segment through aggressive pricing and Zhejiang-based component supply. Graco Inc. occupies a position in electrostatic and airless platforms for industrial coating lines. These three represent distinct competitive vectors: precision heritage, manufacturing scale, and platform breadth.
| Leading Market Players |
|---|
| Anest Iwata |
| Asahi Sunac |
| Fuji Spray |
| Sata GmbH & Co. KG |
| Zhejiang Rongpeng Air Tools |
| Ningbo Lis Industrial |
| Graco Inc. |
| 3M |
| J. Wagner |
| Others |
Value Network & Pricing Analysis
China's waterborne coating mandates under GB standards gate both qualified supply and premium-tier pricing access, compressing replacement cycles for solvent-compatible equipment while elevating certified HVLP systems above commodity tiers. SAMR-enforced electromagnetic compatibility requirements filter unbranded imports from Pearl River Delta distribution channels, concentrating pricing power among compliant manufacturers.
Pricing Analysis
Volume placements concentrate in standard-tier pneumatic systems while margin pools accrue to precision electrostatic configurations. Three-tier pricing structure across premium, standard, and economy levels separates METI-certified Japanese HVLP units from Zhejiang-based pneumatic imports and legacy compressed-air alternatives. Price differentiation hinges on certification grade under China's SAMR and India's BIS schemes, alongside after-sales calibration service bundling. Cost compression in economy tiers is intensifying because aluminum alloy input volatility squeezes fixed-price distribution contracts. DIY enthusiasts and small Vietnamese repair shops exhibit highest price sensitivity; Japanese automotive OEMs demonstrate lowest.
Supply Chain Analysis
Aluminum alloy forging capacity rests on Chinese smelters and Japanese specialty metal processors, with pneumatic component machining concentrated in Zhejiang province and precision electronics sourcing from South Korean semiconductor fabricators. Critical inputs span aluminum alloy billets, solenoid valve assemblies, and programmable logic controllers. Single-source vulnerability runs through Japanese precision-engineered HVLP nozzle suppliers serving automotive OEMs. Distribution runs through direct manufacturer partnerships for industrial coating lines and multi-brand wholesale channels for aftermarket repair networks in Indonesia and Vietnam.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific paint spray guns market sits in a technology-transition phase as connected HVLP systems with IoT-enabled flow monitoring displace legacy pneumatic platforms across Japanese automotive OEM coating lines.
For Market Incumbents: Cement technical leadership in electrostatic pattern control systems serving South Korean semiconductor fabrication facilities. Deepen backward integration into aluminum alloy component production to buffer raw material cost swings. Defend against Zhejiang-based price competition by embedding predictive maintenance capabilities in direct OEM partnerships. For New Entrants and Emerging Players: Capture India's BIS certification gap in Maharashtra and Tamil Nadu collision repair networks where documented compliance creates procurement barriers for unbranded imports. Target architectural airless segments in China's Jiangsu province infrastructure projects. Lead with pre-certified equipment bundles that eliminate customs detention risk for repair chain procurement managers. For Investors and Strategic Acquirers: BIS Compulsory Registration Scheme enforcement extending product launch timelines is the leading indicator that regulatory compliance capabilities will consolidate toward scaled manufacturers with dedicated testing infrastructure. Long-term viability favors precision-engineered specialists with captive Japanese or South Korean electronics supply relationships. Monitor METI energy-efficiency benchmark expansion as the signal for accelerated HVLP fleet replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Alloy Production | In-house forging capacity buffers SAMR-certified manufacturers against raw material volatility in Guangdong corridors. |
| IoT-Enabled Predictive Maintenance Platforms | Connected HVLP units feeding deposition data into Japanese OEM quality management systems compress service intervals. |
| BIS Certification Infrastructure Investment | Designated laboratory testing capabilities unlock Maharashtra and Tamil Nadu repair network procurement consolidation. |
| Direct Manufacturer Partnership Expansion | Bypassing Pearl River Delta wholesale channels captures margin pools from Guangdong architectural painting contractors. |
| Electrostatic Pattern Control R&D | Programmable deposition systems meet South Korean semiconductor fabrication conformal coating specifications. |
Research Methodology
Trade flow databases, SAMR certification registries, and BIS Compulsory Registration Scheme filings formed the secondary backbone, cross-referenced against primary interviews with coating line engineers, automotive refinishing shop owners, pneumatic tool procurement managers, and aftermarket distribution channel heads. Bottom-up equipment shipment analysis triangulated against top-down coating formulation transition timelines across China, Japan, India, and South Korea.
Historical trendline analysis of replacement cycle compression under waterborne coating mandates informed the analytical framework across the projection horizon. Segmentation dimensions modeled encompass product type, application environment, end-user procurement authority, and national regulatory cluster. CAGRs were derived from equipment unit economics and coating chemistry transition velocity. Forecast inputs incorporated aluminum alloy price indices and METI energy-efficiency benchmark adoption curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to divergence between China's GB standards and India's BIS testing protocols, aluminum alloy commodity cycles, and skilled technician availability across Indonesian and Vietnamese repair networks. A small set of triggers—regulatory harmonization progress, electrostatic system technical support infrastructure expansion, and connected platform data standardization—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Global Decorative Coatings Market
Paints & Coatings
Global Construction Paints and Coatings Market
Paints & Coatings
Acrylic Paints Market
Paints & Coatings
Insulating Paints and Coatings Market
Paints & Coatings
Global Decorative Paints and Coatings Market
Paints & Coatings
Low VOC Paint Market
Paints & Coatings
Metal Paint Tray Market
Paints & Coatings
Asia-Pacific Paints and Coatings Additives Market
Paints & Coatings
Architectural Coatings Market
Paints & Coatings
Wall Putty Powder Market
Paints & Coatings
Iraq Paints and Coatings Market
Paints & Coatings
Europe Paints and Coatings Market
Paints & Coatings
Global Texture Paint Market
Paints & Coatings
Nordic Countries Architectural Coatings Market
Paints & Coatings
Refinish Paint Market
Paints & Coatings
Middle East & Africa Corrosion Protection Coating Market