
 Middle-East Paints and Coatings Additives Market | 2026-2036
Middle-East Paints and Coatings Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East Paints and Coatings Additives Market Foresight
Waterborne resin systems is pivoting away from solvent-borne formulations across Gulf manufacturing lines, compressing traditional additive margins while expanding rheology modifier volumes. Dow leverages its regional technical service centers to anchor supply relationships with Saudi and Emirati paint producers. BASF SE competes through localized production of dispersants and wetting agents. Evonik Industries differentiates via silicone-based defoamer technology tailored for high-temperature Gulf application conditions.
Paints and coatings additives comprise specialty chemicals—typically organometallic compounds, polyacrylates, or silicone derivatives dosed at 0.1-5.0 wt%—that modify viscosity stability, substrate wetting, pigment dispersion, or foam control during manufacture and application. Their primary purpose is to enable consistent film formation and performance in formulations subject to extreme Middle Eastern heat, humidity, and UV exposure. Rheology modifiers capture the largest volume share due to architectural coating demand, while dispersants represent the fastest-expanding category as industrial OEMs shift to higher-solids and waterborne systems. Liquid formulations dominate commercial supply, though powder additive demand from furniture and automotive OEM segments is accelerating.
SFDA and SASO standards in Saudi Arabia, alongside UAE's Ministry of Climate Change and Environment regulations, mandate VOC content thresholds and chemical registration for imported additive packages. REACH-equivalent disclosure requirements under Gulf Cooperation Council harmonization initiatives are reshaping import documentation and reformulation cycles for multinational suppliers. Stakeholders must monitor regulatory divergence between Saudi and Emirati enforcement timelines to avoid supply chain fragmentation.
Market Dynamics
Saudi Arabia's giga-project pipeline is compressing formulation cycles as architects demand coatings that withstand 50°C summer peaks and sand abrasion. This construction velocity is forcing additive suppliers to regionalize technical service and pre-approve formulations under divergent Saudi and Emirati regulatory timelines.
Growth Catalysts
- SFDA and SASO VOC thresholds:Saudi chemical registration mandates are accelerating reformulation toward waterborne systems, expanding demand for rheology modifiers and dispersants that maintain performance at lower solvent loads.
- Neom and Red Sea Project specifications:Premium architectural coatings for these developments require UV-stabilized, self-cleaning films that drive consumption of silicone-based surface additives.
- Industrial OEM shift to higher-solids:Automotive and furniture manufacturers across the UAE are adopting waterborne basecoats, necessitating advanced wetting agents for metal and wood substrates.
Market Restraints
- Petrochemical feedstock volatility:Acrylic monomer and silicone precursor costs fluctuate with regional oil output, compressing margins for polyacrylate and organosilicon additive producers.
- Import dependency for specialty intermediates:Rheology modifier core polymers concentrate in European and Asian manufacturing, exposing formulators to shipping bottlenecks through Jebel Ali and Dammam.
- REACH-equivalent disclosure lag:Gulf Cooperation Council harmonization remains incomplete, forcing suppliers to maintain parallel documentation systems for Saudi and Emirati customs clearance.
Strategic Opportunities
- Oman and Kuwait construction recovery:These underpenetrated markets are accelerating infrastructure spending with less saturated supplier competition than Saudi Arabia or the UAE.
- Photocatalytic self-cleaning coatings:Titanium dioxide and zinc oxide additive packages for exterior architectural applications address labor cost pressures in high-dust environments.
- UAE Ministry of Climate Change green procurement:Public project mandates for low-VOC materials create preferential access channels for certified additive portfolios.
Industry Challenges
- Formulation chemist scarcity:The Gulf region lacks sufficient technical personnel trained in waterborne system stabilization under extreme heat and humidity conditions.
- Dual-registration timeline compression:Suppliers must simultaneously navigate SASO's evolving chemical inventory and UAE's substance notification windows, stretching regulatory affairs capacity.
- Legacy solvent-borne equipment retrofit costs:Manufacturing lines across smaller Emirati paint producers require capital investment to handle higher-viscosity waterborne additive packages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East Paints and Coatings Additives Market |
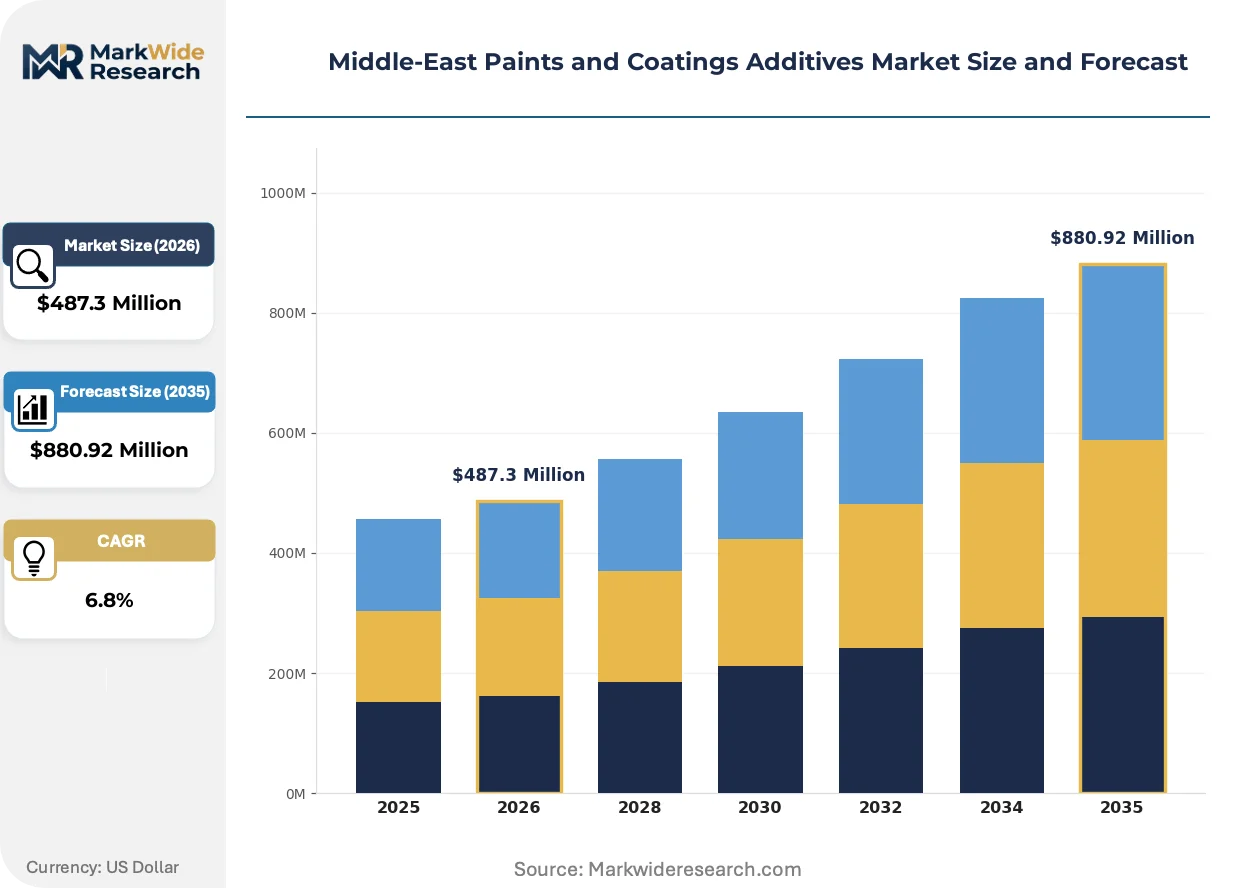
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rheology Modifiers, Wetting Agents, Dispersants, Defoamers Application: Architectural, Industrial, Automotive, Protective Form: Liquid, Powder, Granules, Paste End User: Construction, Furniture, Automotive OEMs, Marine |
| Companies Covered | Dow, Solvay, Altana Group (BYK), Ashland, Elementis, BASF SE, Arkema, Evonik Industries, Cabot Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East Paints and Coatings Additives Market Shifts & Advancements
Formulation science in the Middle East is pivoting toward multifunctional additives that reduce complexity in high-temperature, high-UV application environments. This convergence is reshaping supplier R&D priorities and buyer specification standards across architectural and industrial segments.
Hybrid silicone-polyacrylate surface modifiers are unifying scratch resistance, UV stability, and hydrophobicity in single additive packages. Saudi architectural coating producers are adopting these materials at accelerated rates for Neom exterior specifications. This unification is compressing demand for standalone silicone oils and conventional waxes while elevating technical service requirements.
UAE's Ministry of Climate Change and Environment is tightening VOC content thresholds for imported coating materials ahead of Saudi enforcement timelines. Industrial consequences include accelerated lab testing cycles and reformulation costs concentrated in decorative paint segments. Saudi formulators are responding by pre-qualifying additive packages under both regulatory frameworks to avoid supply chain fragmentation.
Buyer concentration among Saudi giga-project general contractors is compressing supplier negotiation cycles and unbundling technical service from material supply. Large architectural coating tenders now specify direct additive supplier involvement in film performance warranties. This pattern is most visible in Riyadh and Jeddah mega-developments where single-source accountability reduces project risk.
Middle-East Paints and Coatings Additives Market Segmentation
Additives for Middle Eastern paints and coatings operate across distinct technical specifications, each governing how formulators balance VOC compliance with extreme climate performance. Understanding these segment boundaries reveals where procurement power concentrates and where supplier margins face pressure.
Product Type:
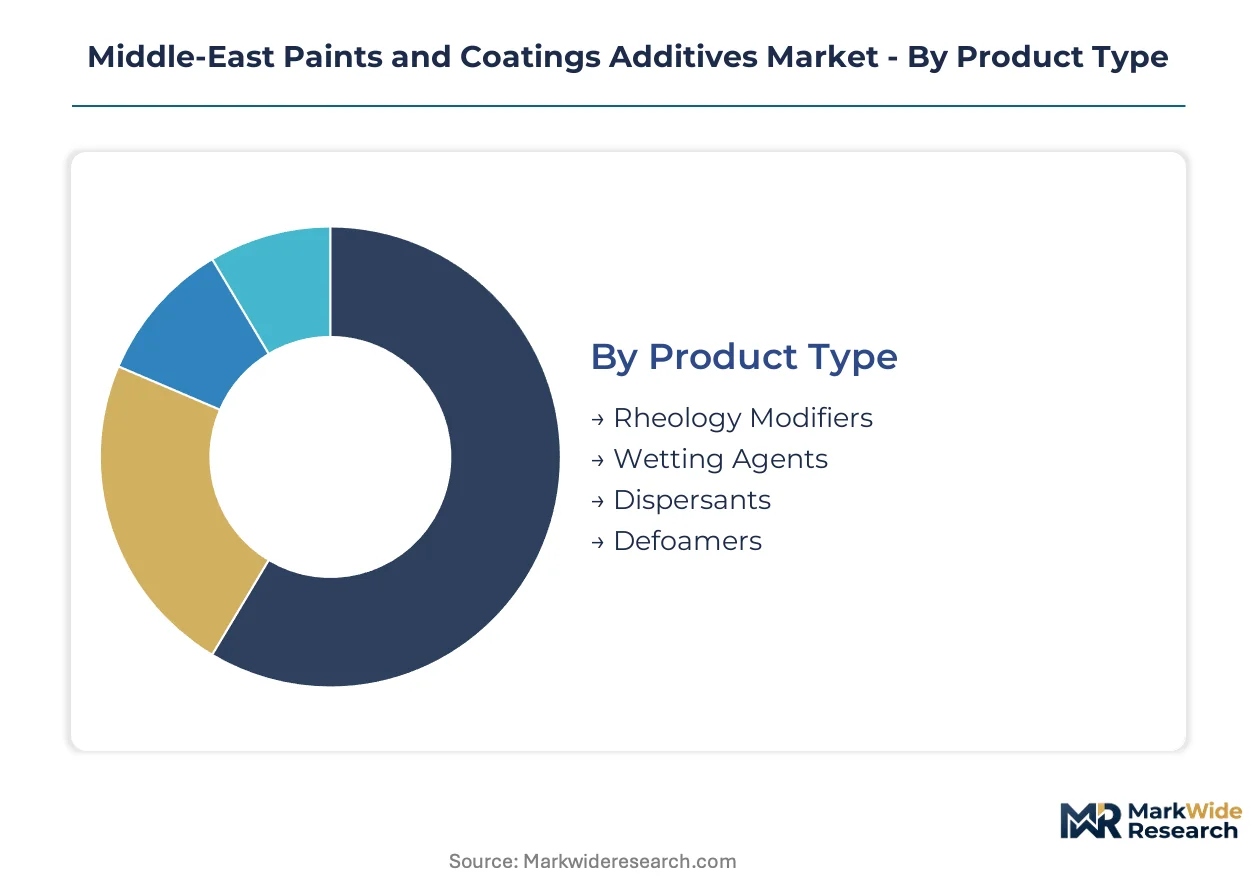
Standalone rheology modifiers dominate formulation complexity, while dispersants and defoamers increasingly embed into pre-mixed additive packages for waterborne system efficiency.
- Rheology Modifiers:Cellulosic, associative, and organoclay thickeners control viscosity stability across Saudi giga-project coatings exposed to 50°C application temperatures. Neom and Red Sea Project specifications drive consumption of high-shear stable grades that maintain sag resistance under desert wind abrasion.
- Dispersants:Polyacrylate and polyphosphate chemistries stabilize pigment loading in higher-solids architectural systems, with demand accelerating as UAE manufacturers shift from solvent-borne alkyd bases. SFDA chemical registration timelines compress supplier qualification cycles for these reformulation-dependent additives.
- Wetting Agents:Silicone and fluorosurfactant grades reduce surface tension for wood and metal substrate coverage in furniture and industrial OEM segments.
- Defoamers:Silicone-based and mineral oil formulations control foam in high-speed dispersion equipment; Evonik's regional silicone technology addresses Gulf-specific high-temperature defoaming requirements.
Rheology modifiers lead volumes today; dispersants are gaining share fastest.
Application:
Cost tier differentiation separates premium specification-grade architectural coatings from commodity industrial maintenance systems across Saudi and Emirati procurement channels.
- Architectural:Interior and exterior decorative coatings for Saudi residential and commercial construction absorb the largest additive volumes, with self-cleaning and UV-stable film specifications commanding premium rheology modifier and surface additive packages.
- Industrial:Factory-applied OEM finishes and maintenance coatings for infrastructure steel drive demand for corrosion-resistant additive systems; procurement concentrates among Saudi Aramco and SABIC-affiliated contractors with stringent pre-qualification requirements.
- Automotive:Waterborne basecoat and clearcoat systems for UAE vehicle assembly and refinishing necessitate specialized wetting agents and flow control additives.
- Protective:Offshore platform and pipeline coatings require extreme-environment additive stability against salt spray and thermal cycling.
Architectural applications dominate value capture; automotive is climbing the fastest as waterborne conversion accelerates.
Form:
Supply concentration in liquid additive manufacturing shapes regional distribution economics, while powder form growth reflects furniture and automotive OEM equipment retrofits.
- Liquid:Pumpable dispersions of rheology modifiers, dispersants, and wetting agents dominate commercial supply, with Jebel Ali and Dammam port infrastructure optimizing bulk chemical handling for Saudi and Emirati formulators.
- Powder:Dry cellulosic thickeners and dispersant blends serve furniture coating producers in UAE industrial zones where solvent-borne line conversion requires powder handling compatibility.
- Granules:Dust-free rheology modifier concentrates address occupational exposure regulations in Saudi manufacturing facilities.
- Paste:High-solid pre-dispersed pigment and additive combinations streamline small-batch architectural tinting operations.
Liquid formulations anchor supply today; powder demand is expanding most quickly among converting OEM segments.
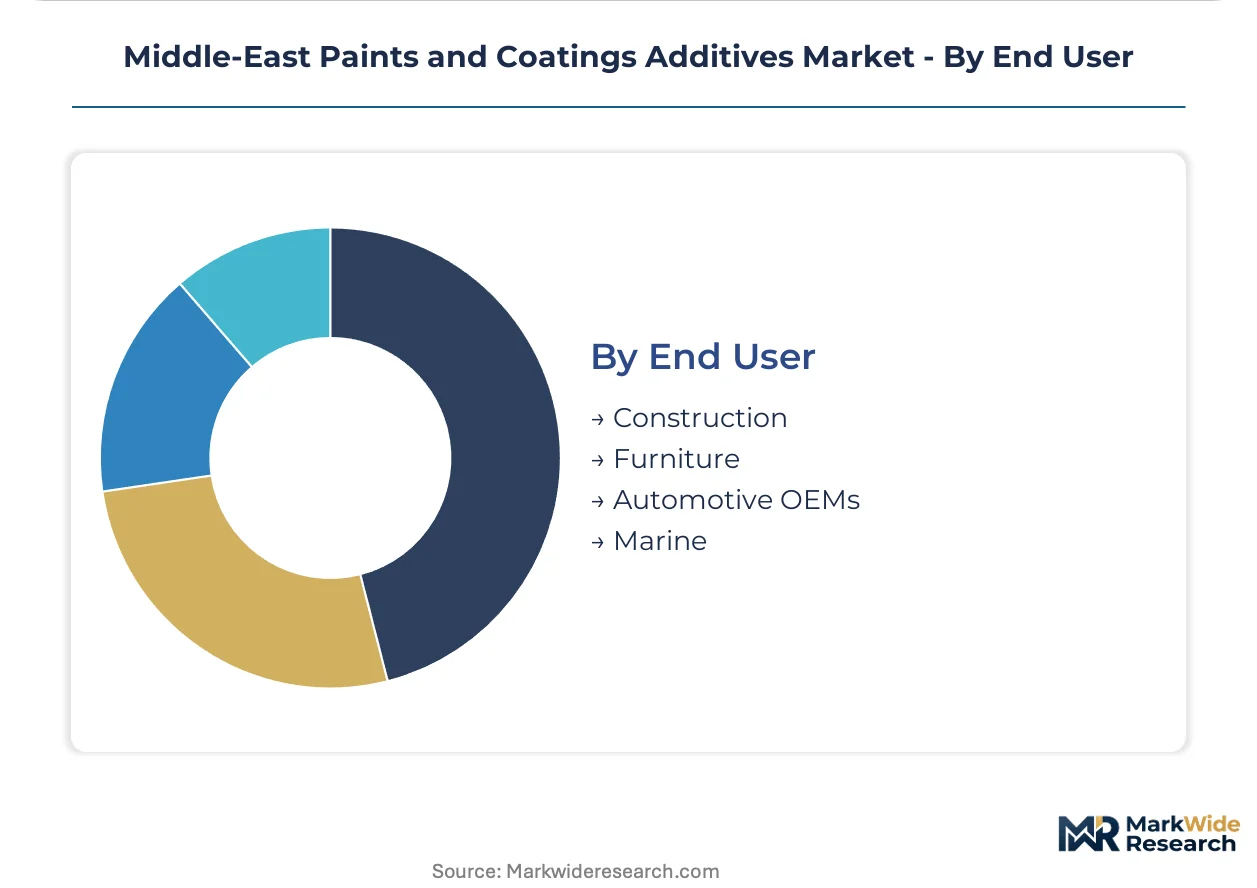
End User:
Customer type fragmentation concentrates procurement leverage among Saudi giga-project general contractors, while smaller furniture and marine segments operate through distributor channels with limited technical service access.
- Construction:Saudi giga-project developers and UAE mega-infrastructure contractors specify additive-inclusive coating systems with direct supplier accountability for film performance warranties under extreme climate exposure.
- Automotive OEMs:Dubai and Jeddah vehicle assembly plants and refinishing networks drive waterborne system conversion, requiring localized technical support for viscosity stabilization under high-temperature shop conditions.
- Furniture:Wood coating manufacturers in UAE industrial clusters source powder and liquid additives for solvent-to-waterborne line transitions.
- Marine:Offshore vessel and platform operators in Arabian Gulf waters procure protective coating systems with anti-corrosive additive packages through specialized marine coatings distributors.
Construction commands the largest procurement volumes; automotive OEMs are driving specification change fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jeddah-Riyadh corridor additive demand is accelerating as Saudi giga-projects compress coating formulation cycles under extreme summer temperatures. Procurement leverage concentrates among general contractors specifying direct supplier accountability for film performance warranties.
Saudi Arabia
Neom and Red Sea Project developments are consuming premium rheology modifiers and UV-stabilized surface additives for self-cleaning exterior specifications. SASO chemical registration mandates under the SFDA framework are accelerating waterborne system conversion ahead of enforcement deadlines. Riyadh manufacturing clusters are pre-qualifying additive packages under dual Saudi-Emirati regulatory timelines to prevent supply chain fragmentation.
United Arab Emirates
Dubai and Abu Dhabi mega-infrastructure contractors are driving specification-grade architectural coating procurement with stringent VOC thresholds. The Ministry of Climate Change and Environment is tightening imported coating material standards ahead of Saudi enforcement, compressing lab testing cycles. Jebel Ali port infrastructure optimizes bulk chemical handling for formulators converting solvent-borne manufacturing lines.
Qatar
World Cup legacy infrastructure maintenance and new stadium-adjacent commercial developments are sustaining additive consumption for protective and decorative systems. The national chemicals regulator maintains substance notification requirements that parallel Gulf Cooperation Council harmonization initiatives. Doha industrial zones are attracting secondary suppliers seeking lower competitive saturation than Saudi or Emirati markets.
Kuwait
Construction recovery in residential and commercial segments is expanding demand for architectural coating additives with desert climate durability specifications. The national environmental authority is implementing VOC content thresholds for imported coating materials following regional regulatory convergence patterns. Shuwaikh industrial area coating manufacturers are retrofitting solvent-borne equipment for waterborne additive package compatibility.
Oman
Port and logistics infrastructure expansion in Duqm and Sohar is driving protective coating additive demand for steel corrosion resistance in marine atmospheres. The national standards body is aligning chemical registration requirements with emerging Gulf Cooperation Council frameworks. Muscat industrial clusters are accelerating infrastructure spending with less saturated supplier competition than core Gulf markets.
Middle-East Paints and Coatings Additives Market Competitive Landscape
Global majors compete with regional champions across technical service proximity and regulatory navigation capabilities. The supplier base organizes into three tiers: integrated petrochemical conglomerates with captive additive production, specialty chemical houses with localized formulation support, and regional distributors with customs clearance expertise. Consolidation pressure intensifies as Saudi giga-project procurement concentrates volume among fewer coating formulators. Dominant competitive moves include regional technical center expansion and dual-jurisdiction regulatory pre-qualification of additive packages.
Among integrated material science conglomerates, Dow and BASF SE anchor the premium tier through regional production assets and localized dispersant manufacturing. Specialty additive producers including Evonik Industries occupy positions defined by silicone-based technology differentiation for high-temperature Gulf application conditions. These three exemplify the strategic archetype of global capability combined with Middle Eastern climate-specific formulation support.
| Leading Market Players |
|---|
| Dow |
| Solvay |
| Altana Group (BYK) |
| Ashland |
| Elementis |
| BASF SE |
| Arkema |
| Evonik Industries |
| Cabot Corporation |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between SFDA-registered and unregistered additive packages bifurcates procurement economics across Saudi and Emirati manufacturing lines. Premium formulations command material margins through guaranteed customs clearance, while commodity alternatives face price erosion from parallel documentation costs and reformulation delays.
Pricing Analysis
Acrylic monomer and silicone precursor cost pass-through dominates contract structures, with petrochemical feedstock volatility compressing margins for polyacrylate and organosilicon producers. Three-tier pricing structure across premium, standard, and economy levels reflects dual-registration compliance status and technical service bundling. Pricing pressure stems from buyer consolidation among Saudi giga-project general contractors demanding direct supplier accountability. Small Emirati furniture coating manufacturers exhibit highest price sensitivity due to legacy equipment retrofit capital constraints.
Supply Chain Analysis
Saudi local-content mandates under Vision 2030 industrialization targets are reshaping sourcing patterns toward Jeddah and Jubail manufacturing clusters. Rheology modifier core polymers concentrate in German, Chinese, and South Korean production, exposing formulators to shipping bottlenecks through Jebel Ali and Dammam. Single-source vulnerability runs through European silicone precursor suppliers serving high-temperature defoamer formulations. Distribution runs through regional technical service centers that anchor bulk chemical handling relationships with Saudi Aramco and SABIC-affiliated contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where Neom and Red Sea Project specifications reward additive suppliers with climate-stabilized formulation capabilities. Premium architectural coating demand is displacing commodity procurement across Saudi giga-project channels.
For Market Incumbents: Anchor regional technical service density in Riyadh and Dubai to defend against emerging Asian suppliers with price-competitive dispersant portfolios. Deepen backward integration into silicone precursor supply to offset petrochemical feedstock volatility. Pre-qualify additive packages under converging Saudi-Emirati regulatory timelines to capture procurement consolidation among general contractors.
For New Entrants and Emerging Players: Photocatalytic self-cleaning additive technology offers a technology-first wedge into underpenetrated Omani and Kuwaiti construction recovery markets. Target protective coating segments for Duqm port infrastructure where corrosion-resistant specifications outpace supplier competition. Partner with Jebel Ali distributors for customs clearance expertise rather than building direct sales infrastructure.
For Investors and Strategic Acquirers: Consolidation pressure builds where formulation chemist scarcity intersects with dual-registration compliance burdens. Five-to-ten year viability favors specialty additive houses with localized production assets and climate-specific R&D capabilities. Acquisition target archetype: mid-cap silicone technology specialists with existing SFDA registration pathways. Watch for GCC chemical inventory harmonization completion as inflection indicator for margin normalization.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Precursors | Captive supply of organosilicon feedstock insulates margin from oil-linked volatility in Saudi production. |
| Dual-Jurisdiction Regulatory Pre-Qualification | Simultaneous SFDA and UAE Ministry of Climate Change registration prevents supply chain fragmentation for multinational suppliers. |
| Regional Technical Center Expansion | Localized formulation support in Jeddah and Dubai anchors relationships with giga-project general contractors. |
| Photocatalytic Additive Package Development | Titanium dioxide and zinc oxide surface modifiers address labor cost pressures in high-dust Neom exterior applications. |
| Long-Term Supply Agreement with Giga-Project Developers | Direct accountability for film performance warranties under extreme climate exposure locks in volume commitments. |
Research Methodology
Multiple input streams — executive interviews with formulation directors at Saudi and Emirati coating manufacturers, procurement leads at giga-project general contractors, and regulatory affairs specialists navigating SFDA and UAE Ministry of Climate Change frameworks — were reconciled against customs and trade data, GCC chemical registration filings, and SEC disclosures from listed material science conglomerates. Bottom-up volume estimates from additive consumption patterns were triangulated with top-down market sizing derived from construction spend allocations and coatings production capacity.
Data-stream reconciliation across product type, application, form, and end-user segmentation dimensions shaped the analytical framework throughout the projection horizon. CAGRs were derived from regression analysis of historical consumption patterns against infrastructure investment pipelines. Industry-specific forecast inputs included Saudi giga-project coating specification timelines and waterborne system conversion rates among UAE furniture OEMs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to GCC regulatory harmonization completion and petrochemical feedstock volatility. Forecasts reflect documented assumptions regarding construction velocity and reformulation cycle timing. Regulatory enforcement divergence, shipping bottleneck persistence through Jebel Ali, and formulation chemist availability constitute specific risk factors that could revise projections. A small set of named triggers — SASO chemical inventory updates, Neom project phase completions, and Emirati green procurement mandate expansion — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Insulating Paints and Coatings Market
Paints & Coatings
Mexico Paints and Coatings Market
Paints & Coatings
Canvas Primer Market
Paints & Coatings
Interior Architectural Coatings Market
Paints & Coatings
Global Paints and Coatings Fillers Market
Paints & Coatings
Faux Finish Coatings Market
Paints & Coatings
Automotive Paints and Coatings Market
Paints & Coatings
Sri Lanka Paints and Coatings Market
Paints & Coatings
Architectural Coatings Market
Paints & Coatings
India Floor Coatings Market
Paints & Coatings
Bituminous Paints Market
Paints & Coatings
Fire Resistant Paints Market
Paints & Coatings
India Automotive Paints and Coatings Market
Paints & Coatings
South America Architectural Coatings Market
Paints & Coatings
India Paints and Coatings Market
Paints & Coatings
Resins in Paints and Coatings Market