
 Paint Thinner Market | 2026-2036
Paint Thinner Market Size, Share, and Industry Trends Forecast 2026-2036
Paint Thinner Market Analytics
Petrochemical refinery output in the US Gulf Coast is hardening the supply base for aromatic hydrocarbon feedstocks. BASF SE leverages integrated aromatics complexes in Geismar, Louisiana to sustain captive toluene and xylene supply for formulated thinners. PPG Industries, Inc. competes through vertical control over distribution channels serving automotive collision repair networks. The Sherwin-Williams Company anchors North American volume with dedicated thinner lines tied to its architectural coatings retail footprint.
Paint thinner denotes a solvent blend, typically comprising aliphatic hydrocarbons, aromatics, oxygenated solvents, or water-carried co-solvents, formulated to reduce coating viscosity for spray application or surface cleaning with specific evaporation rates between 0.5 and 8.0 relative to n-butyl acetate. Its primary commercial purpose centers on enabling proper film formation in alkyd, acrylic, and epoxy coating systems while controlling flow and leveling during application. Mineral spirits formulations occupy the largest volume share in architectural maintenance, whereas bio-based formulations, derived from agricultural esters and terpenes, represent the fastest-expanding category as VOC regulations tighten. Solvent-based chemistry still dominates industrial and automotive end uses where drying speed and substrate adhesion requirements resist waterborne substitution.
The US EPA enforces NESHAP standards that limit HAP emissions from coating operations, directly constraining solvent selection and driving reformulation toward exempt compounds or water-based systems. OSHA permissible exposure limits for toluene and xylene govern workplace handling protocols, affecting industrial user procurement specifications and personal protective equipment requirements. California's South Coast Air Quality Management District imposes the nation's strictest VOC limits on architectural coatings, creating a regulatory laboratory that influences national product development trajectories. Stakeholders must monitor the pace of EPA rulemaking on consumer product VOC limits and assess whether bio-based feedstock cost curves can close the gap with petroleum-derived alternatives before the next regulatory compliance cycle.
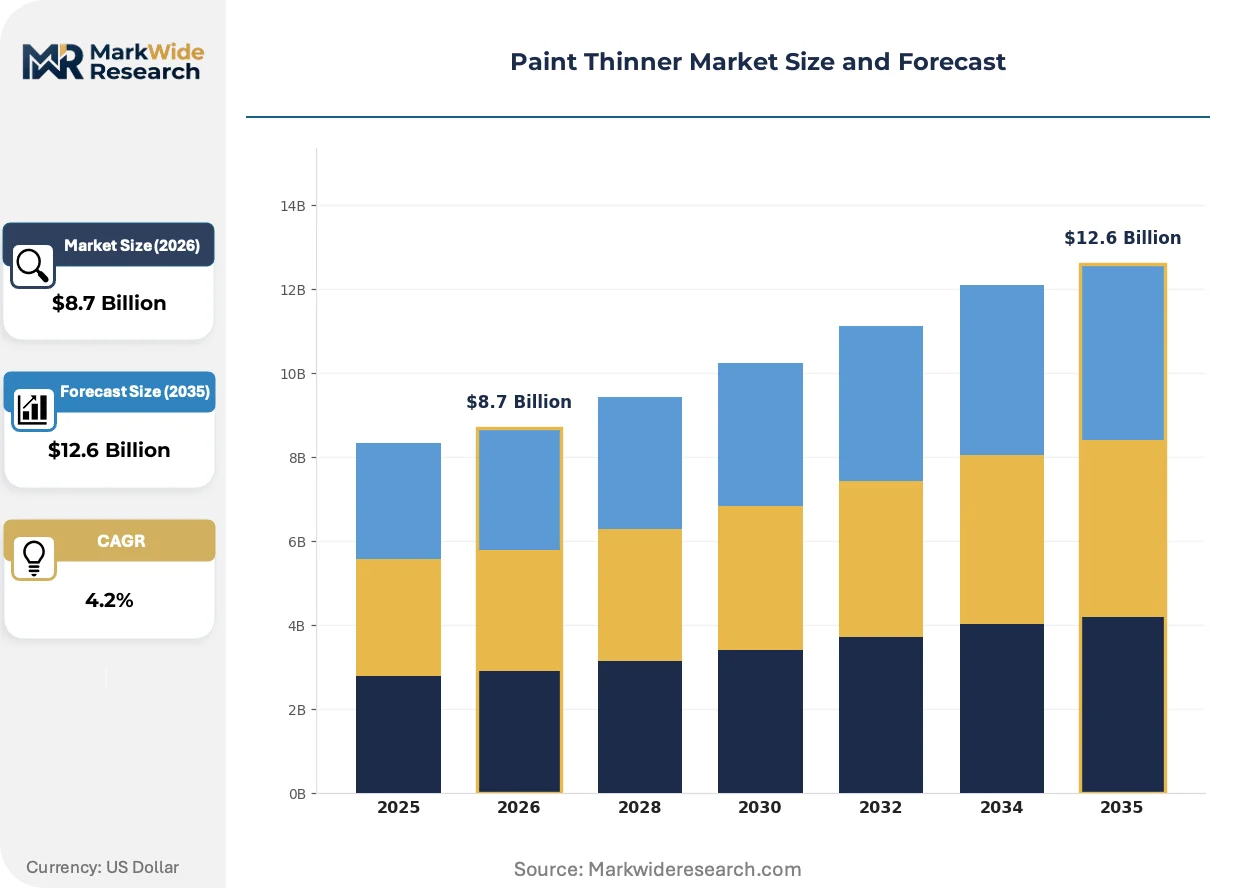
Market Dynamics
EPA's National Emission Standards for Hazardous Air Pollutants is compressing solvent selection flexibility across automotive refinishing and architectural coatings, forcing reformulation toward exempt compounds and waterborne systems before the next compliance cycle.
Growth Catalysts
- Automotive refinishing demand:Collision repair volume in the United States sustains solvent throughput for waterborne basecoat systems. Body shop consolidation concentrates purchasing power with distributors carrying captive thinner lines.
- NESHAP compliance cycles:EPA's tightening volatile organic compound limits on industrial maintenance coatings accelerates replacement of conventional aliphatic formulations. Facilities must retrofit spray booths and recovery systems.
- Petrochemical feedstock availability:Aromatic hydrocarbon output from US Gulf Coast refineries hardens supply security for toluene and xylene derivatives. Integrated aromatics complexes reduce formulation cost volatility.
Market Restraints
- Crude oil price transmission:Naphtha and natural gas liquid feedstock costs determine mineral spirits pricing. Refinery margin compression in the US Gulf Coast passes through to formulated thinner costs.
- Waterborne substitution limits:Industrial epoxy and high-performance alkyd systems resist water-based reformulation due to substrate adhesion and corrosion resistance requirements. Solvent-based chemistry retains captive demand.
- California SCAQMD precedent:The South Coast Air Quality Management District's architectural coating rules create compliance fragmentation. National manufacturers must maintain dual formulation inventories.
Strategic Opportunities
- Agricultural ester feedstocks:Bio-based thinners derived from soy methyl esters and citrus terpenes qualify for VOC-exempt status under EPA regulations. Cost curves are compressing against petroleum alternatives.
- Direct-to-body-shop distribution:E-commerce platforms serving independent collision repair facilities bypass traditional distributor markups. Digital procurement tools enable just-in-time inventory management.
- Consumer product reformulation:EPA rulemaking on architectural coating VOC limits for retail channels opens formulation services contracts. Private-label thinner production for home improvement retailers represents white-space expansion.
Industry Challenges
- Solvent recovery infrastructure:NESHAP-compliant distillation and carbon adsorption systems require capital deployment. Small and mid-sized coating operations face equipment financing constraints.
- Cross-regulatory compliance:OSHA permissible exposure limits for toluene and xylene govern workplace handling protocols. Personal protective equipment specifications vary by state enforcement posture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paint Thinner Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $12.6 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Acetone, Mineral Spirits, Toluene, Xylene Application: Cleaning, Thinning, Paint Stripping, Degreasing Formulation: Water-Based, Solvent-Based, Bio-Based, Conventional End User: Industrial, Automotive, DIY, Professional |
| Companies Covered | Axalta Coating Systems, LLC, Jotun, Akzo Nobel N.V., Kansai Paint Co., Ltd., RPM International Inc., PPG Industries, Inc., Hempel A/S, BASF SE, The Sherwin-Williams Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paint Thinner Market Evolving Landscape
Bio-based solvent chemistry is expanding from niche architectural applications into industrial maintenance segments as VOC regulations tighten and feedstock economics improve.
Low-VOC terpene formulations are expanding into automotive refinishing clearcoat systems. Tier-one collision repair networks in California and the Northeast are piloting citrus-derived thinners for compliance with SCAQMD Rule 1113. The technology is expanding into solvent blends previously dominated by petroleum-derived aromatic hydrocarbons.
REACH authorization requirements for toluene and xylene derivatives in the European Union are accelerating substitution research. Industrial coating manufacturers serving export markets must maintain dual formulation capabilities. The regulation is compressing product development cycles as sunset dates approach for legacy solvent systems.
Specification-driven procurement is consolidating thinner purchasing with integrated coatings suppliers. Automotive OEM certified repair programs now mandate captive thinner lines for warranty compliance. Independent distributors in the United States are losing share to direct manufacturer relationships with multi-shop collision networks.
Paint Thinner Market Segmentation
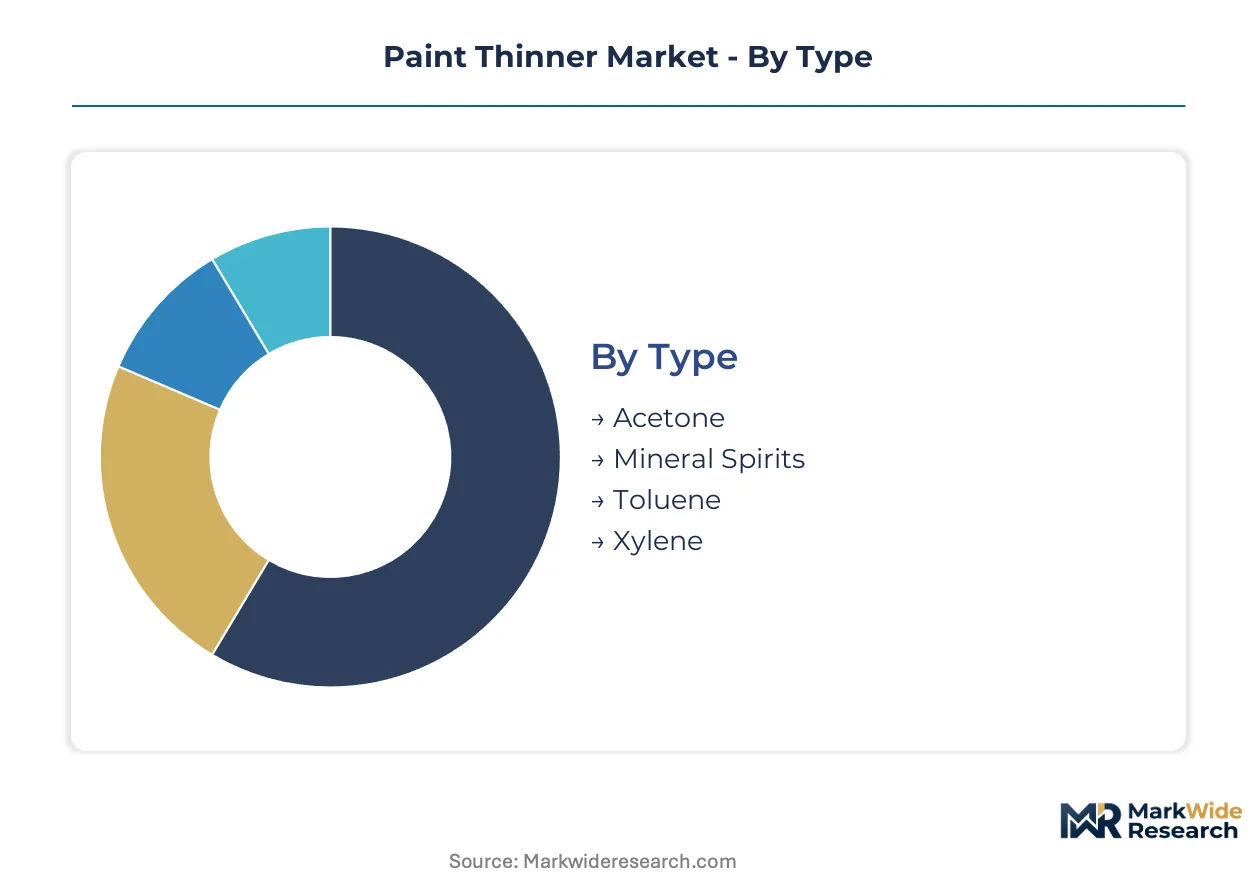
Paint thinner procurement cycles track coating reformulation mandates and substrate-specific performance requirements. Segmentation reveals where solvent chemistry retains pricing power versus where waterborne and bio-based alternatives displace conventional formulations.
Type:
Replacement cycles for thinner types accelerate as EPA NESHAP compliance deadlines force body shops and industrial facilities to retire high-HAP formulations.
- Acetone:A ketone solvent with rapid evaporation rates suited for epoxy and polyester resin cleanup. Demand concentrates in automotive refinishing shops across Texas and Michigan where collision repair volume sustains throughput for waterborne basecoat systems. OSHA's permissible exposure limits drive enclosed storage and automated dispensing investments.
- Mineral Spirits:Aliphatic hydrocarbon blends with controlled evaporation between 0.5 and 3.0 relative to n-butyl acetate. Architectural maintenance contractors in California's South Coast Air Quality Management District territory favor low-aromatic grades to meet Rule 1113 VOC limits. SCAQMD's precedent forces national manufacturers to maintain dual formulation inventories.
- Toluene:Aromatic solvent with strong solvency for alkyd and nitrocellulose coatings. Industrial users in Ohio and Illinois retain demand for high-performance applications where waterborne substitution fails on substrate adhesion.
- Xylene:Mixed isomer aromatic with slower evaporation than toluene, enabling flow control in industrial enamel systems. Refinery output from Louisiana's integrated aromatics complexes hardens supply security for formulated blends.
Mineral Spirits sits at the top of the volume ranking, with Acetone climbing the fastest.
Application:
Application-driven procurement splits between specification-bound industrial contracts and price-sensitive maintenance operations.
- Cleaning:Surface preparation for coating adhesion requires residue-free evaporation. Automotive OEM certified repair programs mandate specific thinner grades for warranty compliance, consolidating purchasing with captive distributor lines.
- Thinning:Viscosity reduction for spray application dominates solvent consumption. Collision repair networks in the Northeast pilot low-VOC terpene formulations to preempt regulatory tightening.
- Paint Stripping:Aggressive solvency for removing cured coatings. Methylene chloride restrictions in consumer products have shifted demand toward NMP-based and bio-derived alternatives in architectural restoration.
- Degreasing:Metal substrate preparation before industrial coating. Heavy equipment manufacturers in Wisconsin and Pennsylvania specify flash point and residue requirements in procurement contracts.
Thinning commands the largest share of solvent throughput, with Cleaning gaining share fastest as surface preparation standards tighten.
Formulation:
Formulation selection tracks the cost curve gap between petroleum-derived and agricultural feedstocks.
- Solvent-Based:Petroleum-derived hydrocarbon and oxygenated solvent blends. Industrial epoxy and high-performance alkyd systems in the US Gulf Coast resist waterborne substitution due to corrosion resistance specifications.
- Water-Based:Co-solvent systems with reduced VOC content. California's architectural coating rules have normalized waterborne alkyd technology for residential maintenance applications.
- Bio-Based:Agricultural ester and terpene derivatives from soy methyl esters and citrus processing. Cost curves are compressing against mineral spirits as VOC-exempt status under EPA regulations improves economics.
- Conventional:Unrestricted aromatic and aliphatic blends predating modern VOC limits. Captive demand persists in industrial segments where reformulation timelines lag regulatory deadlines.
Solvent-Based retains the highest volume position, with Bio-Based expanding most quickly as feedstock scale improves.
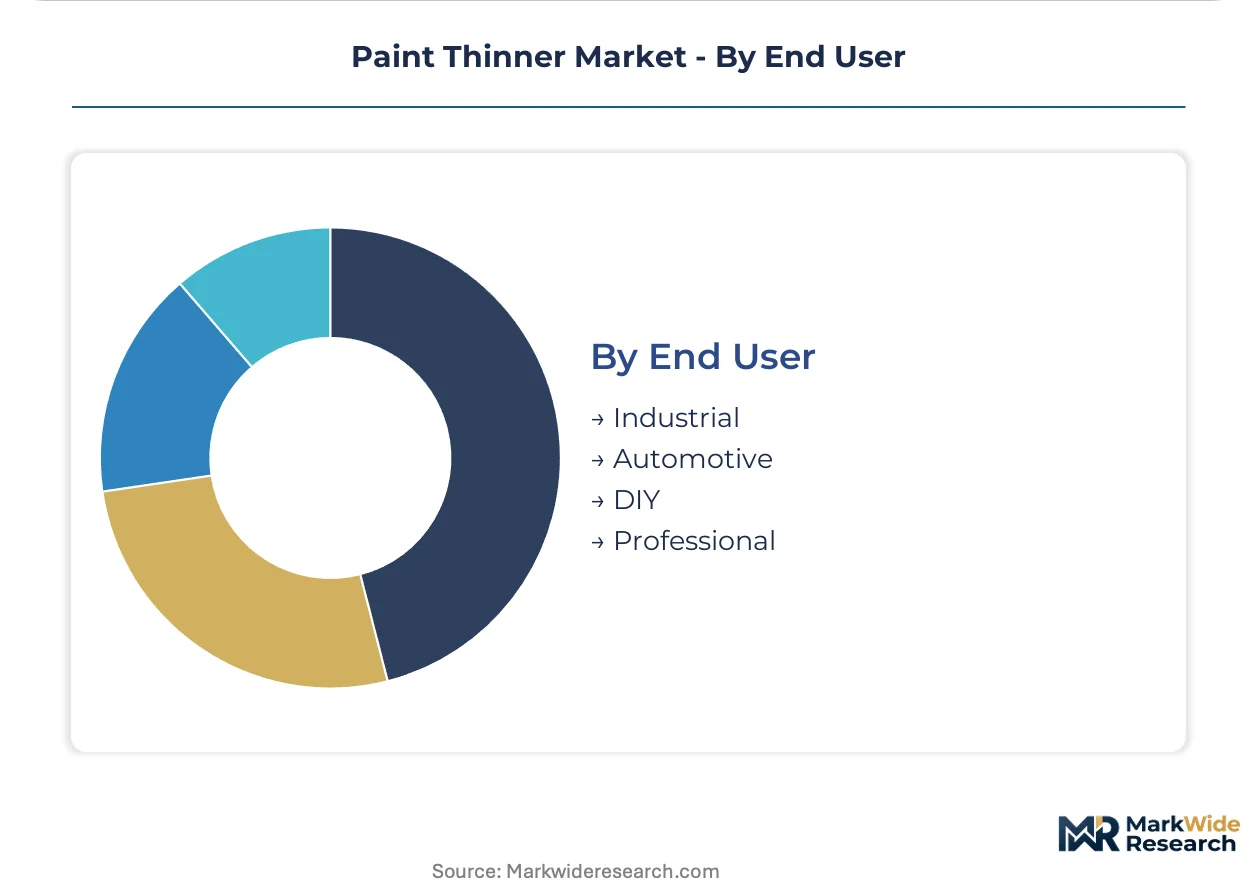
End User:
End user segmentation reflects the divergence between specification-driven procurement and price-elastic retail demand.
- Automotive:Collision repair and OEM refinishing operations with certified thinner mandates. Body shop consolidation concentrates purchasing power with distributors carrying PPG and Sherwin-Williams captive lines.
- Industrial:Manufacturing maintenance and protective coatings with performance-based specifications. NESHAP-compliant spray booth retrofits and solvent recovery systems require capital deployment that favors larger facilities.
- DIY:Home improvement retail channels with price-sensitive demand. EPA rulemaking on consumer product VOC limits opens private-label formulation services contracts.
- Professional:Commercial painting contractors balancing compliance cost against application efficiency. E-commerce platforms serving independent operators bypass traditional distributor markups.
Industrial users represent the largest volume segment, with Automotive expanding fastest as collision repair volume sustains solvent throughput.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive refinishing sector consumes thinner volumes at triple the per-capita rate of Brazil, yet both markets face divergent regulatory pressures on solvent chemistry.
United States
Collision repair volume in Texas and Michigan sustains aromatic hydrocarbon throughput for waterborne basecoat systems. EPA's NESHAP standards compress solvent selection flexibility, forcing body shop retrofits before compliance deadlines. Louisiana's Geismar aromatics complex anchors supply security for toluene and xylene derivatives serving Gulf Coast industrial users.
Germany
Automotive OEM production schedules in Bavaria and Baden-Württemberg drive specification-grade thinner procurement for certified repair networks. REACH authorization requirements for toluene derivatives accelerate substitution research among export-oriented coating manufacturers. The Ruhr industrial cluster maintains captive demand for high-performance alkyd systems resisting waterborne reformulation.
China
Construction activity in the Yangtze River Delta and Pearl River Delta sustains mineral spirits consumption for architectural maintenance applications. MEE enforcement of VOC limits on industrial coatings tightens solvent selection in manufacturing hubs. Shandong Province's petrochemical capacity expands aromatic feedstock availability for domestic formulation.
Brazil
Industrial protective coatings demand in São Paulo and Rio de Janeiro sustains solvent-based chemistry for corrosion resistance specifications. ANVISA workplace exposure protocols govern toluene handling in manufacturing facilities. The Southeast region's automotive assembly plants concentrate thinner procurement with integrated coatings suppliers.
India
Automotive refinishing growth in Maharashtra and Tamil Nadu expands consumption for epoxy and polyurethane coating systems. BIS standards on solvent quality create compliance thresholds for imported formulations. The Delhi-NCR industrial corridor faces intensifying state-level air quality mandates on coating operations.
Paint Thinner Market Competitive Landscape
US producers anchor one tier; European specialists hold formulation technology positions; Asian manufacturers compete on aromatic feedstock integration. The market structures around three tiers: integrated petrochemical majors with captive solvent supply, coatings specialists with dedicated thinner lines, and regional distributors serving fragmented body shop networks. Two dominant competitive moves are reshaping positions: backward integration into aromatics production and direct-to-shop distribution bypassing traditional wholesale channels.
Within the integrated majors tier, BASF SE and PPG Industries, Inc. exemplify divergent strategic postures. BASF's position reflects upstream control over Geismar aromatics complexes. PPG occupies a channel-anchored position through collision repair network relationships. Among coatings specialists, The Sherwin-Williams Company represents the retail-architecture model with dedicated thinner lines tied to architectural coatings distribution. These three entities collectively illustrate how supply security, distribution control, and formulation expertise define competitive separation in solvent markets.
| Leading Market Players |
|---|
| Axalta Coating Systems, LLC |
| Jotun |
| Akzo Nobel N.V. |
| Kansai Paint Co., Ltd. |
| RPM International Inc. |
| PPG Industries, Inc. |
| Hempel A/S |
| BASF SE |
| The Sherwin-Williams Company |
| Others |
Value Network & Pricing Analysis
A performance-grade divergence between NESHAP-compliant reformulated thinners and legacy aromatic formulations manifests in both margin structures and procurement channel configurations. Premium pricing accrues to exempt-compound products serving California SCAQMD and Northeast automotive networks, while commodity mineral spirits compete on refinery-margin pass-through in unregulated maintenance segments.
Pricing Analysis
Distributor margin layering separates captive thinner lines sold through PPG and Sherwin-Williams collision repair networks from private-label alternatives in home improvement retail. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade, with OEM-mandated products commanding 15-25 point premiums over generic mineral spirits. Cost compression in aliphatic hydrocarbon feedstocks is intensifying because US Gulf Coast refinery margin pressure transmits directly to formulated product costs. DIY retail channels exhibit highest price sensitivity, whereas automotive certified repair programs show inelastic demand tied to warranty compliance requirements.
Supply Chain Analysis
Solvent recovery and distillation infrastructure creates reverse-logistics value capture for large industrial coating operations, with spent thinner reclamation reducing virgin solvent procurement by 30-40 percent in NESHAP-compliant facilities. Geographic supply concentration centers on the United States, Germany, and China, with Louisiana's Geismar aromatics complex and Shandong Province petrochemical capacity anchoring regional feedstock security. Raw material dependencies draw from naphtha, natural gas liquids, and agricultural ester feedstocks. Single-source vulnerability concentrates in toluene and xylene derivatives from integrated aromatics complexes. Distribution runs through coatings-specialist distributors serving collision repair networks, bypassed increasingly by direct manufacturer relationships with consolidated multi-shop operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EPA NESHAP compliance cycles and California SCAQMD precedent create sustained reformulation demand across automotive and architectural end uses.
For Market Incumbents: Anticipate bio-based substitution pressure by securing agricultural ester supply agreements before feedstock cost curves compress further. Defensive consolidation moves should prioritize captive aromatics supply through backward integration into refinery partnerships or long-term offtake contracts, while channel control investments in direct-to-body-shop digital platforms counter distributor disintermediation. Threats from waterborne system substitution in automotive clearcoat applications require monitoring pilot programs at Tier-one collision networks in California and the Northeast. For New Entrants and Emerging Players: EPA rulemaking on consumer product VOC limits opens a window for private-label formulation services contracts with home improvement retailers seeking compliant architectural thinner lines. White-space targets concentrate on bio-based terpene formulations for SCAQMD Rule 1113 compliance, where agricultural feedstock scale economies remain underdeveloped. The most penetrable segment sits in professional contractor e-commerce procurement, bypassing traditional distributor markups through just-in-time inventory platforms serving independent painting operations. For Investors and Strategic Acquirers: Consolidation pressure builds where small and mid-sized coating operations face NESHAP-compliant equipment financing constraints, creating acquisition targets with installed customer bases but insufficient capital for solvent recovery infrastructure deployment. Long-term viability favors integrated positions combining feedstock security with distribution channel control. The signal to watch is EPA acceleration of consumer product VOC rulemaking timelines, which would compress reformulation windows and favor scaled formulators with regulatory response capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aromatics | BASF's Geismar complex demonstrates captive toluene security against feedstock volatility. |
| Bio-Based Feedstock Scale-Up | Soy methyl ester and citrus terpene cost curves compress against petroleum alternatives under EPA exempt status. |
| Direct-to-Body-Shop Distribution | Digital procurement platforms bypass traditional distributor markups in consolidated collision repair networks. |
| NESHAP-Compliant Equipment Financing | Solvent recovery infrastructure deployment separates capital-rich facilities from constrained competitors. |
| Private-Label Formulation Services | Home improvement retailers seek compliant architectural thinner lines under pending EPA consumer product rules. |
Research Methodology
Direct dialogue with plant managers at industrial coating facilities, procurement leads at automotive OEM certified repair networks, distribution channel partners, and technical R&D directors at formulated product suppliers grounded qualitative assessment. Secondary validation drew from EPA NESHAP rulemaking dockets, California SCAQMD Rule 1113 compliance records, SEC 10-K filings from coatings specialists, and American Chemistry Council solvent market reports. Bottom-up and top-down triangulation reconciled facility-level consumption estimates with refinery output data across the analysis window.
Bottom-up modeling built from segment-level consumption rates by end-use industry, formulation type, and regional regulatory cluster, then aggregated to market totals. Top-down verification cross-checked against petrochemical feedstock availability and coatings production indices. Segmentation dimensions included solvent chemistry type, application function, formulation category, and end-user procurement specification. CAGRs derived from regression analysis of historical consumption patterns against regulatory compliance deadline schedules and collision repair volume trends.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EPA rulemaking or breakthrough waterborne adhesion technology for industrial epoxy systems. Practitioners should monitor EPA consumer product VOC proposal timelines and agricultural ester feedstock scale announcements for early signals of competitive repositioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Core Plate Varnishes Market
Paints & Coatings
Floor Paints Market
Paints & Coatings
Nordic Countries Architectural Coatings Market
Paints & Coatings
Paint Rollers Market
Paints & Coatings
Industrial Paint Booth Market
Paints & Coatings
Iraq Paints and Coatings Market
Paints & Coatings
Asia-Pacific Paint Spray Guns Market
Paints & Coatings
Water-Borne Latex Paints Market
Paints & Coatings
Middle East and Africa Floor Coatings Market
Paints & Coatings
Radar Absorbing Paint Market
Paints & Coatings
South America Architectural Coatings Market
Paints & Coatings
Global Aerosol Paints Market
Paints & Coatings
Fluorescent Paint Market
Paints & Coatings
North America Paints and Coatings Market
Paints & Coatings
Global Decorative Coatings Market
Paints & Coatings
Bahrain Paints and Coatings Market