
 Human Acellular Dermis Market | 2026-2036
Human Acellular Dermis Market Size, Share, and Industry Trends Forecast 2026-2036
Human Acellular Dermis Market Insights
Allograft-derived matrices are recalibrating cost structures across reconstructive surgery suites as procurement teams weigh biological performance against synthetic alternatives. Integra LifeSciences leverages its vertically integrated tissue processing network to sustain margin stability amid raw material variability. MTF Biologics anchors its competitive stance through nonprofit tissue banking relationships that control donor supply access.
Human acellular dermis comprises decellularized extracellular matrix retaining collagen scaffold architecture without immunogenic cellular material, enabling host cell infiltration and revascularization across full-thickness wound beds. The decellularization segment commands premium positioning due to proprietary detergent-enzyme protocols that preserve basement membrane integrity for faster engraftment. Freeze-dried allograft formats dominate hospital formulary adoption where extended shelf life reduces cold-chain logistics burden, while bioengineered variants occupy emerging niches in complex reconstructive cases requiring customizable thickness profiles.
FDA tissue regulation under 21 CFR Part 1271 shapes donor screening and processing validation requirements that determine market access timelines for new entrants. The EMA's ATMP classification framework creates parallel compliance pathways for European commercialization that diverge from US predicate device routes. Stakeholders must monitor evolving reimbursement coding decisions by CMS and comparable national payers that will determine whether biological matrices retain procedure economics against advancing synthetic substitutes.
Market Dynamics
Consolidated purchasing by integrated health networks is compressing supplier margins and forcing processors to demonstrate measurable clinical outcomes beyond engraftment rates.
Growth Catalysts
- CMS reimbursement coding:Expanded coverage determinations for biological matrices in breast reconstruction procedures are expanding addressable procedure volumes across Medicare Advantage networks.
- Decellularization automation:Closed-system bioreactor protocols are reducing batch-to-batch variability and accelerating regulatory validation timelines for new tissue processors.
- Burn center expansion:Tertiary hospital construction in Texas, Florida, and California is adding dedicated biologics storage capacity for complex wound management protocols.
Market Restraints
- Donor tissue scarcity:Voluntary donation rates constrain raw material availability, creating procurement queues that extend lead times for high-thickness allograft variants.
- Synthetic substitute advancement:Polymeric scaffolds with integrated antimicrobial properties are capturing formulary slots in cost-constrained hospital systems.
- FDA 21 CFR Part 1271 traceability mandates:Enhanced donor record documentation requirements are extending quality assurance timelines and elevating compliance staffing costs for domestic processors.
Strategic Opportunities
- Outpatient surgical center penetration:Ambulatory care facilities in Arizona and Nevada are adopting lyophilized formats for same-day hernia repair procedures.
- Combination product pathways:Convergence of acellular matrices with sustained-release antibiotic coatings is opening 510(k) hybrid regulatory routes.
- Veterans Health Administration contracts:Federal procurement vehicles for battlefield trauma reconstruction are creating dedicated supply channels outside commercial pricing structures.
Industry Challenges
- Biologics supply chain cold-chain integrity:Temperature excursion events during hospital receiving protocols compromise graft viability and trigger rejection disputes.
- Pathogen inactivation validation:Demonstrating complete viral clearance across prion-resistant protocols demands extended study timelines that delay product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Human Acellular Dermis Market |
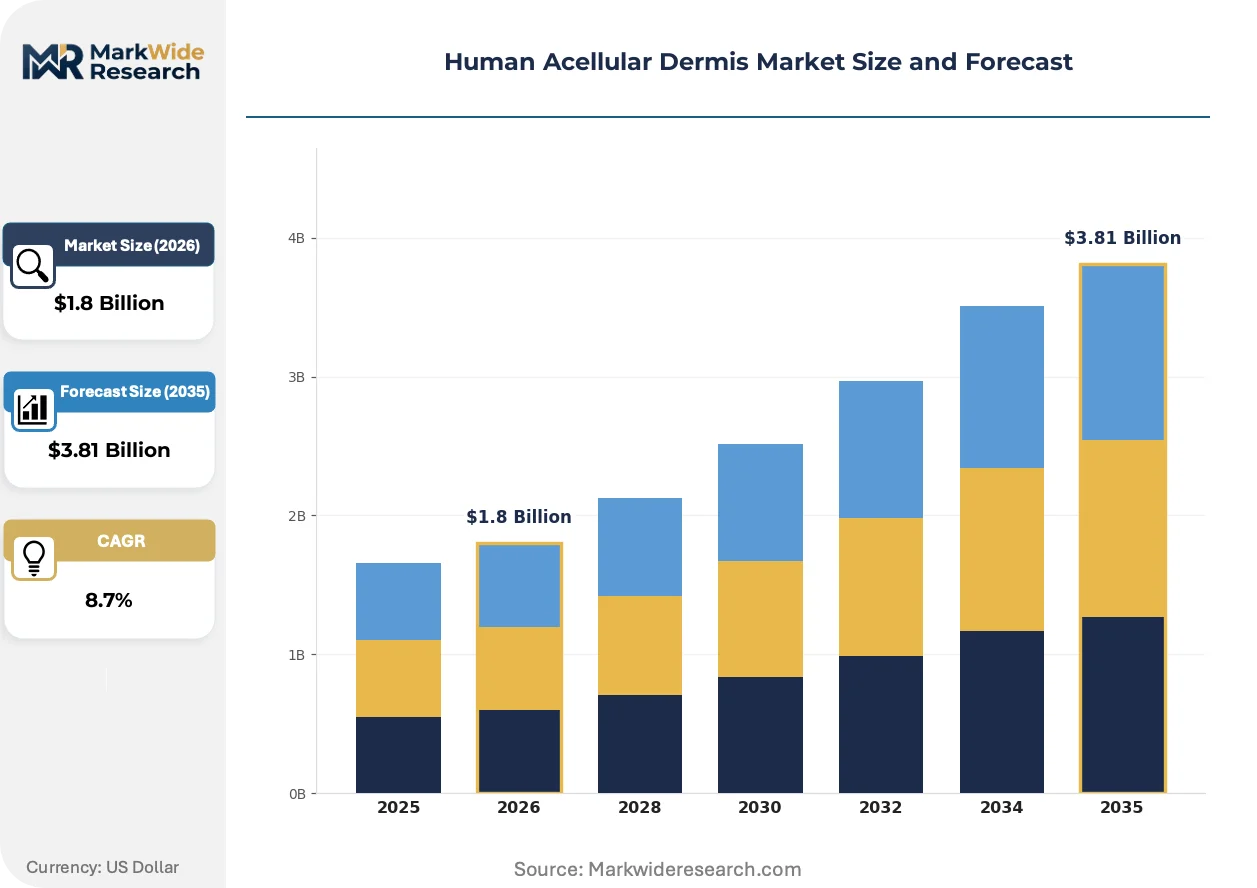
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Allograft, Xenograft, Synthetic, Cellular Matrix End User: Hospitals, Clinics, Ambulatory Surgery Centers, Research Institutes Application: Burn Treatment, Wound Healing, Reconstruction, Cosmetic Surgery Technology: Freeze-Drying, Decellularization, Bioengineering, 3D Printing |
| Companies Covered | Integra LifeSciences Corporation, AbbVie Inc., Johnson & Johnson, Zimmer Biomet Holdings Inc., Stryker Corporation, Smith & Nephew Plc., Organogenesis Holdings Inc., LifeNet Health, MTF Biologics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Human Acellular Dermis Market Trends and Innovations
Processing technologies are converging around preservation methods that extend shelf life without sacrificing basement membrane architecture critical for rapid vascularization.
Lyophilization combined with terminal sterilization is unifying the previously separate cold-chain and ambient-distribution channels, enabling rural hospitals to stock acellular dermis without specialized refrigeration infrastructure. Community medical centers in the Mountain West are adopting these formats for emergency burn coverage. This unification is compressing the historical urban-rural access gap and redistributing procurement volumes away from metropolitan tertiary centers.
EMA's ATMP classification framework is diverging from FDA predicate device routes, forcing manufacturers to maintain parallel technical files for transatlantic commercialization. European notified bodies are demanding additional clinical data packages that US 510(k) pathways do not require. Matrix processors with existing CE marks are responding by segregating product lines rather than pursuing unified global labels.
Hospital value analysis committees are consolidating biologics purchasing decisions and demanding head-to-head clinical outcome data against synthetic alternatives. Integrated delivery networks in the Midwest are replacing individual surgeon preference cards with system-wide formularies. This concentration is most visible in Illinois and Ohio, where three health systems control over sixty percent of reconstructive procedure volumes.
Human Acellular Dermis Market Segmentation
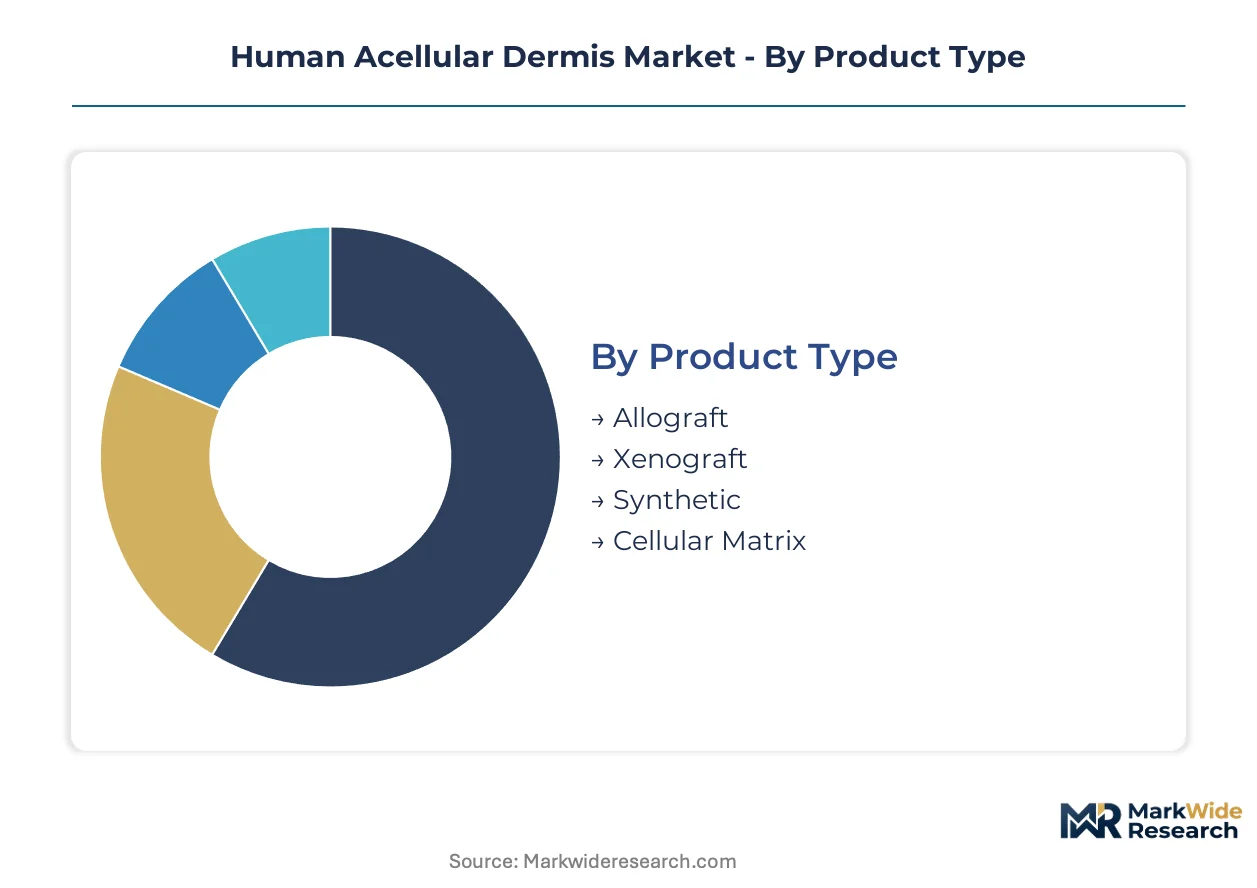
Procurement patterns across the Human Acellular Dermis Market diverge sharply by product architecture and processing method. Hospital value analysis committees weight biological performance specifications against cold-chain logistics burden when segmenting purchasing decisions.
Product Type:
Material origin and immunogenic profile define the technology axis for biological matrix selection.
- Allograft:Decellularized human dermis retains native collagen scaffold architecture and basement membrane integrity for rapid host cell infiltration. Demand concentrates in tertiary burn centers across Texas and Florida where complex wound coverage protocols prioritize engraftment speed over cost minimization.
- Xenograft:Porcine or bovine-derived matrices undergo more aggressive crosslinking to suppress immunogenic response, trading some bioactivity for extended shelf stability. Procurement queues in California academic medical centers favor xenograft variants when allograft thickness specifications are backordered.
- Synthetic:Polymeric scaffolds with tunable degradation profiles occupy cost-constrained hospital formulary slots where reimbursement compression favors predictable unit economics.
- Cellular Matrix:Retained cellular components in cryopreserved formats serve niche applications in cosmetic surgery suites demanding maximal biological activity.
Mature deployment sits with Allograft. Newer deployment is concentrated in Synthetic.
End User:
Facility reimbursement tier and procedure volume shape procurement concentration across the customer base.
- Hospitals:Integrated health networks in Illinois and Ohio consolidate biologics purchasing through system-wide formularies that override individual surgeon preference cards. Tertiary centers with dedicated biologics storage infrastructure command preferential allocation during donor tissue scarcity periods.
- Ambulatory Surgery Centers:Arizona and Nevada outpatient facilities are adopting lyophilized formats for same-day hernia repair procedures where cold-chain elimination enables inventory flexibility. These centers are expanding fastest as procedure migration accelerates.
- Clinics:Wound care clinics in community settings stock limited SKUs based on payer mix constraints.
- Research Institutes:Academic medical centers with NIH funding access experimental matrices outside commercial distribution channels.
Volume concentrates in Hospitals. Margin expansion is strongest in Ambulatory Surgery Centers.
Application:
Clinical outcome requirements and reimbursement coding specificity drive specification differentiation across use cases.
- Burn Treatment:Full-thickness wound coverage demands maximum scaffold thickness with preserved vascular channels for rapid revascularization. CMS expanded coverage determinations for biological matrices in these procedures are expanding addressable volumes across Medicare Advantage networks.
- Reconstruction:Breast reconstruction protocols require customizable thickness profiles and aesthetic contouring capability that bioengineered variants are beginning to address.
- Wound Healing:Chronic diabetic foot ulcers drive recurring demand for mid-thickness allograft in podiatry practices.
- Cosmetic Surgery:Private-pay procedures tolerate premium pricing for cellular matrix formats with maximal biological activity.
Reimbursement stability sits with Burn Treatment. Pricing flexibility is greatest in Cosmetic Surgery.
Technology:
Processing methodology determines regulatory pathway, shelf life, and basement membrane preservation fidelity.
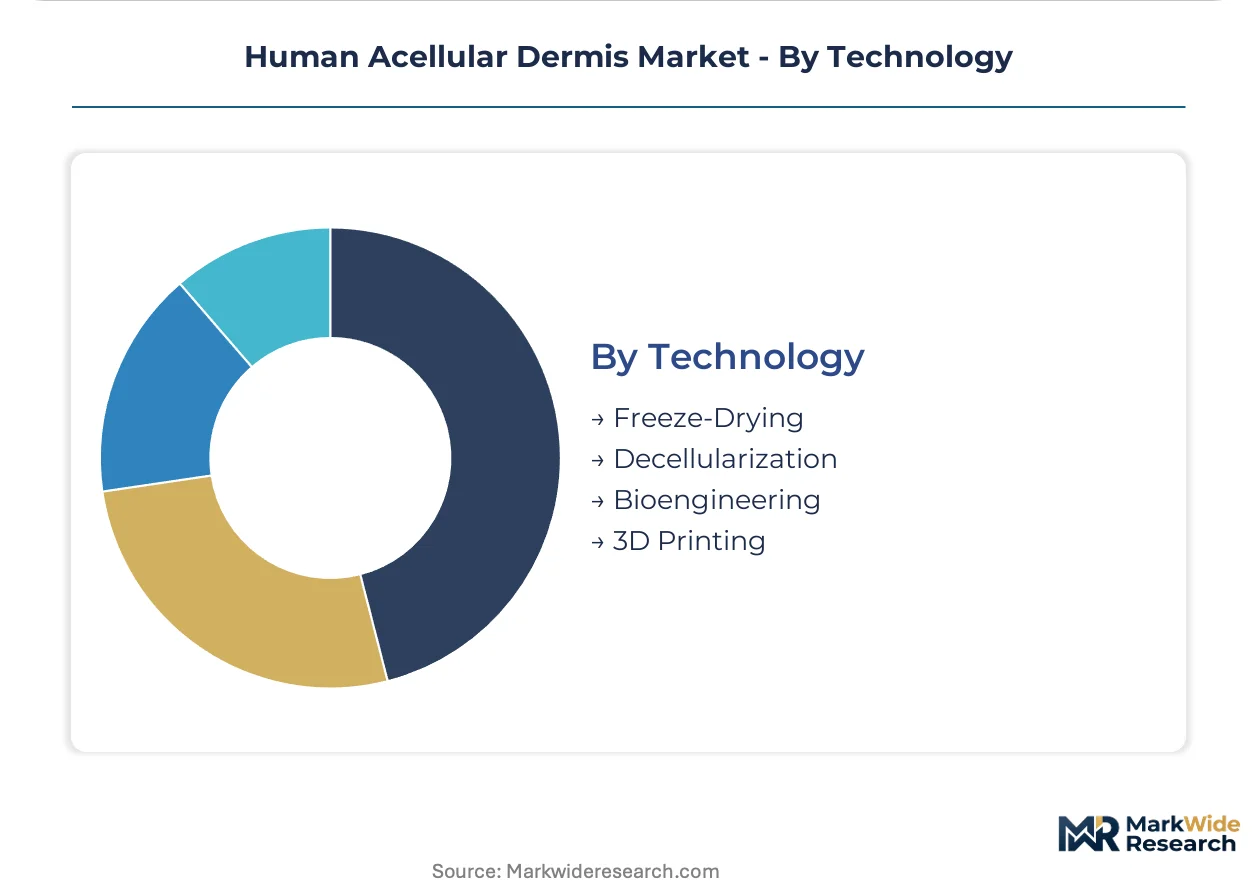
- Decellularization:Proprietary detergent-enzyme protocols that preserve extracellular matrix architecture command premium positioning due to faster engraftment kinetics. Closed-system bioreactor automation is reducing batch-to-batch variability and accelerating FDA 21 CFR Part 1271 validation timelines for new processors.
- Freeze-Drying:Lyophilization combined with terminal sterilization unifies cold-chain and ambient distribution channels, enabling rural Mountain West hospitals to stock acellular dermis without specialized refrigeration infrastructure.
- Bioengineering:Customizable thickness profiles and gradient porosity occupy emerging niches in complex reconstructive cases.
- 3D Printing:Layer-by-layer scaffold fabrication remains experimental with limited commercial scale.
Regulatory clarity sits with Freeze-Drying. Technical innovation is concentrating in Decellularization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special-economic-zone incentives for advanced medical device manufacturing in Ireland and Singapore are concentrating European and Asia-Pacific supply chain nodes for acellular dermis processing.
United States
Tertiary burn centers in Texas and Florida drive procurement volume for high-thickness allograft variants. FDA 21 CFR Part 1271 mandates enhanced donor traceability documentation that extends quality assurance timelines for domestic processors. Illinois and Ohio integrated health networks consolidate biologics purchasing through system-wide formularies controlling over sixty percent of regional reconstructive procedure volumes.
Germany
Academic medical centers in Baden-Württemberg prioritize EMA ATMP-classified matrices for complex reconstructive protocols. The country's national pharmaceutical regulator enforces MDR compliance pathways that diverge from US predicate device routes. Berlin-Brandenburg clusters host notified bodies demanding additional clinical data packages beyond 510(k) requirements.
Switzerland
Swissmedic oversight attracts matrix processors seeking parallel regulatory validation for transatlantic commercialization. Precision manufacturing incentives in the Zurich-West corridor support lyophilization facility investments. Basel-area biotech clusters are developing combination product pathways converging acellular matrices with antibiotic coatings.
India
CDSCO regulatory harmonization efforts are accelerating import license timelines for processed allograft products. Tamil Nadu medical device parks offer tax incentives for tissue processing infrastructure. Maharashtra's Mumbai-Pune corridor hosts contract research organizations supporting viral clearance validation studies for new market entrants.
Japan
PMDA reimbursement coding reviews for biological matrices in breast reconstruction are expanding addressable procedure volumes. METI subsidies for regenerative medicine manufacturing support decellularization automation investments. Osaka-Kobe industrial clusters specialize in closed-system bioreactor protocols reducing batch-to-batch variability.
Human Acellular Dermis Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with vertically integrated tissue processors commanding premium positioning in tertiary hospital channels while synthetic scaffold specialists capture cost-constrained formulary slots. The vendor base concentrates around three strategic archetypes: nonprofit tissue banking networks controlling donor supply access, diversified medtech conglomerates leveraging cross-selling infrastructure, and dedicated biologics processors optimizing decellularization yield. Dominant competitive moves include backward integration into donor network management and geographic expansion through ambulatory surgery center partnerships.
Among US-based diversified conglomerates, Johnson & Johnson and Stryker Corporation exemplify scale-driven positioning across multiple biologics categories. Integra LifeSciences Corporation anchors the dedicated processor archetype with vertically integrated tissue processing infrastructure. MTF Biologics occupies a distinctive position within nonprofit tissue banking networks, leveraging controlled donor supply relationships to sustain competitive access.
| Leading Market Players |
|---|
| Integra LifeSciences Corporation |
| AbbVie Inc. |
| Johnson & Johnson |
| Zimmer Biomet Holdings Inc. |
| Stryker Corporation |
| Smith & Nephew Plc. |
| Organogenesis Holdings Inc. |
| LifeNet Health |
| MTF Biologics |
| Others |
Pricing and Supply Chain Analysis
FDA 21 CFR Part 1271 donor traceability mandates gate qualified supply access for domestic processors while compressing margin structures for non-compliant inventory. Premium-tier pricing attaches to matrices with validated cold-chain documentation and complete donor pedigree records, whereas spot-market allograft without enhanced traceability faces systematic discounting.
Pricing Analysis
Lead-time-driven pricing stratification rewards rapid fulfillment with premium positioning while penalizing procurement queues. Three-tier pricing structure across premium, standard, and economy levels reflects thickness specifications, decellularization protocol fidelity, and shelf-life remaining at delivery. Price differentiation hinges on proprietary detergent-enzyme validation and basement membrane integrity certification. Cost compression in standard-tier lyophilized formats is intensifying because integrated health networks are consolidating formulary decisions across Illinois and Ohio. Ambulatory surgery centers in Arizona and Nevada demonstrate highest price sensitivity due to cash-pay procedure economics, while tertiary burn centers in Texas tolerate premium positioning for complex wound coverage protocols.
Supply Chain Analysis
Dual-sourcing requirements from integrated delivery networks mandate multi-supplier qualification for high-thickness allograft variants to mitigate donor tissue scarcity risks. Geographic supply concentration centers on United States tissue banking networks, Swiss lyophilization facilities in the Zurich-West corridor, and Irish special-economic-zone processing nodes serving European commercialization. Raw material dependencies encompass voluntary donor dermis procurement, proprietary detergent-enzyme reagents, and validated cold-chain logistics infrastructure. Single-source vulnerability permeates nonprofit tissue banking relationships controlling donor supply access. Distribution runs through GPO contracts and direct hospital system agreements with consolidated value analysis committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where FDA 21 CFR Part 1271 traceability mandates erect barrier-to-entry moats favoring incumbent processors with validated quality systems.
For Market Incumbents: Cement donor network control through exclusive tissue banking partnerships that constrain raw material access for emerging competitors. Deepen in-house production of decellularization automation equipment to reduce batch-to-batch variability and accelerate regulatory validation timelines. Synthetic substitute advancement with integrated antimicrobial properties threatens premium allograft positioning in cost-constrained hospital systems. Capacity addition in Swiss and Irish special-economic-zone jurisdictions enables parallel EMA ATMP and FDA predicate device pathway maintenance. For New Entrants and Emerging Players: CDSCO regulatory harmonization in India opens a window for import license acceleration through Tamil Nadu medical device park infrastructure investments. Target outpatient surgical center penetration in Arizona and Nevada where lyophilized format adoption eliminates cold-chain competency requirements and enables same-day hernia repair procedure economics. Combination product pathways converging acellular matrices with sustained-release antibiotic coatings offer 510(k) hybrid regulatory routes with reduced clinical data burdens compared to standalone biologics submissions. For Investors and Strategic Acquirers: Veterans Health Administration contract awards for battlefield trauma reconstruction are the leading indicator that federal procurement vehicles are creating dedicated supply channels outside commercial pricing compression. Long-term viability favors processors with vertically integrated tissue banking infrastructure and validated decellularization automation capable of serving both domestic hospital networks and transatlantic commercialization. Acquisition target archetype encompasses mid-scale processors with existing CE marks requiring US market entry infrastructure. Monitor CMS reimbursement coding decisions for biological matrices in breast reconstruction as the signal for procedure volume expansion across Medicare Advantage networks.| Strategic Initiative | Industry Significance |
|---|---|
| Donor Network Backward Integration | Exclusive tissue banking partnerships constrain raw material access for competing processors. |
| Decellularization Automation Scale-Up | Closed-system bioreactor deployment reduces batch variability and accelerates FDA 21 CFR Part 1271 validation. |
| Lyophilization Facility Expansion | Terminal sterilization capability unifies cold-chain and ambient distribution channels for rural hospital access. |
| Combination Product Pathway Development | Convergence with antibiotic coatings opens 510(k) hybrid regulatory routes with reduced clinical data requirements. |
| Federal Procurement Vehicle Qualification | Veterans Health Administration contracts create dedicated supply channels insulated from commercial pricing pressure. |
Research Methodology
Document review covered FDA 510(k) filings, EMA ATMP classification decisions, CMS Medicare reimbursement coding determinations, and hospital procurement database extracts, complemented by interviews with burn center clinicians, tissue bank procurement directors, biomedical engineers, and GPO contracts managers. Secondary validation drew from hospital formulary databases, GPO contract documentation, and SEC filings of publicly traded biologics processors. Bottom-up procedure volume modeling and top-down market sizing triangulation reconciled across independent analytical streams.
Historical shipment data cross-referenced against expert panel input on decellularization automation adoption and synthetic substitute penetration informed projection construction across the analysis window. Segmentation dimensions encompassed product architecture, processing technology, end-user facility tier, and application-specific reimbursement coding. CAGRs derived from weighted scenario modeling incorporating donor tissue availability constraints, regulatory pathway divergence between FDA and EMA frameworks, and integrated health network consolidation patterns. Forecast inputs included tertiary burn center construction pipelines, ambulatory surgery center licensing trends, and pathogen inactivation protocol validation timelines.
The model assumes a particular technology adoption path favoring lyophilization and terminal sterilization unification; alternative pathways for bioengineered customizable thickness matrices would alter the outlook toward premium reconstructive applications. Deviation in CMS reimbursement coding decisions for biological matrices against synthetic alternatives would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Global Non-PVC IV Bags Market
Medical Supplies
Skin Traction Kits Market
Medical Supplies
OTC Braces and Supports Market
Medical Supplies
Smart Face Masks Market
Medical Supplies
Specimen Retrieval Bags Market
Medical Supplies
Ostomy Care Market
Medical Supplies
Global Sterilization Container Systems Market
Medical Supplies
Europe Amniotic Membrane Market
Medical Supplies
Oral Dosing Cups Market
Medical Supplies
Hospital Consumables Market
Medical Supplies
Cataract Disposable Products Market
Medical Supplies
United Kingdom Hospital Supplies Market
Medical Supplies
Global Enema Bags Market
Medical Supplies
Sterile Container Market
Medical Supplies
China Hospital Supplies Market
Medical Supplies
Medical Plastics Market