
 Steel Ship Plate Market | 2026-2036
Steel Ship Plate Market Size, Share, and Industry Trends Forecast 2026-2036
Steel Ship Plate Market Insights
EH36 and higher-grade high-tensile specifications is reorganizing procurement patterns across major shipyards. POSCO leverages its integrated blast furnace complex in Pohang to dominate premium-grade plate output for LNG carrier construction. Nippon Steel Corporation anchors Japanese naval and commercial programs through specialized TMCP rolling expertise. ArcelorMittal competes across European yards with normalized rolling capabilities that meet Lloyd's Register and DNV certification thresholds.
Steel ship plate denotes hot-rolled structural carbon and alloy steel sheet specifically manufactured for hull construction, typically conforming to ASTM A131 or equivalent classification society grades with minimum yield strengths ranging from 235 MPa to 390 MPa depending on grade designation. Manufacturers produce these plates through controlled rolling and accelerated cooling processes to achieve through-thickness toughness and weldability required for marine environments. Hot rolled plate occupies the largest volume share across newbuild programs given its cost efficiency in standard commercial hull sections, while H High Strength grades capture expanding share in container ships and ice-class vessels where weight reduction directly improves fuel compliance margins. Alloy plate segments serve specialized naval applications where blast resistance and magnetic signature control justify premium pricing structures.
IMO's Energy Efficiency Existing Ship Index and Carbon Intensity Indicator regulations are forcing yards to specify lighter, higher-strength hull steels that reduce propulsion power requirements across vessel lifecycles. Classification societies including Lloyd's Register, DNV, and the Korean Register enforce grade-specific testing protocols that limit supplier qualification to mills with demonstrated TMCP or quenched-and-tempered process control. Buyers must monitor how European CBAM implementation affects imported plate competitiveness and whether Chinese GB/T 712 standard revisions align with international society rules for cross-yard certification acceptance.
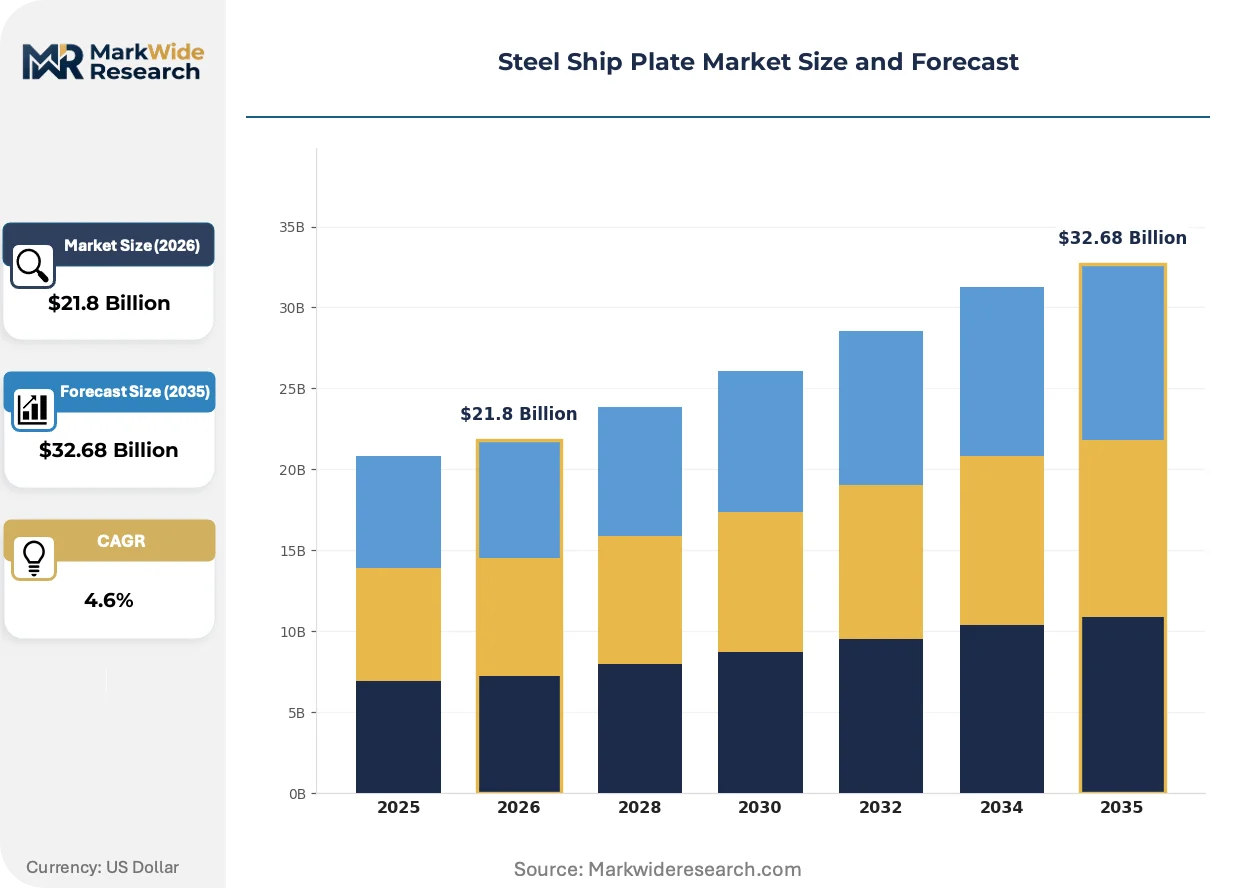
Market Dynamics
IMO's carbon intensity regulations are compressing hull weight requirements, forcing yards to specify higher-strength grades that reduce fuel consumption across vessel lifecycles. This regulatory pressure is concentrating procurement among mills with demonstrated TMCP process control and classification society certification.
Growth Catalysts
- Naval Fleet Modernization:Defense procurement programs across multiple jurisdictions are expanding orders for blast-resistant alloy grades. Shipyards in South Korea and Japan are scaling capacity to meet naval specification volumes.
- EEDI/CII Compliance Mandates:IMO's Energy Efficiency Existing Ship Index is forcing container lines and bulk operators to specify EH36 and above-grade plates. Lighter hulls directly improve carbon intensity ratings.
- Controlled Rolling Technology:Thermo-Mechanical Controlled Processing enables through-thickness toughness without expensive alloying. Yards in Ulsan and Pohang clusters are qualifying suppliers based on TMCP capability.
Market Restraints
- Iron Ore and Scrap Volatility:Blast furnace operators face margin compression when iron ore prices spike. Electric arc furnace plate producers confront scrap availability constraints in coastal industrial zones.
- Mill Concentration in East Asia:Premium-grade TMCP capacity concentrates in South Korea and Japan. European and North American buyers face extended lead times and freight cost premiums for certified material.
- Weldability Certification Barriers:Classification societies enforce grade-specific HAZ toughness testing. Mills without established DNV or Lloyd's Register qualification histories face multi-year approval timelines.
Strategic Opportunities
- Arctic Ice-Class Vessels:Polar Code compliance is expanding demand for cryogenic-tough grades. Yards in Finland and Russia are specifying plates with guaranteed Charpy values at minus 60 degrees Celsius.
- Hydrogen Carrier Hull Designs:Liquid hydrogen transport requires specialized stainless-clad or cryogenic alloy solutions. Japanese shipbuilders are prototyping membrane tank configurations with novel steel specifications.
- EU Carbon Border Adjustment:CBAM implementation creates advantage for European integrated mills with lower-emission blast furnace routes. Imported plate from carbon-intensive production faces escalating cost penalties.
Industry Challenges
- TMCP Process Engineer Scarcity:Controlled rolling expertise requires decades of mill-specific experience. Retirement waves at established producers are thinning the talent pipeline for process optimization.
- Multi-Society Certification Complexity:Yards building for multiple flag states must reconcile Lloyd's Register, DNV, Korean Register, and ClassNK testing protocols. Plate suppliers face redundant qualification audits.
- Capex Intensity for Q&T Lines:Quenched-and-tempered capacity expansion requires furnace investments exceeding typical rolling mill upgrade thresholds. Mid-size producers struggle to justify returns on naval-grade volume.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steel Ship Plate Market |
| Market Size in 2026 | $21.8 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hot Rolled, Cold Rolled, Coated, Alloy Thickness: Below 8mm, 8mm to 15mm, 15mm to 30mm, Above 30mm End User: Commercial Shipping, Naval Defense, Cargo Vessels, Fishing Industry Grade: A Grade, B Grade, D Grade, H High Strength |
| Companies Covered | POSCO, Nippon Steel Corporation, JFE Steel Corporation, Baosteel Group, ArcelorMittal, Hyundai Steel, Ansteel Group Corporation, Tata Steel Limited, Thyssenkrupp AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steel Ship Plate Market Trends and Innovations
Thermo-mechanical processing advances and regulatory carbon accounting are compressing traditional grade hierarchies. Shipyards now specify performance-based toughness criteria rather than legacy grade designations alone.
High-strength low-alloy formulations are fragmenting procurement patterns across commercial newbuild programs. Container ship operators are adopting EH40 and FH40 grades to reduce steel weight by 15-20 percent in deck and bottom structures. This substitution is fragmenting volume concentration among mills with demonstrated yield strength consistency at 390 MPa and above.
EU's Carbon Border Adjustment Mechanism is reshaping import competitiveness for non-European plate suppliers. The phased implementation from 2026 imposes certificate-based carbon cost adjustments on embedded emissions in steel products. Shipyards in Germany and France are prioritizing European mill relationships to avoid CBAM compliance complexity and price volatility.
Buyer concentration among mega-yard groups is compressing supplier negotiation cycles. Consolidated ordering from Hyundai Heavy Industries, Samsung Heavy Industries, and Daewoo Shipbuilding is shifting contract structures toward multi-year framework agreements with fixed-volume, variable-price mechanisms. This consolidation is most visible in South Korea's Ulsan and Geoje shipbuilding clusters where three buyers represent over 60 percent of regional plate demand.
Steel Ship Plate Market Segmentation
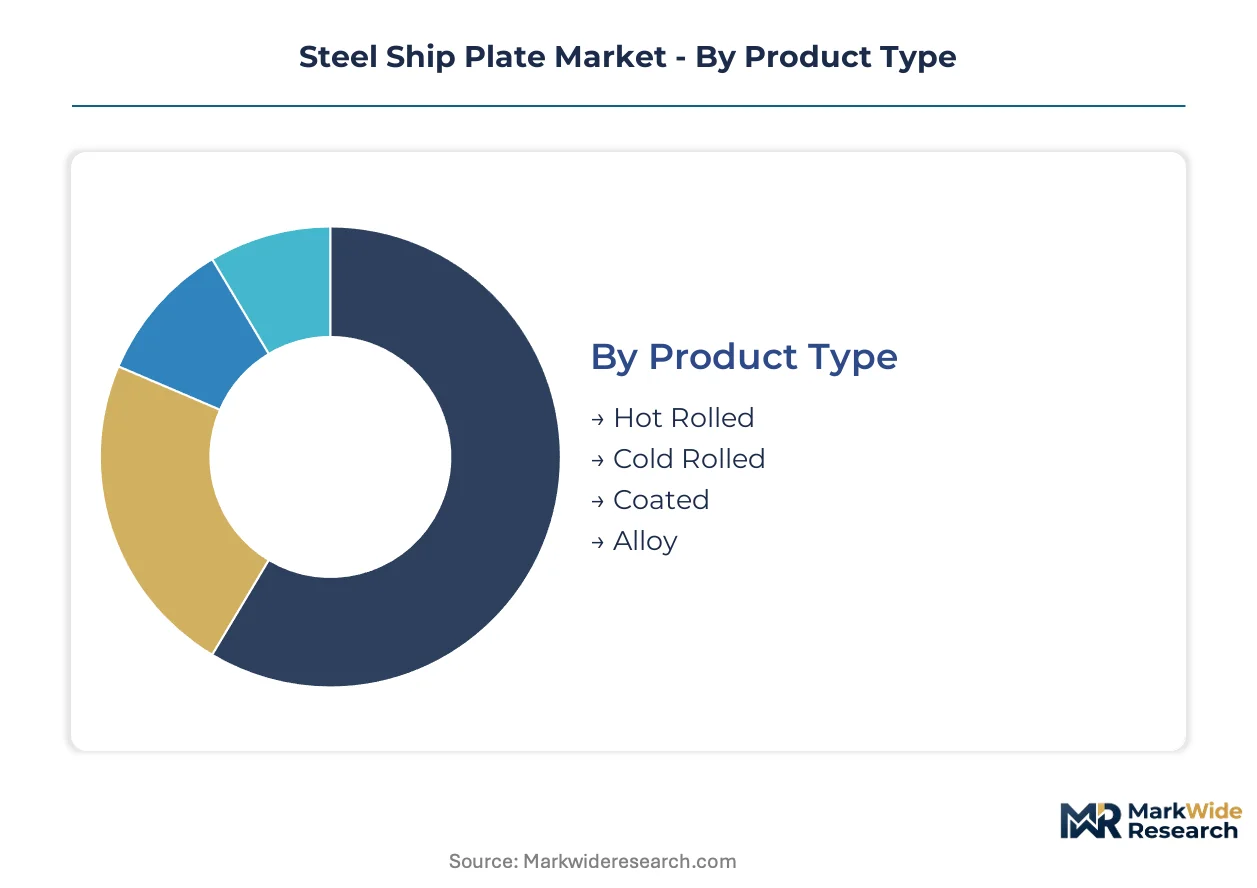
Ship plate segmentation reveals how specification requirements fragment procurement across hull zones and vessel types. Grade and thickness specifications directly determine rolling mill capability requirements and certification complexity.
Product Type:
Margin pools concentrate in alloy and coated grades where naval specifications and corrosion resistance command premium pricing structures.
- Hot Rolled:Structural carbon steel sheet manufactured through continuous casting and controlled rolling to achieve through-thickness toughness for standard hull sections. Demand concentrates in South Korea's Ulsan cluster where Hyundai Heavy Industries and Samsung Heavy Industries specify ASTM A131 Grade A through EH36 for bulk carrier and container ship bottom structures. TMCP process control at POSCO's Pohang complex anchors supply security for high-volume commercial programs.
- Alloy:Specialized formulations incorporating nickel, chromium, or molybdenum additions for blast resistance, cryogenic toughness, or magnetic signature suppression. Procurement is tightening around Japanese mills with quenched-and-tempered expertise as naval modernization programs across multiple jurisdictions expand orders for mine-hunter and frigate hull specifications.
- Cold Rolled:Precision-finished plate with tighter dimensional tolerances for superstructure and deckhouse applications where weight distribution affects vessel stability calculations.
- Coated:Zinc-aluminum or epoxy-primed surfaces for ballast tank and cargo hold zones where corrosion protection extends dry-docking intervals.
The dominant share belongs to Hot Rolled, while Alloy is closing the gap fastest.
Thickness:
Cost tiering follows a U-curve where extreme thin and thick specifications face supply constraints.
- 8mm to 15mm:Standard deck and bulkhead thickness range dominating container ship and general cargo newbuild programs. Demand concentrates at South Korean yards specifying this band for longitudinal strength members where fatigue resistance governs classification society approval.
- 15mm to 30mm:Heavy hull girder and machinery foundation plates requiring normalized rolling or TMCP for through-thickness ductility. Procurement is gravitating toward integrated mills with blast furnace feedstock consistency as ice-class notation requirements tighten material uniformity standards.
- Below 8mm:Superstructure plating and non-structural bulkheads where weight minimization improves stability margins.
- Above 30mm:Stern frame, rudder horn, and specialized naval applications demanding dedicated quenching capacity.
Volume leadership sits with 8mm to 15mm specifications, though 15mm to 30mm segments are expanding most quickly on ice-class and large container ship demand.
End User:
Customer type determines certification burden and contract structure complexity.
- Commercial Shipping:Container lines, bulk operators, and tanker owners specifying standard grades with Lloyd's Register or DNV notation. Procurement is consolidating around multi-year framework agreements with South Korean mega-yards as IMO's CII regulations force lighter hull specifications.
- Naval Defense:Government shipyards requiring blast-resistant alloys, magnetic signature control, and classified performance data. Demand is accelerating across multiple jurisdictions as fleet modernization programs expand orders for frigate and submarine hull specifications.
- Cargo Vessels:Specialized bulk and break-bulk operators with corrosion-focused coating requirements for aggressive cargo holds.
- Fishing Industry:Smaller tonnage builders with flexible grade acceptance and shorter qualification cycles.
Commercial Shipping retains the dominant procurement volume, while Naval Defense is gaining share fastest on defense budget expansion.
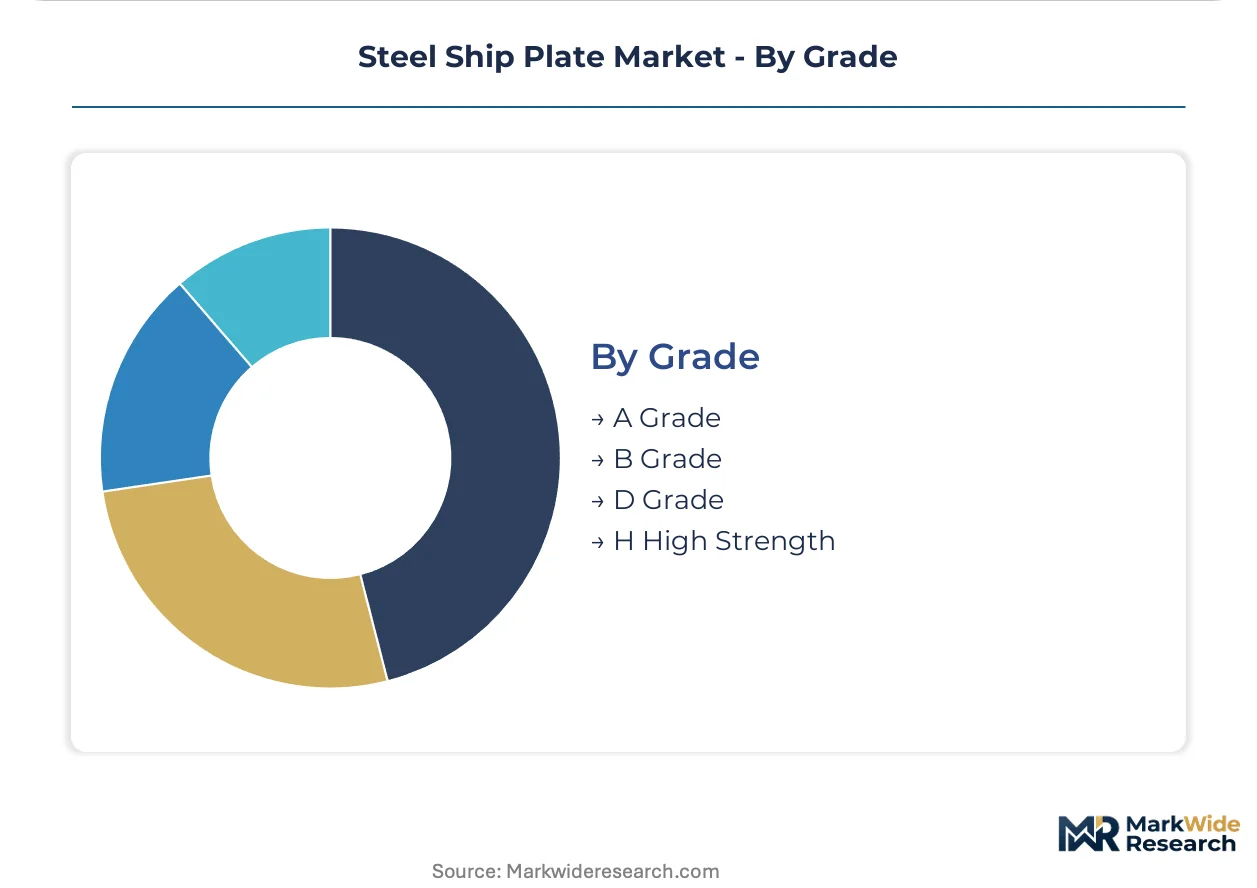
Grade:
Application maturity separates legacy general-strength from rapidly penetrating high-strength specifications.
- H High Strength:Grades EH32 through FH40 with minimum yield strengths of 315-390 MPa enabling 15-20 percent hull weight reduction. Demand is concentrating in Ulsan and Geoje clusters where EEDI compliance pressures container lines to specify EH36 and above for deck and bottom structures.
- A Grade:General-strength 235 MPa yield specification for secondary hull members and non-critical bulkheads. Procurement remains anchored at Chinese and Southeast Asian yards with less stringent classification society oversight.
- B Grade:Moderate-strength 235 MPa grade with improved notch toughness for deck plating in temperature-controlled service.
- D Grade:General-strength grade with guaranteed Charpy impact values at minus 20 degrees Celsius for refrigerated cargo and northern route exposure.
A Grade maintains the largest volume position, while H High Strength is climbing the fastest on regulatory weight reduction mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in steel ship plate tilt heavily toward export-oriented manufacturing clusters, with import dependency shaping procurement strategies in yards lacking integrated mill supply. East Asian producers dominate outbound shipment volumes while European and North American buyers navigate freight cost premiums and carbon border adjustments.
South Korea
Naval fleet modernization and LNG carrier construction drive specification demand for EH36 and above-grade plates. The Korean Register enforces TMCP certification protocols that limit supplier qualification to domestic mills with demonstrated process control. Hyundai Heavy Industries and Samsung Heavy Industries anchor procurement concentration in the Ulsan and Geoje clusters, where three buyers command over sixty percent of regional plate demand.
Japan
Commercial shipbuilding and defense programs sustain orders for high-tensile and blast-resistant alloy grades. METI coordinates industrial policy supporting specialized rolling expertise at integrated steel producers. Yards in the Nagoya and Kobe regions specify plates with guaranteed Charpy values for ice-class and naval applications, concentrating procurement around mills with quenched-and-tempered capabilities.
China
State-directed shipyard expansion and bulk carrier construction sustain volume demand for general-strength grades. GB/T 712 standard revisions under MIIT oversight aim to align domestic certification with Lloyd's Register and DNV rules for cross-yard acceptance. Production concentrates in the Yangtze River Delta and Bohai Rim clusters where Baosteel and Ansteel Group Corporation supply standard commercial hull specifications.
United States
Naval shipbuilding programs at Newport News and Bath Iron Works sustain demand for blast-resistant and magnetic-signature-controlled alloys. Jones Act requirements and Buy American provisions constrain import sourcing for federally funded vessel construction. Plate procurement for commercial yards concentrates on the Gulf Coast and Pacific Northwest, where scrap-based electric arc furnace supply faces availability constraints for certified naval grades.
Germany
Container ship and specialized vessel construction at yards in Hamburg and Bremerhaven drives specification demand for EH40 grades supporting EEDI compliance. EU Carbon Border Adjustment Mechanism implementation from 2026 elevates cost competitiveness of European integrated mills against imported plate. Thyssenkrupp AG anchors domestic supply for premium applications requiring Lloyd's Register and DNV dual certification.
Steel Ship Plate Market Competitive Landscape
Concentration sits with integrated blast furnace operators possessing thermo-mechanical controlled processing capability and multi-society certification histories. Three to five Korean and Japanese producers capture the majority of premium-grade volume for LNG carriers and naval programs. Strategic archetypes separate TMCP-specialized integrated mills, quenched-and-tempered naval-grade specialists, and scrap-based electric arc furnace producers serving standard commercial specifications. Capacity expansion and backward integration into iron ore supply anchor dominant competitive moves among East Asian leaders.
Within the integrated mill tier, POSCO and Nippon Steel Corporation exemplify archetypes built on blast furnace scale and classification society qualification depth. ArcelorMittal occupies a position bridging European normalized rolling capabilities with cross-regional certification reach. These three anchors represent the concentration of premium-grade supply security for yards navigating IMO carbon intensity regulations and multi-year framework contracting.
| Leading Market Players |
|---|
| POSCO |
| Nippon Steel Corporation |
| JFE Steel Corporation |
| Baosteel Group |
| ArcelorMittal |
| Hyundai Steel |
| Ansteel Group Corporation |
| Tata Steel Limited |
| Thyssenkrupp AG |
| Others |
Pricing and Supply Chain Analysis
Grade substitution from general-strength A-grade to high-tensile EH36 and above simultaneously redraws procurement geography toward South Korean and Japanese TMCP-capable mills while compressing per-ton economics through lighter hull designs that reduce absolute steel volume per vessel.
Pricing Analysis
Industrial OEM buyers anchor contract structures around multi-year framework agreements with fixed-volume, variable-price mechanisms. Three-tier pricing stratification separates premium EH40-FH40 grades with DNV-Lloyd's dual certification from standard EH36 specifications and economy A-grade commercial hull plate. Cost compression in standard grades intensifies as Chinese mills expand GB/T 712 production for domestic yards. Container lines and bulk operators exhibit highest price sensitivity on tonnage contracts, while naval procurement teams prioritize performance guarantees over unit economics.
Supply Chain Analysis
Strategic stockpiling of certified plate dominates buyer behavior given twelve-to-eighteen month qualification timelines for new mill approvals. Supply concentrates in South Korea, Japan, and China where integrated blast furnace complexes feed TMCP rolling capacity. Production draws from iron ore pellet feedstock anchored in Australian and Brazilian mine outputs, with metallurgical coal sourcing from Mongolia and Russia. Single-source vulnerability concentrates around POSCO's Pohang complex for premium LNG carrier grades. Distribution runs through direct mill-to-yard contracts with minimal intermediary inventory holding.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Steel ship plate demand tracks naval fleet modernization cycles and IMO regulatory compliance waves, with the current upswing driven by carbon intensity mandates forcing hull weight reduction programs.
For Market Incumbents: Fortify TMCP process control advantages by capturing retiring engineer expertise through structured knowledge transfer programs. Expand quenched-and-tempered capacity for naval alloy grades before European and North American yards face extended lead time crises. Lock in multi-year offtake agreements with Hyundai Heavy Industries and Samsung Heavy Industries to defend volume positions against Chinese mill certification upgrades.
For New Entrants and Emerging Players: Lead with specialized cryogenic toughness capabilities for Arctic ice-class and hydrogen carrier membrane tank applications where established mills lack dedicated R&D investment. Target Finnish and Russian polar vessel yards with guaranteed Charpy values at minus 60 degrees Celsius. Pursue joint qualification programs with classification societies to compress multi-year approval timelines.
For Investors and Strategic Acquirers: The market sits at a capacity-constrained phase that favors integrated mills with captive iron ore supply and established certification histories. Long-term viability rests on backward integration into low-emission metallics and carbon capture retrofit readiness. Watch for European CBAM implementation crossing enforcement thresholds as the signal for accelerated European mill consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| TMCP Capacity Expansion | POSCO and Nippon Steel Corporation anchor supply security for LNG carrier programs through Pohang and Nagoya complex upgrades. |
| Naval Grade Q&T Investment | Quenched-and-tempered line additions at Japanese mills capture frigate and submarine hull modernization demand across multiple jurisdictions. |
| Carbon Capture Retrofit | European integrated mills defend CBAM competitiveness by lowering blast furnace emission intensity ahead of certificate-based adjustment mechanisms. |
| Multi-Society Certification | Simultaneous Lloyd's Register, DNV, and Korean Register qualification reduces redundant audit burdens for yards building multiple flag-state vessels. |
| Cryogenic Alloy Development | Specialized nickel-alloy formulations for liquid hydrogen transport membrane tanks open premium pricing tiers beyond standard commercial hull specifications. |
Research Methodology
Cross-validation between mill production data and shipyard procurement disclosures anchors the qualitative findings on supplier concentration and grade specification trends. Primary interviews with steel plant technical directors, shipyard procurement managers, classification society surveyors, and naval architecture consultants combined with secondary validation from customs trade records, Korean Register certification databases, and IMO regulatory filings. Bottom-up tonnage estimates by vessel type and top-down mill capacity utilization figures triangulate demand-supply balances.
Sensitivity analysis around iron ore price volatility and scrap availability constraints tests forecast robustness across the projection horizon. Segmentation dimensions modeled include grade tier, thickness specification, end-use category, and regional production hub. CAGRs derive from regression against naval procurement budgets, commercial orderbook pipelines, and regulatory compliance deadlines. Industry-specific inputs incorporate Lloyd's Register and DNV grade approval timelines, TMCP process yield curves, and ice-class notation penetration rates.
The analysis sits within stated boundaries; outcomes outside sustained naval modernization funding or IMO enforcement continuity would require recalibration. Forecasts reflect assumptions on classification society certification acceptance rates and Chinese standard harmonization progress. Revision becomes warranted when European CBAM carbon cost adjustments or iron ore supply disruptions cross materiality thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Marine Beacon Market
Marine
Yacht Painting and Maintenance Market
Marine
Asia-Pacific Electric Boat Market
Marine
Marine Shaft Power Meter Market
Marine
Marine Growth Removal Tool Market
Marine
Marine Filter Market
Marine
Sailboat Propellers Market
Marine
Pneumatic Marine Fender Market
Marine
Marine Fuel Injector Market
Marine
GCC ROV Market
Marine
Marine Suspension Seat Bases Market
Marine
Marine Glass Market
Marine
Marine Trenchers Market
Marine
Boat Control Lever Market
Marine
Marine Bearings Market
Marine
Furnace Boats Market