
 Methoprene Market | 2026-2036
Methoprene Market Size, Share, and Industry Trends Forecast 2026-2036
Methoprene Market Foresight
Technical-grade purity specifications above ninety-five percent active ingredient are redrawing supplier credibility benchmarks in methoprene procurement. Syngenta AG leverages its integrated agrochemical distribution network to sustain volume leadership across grain-protection channels. Central Life Sciences anchors the North American veterinary and vector-control segments through specialized formulations. Sumitomo Chemical Co. Ltd. competes on manufacturing scale in Asia-Pacific feedstock corridors.
Methoprene is a terpenoid-based juvenile hormone analog that mimics natural insect growth regulators to disrupt larval metamorphosis, typically formulated at concentrations ranging from one to ten percent depending on target pest and substrate. Its primary commercial purpose is preventive pest suppression in stored commodities, animal health, and public vector programs where adulticide resistance limits conventional alternatives. Liquid concentrate formulations lead volume sales due to ease of tank-mixing and aerial application compatibility, while emulsifiable concentrate grades command margin premiums in precision agriculture and aquaculture settings where oil-based carriers improve rainfastness. The residential end-user segment shows structural momentum as consumer-ready aerosol formats gain shelf space through online retail channels.
EPA's FIFRA registration requirements and residue tolerance setting under FFDCA shape product label claims and seasonal use windows for methoprene applications in food and feed crops. The EU's REACH substance evaluation and Biocidal Products Regulation constrain active-sourcing options and necessitate extensive ecotoxicology dossiers for market access. Brazil's ANVISA and the country's national environmental regulator enforce comparable but distinct import and formulation standards that suppliers must navigate for Latin American expansion. Stakeholders should monitor regulatory divergence between OECD-aligned hazard assessment frameworks and emerging economy data-requirement tiers when prioritizing registration investment sequences.
Market Dynamics
EPA's FIFRA re-registration timeline is compressing formulation development cycles as manufacturers race to meet 2027 data-call deadlines for juvenile hormone analogs, forcing accelerated investment in lower-dose delivery systems ahead of residue tolerance reviews.
Growth Catalysts
- Stored-grain IPM mandates:Brazil's CONAB warehousing standards now require preventive insect growth regulators for federal procurement eligibility, expanding methoprene inclusion in post-harvest commodity protection protocols.
- Vector resistance management:WHO guidelines for integrated mosquito control are elevating juvenile hormone analogs where pyrethroid resistance has compromised adulticide efficacy in urban disease-vector programs.
- Livestock facility biosecurity:USDA-APHIS feedlot inspection protocols are recognizing larval-stage suppression as a measurable component of fly-borne pathogen reduction in confined animal feeding operations.
Market Restraints
- Isoprenoid feedstock volatility:Terpenoid precursor supply concentrates in Southeast Asian plantation corridors, exposing formulation costs to climate-driven harvest disruptions and plantation labor availability.
- EU ecotoxicology dossier requirements:REACH substance evaluation and BPR active-substance renewal timelines extend 18-24 months beyond comparable EPA reviews, freezing new entrant market access.
- Biological substitute advancement:Bacillus thuringiensis israelensis formulations are capturing municipal vector-control tenders where rapid knockdown metrics outweigh residual activity advantages.
Strategic Opportunities
- Aquaculture expansion corridors:Vietnamese shrimp hatchery operations are adopting methoprene for crustacean larval-stage synchronization, opening non-insect application vectors.
- Precision agriculture convergence:Drone-based micro-encapsulated spray systems are enabling targeted larval habitat treatment with reduced buffer-zone requirements.
- Consumer channel digitization:Direct-to-home aerosol formats through e-commerce platforms are capturing residential pest-prevention spending previously routed through professional service contracts.
Industry Challenges
- Entomological toxicology expertise scarcity:Juvenile hormone mode-of-action specialization requires hybrid training in endocrinology and formulation chemistry that university programs have not scaled to industry demand.
- Multi-jurisdiction registration synchronization:Divergent OECD-equivalence determinations between EPA, ECHA, and ANVISA data requirements force redundant chronic toxicity studies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Methoprene Market |
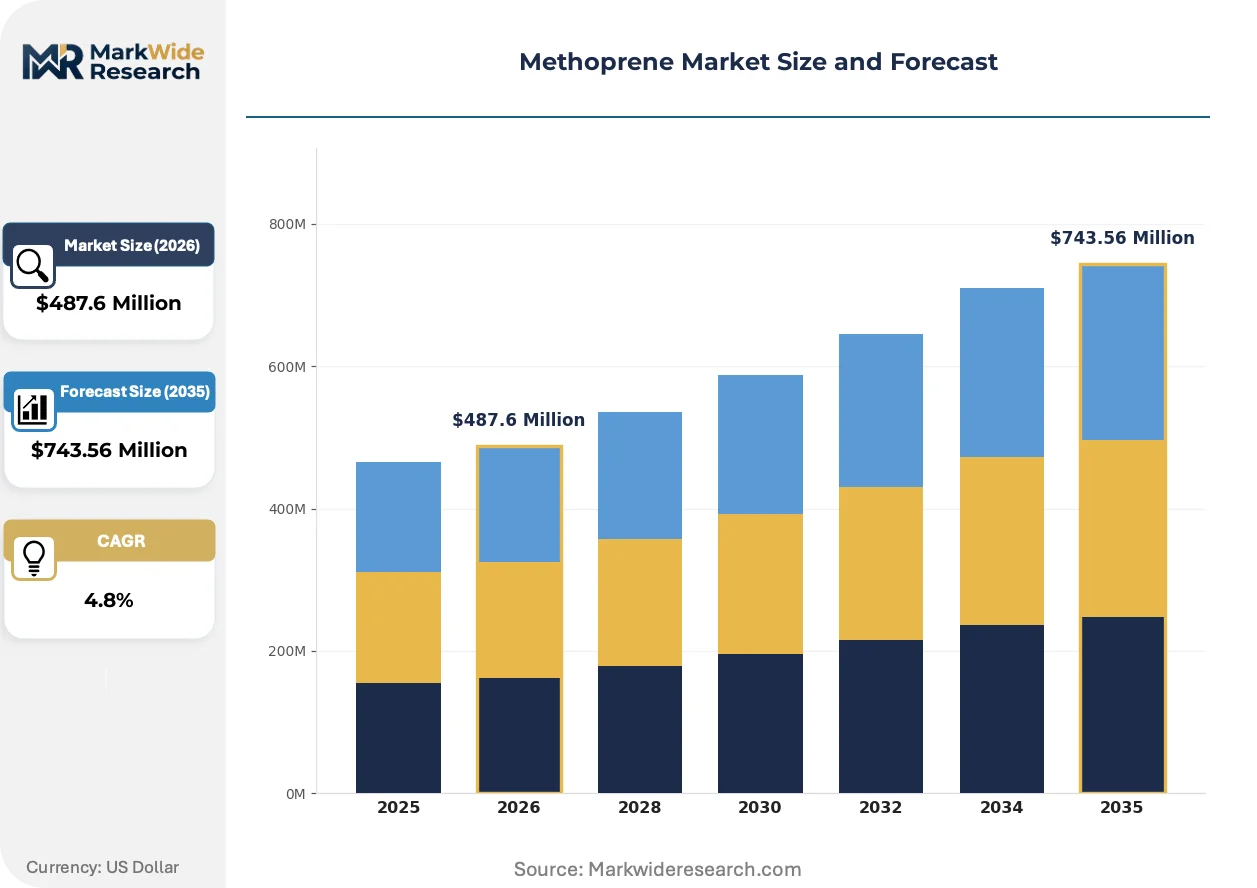
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $743.56 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granules, Liquid Concentrate, Emulsifiable Concentrate, Aerosol End User: Agriculture, Residential, Commercial, Industrial Application: Pest Control, Vector Control, Aquaculture, Forestry Distribution Channel: Online Retail, Direct Sales, Distributors, Retail Stores |
| Companies Covered | Syngenta AG, Corteva Agriscience, Central Life Sciences, Sumitomo Chemical Co. Ltd., BASF SE, Zoecon Corporation, Valent BioSciences, OHP, Inc., Bayer AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Methoprene Market Shifts & Advancements
Formulation chemistry is pivoting toward micro-encapsulation and controlled-release matrices that extend residual efficacy while reducing active ingredient load per treated surface.
Micro-encapsulated methoprene delivery is fragmenting competitive positioning between commodity liquid concentrate suppliers and specialty formulation houses. Grain elevator operators in the US Midwest are adopting polymer-coated granule formats for bin-prophylaxis programs, compressing margins on traditional emulsifiable concentrate grades as buyers prioritize labor-reducing single-application protocols over tank-mix flexibility.
REACH authorization timelines for juvenile hormone analogs are extending data-requirement horizons beyond 2028 for several co-formulant categories. EU-based suppliers are reconfiguring supply chains toward bio-based carrier solvents to preempt SVHC candidate listing, with stored-product protection segments absorbing formulation cost premiums to maintain biocidal product family registrations.
Professional pest-management operators are unbundling preventive larval treatments from bundled adulticide service contracts. Residential and food-processing facility buyers in Germany and the Netherlands are procuring methoprene-based monitoring-and-treatment systems through equipment-leasing structures rather than chemical purchase agreements, transferring application timing risk to service providers while locking in multi-year substrate protection commitments.
Methoprene Market Segmentation
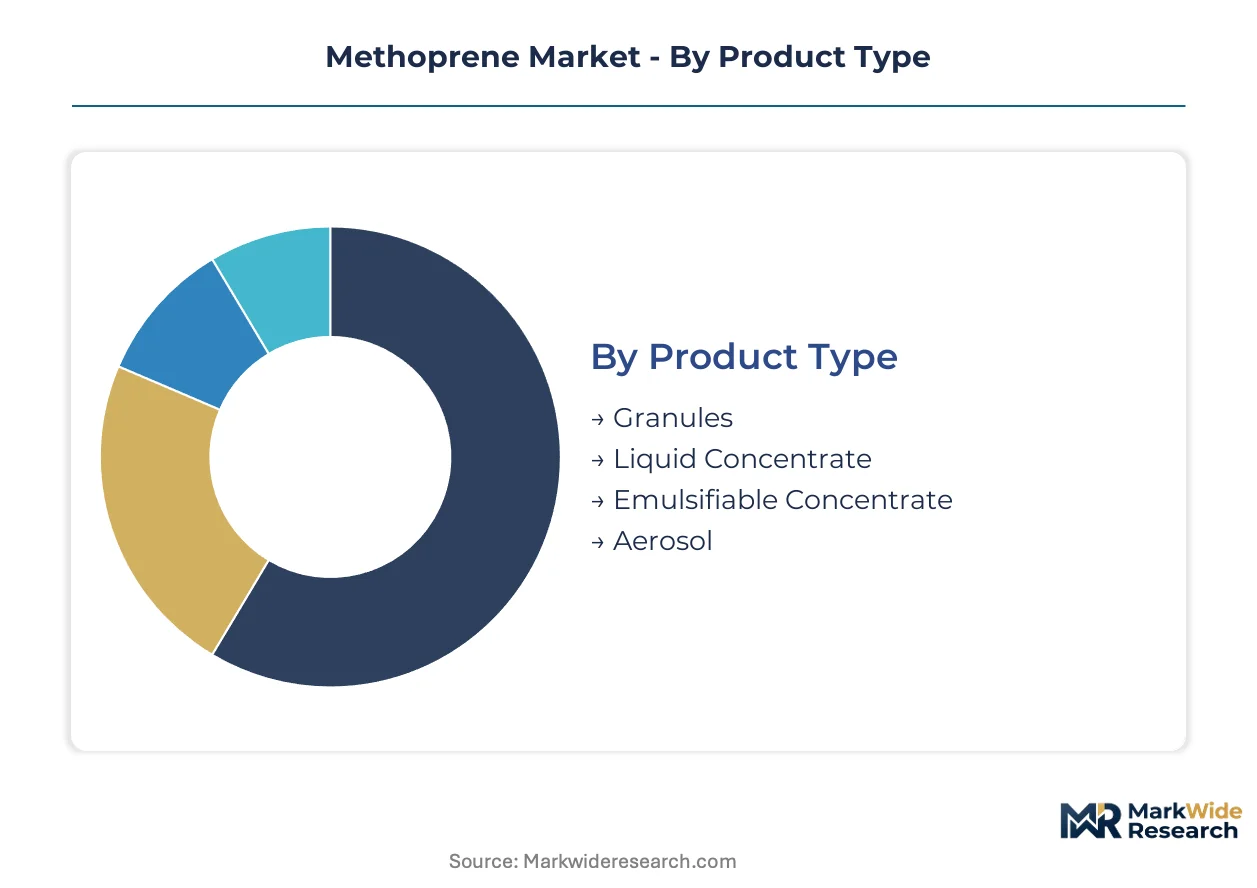
Methoprene formulation diversity demands precise channel alignment. Product viscosity, application equipment requirements, and end-user technical sophistication determine whether formulations flow through bulk agricultural distributors or direct-to-consumer digital platforms.
Product Type:
Liquid concentrates and emulsifiable concentrates dominate professional procurement channels, while granules and aerosols bifurcate between agricultural supply cooperatives and residential e-commerce fulfillment.
- Liquid Concentrate:Water-based formulations containing one to ten percent active ingredient enable tank-mixing flexibility for aerial and ground spray operations. Grain elevator operators in the US Midwest specify liquid concentrates for bin-prophylaxis programs, though polymer-coated alternatives are compressing margins on traditional emulsifiable grades.
- Emulsifiable Concentrate:Oil-based carriers improve rainfastness and substrate penetration for precision agriculture and aquaculture applications. Vietnamese shrimp hatcheries specify emulsifiable grades for crustacean larval-stage synchronization, opening non-insect vectors where residual activity metrics outweigh rapid knockdown requirements.
- Granules:Polymer-coated formats reduce labor through single-application protocols in grain-storage facilities.
- Aerosol:Consumer-ready formats capture residential pest-prevention spending through online retail channels.
Liquid concentrate dominates installed base. Emulsifiable concentrate is where expansion concentrates.
End User:
Cost tier stratification separates commodity bulk purchasers from premium formulation buyers seeking specialized delivery systems.
- Agriculture:Large-scale grain-storage and livestock operations drive volume procurement of technical-grade formulations above ninety-five percent purity. Brazil's CONAB warehousing standards mandate preventive insect growth regulators for federal procurement eligibility, expanding methoprene inclusion in post-harvest commodity protection protocols.
- Residential:Consumer segments show structural momentum as direct-to-home aerosol formats gain shelf space through e-commerce platforms.
- Commercial:Food-processing facilities in Germany and the Netherlands procure monitoring-and-treatment systems through equipment-leasing structures rather than chemical purchase agreements.
- Industrial:Vector-control programs in urban disease-management settings specify juvenile hormone analogs where pyrethroid resistance has compromised adulticide efficacy.
Agriculture dominates installed base. Residential is climbing the fastest.
Application:
Application maturity varies by regulatory clearance depth and entomological expertise requirements.
- Pest Control:Stored-product protection segments absorb formulation cost premiums to maintain biocidal product family registrations under REACH authorization timelines.
- Vector Control:WHO guidelines for integrated mosquito control elevate juvenile hormone analogs in municipal tender processes.
- Aquaculture:Vietnamese shrimp hatchery operations adopt methoprene for crustacean larval-stage synchronization.
- Forestry:Larval habitat treatment applications benefit from drone-based micro-encapsulated spray systems.
Pest control dominates installed base. Vector control is gaining share fastest.
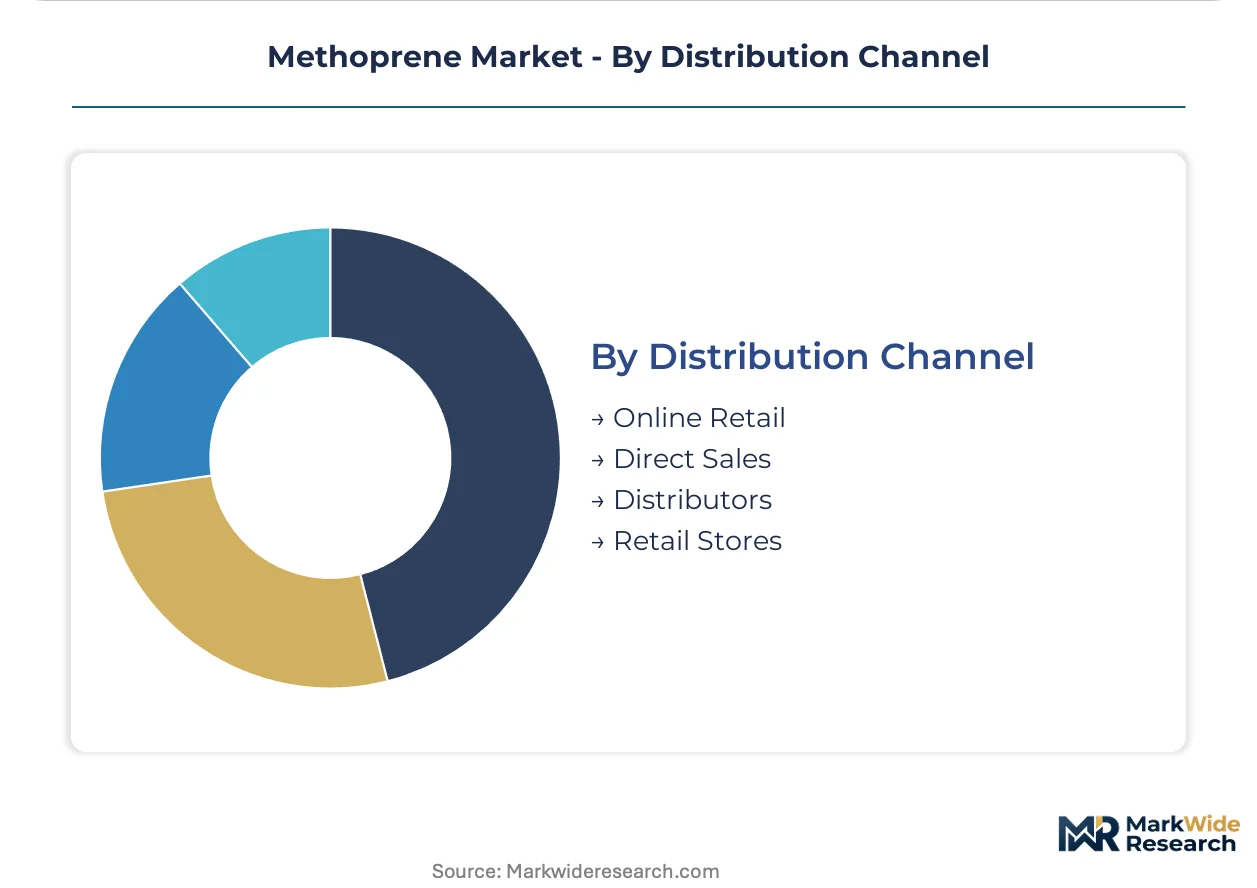
Distribution Channel:
Customer type and purchase frequency determine channel selection, with professional buyers favoring relationship-based procurement and residential users prioritizing convenience.
- Direct Sales:Large agricultural cooperatives and vector-control authorities negotiate volume contracts with formulation manufacturers for technical-grade supply.
- Distributors:Regional agricultural supply networks stock liquid concentrates for grain-protection channels.
- Online Retail:E-commerce platforms capture residential aerosol demand previously routed through professional service contracts.
- Retail Stores:Big-box agricultural retailers serve smallholder farmers with consumer-packaged granule formats.
Distributors dominate installed base. Online retail shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Terpenoid precursor supply concentrates in Southeast Asian plantation corridors, exposing formulation costs to climate-driven harvest disruptions. Procurement patterns diverge sharply between EPA-aligned jurisdictions and REACH-governed markets, with Brazil emerging as the decisive volume swing state for grain-storage applications.
United States
Grain elevator operators across the US Midwest drive bulk procurement of liquid concentrate formulations for bin-prophylaxis programs. EPA's FIFRA re-registration timeline compresses development cycles ahead of 2027 data-call deadlines for juvenile hormone analogs. Iowa and Illinois storage cooperatives are adopting polymer-coated granule formats to reduce labor through single-application protocols.
Brazil
Soybean and corn integrated pest management adoption widens the addressable base for methoprene-based vector and stored-product pest solutions. CONAB warehousing standards now mandate preventive insect growth regulators for federal procurement eligibility. São Paulo and Mato Grosso grain handlers are expanding post-harvest commodity protection protocols under national biosecurity directives.
Germany
Food-processing facilities in Bavaria and North Rhine-Westphalia procure monitoring-and-treatment systems through equipment-leasing structures rather than chemical purchase agreements. REACH substance evaluation and BPR active-substance renewal timelines extend 18-24 months beyond comparable EPA reviews. Cologne-based formulation houses are reconfiguring supply chains toward bio-based carrier solvents to preempt SVHC candidate listing.
Vietnam
Shrimp hatchery operations in the Mekong Delta are adopting methoprene for crustacean larval-stage synchronization, opening non-insect application vectors. The country's national environmental regulator enforces distinct import and formulation standards that suppliers must navigate for Southeast Asian expansion. Ho Chi Minh City aquaculture clusters specify emulsifiable grades where residual activity metrics outweigh rapid knockdown requirements.
Netherlands
Residential and food-processing facility buyers in Rotterdam and Amsterdam are unbundling preventive larval treatments from bundled adulticide service contracts. ECHA ecotoxicology dossier requirements constrain active-sourcing options and necessitate extensive documentation for biocidal product family registrations. Wageningen agrotech corridors are piloting drone-based micro-encapsulated spray systems for targeted larval habitat treatment.
Methoprene Market Competitive Landscape
Concentration sits with integrated agrochemical conglomerates and specialized life sciences operators. The vendor base separates into volume leaders with captive distribution networks, regional formulation specialists with regulatory navigation expertise, and niche players with veterinary and vector-control segment focus. Dominant competitive moves include backward integration into terpenoid feedstock sourcing and technology licensing for micro-encapsulation delivery systems.
Among integrated agrochemical conglomerates, Syngenta AG and BASF SE exemplify scale-driven positioning with global grain-protection channel access. Central Life Sciences and Zoecon Corporation anchor the North American specialized formulation tier. Sumitomo Chemical Co. Ltd. represents Asia-Pacific manufacturing scale in plantation corridor feedstock zones. These three archetypes—integrated conglomerate, regional specialist, and Asia-Pacific scale operator—capture distinct margin pools across regulatory complexity gradients.
| Leading Market Players |
|---|
| Syngenta AG |
| Corteva Agriscience |
| Central Life Sciences |
| Sumitomo Chemical Co. Ltd. |
| BASF SE |
| Zoecon Corporation |
| Valent BioSciences |
| OHP, Inc. |
| Bayer AG |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day terpenoid precursor lead times from Southeast Asian plantation corridors concentrate pricing power with integrated feedstock owners while forcing formulation houses to carry buffer inventory against climate-driven harvest disruptions. This inventory burden compresses working capital margins for non-integrated suppliers during periods of isoprenoid feedstock volatility.
Pricing Analysis
EPA's FIFRA re-registration timeline dictates the pricing tier structure across technical-grade, formulated, and consumer-ready product bands. Three-tier pricing structure across premium, standard, and economy levels separates emulsifiable concentrate grades for precision aquaculture from commodity liquid concentrates for grain-storage and aerosol formats for residential channels. Cost compression in standard-tier liquid concentrates is intensifying because Brazilian CONAB warehousing mandates are expanding volume procurement by agricultural cooperatives. Grain elevator operators in the US Midwest exhibit highest price sensitivity due to thin commodity-handling margins, while Vietnamese shrimp hatcheries show lowest sensitivity where residual activity performance justifies formulation premiums.
Supply Chain Analysis
Port congestion on Southeast Asian trade lanes elevates inbound logistics costs for terpenoid-derived active ingredient shipments to formulation facilities in North America and Europe. Supply concentrates in Indonesia, Malaysia, and Thailand for isoprenoid feedstock extraction, with secondary processing nodes in China and India for technical-grade synthesis. Raw material dependencies center on citronella oil, pine resin derivatives, and synthetic isoprene intermediates. Single-source vulnerability runs through plantation labor availability and monsoon-driven harvest timing. Distribution feeds from regional formulation hubs through agricultural supply cooperatives, veterinary distributors, and direct e-commerce fulfillment for residential aerosol channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Methoprene demand cycles track agricultural commodity storage volumes and vector-control program funding rounds, positioning the market for recovery as Brazil expands post-harvest infrastructure investment and WHO guidelines elevate juvenile hormone analog prioritization.
For Market Incumbents: Shield formulation margin pools by deepening backward integration into terpenoid feedstock sourcing through plantation corridor partnerships or long-term offtake agreements. Accelerate micro-encapsulation R&D investment to differentiate from biological substitute threats like Bacillus thuringiensis israelensis formulations capturing municipal vector tenders. Prioritize EPA FIFRA re-registration dossier completion ahead of data-call deadlines to lock in label claims before tolerance reviews compress seasonal use windows. For New Entrants and Emerging Players: Equipment-leasing service gaps in European food-processing facilities offer white-space entry where incumbents under-serve through traditional chemical purchase structures. Target German and Dutch monitoring-and-treatment system procurement through application-timing risk transfer models rather than commodity formulation sales. Penetrate Vietnamese aquaculture clusters via emulsifiable concentrate specialization for crustacean larval-stage synchronization, leveraging lower regulatory barrier entry compared to REACH-governed biocidal product registrations. For Investors and Strategic Acquirers: Long-term, this sits as a defensive specialty-chemical play because juvenile hormone analog mode-of-action expertise creates durable moats against biological substitute displacement in resistance-management protocols. Acquisition focus should center on regional formulation houses with captive ANVISA registration expertise and established grain-protection channel relationships in Brazil. Monitor EPA residue tolerance review outcomes as inflection signal—adverse determinations would accelerate formulation cost restructuring and consolidation pressure among non-integrated suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Terpenoid Feedstock | Captive isoprenoid supply from Southeast Asian plantation corridors insulates margin pools against climate-driven harvest volatility. |
| Micro-Encapsulation Technology Licensing | Polymer-coated delivery systems command premium positioning in grain-storage bin-prophylaxis programs reducing labor costs. |
| Multi-Jurisdiction Registration Synchronization | Coordinated EPA, ECHA, and ANVISA dossier filing reduces redundant chronic toxicity study expenditure and accelerates market access. |
| Direct-to-Consumer Aerosol Channel Expansion | E-commerce platform partnerships capture residential pest-prevention spending previously routed through professional service contracts. |
| Aquaculture Application Development | Vietnamese shrimp hatchery specifications for crustacean larval-stage synchronization open non-insect revenue vectors with distinct competitive dynamics. |
Research Methodology
Operator-level perspectives from grain elevator managers, veterinary procurement leads, vector-control program directors, and aquaculture hatchery operators anchored the qualitative base for this study. Primary field engagement combined structured interviews with downstream formulation users and upstream feedstock specialists, validated against secondary sources including EPA FIFRA registration databases, ECHA biocidal product dossiers, ANVISA import records, and CONAB warehousing standard documentation. Bottom-up demand modeling across application segments triangulated with top-down supply-side capacity assessments.
Sensitivity analysis tested forecast robustness across feedstock price volatility bands, regulatory timeline delay scenarios, and biological substitute penetration rates. The analytical framework segmented volume and value outputs by formulation type, end-use industry, application method, and regional regulatory cluster across the projection horizon. CAGRs derived from segment-level demand build-ups incorporating procurement pattern shifts, technology substitution curves, and channel migration trends. Key inputs included grain-storage capacity expansion pipelines, WHO vector-control guideline revision schedules, and shrimp aquaculture stocking intensity projections.
Forecasts assume regulatory continuity in EPA FIFRA, EU REACH/BPR, and Brazil ANVISA regimes; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
3-Fluoro-5-Nitrotoluene Market
Chemicals
South America Construction Chemicals Market
Chemicals
Spirodiclofen Market
Chemicals
Global Tetraacetylethylenediamine (TAED) Market
Chemicals
4-Dichlorodiphenyl Sulfone (DCDPS) Market
Chemicals
Canada Methanol Market
Chemicals
Global Benzalkonium Chloride Market
Chemicals
Phosgene Market
Chemicals
Egypt Construction Chemicals Market
Chemicals
Cetyl Stearyl Alcohol Market
Chemicals
Hexafluorosilicic Acid Market
Chemicals
Europe Calcium Peroxide Market
Chemicals
China Amines Market
Chemicals
Diphenyl Sulfone Market
Chemicals
Inorganic Chemicals Market
Chemicals
Anhydrous Hydrogen Fluoride Market