
 Global Glycine Market | 2026-2036
Global Glycine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Glycine Market Foresight
Pharmaceutical end-use is consolidating share within the Global Glycine Market as parenteral nutrition and biologic buffer applications expand. Ajinomoto Co., Inc. leverages fermentation expertise to sustain pharmaceutical-grade supply chains across Asia. Evonik Industries AG anchors industrial-grade production through chemical synthesis scale in Germany. Showa Denko K.K. competes on high-purity grades for semiconductor and electronics applications in Japan.
Glycine is a non-essential amino acid with the chemical formula NH₂CH₂COOH, manufactured primarily through Strecker synthesis or enzymatic fermentation to achieve purity thresholds ranging from 98.5% for feed applications to 99.5%+ for pharmaceutical injectables. Its primary industrial purpose spans protein synthesis intermediates, metal chelation in electroplating, and buffering agents in cell culture media. Pharmaceutical-grade glycine commands the deepest margin pool due to FDA and EMA validation requirements, while feed-grade volume dominates tonnage through integration with lysine and threonine premix operations. Chemical synthesis retains cost leadership for industrial applications, though enzymatic routes are gaining share in food and cosmetic segments where non-GMO certification carries premium positioning.
FDA purity standards for injectable-grade glycine, REACH substance registration thresholds in Europe, and China's GB standards for feed additives collectively shape market access and product differentiation across supply chains. The EPA monitors glycine-derived glyphosate precursor pathways, creating compliance complexity for North American agrochemical end users. Stakeholders must monitor fermentation yield improvements and regulatory divergence between pharmaceutical and feed-grade specifications to align capacity investments with margin trajectory.
Market Dynamics
Feed-grade glycine capacity expansion in China is compressing global pricing benchmarks while pharmaceutical-grade purity requirements tighten under FDA and EMA validation protocols, creating a bifurcated margin structure across end-use segments.
Growth Catalysts
- Biologic manufacturing expansion:Cell culture media producers are scaling glycine procurement for monoclonal antibody buffer systems, with parenteral nutrition formulators following similar volume trajectories.
- REACH substance registration thresholds:EU importers are consolidating supplier relationships to meet ECHA compliance documentation, favoring validated pharmaceutical-grade producers over commodity traders.
- Strecker synthesis yield improvements:Chemical manufacturers in Shandong and Hebei provinces are achieving cost parity with fermentation routes for 98.5% purity grades, accelerating feed additive penetration.
Market Restraints
- Chloroacetic acid price volatility:This petrochemical feedstock for Strecker synthesis fluctuates with ethylene chain economics, compressing margins for industrial-grade producers during upstream energy spikes.
- China supply concentration:Over 60% of global feed-grade capacity sits within 200 kilometers of Shanghai, exposing buyers to port congestion risks and regional environmental enforcement actions.
- Glyphosate substitution pressures:Glycine-derived glyphosate precursors face regulatory scrutiny under EPA monitoring protocols, constraining agrochemical pathway expansion in North America.
Strategic Opportunities
- Indian pharmaceutical manufacturing:CDSCO's accelerating approval timelines for injectable-grade excipients create first-mover advantages for suppliers achieving USP-NF certification ahead of domestic capacity buildout.
- Semiconductor wet chemistry:Ultra-high-purity glycine for wafer cleaning applications commands 4-5x pharmaceutical-grade premiums, with Japanese and South Korean fabs expanding qualification programs.
- EU Green Deal bio-based mandates:Fermentation-derived glycine qualifies for renewable content credits in cosmetic and food applications, creating positioning advantages over petrochemical routes in European personal care supply chains.
Industry Challenges
- Multi-jurisdiction validation timelines:Simultaneous FDA, EMA, and NMPA dossier preparation for pharmaceutical-grade glycine extends certification cycles to 18-24 months, freezing working capital in regulatory submissions.
- Legacy electroplating customer retention:Metal finishing shops in Germany and Japan resist purity upgrades for chelation applications, fragmenting SKU requirements across customer tiers.
- Fermentation scale-up biology:Microbial strain optimization for food-grade non-GMO certification requires specialized biochemist talent pools concentrated in Denmark and Netherlands contract research organizations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Glycine Market |
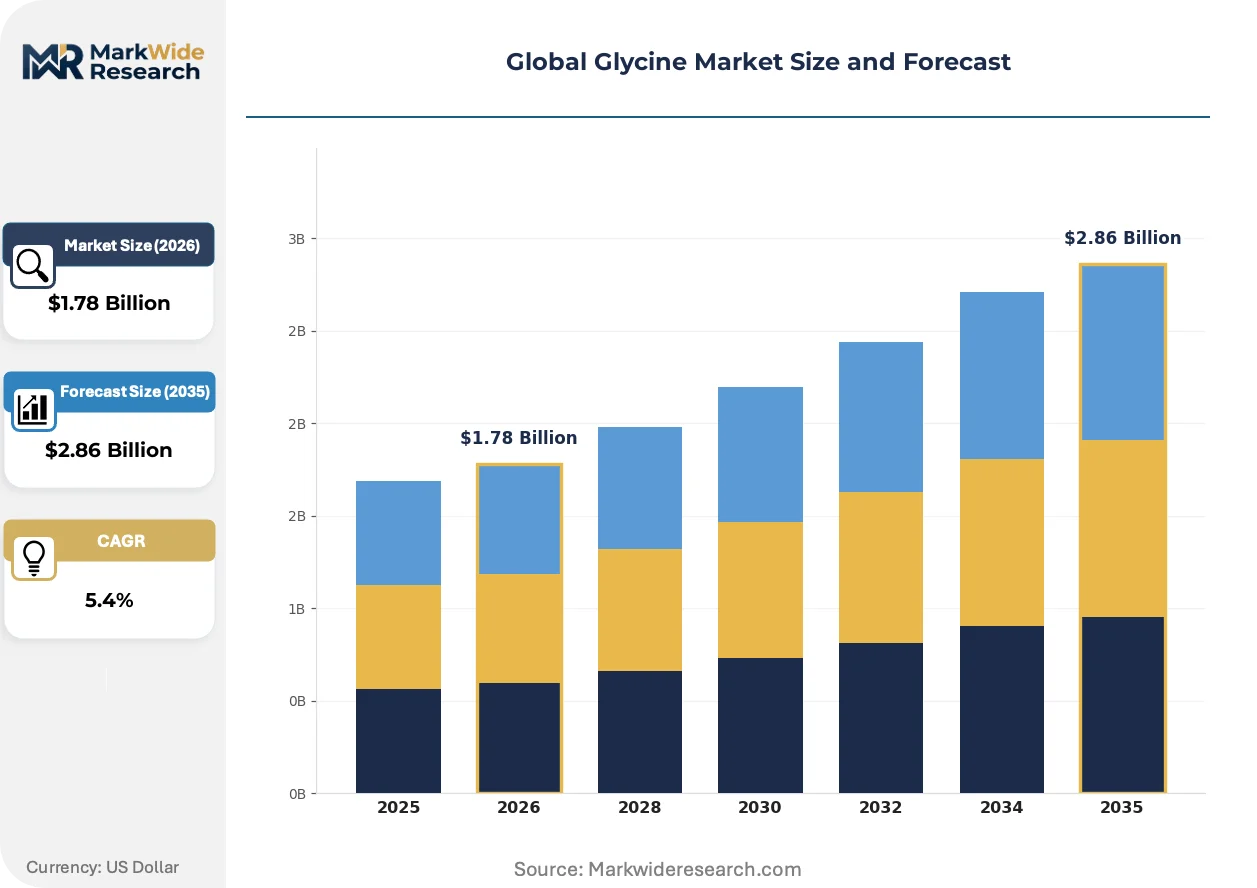
| Market Size in 2026 | $1.78 Billion |
| Market Size in 2035 | $2.86 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Feed Grade, Food Grade, Pharmaceutical Grade, Industrial Grade, Cosmetic Grade Application: Animal Nutrition, Food & Beverage, Personal Care, Pharmaceuticals, Agriculture Chemicals Manufacturing Process: Fermentation, Chemical Synthesis, Enzymatic Synthesis, Extraction, Hydrogenation End User Industry: Feed Manufacturers, Food Processing Units, Pharmaceutical Companies, Cosmetic Producers, Agrochemical Firms |
| Companies Covered | Ajinomoto Co., Inc., Evonik Industries AG, Showa Denko K.K., GEO Specialty Chemicals, Chattem Chemicals, Yuki Gosei Kogyo Co., Ltd., Nantong Guangrong Chemical Co., Ltd., Hebei Donghua Jiheng Chemical Co., Ltd., Shijiazhuang Donghua Jinlong Chemical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Glycine Market Shifts & Advancements
Enzymatic fermentation routes are gaining commercial traction against chemical synthesis as non-GMO certification becomes a definitional purchasing criterion in premium food and cosmetic segments.
Continuous flow Strecker synthesis is overtaking batch reactor configurations for industrial-grade production. German chemical engineering firms are licensing skid-mounted systems to Chinese producers seeking yield consistency above 94% for electroplating and agrochemical intermediates. This process intensification is compressing capital requirements per ton of installed capacity by half versus conventional stirred-tank operations.
REACH Annex XVII restrictions on chloroacetic acid impurities are tightening residual limits for glycine entering European pharmaceutical supply chains. ECHA's 2023 substance evaluation dossier is forcing importers to source from producers with dedicated pharmaceutical lines rather than dual-use feed-grade facilities. German and French formulators are responding by auditing Chinese suppliers for segregated manufacturing protocols and dedicated QC laboratories.
Long-term offtake contracting is displacing spot market purchasing among North American parenteral nutrition compounders. Hospital procurement consortiums are locking 36-48 month supply agreements with validated producers to secure buffer inventory against China port disruptions. This behavior shift is most visible in California and Massachusetts bioclusters, where just-in-time inventory models previously dominated amino acid sourcing.
Global Glycine Market Segmentation
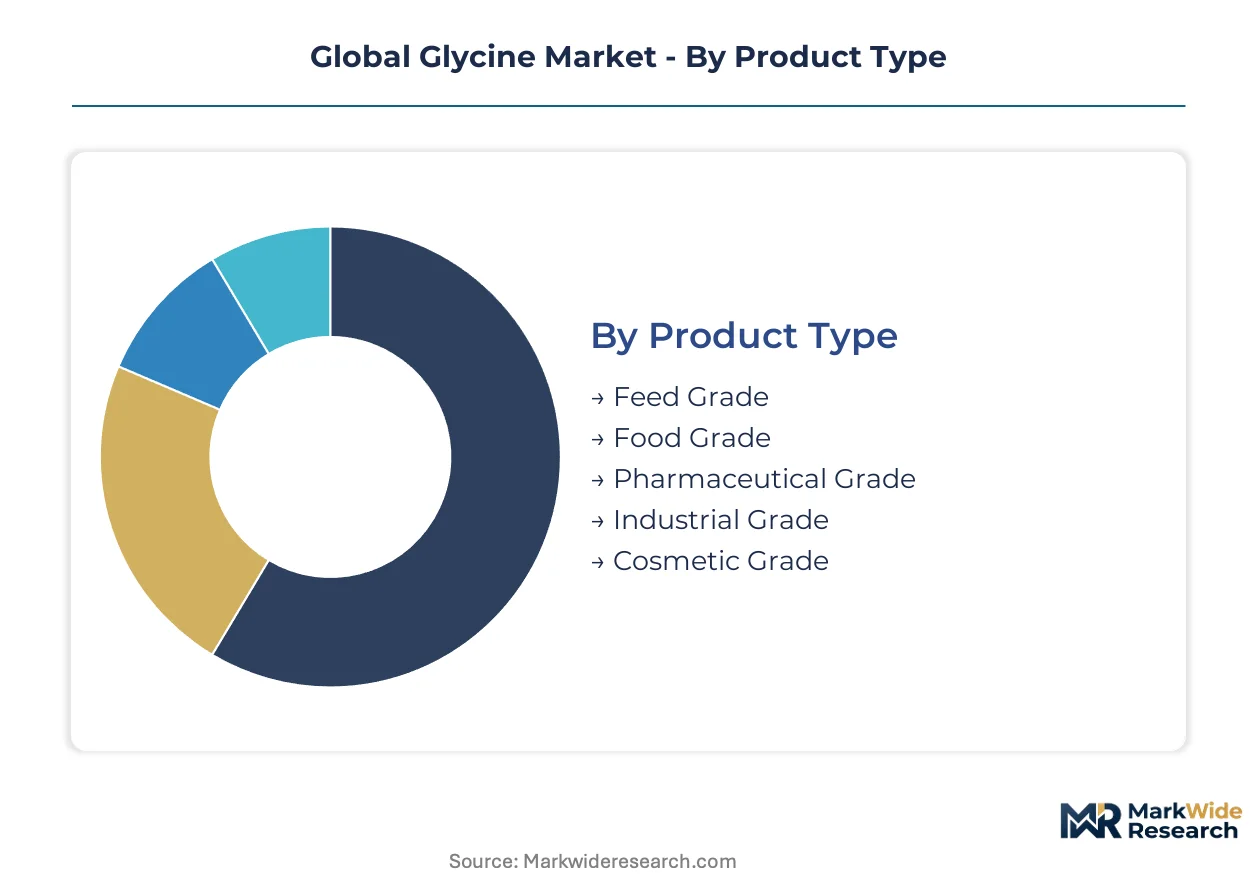
Glycine market segmentation reflects a fundamental tension between commodity volume and certified purity premiums. Manufacturers configure production lines around either feed-grade scale economics or pharmaceutical-grade validation protocols, with limited overlap in equipment and quality systems.
Product Type:
Volume concentration in feed-grade output contrasts sharply with margin capture in pharmaceutical and cosmetic certifications.
- Feed Grade:Specifications center on 98.5% minimum purity with controlled moisture content for premix stability. Demand concentrates in Shandong and Hebei province feed additive operations, where Strecker synthesis cost leadership supports lysine-threonine premix integration. Capacity expansion here compresses global pricing benchmarks.
- Pharmaceutical Grade:USP-NF and EP monograph compliance requires 99.5%+ purity with endotoxin and heavy metal documentation. Parenteral nutrition compounders in Massachusetts and California bioclusters drive procurement, with FDA validation timelines extending supplier qualification to 18-24 months.
- Food Grade:FCC and non-GMO certification protocols apply, with fermentation routes preferred for clean-label positioning in European natural food channels.
- Industrial Grade:Metal chelation specifications for electroplating baths dominate, with German and Japanese metal finishing shops resisting purity upgrades that disrupt established process chemistry.
- Cosmetic Grade:EU Green Deal bio-based content credits favor fermentation-derived supply chains in French and German personal care formulator networks.
Today's leader: Feed Grade. Tomorrow's challenger: Pharmaceutical Grade.
Application:
End-use diversification tracks regulatory stringency and formulation complexity across consumer and industrial markets.
- Animal Nutrition:Swine and poultry premix integration accounts for dominant tonnage, with procurement centralized through integrated feed compounders seeking amino acid bundle economics.
- Pharmaceuticals:Monoclonal antibody buffer systems and parenteral nutrition formulations command premium positioning, with cell culture media producers scaling glycine procurement fastest.
- Food & Beverage:Sweetness modulation and buffering applications in beverage processing, constrained by clean-label certification requirements in EU and North American markets.
- Personal Care:Moisturizer and anti-aging formulations leverage glycine collagen synthesis signaling, with South Korean cosmetic manufacturers expanding qualification programs.
- Agriculture Chemicals:Glyphosate precursor pathways face EPA monitoring constraints in North America, redirecting investment toward Asian agrochemical intermediate production.
Pharmaceutical applications expand most quickly; animal nutrition retains volume dominance.
Manufacturing Process:
Process selection determines certification eligibility and capital intensity across end-use segments.
- Chemical Synthesis:Strecker synthesis with chloroacetic acid and ammonia delivers cost leadership for 98.5% purity grades, with Chinese producers achieving yield consistency above 94% through continuous flow reactor adoption licensed from German engineering firms.
- Fermentation:Corynebacterium glutamicum strain optimization enables non-GMO certification for food and cosmetic segments, with biochemist talent concentrated in Danish and Dutch contract research organizations constraining scale-up velocity.
- Enzymatic Synthesis:Transaminase biocatalysis routes are gaining commercial traction for pharmaceutical-grade purity with reduced environmental footprint.
- Extraction:Protein hydrolysate recovery from collagen-rich substrates serves niche cosmetic and nutraceutical applications with limited scale potential.
- Hydrogenation:Imine reduction pathways for specialized high-purity grades in semiconductor wet chemistry applications command 4-5x pharmaceutical-grade premiums.
Chemical synthesis holds current volume leadership; fermentation claims the steepest expansion trajectory.
End User Industry:
Customer concentration and procurement sophistication vary sharply across downstream sectors.
- Feed Manufacturers:Integrated amino acid procurement through lysine-threonine premix bundling concentrates purchasing power among top-tier compounders, with specifications standardized around cost-per-unit-protein metrics.
- Pharmaceutical Companies:Parenteral nutrition formulators and biologic manufacturers enforce multi-jurisdiction validation requirements, with 36-48 month offtake contracting displacing spot purchasing among North American hospital procurement consortiums.
- Food Processing Units:Clean-label and non-GMO certification requirements fragment supplier relationships, with European processors auditing Chinese facilities for segregated manufacturing protocols.
- Cosmetic Producers:Bio-based content mandates under EU Green Deal create positioning advantages for fermentation-derived glycine in premium personal care supply chains.
- Agrochemical Firms:Glyphosate precursor demand faces regulatory substitution pressures in North American markets, with capacity investment redirecting toward Asian intermediate export channels.
Feed manufacturers dominate current procurement volume; pharmaceutical companies set tomorrow's purity and documentation standards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shandong province's chemical corridor commands the dominant share of global glycine manufacturing capacity, with fermentation and Strecker synthesis operations clustered within 200 kilometers of Qingdao port facilities.
China
Feed-grade glycine output concentrates in Hebei and Shandong provinces where chloroacetic acid supply chains integrate with lysine-threonine premix operations. NMPA pharmaceutical-grade validation requirements are tightening documentation standards for export-oriented producers. Zhejiang province's fermentation specialists are scaling non-GMO certified capacity for European cosmetic and food ingredient channels.
United States
Parenteral nutrition compounders in Massachusetts and California bioclusters are locking 36-48 month supply agreements to buffer against port disruptions. FDA injectable-grade purity standards enforce endotoxin and heavy metal documentation thresholds that disqualify dual-use feed-grade facilities. EPA monitoring of glyphosate precursor pathways constrains agrochemical intermediate expansion in Gulf Coast chemical corridors.
Germany
Evonik Industries anchors industrial-grade production through continuous flow reactor systems licensed to Asian producers seeking yield improvements. REACH Annex XVII restrictions on chloroacetic acid residuals force pharmaceutical formulators to audit Chinese suppliers for segregated manufacturing protocols. North Rhine-Westphalia's metal finishing shops resist purity upgrades for electroplating chelation applications.
Japan
Showa Denko K.K. and Yuki Gosei Kogyo occupy positions in ultra-high-purity glycine for semiconductor wet chemistry applications commanding 4-5x pharmaceutical-grade premiums. METI industrial policy supports biocatalysis research for reduced environmental footprint manufacturing. Kanto region fabs are expanding qualification programs for wafer cleaning buffer systems.
India
CDSCO's accelerating approval timelines for injectable-grade excipients create positioning opportunities for suppliers achieving USP-NF certification. Maharashtra and Gujarat pharmaceutical manufacturing clusters are building downstream formulation capacity that will absorb certified glycine volumes. Domestic fermentation capacity remains underdeveloped relative to projected biologic manufacturing expansion through 2035.
Global Glycine Market Competitive Landscape
Capacity expansion dominates the current landscape as Chinese producers scale continuous flow reactor installations and Indian pharmaceutical compounders build captive buffer inventory. The vendor base organizes around three strategic archetypes: fermentation-based specialists serving non-GMO certification markets, chemical synthesis scale operators optimizing feed-grade cost positions, and multi-process integrated suppliers spanning pharmaceutical and industrial grades. M&A activity concentrates on fermentation technology access, while strategic partnerships lock long-term offtake arrangements between validated producers and North American hospital procurement consortiums.
Among Japanese chemical specialists, Showa Denko K.K. exemplifies the ultra-high-purity archetype for semiconductor applications, while Ajinomoto Co., Inc. represents fermentation-based supply chains validated across Asian pharmaceutical markets. Evonik Industries AG anchors the chemical synthesis scale tier from German manufacturing bases. These three occupy positions that reflect divergent process technology bets rather than direct segment overlap.
| Leading Market Players |
|---|
| Ajinomoto Co., Inc. |
| Evonik Industries AG |
| Showa Denko K.K. |
| GEO Specialty Chemicals |
| Chattem Chemicals |
| Yuki Gosei Kogyo Co., Ltd. |
| Nantong Guangrong Chemical Co., Ltd. |
| Hebei Donghua Jiheng Chemical Co., Ltd. |
| Shijiazhuang Donghua Jinlong Chemical Co., Ltd. |
| Others |
Supply & Pricing Matrix
EU Green Deal bio-based mandates gate qualified supply for fermentation-derived glycine and premium-tier pricing access in French and German personal care channels. Pharmaceutical-grade certification requirements under FDA and EMA protocols further stratify pricing power, separating validated producers from commodity traders serving feed-grade buyers.
Pricing Analysis
Distributor margins for pharmaceutical-grade glycine compress under long-term offtake contracting as North American hospital procurement consortiums lock 36-48 month supply agreements. Three-tier pricing structure across pharmaceutical, food, and feed grades reflects purity thresholds and documentation burden. Cost compression in feed-grade runs through Shandong province capacity expansion. Feed manufacturers exhibit highest price sensitivity; semiconductor fabs accept 4-5x premiums for ultra-high-purity grades.
Supply Chain Analysis
India's PLI scheme for pharmaceutical manufacturing is reshaping sourcing patterns as Maharashtra and Gujarat clusters build downstream formulation capacity. Supply concentrates in China, Germany, and Japan, with chloroacetic acid, ammonia, and fermentation feedstocks anchoring input costs. Single-source vulnerability from Shandong-Hebei corridor concentration exposes buyers to port congestion. Distribution runs through integrated feed compounders and validated pharmaceutical suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Parenteral nutrition formulators are shifting procurement toward USP-NF certified suppliers with dedicated pharmaceutical lines and segregated QC protocols.
For Market Incumbents: Anticipate margin compression from Chinese Strecker synthesis scale by securing backward integration into chloroacetic acid supply or fermentation capacity expansion in Zhejiang province. Defend position through NMPA, FDA, and EMA tri-validation dossiers that freeze out dual-use feed-grade facilities. Prioritize 36-48 month offtake contracting with Massachusetts and California bioclusters to lock buffer inventory relationships.
For New Entrants and Emerging Players: Enzymatic biocatalysis routes offer technology-first wedge into pharmaceutical-grade purity tiers with reduced environmental footprint versus petrochemical pathways. Target CDSCO injectable-grade excipient approvals in Maharashtra and Gujarat before domestic Indian fermentation capacity matures. Lead with non-GMO certification for European cosmetic and food ingredient channels where EU Green Deal bio-based credits command positioning premiums.
For Investors and Strategic Acquirers: Roll-up economics work for fermentation-based specialists with validated strain libraries because multi-jurisdiction certification timelines create captive customer relationships and switching costs. Five-to-ten year viability hinges on biologic manufacturing expansion and semiconductor wet chemistry qualification programs. Watch for ECHA substance evaluation dossier enforcement as inflection indicator for supplier consolidation toward segregated pharmaceutical lines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chloroacetic Acid | Secures petrochemical feedstock supply against ethylene chain volatility for Strecker synthesis operators. |
| Fermentation Capacity Expansion | Enables non-GMO certification access to EU Green Deal bio-based credit markets in personal care. |
| Multi-Jurisdiction Validation Investment | Creates 18-24 month qualification barriers against dual-use feed-grade competitors under FDA and EMA protocols. |
| Long-Term Supply Agreement Lock | Displaces spot purchasing among North American parenteral nutrition compounders facing port disruption risks. |
| Semiconductor Wet Chemistry Qualification | Captures 4-5x pharmaceutical-grade premiums through ultra-high-purity hydrogenation pathway development. |
Research Methodology
Multiple input streams — primary interviews with pharmaceutical procurement managers, fermentation R&D directors, and feed compounder supply chain leads; secondary validation through FDA 510(k) filings, EMA submission databases, and Chinese customs trade data; plus technical literature on Strecker synthesis yield optimization — were reconciled through bottom-up capacity modeling and top-down demand segmentation triangulation.
Data-stream reconciliation anchored volume and value outputs across the projection horizon. Segmentation dimensions modeled include grade tier, end-use industry, manufacturing process, and regional production hub. CAGRs were derived from trend extrapolation of parenteral nutrition formulation growth and semiconductor fab qualification program expansion. Forecast inputs incorporated chloroacetic acid feedstock cost trajectories and REACH Annex XVII regulatory enforcement timelines.
The model holds under steady regulatory enforcement and biologic manufacturing expansion; deviation in EPA glyphosate precursor restrictions or China environmental enforcement actions would shift capacity investment patterns. Forecasts reflect documented assumptions on yield improvements and certification timeline standardization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Fungicide Active Ingredients Market
Chemicals
Desalination Chemicals Market
Chemicals
2-(4-(Bromomethyl)phenyl)propionic Acid (BMPPA) Market
Chemicals
Methidathion (CAS 950-37-8) Market
Chemicals
Chloroplatinic Acid Market
Chemicals
Inorganic Chemicals Market
Chemicals
Welding Chemicals Market
Chemicals
Pyromellitic Dianhydride Market
Chemicals
United Kingdom Methanol Market
Chemicals
Tetrapotassium Pyrophosphate Market
Chemicals
Mining Flotation Chemicals Market
Chemicals
Automotive Appearance Chemicals Market
Chemicals
Sodium Methoxide Market
Chemicals
Carbon Tetrabromide Market
Chemicals
Hexachloroethane Market
Chemicals
North America Ethylene Dichloride (EDC) Market