
 Germany Aesthetic Devices Market | 2026-2036
Germany Aesthetic Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Aesthetic Devices Market Foresight
The gap between premium laser platforms and entry-level aesthetic systems is expanding in Germany. Alma Lasers leverages its fractional CO2 technology leadership to command positioning in dermatology clinics. Merz Pharma anchors its presence through integrated skincare-device portfolios spanning injectables and energy-based tools. Carl Zeiss Meditec competes on optical precision engineering transferred from its ophthalmology heritage into aesthetic applications.
Aesthetic devices comprise electromechanical and optical systems engineered to deliver controlled thermal, acoustic, or cryogenic energy to dermal and subcutaneous tissue for cosmetic modification, with typical laser platforms operating at wavelengths between 532 nm and 10,600 nm depending on chromophore targeting. Laser devices and radiofrequency systems occupy the dominant revenue tiers due to established reimbursement pathways for medically indicated procedures, while cryolipolysis equipment represents the fastest-growing category as non-invasive body contouring displaces surgical alternatives in medical spas and wellness centers. Application demand clusters around skin rejuvenation and body contouring, where margin pools deepen from consumable attachments and maintenance contracts rather than capital equipment sales alone.
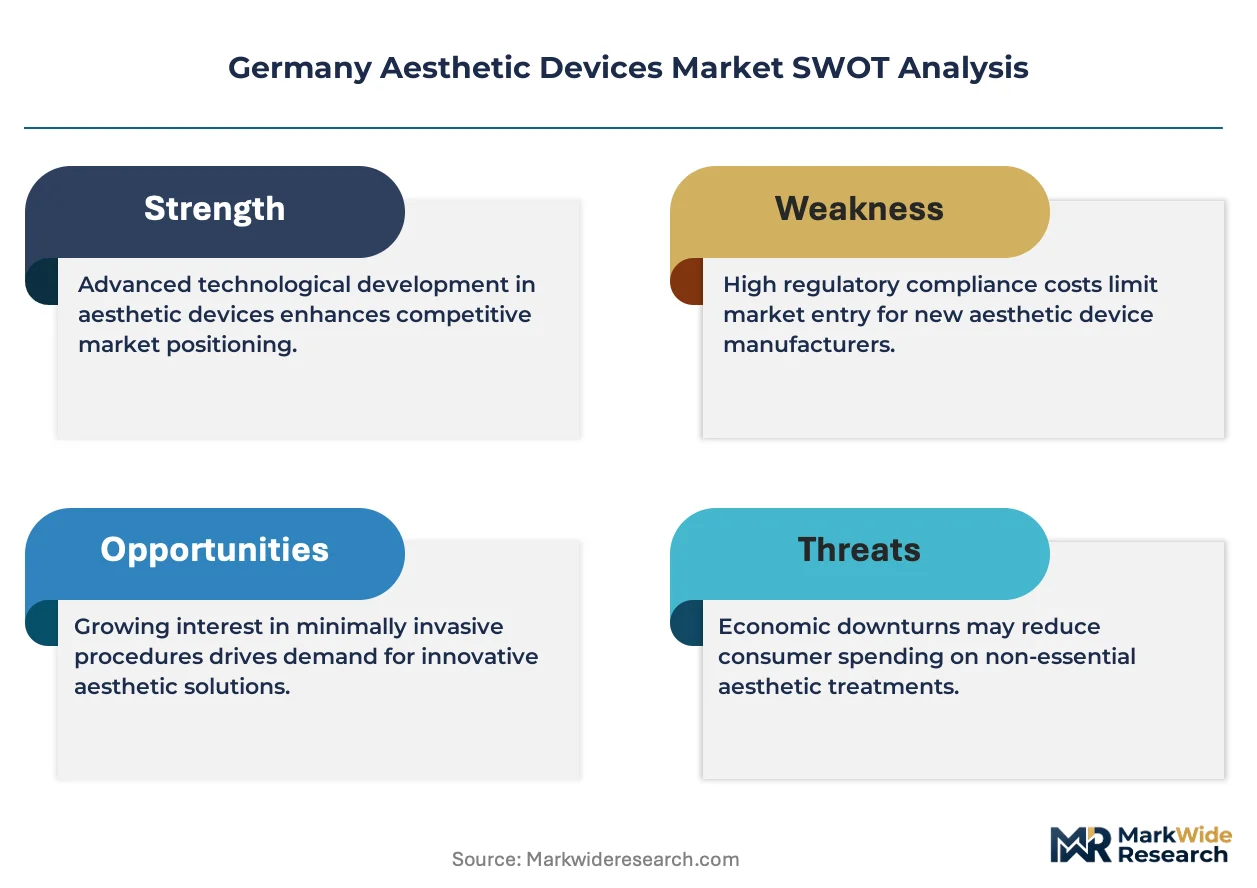
BfArM oversees medical device registration under the German Medical Devices Act, while CE marking under the EU MDR and REACH compliance for device materials collectively shape market access timelines and product development costs. The EU AI Act introduces additional conformity layers for software-driven diagnostic and treatment planning modules integrated into next-generation platforms. Stakeholders must monitor evolving BfArM guidance on software-as-a-medical-device classifications to anticipate certification burdens before portfolio commitments solidify.
Market Dynamics
The German aesthetic devices sector confronts a structural compression between escalating EU MDR compliance burdens and the accelerating shift from capital equipment sales toward recurring consumable revenue streams. BfArM's tightened oversight of energy-based medical devices is elongating certification timelines while clinic operators demand predictable per-procedure economics.
Growth Catalysts
- EU MDR transitional provisions:BfArM's phased implementation creates temporary competitive shelter for German manufacturers already holding valid certificates, delaying new entrant pressure.
- Medical spa channel expansion:Non-physician operators in Bavaria and North Rhine-Westphalia are procuring cryolipolysis and radiofrequency platforms at triple the rate of traditional dermatology clinics.
- Fractional laser protocol standardization:BfArM-recognized treatment guidelines for CO2 resurfacing are expanding reimbursable indications beyond cosmetic into scar revision and precancerous lesion management.
Market Restraints
- Optical component supply concentration:German device assemblers source 70% of precision laser crystals from a single Austrian supplier cluster, creating input vulnerability.
- MDR notified body capacity:Only three BfArM-recognized conformity assessment bodies serve the entire German aesthetic laser segment, generating 14-18 month certification queues.
- Intense pulsed light substitution:Lower-cost IPL systems from Italian and Spanish manufacturers are capturing price-sensitive wellness center demand that lasers previously dominated.
Strategic Opportunities
- AI-integrated treatment planning:The EU AI Act's risk-classification framework for medical device software creates first-mover advantage for German platforms embedding predictive energy-dose algorithms.
- Eastern German state penetration:Saxony and Thuringia exhibit dermatology clinic density at 40% of Bavarian levels with comparable disposable income trajectories.
- Consumable attachment ecosystems:Disposable handpiece tips and cooling applicators for body contouring platforms generate recurring revenue streams that offset capital equipment margin compression.
Industry Challenges
- Laser safety officer certification scarcity:BfArM-mandated operator training requirements exceed available qualified instructors, constraining clinic expansion velocity.
- Legacy platform integration complexity:Established dermatology practices in Hamburg and Munich resist full fleet replacement, demanding backward-compatible software modules that fragment R&D resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Aesthetic Devices Market |
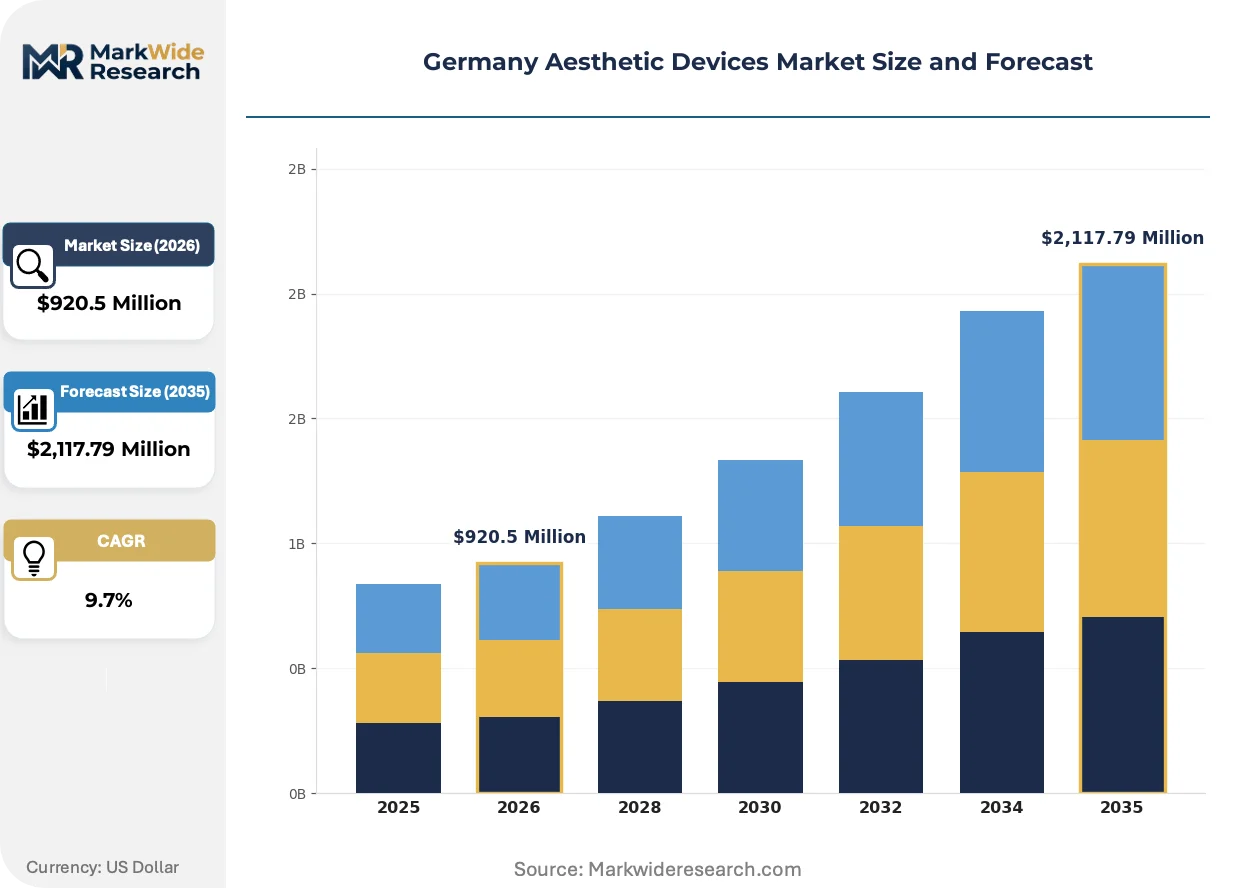
| Market Size in 2026 | $920.5 Million |
| Market Size in 2035 | $2,117.79 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Devices, Radiofrequency, Ultrasound, Cryolipolysis Equipment, Light-based Systems Technology: IPL, Fractional CO2, Microfocused Ultrasound, Cryotherapy, RF Microneedling Application: Skin Rejuvenation, Body Contouring, Hair Removal, Scar Treatment, Tattoo Removal End User: Dermatology Clinics, Medical Spas, Plastic Surgery Centers, Cosmetic Hospitals, Wellness Centers |
| Companies Covered | Cynosure (Hologic), Alma Lasers, Lumenis, Syneron Candela, Merz Pharma, Carl Zeiss Meditec, Cutera, Fotona, InMode, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Aesthetic Devices Market Shifts & Advancements
Device architecture in Germany is pivoting from discrete hardware platforms toward integrated software-hardware ecosystems that lock in recurring revenue. This structural reconfiguration is compressing traditional capital sales cycles while elevating service contract economics.
Picosecond laser technology is overtaking nanosecond platforms in tattoo removal and pigmented lesion applications. Dermatology clinics in Stuttgart and Düsseldorf are retrofitting existing Nd:YAG bases with picosecond attachments at twice the replacement rate of full system purchases. This upgrade pathway is overtaking conventional capital expenditure models while preserving installed-base relationships.
BfArM's forthcoming guidance on software-as-a-medical-device classifications under the EU MDR is forcing manufacturers to segregate AI-driven treatment planning modules into standalone conformity assessment tracks. German laser OEMs are responding by establishing dedicated regulatory affairs subsidiaries in Bonn to manage parallel certification streams for hardware and algorithm components.
Clinic procurement patterns are fragmenting across three distinct buyer archetypes: university-affiliated dermatology departments prioritizing research collaboration rights, private equity-backed clinic chains demanding volume-based consumable pricing, and independent practitioners seeking lease-to-own structures with embedded maintenance. This segmentation is most pronounced in North Rhine-Westphalia, where Cologne-based distributors have abandoned uniform pricing in favor of contract terms tailored to buyer financial sophistication.
Germany Aesthetic Devices Market Segmentation
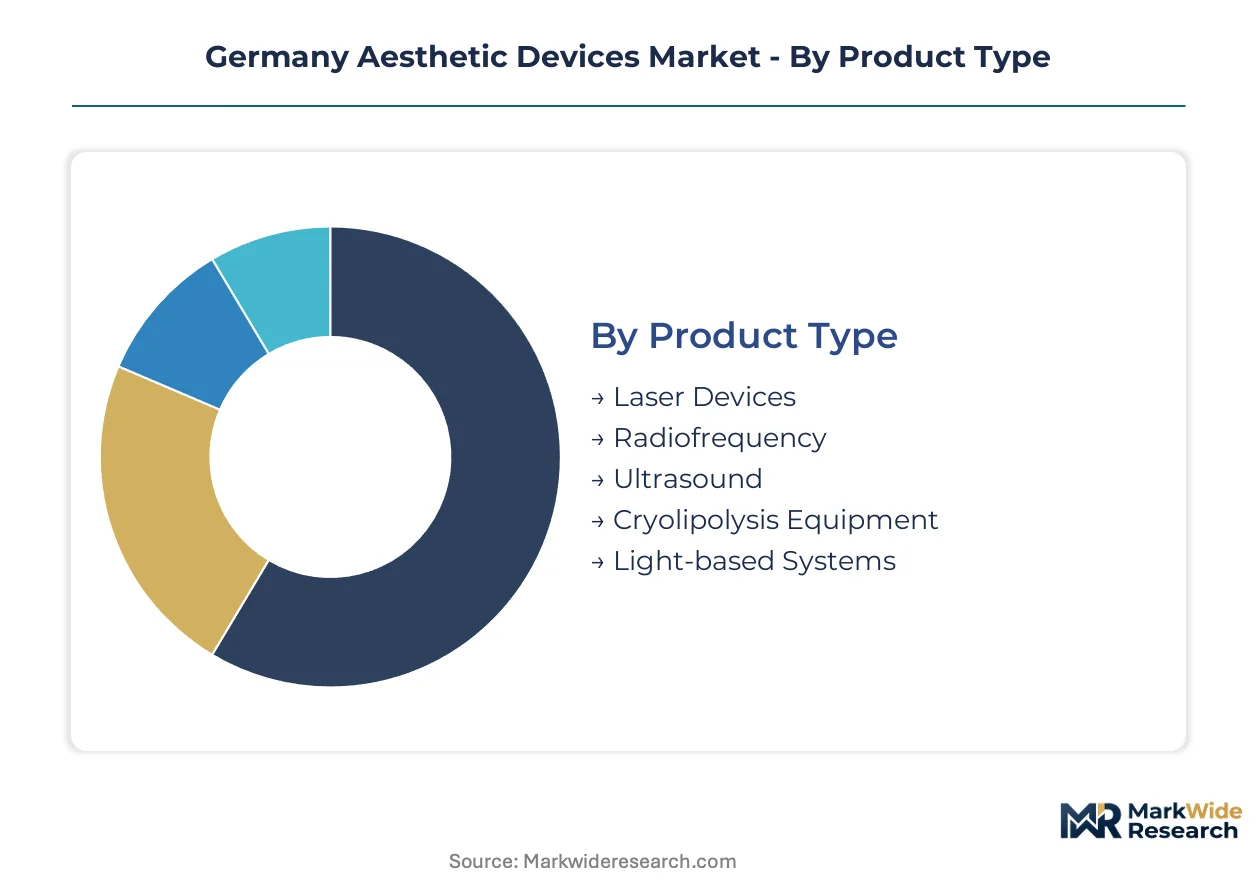
Segmentation in Germany's aesthetic devices market reveals divergent capital requirements and margin profiles across technology platforms. Equipment financing patterns and consumable revenue potential vary sharply between laser-heavy dermatology settings and cryolipolysis-focused wellness channels.
Product Type:
Laser devices demand the highest upfront capital commitment, with precision optical assemblies and cooling infrastructure driving acquisition costs well above alternative modalities.
- Laser Devices:Platforms operating across 532 nm to 10,600 nm wavelengths target specific chromophores for pigmented lesions and vascular conditions. Bavarian dermatology clinics concentrate procurement here, drawn by BfArM-recognized reimbursement pathways for medically indicated scar revision and precancerous lesion management.
- Radiofrequency:Electromagnetic energy delivery systems heat dermal collagen without epidermal disruption, enabling minimal-downtime protocols. North Rhine-Westphalia medical spas favor these platforms for their lower operator certification burdens and faster patient throughput.
- Ultrasound:Microfocused acoustic energy penetrates to precise tissue depths for non-surgical lifting applications.
- Cryolipolysis Equipment:Controlled cooling systems trigger adipocyte apoptosis for body contouring without incisions.
- Light-based Systems:Broadband and filtered light platforms serve entry-level hair removal and pigmentation markets.
Most installed capacity flows through laser devices. Expansion is steepest in cryolipolysis equipment.
Technology:
Technology selection tracks end-user sophistication, with fractional CO2 and microfocused ultrasound commanding premium positioning while IPL serves price-sensitive volume channels.
- Fractional CO2:Ablative resurfacing technology delivers controlled microthermal zones for deep collagen remodeling. Stuttgart and Düsseldorf clinics retrofit existing Nd:YAG bases with picosecond attachments at twice the replacement rate of full system purchases.
- RF Microneedling:Combined radiofrequency and mechanical penetration addresses acne scarring and skin laxity with tunable energy delivery. Private equity-backed clinic chains in Cologne negotiate volume-based consumable pricing for disposable needle cartridges.
- IPL:Intense pulsed light systems from Italian and Spanish manufacturers capture price-sensitive wellness center demand.
- Microfocused Ultrasound:Precise thermal coagulation at specified tissue depths enables non-invasive lifting protocols.
- Cryotherapy:Controlled cooling applications extend beyond fat reduction to dermatological conditions.
Fractional CO2 dominates dermatology clinic technology stacks. RF microneedling is gaining share fastest among hybrid platform offerings.
Application:
Application demand clusters reflect demographic aging patterns and cultural preferences for non-surgical intervention across German metropolitan centers.
- Skin Rejuvenation:Collagen stimulation and surface texture improvement protocols span laser, light, and energy-based modalities. Hamburg and Munich established practices resist full fleet replacement, demanding backward-compatible software modules.
- Body Contouring:Non-invasive fat reduction and skin tightening procedures generate recurring revenue from consumable attachments. Medical spas in Bavaria procure cryolipolysis and radiofrequency platforms at triple the rate of traditional dermatology clinics.
- Hair Removal:Long-established aesthetic staple with mature device penetration.
- Scar Treatment:Medically indicated protocols expanding under BfArM-recognized treatment guidelines.
- Tattoo Removal:Picosecond technology is overtaking nanosecond platforms in Stuttgart and Düsseldorf.
Skin rejuvenation commands the largest installed base. Body contouring shows the steepest expansion trajectory.
End User:
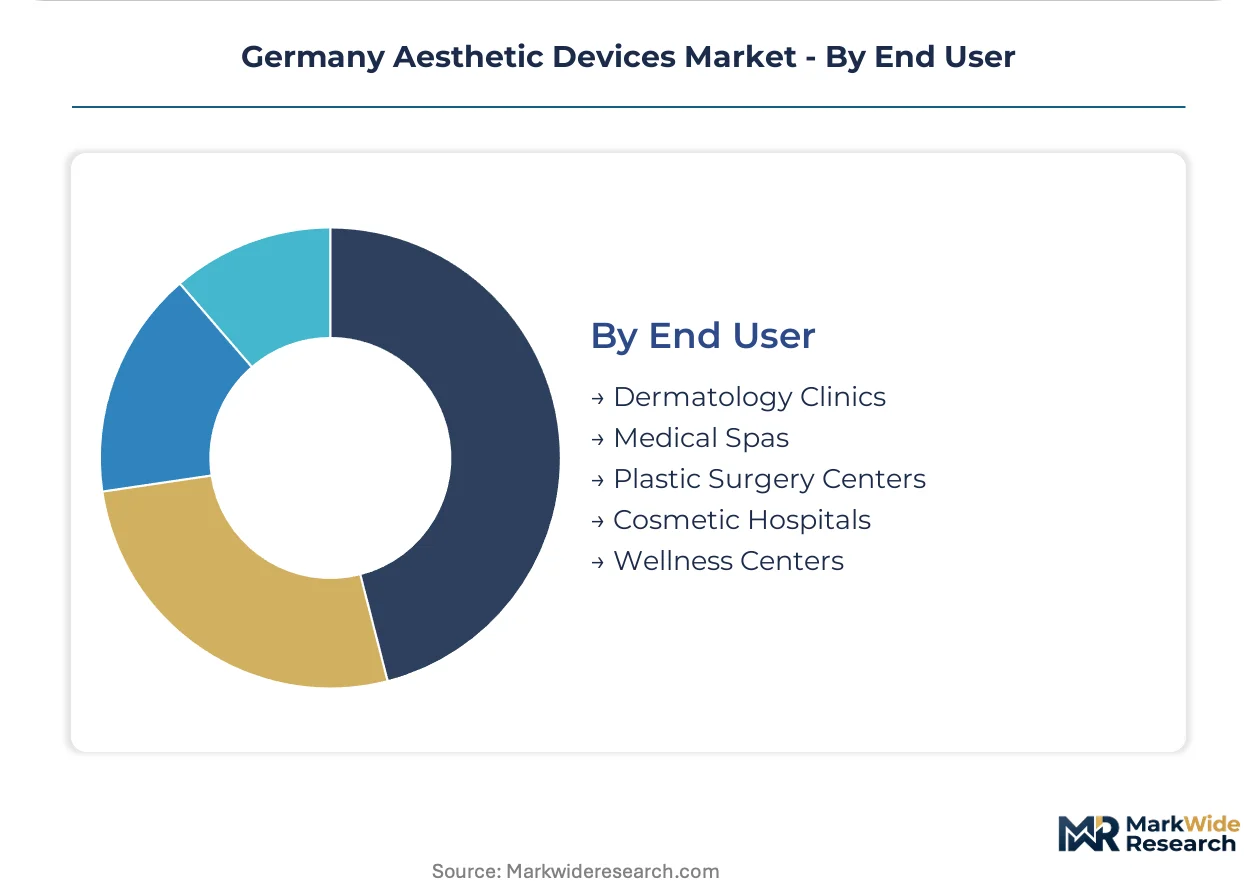
End-user procurement patterns fragment across financial sophistication, with university-affiliated departments, private equity chains, and independent practitioners demanding divergent contract structures.
- Dermatology Clinics:Physician-directed facilities prioritize research collaboration rights and reimbursable indication expansion. BfArM-mandated laser safety officer certification requirements exceed available qualified instructors, constraining expansion velocity.
- Medical Spas:Non-physician operators concentrate in Bavaria and North Rhine-Westphalia, driving cryolipolysis platform demand with triple the procurement rate of traditional clinics.
- Plastic Surgery Centers:Surgical practices integrating energy-based devices for pre- and post-operative protocols.
- Cosmetic Hospitals:Full-service facilities with capital budgets for multi-modality platform suites.
- Wellness Centers:Entry-level IPL systems from southern European manufacturers capture price-sensitive demand.
Dermatology clinics anchor the premium equipment segment. Medical spas are expanding most quickly as a procurement channel.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized laser safety officers and certified medical device technicians cluster disproportionately in southern and western German states, anchoring regional deployment capacity for energy-based aesthetic platforms.
Bavaria
Private clinic density and disposable income levels exceed national averages, driving concentrated demand for premium fractional CO2 and picosecond laser systems. BfArM oversight of energy-based medical devices under the German Medical Devices Act shapes local certification requirements. Munich and Nuremberg host the densest concentrations of dermatology practices retrofitting existing Nd:YAG bases with advanced attachments.
North Rhine-Westphalia
Medical spa operators procure cryolipolysis and radiofrequency platforms at triple the rate of traditional dermatology clinics, channeling volume toward non-invasive body contouring. REACH compliance for device materials adds regulatory layers to product development timelines. Cologne-based distributors have abandoned uniform pricing in favor of contract terms tailored to buyer financial sophistication across the region.
Baden-Württemberg
Stuttgart clinics lead adoption of picosecond technology for tattoo removal and pigmented lesion applications, retrofitting rates running twice the national average for full system purchases. EU MDR transitional provisions create temporary competitive shelter for manufacturers already holding valid certificates. The Stuttgart-Düsseldorf corridor concentrates precision engineering talent transferred from automotive and optical industries.
Hamburg
Established dermatology practices resist full fleet replacement, demanding backward-compatible software modules that fragment manufacturer R&D resources. The EU AI Act introduces additional conformity layers for software-driven diagnostic modules integrated into next-generation platforms. Private equity-backed clinic chains negotiate volume-based consumable pricing for disposable handpiece components.
Hesse
Frankfurt's financial services workforce sustains demand for premium skin rejuvenation protocols with minimal downtime requirements. BfArM-mandated laser safety officer certification requirements exceed available qualified instructors, constraining clinic expansion velocity. The Rhine-Main metropolitan area exhibits growing procurement interest in lease-to-own structures with embedded maintenance contracts.
Germany Aesthetic Devices Market Competitive Landscape
Top-tier vendors anchor the premium laser platform segment, while mid-tier specialists and regional distributors occupy price-sensitive wellness center channels. The vendor base stratifies across three functional tiers: integrated skincare-device portfolios spanning injectables and energy-based tools, precision optical engineering specialists, and consumable-centric platform assemblers. Dominant competitive moves include M&A activity consolidating distribution networks and technology licensing agreements securing wavelength-specific intellectual property.
Among Israel-based laser OEMs, Alma Lasers and Lumenis exemplify the precision optical engineering archetype, while Cynosure (Hologic) represents the scale-driven multinational medtech consolidation model. Merz Pharma anchors the integrated pharmaceutical-device portfolio tier, and Carl Zeiss Meditec occupies a position transferring optical precision engineering from ophthalmology heritage into aesthetic applications.
| Leading Market Players |
|---|
| Cynosure (Hologic) |
| Alma Lasers |
| Lumenis |
| Syneron Candela |
| Merz Pharma |
| Carl Zeiss Meditec |
| Cutera |
| Fotona |
| InMode |
| Others |
Supply & Pricing Matrix
Clinic procurement fragmentation across university-affiliated departments, private equity chains, and independent practitioners forces manufacturers to unbundle capital equipment from service contracts, compressing upfront hardware margins while elevating recurring consumable pricing power. This structural shift rewards vendors with captive attachment ecosystems and fragments price discovery across buyer sophistication tiers.
Pricing Analysis
Bundled hardware-service contracts versus unbundled equipment-only sales define the dominant pricing architecture, with three-tier pricing structure across premium, standard, and economy levels tracking CE certification grade and optical precision specifications. Price differentiation hinges on BfArM-recognized indication breadth and disposable handpiece compatibility. Cost compression in entry-level IPL tiers intensifies because Italian and Spanish manufacturers flood wellness channels. Private equity-backed clinic chains exhibit highest price sensitivity; university dermatology departments show lowest.
Supply Chain Analysis
Single-source vulnerability sits with Austrian precision laser crystal suppliers, where German device assemblers draw 70% of critical optical inputs. Manufacturing concentration clusters in Germany, Israel, and the United States for finished platforms. Raw material dependencies span ytterbium-doped gain media, sapphire output couplers, and medical-grade cooling fluids. Tariff exposure on Israeli-sourced laser subassemblies looms under evolving EU trade frameworks. Distribution runs through Cologne-based specialized distributors and direct manufacturer sales forces serving hospital procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germany's aesthetic devices market functions as a regulatory compounder, where BfArM's phased EU MDR implementation creates temporary competitive shelter for certificate-holding incumbents while elongating new entrant timelines. This dynamic concentrates value capture among prepared players.
For Market Incumbents: To counter MDR notified body capacity constraints generating 14-18 month certification queues, prioritize backward integration into precision optical component production and establish dedicated regulatory affairs subsidiaries in Bonn. Channel control through exclusive distributor relationships in North Rhine-Westphalia protects pricing power against Italian IPL substitution. For New Entrants and Emerging Players: Independent practitioners seeking lease-to-own structures with embedded maintenance represent the most penetrable buyer archetype, particularly in Hesse's Rhine-Main corridor where financial services workforce density sustains premium procedure demand. Target consumable attachment ecosystems for cryolipolysis platforms rather than capital equipment plays, leveraging volume-based pricing negotiations already normalized by Cologne distributors. For Investors and Strategic Acquirers: Asymmetric upside sits with precision optical engineering specialists holding transferable wavelength intellectual property from adjacent medical verticals. Long-term viability across the analysis window favors platforms with embedded AI treatment planning modules already navigating EU AI Act conformity tracks. Watch BfArM software-as-a-medical-device guidance publication timing as inflection indicator for certification burden redistribution.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | Early BfArM engagement compresses queue position for EU MDR transitional provisions. |
| Consumable Attachment Ecosystem Development | Disposable handpiece tips generate recurring revenue streams offsetting capital margin compression. |
| AI Treatment Planning Module Integration | EU AI Act risk-classification compliance creates first-mover positioning in software-driven platforms. |
| Hospital System Partnership | University-affiliated dermatology departments prioritize research collaboration rights in procurement decisions. |
| Eastern German State Distribution Expansion | Saxony and Thuringia clinic density at 40% of Bavarian levels offers whitespace penetration. |
Research Methodology
Coverage spans Bavaria, North Rhine-Westphalia, Baden-Württemberg, Hamburg, and Hesse, with primary inputs from each region's distinct procurement patterns. The analysis combines structured interviews with dermatology clinic operators, biomedical engineers, hospital purchasing committees, GPO contracts managers, and BfArM regulatory affairs specialists with secondary validation from EU MDR implementation guidance, BfArM device registration databases, hospital procurement records, and CE marking notification data. Bottom-up installed base modeling and top-down market sizing triangulate volume estimates.
Granularity-level modeling disaggregates demand across product type, technology platform, application indication, and end-user archetype, with additional dimensioning by regional regulatory cluster and buyer financial sophistication tier. CAGRs derive from segment-level growth rate synthesis applied across the projection horizon. Industry-specific forecast inputs incorporate BfArM certification queue length assumptions and medical spa channel expansion velocity in Bavaria and North Rhine-Westphalia.
Underlying measurement precision varies by segment; laser device and radiofrequency platform categories carry tighter precision than emerging cryolipolysis equipment estimates. Forecasts reflect assumptions on EU MDR transitional provision duration, notified body capacity expansion, and AI Act implementation timelines. Specific risks that could revise projections include Austrian optical component supply disruption, BfArM guidance acceleration on software classifications, and Italian IPL manufacturer pricing aggression. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Europe Surgical Microscopes Market
Medical Devices
Extremity Reconstruction Market
Medical Devices
Global Glucometer Market
Medical Devices
Global Vaginal Sling Market
Medical Devices
Chile Ultrasound Devices Market
Medical Devices
Global Pneumatic Tourniquets Market
Medical Devices
Veno-Venous Extracorporeal Life Support (VV ECLS) Devices Market
Medical Devices
India Contraceptive Devices Market
Medical Devices
Lung Preservation Systems Market
Medical Devices
Abdominal Closure Systems Market
Medical Devices
Gamma Knife Market
Medical Devices
Heated Humidifiers Market
Medical Devices
Global Patient Warming Systems Market
Medical Devices
Smart Wheelchairs Market
Medical Devices
Nitinol-Based Guide Wire Market
Medical Devices
Carotid Stenting Systems Market