
 Asia-Pacific Nanofiber Market | 2026-2036
Asia-Pacific Nanofiber Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Nanofiber Market Outlook
Subscription-based technical support and predictive maintenance software for electrospinning equipment is realigning how nanofiber producers monetize output. Toray Industries leverages captive polymer supply chains to dominate high-performance filtration media in Japan. Donaldson Company anchors its Asia-Pacific position through localized air filtration R&D centers in China. Shenzhen Nanotech Port competes on cost-engineered composite nanofibers for domestic electronics supply chains.
Nanofibers are synthetic fibers with diameters below 100 nanometers, typically produced through electrospinning of polymers such as polyacrylonitrile, polyvinylidene fluoride, or biodegradable aliphatic polyesters into non-woven mats with surface-area-to-volume ratios exceeding conventional microfibers by orders of magnitude. These structures serve primarily as precision barriers, controlled-release matrices, or conductive scaffolds across medical, environmental, and energy applications. Electrospinning technology occupies the dominant production position due to its versatility across polymer classes and established scale-up pathways from laboratory to industrial roll-to-roll systems. Functionalized product types command premium positioning where surface chemistry modifications enable targeted drug delivery or selective molecular capture. Energy storage applications represent the fastest-expanding demand pool as solid-state battery developers adopt ceramic-polymer nanofiber separators.
China's SAMR enforces GB standards for nanomaterial classification and workplace exposure limits that directly shape factory certification requirements and import acceptance protocols. Japan's PMDA and METI coordinate on medical nanofiber device approvals, while South Korea's MFDS governs bioresorbable surgical mesh standards. India's CDSCO and BIS are developing aligned frameworks for nanofiber-based wound care products under the national pharmaceutical and quality infrastructure mandates. Stakeholders must monitor regulatory divergence on nanomaterial safety data sheet requirements across these jurisdictions to avoid fragmented compliance costs.
Market Dynamics
Electrospinning scale-up bottlenecks and China's dual carbon mandates are compressing margins for commodity-grade nanofiber producers while rewarding functionalized premium grades. Regional supply chains now pivot on polymer feedstock access and SAMR certification velocity.
Growth Catalysts
- Dual carbon goals:China's MEE enforcement tightens industrial air filtration standards, forcing power plants and steel mills toward high-efficiency nanofiber media replacement cycles.
- Solid-state battery separators:Ceramic-polymer nanofiber architectures are displacing conventional polyolefin separators as South Korean and Japanese cell makers advance next-generation energy density targets.
- Bioresorbable surgical mesh:Japan's PMDA fast-track pathways for nanofiber-based tissue scaffolds accelerate clinical adoption in hernia repair and wound closure applications.
Market Restraints
- Acrylonitrile price volatility:Polyacrylonitrile feedstock costs swing with crude oil and coal-chemicals pricing, squeezing electrospinning margins for standard filtration grades.
- Electrospinning equipment concentration:Precision nozzle and high-voltage system supply clusters in Germany and Japan create import dependency and extended lead times for Chinese and Indian producers.
- Regulatory fragmentation:Divergent nanomaterial safety data sheet requirements between China's SAMR, Japan's METI, and South Korea's MFDS multiply compliance overhead for cross-border suppliers.
Strategic Opportunities
- India's CDSCO alignment:Emerging wound care product frameworks under BIS quality infrastructure mandates open first-mover positioning for nanofiber dressing manufacturers.
- AI-driven process control:Machine vision and real-time fiber diameter monitoring converge with electrospinning lines to reduce defect rates and enable lot-to-lot consistency premiums.
- Subscription technical support:Predictive maintenance software for electrospinning equipment creates recurring revenue streams independent of commodity fiber pricing.
Industry Challenges
- Electrospinning operator expertise:Thin-film polymer rheology and high-voltage field optimization require specialized technicians scarce outside Japan's Kansai chemical corridor and select Chinese research institutes.
- GB standard certification timelines:China's SAMR nanomaterial classification protocols impose 12-18 month factory approval cycles that delay product launches and lock working capital.
- Roll-to-roll integration complexity:Laboratory-scale electrospinning protocols fail to translate directly to industrial continuous production, yielding yield losses during scale-up transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Nanofiber Market |
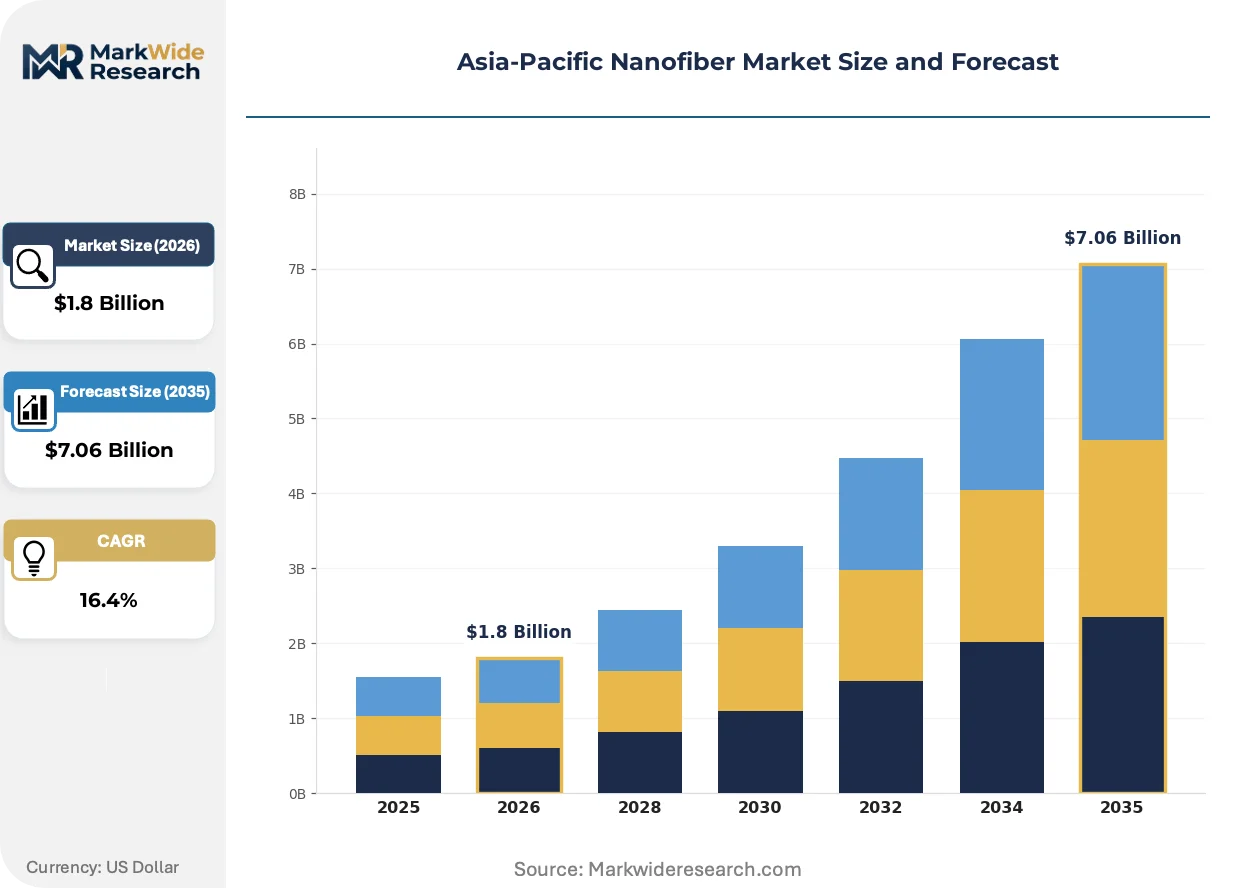
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Incorporated, Composite, Coated, Functionalized End User: Medical, Textiles, Filtration, Electronics Application: Drug Delivery, Air Filtration, Wound Care, Energy Storage Technology: Electrospinning, Phase Separation, Self-Assembly, Melt Blowing |
| Companies Covered | Toray Industries, Inc., Asahi Kasei Corporation, Teijin Limited, Mitsubishi Chemical Corporation, Ahlstrom-Munksjo, Donaldson Company, Inc., Kuraray Co., Ltd., Japan Vilene Company, Ltd., Shenzhen Nanotech Port Co., Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Nanofiber Market Strategic Shifts
Functional surface chemistry and process digitization are redefining competitive differentiation beyond raw fiber diameter metrics. Regional innovation clusters now specialize by application vertical rather than generic capacity expansion.
Needleless electrospinning using rotating cylinder or wire-electrode configurations is consolidating production economics for air filtration media. Chinese industrial filter manufacturers adopt these systems to bypass nozzle clogging limitations and achieve throughput parity with meltblown alternatives. The technology is compressing capital requirements for mid-scale entrants previously blocked by precision nozzle supply constraints.
Japan's METI efficiency mandates and PMDA device approval coordination are tightening documentation requirements for nanofiber medical products. Manufacturers must now submit electrospinning process parameter traceability alongside biocompatibility data. High-performance wound care segments in the Kansai corridor are responding by integrating quality management systems directly into production line control architecture.
Buyer consolidation among Chinese automotive battery producers is compressing supplier qualification cycles for nanofiber separator materials. Cell makers now demand combined mechanical and electrochemical performance guarantees rather than component-level specifications. This behavioral shift is most visible in the Yangtze River Delta, where CATL and BYD procurement teams enforce single-source accountability for separator failure modes.
Asia-Pacific Nanofiber Market Segmentation
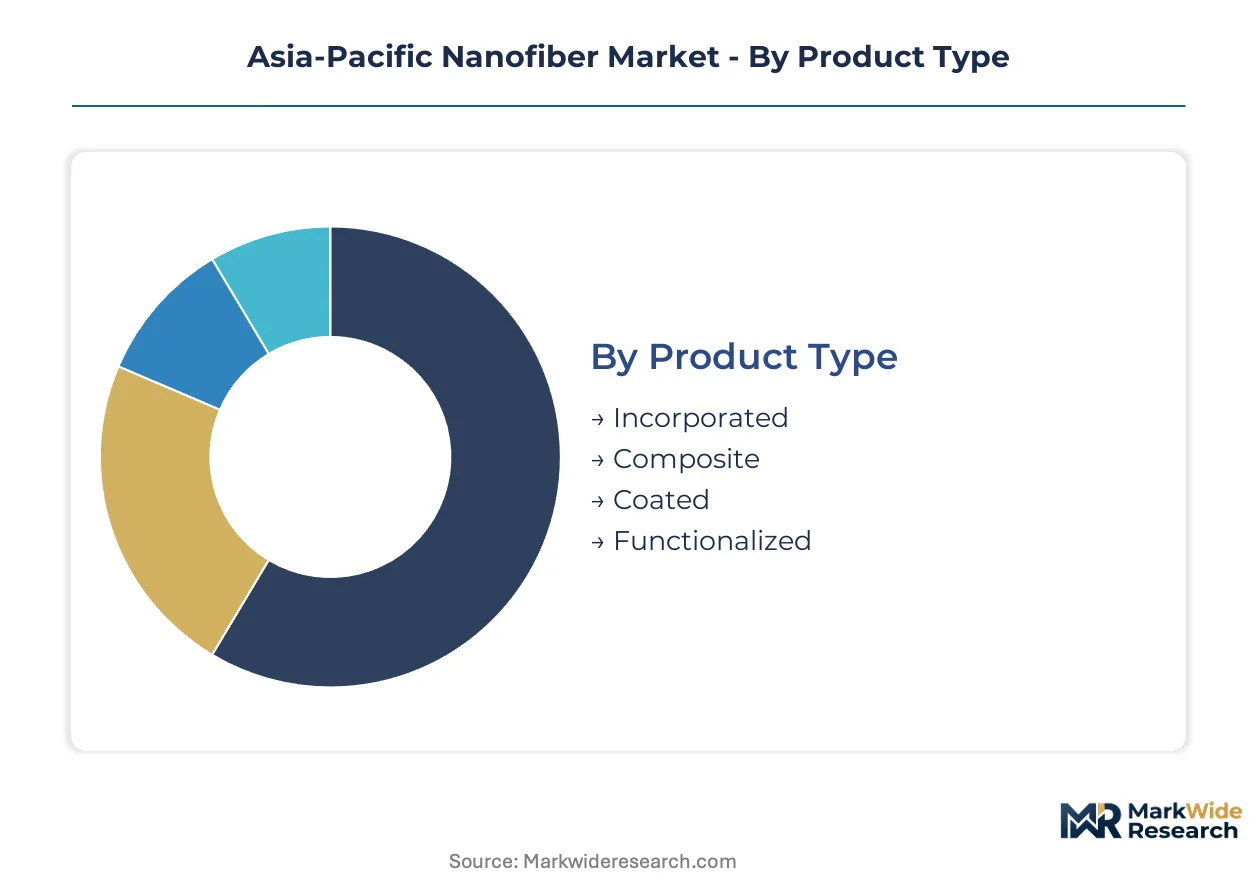
Segmentation in the Asia-Pacific nanofiber market reflects divergent technical requirements across medical device approvals, industrial filtration mandates, and battery separator specifications. Each category maps to distinct certification pathways and polymer feedstock strategies that determine supplier positioning.
Product Type:
Standardization dominates commodity grades while functionalized variants command customization premiums tied to surface chemistry specifications.
- Functionalized:Surface-modified nanofibers with grafted functional groups enable targeted molecular capture and controlled drug release. Japan's PMDA fast-track pathways for functionalized wound care scaffolds concentrate demand in the Kansai medical device corridor. Leading the category by volume: Functionalized. Growing fastest: Composite.
- Composite:Polymer-ceramic or polymer-metal hybrid structures combine mechanical strength with electrochemical stability for solid-state battery separators. South Korean cell makers in the Seoul metropolitan area specify composite architectures for next-generation energy density targets.
- Coated:Post-spinning surface deposition layers add barrier properties without altering bulk fiber morphology. China's Yangtze River Delta electronics manufacturers source coated nanofibers for flexible circuit protection films.
- Incorporated:Nanofibers embedded within conventional textile or polymer matrices enhance base material performance at lower loadings. Indian textile processors in the Tiruppur cluster trial incorporated structures for breathable sportswear applications.
Functionalized grades capture premium positioning through PMDA and SAMR certification requirements that lock out unqualified competitors.
End User:
Volume concentration follows regulatory enforcement intensity rather than raw application breadth.
- Filtration:Industrial air purification media utilizing polyacrylonitrile and polyvinylidene fluoride nanofibers achieve sub-micron particulate capture efficiencies. China's MEE enforcement of dual carbon goals in the Yangtze River Delta and Pearl River Delta manufacturing belts drives replacement cycles for power plant and steel mill filtration systems. Filtration dominates volume share. Medical expands most quickly.
- Medical:Bioresorbable surgical meshes and drug delivery matrices require PMDA and MFDS biocompatibility documentation alongside electrospinning process traceability. Japan's Kansai corridor hosts concentrated demand for hernia repair and wound closure applications.
- Electronics:Battery separator films and flexible substrate coatings demand combined mechanical and electrochemical performance guarantees. Chinese automotive cell producers in Shenzhen and Ningbo enforce single-source accountability for separator failure modes.
- Textiles:Breathable waterproof membranes and antimicrobial fabrics incorporate nanofiber layers for performance apparel. South Korean sportswear brands in the Seoul-Gyeonggi region specify nanofiber-enhanced materials for premium outerwear lines.
Filtration absorbs the largest polymer volumes; medical applications generate the steepest margin expansion.
Application:
Specification complexity escalates from passive barrier functions toward active therapeutic and electrochemical roles.
- Energy Storage:Ceramic-polymer nanofiber separators for lithium-metal and solid-state batteries displace conventional polyolefin films. South Korean and Japanese cell makers advance next-generation energy density targets through tailored pore architectures and ionic conductivity optimization. Energy Storage leads by volume. Wound Care climbs fastest.
- Wound Care:Bioresorbable nanofiber dressings provide moist healing environments with controlled antimicrobial release. India's CDSCO and BIS framework development for nanofiber-based wound products creates first-mover positioning opportunities in the Mumbai-Pune pharmaceutical belt.
- Air Filtration:High-efficiency particulate arresting media for industrial and HVAC applications leverage surface-area-to-volume ratios exceeding microfibers by orders of magnitude. China's GB standard certification timelines shape factory qualification cycles for domestic filter manufacturers.
- Drug Delivery:Encapsulated therapeutic nanofibers enable localized, sustained-release pharmacokinetics. Japan's PMDA coordination with METI tightens documentation requirements for electrospinning process parameters in implantable device submissions.
Energy Storage commands the largest capital commitments; Wound Care exhibits the sharpest regulatory tailwinds.
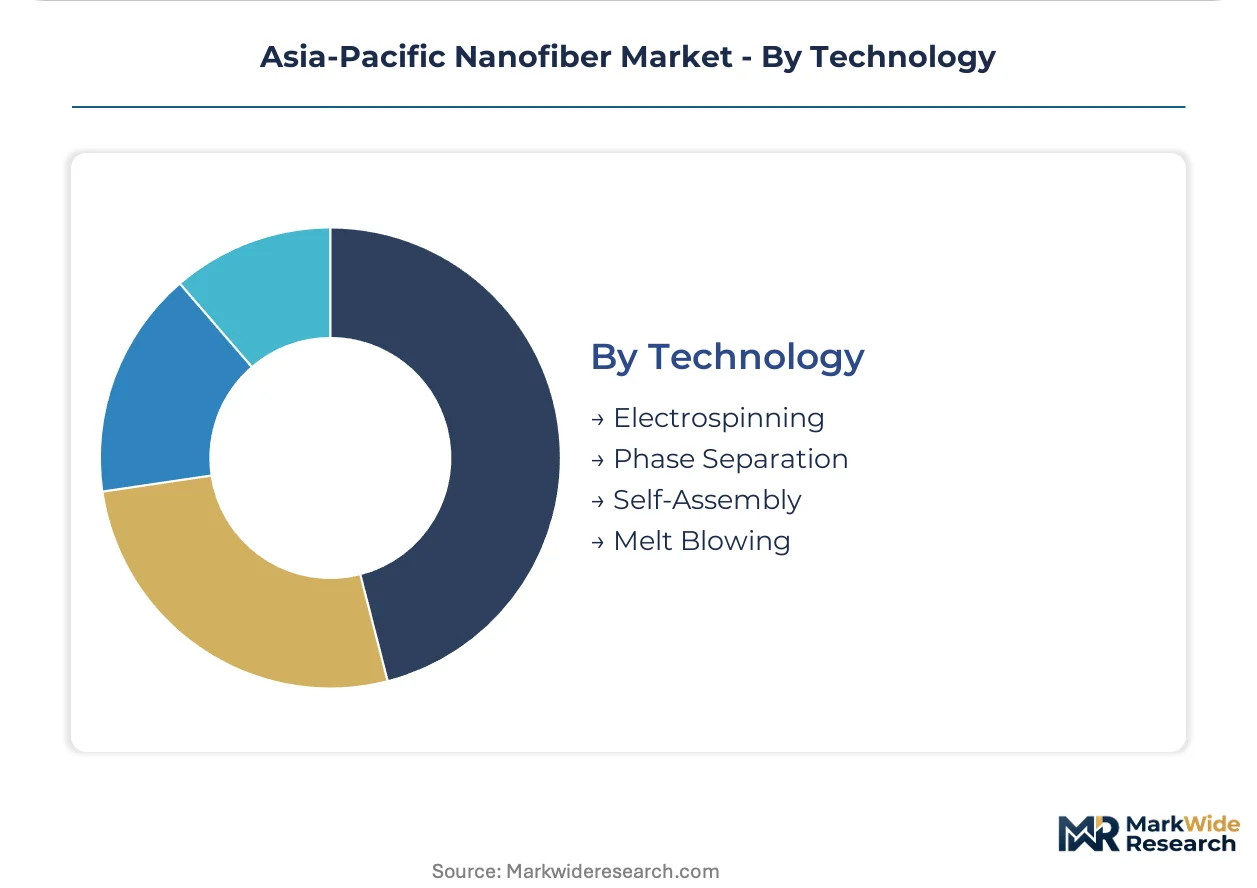
Technology:
Production scale and fiber diameter precision determine technology selection across application tiers.
- Electrospinning:High-voltage polymer jet stretching produces continuous nanofibers with diameters below 100 nanometers from diverse polymer classes. Roll-to-roll system supply concentration in Germany and Japan creates import dependency and extended lead times for Chinese and Indian producers seeking industrial scale-up. Electrospinning dominates volume. Phase Separation gains share fastest.
- Phase Separation:Thermally or chemically induced polymer demixing generates porous nanofiber structures without electrical equipment requirements. Chinese researchers in the Beijing-Tianjin-Hebei cluster advance phase separation protocols for biomedical scaffold applications.
- Melt Blowing:Extruded polymer attenuation using high-velocity hot air achieves throughput parity with conventional nonwoven production. Mid-scale Chinese filtration manufacturers adopt melt-blown nanofibers to bypass electrospinning nozzle supply constraints.
- Self-Assembly:Molecular recognition-driven fiber formation enables precise control over supramolecular architectures. Japanese academic-industry partnerships in the Tsukuba research zone explore self-assembly for targeted drug delivery applications.
Electrospinning retains process versatility leadership; Phase Separation offers the most significant capital cost reduction potential.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes the majority of nanofiber output across filtration and energy storage applications, while Japan and South Korea concentrate higher-margin medical and battery separator production. India's regulatory frameworks are still formalizing, creating timing arbitrage for early entrants.
China
Power plant retrofit cycles and steel mill air filtration upgrades drive industrial media demand under MEE enforcement of dual carbon targets. SAMR's GB nanomaterial classification standards impose 12-18 month factory certification timelines that filter supplier participation. The Yangtze River Delta manufacturing corridor hosts concentrated filter fabrication capacity serving domestic heavy industry.
Japan
Solid-state battery separator development and bioresorbable surgical mesh commercialization anchor premium-grade consumption. METI efficiency mandates coordinate with PMDA device approval pathways to tighten documentation requirements for electrospinning process traceability. The Kansai chemical cluster around Osaka maintains specialized technician pools for thin-film polymer rheology optimization.
South Korea
Automotive cell producers specify ceramic-polymer composite separators for next-generation energy density targets. MFDS governs bioresorbable surgical mesh standards alongside national battery safety regulations. Seoul metropolitan area cell makers enforce single-source accountability for separator mechanical and electrochemical performance guarantees.
India
Wound care product frameworks under CDSCO and BIS alignment create first-mover positioning for nanofiber dressing manufacturers. The national pharmaceutical infrastructure mandate accelerates quality system development for medical device entrants. The Mumbai-Pune pharmaceutical belt concentrates trial production for bioresorbable scaffolds targeting hernia repair applications.
Australia
Industrial air filtration replacement cycles follow mining and minerals processing emissions controls. TGA medical device regulations provide reference frameworks for wound care product development. Research partnerships between Melbourne universities and filtration manufacturers explore needleless electrospinning scale-up for commodity-grade media.
Asia-Pacific Nanofiber Market Competitive Environment
Top-tier vendors anchor premium functionalized grades, while mid-scale fabricators compete on cost-engineered composites for domestic supply chains. Japanese conglomerates leverage captive polymer supply chains to dominate high-performance filtration media. Chinese industrial filter manufacturers adopt needleless electrospinning to bypass precision nozzle supply constraints. Strategic moves concentrate on SAMR certification velocity and PMDA fast-track pathway access rather than raw capacity expansion.
Within the Japanese conglomerate tier, Toray Industries, Inc. and Teijin Limited exemplify integrated polymer-to-fiber positioning. Donaldson Company, Inc. represents the multinational specialist archetype with localized R&D presence. Shenzhen Nanotech Port Co., Ltd. occupies the cost-engineered composite segment serving domestic electronics supply chains.
| Leading Market Players |
|---|
| Toray Industries, Inc. |
| Asahi Kasei Corporation |
| Teijin Limited |
| Mitsubishi Chemical Corporation |
| Ahlstrom-Munksjo |
| Donaldson Company, Inc. |
| Kuraray Co., Ltd. |
| Japan Vilene Company, Ltd. |
| Shenzhen Nanotech Port Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Functionalized premium grades and commodity filtration media occupy divergent pricing strata, with PMDA fast-track certification and SAMR GB compliance creating a two-ladder system that simultaneously elevates Japanese wound care margins and compresses Chinese industrial filter returns. This bifurcation feeds directly into supply chain configuration: premium players anchor in captive polymer supply chains around Osaka, while cost-optimized producers in the Yangtze River Delta source acrylonitrile feedstock through spot-market coal-chemical channels.
Pricing Analysis
Margin tightening in standard filtration grades reflects acrylonitrile price volatility tied to crude oil and coal-chemicals indices. Pricing stratifies across PMDA-certified functionalized tiers, SAMR-compliant industrial grades, and non-certified commodity alternatives. Cost-down pressure on Chinese domestic producers accelerates because melt-blown and needleless electrospinning alternatives bypass German and Japanese precision nozzle import dependencies. Battery separator procurement teams at CATL and BYD exhibit lowest price sensitivity, while Tiruppur textile processors trial incorporated nanofibers primarily on landed cost metrics.
Supply Chain Analysis
China's dual carbon mandates and local-content preferences for SAMR-certified factory equipment are reshaping sourcing patterns toward domestic electrospinning system manufacturers. Polymer feedstock concentration rests on Chinese coal-chemical complexes, Japanese petrochemical complexes in the Kansai corridor, and South Korean refinery outputs. Single-source vulnerability concentrates in precision high-voltage power supply units and specialized nozzle arrays from German and Japanese producers. Distribution runs through direct technical service relationships for premium grades, with commodity filtration media flowing through industrial distribution channels serving power plant and steel mill procurement desks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive positioning in this market is concentrating around upstream polymer supply control and downstream certification velocity, with backward integration into specialty polymer production emerging as the decisive capability differentiator across Japanese and Chinese tiers.
For Market Incumbents: Anchor defensive positioning through captive polyacrylonitrile and polyvinylidene fluoride supply chains that insulate margin structures from feedstock volatility. Accelerate SAMR certification velocity for Yangtze River Delta manufacturing assets to preempt domestic Chinese competitors exploiting needleless electrospinning cost advantages. METI efficiency mandate alignment and PMDA process traceability documentation serve as additional moats against mid-scale entrants. For New Entrants and Emerging Players: Capture white-space positioning in India's CDSCO-aligned wound care frameworks before BIS quality infrastructure mandates fully crystallize. Target Mumbai-Pune pharmaceutical belt trial production partnerships for bioresorbable hernia repair scaffolds. Needleless electrospinning technology licensing offers a capital-efficient entry vector bypassing precision nozzle supply constraints that block conventional electrospinning scale-up. For Investors and Strategic Acquirers: Re-rating potential sits with functionalized medical-grade specialists given PMDA fast-track pathway access and METI efficiency mandate tailwinds. Long-term viability favors archetypes with demonstrated electrospinning process parameter traceability and integrated quality management systems embedded in production line control architecture. Monitor SAMR certification timeline compression as the inflection signal indicating regulatory arbitrage closure for early entrants.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Polymer Production | Captive polyacrylonitrile supply secures margin insulation against coal-chemicals price swings. |
| PMDA Fast-Track Pathway Investment | Accelerated bioresorbable surgical mesh approvals concentrate demand in Kansai corridor medical device clusters. |
| Needleless Electrospinning Technology Licensing | Bypasses German and Japanese precision nozzle import dependencies for mid-scale Chinese filtration entrants. |
| SAMR Certification Velocity Enhancement | Compresses 12-18 month factory approval cycles to preempt domestic competitor lock-in. |
| AI-Driven Process Control Integration | Machine vision fiber diameter monitoring enables lot-to-lot consistency premiums in battery separator supply. |
Study Parameters
Trade statistics, SEC filings from listed filtration and chemical conglomerates, and SAMR nanomaterial classification protocols formed the secondary backbone for demand quantification. Primary interviews with electrospinning equipment operators, polymer procurement leads at filter manufacturers, PMDA regulatory consultants, and CDSCO medical device officers validated secondary findings. Bottom-up polymer consumption estimates and top-down filtration media revenue triangulation anchored market sizing across the analysis window.
Historical trendline analysis of electrospinning capacity additions, acrylonitrile price indices, and certification timeline data informed projection mechanics. Segmentation modeling spanned product type tiers, end-use verticals, application specifications, and technology categories. CAGRs derived from fitted trend extrapolation adjusted for regulatory enforcement intensity and buyer consolidation patterns among automotive cell producers. Solid-state battery separator adoption curves and MEE air filtration mandate implementation schedules served as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to acrylonitrile feedstock volatility, SAMR certification protocol revisions, and PMDA-METI coordination changes. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fibers
High Performance Fibers for Defense Market
Fibers
Keratin Market
Fibers
Polytetrahydrofuran Market
Fibers
Carbon Fiber Wrap Market
Fibers
Global Metal Fiber Market
Fibers
Global R-Glass Fiber Market
Fibers
Asia-Pacific Carbon Fiber Market
Fibers
Global Polyvinyl Alcohol Fiber Market
Fibers
Global Nylon Monofilament Market
Fibers
North America Optical Fiber Raw Material Market
Fibers
Basalt Continuous Fiber (BCF) Market
Fibers
Global Fiber Reinforced Composites Market
Fibers
Natural Fiber Reinforcement Materials Market
Fibers
Bleached Linter Cellulose Market
Fibers
Precision Fiber Molding Market
Fibers
Viscose Market