
 Firewood Processors Market | 2026-2036
Firewood Processors Market Size, Share, and Industry Trends Forecast 2026-2036
Firewood Processors Market Analysis
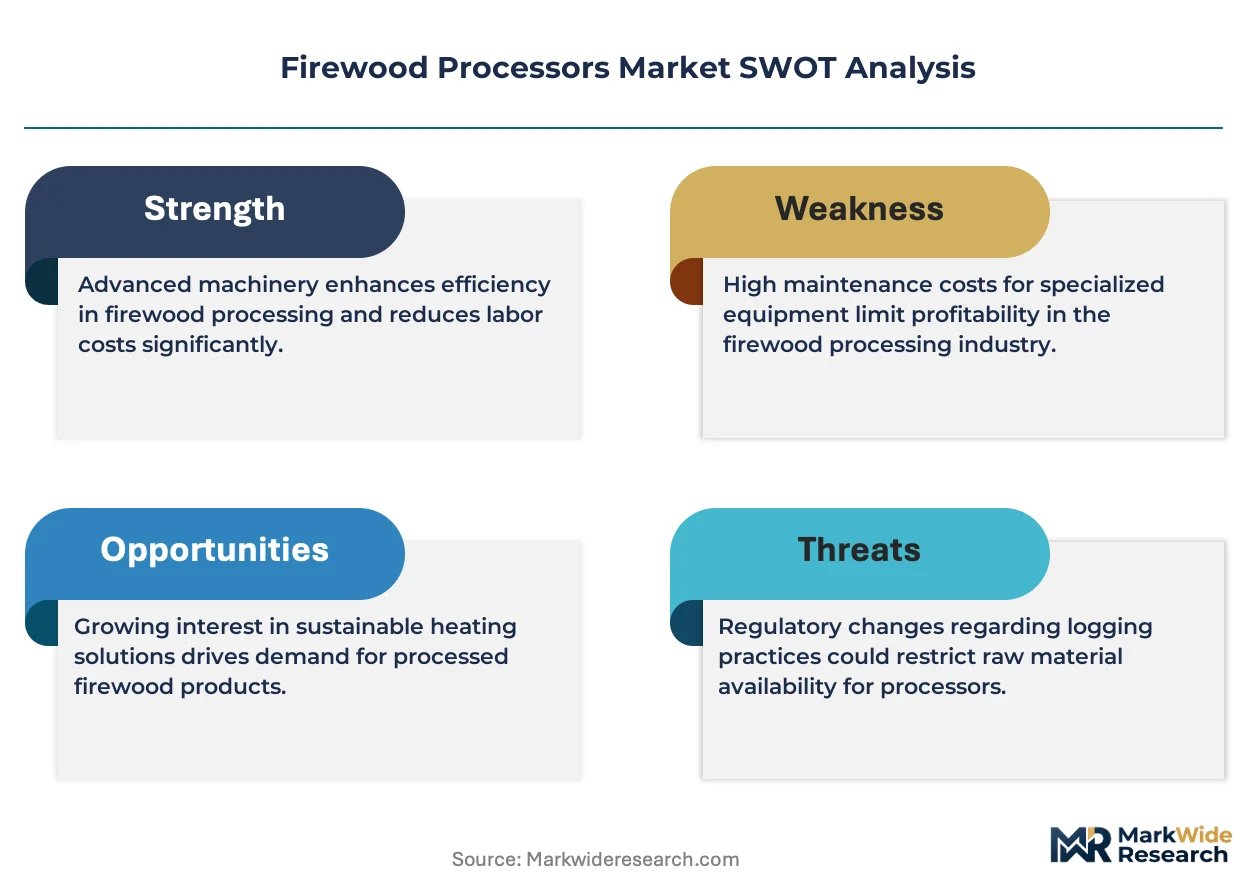
Multi-source component procurement is expanding across the firewood processor supply chain as manufacturers hedge against engine and hydraulic system volatility. Blockbuster Firewood Processors leverages captive fabrication to control lead times on cutting assemblies. Cord King sustains its position through concentrated R&D in high-cycle splitting mechanisms. Timberwolf Equipment anchors its competitive stance with deep distribution across North American farm and ranch channels.
Firewood processors are mechanical systems that combine log infeed, cutting, splitting, and outfeed functions to convert raw timber into stove-ready fuel, typically processing diameters from 6 to 24 inches through hydraulic or kinetic splitting force. These machines serve commercial firewood yards, forestry operations, and residential estates where manual splitting proves uneconomical at volume. Mobile processors lead equipment deployment for remote logging sites and seasonal contractors requiring field portability. Diesel power source configurations command the premium segment due to torque density and runtime endurance in continuous-duty commercial settings. Small-size residential units remain the most mature category with price-driven competition and thinner margin pools.
EPA Phase 3 emissions regulations for non-road spark-ignition engines constrain gasoline-powered processor designs and elevate compliance costs for manufacturers serving the US market. OSHA machine guarding standards and CE marking requirements in Europe shape safety system architecture and limit market access for uncertified producers. Buyers and fleet operators must monitor power train electrification timelines and regional emissions enforcement intensity when committing to capital equipment replacement cycles.
Market Dynamics
EPA Phase 3 emissions standards for small spark-ignition engines are compressing gasoline-powered processor viability and forcing rapid power train diversification across the supply base. This regulatory pressure intersects with hydraulic component volatility to create a dual squeeze on mid-tier manufacturers lacking captive engine sourcing or electrification roadmaps.
Growth Catalysts
- Residential wood heating demand:Cold-climate zones in the United States, particularly the Northeast and Upper Midwest, sustain replacement cycles for automated splitting equipment as energy cost volatility drives fuel diversification.
- OSHA machine guarding standards:Stricter safety enforcement elevates certified equipment preference and filters uncertified imports from the commercial fleet channel.
- Diesel torque density:Continuous-duty commercial yards favor diesel configurations for runtime endurance, anchoring premium segment pricing power.
Market Restraints
- Gasoline engine compliance costs:EPA Phase 3 certification expenses disproportionately burden small-format residential manufacturers with thinner margin pools.
- Hydraulic system supply concentration:Dependence on concentrated European and Asian hydraulic component suppliers exposes lead time volatility during demand spikes.
- Manual splitting substitution:Low-volume residential users in temperate zones retain manual methods, capping penetration in marginal heating climates.
Strategic Opportunities
- Electric power train white space:Battery-electric configurations for sub-15-horsepower residential units remain underdeveloped relative to commercial diesel electrification timelines.
- Seasonal contractor rental channels:Mobile processor deployment through farm and ranch equipment rental networks addresses capital constraint among intermittent users.
- CE marking expansion:European safety certification creates access path for compliant manufacturers into forestry contractor fleets across Germany, Sweden, and Finland.
Industry Challenges
- Electrification skill gap:Field service technician pools lack battery-electric power train diagnostics training, constraining aftermarket support for early electric deployments.
- Multi-certification timeline compression:Simultaneous EPA, OSHA, and CE compliance creates engineering bandwidth bottlenecks for mid-cap manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Firewood Processors Market |
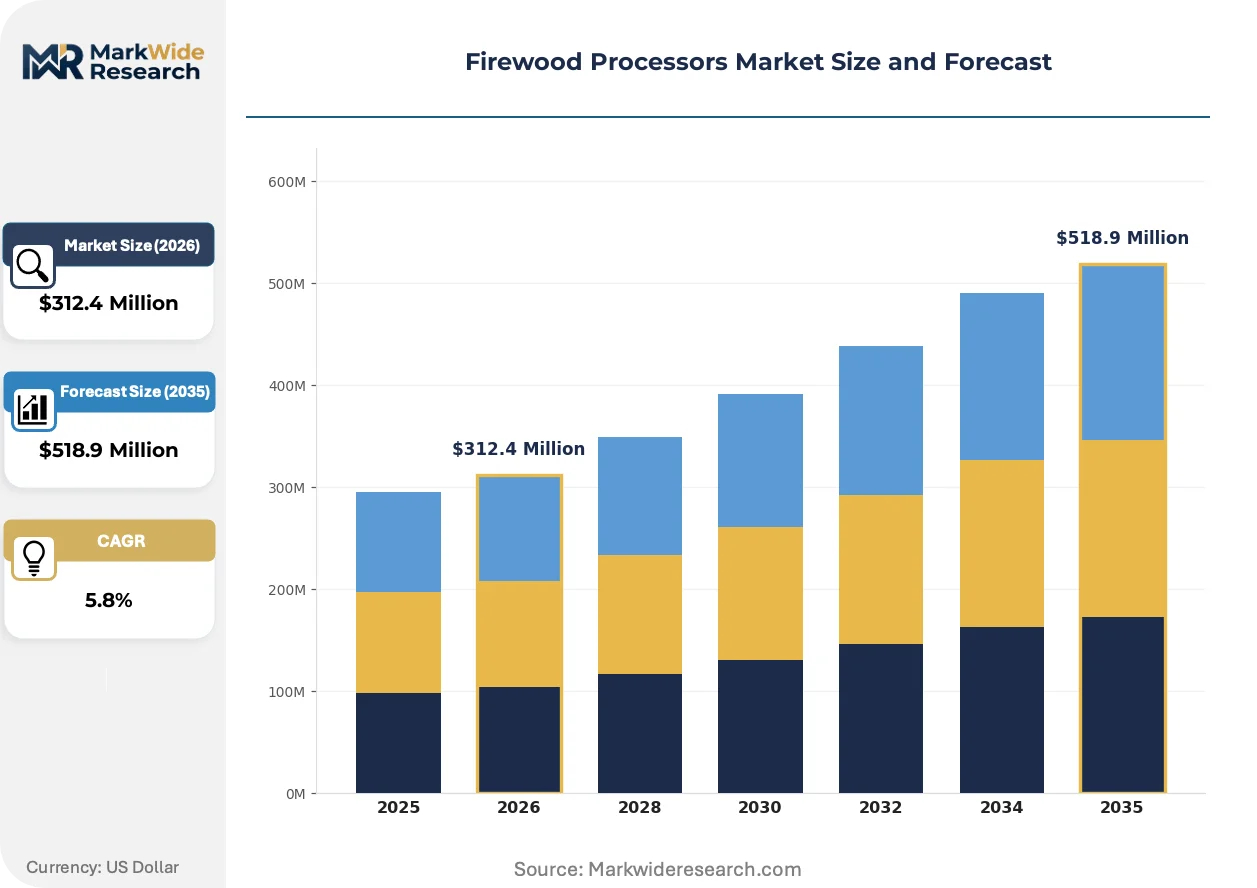
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stationary Processors, Mobile Processors, Manual Splitters, Automatic Splitters Size: Small, Medium, Large, Extra Large Application: Residential, Commercial, Industrial, Forestry Power Source: Gasoline, Diesel, Electric, Hybrid |
| Companies Covered | BruteForce USA, Doosan Industrial Vehicle Company, Blockbuster Firewood Processors, Kohler Company, Briggs and Stratton, Cord King, Hatz Diesel Engines, Vanguard Power Equipment, Timberwolf Equipment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Firewood Processors Market Emerging Trajectories
Kinetic splitting mechanisms are gaining engineering attention as alternatives to hydraulic force delivery, promising cycle time compression without fluid system maintenance burden. This mechanical innovation intersects with power train electrification to reshape equipment architecture across residential and commercial tiers.
Kinetic flywheel systems accumulate rotational energy for rapid ram deployment, cutting split cycles to under three seconds for softwood diameters below twelve inches. Rural estate owners and small commercial yards in the United States are piloting these configurations for mixed-hardwood operations. The technology is expanding into mid-duty commercial segments previously dominated by conventional hydraulic rams, compressing the performance gap between entry and premium tiers.
EPA Phase 3 emissions regulations for non-road spark-ignition engines now constrain gasoline-powered processor designs with evaporative emission controls and catalytic converter mandates. Manufacturers serving the United States market face elevated certification costs and shortened product lifecycles for carbureted engines. Diesel and electric alternatives capture displaced engineering resources, with commercial fleet operators accelerating diesel replacement timelines to preempt gasoline model phase-outs.
Equipment-as-a-service arrangements are emerging among seasonal contractors seeking to avoid capital deployment for intermittent firewood production. Regional rental cooperatives and farm supply chains in the Upper Midwest are bundling mobile processors with maintenance and haulage logistics. This consumption pattern shift concentrates fleet ownership among capitalized distributors while fragmenting end-user purchase decisions across sporadic rental transactions.
Firewood Processors Market Segmentation
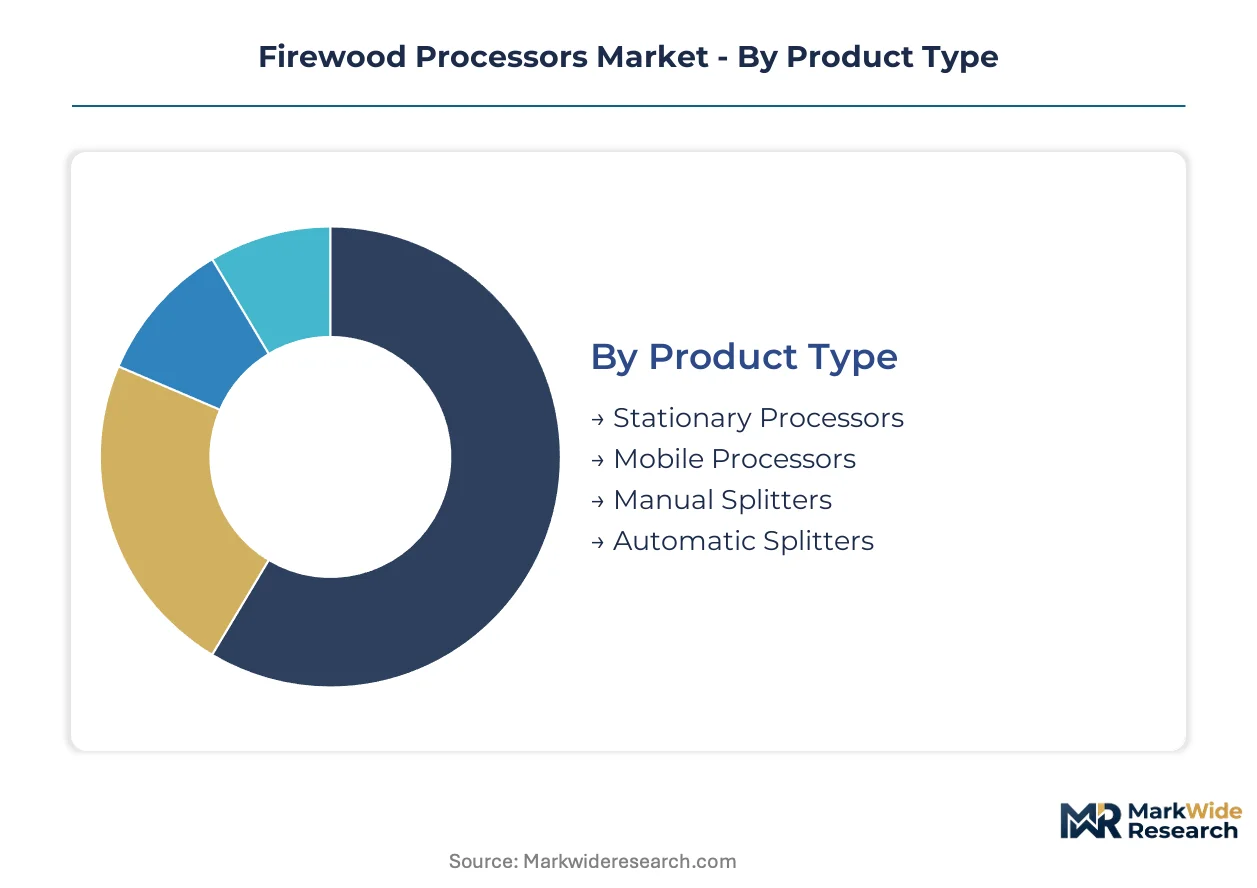
Firewood processor buyers sort equipment across four distinct classification schemes. Each dimension captures different trade-offs between capital outlay, operational intensity, and regulatory exposure.
Product Type:
Volume processors dominate commercial yards while premium mobility commands rental premiums.
- Stationary Processors:Fixed-base hydraulic systems with integrated infeed decks and conveyor outfeeds. Demand concentrates in commercial firewood yards across Maine and Wisconsin where throughput economics justify permanent installation.
- Mobile Processors:Trailer-mounted or skid-steer compatible units with folding conveyors and road-legal towing configurations. Seasonal contractors in Vermont and Minnesota deploy these for remote logging sites and estate clearing contracts.
- Manual Splitters:Foot-pedal or hand-operated hydraulic rams for low-volume residential use.
- Automatic Splitters:Programmable cycle systems with log length sensing and multi-way wedge indexing.
Mature deployment sits with stationary processors. Newer deployment is concentrated in mobile processors.
Size:
Commercial buyers optimize for log diameter capacity while residential buyers prioritize storage footprint.
- Small:Units processing logs under 10 inches diameter with sub-20-ton splitting force. Northeastern residential estates purchase these for supplemental heating fuel production where manual splitting proves impractical.
- Medium:10-16 inch capacity with 20-30 ton force and gasoline or electric power options. Rural property owners in Michigan and Pennsylvania favor this tier for mixed hardwood operations.
- Large:16-22 inch capacity with 30-50 ton force and diesel or PTO configurations.
- Extra Large:22+ inch capacity with 50+ ton force and continuous infeed systems for commercial pulpwood conversion.
Margins compress most severely in small units. Extra large systems retain pricing power through limited supplier base.
Application:
End-use differentiation determines safety certification requirements and financing availability.
- Residential:Homeowners and rural estate operators processing fuel for personal consumption. EPA gasoline engine restrictions and OSHA guarding mandates filter uncertified imports from this channel.
- Commercial:Firewood yards and landscaping contractors selling processed fuel to retail and wholesale accounts. Diesel configurations anchor this segment due to runtime endurance during peak heating season.
- Industrial:Biomass processors and pallet manufacturers converting waste streams to fuel.
- Forestry:Logging contractors and land management agencies producing roadside fuel from harvest residuals.
Commercial application absorbs the steepest expansion trajectory as energy cost volatility drives fuel diversification. Industrial application remains supply-constrained by feedstock logistics.
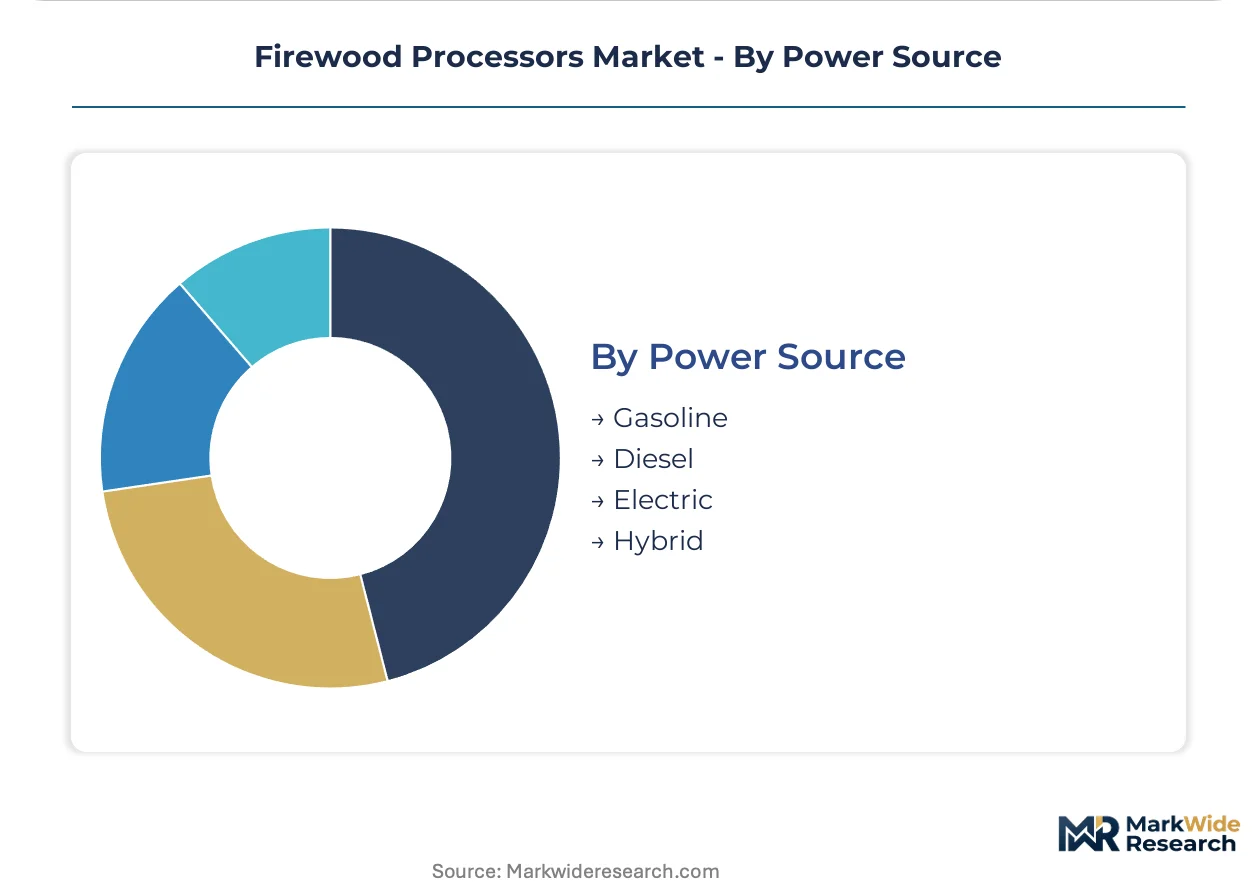
Power Source:
Regulatory pressure on gasoline engines is accelerating technology transition across all size tiers.
- Gasoline:Carbureted and fuel-injected spark-ignition engines under 25 horsepower. EPA Phase 3 evaporative emission controls and catalytic converter mandates elevate compliance costs for manufacturers serving US market.
- Diesel:Compression-ignition engines with torque density advantages for continuous-duty splitting cycles. Commercial fleet operators in Minnesota and Wisconsin accelerate diesel replacement timelines to preempt gasoline model phase-outs.
- Electric:Battery-electric and corded configurations for sub-15 horsepower residential units.
- Hybrid:Dual power train systems with electric splitting and diesel or gasoline auxiliary generation.
Gasoline retains installed base dominance. Electric configurations are gaining share fastest in residential sub-segments where runtime demands remain modest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hardwood forest belts in the United States Northeast and Upper Midwest anchor regional demand for automated splitting equipment, while European coniferous zones and Canadian boreal forests sustain parallel procurement cycles across distinct regulatory environments.
United States
Rural estates in Vermont and Maine drive residential replacement cycles as heating oil price volatility accelerates fuel diversification. EPA Phase 3 emissions standards for non-road spark-ignition engines constrain gasoline-powered processor designs with catalytic converter mandates. Wisconsin commercial yards concentrate diesel configuration demand where continuous-duty runtime economics justify premium capital outlay.
Canada
Boreal logging contractors in Ontario and Quebec deploy mobile processors for roadside fuel production from harvest residuals. Health Canada and PMRA coordinate machinery safety standards with provincial occupational regulators. British Columbia forestry operations favor trailer-mounted units for remote site access during seasonal clearing contracts.
Germany
Forestry contractors in Bavaria and Baden-Württemberg sustain demand for CE-certified equipment meeting EU machinery directives. REACH chemical regulations and F-Gas standards shape hydraulic fluid specifications and component sourcing. The Black Forest region anchors commercial processor deployment for mixed-hardwood fuel production serving regional heating cooperatives.
Sweden
District heating networks in Stockholm County and Västra Götaland create institutional demand for processed biomass fuel. The country's national environmental protection agency enforces strict particulate standards for combustion equipment. Småland forestry clusters concentrate processor manufacturing and field service technician training for Nordic export markets.
Finland
Lake District logging cooperatives process softwood residuals for combined heat and power plants. METI-aligned efficiency standards drive equipment replacement toward higher-throughput configurations. Tampere industrial zones host hydraulic component suppliers serving regional processor fabricators with integrated system architectures.
Firewood Processors Market Vendor Landscape
Technology licensing dominates the current landscape as mid-tier manufacturers seek electrification capabilities without captive R&D investment. The vendor base stratifies across three tiers: integrated engine-hydraulic system suppliers, specialized processor fabricators, and regional assembly houses sourcing commodity components. Two strategic archetypes anchor competitive positioning: torque-density specialists optimizing diesel configurations for commercial duty cycles, and mobility-focused engineers compressing deployment logistics for seasonal contractors. M&A activity concentrates among hydraulic component suppliers seeking backward integration into cutting assemblies, while strategic partnerships proliferate between engine manufacturers and processor OEMs navigating EPA compliance timelines.
Among North American fabricators, Blockbuster Firewood Processors and Cord King occupy positions within the specialized processor tier, with Timberwolf Equipment anchoring the distribution-intensive archetype across farm and ranch channels. Engine suppliers including Kohler Company and Briggs and Stratton represent the power train concentration layer that constrains design flexibility for downstream equipment builders. European diesel specialists such as Hatz Diesel Engines exemplify the torque-density optimization path, while Doosan Industrial Vehicle Company sits within the industrial conglomerate structure capable of vertical integration across component categories. BruteForce USA and Vanguard Power Equipment represent regional assembly competitiveness in price-sensitive residential segments.
| Leading Market Players |
|---|
| BruteForce USA |
| Doosan Industrial Vehicle Company |
| Blockbuster Firewood Processors |
| Kohler Company |
| Briggs and Stratton |
| Cord King |
| Hatz Diesel Engines |
| Vanguard Power Equipment |
| Timberwolf Equipment |
| Others |
Supply Flow & Price Mechanics
Captive engine sourcing by integrated manufacturers anchors both supply security and pricing power in the firewood processor market, insulating premium diesel configurations from hydraulic component volatility while forcing mid-tier fabricators into exposed cost positions.
Pricing Analysis
Warranty and field service bundling separates premium diesel configurations from unbundled gasoline alternatives, with commercial yards in Wisconsin and Minnesota absorbing higher upfront capital for comprehensive maintenance coverage. Three-tier pricing structure across premium, standard, and economy levels reflects EPA certification grade, torque density specifications, and regional delivery logistics. Cost compression in small-format residential units intensifies because gasoline engine compliance expenses disproportionately burden thin-margin manufacturers. Price sensitivity concentrates among seasonal contractors in Vermont, while continuous-duty commercial operators in Maine exhibit lowest elasticity due to runtime economics.
Supply Chain Analysis
Dual-sourcing mandates from commercial fleet operators in the Upper Midwest force processor fabricators to qualify hydraulic component suppliers across Germany, Japan, and the United States. Manufacturing draws from concentrated European and Asian hydraulic system suppliers, diesel engine specialists in Germany and Japan, and North American steel fabrication. Single-source vulnerability in high-pressure hydraulic pumps exposes lead time volatility during Q4 demand spikes. Distribution runs through farm and ranch equipment cooperatives, regional rental networks, and direct OEM relationships with commercial yards.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA Phase 3 compliance costs are compressing weaker gasoline-dependent manufacturers toward exit, consolidating procurement influence among diesel-integrated incumbents with captive power train capabilities.
For Market Incumbents: To counter electrification skill gaps constraining aftermarket support, deepen technician training partnerships with community colleges in forestry clusters and anchor channel control through exclusive service agreements with Upper Midwest rental cooperatives. For New Entrants and Emerging Players: Begin with battery-electric configurations for sub-15-horsepower residential units in Northeastern states, exploiting white space where runtime demands remain modest and EPA gasoline restrictions filter established competitors. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by industrial conglomerates seeking hydraulic system backward integration; hydraulic component suppliers with cutting assembly capabilities represent the priority target archetype. Watch electrification roadmap announcements from engine manufacturers as the inflection signal for power train transition velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Electrification Roadmap Investment | Battery-electric configurations for residential tiers capture EPA-driven gasoline displacement in Vermont and Maine. |
| Technician Training Partnership | Community college alliances in Wisconsin address field service gaps constraining early electric deployments. |
| CE Marking Certification | EU machinery directive compliance opens forestry contractor channels in Bavaria and Baden-Württemberg. |
| Rental Cooperative Integration | Exclusive service agreements with farm supply chains lock seasonal contractor demand in Minnesota. |
| Kinetic Splitting R&D | Flywheel cycle compression without hydraulic maintenance burden reshapes mid-duty commercial tiers. |
Methodological Framework
Independent corroboration across equipment fabricator executives, hydraulic component procurement leads, commercial yard operators, and regional rental cooperative managers underwrites the qualitative findings. Primary fieldwork combined maintenance directors at forestry operations, aftermarket service heads at distributor networks, and OEM engineering leads with secondary validation through EPA certification databases, OSHA machine guarding standards filings, and customs trade records for hydraulic system imports. Bottom-up unit economics triangulate against top-down market sizing across power source, size tier, and application segments.
Comparable historical reference periods anchored the projection horizon to replacement cycle patterns in cold-climate heating markets. The analytical framework models demand across product type, size classification, end-use application, and power source configuration, with regional regulatory enforcement intensity as an overlay dimension. CAGRs derive from installed base turnover rates, energy cost volatility indices, and emissions compliance timeline acceleration. Forecast inputs include heating oil price differentials, EPA enforcement intensity scoring, and electrification readiness assessments by state.
Underlying measurement precision varies by segment; commercial diesel configurations carry tighter precision than emerging electric alternatives due to established replacement cycle documentation. Forecasts reflect assumptions about regulatory enforcement continuity, heating fuel price relationships, and hydraulic component supply stability. Deviation in EPA Phase 3 implementation timing or electrification subsidy programs would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Global Lifting Columns Market
Material Handling Equipment
Heavy Duty Ramp Market
Material Handling Equipment
Drum Dumper Market
Material Handling Equipment
Heavy Loader Market
Material Handling Equipment
Linear Slides Market
Material Handling Equipment
Dry Bulk Handling System Market
Material Handling Equipment
Rubber Tyre Gantry Crane Market
Material Handling Equipment
East Africa Elevator and Escalator Market
Material Handling Equipment
Bridge Cable Sockets Market
Material Handling Equipment
Circular Stacker and Reclaimer Market
Material Handling Equipment
Reach Stacker Market
Material Handling Equipment
Water Hose Market
Material Handling Equipment
Hydraulic Hoist Market
Material Handling Equipment
Robotic Palletizers and De-Palletizers Market
Material Handling Equipment
Global Hydraulic Equipment Market
Material Handling Equipment
Japan Conveyor Belt Market