
 Asia-Pacific Drilling Waste Management Services Market | 2026-2036
Asia-Pacific Drilling Waste Management Services Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Drilling Waste Management Services Market Outlook
Synthetic-based drilling fluids are displacing diesel-based formulations across offshore Australia, and this substitution is realigning treatment economics toward thermal and biological processing units. Halliburton Company leverages its integrated well construction portfolio to bundle waste management with drilling contracts across Southeast Asian basins. Schlumberger Ltd anchors its position through proprietary closed-loop systems that cut discharge volumes at deepwater sites.
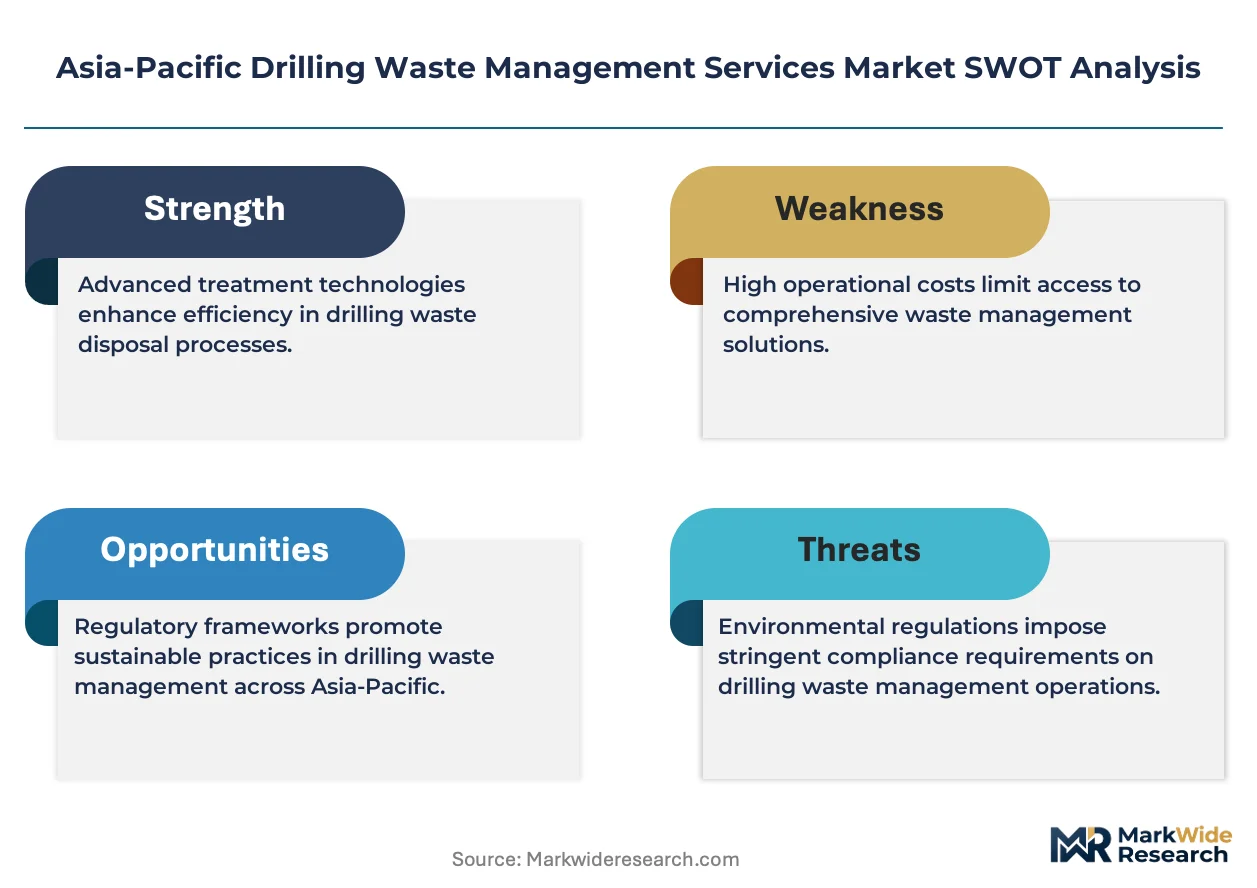
Asia-Pacific drilling waste management services encompass the containment, treatment, and disposal of solids and liquids generated during borehole construction, with thermal treatment systems typically operating at 450–600°C to separate hydrocarbons from drill cuttings for reuse or safe landfill. Oil-based waste streams command the highest treatment intensity due to residual hydrocarbon content that exceeds MEE discharge thresholds. Recycling services now outpace disposal in revenue growth as operators seek to reclaim base fluids and reduce logistics costs. Thermal treatment technology leads capital deployment in Australia's offshore sector where space constraints on platforms favor compact, high-throughput units.
China's MEE enforces stricter marine discharge limits while Australia's NOPSEMA mandates oil-on-cuttings below 1% for seabed disposal, forcing operators to upgrade from basic solidification to chemical and thermal processing. India's CEA coastal zone rules add compliance layers for eastern seaboard drilling campaigns. Stakeholders must weigh capital intensity against regulatory trajectory when selecting between mobile treatment units and permanent shore-base infrastructure.
Market Dynamics
Offshore operators across Southeast Asian basins face mounting pressure to eliminate ocean discharge entirely, forcing a wholesale shift from marine dumping to shore-based thermal and biological processing infrastructure.
Growth Catalysts
- MEE discharge standards:China's Ministry of Ecology and Environment mandates stricter marine discharge limits for drilling operations, compelling operators to upgrade waste treatment capacity at Bohai Bay and South China Sea facilities.
- Deepwater exploration:Australia's Northwest Shelf and Timor Sea developments generate oil-based cuttings volumes that exceed on-site storage capacity, driving demand for high-throughput thermal treatment units.
- Base fluid reclamation:Synthetic-based drilling muds enable hydrocarbon recovery rates above 90 percent through thermal desorption, cutting logistics costs for remote offshore platforms.
Market Restraints
- Capital intensity:Mobile thermal treatment units require diesel generators and specialized vessel chartering, with daily operating costs exceeding shore-base alternatives by 40-60 percent in Australian waters.
- Skilled technician scarcity:Certified thermal desorption operators concentrate in Perth and Singapore, creating bottlenecks for rapid deployment across Indonesia's frontier basins.
- Permitting timelines:India's CEA coastal zone regulations impose multi-layer approval processes for shore-base construction, delaying project commissioning by 12-18 months.
Strategic Opportunities
- Vietnam's offshore licensing round:New production sharing contracts in the Cuu Long and Nam Con Son basins will generate drilling waste volumes requiring treatment infrastructure currently absent from the domestic market.
- Closed-loop system integration:Convergence of real-time drilling data with automated waste segregation enables predictive treatment scheduling, reducing platform storage requirements.
- Bioremediation services:Microbial hydrocarbon degradation offers lower-energy alternatives for land-based drill cuttings disposal, qualifying for carbon credit offsets under Australia's safeguard mechanism.
Industry Challenges
- Certification fragmentation:NOPSEMA, MEE, and CEA maintain divergent oil-on-cuttings testing protocols, forcing service providers to maintain multiple laboratory accreditation streams.
- Platform space constraints:Legacy offshore installations lack deck load capacity for thermal treatment skids, requiring modular unit design or costly structural reinforcement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Drilling Waste Management Services Market |
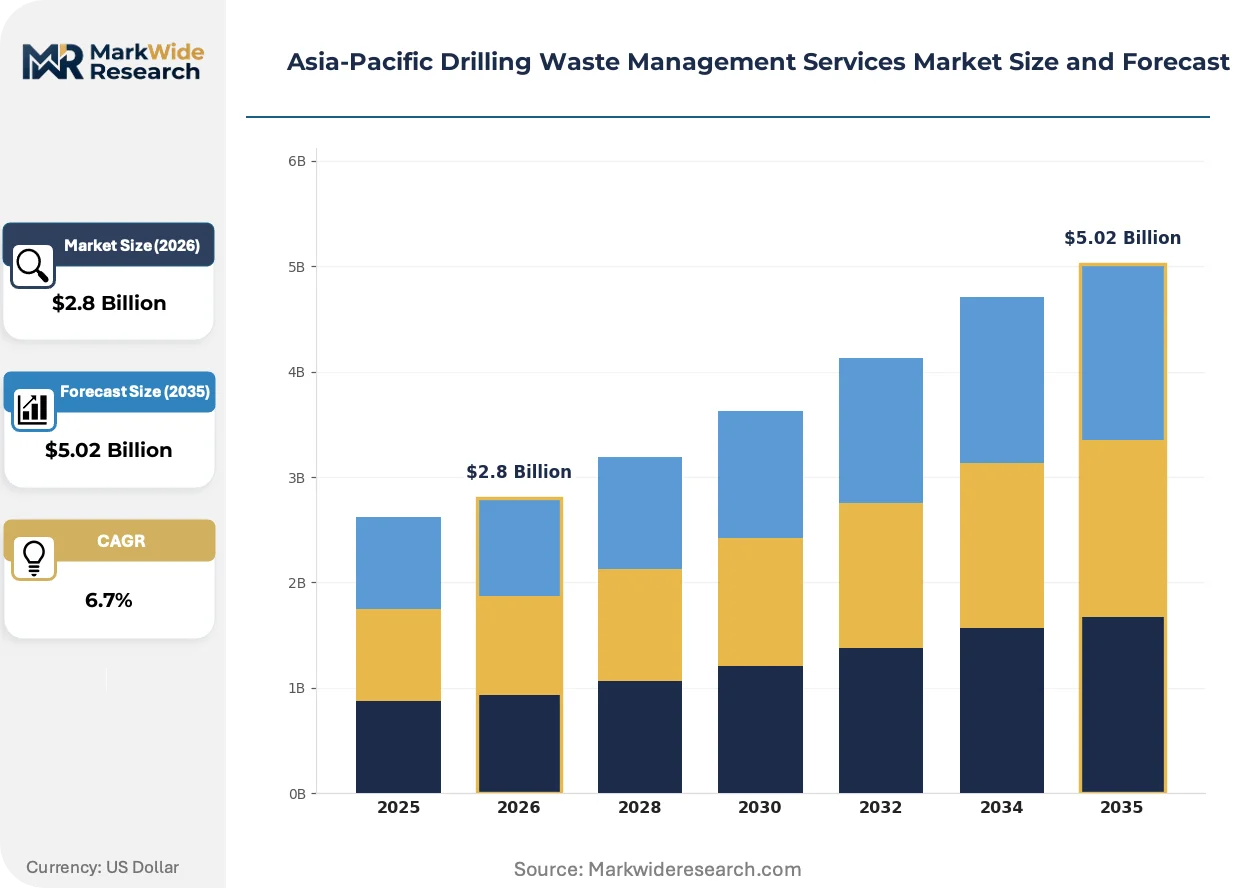
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
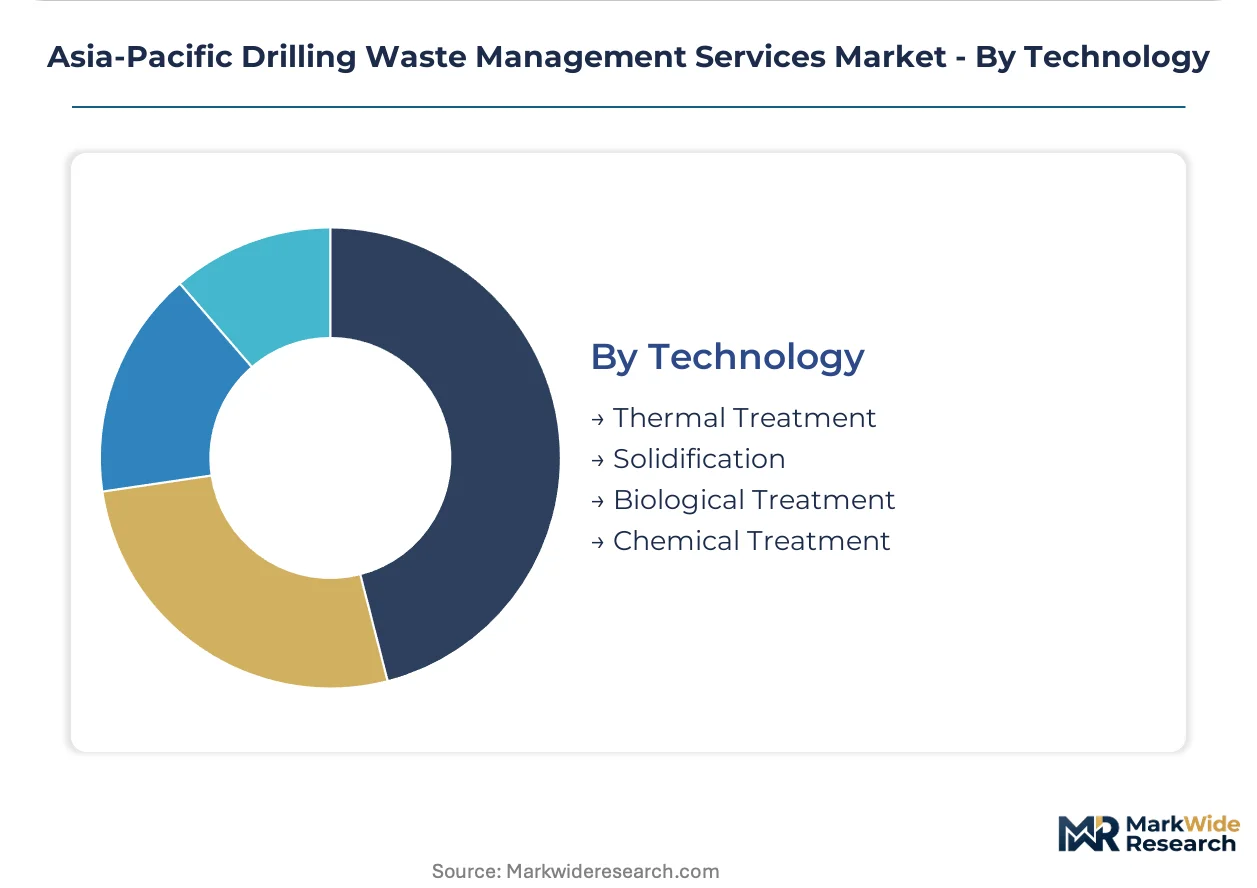
| Segmentation | Waste Type: Drill Cuttings, Mud, Fluids, Oil-Based Waste Service Type: Disposal, Treatment, Recycling, Collection End User: Oil & Gas Companies, Service Providers, Regulatory Agencies, Contractors Technology: Thermal Treatment, Solidification, Biological Treatment, Chemical Treatment |
| Companies Covered | Schlumberger Ltd, Halliburton Company, Baker Hughes Company, Weatherford International plc, China Oilfield Services Ltd, National Oilwell Varco, Inc., Veolia Environnement S.A., Scomi Group Bhd, Nuverra Environmental Solutions, Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Drilling Waste Management Services Market Strategic Shifts
Technology providers are compressing treatment footprints while regulators tighten discharge thresholds, creating a race between compliance mandates and equipment miniaturization across Asia-Pacific offshore basins.
Electro-thermal desorption units operating at 550-650°C are expanding into Australia's floating production facilities where deck space limitations previously precluded on-site treatment. Woodside Energy and Santos have piloted containerized systems on the Scarborough and Barossa developments, cutting cuttings transport volumes by 70 percent. The technology is expanding into service contract structures that bundle treatment fees per meter drilled rather than per-tonne disposal rates.
Australia's NOPSEMA has revised seabed disposal thresholds from 6.9 percent oil-on-cuttings to 1 percent for new field developments, rendering traditional solidification techniques non-compliant. This industrial consequence forces operators to pre-treat all oil-based waste streams before marine discharge or complete shipment to shore-base facilities. Deepwater projects in the Browse Basin face the steepest compliance burden, with some developments budgeting 15-20 percent of drilling AFE for waste management infrastructure.
Integrated service contracts now dominate procurement patterns in Southeast Asian markets, with national oil companies bundling waste management into integrated drilling packages rather than awarding standalone treatment tenders. Petronas and Pertamina have shifted to single-point accountability models where drilling contractors assume full waste liability. This channel consolidation is most visible in Malaysia's Sarawak waters, where Petronas Carigali has eliminated discrete waste service awards since 2022.
Asia-Pacific Drilling Waste Management Services Market Segmentation
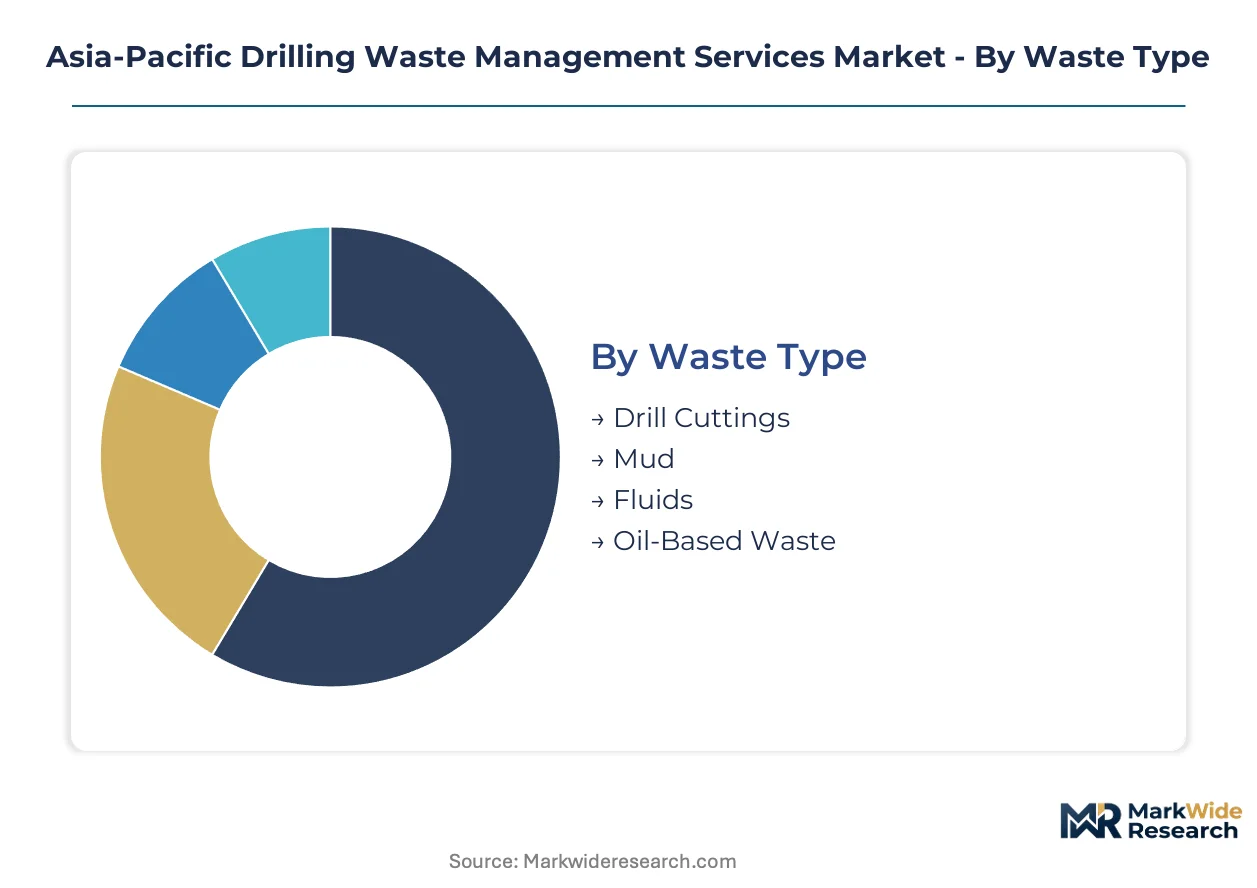
Segmentation reveals how regulatory pressure and offshore logistics reshape service procurement across the Asia-Pacific basin. Each dimension exposes distinct margin structures and capital deployment patterns that diverge sharply from onshore markets.
Waste Type:
Supply concentration tilts toward oil-contaminated streams where treatment complexity creates pricing power for specialized operators.
- Oil-Based Waste:Residual hydrocarbon content exceeding MEE discharge thresholds demands thermal or chemical processing before any marine release. Australia's Northwest Shelf developments generate volumes that exhaust on-platform storage, forcing continuous shore-base shipment.
- Drill Cuttings:Solid-laden slurries dominate physical mass flows from deepwater campaigns in the Timor Sea and South China Sea. NOPSEMA's tightened oil-on-cuttings limits to 1 percent render basic solidification non-compliant for new field developments.
- Mud:Water-based and synthetic formulations require segregation at source to protect base fluid recovery economics.
- Fluids:Spent drilling and completion fluids carry dissolved solids and chemical additives that complicate discharge permitting.
Oil-Based Waste absorbs the bulk of installed capacity; Drill Cuttings is expanding most quickly.
Service Type:
Cost tier differentiation separates commodity disposal from value-added recovery services where operators reclaim base fluids.
- Treatment:Thermal desorption units operating at 450–600°C separate hydrocarbons from solids for reuse or safe landfill. Australia's offshore platforms favor compact, high-throughput configurations given deck load constraints.
- Recycling:Base fluid reclamation from synthetic-based muds achieves recovery rates above 90 percent, cutting logistics expenditure for remote installations. Revenue growth now outpaces disposal as operators prioritize circular resource flows.
- Disposal:Landfill and seabed discharge face tightening MEE and NOPSEMA restrictions, compressing addressable volume.
- Collection:Vessel chartering and skip logistics constitute necessary but low-margin enablers of downstream treatment.
Treatment commands the capital intensity premium; Recycling is gaining share fastest.
Technology:
Application requirements vary dramatically between offshore platforms with space constraints and shore-base facilities with scale economies.
- Thermal Treatment:Electro-thermal desorption at 550–650°C penetrates Australia's floating production facilities where deck limitations previously excluded on-site processing. Woodside Energy and Santos have piloted containerized systems cutting transport volumes by 70 percent.
- Biological Treatment:Microbial hydrocarbon degradation offers lower-energy alternatives for land-based disposal, qualifying for carbon credit offsets under Australia's safeguard mechanism.
- Chemical Treatment:Flocculation and stabilization processes bridge compliance gaps where thermal infrastructure is unavailable.
- Solidification:Cement and polymer encapsulation faces obsolescence as regulators tighten oil-on-cuttings thresholds.
Thermal Treatment anchors capital deployment; Biological Treatment follows the steepest expansion trajectory.
End User:
Customer type determines liability allocation and contract structure across integrated versus standalone procurement models.
- Oil & Gas Companies:Majors and national oil companies in Malaysia and Indonesia increasingly bundle waste management into integrated drilling packages, eliminating discrete service awards since 2022.
- Service Providers:Drilling contractors assume full waste liability under single-point accountability models spreading across Southeast Asian basins.
- Contractors:Subsurface specialists and completions teams generate fragmented waste streams requiring coordination with primary treatment vendors.
- Regulatory Agencies:MEE, NOPSEMA, and CEA enforcement activities create compliance-driven demand spikes during audit periods.
Oil & Gas Companies concentrate procurement authority; Service Providers are consolidating operational responsibility most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Offshore drilling campaigns concentrate demand across Australia's Northwest Shelf, China's Bohai Bay, and Indonesia's frontier basins, with national oil companies consolidating procurement authority through integrated service contracts.
China
Deepwater exploration in the South China Sea generates oil-based cuttings volumes that overwhelm platform storage capacity. MEE discharge standards mandate thermal or chemical processing before any marine release, compelling operators at Bohai Bay facilities to upgrade treatment infrastructure. CNOOC and Sinopec anchor demand in Tianjin and Shenzhen clusters where shore-base thermal units handle continuous waste streams.
Australia
The Northwest Shelf and Timor Sea developments produce synthetic-based drilling mud waste requiring base fluid reclamation above 90 percent recovery rates. NOPSEMA tightened seabed disposal thresholds to 1 percent oil-on-cuttings, rendering solidification non-compliant for new Browse Basin fields. Perth serves as the technician certification hub, while Karratha and Darwin host shore-base thermal treatment facilities.
Indonesia
Pertamina's integrated drilling packages now bundle waste liability with drilling contracts across Sarawak waters and frontier basins. The country's national petroleum regulator enforces discharge protocols that favor shore-based biological processing over marine dumping. Balikpapan and Jakarta concentrate service provider operations for eastern seaboard campaigns.
Malaysia
Petronas Carigali eliminated discrete waste service awards since 2022, shifting to single-point accountability models where drilling contractors assume full waste liability. Offshore licensing rounds in deepwater blocks generate treatment demand currently met by Singapore-based vessel charters. Kuala Lumpur anchors regional procurement decisions for Southeast Asian basin developments.
Vietnam
New production sharing contracts in the Cuu Long and Nam Con Son basins will generate drilling waste volumes exceeding domestic treatment capacity. The absence of established shore-base infrastructure creates openings for mobile thermal units and cross-border service arrangements. Ho Chi Minh City concentrates operator headquarters activity for southern basin development planning.
Asia-Pacific Drilling Waste Management Services Market Competitive Environment
Integrated service bundling dominates the current landscape as national oil companies consolidate procurement authority. The market structures around three tiers: international oilfield service conglomerates with closed-loop system portfolios, regional specialists with mobile treatment fleets, and engineering contractors pivoting into waste management through partnerships. Strategic archetypes separate technology licensors from equipment operators and logistics integrators. Competitive moves center on vertical integration into drilling contracts and geographic expansion through vessel-based mobility.
Among Houston-based oilfield service conglomerates, Halliburton Company and Schlumberger Ltd exemplify the integrated bundling archetype, while Baker Hughes Company occupies a position within the technology licensing tier. Weatherford International plc represents the mobile equipment specialization vector. These entities anchor competitive dynamics without constituting exclusive market control, as regional operators and engineering specialists retain procurement access through subcontracting relationships.
| Leading Market Players |
|---|
| Schlumberger Ltd |
| Halliburton Company |
| Baker Hughes Company |
| Weatherford International plc |
| China Oilfield Services Ltd |
| National Oilwell Varco, Inc. |
| Veolia Environnement S.A. |
| Scomi Group Bhd |
| Nuverra Environmental Solutions, Inc. |
| Others |
Value Chain & Pricing Dynamics
Integrated drilling contract bundling by Petronas and Pertamina is compressing standalone waste service margins and forcing providers to absorb thermal treatment capital costs within fixed per-meter drilling fees rather than variable disposal rates.
Pricing Analysis
Volume-based per-tonne disposal rates are yielding to bundled per-meter drilling fees as integrated contracts dominate Southeast Asian procurement. Price differentiation separates thermal treatment tiers certified for NOPSEMA's 1 percent oil-on-cuttings limit from solidification-based alternatives facing obsolescence. Pricing pressure stems from national oil company consolidation of procurement authority into single-point accountability models. Independent treatment operators exhibit highest price sensitivity as drilling contractors internalize waste liability and squeeze subcontractor margins.
Supply Chain Analysis
Direct-to-operator channels handle integrated contract demand while vessel-charter intermediaries serve spot treatment requirements in frontier basins. Manufacturing concentrates in Singapore for mobile thermal skids, Australia for containerized electro-thermal systems, and China for diesel generator packages. Equipment supply draws from specialized steel fabrication, ceramic insulation, and emissions control subsystems. Single-source vulnerability runs through certified thermal desorption operator pools concentrated in Perth and Singapore. Distribution runs through drilling contractor procurement desks rather than standalone waste service tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance arena where MEE discharge thresholds and NOPSEMA's 1 percent oil-on-cuttings limit erect capital barriers that filter out undercapitalized entrants and reward compliant incumbents with pricing power.
For Market Incumbents: Anticipate continued procurement consolidation by national oil companies and preemptively integrate thermal treatment capacity into drilling contract structures before competitors lock in integrated positions. Defensive positioning requires securing NOPSEMA and MEE certification moats while building captive technician training pipelines to offset Perth-Singapore operator scarcity. Capacity addition in Vietnam's Cuu Long basin ahead of licensing round waste volume spikes offers geographic hedge against Australian market saturation.
For New Entrants and Emerging Players: Mobile vessel-based thermal units represent the most penetrable entry vector for Indonesia's frontier basins where shore-base infrastructure remains undeveloped and Pertamina's integrated contracts create subcontractor access points. Bioremediation services for land-based drill cuttings disposal in Australia qualify for carbon credit offsets under the safeguard mechanism, opening differentiated positioning against thermal incumbents. Go-to-market execution should target drilling contractor subcontracts rather than direct national oil company awards.
For Investors and Strategic Acquirers: The window for entry favors regional mobile treatment specialists with vessel-deployable assets and existing NOPSEMA certification rather than greenfield technology developers facing 12-18 month permitting timelines. Long-term viability hinges on exposure to Vietnam and Indonesia frontier basins where treatment infrastructure lags drilling activity. Monitor India's CEA coastal zone approval velocity as inflection signal for eastern seaboard market opening.
| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Service Contracting | Petronas Carigali's elimination of discrete waste awards since 2022 demonstrates single-point accountability dominance. |
| Containerized Thermal Deployment | Woodside Energy and Santos pilots on Scarborough and Barossa cut transport volumes by 70 percent. |
| Technician Certification Pipeline | Perth-based operator training addresses skilled scarcity bottlenecks across Indonesia's frontier basins. |
| Bioremediation Service Expansion | Microbial hydrocarbon degradation qualifies for Australia's safeguard mechanism carbon credit offsets. |
| Cross-Border Mobile Positioning | Vessel-based thermal units exploit Vietnam's domestic treatment capacity gap in Cuu Long and Nam Con Son. |
Study Parameters
Independent corroboration across drilling contractor procurement directors, thermal treatment plant operators, and national oil company environmental compliance officers underwrites the qualitative findings. Primary fieldwork encompassed interviews with Singapore-based vessel charter specialists, Perth technician certification bodies, and CNOOC facilities engineers at Tianjin and Shenzhen clusters. Secondary validation drew from NOPSEMA discharge compliance databases, MEE environmental filings, Australian Bureau of Statistics energy sector data, and ASEAN petroleum regulatory circulars. Bottom-up treatment capacity counts triangulated against top-down drilling activity forecasts.
Rate-of-change decomposition across the analysis window separates volume growth from value-per-unit shifts driven by regulatory threshold tightening and technology substitution. Segmentation modeling incorporated waste type, service tier, treatment technology, and end-user procurement structure dimensions. CAGRs were derived from installed capacity deployment trajectories and drilling campaign schedules across the projection horizon. Forecast inputs included Australia's Browse Basin development timelines and China's Bohai Bay facility upgrade cycles.
Caveats apply where MEE enforcement intensity variations or NOPSEMA threshold revisions could materially shift the outlook. Forecasts reflect assumptions about national oil company contract bundling persistence and thermal desorption technology cost curves. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
US Sludge Management and Dewatering Market
Water & Sludge Treatment
Global Sodium Hypochlorite Market
Water & Sludge Treatment
Global Water Softeners Market
Water & Sludge Treatment
India Water Treatment Market
Water & Sludge Treatment
Water Treatment Market
Water & Sludge Treatment
Swimming Pool Treatment Chemicals Market
Water & Sludge Treatment
Global Liquid Waste Management Market
Water & Sludge Treatment
Fluid Waste Disposal Systems Market
Water & Sludge Treatment
Nanotechnology in Water Treatment Market
Water & Sludge Treatment
Oil and Gas Water Treatment Chemicals Market
Water & Sludge Treatment
Saudi Arabia Industrial Hazardous Waste Management Market
Water & Sludge Treatment
Hazardous Waste Treatment System Market
Water & Sludge Treatment
Slurry Valves Market
Water & Sludge Treatment
Water Treatment Chemicals Market
Water & Sludge Treatment
Asia-Pacific Boiler Water Treatment Chemicals Market
Water & Sludge Treatment
Ultrapure Water Market