
 Europe Membrane Water and Wastewater Treatment (WWT) Market | 2026-2036
Europe Membrane Water and Wastewater Treatment (WWT) Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Membrane Water and Wastewater Treatment (WWT) Market Foresight
High-flux ultrafiltration specifications is collapsing the cost gap between membrane bioreactors and conventional activated sludge in municipal retrofits. Veolia leverages its integrated service contracts across French and Italian utilities to lock in long-term membrane replacement revenue. Suez anchors its position through proprietary hollow-fiber chemistry that extends cleaning intervals in high-fouling industrial streams.
Membrane Water and Wastewater Treatment encompasses pressure-driven separation processes that use semi-permeable barriers with pore sizes ranging from 0.1 microns in microfiltration to sub-nanometer precision in reverse osmosis, typically constructed from polyethersulfone, polyamide thin-film composites, or inorganic ceramics. These systems remove suspended solids, dissolved salts, pathogens, and micropollutants to produce water suitable for discharge, reuse, or potable supply across municipal and industrial settings. Reverse osmosis dominates value capture in desalination and high-purity industrial applications where energy recovery devices and fouling-resistant coatings protect margin pools. Ultrafiltration leads volume in municipal tertiary treatment as utilities replace aging sand filters with compact membrane modules that slash footprint and improve pathogen log removal.
The EU Urban Wastewater Treatment Directive and F-Gas Regulation shape membrane technology selection by mandating nutrient removal thresholds and restricting synthetic refrigerants in energy-intensive desalination. ECHA's REACH framework governs chemical compatibility testing for polymeric membrane materials, while CE marking requirements enforce performance validation before market entry. Stakeholders must weigh ceramic membrane capital premiums against extended lifespans in abrasive industrial effluents as polymer innovation narrows the durability gap.
Market Dynamics
The EU Green Deal's water reuse mandates are compressing replacement cycles for legacy sand filtration systems across municipal utilities, forcing rapid membrane technology adoption in Germany's industrial Rhine-Ruhr corridor and France's chemical processing hubs.
Growth Catalysts
- EU Urban Wastewater Treatment Directive:Tightening nutrient removal thresholds in Germany, France, and Spain are accelerating ultrafiltration retrofits at aging municipal plants.
- Ceramic membrane durability advances:Extended operational lifespans in abrasive industrial effluents from chemical processors are narrowing replacement cost premiums versus polymeric alternatives.
- Industrial Rhine-Ruhr corridor demand:Concentrated chemical and food processing operations face the continent's strictest effluent limits, driving continuous membrane capacity expansion.
Market Restraints
- Energy cost volatility:Reverse osmosis desalination and high-pressure ultrafiltration operations remain exposed to European electricity price fluctuations, compressing operating margins for utilities.
- Polymer supply concentration:Polyethersulfone and polyamide thin-film composite feedstock production clusters in select Asian manufacturing hubs create import dependency risks for European module assemblers.
- F-Gas Regulation friction:Restrictions on synthetic refrigerants in energy-intensive desalination applications limit technology options for coastal utilities seeking thermal hybrid configurations.
Strategic Opportunities
- Spain's agricultural water reuse:The EU Green Deal's irrigation targets create untapped demand for tertiary membrane treatment in Mediterranean farming regions facing chronic scarcity.
- Membrane bioreactor convergence:Integration of high-flux ultrafiltration with biological treatment is collapsing footprint requirements for municipal retrofits in dense urban cores.
- CE marking performance validation:Streamlined certification pathways for ceramic modules are accelerating market entry for durable alternatives in high-fouling industrial streams.
Industry Challenges
- Specialized membrane fabrication expertise:Shortages of process engineers capable of optimizing hollow-fiber chemistry for site-specific fouling profiles constrain deployment timelines.
- Legacy activated sludge integration:Retrofitting membrane modules into existing biological treatment trains without disrupting continuous operations demands complex sequencing and downtime management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Membrane Water and Wastewater Treatment (WWT) Market |
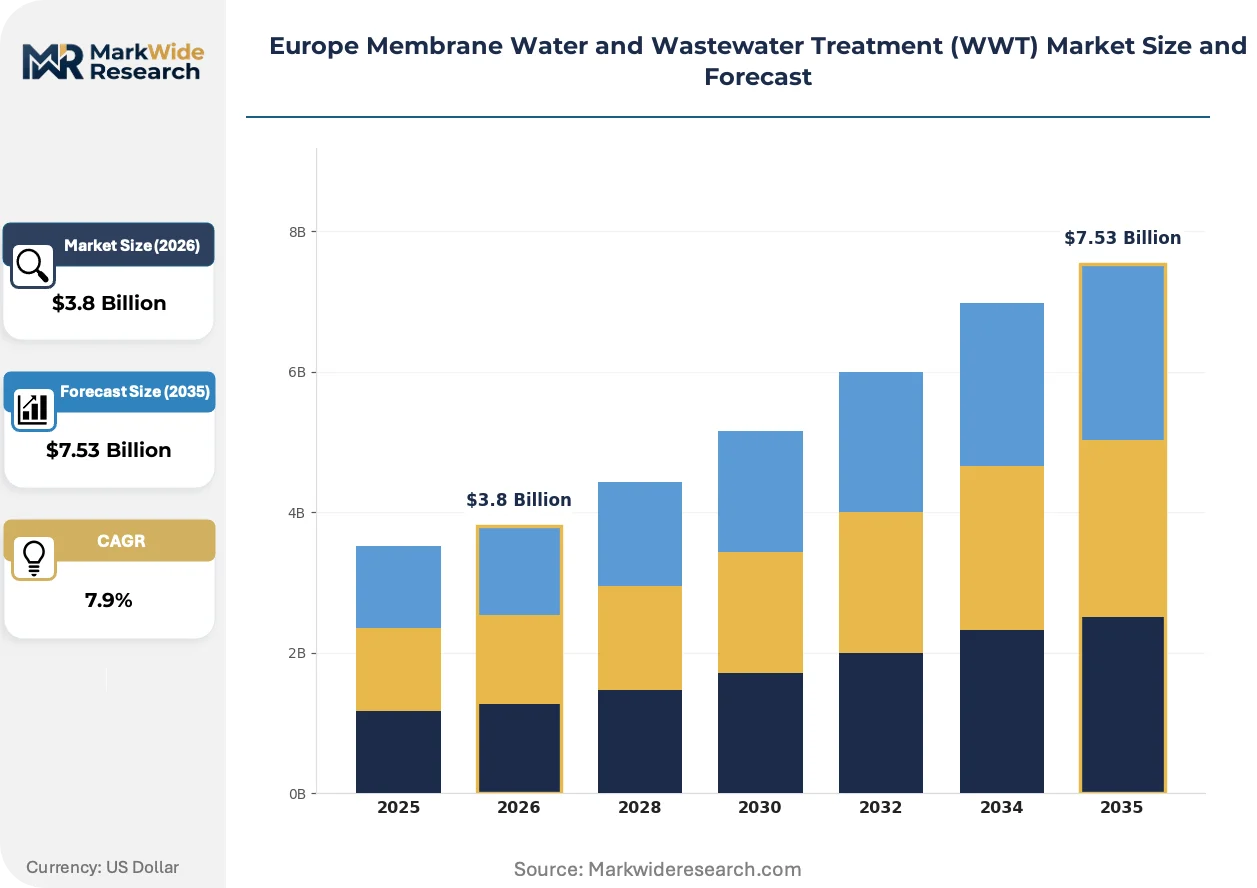
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.53 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microfiltration, Ultrafiltration, Nanofiltration, Reverse Osmosis Application: Municipal, Industrial, Agricultural, Desalination Treatment Stage: Primary Treatment, Secondary Treatment, Tertiary Treatment, Advanced Oxidation End User: Civic Authorities, Industries, Agricultural Sector, Research Institutions |
| Companies Covered | Veolia, Suez, Evoqua Water Technologies, Kemira, GEA Group, Pentair, Ecolab, Berghof Membranes, DuPont Water Solutions, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Membrane Water and Wastewater Treatment (WWT) Market Shifts & Advancements
Membrane water and wastewater treatment technology is undergoing rapid specification divergence as utilities and industrial processors pursue divergent performance priorities. Three interconnected developments are reshaping competitive positioning across the European market.
Ceramic membrane construction is bifurcating the industrial treatment segment. Alumina and silicon carbide modules deliver superior abrasion resistance for chemical and mining effluents. German and French heavy processors are adopting these systems despite capital premiums of forty to sixty percent above polymeric equivalents. This technology split is compressing addressable market overlap between ceramic specialists and polymer-focused suppliers.
REACH framework chemical compatibility testing is tightening material selection protocols for membrane manufacturers. ECHA's expanded substance restrictions are forcing reformulation of polyethersulfone blends and adhesive chemistries. Municipal utilities in the Netherlands and Belgium are prioritizing suppliers with pre-validated material safety dossiers, shifting procurement evaluation criteria toward regulatory documentation depth.
Service contract unbundling is fragmenting traditional vendor relationships. French and Italian utilities are separating membrane supply from replacement and cleaning service obligations. Equipment-only procurement is gaining share in Spain's agricultural reuse sector, where specialized local operators assume operational responsibility. This pattern is most pronounced in Mediterranean markets with established water service outsourcing cultures.
Europe Membrane Water and Wastewater Treatment (WWT) Market Segmentation
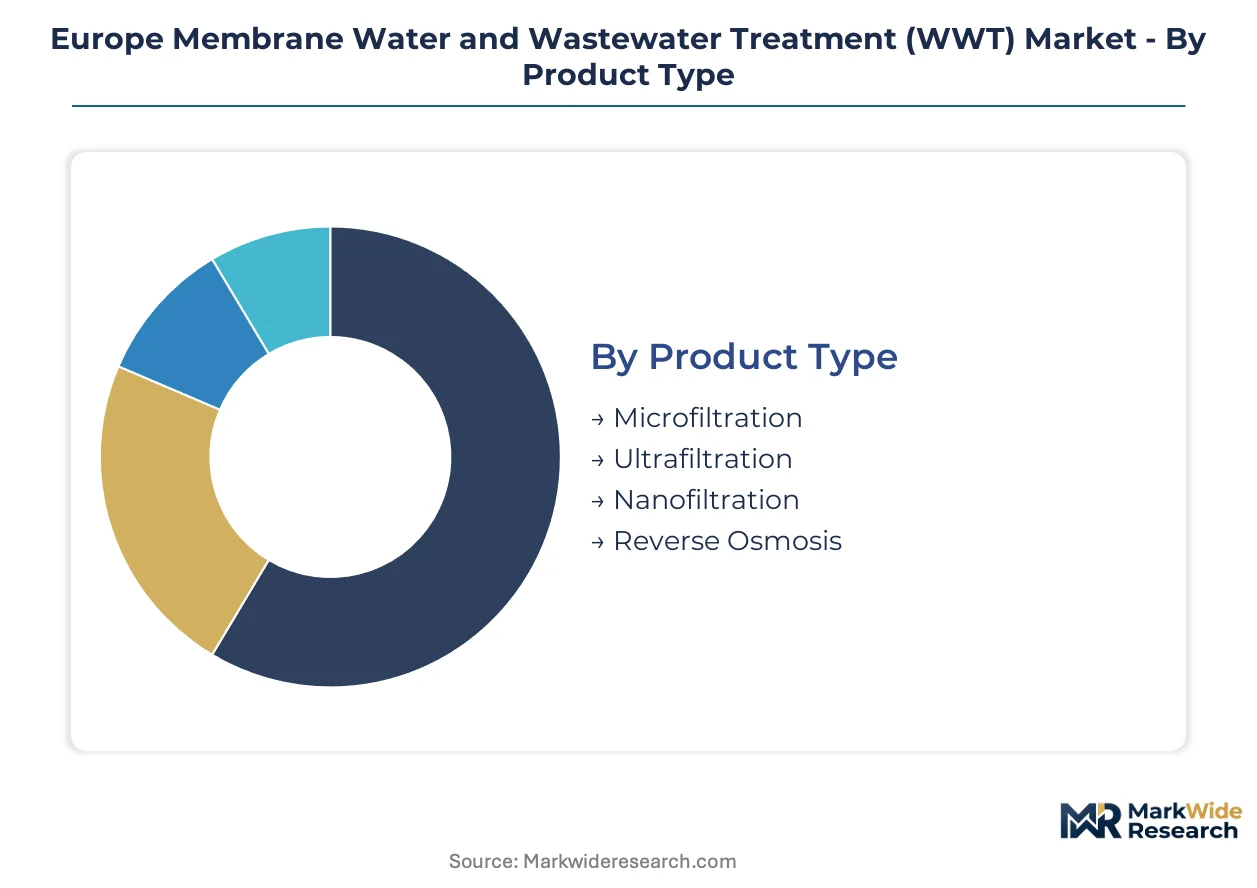
Membrane technology selection in Europe hinges on effluent quality targets and energy economics. Product type determines capital intensity and operating cost structure, while application segments reflect divergent regulatory pressure across municipal and industrial discharge regimes.
Product Type:
Reverse osmosis commands the steepest margin pools due to energy recovery device integration and fouling-resistant coating premiums in high-purity industrial streams.
- Reverse Osmosis:Polyamide thin-film composite barriers achieve sub-nanometer separation precision for dissolved salts and micropollutants. German chemical processors in the Rhine-Ruhr corridor deploy these systems under strict effluent limits, though electricity price volatility compresses operating returns.
- Ultrafiltration:Hollow-fiber polyethersulfone modules with 0.01-micron pore ratings dominate municipal tertiary retrofits. French and Spanish utilities are replacing aging sand filters to meet EU Urban Wastewater Treatment Directive nutrient thresholds, slashing footprint while improving pathogen log removal.
- Microfiltration:0.1-micron rated membranes handle suspended solids pre-treatment for downstream reverse osmosis trains.
- Nanofiltration:Selective divalent ion rejection serves softening applications and selective contaminant removal in food processing effluents.
Reverse osmosis holds installed capacity. Ultrafiltration is rotating up the share rankings.
Application:
Industrial discharge compliance drives premium technology adoption, while municipal retrofits concentrate volume at standard specifications.
- Industrial:Chemical, food, and pharmaceutical processors face Europe's strictest effluent limits. Ceramic membrane durability advances are narrowing replacement cost premiums versus polymeric alternatives in abrasive mining and chemical streams across Germany and France.
- Municipal:Aging activated sludge plants require membrane bioreactor convergence to compress footprint in dense urban cores. The EU Green Deal's water reuse mandates are forcing rapid ultrafiltration adoption across German, French, and Spanish utilities.
- Agricultural:Spain's irrigation-dependent farming regions generate tertiary treatment demand for reclaimed water supply under Mediterranean scarcity conditions.
- Desalination:Coastal utilities face F-Gas Regulation constraints on thermal hybrid configurations, limiting technology options for energy-intensive seawater processing.
Municipal holds installed capacity. Agricultural is rotating up the share rankings.
Treatment Stage:
Tertiary and advanced oxidation stages capture margin concentration as utilities upgrade beyond basic biological treatment.
- Tertiary Treatment:Membrane filtration replaces conventional clarification and disinfection for pathogen removal and micropollutant capture. Dutch and Belgian utilities prioritize suppliers with pre-validated REACH material safety dossiers, shifting procurement toward regulatory documentation depth.
- Advanced Oxidation:Combined membrane-oxidation processes address emerging contaminant destruction in industrial effluents with complex organic loads.
- Secondary Treatment:Membrane bioreactor integration of ultrafiltration with biological processes collapses footprint requirements for municipal retrofits.
- Primary Treatment:Coarse screening and grit removal precedes membrane stages, offering limited technology differentiation.
Tertiary Treatment holds installed capacity. Advanced Oxidation is rotating up the share rankings.
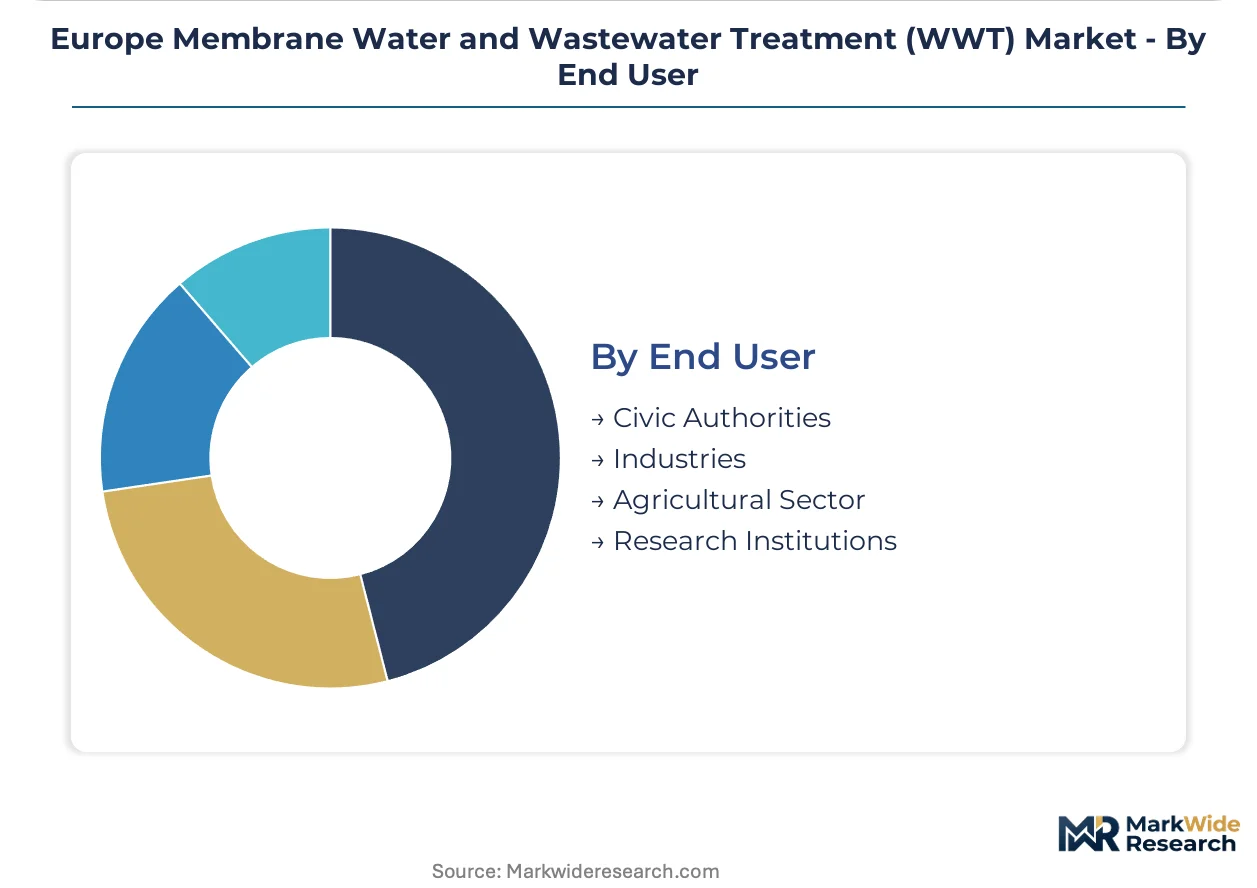
End User:
Civic authorities concentrate procurement volume, while industrial end users drive specification complexity and service contract fragmentation.
- Civic Authorities:Municipal utilities across Germany, France, and Spain are expanding ultrafiltration capacity under tightening EU discharge standards. Service contract unbundling is separating membrane supply from replacement obligations in French and Italian markets.
- Industries:Chemical and food processors in the Rhine-Ruhr corridor deploy ceramic membranes despite capital premiums for abrasion resistance in high-fouling streams.
- Agricultural Sector:Spanish farming cooperatives are adopting equipment-only procurement models where specialized local operators assume operational responsibility.
- Research Institutions:Pilot-scale membrane testing supports technology validation for novel ceramic formulations and fouling-resistant coatings.
Civic Authorities hold installed capacity. Industries is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe's membrane water and wastewater treatment market runs a structural trade deficit in polymeric membrane modules, importing polyethersulfone and polyamide thin-film composites from Asian manufacturing hubs while exporting ceramic membrane technology and integrated service expertise to Mediterranean and Middle Eastern markets.
Germany
Rhine-Ruhr chemical processors and food manufacturers deploy ceramic membranes for abrasive effluent streams under strict state-level discharge permits. The EU Urban Wastewater Treatment Directive accelerates ultrafiltration retrofits across North Rhine-Westphalia's aging municipal plants. Bavaria's semiconductor fabrication clusters drive demand for high-purity reverse osmosis systems with energy recovery integration.
France
Veolia and Suez anchor integrated service contracts across municipal utilities in Île-de-France and Provence-Alpes-Côte d'Azur. The EU Green Deal's water reuse targets compress replacement cycles for legacy sand filtration in Mediterranean coastal cities. Auvergne-Rhône-Alpes hosts specialized hollow-fiber chemistry development for high-fouling industrial applications.
Spain
Agricultural cooperatives in Andalusia and Valencia adopt equipment-only procurement models for tertiary membrane treatment serving irrigation-dependent farming. ECHA's REACH framework governs material compatibility testing for polymeric membranes entering reclaimed water distribution networks. Catalonia's dense urban cores favor membrane bioreactor convergence to slash biological treatment footprints.
Netherlands
Dutch utilities prioritize suppliers with pre-validated REACH material safety dossiers, shifting procurement evaluation toward regulatory documentation depth. The F-Gas Regulation constrains thermal hybrid desalination options for coastal municipalities in Zeeland and Noord-Holland. Rotterdam's industrial port complex drives ceramic membrane adoption for chemical processing effluents.
Italy
Service contract unbundling fragments traditional vendor relationships across Lombardy and Emilia-Romagna water utilities. CE marking performance validation accelerates market entry for ceramic alternatives in high-fouling textile and tanning streams around Milan and Bologna. Po Valley agricultural districts generate emerging demand for membrane-based tertiary treatment under EU irrigation reuse mandates.
Europe Membrane Water and Wastewater Treatment (WWT) Market Competitive Landscape
Listed leaders compete with private specialists across contract bundling strategies, creating a tiered structure where integrated service providers capture long-term replacement revenue while equipment-only vendors fight for procurement share. French and German players dominate the premium service tier through multi-decade utility relationships. Three archetypes define competitive positioning: integrated water service conglomerates, specialized membrane fabricators, and regional equipment distributors. M&A activity concentrates on technology licensing agreements and backward integration into hollow-fiber chemistry production.
Within the integrated service tier, Veolia and Suez exemplify the contract-bundling model that locks in municipal replacement cycles across French and Italian utilities. DuPont Water Solutions occupies a position representing specialized membrane chemistry suppliers competing on fouling-resistant coating specifications. Evoqua Water Technologies anchors the mid-market equipment vector with standardized module configurations targeting industrial processors seeking operational flexibility without full-service obligations.
| Leading Market Players |
|---|
| Veolia |
| Suez |
| Evoqua Water Technologies |
| Kemira |
| GEA Group |
| Pentair |
| Ecolab |
| Berghof Membranes |
| DuPont Water Solutions |
| Others |
Supply & Pricing Matrix
Capacity utilization at Asian polyethersulfone and polyamide thin-film composite manufacturing hubs anchors European membrane module pricing floors, compressing margin pools for European assemblers while ceramic membrane specialists command capital premiums through localized production scale. This scale asymmetry stratifies procurement power across industrial OEM buyers, municipal utilities, and agricultural cooperatives facing divergent total-cost-of-ownership pressures.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake pricing structure where volume scale and REACH material safety dossier certification grade drive differentiation. Ceramic membrane capital premiums of forty to sixty percent above polymeric equivalents reflect abrasion resistance and extended operational lifespans. Cost compression in standard ultrafiltration modules intensifies as hollow-fiber chemistry commoditizes, squeezing equipment-only vendors. Municipal utilities exhibit lowest price sensitivity due to bundled service contracts, while Spanish agricultural cooperatives negotiating equipment-only procurement show highest sensitivity.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Hamburg port corridors fluctuate with container availability on Asia-Europe trade lanes, amplifying working capital requirements for polymeric membrane importers. Polyethersulfone and polyamide thin-film composite feedstock production concentrates in China, South Korea, and Japan, drawing European module assemblers into import dependency. Single-source vulnerability for specialized hollow-fiber chemistry creates supply risk. Distribution runs through integrated water service conglomerates in France and Italy, equipment distributors in Spain, and direct procurement channels for Rhine-Ruhr industrial processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service contract unbundling fragments traditional vendor relationships across Mediterranean utilities, creating white-space opportunities for specialized membrane fabricators and regional equipment distributors. Agricultural water reuse mandates under the EU Green Deal generate niche demand for tertiary treatment systems outside incumbent service footprints.
For Market Incumbents: Shield replacement revenue streams by deepening backward integration into hollow-fiber chemistry production and locking multi-decade municipal contracts before CE marking validation accelerates ceramic competitor entry. Counter service contract unbundling through predictive maintenance software bundling that raises switching costs for French and Italian utilities. For New Entrants and Emerging Players: Differentiate on ceramic membrane durability specifications for abrasive chemical effluents in Germany's Rhine-Ruhr corridor, where capital premium tolerance runs highest. Target Spain's equipment-only agricultural reuse segment with standardized ultrafiltration modules sold through local operator partnerships, bypassing integrated service incumbents. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors ceramic membrane specialists with validated REACH dossiers and established hollow-fiber chemistry R&D pipelines. Long-term viability hinges on regulatory compliance depth rather than manufacturing scale alone. Watch ECHA substance restriction expansion timelines as inflection indicators for material reformulation cost spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hollow-Fiber Chemistry | Captive polyethersulfone production insulates margin pools from Asian feedstock volatility. |
| REACH Dossier Pre-Validation Investment | Accelerated CE marking pathways compress time-to-revenue for ceramic membrane entrants. |
| Membrane Bioreactor Platform Convergence | Integrated ultrafiltration-biological treatment captures municipal retrofit volume in dense urban cores. |
| Equipment-Only Distribution Partnership | Spanish agricultural cooperative networks bypass incumbent service bundling. |
| Predictive Maintenance Software Development | Digital service layers raise switching costs against unbundling pressures in French utilities. |
Research Methodology
Operator-level perspectives from municipal utility procurement directors, industrial plant engineers, membrane fabrication R&D leads, and aftermarket service managers anchored the qualitative base. Primary fieldwork combined with secondary validation from ECHA REACH substance restriction databases, EU Urban Wastewater Treatment Directive implementation reports, customs trade data for polymeric membrane imports, and SEC filings of listed water service conglomerates. Bottom-up module shipment estimates triangulated against top-down utility capital expenditure tracking across Germany, France, Spain, Netherlands, and Italy.
Sensitivity analysis tested forecast robustness across electricity price volatility scenarios and ceramic membrane durability improvement trajectories throughout the projection horizon. Segmentation modeling spanned product type, application, treatment stage, and end user, with additional dimensioning by regulatory compliance tier. CAGRs derived from installed base replacement cycle analysis and greenfield capacity addition pipelines. Industry-specific inputs included EU Green Deal water reuse target implementation schedules and F-Gas Regulation constraint evolution for coastal desalination.
Material uncertainties — energy cost volatility, ECHA substance restriction expansion, and ceramic membrane capital premium compression rates — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory enforcement intensity and technology adoption curves. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
Industrial Wastewater Real-Time Toxicity Monitoring Test Systems Market
Water & Sludge Treatment
Anionic Flocculants Market
Water & Sludge Treatment
Water Dispersible Granules Market
Water & Sludge Treatment
Low-Dosage Hydrate Inhibitors (Ldhis) Market
Water & Sludge Treatment
Global Mobile Water Treatment Market
Water & Sludge Treatment
Global Industrial Sludge Treatment Chemicals Market
Water & Sludge Treatment
Membrane Filtration Systems Market
Water & Sludge Treatment
Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
Ballast Water Treatment Market
Water & Sludge Treatment
Europe Membrane Bioreactor (MBR) Market
Water & Sludge Treatment
Fluid Waste Disposal Systems Market
Water & Sludge Treatment
Ultrapure Water Market
Water & Sludge Treatment
Global Water Clarifiers Market
Water & Sludge Treatment
Deionized Water Systems Market
Water & Sludge Treatment
US Sludge Management and Dewatering Market
Water & Sludge Treatment
Germany Water Treatment Chemicals Market