
 Global Check Valve Market | 2026-2036
Global Check Valve Market Size, Share, and Industry Trends Forecast 2026-2036
Global Check Valve Market Foresight
A capital-intensity divergence between foundry-owning incumbents and outsourced-assembly competitors is redrawing competitive boundaries in the Global Check Valve Market. Emerson Electric Co. leverages captive casting operations and in-house metallurgy labs to sustain margin control across its stainless steel product lines. Flowserve Corporation anchors its position through API-certified alloy steel valves for petrochemical clients, while Velan Inc. differentiates via nuclear-grade manufacturing credentials that command premium positioning in energy facilities.
A check valve is a mechanical flow-control device permitting unidirectional fluid passage while automatically preventing reverse flow, typically specified by cracking pressure, seat material compatibility, and flow coefficient (Cv) ratings. Its primary industrial purpose is protecting pumps, compressors, and pipeline infrastructure from water hammer, backflow contamination, and equipment damage in pressurized systems. Swing check valves dominate water treatment and municipal applications due to low head-loss characteristics and self-cleaning operation, while diaphragm and cartridge variants are gaining fastest in food & beverage and HVAC systems where sanitary design and compact installation constraints command price premiums over standard cast iron models.
The American Society of Mechanical Engineers (ASME) Boiler and Pressure Vessel Code, the European Pressure Equipment Directive (PED), and China's GB/T standard series collectively shape material certification requirements, testing protocols, and market access conditions for check valve manufacturers serving cross-border projects. The EPA's revised Lead and Copper Rule and the EU REACH regulation on hazardous substances are forcing alloy substitutions that elevate production costs but create compliance-based differentiation for certified suppliers. Stakeholders must monitor evolving drinking-water contact material standards across multiple jurisdictions to anticipate procurement specification shifts before they disrupt existing supply relationships.
Market Dynamics
Material substitution mandates and foundry capacity concentration are restructuring procurement economics in the Global Check Valve Market, forcing buyers to qualify new alloy suppliers while incumbent manufacturers exploit captive metallurgy capabilities to lock in municipal utility contracts.
Growth Catalysts
- EPA Lead and Copper Rule Revisions:The United States Environmental Protection Agency's updated drinking water standards are compelling municipal utilities to replace legacy bronze installations with lead-free stainless steel and copper-nickel alloys, triggering system-wide infrastructure procurement cycles.
- China State-Backed Desalination Expansion:Government-funded coastal water treatment facilities are generating bulk orders for large-diameter cast iron swing check valves engineered for high-salinity corrosion resistance.
- Swing Check Valve Low Head-Loss Performance:Water treatment engineers specify self-cleaning swing designs over spring-loaded alternatives to minimize pumping energy consumption across extended pipeline networks.
Market Restraints
- Nickel and Molybdenum Price Volatility:Stainless steel 316L production costs fluctuate with London Metal Exchange pricing for nickel, compressing margins on corrosion-resistant product lines during commodity spikes.
- Foundry Capacity Concentration in China and India:Over half of global gray and ductile iron casting output originates from East Asian facilities, exposing Western assemblers to shipping disruptions and tariff exposure.
- Butterfly Valve Substitution in HVAC:Compact wafer-style butterfly valves with integrated check functions are displacing standalone check valves in commercial building climate systems where space constraints dominate specification criteria.
Strategic Opportunities
- Saudi Arabia NEOM and Red Sea Project Pipeline:The Kingdom's giga-project construction schedule is creating demand for seawater-resistant duplex stainless steel check valves in desalination and district cooling infrastructure.
- IoT-Enabled Condition Monitoring Convergence:Integration of pressure sensors and wireless transmitters into valve bodies allows predictive maintenance contracts that capture recurring revenue from industrial facility operators.
- India Jal Jeevan Mission Rural Water Supply:The national rural tap water program is deploying millions of small-diameter plastic and brass check valves in village-level distribution networks previously unserved by formal suppliers.
Industry Challenges
- ASME Section III Nuclear Certification Timelines:Qualifying manufacturing processes for nuclear-grade check valves requires 18-36 months of documentation and third-party audit cycles that delay revenue recognition.
- Legacy System Integration Complexity:Retrofitting automated check valve assemblies into existing petrochemical plants demands custom flange adaptations and control system protocol matching that extend project commissioning schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Check Valve Market |
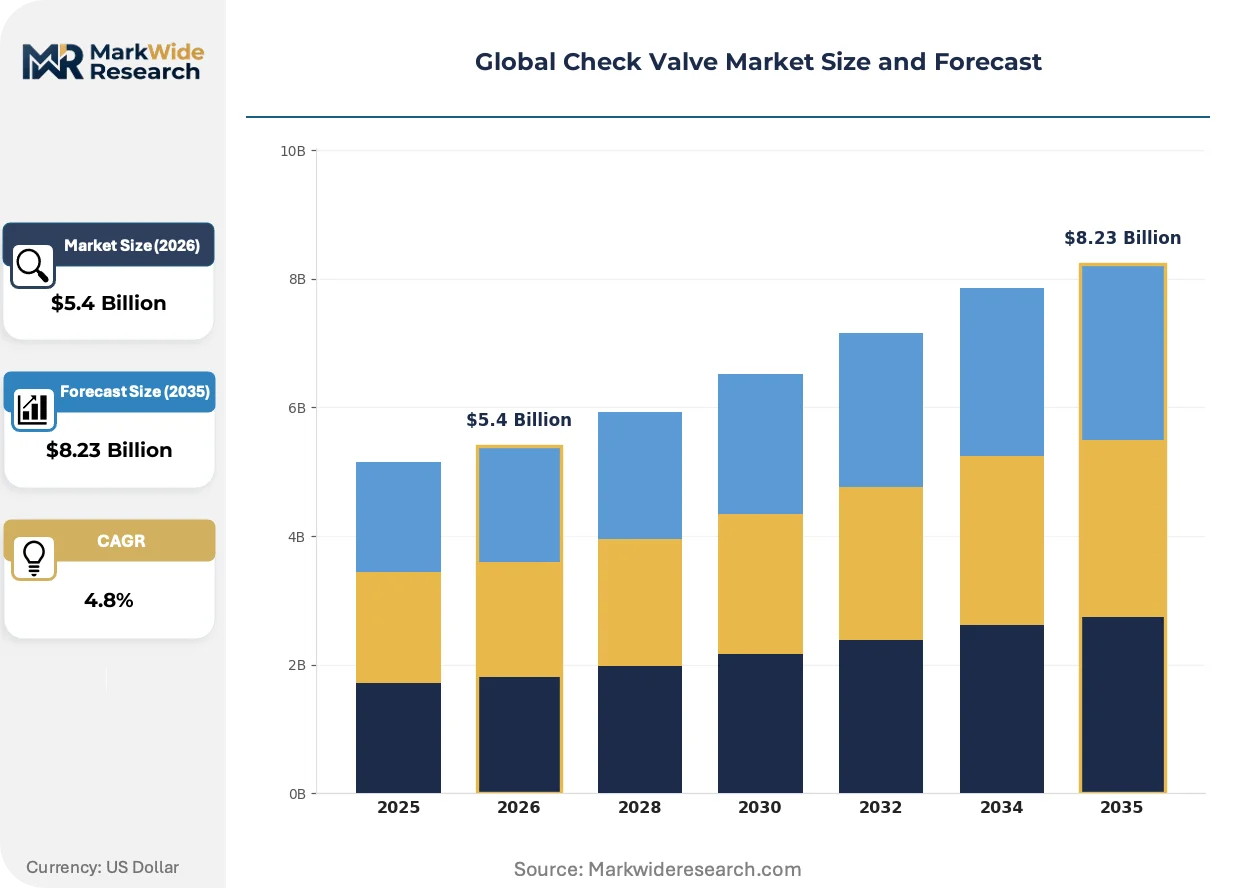
| Market Size in 2026 | $5.4 Billion |
| Market Size in 2035 | $8.23 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Swing, Lift, Ball, Diaphragm, Butterfly, Cartridge Material: Stainless Steel, Bronze, Cast Iron, PVC, Alloy Steel, Brass Application: Water Treatment, Chemical Processing, Power Generation, Food & Beverage, HVAC Systems, Pulp & Paper End User Industry: Municipal Facilities, Petrochemical Plants, Energy Facilities, Beverage Manufacturers, Paper Mills, Heating Contractors |
| Companies Covered | Eaton Corporation, Bosch Rexroth, Emerson Electric Co., Curtiss-Wright Corp., Velan Inc., Flowserve Corporation, Schlumberger, AVK Holding A/S, Crane Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Check Valve Market Shifts & Advancements
Additive manufacturing of valve components and computational fluid dynamics simulation are compressing product development cycles while enabling geometries impossible with traditional sand casting, reshaping how manufacturers validate performance before physical prototyping.
Metal 3D printing using laser powder bed fusion is bifurcating the prototyping and low-volume production landscape. Aerospace and nuclear facility engineers now specify topology-optimized check valve bodies with internal lattice structures for weight reduction. Conventional foundry-dependent suppliers face margin compression on sub-100 unit orders as printed stainless steel components achieve comparable pressure ratings without tooling investment.
REACH regulation amendments in the European Union are restricting chromium VI compounds in surface treatment processes. Valve manufacturers serving EU water utilities must convert passivation and coating lines to trivalent chromium or citric acid alternatives. German and French municipal procurement specifications now require material safety data sheet disclosure of all surface chemistry, favoring suppliers with certified green process documentation.
Utility engineering departments are consolidating vendor lists and demanding extended warranty packages that bundle installation supervision with multi-year parts availability commitments. Traditional distributor channels face disintermediation as direct manufacturer relationships offer lifecycle cost guarantees that distributors cannot underwrite. This pattern is most pronounced in Australian and Canadian municipal water authorities where centralized procurement agencies negotiate framework agreements spanning hundreds of individual treatment facilities.
Global Check Valve Market Segmentation
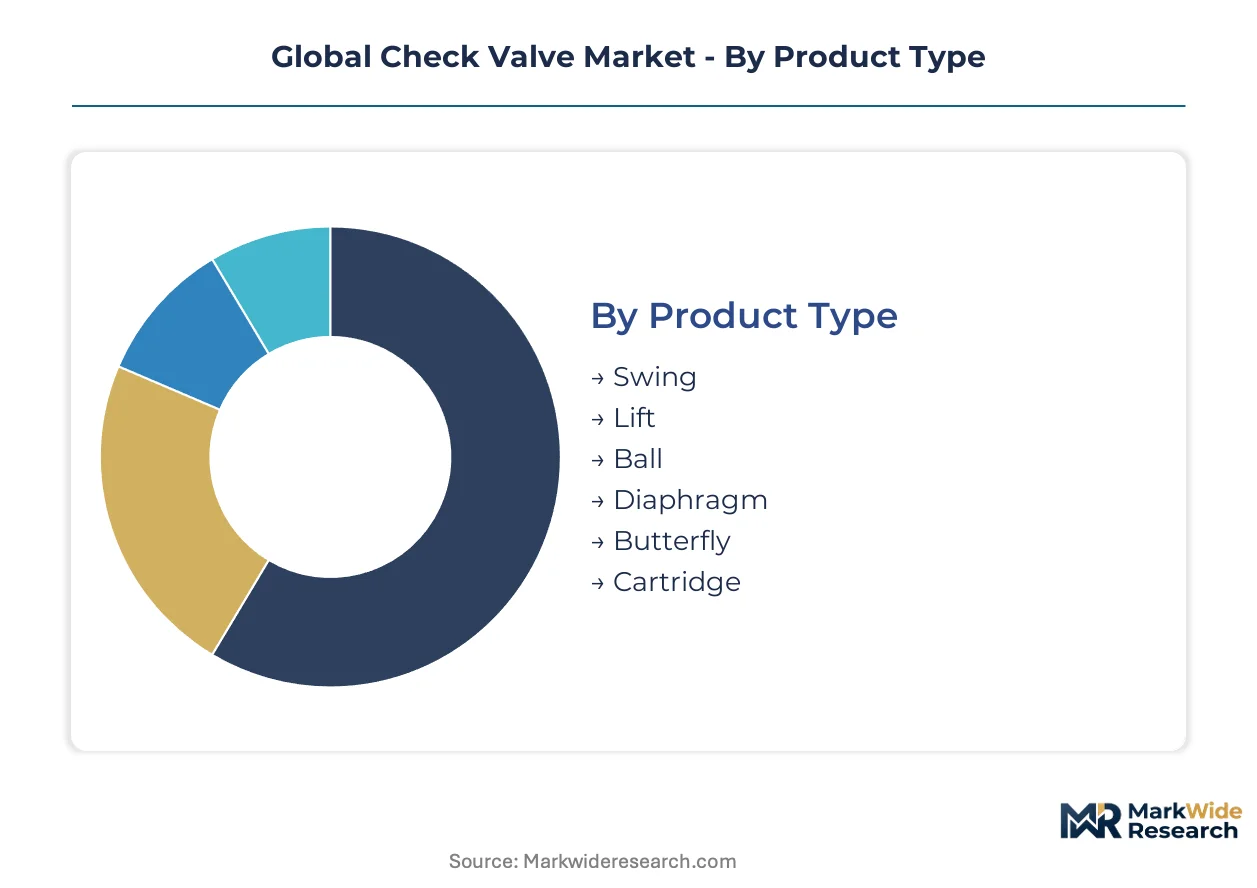
Check valve procurement decisions cascade through multiple technical dimensions simultaneously. Engineers specify by flow dynamics first, then filter through material compatibility against fluid chemistry, installation geometry, and lifecycle cost constraints.
Product Type:
Swing check valves face the most severe substitution pressure from integrated butterfly valve assemblies in commercial HVAC specifications, forcing standalone swing manufacturers to defend municipal water treatment strongholds where low head-loss performance remains non-negotiable.
- Swing:Hinged disc design rotates fully open with minimal flow resistance, making it the default specification for raw water intake stations and wastewater discharge headers across North American municipal utilities. EPA Lead and Copper Rule upgrades are accelerating stainless steel swing procurement cycles in legacy bronze replacement programs.
- Diaphragm:Elastomer membrane seals against weir bodies for bubble-tight shutoff in sanitary process lines. Beverage manufacturers in Germany and France specify diaphragm variants with EPDM or PTFE membranes to satisfy REACH surface chemistry disclosure requirements for potable water contact.
- Lift:Piston or ball-guided vertical travel suits high-pressure pump discharge lines in petrochemical facilities where water hammer protection takes priority over energy efficiency.
- Ball:Spherical closure element provides rapid response in pulsating flow conditions common to reciprocating compressor installations.
- Butterfly:Wafer-body dual-plate designs integrate check function with space-saving geometry, displacing standalone units in chilled water circuits where ductwork clearances dominate.
- Cartridge:Insert-style bodies thread directly into manifold blocks, serving OEM hydraulic systems and compact beverage dispensing equipment.
Swing check valves anchor the volume base across municipal infrastructure while diaphragm variants gain share at the steepest rate in food-grade process specifications.
Material:
Cost tier stratification separates commodity cast iron from premium duplex stainless grades, with mid-range bronze and brass alloys losing ground to regulatory-driven substitution mandates.
- Stainless Steel:316L and 304 grades dominate desalination intake structures and chemical process lines where chloride exposure would destroy lesser alloys. Nickel price volatility on the London Metal Exchange compresses margins unpredictably.
- Cast Iron:Gray and ductile iron bodies serve bulk water transmission mains where internal epoxy linings protect against graphitic corrosion. Foundry concentration in China and India exposes Western assemblers to shipping disruptions.
- Bronze:Leaded alloys face phased elimination under EPA drinking water contact standards, forcing rapid qualification of bismuth or silicon substitutes.
- Alloy Steel:Chrome-molybdenum grades withstand superheated steam conditions in thermal power generation facilities.
- Brass:Dezincification-resistant formulations persist in small-diameter residential plumbing where lead-free compliance is mandatory.
- PVC:Thermoplastic bodies serve corrosive chemical handling and irrigation systems where metallic corrosion is unacceptable.
Cast iron underpins the installed base by sheer tonnage while stainless steel climbs fastest in specification frequency across coastal and chemical applications.
Application:
Customer type concentration distinguishes utility capital projects with decade-long procurement cycles from industrial maintenance purchases driven by emergency replacement needs.
- Water Treatment:Filtration backwash prevention and pump protection across municipal plants and desalination facilities. China's state-backed coastal projects generate concentrated bulk orders for large-diameter variants.
- Power Generation:Boiler feedwater and cooling water circuits in combined-cycle and nuclear facilities. ASME Section III certification requirements create 18-36 month qualification barriers for nuclear-grade suppliers.
- Chemical Processing:Aggressive fluid containment in sulfuric acid and caustic handling systems where material selection determines service life.
- Food & Beverage:Clean-in-place compatibility and 3-A sanitary standards govern dairy, brewing, and bottled water installations.
- HVAC Systems:Chilled and hot water distribution in commercial buildings where butterfly valve substitution threatens standalone check valve placement.
- Pulp & Paper:Black liquor and stock flow handling in kraft mills with severe erosion conditions.
Water treatment commands the largest absolute procurement volume while power generation exhibits the steepest expansion trajectory in nuclear and renewable thermal segments.
End User Industry:
Geographic procurement concentration clusters demand in coastal China desalination zones, Saudi giga-project construction corridors, and Indian rural water distribution networks.
- Municipal Facilities:City water departments and regional wastewater authorities executing infrastructure renewal programs. Australian and Canadian centralized procurement agencies negotiate framework agreements spanning hundreds of treatment facilities.
- Petrochemical Plants:Refinery and olefins complex operators specifying API-certified valves for hydrocracker and reformer unit protection.
- Energy Facilities:Combined-cycle, nuclear, and renewable thermal operators with divergent material requirements by steam condition.
- Beverage Manufacturers:Bottled water, soft drink, and brewing operations demanding sanitary design with full material traceability.
- Paper Mills:Integrated pulp and paper producers in Scandinavia and Southeast Asia with severe service conditions.
- Heating Contractors:Commercial and residential mechanical contractors installing packaged hydronic systems.
Municipal facilities provide the foundational demand volume while energy facilities expand most quickly in nuclear certification and renewable thermal applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian municipal buyers exhibit acute price sensitivity on small-diameter brass valves, while Saudi desalination operators absorb premium duplex stainless steel pricing without volume elasticity. Chinese state procurement sits between these poles, negotiating bulk discounts on cast iron swing variants while specifying corrosion-resistant alloys for coastal exposure.
United States
EPA Lead and Copper Rule revisions are forcing system-wide bronze replacement cycles across 50,000 municipal water systems. The agency's updated drinking water contact standards are disqualifying legacy leaded alloys from new installations. Texas and California water districts are consolidating vendor lists under multi-year framework agreements that bundle installation supervision with extended parts availability.
China
State-backed desalination expansion along the eastern seaboard is generating concentrated demand for large-diameter cast iron swing check valves with internal epoxy linings. MIIT-funded coastal water treatment facilities in Shandong and Jiangsu provinces are specifying GB/T-certified alloy steel variants for high-salinity corrosion resistance. Foundry capacity concentration in Hebei and Shanxi provinces exposes Western assemblers to shipping disruptions during port congestion.
Germany
REACH regulation amendments are restricting chromium VI compounds in valve surface treatment processes, forcing conversion to trivalent chromium or citric acid passivation alternatives. Municipal procurement specifications in Bavaria and North Rhine-Westphalia now require full material safety data sheet disclosure of all surface chemistry. German beverage manufacturers are specifying diaphragm variants with EPDM membranes to satisfy sanitary process line requirements.
Saudi Arabia
NEOM and Red Sea giga-project construction schedules are creating demand for seawater-resistant duplex stainless steel check valves in desalination and district cooling infrastructure. The Kingdom's sovereign wealth-funded development corridors are specifying API-certified alloy steel valves for thermal power integration. Eastern Province industrial cities are consolidating procurement under centralized agencies that negotiate lifecycle cost guarantees rather than unit pricing.
India
Jal Jeevan Mission rural water supply deployment is distributing millions of small-diameter plastic and brass check valves through village-level distribution networks previously unserved by formal suppliers. BIS certification requirements are filtering out uncertified local fabricators from national procurement tenders. Maharashtra and Gujarat state water authorities are executing infrastructure renewal programs with budget constraints that favor dezincification-resistant brass over stainless steel for residential plumbing connections.
Global Check Valve Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive foundry operations separating margin-sustainable incumbents from outsourced-assembly competitors. The upper tier controls metallurgy certification and API-grade production capacity, while mid-scale fabricators compete on municipal specification compliance and regional distribution density. Strategic archetypes include vertically integrated valve specialists, foundry-dependent regional assemblers, and diversified industrial conglomerates with fluid control divisions. Dominant competitive moves involve nuclear-grade certification investments and direct utility framework agreements that disintermediate traditional distributor channels.
Within the integrated industrial tier, Emerson Electric Co. and Flowserve Corporation exemplify captive casting capabilities that lock in municipal utility contracts through metallurgy lab certification and API-grade alloy steel production. Velan Inc. occupies a premium positioning anchored by nuclear-grade manufacturing credentials that command extended qualification timelines and corresponding price premiums in energy facility procurement. Among diversified industrial conglomerates, Eaton Corporation and Bosch Rexroth sit within broader power management and hydraulics portfolios where check valve production leverages shared distribution infrastructure across complementary fluid control product lines.
| Leading Market Players |
|---|
| Eaton Corporation |
| Bosch Rexroth |
| Emerson Electric Co. |
| Curtiss-Wright Corp. |
| Velan Inc. |
| Flowserve Corporation |
| Schlumberger |
| AVK Holding A/S |
| Crane Co. |
| Others |
Supply & Pricing Matrix
Foundry capacity utilization above 85% in Hebei and Shanxi provinces compresses margin buffers for Western assemblers while elevating price floors on gray and ductile iron castings. This scale concentration simultaneously locks in supply-side bargaining power for integrated incumbents and forces procurement officers to absorb commodity volatility or qualify alternative metallurgy sources.
Pricing Analysis
After-market parts availability contracts and predictive maintenance subscriptions now drive lifetime value capture beyond initial unit sales. Three-tier pricing structure across nuclear-certified premium, API-grade standard, and municipal-economy levels separates ASME Section III suppliers from commodity foundries. Cost compression in stainless steel 316L product lines is intensifying because London Metal Exchange nickel pricing swings unpredictably. Municipal utilities in Texas and California exhibit acute price sensitivity on large-diameter cast iron orders, while Saudi desalination operators absorb duplex stainless premiums without volume elasticity.
Supply Chain Analysis
Strait of Malacca transit congestion and Red Sea routing disruptions expose just-in-time foundry shipments to 3-4 week delays that cascade through project schedules. Gray and ductile iron casting supply concentrates in China and India, with secondary stainless steel forging capacity anchored in Germany and Japan. Raw material procurement draws from nickel ore processing in Indonesia, molybdenum concentrate from Chile, and scrap metal recovery networks across North America. Tariff exposure on Chinese cast iron imports into the United States creates margin pressure for outsourced assemblers lacking captive metallurgy capabilities. Distribution runs through direct manufacturer framework agreements with Australian and Canadian centralized procurement agencies, bypassing traditional distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Municipal procurement consolidation across Australian and Canadian centralized agencies shifts buyer power toward lifecycle cost guarantees rather than unit pricing, fragmenting vendor lists to 3-5 approved suppliers per region.
For Market Incumbents: Shield municipal utility relationships through captive foundry operations that guarantee lead times during shipping disruptions, while accelerating ASME Section III nuclear certification investments to defend against Velan Inc.'s premium positioning. Lock in multi-year parts availability commitments that distributor channels cannot underwrite, converting transactional sales into recurring revenue streams. For New Entrants and Emerging Players: API certification fast-track programs offer the most penetrable entry point into petrochemical maintenance cycles, where incumbent qualification timelines stretch 18-36 months. Target India's Jal Jeevan Mission rural distribution networks with BIS-certified brass and thermoplastic valves, leveraging price sensitivity gaps left by stainless steel specialists. Pursue OEM cartridge valve partnerships for compact beverage dispensing equipment where sanitary design specifications favor agile prototyping over foundry scale. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among nuclear-grade manufacturers with 10-year parts availability contracts and predictive maintenance sensor integration. Long-term viability over a 5-10 year window favors acquisition targets with captive casting operations and in-house metallurgy labs rather than outsourced-assembly competitors exposed to commodity volatility. Monitor EPA drinking water contact standard evolution as the signal to watch for material substitution inflection that would accelerate bronze replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Nuclear Certification Investment | ASME Section III qualification creates 18-36 month barriers that sustain premium pricing in energy facilities. |
| IoT Sensor Integration | Pressure transmitter embedding enables predictive maintenance contracts with industrial facility operators. |
| Direct Utility Framework Agreements | Australian and Canadian centralized procurement consolidation disintermediates traditional distributor channels. |
| Lead-Free Alloy Qualification | EPA Lead and Copper Rule compliance accelerates material substitution toward bismuth and silicon bronze substitutes. |
| Additive Manufacturing Prototyping | Laser powder bed fusion compresses development cycles for topology-optimized valve bodies in aerospace specifications. |
Research Methodology
The analysis maps swing check valve, diaphragm valve, and cartridge valve sub-sectors, each validated through municipal procurement officers, petrochemical maintenance directors, and nuclear facility engineering leads. Primary interviews with foundry operations managers, OEM procurement teams, and aftermarket service heads combined with secondary validation against customs trade data, ASME certification registries, and EPA enforcement records. Bottom-up unit shipment estimates triangulated against top-down infrastructure spending projections across water treatment, power generation, and chemical processing end uses.
Consistency checks validated volume and value outputs against external benchmarks including MIIT-funded project disclosures, Saudi sovereign wealth development announcements, and Indian Jal Jeevan Mission deployment reports. The analytical framework models product type, material grade, application severity, and end-user industry segmentation across the projection horizon. CAGRs derive from regression analysis of historical procurement cycles correlated with regulatory compliance deadlines and infrastructure investment waves. Industry-specific forecast inputs include London Metal Exchange nickel price scenarios and ASME Section III certification queue lengths.
Underlying assumptions cover continued EPA Lead and Copper Rule enforcement, sustained China state-backed desalination funding, and stable foundry capacity utilization in Hebei province, with deviation risk concentrated in nickel commodity spikes and Red Sea logistics disruptions. Practitioners should keep alternative scenarios live as REACH surface chemistry amendments and India BIS certification expansion evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Vacuum Insulated Pipe Market
Valves
Pressure Reducing Valve Market
Valves
Safety Valve Test Benches Market
Valves
Blasting Stemming Plugs Market
Valves
Valve Driver Market
Valves
Global Valves in Chemical Market
Valves
Lined Valves Market
Valves
Global Stainless Steel Control Valves Market
Valves
Penstock Market
Valves
Hydraulic Diaphragm Valve Market
Valves
Dense Phase Vessels Market
Valves
Fluid Handling Systems Market
Valves
Pipeline and Process Services Market
Valves
Pressure Gauge Market
Valves
Emergency Shut Down Valves (ESDV) Market
Valves
Middle East and Africa Electro Hydraulic Servo Valve Market