
 North America Medical Devices Packaging Market | 2026-2036
North America Medical Devices Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
North America Medical Devices Packaging Market Foresight
Home care settings is realigning procurement priorities across the North America medical devices packaging landscape as patients shift procedures outside institutional walls. Amcor plc leverages its continental manufacturing footprint to serve this decentralized demand. Berry Global Inc. specializes in multi-layer sterile barrier films for portable diagnostic equipment. Sonoco Products Company anchors hospital supply chain relationships through dedicated cleanroom production facilities.
North America medical devices packaging encompasses engineered materials and sealed systems designed to maintain sterility, provide tamper evidence, and enable aseptic presentation of instruments and implants through processes such as thermoforming, extrusion coating, and ethylene oxide sterilization compatibility testing. Pouches and trays dominate unit volume, with pouches capturing the fastest trajectory in point-of-care diagnostics where compact footprint and peelability matter. Flexible packaging occupies concentrated margin pools in biologics and temperature-sensitive shipments, while rigid tray segments face price compression from commoditized orthopedic kit standards.
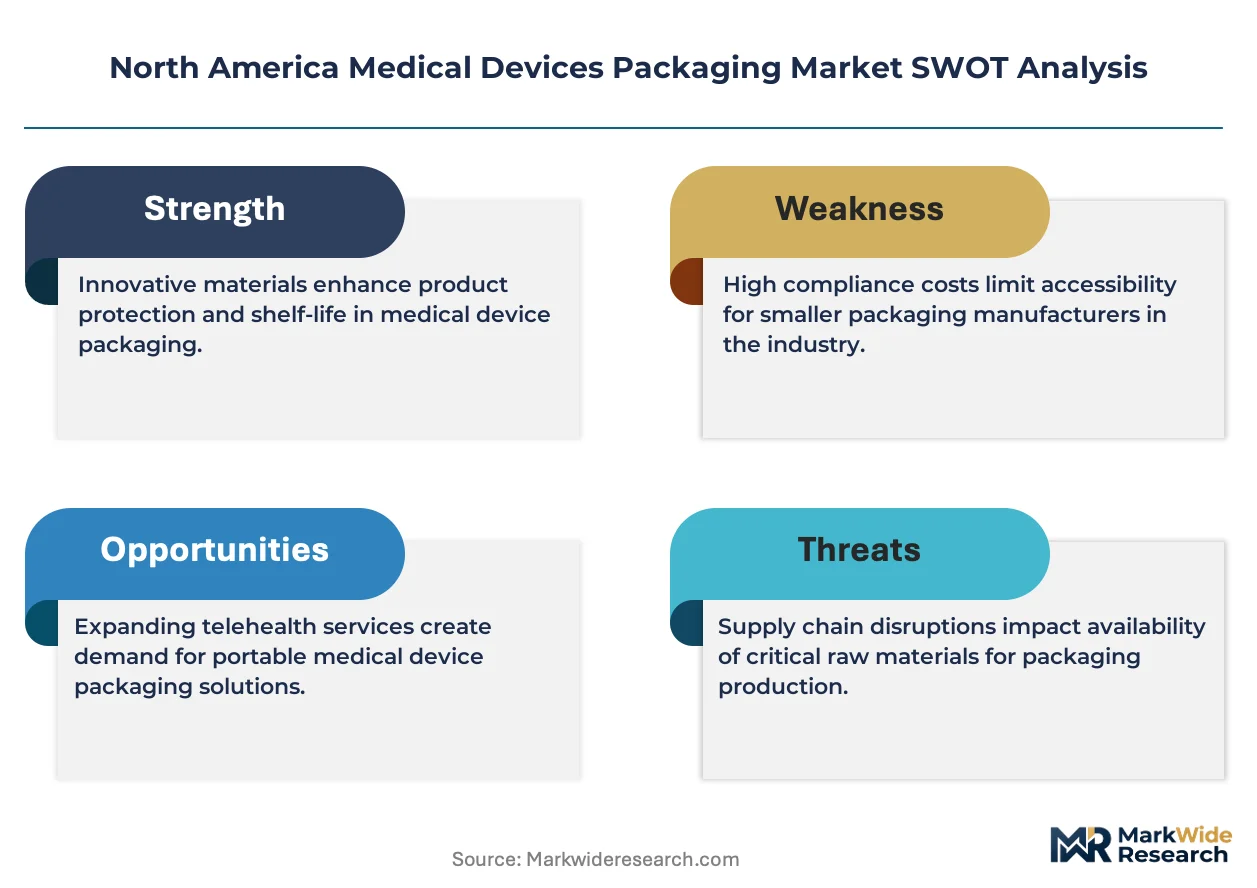
FDA enforces Quality System Regulation and sterility assurance levels that mandate validated packaging processes for Class II and III devices, directly elevating barrier material specifications and documentation burdens. ISO 11607 and ASTM F2097 provide complementary technical frameworks that harmonize with Health Canada and Mexican COFEPRIS requirements across the tri-national trade zone. Stakeholders must monitor evolving EPA per- and polyfluoroalkyl substance restrictions and their downstream impact on fluoropolymer-coated barrier films used in implantable device packaging.
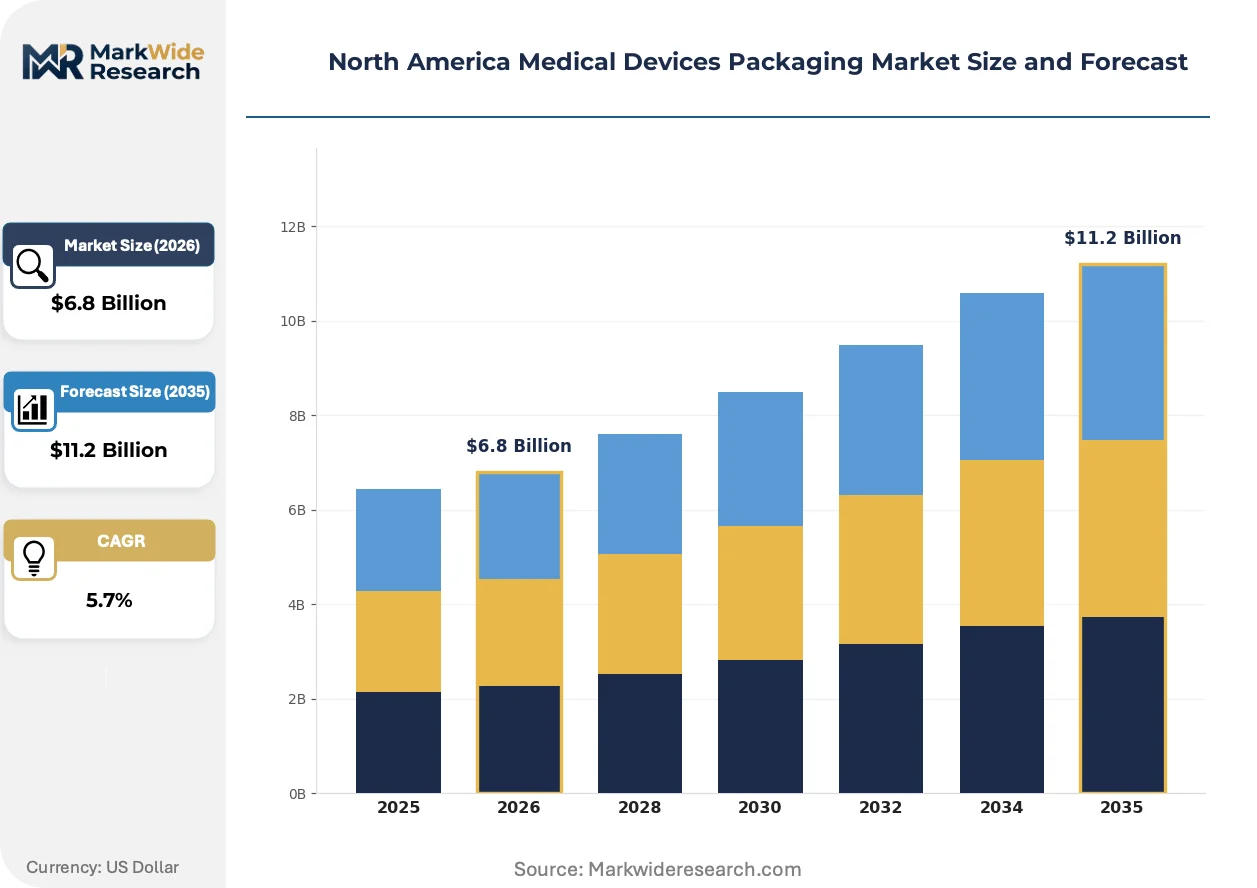
Market Dynamics
Home care migration is compressing hospital procurement volumes while fragmenting demand across thousands of decentralized points, forcing packaging suppliers to rebuild logistics networks around patient delivery rather than institutional bulk shipment.
Growth Catalysts
- ISO 11607 Revision Pressure:Updated validation protocols for sterile barrier systems are compelling manufacturers to upgrade material specifications and documentation capabilities, creating pull for engineered films with enhanced peelability and microbial resistance.
- Minimally Invasive Surgery Expansion:Procedure volumes in outpatient surgical centers are climbing, driving consumption of compact, procedure-matched pouches and trays designed for single-instrument sets rather than bulk kits.
- Biologics Cold Chain Requirements:Temperature-sensitive cell and gene therapies are demanding multi-layer flexible packaging with validated thermal protection, opening premium segments beyond traditional device packaging.
Market Restraints
- Fluoropolymer Feedstock Volatility:EPA restrictions on per- and polyfluoroalkyl substances are constraining availability of high-performance barrier coatings, forcing reformulation cycles and qualification delays.
- Ethylene Oxide Sterilization Capacity Concentration:Commercial sterilization services cluster in the US Midwest and Southeast, creating geographic bottlenecks and extended lead times for coastal manufacturers.
- Rigid Tray Commoditization:Standardized orthopedic kit formats have eroded pricing power, compressing margins for injection-molded tray producers serving high-volume implant distributors.
Strategic Opportunities
- Mexican Manufacturing Expansion:COFEPRIS regulatory harmonization with FDA standards is enabling nearshored production for US-bound medical devices, reducing cross-border logistics complexity.
- Smart Packaging Convergence:Integration of RFID tracking and temperature sensors into sterile barriers is creating value-added propositions for high-value implant shipments requiring chain-of-custody documentation.
- Home Infusion Therapy Growth:Self-administered biologic injections are demanding patient-friendly peel pouches with intuitive opening mechanics, opening design-led differentiation beyond clinical settings.
Industry Challenges
- Cleanroom Technician Scarcity:Validated packaging operations require personnel trained in ISO 14644 environments, with labor pools tightening in Midwest manufacturing corridors where demand concentrates.
- Dual Regulatory Qualification Burden:Simultaneous FDA 510(k) packaging validation and Health Canada MDL submissions are stretching regulatory affairs capacity, particularly for mid-sized device manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Medical Devices Packaging Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Trays, Pouches, Labels, Blister Packs Material: Plastic, Paper, Glass, Metal End User: Hospitals, Clinics, Laboratories, Home Care Packaging Type: Rigid Packaging, Flexible Packaging, Semi-Rigid Packaging, Others |
| Companies Covered | Amcor plc, DuPont de Nemours, Inc., Sonoco Products Company, 3M Company, West Pharmaceutical Services, Berry Global Inc., Klöckner Pentaplast Group, AptarGroup, Inc., WestRock Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Medical Devices Packaging Market Shifts & Advancements
Material science advances and regulatory precision are converging to redefine performance benchmarks, with sustainability pressures and digital traceability requirements layering onto traditional sterility assurance functions.
Tyvek medical packaging is integrating recycled content streams while maintaining microbial barrier performance, responding to hospital sustainability procurement mandates. Major health systems in California and New York are embedding environmental criteria into supplier scorecards, accelerating qualification of bio-based alternatives. This transition is compressing demand for conventional petroleum-derived nonwovens in premium segments.
FDA's updated guidance on sterilization process changes is forcing manufacturers to revalidate packaging compatibility with reduced ethylene oxide cycles. Device companies serving orthopedic and cardiovascular segments are conducting accelerated aging studies to demonstrate shelf-life equivalence under modified sterilization parameters. The agency's sterility assurance level requirements remain unchanged, tightening documentation burdens without relaxing technical thresholds.
Point-of-care diagnostic manufacturers are consolidating supplier relationships to reduce qualification overhead, favoring packaging partners with integrated sterile barrier and labeling capabilities. Large reference laboratories in Texas and Florida are streamlining inbound inspection by pre-approving vendor quality systems rather than lot-by-lot testing. This concentration pattern is displacing fragmented regional packaging distributors from high-volume accounts.
North America Medical Devices Packaging Market Segmentation
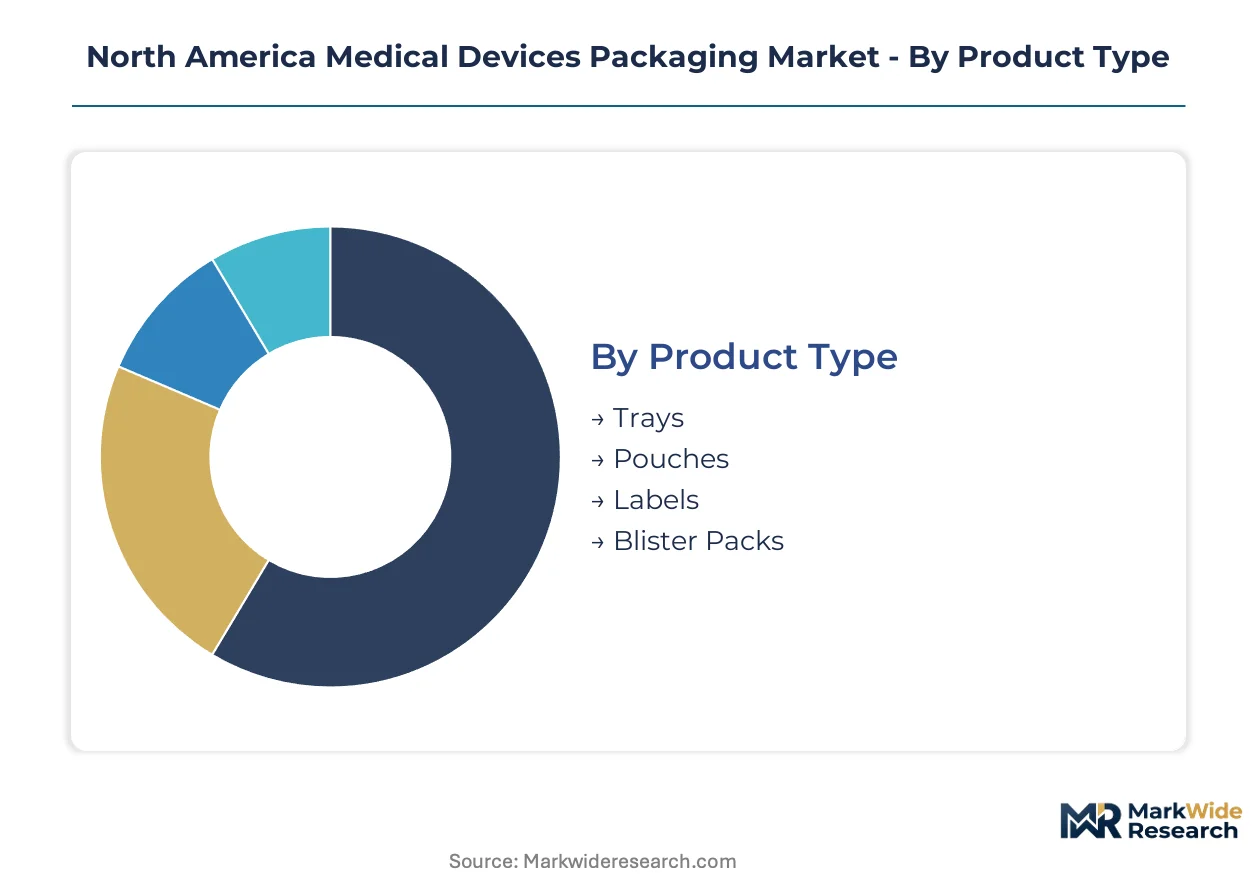
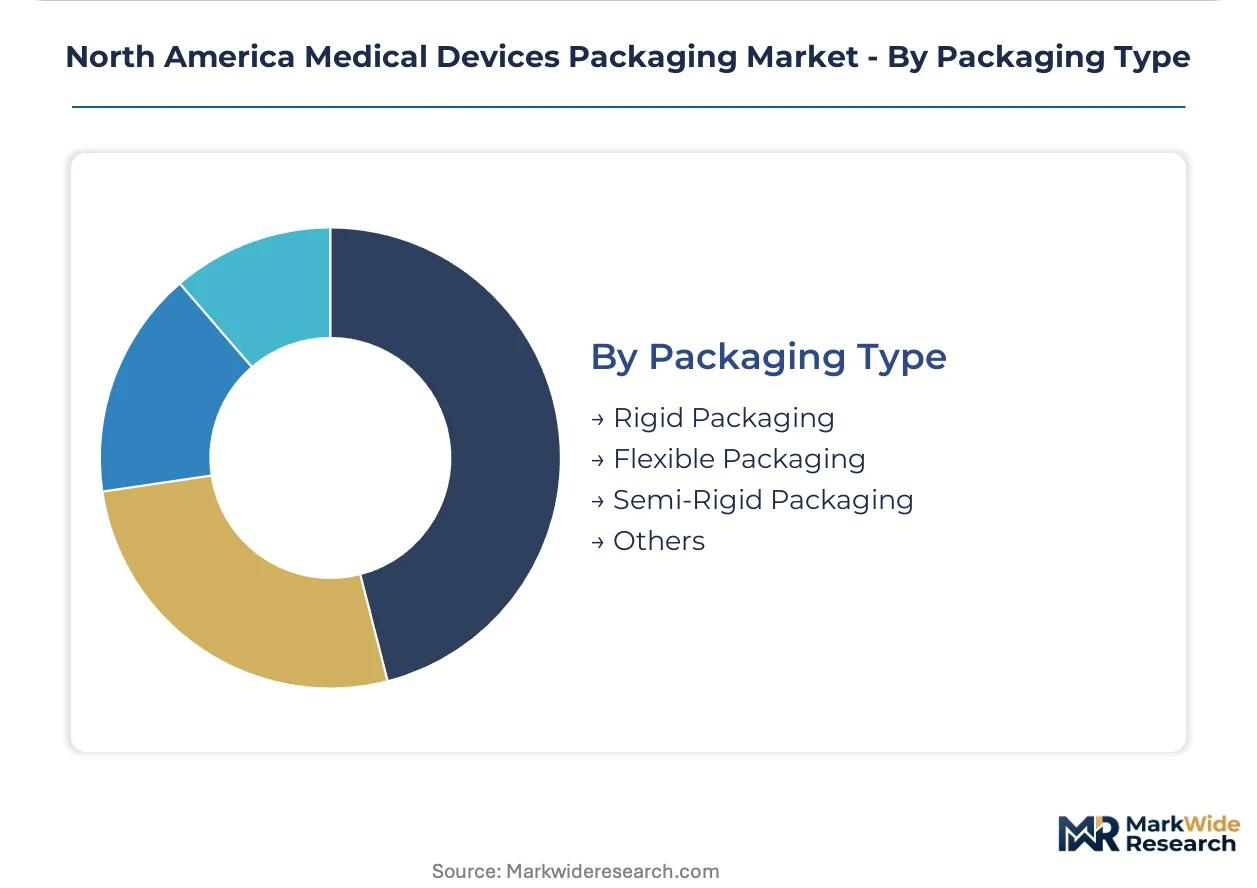
Packaging specifications in North America medical devices diverge sharply by sterilization compatibility, barrier performance, and point-of-use requirements. Each segment category reflects distinct technical validation protocols and procurement economics that shape supplier positioning across the value chain.
Product Type:
Functional demands around sterile presentation and aseptic opening mechanics define competitive differentiation across product formats.
- Trays:Injection-molded or thermoformed polymer structures with lidding films provide dimensional protection for complex instrument geometries. Demand concentrates in orthopedic kit packaging across the US Midwest manufacturing corridor, where sterilization service proximity reduces logistics costs for high-volume implant distributors.
- Pouches:Multi-layer flexible barriers with peelable seals dominate single-instrument and diagnostic applications. Compact footprint requirements in point-of-care settings across Texas and Florida are driving specification upgrades for microbial resistance and intuitive opening mechanics.
- Labels:Pressure-sensitive and in-mold varieties integrate sterilization indicators and regulatory markings directly onto primary packaging surfaces.
- Blister Packs:Thermoformed cavities with foil or film backing serve small-device and pharmaceutical-device combination products.
Trays lead on scale; pouches lead on momentum.
Material:
Cost tiers separate commodity substrates from engineered barriers with validated sterilization compatibility.
- Plastic:Polyethylene, polypropylene, and polyester films dominate through thermoforming and extrusion coating versatility. FDA sterility assurance requirements for Class II and III devices are elevating specification grades for multi-layer coextrusions in cardiovascular and orthopedic segments.
- Paper:Medical-grade kraft and Tyvek nonwovens provide breathable microbial barriers for ethylene oxide and gamma sterilization cycles. California and New York health system sustainability mandates are accelerating qualification of recycled-content streams.
- Glass:Borosilicate and soda-lime varieties serve parenteral device and diagnostic reagent containment with inert chemical properties.
- Metal:Aluminum foils and stainless-steel enclosures address high-barrier pharmaceutical-device combinations and reusable surgical instrument cases.
Plastic dominates volume economics; paper is gaining share fastest on sustainability procurement shifts.
End User:
Customer type determines packaging complexity, with institutional buyers prioritizing standardization and home settings demanding patient-centric designs.
- Hospitals:Centralized procurement of bulk sterile barrier systems for surgical services and sterile processing departments.
- Clinics:Outpatient surgical centers require procedure-matched pouches and compact trays for minimally invasive volumes.
- Laboratories:Reference labs in Texas and Florida are consolidating supplier relationships to reduce inbound inspection overhead.
- Home Care:Self-administered biologic injections and portable diagnostics demand intuitive peel mechanics and compact footprint designs. Decentralized point-of-care expansion across the United States is fragmenting demand across thousands of patient delivery endpoints.
Hospitals anchor procurement volume; home care is expanding most quickly.
Packaging Type:
Structural rigidity correlates with protection requirements and margin pools, with flexibility commanding premium positioning in temperature-sensitive applications.
- Rigid Packaging:Injection-molded and thermoformed trays and containers provide structural protection for delicate instruments. Standardized orthopedic kit formats have compressed pricing power in high-volume segments.
- Flexible Packaging:Multi-layer films and pouches offer lightweight barrier protection with minimal material usage. Biologics cold chain requirements for cell and gene therapies are opening premium segments with validated thermal protection specifications.
- Semi-Rigid Packaging:Hybrid structures combining thermoformed bases with flexible lidding balance protection and material efficiency.
- Others:Specialty formats including vacuum skin packaging and form-fill-seal systems for automated production lines.
Flexible packaging leads on margin expansion; rigid formats retain volume concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints as manufacturers exploit cost-of-compliance gaps between FDA stringency and COFEPRIS harmonization protocols. Mexico's nearshoring advantages are pulling sterile barrier assembly southward while Midwest sterilization infrastructure anchors final packaging stages in the United States.
United States
Home infusion therapy expansion and outpatient surgical center proliferation are fragmenting demand across decentralized endpoints. FDA sterility assurance level requirements for Class II and III devices mandate validated packaging processes that elevate documentation burdens. The Midwest manufacturing corridor from Minneapolis through Chicago concentrates ethylene oxide sterilization capacity and cleanroom production facilities serving orthopedic implant distributors.
Canada
Health Canada MDL submission requirements and provincial health system procurement centralization are consolidating supplier relationships. ISO 11607 alignment with FDA standards enables cross-border qualification efficiencies for manufacturers serving both markets. The Greater Toronto Area anchors medical device packaging operations with proximity to Detroit-Windsor logistics corridors.
Mexico
COFEPRIS regulatory harmonization with FDA protocols is accelerating nearshored production for US-bound medical devices. Labor cost advantages and USMCA trade facilitation are attracting sterile barrier assembly operations. The Bajío Region and Nuevo León are developing medical device manufacturing clusters with validated packaging capabilities for cardiovascular and diagnostic segments.
North America Medical Devices Packaging Market Competitive Landscape
Capacity expansion dominates the current landscape as suppliers rebuild logistics networks around patient delivery rather than institutional bulk shipment. The market structure consolidates around integrated material science conglomerates with continental manufacturing footprints and specialized sterile barrier film producers. Three archetypes define positioning: diversified packaging conglomerates with healthcare verticals, pure-play medical barrier specialists, and diversified industrial manufacturers with medical divisions. Geographic expansion into Mexican manufacturing zones and portfolio diversification into smart packaging with RFID integration represent the dominant competitive moves.
Among diversified packaging conglomerates, Amcor plc and Berry Global Inc. exemplify the scale-driven archetype with continental manufacturing footprints serving decentralized home care demand. Sonoco Products Company represents the hospital supply chain anchor position through dedicated cleanroom production relationships. These three entities illustrate how market participants are repositioning around regulatory harmonization advantages and sustainability procurement mandates from major health systems.
| Leading Market Players |
|---|
| Amcor plc |
| DuPont de Nemours, Inc. |
| Sonoco Products Company |
| 3M Company |
| West Pharmaceutical Services |
| Berry Global Inc. |
| Klöckner Pentaplast Group |
| AptarGroup, Inc. |
| WestRock Company |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up sterile barrier specialists anchor supply consolidation across the Midwest manufacturing corridor, translating geographic sterilization proximity into pricing discipline that resists coastal competitors lacking ethylene oxide access.
Pricing Analysis
Distributor margin layers absorb 12-18 points before hospital procurement committees, compressing manufacturer net realization on standardized orthopedic trays while premium biologics pouches command direct-to-OEM contract structures with volume-scaled rebates. FDA sterility assurance tiering separates validated multi-layer films from commodity single-barrier alternatives, with ISO 11607 documentation burdens adding qualification premiums. Cost compression in rigid tray segments intensifies as Mexican nearshoring erodes Midwest labor arbitrage. Home care settings prove least price-sensitive, prioritizing intuitive peel mechanics over per-unit cost.
Supply Chain Analysis
Freight cost differentials between coastal device manufacturers and Midwest sterilization hubs add 8-12% landed cost penalties, reinforcing concentration of final packaging stages in Illinois, Indiana, and Ohio. Raw material flows draw from Texas Gulf Coast polyethylene producers, Canadian kraft pulp mills for Tyvek substrates, and domestic fluoropolymer compounders facing EPA feedstock restrictions. Single-source vulnerability concentrates in ethylene oxide sterilization capacity clustered around Chicago and Minneapolis. Distribution runs through hospital GPO contracts and direct-to-home infusion pharmacy networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
COFEPRIS-FDA regulatory harmonization creates a geographic-arbitrage play where Mexican assembly labor costs 40-60% below Midwest equivalents while maintaining US market access under USMCA provisions.
For Market Incumbents: Cement sterile barrier validation capabilities as moats against Mexican nearshored entrants by investing in ISO 11607 documentation automation and captive ethylene oxide sterilization capacity. Vertical integration into fluoropolymer-alternative film R&D addresses EPA feedstock volatility threatening barrier coating supply. Channel control through GPO sole-source contracts locks out regional packaging distributors consolidating around Texas and Florida laboratory accounts. For New Entrants and Emerging Players: Home infusion therapy distributors represent the most penetrable channel partner type for patient-friendly pouch designs lacking incumbent relationships with hospital sterile processing departments. Target decentralized point-of-care diagnostics in secondary US metros where qualification overhead has displaced fragmented regional suppliers. Go-to-market angle: pre-validated sterile barrier-plus-labeling integrated systems that reduce inbound inspection burden for reference laboratories. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap sterile barrier film producers lacking Mexican manufacturing footprints or smart packaging RFID capabilities. Long-term viability over a 5-10 year window hinges on sustainability credentialing as California and New York health systems embed environmental criteria into supplier scorecards. Signal to watch: EPA per- and polyfluoroalkyl substance enforcement actions accelerating fluoropolymer-alternative qualification timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Mexican Manufacturing Footprint Expansion | COFEPRIS harmonization enables USMCA-accessible cost arbitrage for sterile barrier assembly. |
| Smart Packaging RFID Integration | Temperature sensor embedding captures premium positioning in high-value implant chain-of-custody documentation. |
| Fluoropolymer-Alternative Film Development | EPA restriction compliance secures barrier coating supply continuity for implantable device packaging. |
| Home Care Pouch Design Specialization | Intuitive peel mechanics open differentiation beyond institutional procurement standardization. |
| GPO Contract Consolidation | Sole-source sterile processing agreements displace fragmented regional packaging distributors. |
Research Methodology
Bottom-up home care setting modeling reconciled against top-down sterile barrier film production tracking forms the analytical core. Primary interviews with hospital purchasing committee chairs, GPO contracts managers, biomedical engineers, and sterile processing department heads combined with secondary validation against FDA 510(k) packaging submissions, Health Canada MDL databases, hospital procurement records, and COFEPRIS registration filings. Triangulation across these sources anchors volume estimates.
Historical trendline analysis of ethylene oxide sterilization capacity expansion and Tyvek substrate pricing informed projection frameworks across the analysis window. Segmentation dimensions modeled include product type, material grade tier, end-user setting, and sterilization compatibility protocol. CAGRs derived from curve-fitting against validated packaging process adoption rates and biologics cold chain expansion trajectories. Forecast inputs incorporate ISO 11607 revision implementation timelines and EPA per- and polyfluoroalkyl substance regulatory enforcement patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to fluoropolymer feedstock availability and Mexican regulatory harmonization durability. Forecasts reflect assumptions about sterilization capacity geographic distribution and sustainability procurement mandate diffusion across US health systems. A model refresh is warranted upon material change in EPA enforcement posture or COFEPRIS inspection protocol alignment with FDA standards.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices Packaging
Healthcare Packaging Market
Medical Devices Packaging
Global Medical Devices Packaging Market
Medical Devices Packaging
Asia-Pacific Parenteral Packaging Market
Medical Devices Packaging
Sterile Packaging Market
Medical Devices Packaging
Europe Medical Devices Packaging Market
Medical Devices Packaging
Global Custom Procedure Trays and Packs Market
Medical Devices Packaging
Syringe Trays Market
Medical Devices Packaging
Medical Processing Seals (MPS) Market
Medical Devices Packaging
Molded Pulp Clinical Packaging Market
Medical Devices Packaging
Europe Parenteral Packaging Market
Medical Devices Packaging
Medical Implants Sterile Packaging Market
Medical Devices Packaging
Bio-Medical Packaging Market
Medical Devices Packaging
Middle East and Africa Medical Devices Packaging Market
Medical Devices Packaging
Medical-Grade Foil Market
Medical Devices Packaging
Asia-Pacific Medical Devices Packaging Market
Medical Devices Packaging
Asia Pacific Blood Glucose Test Strip Packaging Market