
 Automotive Radar Applications Market | 2026-2036
Automotive Radar Applications Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Radar Applications Market Analysis
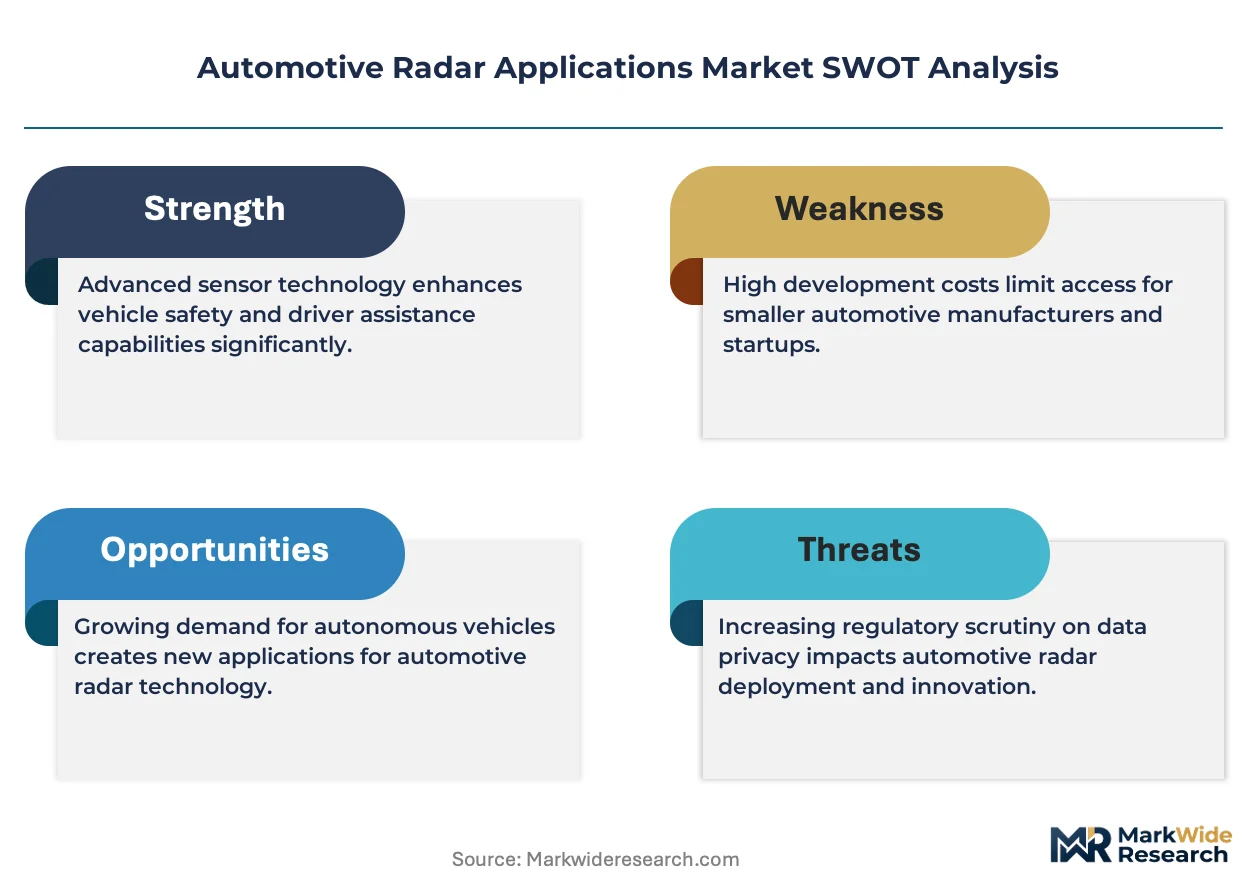
Silicon germanium is pivoting toward gallium nitride and advanced CMOS processes for radar front-end modules, cutting per-unit costs while extending detection range. Robert Bosch GmbH leverages in-house semiconductor capabilities to control chip supply for its sensor portfolio. Continental AG sustains R&D intensity across frequency-modulated continuous wave architectures. NXP Semiconductors dominates merchant silicon supply for tier-one radar module producers.
Automotive radar applications encompass radio-frequency sensing systems operating at 77-81 GHz that detect object range, velocity, and angle through transmitted and reflected electromagnetic waves, primarily enabling advanced driver-assistance systems and autonomous vehicle perception stacks. Frequency modulated continuous wave technology leads volume deployment due to its simultaneous range-velocity measurement capability and lower peak power requirements. Imaging radar represents the fastest-growing product category as automakers demand higher angular resolution for urban autonomous navigation. OEM end users anchor the value pool, though aftermarket suppliers occupy a growing niche in retrofit collision-avoidance kits for commercial fleets.
The European New Car Assessment Programme, the United States Federal Communications Commission, and the United Nations Economic Commission for Europe shape product standards through mandatory automatic emergency braking requirements and spectrum allocation rules. These frameworks compel radar module suppliers to certify for multi-regional electromagnetic compatibility and functional safety protocols. Stakeholders must monitor pending spectrum harmonization decisions and next-generation NCAP test protocol expansions that will redefine minimum sensor performance thresholds.
Market Dynamics
Frequency-modulated continuous wave architectures are displacing legacy pulse-Doppler systems as automakers demand simultaneous range-velocity measurement without the cost and complexity of multi-sensor fusion. This technology transition is compressing module prices while extending detection capabilities into urban autonomous navigation scenarios.
Growth Catalysts
- Euro NCAP Mandates:Automatic emergency braking requirements now extend to vulnerable road user detection, compelling OEMs to deploy corner radar and front-facing arrays across vehicle classes.
- 77-81 GHz Spectrum Harmonization:FCC allocations in the United States and aligned UNECE frameworks in Europe are accelerating single-chip CMOS radar deployment with wider bandwidth for finer resolution.
- Mid-Range Vehicle Penetration:Radar modules are migrating from luxury flagships into compact and mid-size passenger cars as semiconductor integration cuts per-unit costs.
Market Restraints
- Silicon Supply Concentration:Merchant gallium nitride and advanced CMOS wafer capacity concentrates among a handful of foundries, creating allocation risk during automotive demand surges.
- Electromagnetic Compatibility Certification:Multi-regional type approval for 77-81 GHz devices requires redundant testing cycles against FCC, ETSI, and ARIB standards, extending time-to-market.
- Lidar Cost Compression:Solid-state optical sensors are approaching price parity for certain highway automation functions, threatening radar's dominance in long-range detection.
Strategic Opportunities
- Imaging Radar Architectures:Dense antenna arrays and MIMO signal processing are enabling angular resolution below one degree, opening urban autonomous navigation applications previously reserved for camera-lidar fusion.
- Commercial Fleet Retrofit:Aftermarket collision-avoidance kits for logistics and construction vehicles represent an underpenetrated channel with lower certification barriers than OEM integration.
- UNECE ALKS Expansion:Automated lane-keeping system regulations are mandating redundant sensing, creating dual-radar configuration opportunities for highway automation tiers.
Industry Challenges
- RF System Design Talent:Scarcity of engineers with millimeter-wave circuit and antenna-in-package expertise is constraining module supplier expansion and inflating compensation costs.
- Functional Safety Certification:ASIL-B and ASIL-D compliance for radar perception stacks requires exhaustive failure-mode analysis, extending development timelines by 12-18 months.
- Legacy Vehicle Integration:Retrofitting 77-81 GHz sensors into older CAN bus architectures demands protocol translation layers that introduce latency and diagnostic complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Radar Applications Market |
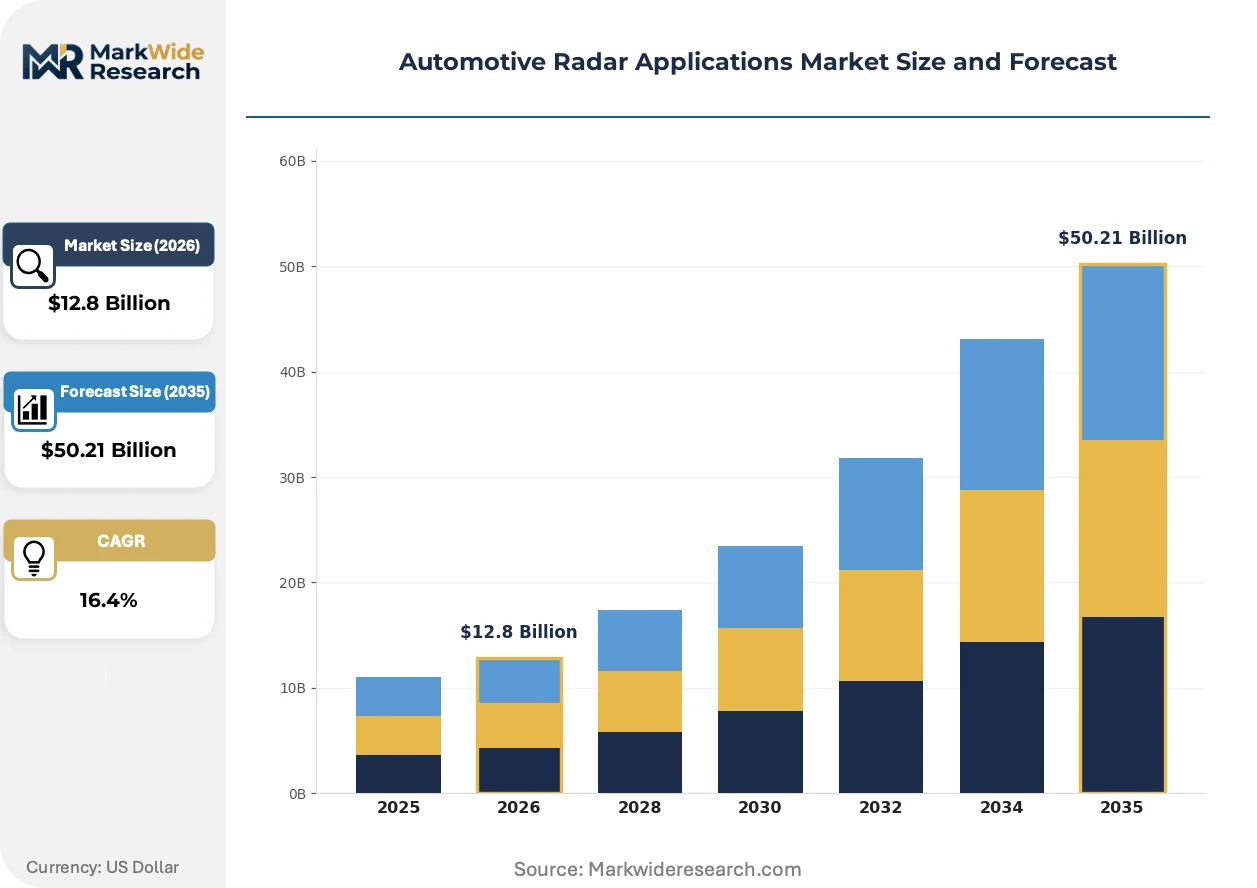
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $50.21 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Short-Range Radar, Medium-Range Radar, Long-Range Radar, Imaging Radar Technology: Frequency Modulated Continuous Wave, Pulsed Radar, Doppler Radar, Millimeter Wave Radar Application: Adaptive Cruise Control, Lane Change Assistance, Collision Avoidance, Parking Assistance End User: OEMs, Aftermarket Suppliers, Fleet Operators, Ride-Sharing Services |
| Companies Covered | Robert Bosch GmbH, Continental AG, Denso Corporation, Autoliv Inc., Valeo SA, Aptiv, NXP Semiconductors, Texas Instruments Incorporated, ZF Friedrichshafen AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Radar Applications Market Emerging Trajectories
Silicon process evolution and regulatory mandate expansion are converging to redefine radar module architecture and deployment patterns. Three developments are compressing cost structures while extending performance envelopes.
4D imaging radar is automating the perception stack for urban autonomous navigation. Dense MIMO antenna arrays generate point clouds with elevation data, eliminating the need for separate sensors in certain parking and low-speed scenarios. Tier-one module producers are sampling these devices to OEMs targeting Level 3 conditional automation.
UNECE Regulation 79 revisions are mandating enhanced sensor redundancy for automated steering functions. This framework compels dual-radar configurations with cross-validation protocols, directly increasing content per vehicle for highway automation tiers. German and Japanese OEMs are certifying integrated front-corner radar pairs to satisfy these requirements without lidar cost premiums.
Fleet operators are unbundling collision-avoidance procurement from OEM service contracts. Third-party retrofit specialists now source radar modules directly from merchant silicon vendors, bypassing traditional tier-one distribution channels. This pattern concentrates in North American and European commercial vehicle markets where insurance incentives reward aftermarket safety upgrades.
Automotive Radar Applications Market Segmentation
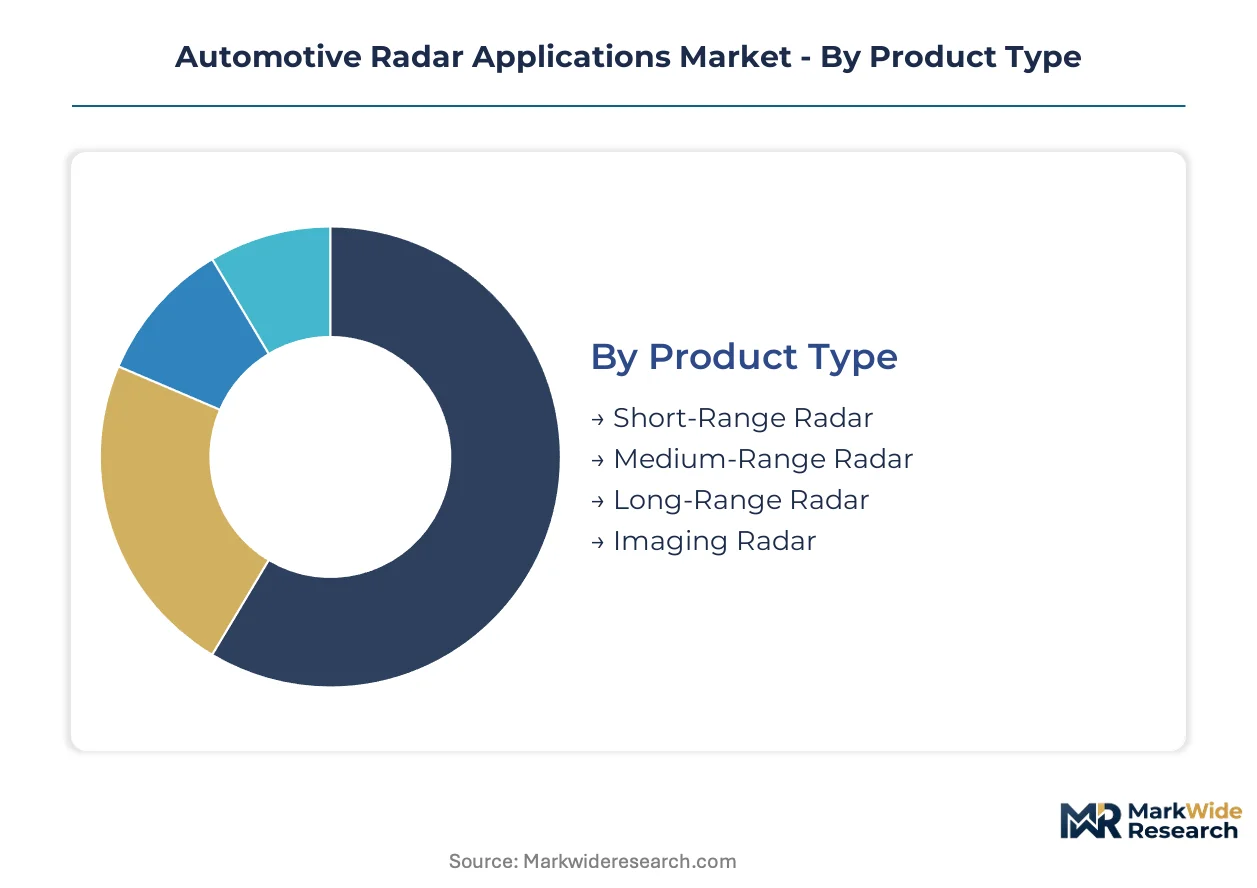
Automotive radar segmentation reflects divergent buyer priorities across vehicle classes and automation tiers. OEM procurement teams select range-performance combinations based on NCAP compliance requirements and sensor fusion architectures, while aftermarket channels prioritize retrofit compatibility and installation simplicity.
Product Type:
Cost tier drives selection, with automakers balancing detection range against semiconductor content and packaging complexity.
- Long-Range Radar:Front-facing modules detect objects beyond 200 meters using narrow beamwidth antennas and high-gain amplifiers. German and US OEMs specify these for highway adaptive cruise control on premium sedans and electric crossovers, constrained by thermal management requirements for sustained high-power operation.
- Imaging Radar:Dense MIMO antenna arrays generate elevation-resolved point clouds through coherent signal processing. Chinese EV manufacturers and German luxury brands are integrating these for urban autonomous navigation where angular resolution below one degree replaces camera-lidar fusion in certain scenarios.
- Short-Range Radar:Corner-mounted units with wide azimuth coverage enable blind-spot monitoring and cross-traffic alert functions.
- Medium-Range Radar:Mid-field detection modules bridge gap coverage for lane-change assistance and intersection collision warning.
Long-range radar leads on scale; imaging radar leads on momentum.
Technology:
Volume concentration follows CMOS process maturity, with foundry capacity allocation determining supply security for module producers.
- Frequency Modulated Continuous Wave:Simultaneous range-velocity measurement through chirp modulation eliminates Doppler ambiguity without multi-sensor fusion. This architecture dominates production volumes across Bosch, Continental, and Denso module portfolios, driven by lower peak power requirements and simplified signal processing chains.
- Millimeter Wave Radar:77-81 GHz operation exploits wider bandwidth allocations for finer range resolution and smaller antenna apertures. FCC and UNECE spectrum harmonization is accelerating single-chip CMOS implementations, with NXP and Infineon sampling integrated transceivers to tier-one suppliers.
- Pulsed Radar:Legacy time-of-flight architectures persist in certain commercial vehicle applications requiring extreme range.
- Doppler Radar:Velocity-only measurement systems occupy niche applications in traffic monitoring and speed enforcement.
Frequency modulated continuous wave commands installed base; millimeter wave radar climbs the fastest.
Application:
Functional safety certification requirements stratify procurement, with ASIL-rated systems commanding price premiums over convenience features.
- Collision Avoidance:Automatic emergency braking with vulnerable road user detection requires redundant sensor validation and sub-100 millisecond latency. Euro NCAP mandates are compelling deployment across vehicle classes in Germany, France, and Italy, with module suppliers certifying for pedestrian and cyclist recognition protocols.
- Adaptive Cruise Control:Longitudinal speed and distance maintenance functions integrate radar with camera fusion for stop-and-go traffic handling. US and Japanese OEMs specify these for mid-range sedans and crossovers, with semiconductor integration reducing module costs to enable compact vehicle penetration.
- Lane Change Assistance:Rear-quarter coverage with Doppler processing monitors adjacent vehicle approach rates.
- Parking Assistance:Short-range corner radar enables automated perpendicular and parallel parking maneuvers.
Collision avoidance leads on scale; adaptive cruise control leads on momentum.
End User:
Channel structure determines specification authority, with OEMs controlling sensor architecture versus aftermarket operators optimizing for installation speed.
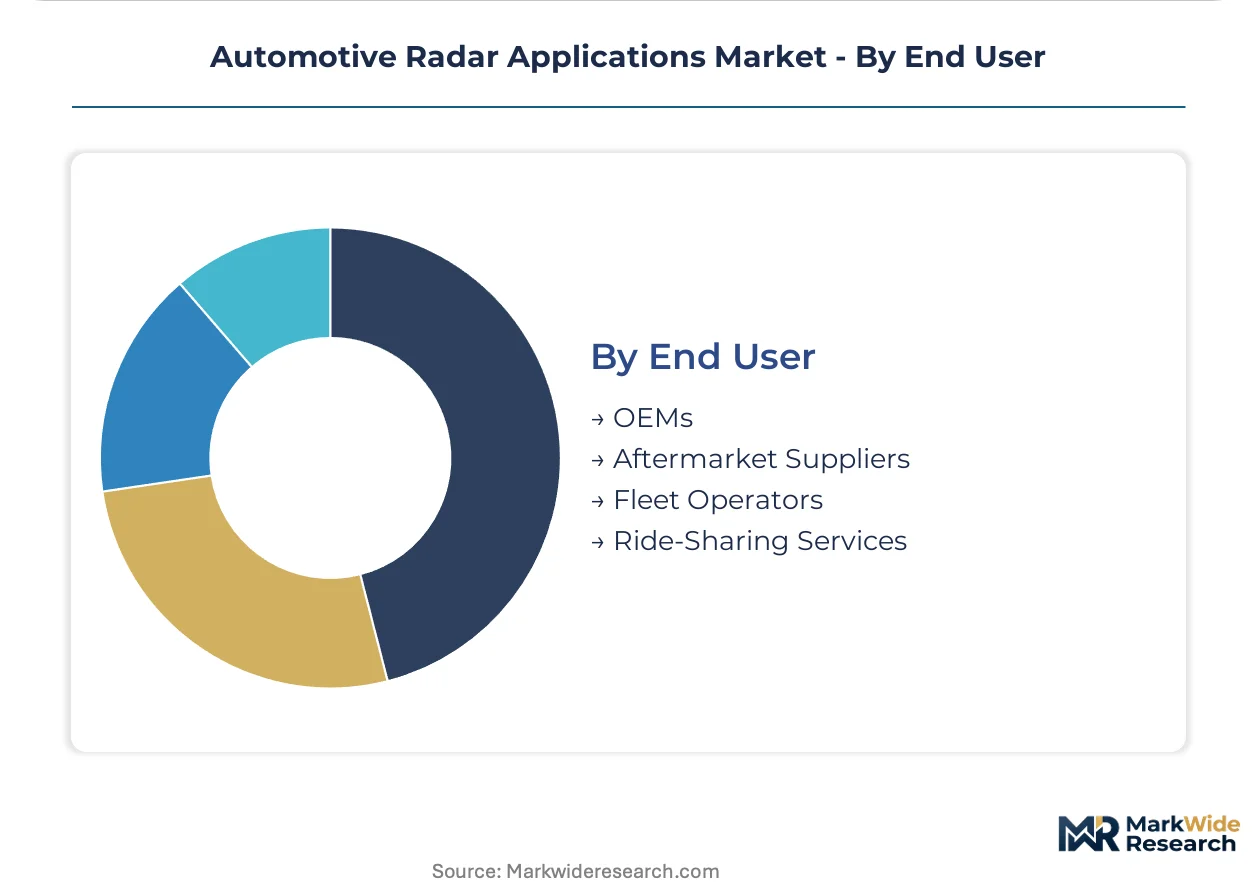
- OEMs:Vehicle manufacturers specify radar performance thresholds, mechanical packaging, and vehicle network integration during platform development. Volkswagen, Toyota, and General Motors source through tier-one module producers with multi-year supply agreements tied to production volume commitments.
- Fleet Operators:Logistics and construction vehicle owners procure retrofit collision-avoidance kits through direct merchant silicon relationships, bypassing traditional distribution. North American and European insurance incentive programs are accelerating adoption in heavy-duty trucking and municipal service fleets.
- Aftermarket Suppliers:Independent distributors serve retail consumers with universal-fit parking assistance and blind-spot monitoring systems.
- Ride-Sharing Services:Mobility fleet managers specify enhanced sensor suites for liability reduction in high-utilization vehicle deployments.
OEMs lead on scale; fleet operators lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart's automotive manufacturing corridor anchors radar module demand through dense OEM and tier-one supplier concentration. German production clusters drive frequency-modulated continuous wave adoption across premium and mid-range vehicle platforms.
United States
Detroit's automakers and Silicon Valley autonomous vehicle developers consume long-range radar for highway automation stacks. FCC spectrum allocations at 77-81 GHz accelerate single-chip CMOS deployment. Michigan's automotive corridor hosts validation facilities where tier-one suppliers certify modules for NHTSA safety mandates.
Germany
Bavarian and Baden-Württemberg OEMs specify imaging radar for urban autonomous navigation in premium electric vehicles. Euro NCAP's vulnerable road user detection requirements compel corner radar integration across compact and mid-size classes. Ingolstadt and Wolfsburg production lines source modules from captive semiconductor operations and merchant silicon vendors.
China
Shanghai and Shenzhen electric vehicle manufacturers drive imaging radar volume for Level 2+ automation. MIIT spectrum harmonization with UNECE frameworks enables 77-81 GHz module deployment. Yangtze River Delta production clusters host radar assembly operations serving domestic OEMs and export markets.
Japan
Nagoya-based automakers integrate medium-range radar for lane-change assistance and intersection collision warning. METI safety standards align with UNECE automated lane-keeping system regulations. Toyota City and Yokohama engineering centers co-develop frequency-modulated continuous wave architectures with tier-one module producers.
South Korea
Seoul Capital Area Hyundai-Kia production complexes deploy radar across mass-market electric crossovers. MFDS automotive safety guidelines and KATRI certification protocols govern electromagnetic compatibility testing. Hwaseong and Asan manufacturing plants source merchant silicon from domestic and German semiconductor suppliers.
Automotive Radar Applications Market Vendor Landscape
Strategic partnerships dominate the current landscape as module producers secure merchant silicon supply and foundry capacity. The vendor base concentrates among tier-one automotive suppliers with captive radar portfolios and semiconductor specialists supplying transceiver chips. Two archetypes prevail: vertically integrated automotive conglomerates controlling chip-to-module production, and fabless semiconductor designers partnering with tier-one system integrators. Capacity expansion and technology licensing represent the dominant competitive vectors as participants race to qualify 4D imaging radar for OEM platform awards.
Among German-based diversified suppliers, Robert Bosch GmbH and Continental AG exemplify the integrated archetype through in-house semiconductor capabilities and module assembly operations. NXP Semiconductors anchors the merchant silicon tier as a Netherlands-based semiconductor supplier whose radar transceivers populate tier-one module designs. These three entities occupy positions spanning the value chain from wafer fabrication through vehicle platform integration.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| Denso Corporation |
| Autoliv Inc. |
| Valeo SA |
| Aptiv |
| NXP Semiconductors |
| Texas Instruments Incorporated |
| ZF Friedrichshafen AG |
| Others |
Supply Flow & Price Mechanics
Captive semiconductor fabrication by Robert Bosch GmbH and Continental AG anchors both supply security and pricing power for tier-one radar module producers. This backward integration insulates integrated suppliers from foundry allocation shocks while merchant silicon vendors compete on die-shrink roadmaps and automotive qualification speed.
Pricing Analysis
Wafer cost pass-through from TSMC and GlobalFoundries governs module pricing trajectories across the automotive radar stack. Pricing stratifies across ASIL-D certified premium tiers, ASIL-B standard tiers, and non-safety economy tiers for aftermarket retrofits. Cost compression in imaging radar architectures is intensifying because Chinese EV manufacturers demand sub-hundred-dollar-per-unit pricing for Level 2+ sensor suites. Fleet operators exhibit highest price sensitivity due to thin commercial vehicle margins, while German luxury OEMs prioritize performance thresholds over unit economics.
Supply Chain Analysis
Domestic content mandates under China's MIIT localization requirements and India's phased manufacturing programs are reshaping sourcing patterns for radar assembly operations. Merchant CMOS wafer supply concentrates in Taiwan, South Korea, and the United States, with antenna-in-package substrates drawn from Japanese and German substrate specialists. Single-source vulnerability pervades gallium nitride foundry capacity for high-power front-end amplifiers. Distribution runs through tier-one module producers holding multi-year OEM platform awards, with aftermarket channels bypassing traditional distribution through direct merchant silicon relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive radar applications market compounds steadily as regulatory mandate expansion creates irreversible sensor content growth per vehicle. Euro NCAP protocol evolution and UNECE automated driving regulations institutionalize radar as mandatory safety infrastructure.
For Market Incumbents: Deploy ASIL-D certification investment as the primary defensive lever. Accelerate failure-mode analysis capabilities to compress development timelines threatened by functional safety bottlenecks. Secure multi-year foundry capacity reservations against gallium nitride allocation risk during automotive demand surges. Consolidate corner radar and front-facing array portfolios to capture dual-radar configuration mandates under UNECE Regulation 79.
For New Entrants and Emerging Players: Commercial fleet retrofit specialists represent the most penetrable buyer archetype for merchant silicon direct relationships. Target North American heavy-duty trucking and European municipal service fleets where insurance incentives accelerate aftermarket collision-avoidance adoption. Bypass tier-one distribution through direct sourcing agreements with NXP Semiconductors or Texas Instruments. Develop CAN bus protocol translation layers to solve legacy vehicle integration complexity that constrains incumbent solution architectures.
For Investors and Strategic Acquirers: Consolidation pressure builds where imaging radar development costs exceed standalone module producer balance sheet capacity. Frame long-term viability around 4D imaging radar qualification for urban autonomous navigation platforms. Acquire fabless semiconductor designers with millimeter-wave CMOS expertise and existing automotive qualification pathways. Watch FCC spectrum harmonization decisions with ARIB and ETSI as the critical inflection indicator for single-chip CMOS deployment acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Imaging Radar Platform Standardization | Reduces NRE costs for OEMs specifying Level 3 automation across multiple vehicle classes. |
| Merchant Silicon Supply Agreement | Locks wafer allocation for tier-one module producers facing foundry capacity constraints. |
| ASIL-D Certification Investment | Opens premium pricing tiers for collision avoidance systems under Euro NCAP mandates. |
| Fleet Retrofit Channel Development | Captures insurance-incentivized demand from North American logistics operators. |
| Antenna-in-Package Manufacturing Scale-Up | Enables dense MIMO array production for angular resolution below one degree. |
Methodological Framework
Bottom-up OEM platform modeling reconciled against top-down tier-one supplier production tracking forms the analytical core of this study. Primary interviews with radar module procurement directors, semiconductor product marketing managers, OEM platform engineers, and fleet safety managers inform demand-side assumptions. Secondary validation draws from FCC equipment authorization databases, UNECE regulatory filings, vehicle production registries, and tier-one supplier annual disclosures. Triangulation between end-use consumption patterns and supply-side capacity announcements ensures consistency across volume and value estimates.
Input-output matrices map semiconductor die supply through module assembly to vehicle platform integration across the projection horizon. Segmentation dimensions include radar range tier, technology architecture, functional safety certification level, vehicle class, and regional production cluster. CAGRs derive from regression analysis against historical content-per-vehicle trajectories and regulatory mandate implementation schedules. Forecast inputs incorporate NCAP protocol expansion timelines and spectrum harmonization milestones.
Underlying measurement precision varies by segment; imaging radar and long-range radar carry tighter precision than aftermarket short-range modules due to concentrated OEM disclosure patterns. Forecasts reflect assumptions regarding regulatory implementation speed and foundry capacity expansion schedules. Semiconductor allocation shocks, autonomous vehicle platform delays, and lidar cost breakthroughs represent primary revision triggers warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Seat Belt Pretensioner and Load Limiter Market
Automotive Safety and Security Systems
Automotive Pedestrian Protection System Market
Automotive Safety and Security Systems
Highway Crash Cushion Market
Automotive Safety and Security Systems
China Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
Automotive Seatbelt Market
Automotive Safety and Security Systems
Africa and Middle East Airbag Systems Market
Automotive Safety and Security Systems
Automotive Seat Belt Sensor Market
Automotive Safety and Security Systems
Smart Airbag Coats Market
Automotive Safety and Security Systems
Motorcycle Anti-Lock Braking System Market
Automotive Safety and Security Systems
Automatic Emergency Braking Market
Automotive Safety and Security Systems
Global Automotive Seat Belt Reminder Market
Automotive Safety and Security Systems
Automotive Anti-Lock Braking System Market
Automotive Safety and Security Systems
Automotive Mirror System Market
Automotive Safety and Security Systems
Automotive Keyless Entry System Market
Automotive Safety and Security Systems
Automotive Radar Market
Automotive Safety and Security Systems
Automotive Seat Belt System Market