
 Citrus Pulp Fiber Market | 2026-2036
Citrus Pulp Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
Citrus Pulp Fiber Market Analysis
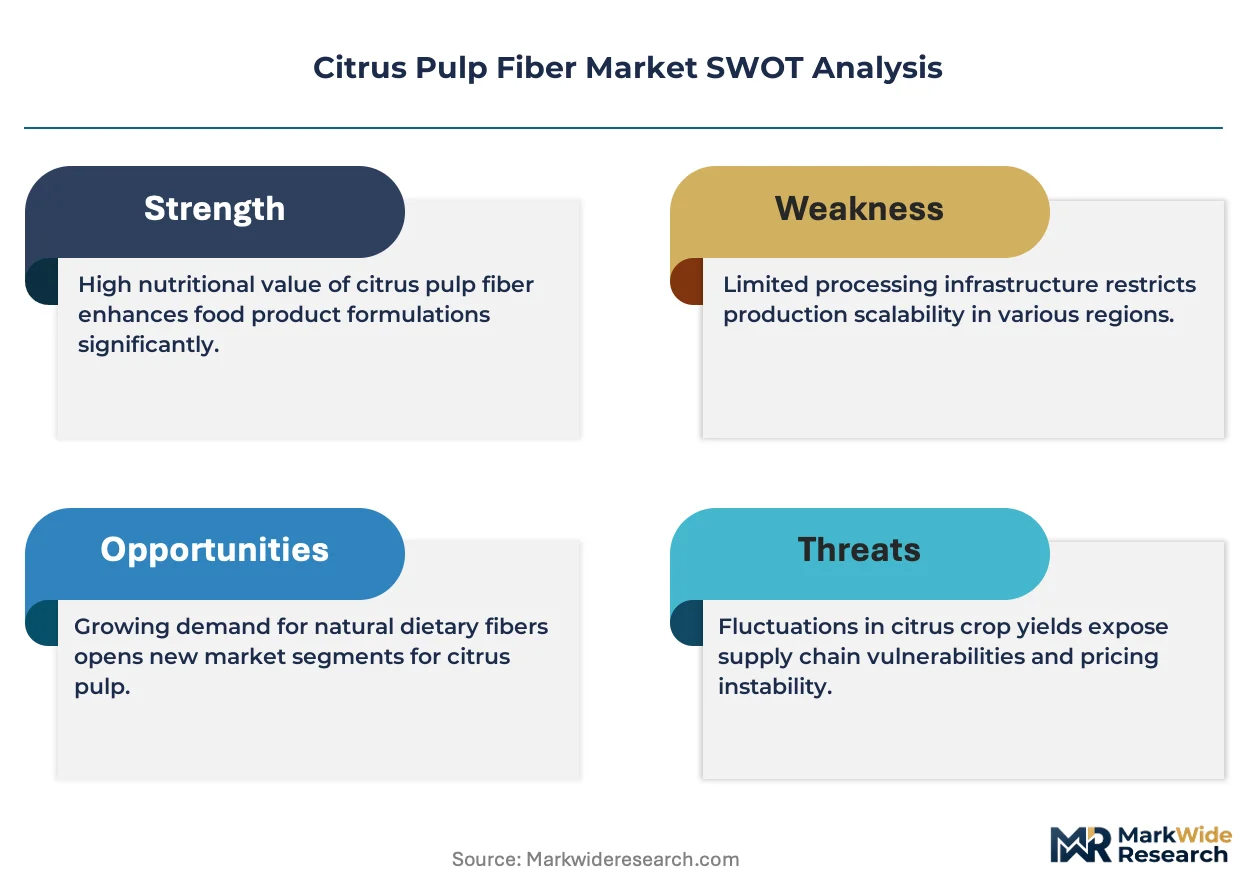
Organic certification under USDA NOP and EU Organic Regulation 2018/848 is reorganizing supplier eligibility, forcing citrus pulp fiber producers to demonstrate traceable, pesticide-free sourcing. Herbstreith & Fox GmbH leverages its German manufacturing base to sustain premium positioning in pharmaceutical-grade fiber. Fiberstar, Inc. anchors North American supply through citrus byproduct partnerships with Florida processors. Ceamsa competes on scale in pectin-adjacent fiber extraction, while Cargill, Incorporated controls global distribution through its integrated food ingredient platform.
Citrus pulp fiber consists of the lignocellulosic residue remaining after juice extraction, typically containing 60-75% dietary fiber with pectin, cellulose, and hemicellulose fractions that provide water-binding capacity and texture modification. Manufacturers dry and mill this byproduct into functional ingredients that replace synthetic stabilizers in reduced-fat and gluten-free formulations. Powder formats dominate food and beverage applications where dispersibility determines processing efficiency, while granules command premium placement in pet food applications requiring controlled hydration kinetics. The food and beverage segment leads absolute volume, though dietary supplement firms represent the fastest-growing end user channel as prebiotic fiber claims proliferate.
FDA GRAS self-determination and EFSA novel food assessments govern ingredient approval pathways, with Brazil's ANVISA and India's FSSAI adding registration complexity for imported fiber. REACH compliance in Europe and California's Proposition 65 labeling requirements shape contaminant testing protocols and documentation burdens for cross-border suppliers. Stakeholders must monitor evolving clean-label definitions and fiber quantification methodologies, as regulatory divergence between jurisdictions threatens to fragment formulation standards and complicate global product platform strategies.
Market Dynamics
Clean-label formulation mandates from EU Green Deal farm-to-fork targets are compressing synthetic hydrocolloid demand while redirecting procurement toward citrus byproduct recovery systems. Food manufacturers now face binding sustainability disclosure requirements that privilege traceable fiber sourcing over conventional stabilizers.
Growth Catalysts
- EU Green Deal compliance:Binding farm-to-fork sustainability targets force food manufacturers to replace synthetic hydrocolloids with recovered citrus fiber in bakery and beverage formulations.
- Prebiotic fiber claims:Dietary supplement firms are accelerating procurement of citrus pulp fiber to support gut health positioning in functional nutrition products.
- Brazil:Orange processing byproduct volumes in São Paulo state anchor export-grade fiber supply chain development for international ingredient distributors.
Market Restraints
- Input cost volatility:Citrus fruit harvest fluctuations in Florida and São Paulo directly compress fiber recovery economics and margin predictability for processors.
- Regulatory friction:Divergent fiber quantification methodologies between FDA GRAS self-determination and EFSA novel food assessments fragment formulation standards across Atlantic trade routes.
- Substitution threat:Oat and pea fiber alternatives with established supply chains and lower certification burdens capture price-sensitive clean-label accounts.
Strategic Opportunities
- India:FSSAI registration pathways for imported fiber remain underdeveloped, creating first-mover positioning for suppliers establishing compliant documentation systems.
- Pharmaceutical-grade fiber:USP-grade certification for excipient applications opens formulation partnerships with contract drug manufacturers seeking natural binders.
- Pet food hydration control:Granule format citrus fiber with controlled hydration kinetics commands premium placement in specialty pet nutrition channels.
Industry Challenges
- Organic certification timelines:USDA NOP and EU Organic Regulation 2018/848 traceability requirements extend supplier qualification cycles by 18-24 months.
- REACH compliance documentation:ECHA contaminant testing protocols for lignocellulosic residues impose documentation burdens that strain mid-scale processor capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Citrus Pulp Fiber Market |
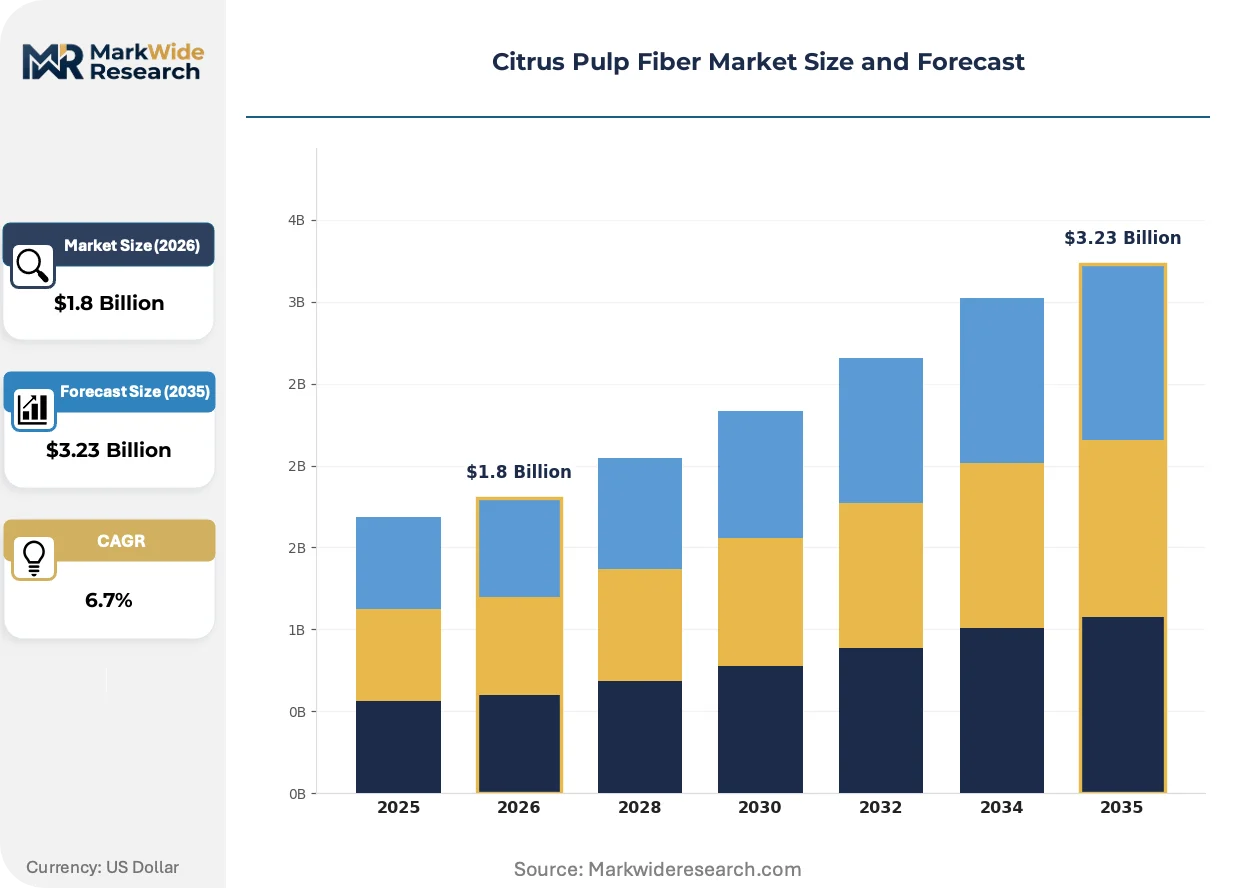
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granules, Pellets, Flakes Application: Food & Beverage, Animal Feed, Cosmetics, Pharmaceuticals End User: Food Manufacturers, Pet Food Producers, Cosmetic Brands, Dietary Supplement Firms Distribution Channel: Online Retail, Direct Sales, Wholesalers, Distributors |
| Companies Covered | DuPont de Nemours, Inc., Herbstreith & Fox GmbH, CP Kelco, Naturex (Givaudan), Yantai Andre Pectin Co., Ltd., Fiberstar, Inc., Ceamsa, SunOpta Inc., Cargill, Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Citrus Pulp Fiber Market Emerging Trajectories
Enzymatic fiber extraction and precision drying technologies are compressing production costs while enabling pharmaceutical-grade purity tiers. These advances intersect with tightening contaminant standards and shifting procurement accountability toward verified supply chain documentation.
Enzymatic pectinase treatment of citrus peel residue is decomposing cell wall matrices to liberate higher-purity cellulose and hemicellulose fractions. Brazilian processors are adopting continuous enzymatic systems at commercial scale. This technology is decomposing the cost barrier between food-grade and pharmaceutical-grade fiber specifications.
REACH compliance in Europe now mandates expanded contaminant testing for heavy metals and pesticide residues in lignocellulosic food ingredients. ECHA documentation requirements have forced fiber exporters to implement batch-level traceability systems. Dietary supplement manufacturers in Germany and France are responding by consolidating procurement around certified suppliers with established European distribution.
Clean-label accountability is shifting procurement decisions from price-based tenders to verified supply chain documentation. Food manufacturers now require pesticide-free sourcing certificates and carbon footprint disclosures from citrus fiber suppliers. This pattern concentrates most visibly in Nordic markets where retail chains enforce binding sustainability criteria for private-label product development.
Citrus Pulp Fiber Market Segmentation
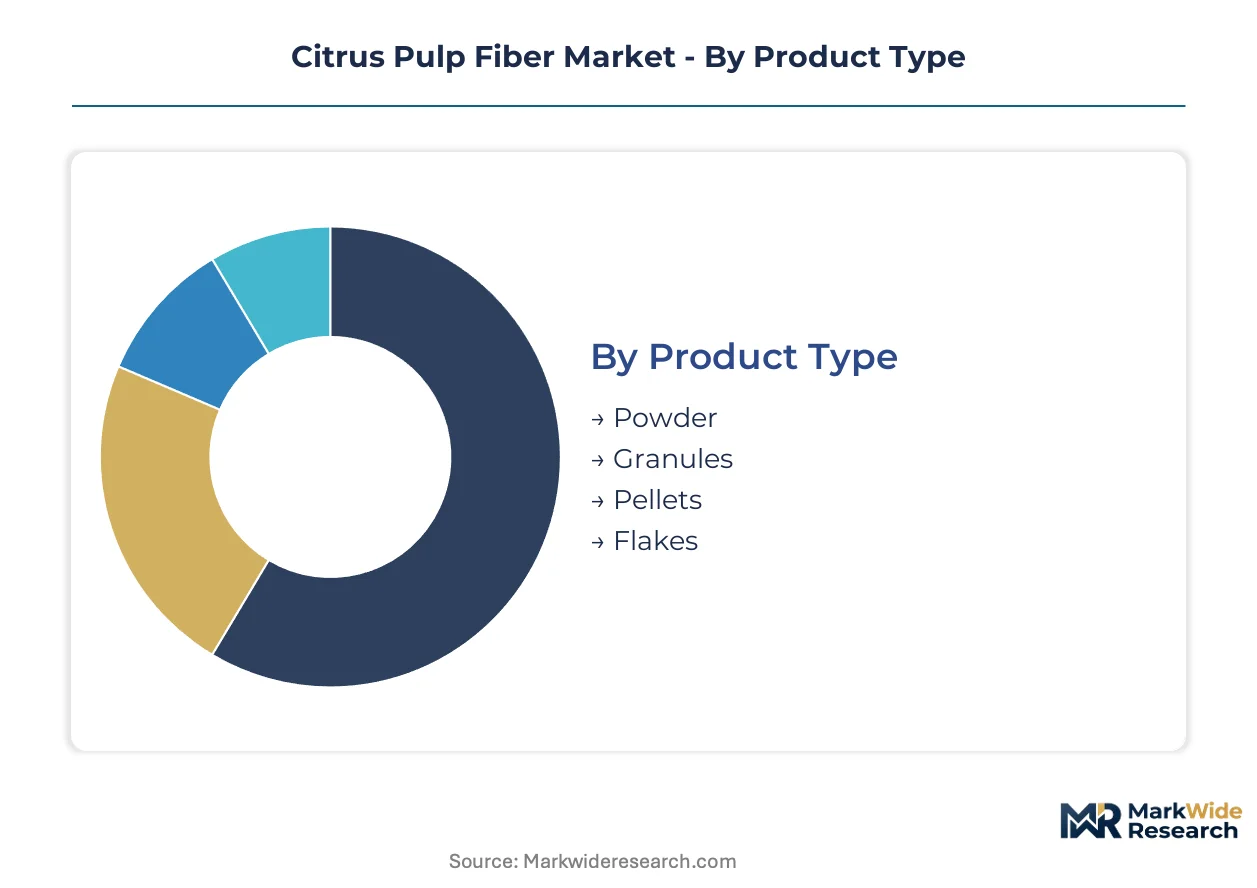
Citrus pulp fiber procurement patterns diverge sharply between export-led commodity grades and domestically consumed specialty formats. Understanding these segment boundaries reveals where margin compression threatens and where certification premiums sustain profitability.
Product Type:
Powder formats dominate export volumes from Brazil and Florida processing clusters, while granules and specialty shapes serve captive regional markets with tighter hydration specifications.
- Powder:Fine-milled particles achieve 60-75% dietary fiber concentration with rapid dispersibility in beverage emulsions. Brazilian processors export this grade to European bakery manufacturers replacing synthetic hydrocolloids under EU Green Deal compliance deadlines.
- Granules:Controlled particle sizing between 0.5-2.0mm enables staged hydration kinetics critical for pet food texture engineering. North American pet food producers in Kansas and Iowa procurement regions specify this format for premium private-label formulations.
- Pellets:Compressed fiber matrices reduce dust handling losses in bulk animal feed milling operations. Midwest US feed compounders favor pelletized delivery for ruminant nutrition blending.
- Flakes:Irregular sheet structures from drum-dried peel residue serve cosmetic exfoliant applications with visual texture requirements. French and German cosmetic formulators source flake grades for natural personal care positioning.
Powder commands the established base. The steepest expansion runs through granules.
Application:
Cost tiers separate commodity feed applications from pharmaceutical-grade fiber commanding tenfold price multiples based on contaminant testing documentation.
- Food & Beverage:Clean-label bakery and functional beverage formulations absorb the majority of food-grade powder volumes. EU manufacturers facing farm-to-fork sustainability disclosure mandates are displacing carrageenan and synthetic stabilizers with traceable citrus fiber sourcing.
- Animal Feed:Pellet and granule formats integrate into ruminant and companion animal nutrition at price points sensitive to harvest-driven input volatility. São Paulo processors supply this segment through long-term offtake contracts with international feed traders.
- Cosmetics:Flake and micro-powder grades serve natural exfoliant and thickening applications where visual aesthetics and INCI labeling purity determine specification. REACH compliance documentation requirements filter supplier eligibility toward established European distributors.
- Pharmaceuticals:USP-grade fiber excipients for tablet binding require enzymatic purification and heavy metal testing protocols that only Herbstreith & Fox and select Brazilian processors currently satisfy. Contract drug manufacturers in Germany and India represent the concentrated demand pool.
Food & Beverage anchors volume throughput. Pharmaceuticals climbs the fastest on margin expansion.
End User:
Customer type determines whether procurement flows through spot commodity markets or locked multi-year supply agreements with traceability documentation.
- Food Manufacturers:Industrial bakery and beverage compounders in Germany, France, and the US Midwest source powder grades through distributors requiring pesticide-free certificates and carbon footprint disclosures. Clean-label accountability has shifted tender evaluation from price to verified supply chain documentation.
- Pet Food Producers:Specialty and mass-market pet nutrition firms in Kansas, Iowa, and São Paulo state specify granule formats with controlled hydration profiles. Procurement concentrates around processors offering batch-level contaminant testing.
- Cosmetic Brands:Natural personal care formulators in France and Germany source flake and micro-powder grades through cosmetic ingredient distributors with established REACH compliance dossiers.
- Dietary Supplement Firms:Prebiotic fiber positioning in gut health products drives accelerating procurement of high-purity powder. German and French supplement manufacturers are consolidating vendor bases around certified suppliers with pharmaceutical-grade extraction capabilities.
Food Manufacturers retain the volume anchor. Dietary Supplement Firms gain share fastest on prebiotic claim proliferation.
Distribution Channel:
Channel selection tracks customer scale and documentation burden tolerance, with direct sales capturing the most demanding accounts.
- Direct Sales:Pharmaceutical and major food manufacturers negotiate multi-year supply agreements directly with Brazilian and Florida processors. These contracts specify batch traceability, organic certification, and customized particle size distributions.
- Distributors:Regional ingredient distributors in Europe and North America hold inventory positions for mid-scale food and cosmetic manufacturers requiring shorter lead times than direct importation allows. REACH and FDA GRAS documentation flows through these intermediaries.
- Wholesalers:Animal feed wholesalers aggregate pellet and standard-grade powder volumes for ruminant nutrition compounders. Price sensitivity in this channel favors Brazilian origin material with lower certification overhead.
- Online Retail:Small-scale cosmetic formulators and specialty pet food startups procure kilogram-scale flake and granule samples through B2B platforms. This channel remains marginal to total volume but serves market entry and product development sampling.
Direct Sales commands the premium tier. Distributors capture the broadest geographic spread.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Santos in São Paulo state anchors Latin American citrus pulp fiber export capacity, connecting Brazilian processing clusters to European and Asian ingredient distributors through established refrigerated bulk shipping lanes.
United States
Florida's citrus belt supplies orange processing byproduct volumes to domestic fiber recovery facilities serving bakery and pet food manufacturers. FDA GRAS self-determination pathways govern ingredient approval, though California's Proposition 65 labeling requirements add documentation burdens for cross-state distribution. Tampa Bay and Orlando processing clusters concentrate enzymatic extraction investments targeting pharmaceutical-grade purity tiers.
Brazil
São Paulo state's orange harvest volumes generate the world's largest citrus byproduct stream for fiber recovery, with processors exporting powder grades to EU clean-label formulators. ANVISA registration requirements for imported fiber remain less stringent than EFSA novel food assessments, creating regulatory arbitrage for domestic exporters. The São Paulo-Triângulo Mineiro corridor hosts continuous enzymatic extraction systems adopted at commercial scale.
Germany
Industrial bakery manufacturers in Bavaria and North Rhine-Westphalia displace synthetic hydrocolloids with traceable citrus fiber under binding EU Green Deal farm-to-fork sustainability disclosure mandates. REACH compliance documentation requirements from ECHA filter supplier eligibility toward established distributors with batch-level contaminant testing protocols. Herbstreith & Fox leverages its German manufacturing base to sustain premium positioning in pharmaceutical-grade fiber excipients.
France
Cosmetic formulators in Île-de-France source flake-grade citrus fiber for natural exfoliant applications, with REACH dossier requirements concentrating procurement around certified European distributors. EFSA novel food assessments govern fiber ingredient approvals for functional beverage applications, extending qualification timelines relative to FDA pathways. The Paris cosmetics cluster drives demand for drum-dried peel residue with visual texture specifications.
India
Dietary supplement manufacturers in Maharashtra and Karnataka accelerate procurement of citrus pulp fiber to support prebiotic gut health positioning in functional nutrition products. FSSAI registration pathways for imported fiber remain underdeveloped, creating first-mover positioning for suppliers establishing compliant documentation systems. Mumbai and Pune distribution hubs consolidate procurement around certified suppliers with established import clearance capabilities.
Citrus Pulp Fiber Market Vendor Landscape
Listed leaders compete with private specialists across certification tier and geographic coverage, producing a tiered structure where scale-driven commodity processors coexist with premium-grade purification specialists. The vendor base fragments across enzymatic extraction capability, with pharmaceutical-grade certification separating premium suppliers from standard food-grade operators. Three archetypes dominate: integrated food ingredient platforms controlling global distribution, pectin-adjacent processors leveraging citrus processing proximity, and dedicated fiber specialists with backward integration into byproduct sourcing. Dominant competitive moves include strategic partnerships with Florida and São Paulo citrus processors to secure captive byproduct supply, and capacity expansion in enzymatic purification systems to bridge food-grade and pharmaceutical-grade specification gaps.
Within the integrated platform tier, Cargill, Incorporated and DuPont de Nemours, Inc. occupy positions exemplifying global distribution control through captive food ingredient networks. Herbstreith & Fox GmbH represents the premium purification specialist archetype, leveraging its German manufacturing base to anchor pharmaceutical-grade fiber supply. Fiberstar, Inc. and Ceamsa exemplify processors with citrus processing proximity advantages, securing byproduct partnerships with Florida and Brazilian operators respectively. Yantai Andre Pectin Co., Ltd. occupies a position within the Asia-Pacific pectin-adjacent processor group, while SunOpta Inc. represents the North American organic-certified ingredient distributor archetype targeting clean-label accountability requirements.
| Leading Market Players |
|---|
| DuPont de Nemours, Inc. |
| Herbstreith & Fox GmbH |
| CP Kelco |
| Naturex (Givaudan) |
| Yantai Andre Pectin Co., Ltd. |
| Fiberstar, Inc. |
| Ceamsa |
| SunOpta Inc. |
| Cargill, Incorporated |
| Others |
Supply Flow & Price Mechanics
Commercial-scale enzymatic extraction capacity in São Paulo state compresses unit economics for Brazilian processors, anchoring global price floors while concentrating supply leverage among operators with backward integration into orange processing waste streams. This scale concentration privileges volume-contract buyers in European bakery and North American pet food channels, while spot-market purchasers absorb harvest-driven volatility.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates USP-grade pharmaceutical fiber from food-grade powder and unprocessed peel residue. Price differentiation rests on certification depth—REACH dossier completeness and USDA NOP organic status command 4-6x multiples over commodity grades. Cost compression in standard-tier powder is intensifying because oat and pea fiber substitutes with lower documentation burdens capture price-sensitive clean-label accounts. Animal feed compounders exhibit highest price sensitivity due to ruminant nutrition margin structures, while pharmaceutical contract manufacturers show lowest sensitivity contingent on excipient purity documentation.
Supply Chain Analysis
Port of Santos refrigerated bulk terminal chokepoints concentrate Brazilian export leverage, with São Paulo-Triângulo Mineiro corridor processors commanding 60-70% of internationally traded food-grade volumes. Raw material flows draw from Valencia orange peel residue in Florida's citrus belt and Hamlin/Tomango harvests in Brazil's interior, with enzymatic pectinase and precision drying equipment as critical processing inputs. Single-source vulnerability runs through Florida's hurricane-exposed harvest cycles, which transmit directly to fiber recovery economics. Distribution runs through integrated food ingredient platforms for pharmaceutical and major food accounts, with regional distributors holding inventory positions for mid-scale European and North American manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified supply chain documentation services represent a faster-expanding revenue layer than base fiber commodity sales, as EU Green Deal farm-to-fork disclosure mandates and REACH batch-level traceability requirements convert compliance into recurring audit and certification management relationships.
For Market Incumbents: Secure multi-year offtake agreements with São Paulo and Florida citrus processors to lock captive byproduct supply before harvest volatility transmits to margin structures. Invest in continuous enzymatic extraction capacity to bridge food-grade and pharmaceutical-grade specification gaps, defending against pectin-adjacent processors with existing citrus processing proximity. For New Entrants and Emerging Players: Organic certification management gaps in India and Southeast Asia offer white-space positioning, as FSSAI registration pathways for imported fiber remain underdeveloped and local dietary supplement manufacturers seek prebiotic fiber suppliers with compliant documentation systems. Target pharmaceutical excipient partnerships in Germany and India through USP-grade purification investments, leveraging contract drug manufacturer consolidation around certified natural binders. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among enzymatic purification specialists with pharmaceutical-grade certification and established European distribution, as these operators capture multi-year supply agreements with built-in documentation service fees. Long-term viability favors processors with backward integration into citrus waste streams rather than merchant fiber traders exposed to harvest volatility. Watch for EU Green Deal enforcement intensity in Nordic retail chains as the signal indicating clean-label procurement accountability acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Purification Capacity Expansion | Bridges food-grade and USP-grade fiber specifications, opening pharmaceutical excipient partnerships. |
| Backward Integration into Citrus Processing | Captures orange peel residue supply before merchant market exposure to São Paulo harvest fluctuations. |
| Organic Certification Infrastructure Investment | Meets EU Organic Regulation 2018/848 traceability requirements extending supplier qualification cycles. |
| REACH Compliance Documentation Systems | Enables ECHA heavy metal and pesticide residue testing protocols for European dietary supplement channels. |
| Direct Sales Channel Development | Bypasses distributor margins for pharmaceutical and major food manufacturers requiring batch traceability. |
Methodological Framework
A standing panel of citrus processing plant managers, European bakery procurement leads, dietary supplement R&D directors, and pet food formulation scientists provided ongoing calibration across primary fieldwork phases. Secondary validation drew from ANVISA registration databases, EFSA novel food assessment filings, USDA NOP organic certification records, and Brazilian agricultural harvest statistics. Bottom-up fiber volume estimates from processor capacity utilization triangulated against top-down demand projections from end-use consumption patterns.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including product format, application tier, certification grade, and regional regulatory cluster. CAGRs were derived from trend extrapolation of enzymatic extraction adoption rates and clean-label formulation displacement patterns in EU bakery and functional beverage channels.
Forecasts assume regulatory continuity in EU Green Deal farm-to-fork targets, FDA GRAS self-determination pathways, and REACH contaminant testing protocols; material policy shifts in organic certification timelines or novel food assessment procedures would require re-modeling. Practitioners should keep alternative scenarios live as harvest volatility in Florida and São Paulo and substitution dynamics from oat and pea fiber alternatives evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fibers
Fiber Metal Laminate (FML) Market
Fibers
Metal Fiber Felt Market
Fibers
North America Carbon Fiber Market
Fibers
Fiberglass Resin Market
Fibers
Sisal Market
Fibers
Pitch-Based Carbon Fiber Market
Fibers
Vinylon Market
Fibers
Global Basalt Fiber Market
Fibers
Global Electronic Grade Glass Fibers Market
Fibers
Bleached Linter Cellulose Market
Fibers
Natural Fiber Reinforcement Materials Market
Fibers
Carbon Fiber Market
Fibers
4-Strand Fan-Shaped Strand Wire Rope Market
Fibers
Acoustical Fiber Board Market
Fibers
Polytetrahydrofuran Market
Fibers
Drug Integrated Polymer Fibers Market