
 Asia-Pacific Industrial Brakes Market | 2026-2036
Asia-Pacific Industrial Brakes Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Industrial Brakes Market Analytics
Electromechanical brake integration with servo motor architectures is reshaping how industrial braking systems deliver precision torque control and energy recuperation. Eaton Corporation plc leverages its hydraulic heritage while building electromechanical portfolios for Asian factory automation. AMETEK Inc. anchors North American technology into regional supply chains through localized production facilities. Altra Industrial Motion Corp. specializes in modular brake-motor packages that reduce commissioning time for OEM integrators.
Asia-Pacific industrial brakes are friction-based or electromagnetic motion control devices engineered to decelerate, hold, or stop rotating machinery within torque ratings spanning tens to thousands of newton-meters. These systems employ sintered metallic or organic friction linings bonded to steel carriers, with thermal capacity determining duty cycle suitability for crane hoists, conveyor drives, and wind turbine yaw mechanisms. Disc brakes capture premium positioning in high-torque mining and marine applications where heat dissipation requirements exceed drum brake thermal limits. Electromagnetic technology leads growth trajectories as factories replace pneumatic infrastructure with electrically actuated systems that eliminate compressor dependency and improve positioning accuracy.
China's MIIT mandates equipment efficiency standards that directly constrain brake energy consumption in motor-driven systems. Japan's METI enforces JIS C 0920 environmental testing protocols that brake manufacturers must satisfy for industrial machinery certification. India's BIS implements compulsory registration for electro-technical equipment including brake coils and rectifier modules. Stakeholders must monitor how China's GB standards evolution and India's PLI scheme for manufacturing equipment reshape supplier qualification requirements and localize content obligations across the regional value chain.
Market Dynamics
China's dual carbon mandates and Japan's METI efficiency protocols are forcing a wholesale replacement of pneumatic brake infrastructure with electromechanical architectures across factory automation networks.
Growth Catalysts
- MIIT Equipment Efficiency Mandates:China's Ministry of Industry and Information Technology enforces motor system energy standards that directly accelerate electromechanical brake adoption in Jiangsu and Zhejiang manufacturing corridors.
- Warehouse Automation Scaling:E-commerce fulfillment networks across the Asia-Pacific are deploying precision braking systems for automated guided vehicles and robotic sortation equipment.
- Sintered Metallic Friction Materials:Advanced friction lining compositions with superior thermal capacity are extending duty cycles in high-torque mining and marine disc brake applications.
Market Restraints
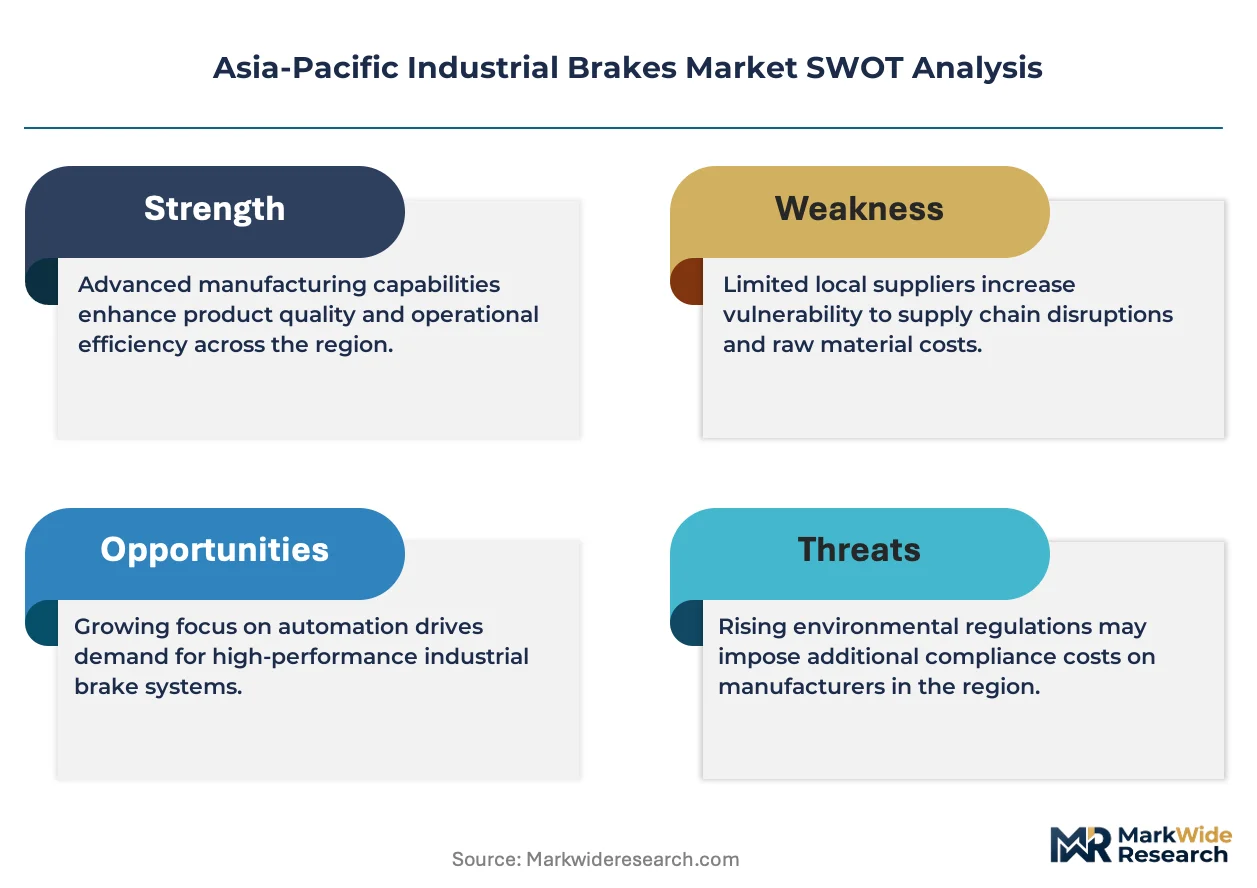
- Rare Earth Magnet Supply Concentration:Electromagnetic brake production depends on neodymium supply chains concentrated in Chinese processing facilities, creating input vulnerability.
- Pneumatic Infrastructure Lock-In:Legacy compressed air systems in established Japanese and South Korean factories impose switching costs that delay electromechanical conversion timelines.
- JIS C 0920 Certification Complexity:Japan's environmental testing protocols for industrial machinery create extended validation periods that constrain new entrant market access.
Strategic Opportunities
- India's PLI Manufacturing Equipment Scheme:Production-linked incentives for industrial machinery are attracting brake system localization investments to serve domestic OEM demand.
- Servo Motor Integration Convergence:Brake-motor package standardization with precision motion control systems is opening specification opportunities in semiconductor manufacturing equipment.
- Wind Turbine Yaw System Demand:Offshore wind installations across China's coastal provinces and Vietnam's emerging projects require high-reliability electromechanical braking for nacelle positioning.
Industry Challenges
- Electromechanical System Integration Expertise:Factory maintenance teams trained on pneumatic diagnostics lack proficiency in servo-drive brake commissioning and fault analysis.
- BIS Compulsory Registration Timelines:India's Bureau of Indian Standards electro-technical equipment certification creates 6-12 month approval delays for brake coil and rectifier module introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Industrial Brakes Market |
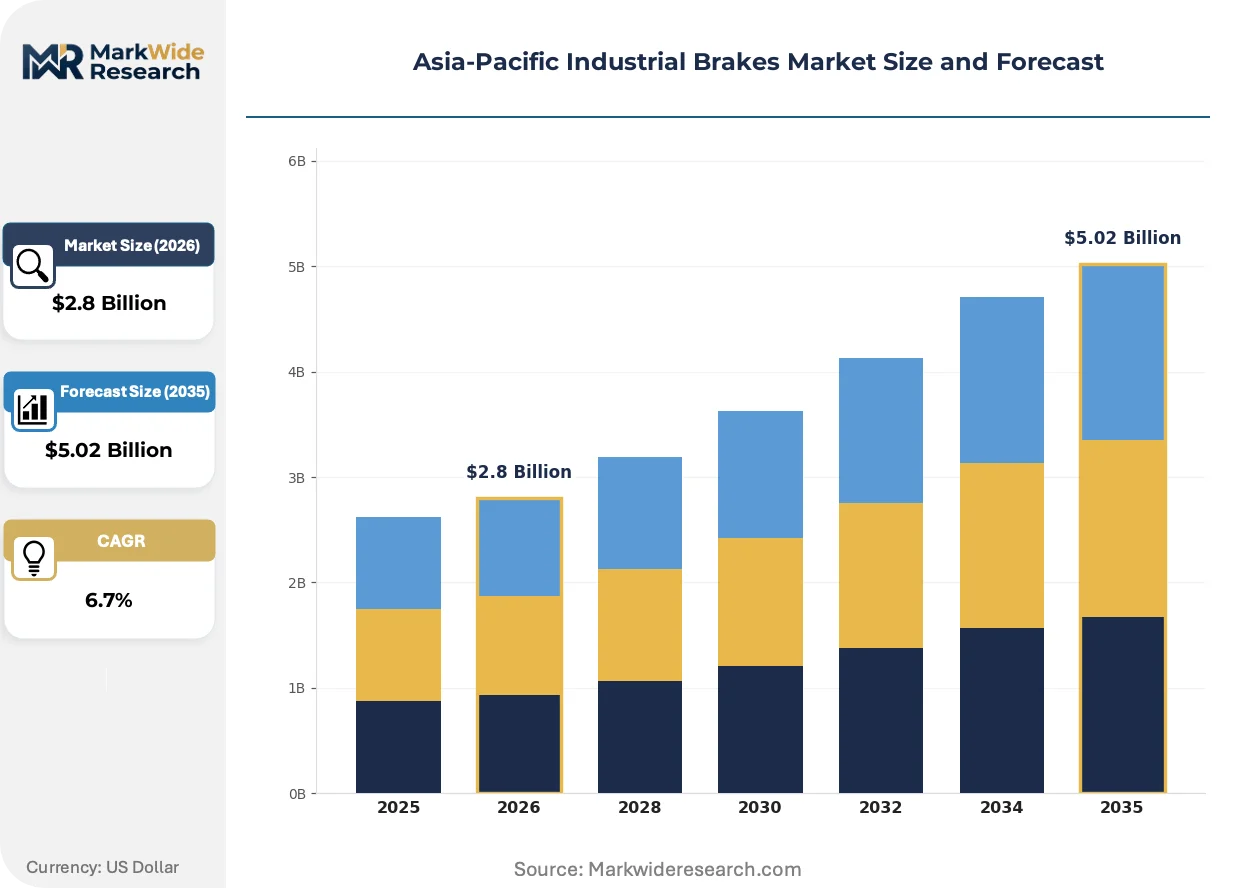
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
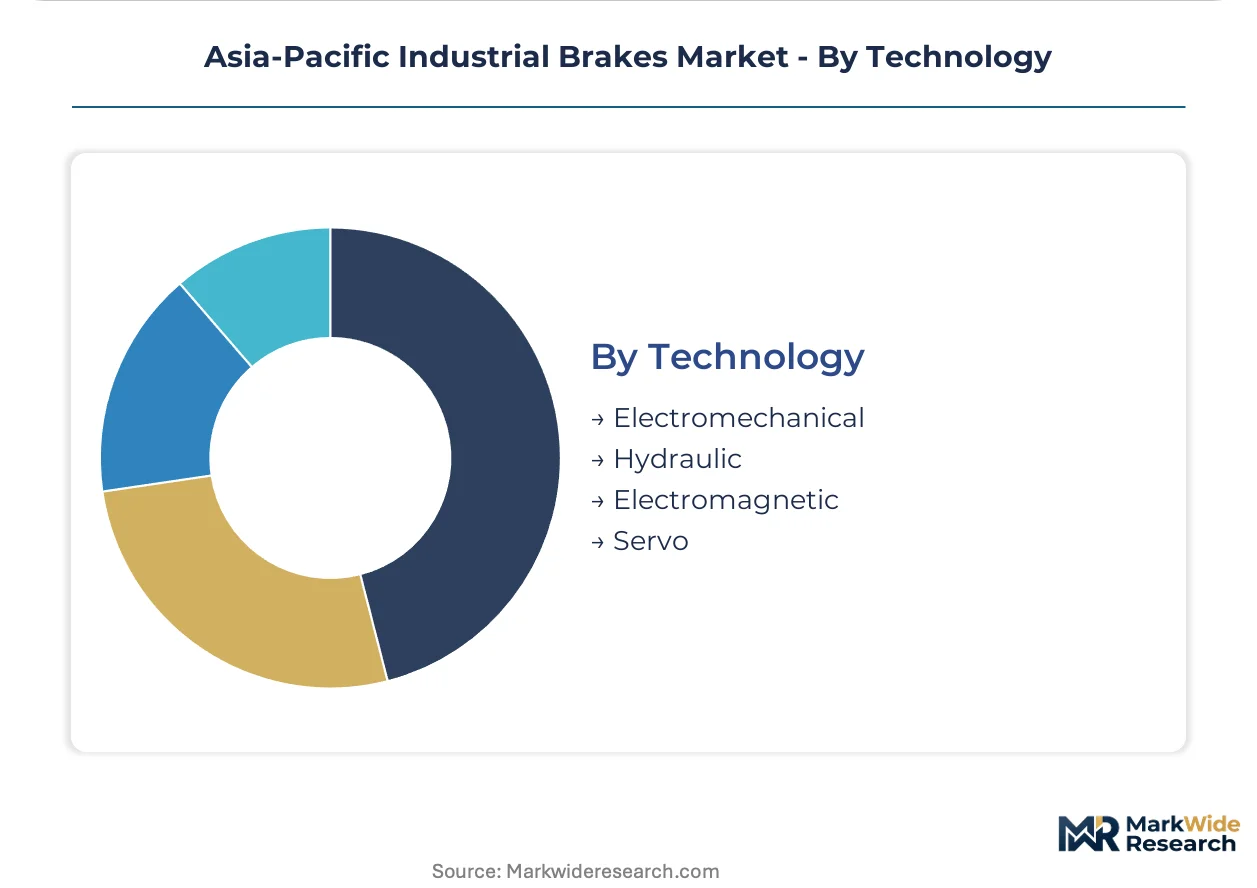
| Segmentation | Product Type: Disc Brakes, Drum Brakes, Hydraulic Brakes, Pneumatic Brakes Application: Manufacturing Equipment, Material Handling, Automotive Production, Mining Equipment End User: Aerospace, Construction, Logistics, Marine Technology: Electromechanical, Hydraulic, Electromagnetic, Servo |
| Companies Covered | Eaton Corporation plc, AMETEK Inc., Altra Industrial Motion Corp., Emco Precima Engineering Pvt Ltd., Coremo Ocmea S.p.A., Akebono Brake Industry Co., Ltd., DELLNER BUBENZER, SIBRE Siegerland Bremsen GmbH, ADVICS CO., LTD., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Industrial Brakes Market Evolving Landscape
Electromechanical architectures are displacing legacy pneumatic systems through precision torque control capabilities and energy recuperation functions that align with regional decarbonization mandates.
Intelligent brake systems with embedded torque sensors and thermal monitoring are hybridizing mechanical friction elements with predictive analytics platforms. Mining equipment operators in Australia's Pilbara region and China's Shanxi province are piloting these systems to optimize maintenance intervals. The technology is hybridizing traditional hardware margins with software-enabled service revenue streams.
METI's 2024 amendments to JIS C 4034 motor efficiency standards are tightening brake energy loss thresholds for industrial machinery sold in Japan. Manufacturers must redesign electromagnetic coil specifications and friction material compounds to satisfy revised testing protocols. Premium positioning equipment for semiconductor wafer handling faces the most stringent compliance timelines.
Specification authority is migrating from maintenance departments to corporate sustainability offices as energy accounting becomes mandatory under China's GB 18613 motor efficiency standards and emerging CSRD-aligned reporting requirements. Purchasing committees now prioritize lifecycle energy consumption over upfront capital cost in crane hoist and conveyor drive procurement. This shift is most pronounced in multinational manufacturing facilities across Malaysia's Penang corridor and Thailand's Eastern Economic Zone.
Asia-Pacific Industrial Brakes Market Segmentation
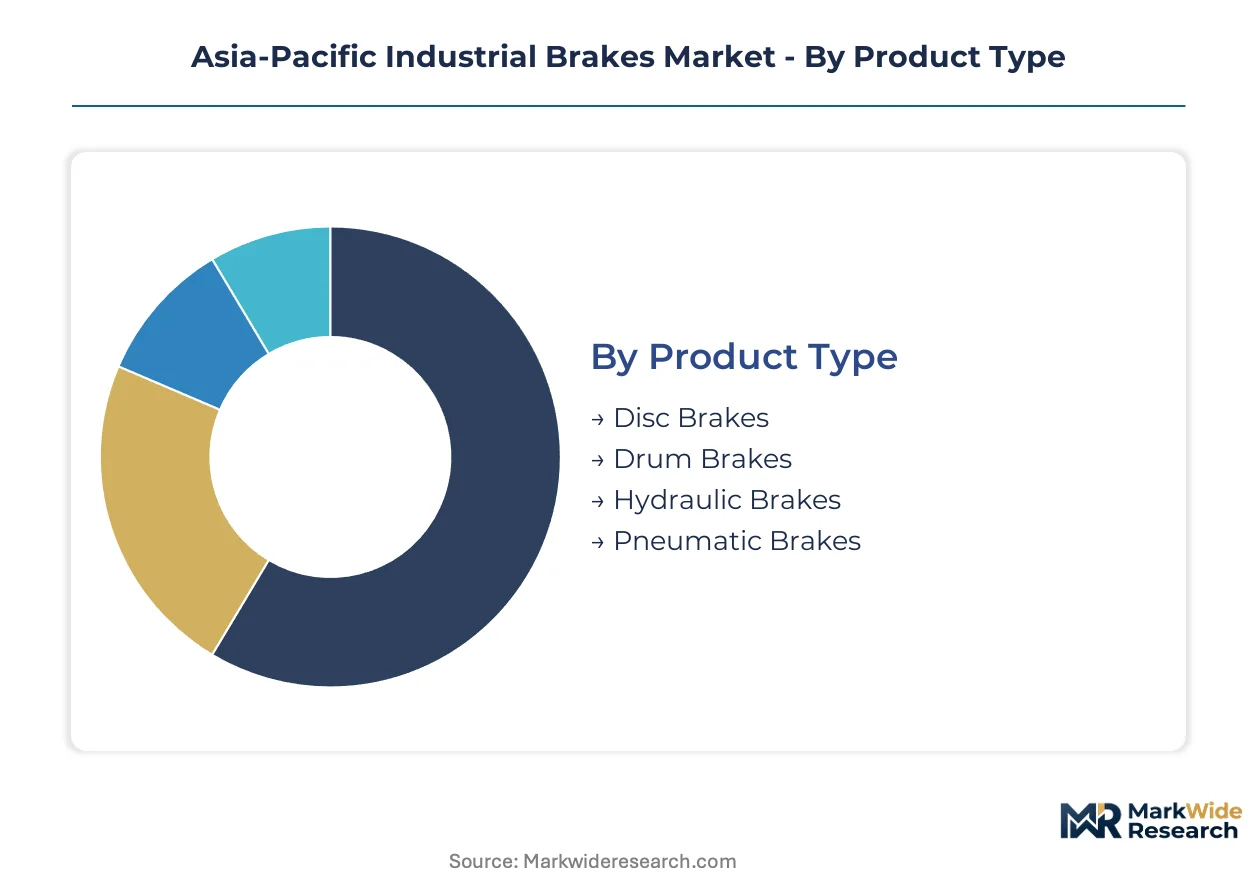
Industrial brake procurement patterns diverge sharply across product architectures and end-use intensities. Maintenance contract structures and spare parts availability reshape supplier selection criteria more than upfront capital cost in Asia-Pacific factory automation networks.
Product Type:
After-sales service intensity varies dramatically across brake architectures, with disc and electromechanical systems requiring specialized technician networks while drum configurations sustain longer replacement intervals.
- Disc Brakes:Sintered metallic friction linings bonded to ventilated steel rotors deliver thermal capacity exceeding drum alternatives. Mining haul trucks in Australia's Pilbara region and marine winch systems across China's Fujian shipyards specify these for heat-intensive duty cycles.
- Drum Brakes:Expanding shoe mechanisms with organic friction materials dominate cost-sensitive conveyor drives and legacy crane installations. Jiangsu province textile manufacturers retain these for low-speed hoisting where thermal loading remains modest.
- Hydraulic Brakes:Oil-actuated piston configurations provide failsafe holding torque for wind turbine yaw mechanisms.
- Pneumatic Brakes:Compressed-air actuation persists in established Japanese automotive stamping lines despite efficiency mandates.
By volume, drum brakes lead. By growth pace, disc configurations are expanding most quickly.
Application:
Cost tier stratification separates precision-positioning applications from bulk material handling, with semiconductor equipment commanding premium specifications against mining's durability focus.
- Manufacturing Equipment:Servo-integrated electromechanical systems enable nanometer-scale positioning for semiconductor wafer handling. Penang's electronics corridor and Hsinchu Science Park fabs specify MIIT-compliant energy recovery braking.
- Material Handling:Automated guided vehicles and robotic sortation systems in Singapore's Tuas port and Shanghai's Yangshan terminals demand rapid-cycle braking with predictive maintenance integration.
- Automotive Production:Press line feeds and body-in-white conveyors require synchronized multi-axis braking.
- Mining Equipment:Dragline and shovel drive systems in Indonesia's Kalimantan operations prioritize thermal endurance over precision.
Material handling captures the steepest expansion trajectory as e-commerce fulfillment scales across Southeast Asian logistics hubs.
End User:
Customer type segmentation reveals divergent procurement authority structures, with aerospace and marine buyers centralizing specifications through engineering departments while construction decentralizes to project sites.
- Aerospace:MRO facilities in Singapore and Bangkok enforce AS9100-certified brake overhaul protocols for landing gear and cargo handling systems. Component traceability requirements exceed industrial norms.
- Construction:Tower crane and hoist operators across Vietnam's urban corridor favor locally serviceable drum brake configurations with rapid pad replacement.
- Logistics:Third-party fulfillment networks in Malaysia's Shah Alam district specify standardized brake-motor packages for automated storage retrieval.
- Marine:Offshore platform winch and mooring systems in Australia's Northwest Shelf require salt-spray resistant coatings and redundant actuation.
Construction leads by installed base volume. Aerospace exhibits the most rapid specification evolution toward electromechanical architectures.
Technology:
Maturity gradients separate established hydraulic infrastructures from emerging servo-integrated platforms, with electromagnetic systems occupying the transitional adoption phase.
- Electromechanical:Ball screw and roller screw actuation eliminates compressor dependency while enabling energy recuperation into servo drives. METI efficiency mandates accelerate replacement of pneumatic infrastructure in Japan's Kansai manufacturing belt.
- Electromagnetic:Spring-applied, electrically released configurations provide failsafe holding for elevator and stage equipment. China's GB standards evolution tightens coil efficiency requirements.
- Hydraulic:Accumulator-backed systems retain dominance in mining and marine applications requiring absolute holding torque.
- Servo:Integrated brake-motor packages with real-time torque feedback enable predictive wear modeling in precision automation.
Electromechanical systems lead by new installation growth rate. Hydraulic technology retains the largest cumulative installed base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Jiangsu and Zhejiang provinces export brake-motor packages to Southeast Asian automation integrators, while Japanese electromechanical systems supply precision equipment fabricators across Penang and Singapore.
China
MIIT equipment efficiency mandates accelerate electromechanical brake deployment across motor-driven systems. The country's dual carbon goals constrain energy consumption in industrial machinery certification. Eastern manufacturing corridors spanning Suzhou and Hangzhou concentrate demand for servo-integrated braking in warehouse automation networks.
Japan
METI efficiency protocols force replacement of pneumatic infrastructure in factory automation networks. JIS C 0920 environmental testing protocols extend validation periods for brake system certification. Kansai manufacturing belt operations in Osaka and Kyoto prioritize electromechanical architectures with energy recuperation capabilities.
India
BIS compulsory registration for electro-technical equipment creates approval delays for brake coil introductions. The PLI scheme for manufacturing equipment attracts localization investments from multinational brake suppliers. Gujarat and Maharashtra industrial corridors drive demand for cost-optimized drum brake configurations in construction equipment.
South Korea
Legacy compressed air systems in established automotive stamping lines impose switching costs for electromechanical conversion. National efficiency standards align with METI-equivalent protocols for industrial machinery energy performance. Busan-Ulsan manufacturing clusters sustain demand for high-torque disc brakes in shipyard winch applications.
Vietnam
Offshore wind installations along central coastal provinces require electromechanical braking for nacelle positioning systems. Emerging factory automation networks import brake-motor packages from Chinese suppliers across the northern border. Ho Chi Minh City logistics hubs deploy precision braking for automated guided vehicles in e-commerce fulfillment centers.
Asia-Pacific Industrial Brakes Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered procurement structures. The vendor base organizes around hydraulic heritage firms diversifying into electromechanical portfolios, modular brake-motor integrators reducing OEM commissioning time, and regional fabricators serving localized aftermarket demand. Dominant competitive moves include strategic partnerships with servo drive manufacturers and geographic expansion through production-linked incentive schemes.
Among diversified industrial conglomerates, Eaton Corporation plc and AMETEK Inc. exemplify archetypes leveraging cross-technology portfolios to anchor regional supply chain positions. Altra Industrial Motion Corp. occupies a specialist position within modular system integration. SIBRE Siegerland Bremsen GmbH and Coremo Ocmea S.p.A. represent European engineering-intensive fabricators competing on technical specification authority.
| Leading Market Players |
|---|
| Eaton Corporation plc |
| AMETEK Inc. |
| Altra Industrial Motion Corp. |
| Emco Precima Engineering Pvt Ltd. |
| Coremo Ocmea S.p.A. |
| Akebono Brake Industry Co., Ltd. |
| DELLNER BUBENZER |
| SIBRE Siegerland Bremsen GmbH |
| ADVICS CO., LTD. |
| Others |
Value Network & Pricing Analysis
Neodymium processing concentration in Chinese rare earth facilities anchors input costs for electromagnetic brake coil production, with margin pools accumulating downstream at electromechanical system integrators who control specification authority in Japan's Kansai belt and China's Jiangsu corridor.
Pricing Analysis
Current-generation electromechanical systems command premiums against prior-generation pneumatic architectures and emerging next-gen servo-integrated platforms. Three-tier pricing structure across premium MIIT-certified energy recovery systems, standard JIS-compliant electromagnetic configurations, and economy drum brake alternatives separates procurement tiers. Cost compression in economy drum brake segments is intensifying because Indian and Vietnamese construction equipment OEMs prioritize upfront capital minimization over lifecycle efficiency. Third-party logistics operators in Malaysia's Shah Alam district exhibit the highest price sensitivity, while semiconductor equipment fabricators in Penang tolerate premium positioning for nanometer-scale precision.
Supply Chain Analysis
Extended payment terms from 90 to 120 days characterize supplier-financing arrangements for sintered metallic friction material imports. Manufacturing concentration spans China for electromagnetic coil assemblies, Japan for precision servo-integrated packages, and South Korea for automotive stamping line pneumatic systems. Raw material dependencies encompass neodymium for permanent magnets, copper for coil windings, and specialized steel alloys for disc brake rotors. Single-source vulnerability concentrates in Chinese rare earth processing facilities. Distribution runs through authorized service networks for electromechanical systems and independent aftermarket channels for legacy drum brake configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Proficiency gaps in servo-drive brake commissioning and fault analysis constrain electromechanical adoption velocity, with factory maintenance teams trained on pneumatic diagnostics unable to support precision automation deployments.
For Market Incumbents: Build certification authority moats through accelerated BIS and JIS C 0920 compliance investments ahead of India's PLI scheme maturation and Japan's METI efficiency protocol tightening. Anchor regional supply chain positions through localized coil winding and friction material bonding facilities in Gujarat and Jiangsu. Defensive consolidation should prioritize backward integration into neodymium magnet sourcing partnerships to offset Chinese processing concentration risk. For New Entrants and Emerging Players: Mid-market warehouse automation integrators in Vietnam's Ho Chi Minh City logistics corridor represent the most penetrable entry point, with specification authority migrating from maintenance departments to corporate sustainability offices creating vendor switching windows. Target India's construction equipment aftermarket through cost-optimized drum brake configurations with rapid pad replacement protocols. Go-to-market execution should emphasize localized service technician certification programs to overcome electromechanical system integration expertise scarcity. For Investors and Strategic Acquirers: Secondary-cycle assets sit with European engineering-intensive fabricators holding technical specification authority in mining and marine disc brake niches but lacking Asia-Pacific electromechanical portfolio breadth. Long-term viability over a 5-10 year horizon hinges on servo motor integration convergence in semiconductor manufacturing equipment. The signal to watch is METI amendment velocity for JIS C 4034 motor efficiency standards, which would accelerate pneumatic infrastructure replacement timelines and expand addressable market for electromechanical specialists.| Strategic Initiative | Industry Significance |
|---|---|
| Servo Motor Integration Partnership | Brake-motor package standardization with precision motion control systems opens specification opportunities in semiconductor fabrication equipment across Penang and Hsinchu. |
| Localized Production Investment | PLI scheme qualification in Gujarat and Maharashtra industrial corridors accelerates domestic OEM supply relationships and reduces BIS registration timeline exposure. |
| Neodymium Supply Security Program | Magnet sourcing partnerships outside Chinese processing concentration mitigate input vulnerability for electromagnetic brake coil production. |
| Predictive Maintenance Platform Development | Embedded torque sensors and thermal monitoring hybridize hardware margins with software-enabled service revenue in Australian Pilbara mining operations. |
| Certification Acceleration Investment | Pre-emptive JIS C 0920 and BIS compliance ahead of regulatory tightening secures specification authority in Japan's Kansai manufacturing belt. |
Research Methodology
Initial hypotheses were tested against primary input from maintenance directors at warehouse automation networks, OEM procurement teams in construction equipment, aftermarket service heads for mining brake systems, and plant engineers in automotive stamping facilities, then refined through secondary validation against MIIT equipment efficiency filings, METI JIS standard amendments, BIS compulsory registration databases, and customs trade data for friction material imports. Bottom-up segment sizing triangulated with top-down macroeconomic drivers anchored regional demand projections.
Demand-supply-balance framing structured the analytical framework across the analysis window, with segmentation modeling across product architecture, application intensity, end-user procurement authority structure, and technology maturity gradient. CAGRs were derived from installed base turnover dynamics and new installation growth trajectories. Forecast inputs incorporated e-commerce fulfillment scaling velocity, offshore wind nacelle positioning system demand, and semiconductor equipment capital expenditure patterns.
Practitioners should monitor rare earth magnet supply disruption indicators and METI efficiency protocol amendment schedules for early signals of forecast revision triggers. Forecasts reflect assumptions regarding electromechanical conversion timelines and PLI scheme participation rates. Macroeconomic deviation in Chinese manufacturing investment, regulatory acceleration in Japanese efficiency mandates, or technological breakthrough in friction material compounds would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Global Electric Vehicle Parts and Components Market
Vehicle Components
Rail Wheel Market
Vehicle Components
Latin America Two-Wheeler Components Market
Vehicle Components
Car Radiator Market
Vehicle Components
Bicycle Components Aftermarket Market
Vehicle Components
UK Automotive Carbon Fiber Composites Market
Vehicle Components
Advanced Driver Assistance System (ADAS) Sensor Market
Vehicle Components
Piston Market
Vehicle Components
Railway Air Filter Market
Vehicle Components
Argentina Automotive Carbon Fiber Composites Market
Vehicle Components
Engine Components Market
Vehicle Components
Trailer Surge Brake Market
Vehicle Components
5th Wheel Hitches Market
Vehicle Components
Global Undercarriage Components Market
Vehicle Components
Automotive Powertrain Sensors Market
Vehicle Components
Ceramic Ball Bearings Market