
 Dog Food Toppers Market | 2026-2036
Dog Food Toppers Market Size, Share, and Industry Trends Forecast 2026-2036
Dog Food Toppers Market Analysis
Pet meal customization revenue is reshaping how brands capture lifetime value in companion animal nutrition. The Honest Kitchen leverages human-grade ingredient sourcing to sustain premium positioning across freeze-dried formats. Native Pet anchors its portfolio in single-ingredient functional toppers that compete on digestive health claims. Ziwi Peak dominates air-dried meat segments with New Zealand-origin supply chains that extend shelf stability without synthetic preservatives.
Dog food toppers are nutritional supplements added to base kibble or wet food, typically comprising 5-15% moisture content in freeze-dried formats or 60-85% in fresh refrigerated preparations, designed to enhance palatability, introduce functional ingredients like probiotics or omega fatty acids, and elevate feeding rituals for companion animals. Grain-free and freeze-dried product types command the widest margin pools as pet owners trade up from conventional wet mixers, while organic segments face supply constraints that limit volume scaling despite price premiums. Meat-based ingredient formulations lead volume share, though vegetable and fruit inclusions are gaining traction among owners managing protein sensitivities or seeking antioxidant supplementation.
FDA Center for Veterinary Medicine oversight and AAFCO model feed regulations shape permissible nutrient claims and ingredient definitions, creating compliance thresholds that favor established manufacturers with dedicated regulatory affairs capacity. State-level feed control officials in California, Texas, and New York enforce additional labeling requirements that fragment market access for smaller importers. Stakeholders must monitor evolving positions on novel proteins and cellular agriculture inputs, as these determinations will redraw permissible ingredient boundaries and reformulation costs.
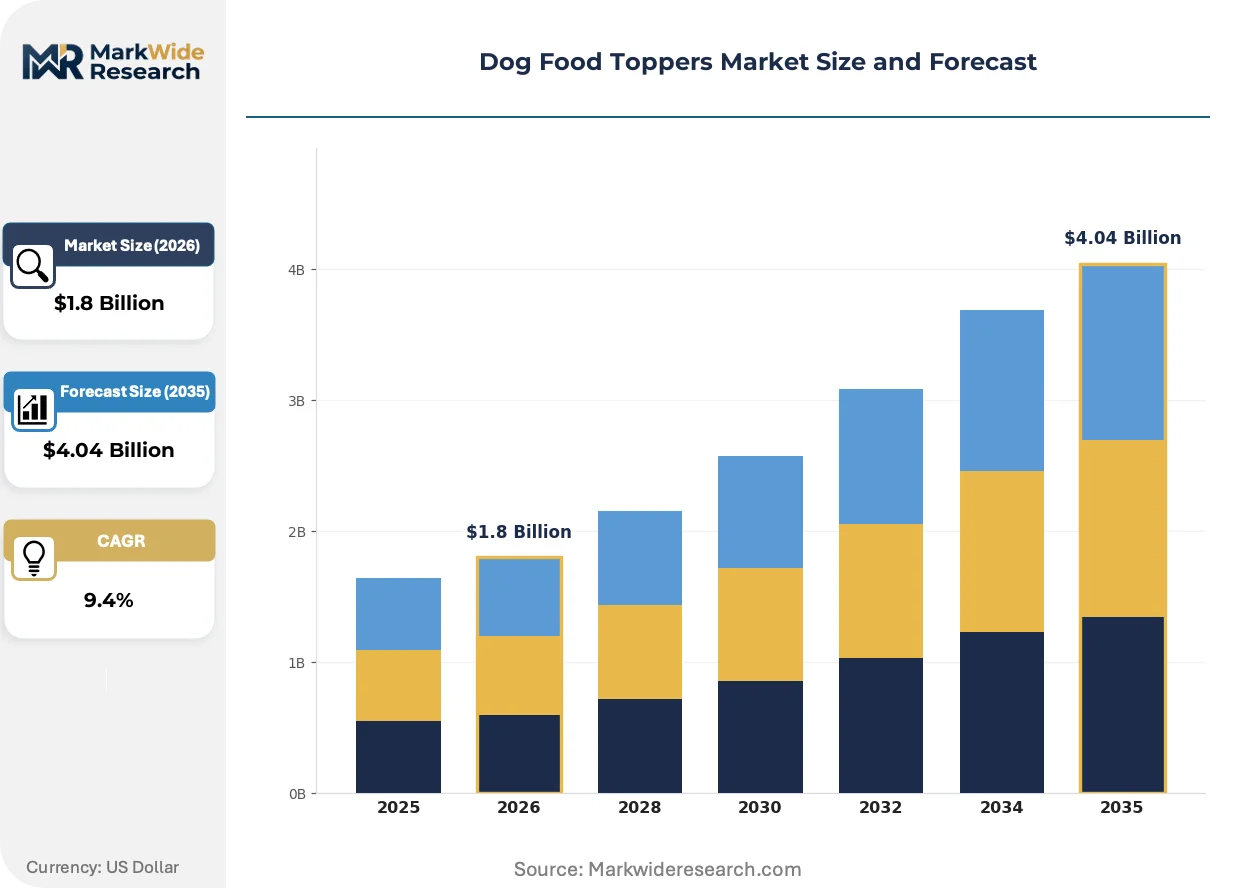
Market Dynamics
Millennial pet owners are forcing a recalibration of value capture in companion animal nutrition, trading up from commodity kibble to functional meal add-ons that command sustained price premiums and subscription-based recurring revenue streams.
Growth Catalysts
- Human-grade ingredient sourcing standards:FDA Center for Veterinary Medicine oversight of pet food labeling is compelling manufacturers to upgrade supply chain documentation and ingredient provenance claims.
- Freeze-dried format adoption:Pet owners in the United States are displacing conventional wet mixers with shelf-stable formats that preserve nutrient density without synthetic preservatives.
- Functional health positioning:Digestive health and joint support claims anchored in omega fatty acid and probiotic inclusion are capturing veterinary recommendation channels.
Market Restraints
- Novel protein supply volatility:Insect and cellular agriculture ingredient pipelines face AAFCO definition delays that stall product commercialization timelines.
- Refrigerated cold chain fragmentation:Fresh-format toppers require last-mile temperature control infrastructure concentrated in coastal metropolitan zones.
- Organic certification scarcity:USDA organic livestock protein supply constraints limit volume scaling despite persistent price premiums.
Strategic Opportunities
- Veterinary clinic channel penetration:Professional recommendation networks in Canada represent underdeveloped distribution for clinically positioned digestive health formulations.
- Subscription direct-to-consumer models:Portion-customized auto-ship programs are displacing mass retail shelf reliance for fresh and freeze-dried categories.
- Cellular agriculture regulatory clarity:FDA novel protein approval pathways will unlock ingredient cost structures competitive with conventional rendered meats.
Industry Challenges
- Regulatory affairs talent scarcity:Dedicated compliance capacity for state-level feed control official variations across California, Texas, and New York strains mid-tier manufacturers.
- Reformulation cost compression:AAFCO nutrient profile updates force rapid label redesign and ingredient substitution without guaranteed price recovery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dog Food Toppers Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Grain-Free, Organic, Freeze-Dried, Dehydrated Ingredient Type: Meat, Vegetables, Fruits, Grains Packaging Type: Plastic Pouches, Tins, Boxes, Bags End User: Pet Owners, Pet Stores, Veterinarians, Dog Trainers |
| Companies Covered | The Honest Kitchen, Native Pet, JustFoodForDogs, Jinx, Solid Gold, Ziwi Peak, Open Farm, Sundays for Dogs, Instinct, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dog Food Toppers Market Emerging Trajectories
Product format convergence and regulatory transparency mandates are compressing traditional boundaries between fresh, freeze-dried, and air-dried preservation methods. Manufacturers must now engineer for simultaneous palatability, shelf stability, and clean-label compliance.
High-pressure processing technology is hybridizing fresh-format safety assurance with extended refrigerated shelf life. Subscription service operators in the United States are adopting HPP systems to reduce spoilage rates without synthetic preservative inclusion. This convergence is compressing the cost gap between fresh and freeze-dried formats.
AAFCO model feed regulation updates are tightening permissible nutrient claim language and ingredient definition precision. Manufacturers face reformulation costs to align product positioning with revised labeling standards. Freeze-dried meat segments bear the highest compliance burden given protein content claim sensitivity.
Pet owner purchasing through veterinary recommendation channels is displacing mass retail discovery for clinically positioned functional toppers. Digestive health and joint support formulations now capture professional endorsement before consumer trial. This pattern concentrates fastest in metropolitan markets with integrated veterinary-subscription service partnerships.
Dog Food Toppers Market Segmentation
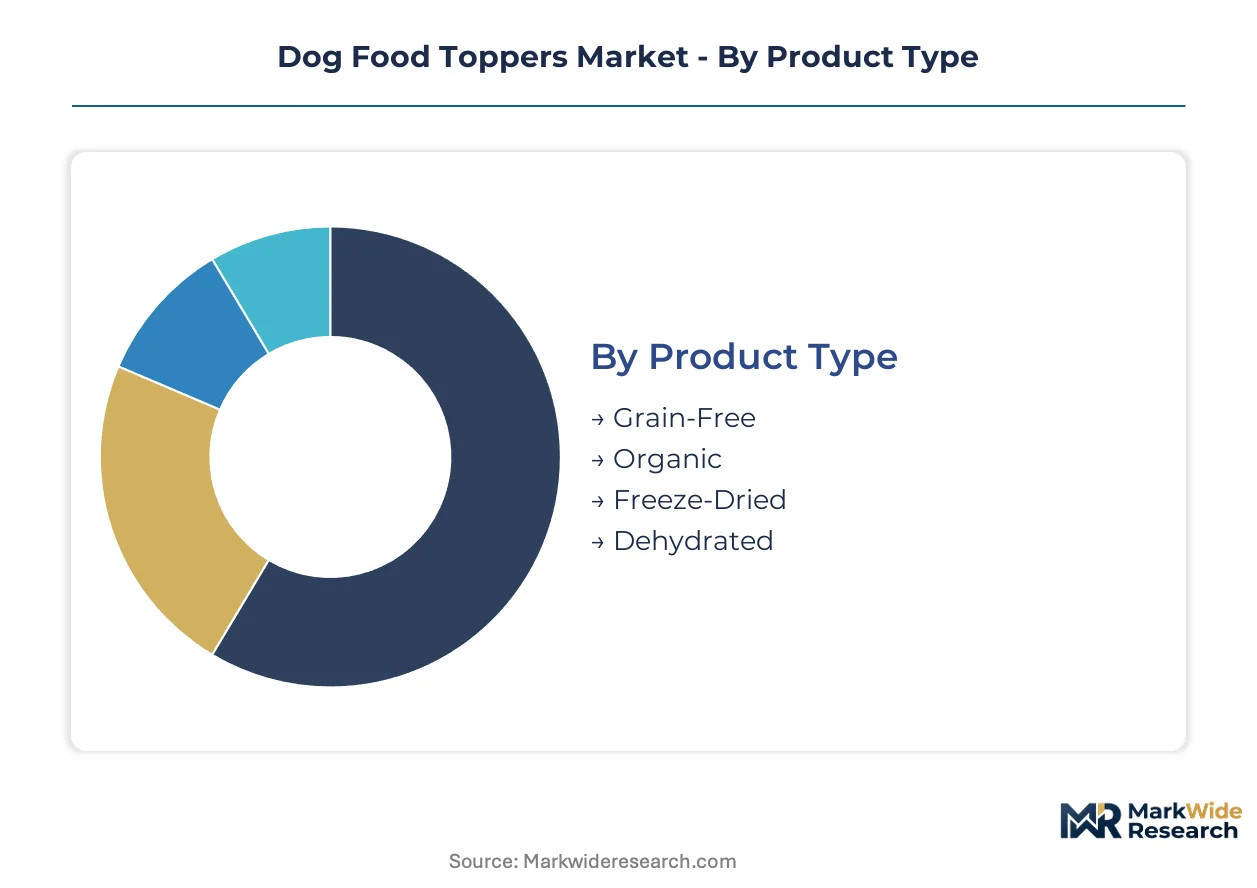
Segmentation in dog food toppers reveals how preservation technology, ingredient sourcing, and distribution channel economics partition value capture across the $1.8 billion market. Manufacturers engineer format-specific supply chains while retailers optimize shelf configurations around purchase frequency and margin profiles.
Product Type:
Freeze-dried and dehydrated formats span the use-case spectrum from daily meal enhancement to veterinary-prescribed therapeutic supplementation, with moisture content and shelf stability requirements driving manufacturing investment intensity.
- Freeze-Dried:Low-temperature sublimation preserves cellular structure of meat proteins and probiotics, yielding 5-15% moisture content with 12-18 month ambient shelf stability. Demand concentrates in United States metropolitan subscription services where pet owners prioritize convenience without synthetic preservatives. FDA labeling scrutiny on nutrient density claims elevates compliance costs for new entrants.
- Grain-Free:Elimination of wheat, corn, and soy addresses protein sensitivity management and ancestral diet positioning among millennial pet owners. United States coastal markets show highest penetration, though AAFCO carbohydrate definition updates force periodic reformulation. This segment commands widest margin pools as trade-up from conventional kibble accelerates.
- Organic:USDA-certified livestock protein sourcing faces supply constraints that limit volume scaling despite persistent price premiums. Mid-Atlantic and Pacific Northwest pet owners drive regional concentration.
- Dehydrated:Warm air circulation reduces moisture to 10-12%, offering intermediate shelf stability at lower capital equipment thresholds than freeze-drying. Bulk retail channels in Texas and Florida favor this format for price-sensitive volume buyers.
The dominant share belongs to Freeze-Dried, while Grain-Free is closing the gap fastest.
Ingredient Type:
Cost tier differentiation separates commodity protein inputs from functional superfood inclusions, with veterinary recommendation channels increasingly validating specific ingredient efficacy claims.
- Meat:Beef, poultry, and lamb derivatives constitute the volume foundation, with New Zealand-origin air-dried meats capturing premium positioning through novel protein avoidance. AAFCO protein content claim precision demands laboratory verification of amino acid profiles.
- Vegetables:Sweet potato, pumpkin, and carrot inclusions address fiber supplementation and glycemic control for senior dogs. California and Pacific Northwest markets show strongest adoption among owners managing weight and digestive conditions.
- Fruits:Blueberry and cranberry antioxidant positioning targets oxidative stress reduction claims, though supply seasonality compresses margin consistency. Northeastern United States veterinary clinics recommend these formulations for immune support.
- Grains:Oat and rice derivatives persist in value-tier products and therapeutic gastrointestinal formulations where soluble fiber benefits outweigh grain-free positioning. Midwest mass retail channels retain highest share of grain-inclusive purchases.
Meat-based formulations anchor volume leadership, though Vegetables are expanding most quickly as protein sensitivity diagnoses multiply.
Packaging Type:
Customer type and purchase occasion dictate format selection, with subscription services and veterinary channels demanding divergent shelf-life and portion-control specifications.
- Plastic Pouches:Flexible barrier films with resealable closures dominate fresh-format refrigerated distribution, enabling single-serve portioning that reduces spoilage in direct-to-consumer auto-ship programs. High-pressure processing compatibility requirements constrain supplier selection.
- Tins:Metal canning preserves wet mixer formats with 24-month shelf stability, though weight and recycling friction limit e-commerce viability. Veterinary clinic dispensing favors this format for prescription digestive health products.
- Boxes:Corrugated retail packaging supports multi-unit freeze-dried presentations in club store environments, with California and Texas enforcement of extended producer responsibility regulations elevating recycled content mandates.
- Bags:Multi-layer polyethylene structures with oxygen scavengers protect dehydrated products through mass retail distribution, where standing pouch formats maximize shelf facings in pet specialty stores.
Plastic Pouches command the dominant position in growth channels, while Bags retain the largest installed base in conventional retail.
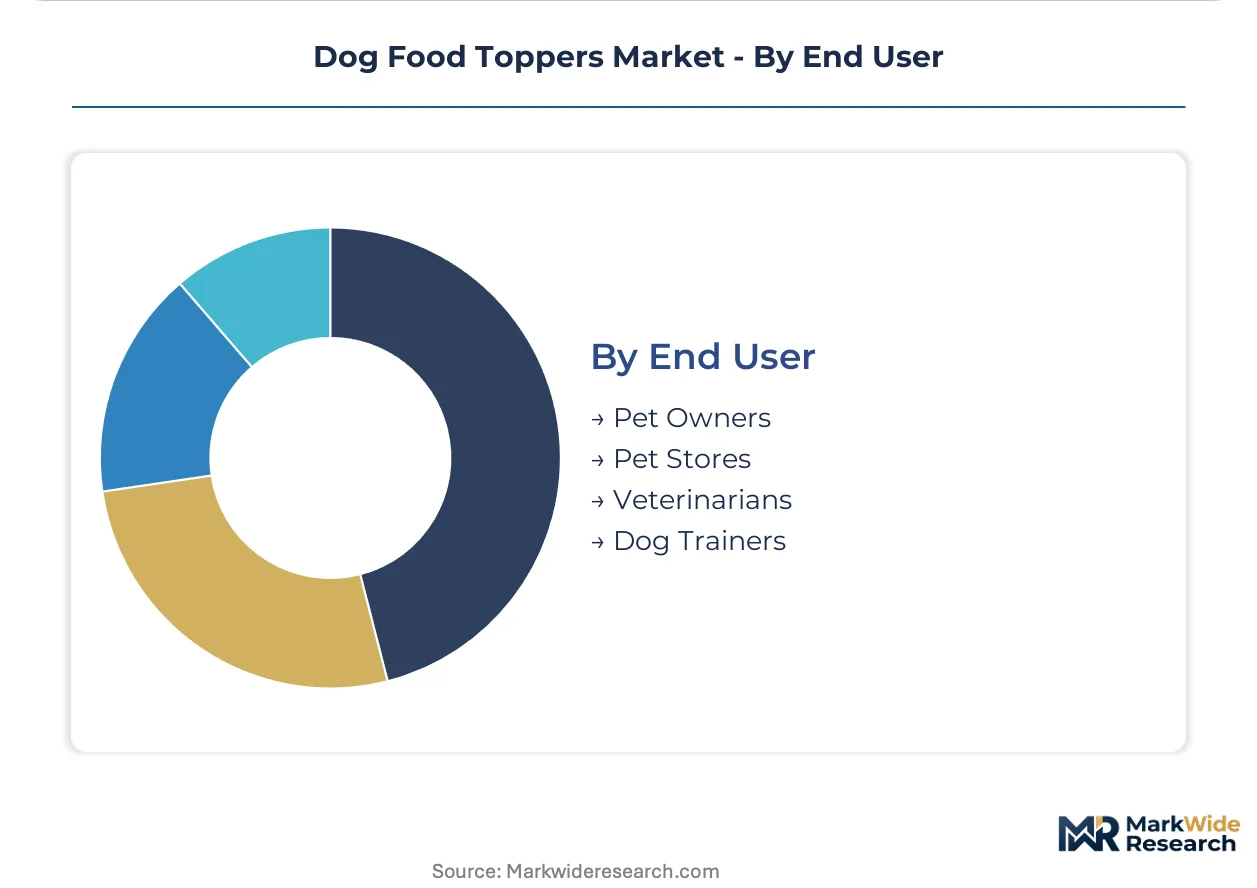
End User:
Application maturity varies sharply across professional recommendation networks, subscription platforms, and mass consumer self-selection.
- Pet Owners:Direct purchasing through subscription services and e-commerce platforms concentrates among millennial households in United States metropolitan areas, with auto-ship retention rates exceeding conventional replenishment cycles. Human-grade ingredient sourcing transparency drives brand switching costs.
- Pet Stores:Specialty retail staff recommendations influence trial conversion for functional health positioning, though shelf space compression from private label expansion constrains national brand access. Independent stores in Colorado and Oregon show highest functional topper attachment rates.
- Veterinarians:Clinical endorsement of digestive health and joint support formulations precedes consumer trial in integrated veterinary-subscription partnerships. Canada represents underdeveloped penetration for this channel.
- Dog Trainers:High-value treat applications in positive reinforcement protocols favor air-dried meat formats with rapid consumption and minimal caloric load. Performance dog communities in Florida and Arizona drive regional concentration.
Pet Owners generate the dominant revenue share, though Veterinarians are gaining share fastest as professional recommendation networks consolidate influence over functional nutrition selection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ingredient sourcing standards and subscription logistics infrastructure concentrate manufacturing and distribution capacity in specific national markets. Regulatory enforcement intensity varies sharply across jurisdictions, creating asymmetric compliance burdens that favor established operators with dedicated regulatory affairs capacity.
United States
Millennial pet owners in metropolitan coastal markets drive premium-format adoption through direct-to-consumer subscription platforms. FDA Center for Veterinary Medicine labeling requirements compel manufacturers to upgrade supply chain documentation and substantiate nutrient density claims. Austin and Denver anchor freeze-dried production clusters where human-grade ingredient sourcing protocols have become baseline competitive requirements.
Canada
Veterinary clinic channel penetration for digestive health formulations remains underdeveloped relative to consumer-direct alternatives. Health Canada and Canadian Food Inspection Agency oversight of pet food safety creates parallel but less fragmented regulatory pathways than US state-level variations. Toronto and Vancouver concentrate fresh-format distribution infrastructure serving urban subscription households.
Germany
EFSA novel protein evaluation timelines and EU organic certification standards shape permissible ingredient boundaries for continental market access. Berlin and Munich host specialized pet nutrition research clusters advancing probiotic stability in shelf-stable formats. German retailers enforce extended producer responsibility mandates that elevate sustainable packaging investment thresholds.
United Kingdom
Post-Brexit divergence from EU feed regulations introduces dual compliance obligations for cross-channel suppliers. London and Southeast England concentrate premium pet food e-commerce fulfillment capacity serving subscription bases. UK veterinary recommendation networks increasingly validate functional health claims before consumer trial.
Australia
TGA-adjacent pet food regulatory frameworks and quarantine restrictions on animal-derived imports constrain novel protein pipeline development. Sydney and Melbourne anchor air-dried meat processing capacity leveraging proximity to New Zealand-origin supply chains. Australian consumers show elevated price sensitivity to organic certification premiums relative to North American markets.
Dog Food Toppers Market Vendor Landscape
Human-grade sourcing specialists and functional nutrition formulators split the market between premium positioning and veterinary-channel credibility. Consolidation pressure concentrates among mid-tier operators lacking dedicated regulatory affairs capacity to navigate state-level feed control variations. Three archetypes dominate: freeze-dried format innovators, fresh-format subscription operators, and air-dried meat traditionalists. Competitive moves center on strategic partnerships with veterinary recommendation networks and backward integration into ingredient provenance verification systems.
Within the human-grade sourcing tier, The Honest Kitchen and Open Farm exemplify supply chain transparency positioning that commands sustained price premiums. Ziwi Peak anchors the air-dried meat segment through New Zealand-origin supply chain control. Native Pet occupies a position in single-ingredient functional formats competing on digestive health validation.
| Leading Market Players |
|---|
| The Honest Kitchen |
| Native Pet |
| JustFoodForDogs |
| Jinx |
| Solid Gold |
| Ziwi Peak |
| Open Farm |
| Sundays for Dogs |
| Instinct |
| Others |
Supply Flow & Price Mechanics
Intermodal freight corridors connecting New Zealand processing facilities to United States distribution hubs concentrate cost dynamics that cascade through supply concentration and downstream price differentiation. Refrigerated container rates on these lanes directly compress margins for air-dried meat formats while elevating premium positioning for domestic freeze-dried alternatives.
Pricing Analysis
AAFCO model feed regulations dictate the pricing tier structure by forcing compliance investments that stratify manufacturers across certification-grade boundaries. Three-tier pricing structure across premium, standard, and economy levels separates human-grade sourcing specialists from conventional rendered-protein operators, with FDA labeling precision demands widening the gap. Cost compression in the standard tier is intensifying because organic certification scarcity limits volume scaling. Mass retail buyers in the Midwest exhibit highest price sensitivity, while metropolitan subscription households demonstrate lowest elasticity.
Supply Chain Analysis
USDA organic livestock certification restrictions limit flows of premium protein inputs into domestic manufacturing. New Zealand, Australia, and the United States anchor geographic supply concentration for air-dried and freeze-dried meat processing. Raw material dependencies center on grass-fed beef, free-range poultry, and novel protein pipelines. Single-source vulnerability runs through New Zealand-origin supply chains given quarantine and export permit constraints. Distribution runs through direct-to-consumer subscription platforms and veterinary clinic networks in parallel.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among millennial subscription households whose auto-ship retention rates exceed conventional replenishment cycles, fragmenting price discovery away from mass retail.
For Market Incumbents: Harden regulatory affairs capacity against AAFCO definition updates that force rapid reformulation without guaranteed price recovery. Deepen backward integration into human-grade ingredient provenance verification to defend margin position against emerging private-label expansion. Priority lever: captive supply partnerships with USDA-certified organic livestock operations. For New Entrants and Emerging Players: Canadian veterinary clinic channels represent the most penetrable entry point given underdeveloped penetration for clinically positioned digestive health formulations. Mid-tier metropolitan markets in Texas and Florida offer secondary white-space for dehydrated format disruption. Go-to-market angle: integrated veterinary-subscription service partnerships that professionalize consumer trial. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors freeze-dried format innovators with high-pressure processing compatibility and shelf-stable probiotic stability. Long-term viability over the next decade rests on regulatory clarity for cellular agriculture inputs that unlock cost structures competitive with conventional rendered meats. Signal to watch: FDA novel protein approval pathway acceleration as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary Channel Penetration | Professional endorsement networks in Canada validate digestive health claims before consumer trial. |
| High-Pressure Processing Adoption | HPP systems reduce spoilage rates in fresh-format subscription services without synthetic preservatives. |
| Backward Integration into Ingredient Sourcing | Human-grade supply chain control sustains premium positioning against private-label compression. |
| Subscription Platform Expansion | Auto-ship retention rates exceed conventional replenishment cycles in metropolitan coastal markets. |
| Novel Protein Regulatory Engagement | AAFCO definition clarity for insect and cellular inputs unlocks commercialization timelines. |
Methodological Framework
A spread of perspectives from brand managers at freeze-dried specialists, category buyers at pet specialty retailers, regulatory affairs directors, and supply chain planners converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against FDA Center for Veterinary Medicine filings, AAFCO model feed regulation updates, USDA organic certification databases, and Nielsen retail audit data. Bottom-up segment sizing and top-down macroeconomic triangulation anchored volume and value estimates.
Demand-supply balance dynamics across preservation technology segments, ingredient sourcing tiers, and distribution channel economics structured the analytical framework. Segmentation dimensions spanned product format, certification grade, and customer type. CAGRs were derived from fitted growth curves calibrated to historical subscription service penetration patterns and veterinary recommendation channel expansion rates. Forecast inputs incorporated AAFCO regulatory timeline assumptions and cold chain infrastructure buildout trajectories.
Practitioners should monitor novel protein approval pathways and organic livestock supply constraints for early signals. Forecasts reflect documented assumptions on regulatory clarity timelines and subscription retention rate stability. Material shifts in FDA cellular agriculture positioning or USDA organic certification availability would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Kelp Noodles Market
Specialty Foods
Halal Products Market
Specialty Foods
Spirulina Chocolate Market
Specialty Foods
Gluten-Free Desserts and Ice Creams Market
Specialty Foods
Europe Hummus Market
Specialty Foods
Low Calorie Veggie Dip Market
Specialty Foods
Low Calorie Diet Meal Plan Market
Specialty Foods
Aloe Vera Gel Market
Specialty Foods
Aloe Butter Market
Specialty Foods
Poke Food Market
Specialty Foods
Coconut Butter Market
Specialty Foods
Global Bee Products Market
Specialty Foods
United States Tofu Market
Specialty Foods
Carbonic Maceration Market
Specialty Foods
Low Calorie Chocolate Desserts Market
Specialty Foods
Manuka Honey Market