
 Asia Pacific Olive Market | 2026-2036
Asia Pacific Olive Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Olive Market Outlook
Buyer concentration across Asia Pacific food service chains is restructuring procurement volumes toward consolidated national distributors with direct Mediterranean sourcing contracts. Deoleo S.A. leverages its Spanish crushing infrastructure to supply bulk extra-virgin shipments into Australian and Japanese institutional kitchens. Borges International Group anchors its position through controlled-atmosphere storage facilities in Singapore that reduce transit oxidation for high-polyphenol oils. California Olive Ranch competes on shorter ocean freight lanes to East Asian ports, cutting lead times against traditional Mediterranean suppliers.
Asia Pacific olives encompass the fruit and derived products of Olea europaea cultivars, typically harvested at oil content of 15–25% by fresh weight or brine-cured at 2–6% salinity for table consumption, serving nutritional, cosmetic, and industrial extraction purposes. Olive oil commands the dominant value share across product type segments, though olive paste gains traction in Southeast Asian manufacturing of condiments and marinades. Distribution through supermarkets still captures the largest volume flow, yet online retail segments in South Korea and Japan are expanding fastest as direct-to-consumer subscription models for single-origin oils mature.
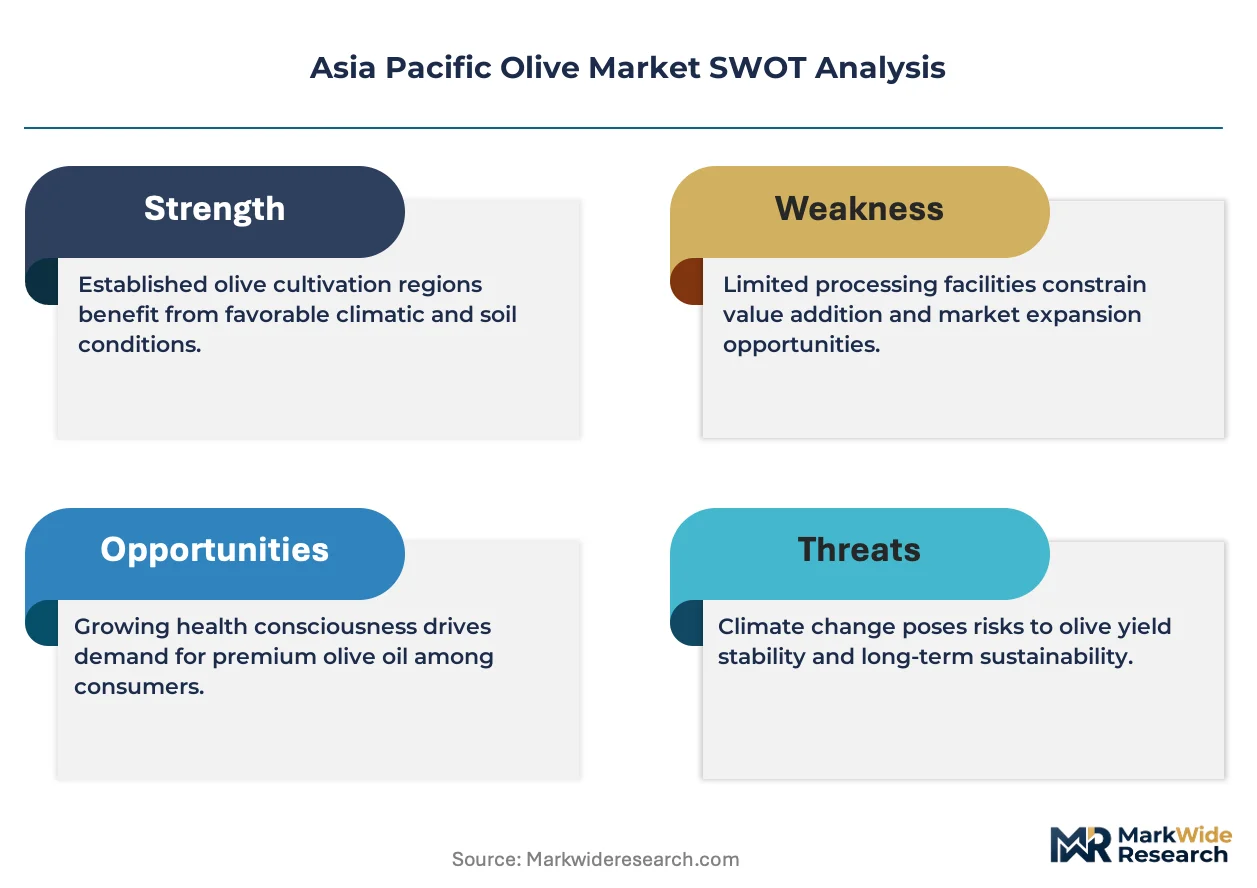
Food safety frameworks from Food Standards Australia New Zealand, Japan's Ministry of Health, Labour and Welfare, and China's SAMR collectively govern maximum residue limits, labeling integrity, and import documentation for olive products entering Asia Pacific markets. These bodies enforce divergent testing protocols that fragment compliance costs and favor suppliers with multi-jurisdiction certification capabilities. Stakeholders must monitor evolving domestic cultivation subsidies in Australia against import tariff schedules that could alter the cost advantage of locally pressed versus shipped oil.
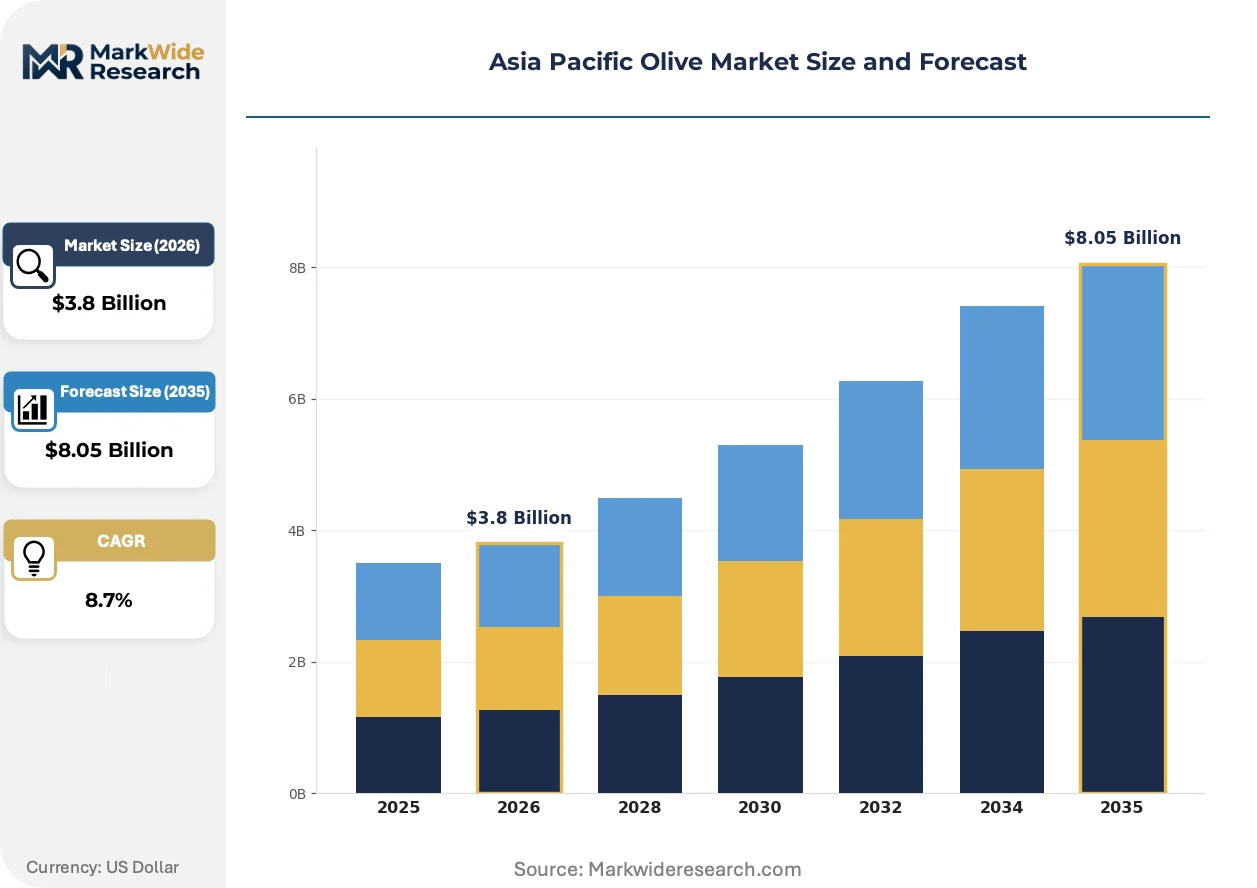
Market Dynamics
Biosecurity-driven import redirection is fragmenting Asia Pacific olive supply chains toward certified Mediterranean nursery stock and pre-approved crushing infrastructure, compressing traditional bulk-shipment economics while elevating traceability premiums.
Growth Catalysts
- Food Standards Australia New Zealand residue protocols:Stringent maximum residue limits for pesticide contaminants are filtering out informal suppliers and consolidating procurement toward certified Mediterranean exporters with multi-jurisdiction testing capabilities.
- Japanese institutional kitchen expansion:Hospital and corporate cafeteria operators are expanding Mediterranean menu lines, pulling bulk extra-virgin volumes through consolidated national distributors with direct Spanish and Italian sourcing contracts.
- Singapore controlled-atmosphere storage:Nitrogen-flushed tank facilities at transshipment hubs are reducing polyphenol oxidation during tropical transit, enabling high-grade oil positioning previously impossible for Mediterranean-origin shipments.
Market Restraints
- Australian biosecurity inspection bottlenecks:Tightening protocols for olive plant material imports are extending nursery stock quarantine periods and elevating working capital requirements for domestic orchard expansion.
- Input cost volatility in irrigation infrastructure:Electricity and water pricing fluctuations across Australia's Murray-Darling and South Australian corridors are compressing margins for table-olive processors with heavy pumping dependencies.
- Substitution pressure from rice bran and grapeseed oils:Southeast Asian food manufacturers are reformulating condiment bases toward lower-cost domestic oil inputs when polyphenol content is not specification-critical.
Strategic Opportunities
- South Korean direct-to-consumer subscription channels:Online retail segments for single-origin oils are maturing fastest in Seoul and Busan metro areas, bypassing traditional supermarket markups.
- Olive paste in Southeast Asian manufacturing:Malaysian and Thai sauce producers are integrating olive-derived bases into premium marinade lines targeting export halal certification.
- China SAMR import documentation streamlining:Pilot programs for pre-cleared Mediterranean suppliers are reducing customs clearance friction for bulk shipments entering Shanghai and Guangzhou ports.
Industry Challenges
- Multi-jurisdiction certification complexity:Suppliers must maintain parallel testing protocols for Japan's Ministry of Health, Labour and Welfare, Australia's FSANZ, and China's SAMR, fragmenting compliance staffing.
- Cold chain reconfiguration for high-polyphenol grades:Refrigerated container availability constraints between Mediterranean crush facilities and East Asian ports are forcing inventory positioning decisions six to eight weeks ahead of harvest.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Olive Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Black Olives, Green Olives, Olive Oil, Olive Paste End User: Food Service, Retail, Organic Markets, Exporters Application: Culinary Uses, Cosmetic Products, Health Supplements, Industrial Uses Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Wholesalers |
| Companies Covered | Deoleo S.A., Sovena Group, Borges International Group, Colavita S.p.A., California Olive Ranch, Gallo Worldwide, Del Monte Foods, Inc, Cargill, Incorporated, Ybarra Group, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Olive Market Strategic Shifts
Processing technology and distribution infrastructure are converging to preserve bioactive compounds through extended supply chains, while regulatory differentiation and channel fragmentation are rewriting competitive positioning across the region.
Nitrogen-sparged crushing and malaxation systems are preserving volatile phenolic compounds through extended ocean transit. Australian and Japanese bulk buyers are specifying these technologies in supply contracts with Spanish and Italian cooperatives. The premium price compression this enables is absorbing margin from traditional commodity-grade bulk shipments.
Japan's Ministry of Health, Labour and Welfare is tightening origin labeling requirements for blended olive oils sold through food service channels. The industrial consequence is forced segregation of crush lots at Mediterranean source facilities. Australian institutional kitchens are responding by shifting procurement toward single-origin certified shipments with blockchain traceability documentation.
Subscription-based direct purchasing is displacing supermarket intermediation for premium grades in Seoul and Tokyo metropolitan markets. Younger household segments are sourcing single-estate oils through mobile-first platforms that bypass traditional importer-distributor markups. This channel rotation is most visible in South Korea, where olive oil consumption per capita remains below Japanese levels but online penetration rates exceed regional averages.
Asia Pacific Olive Market Segmentation
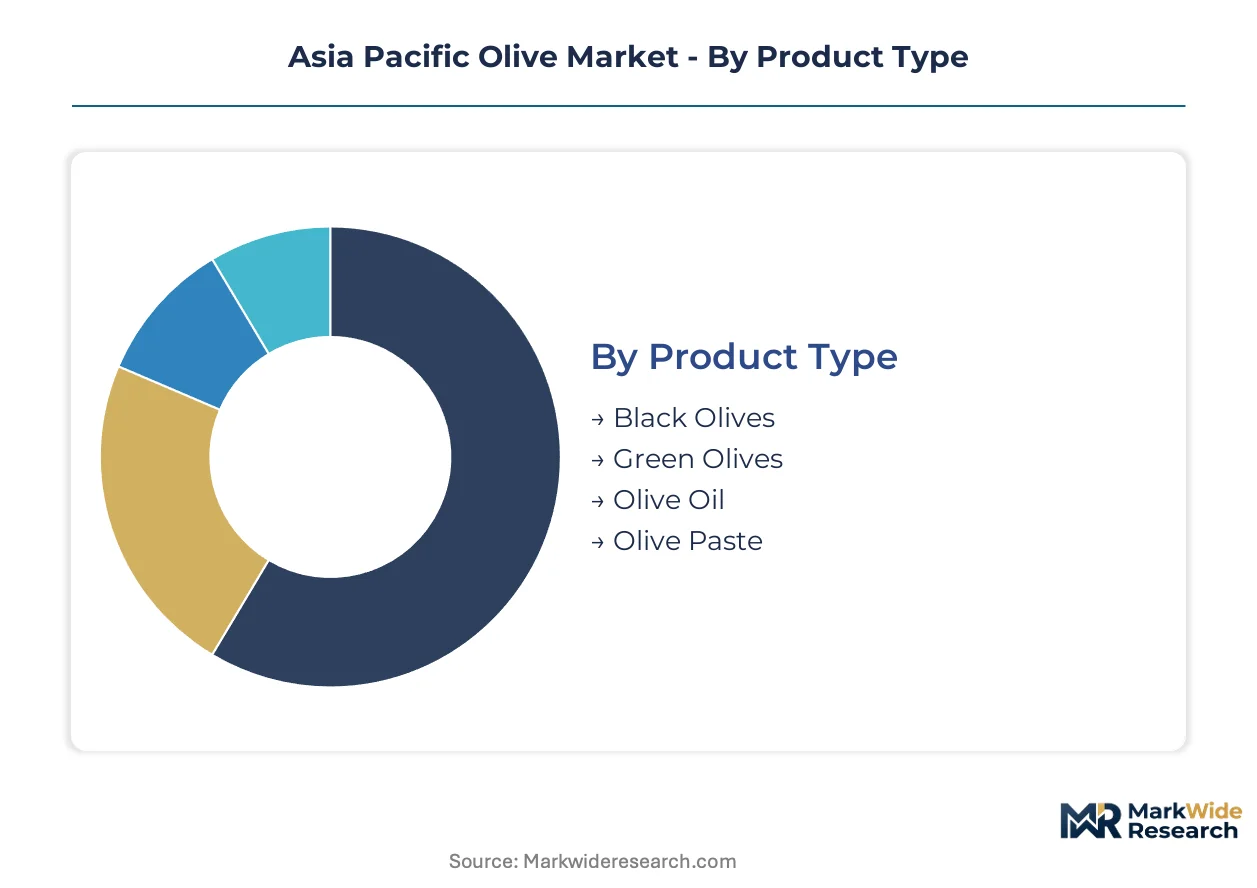
Asia Pacific olive procurement splits sharply between commodity-grade bulk shipments and traceable premium grades, with channel and application choices determining margin capture across Australian, Japanese, and South Korean buyers. Segmentation discipline separates volume-driven food service contracts from emerging direct-to-consumer subscription channels where polyphenol certification commands price premiums.
Product Type:
Olive Oil dominates value flow through institutional kitchens, while Olive Paste and table olive formats fragment across manufacturing and retail channels with divergent margin structures.
- Olive Oil:Extra-virgin grades with polyphenol counts above 250 mg/kg absorb procurement focus from Tokyo hospital cafeterias and Sydney fine-dining groups. Nitrogen-flushed bulk shipments through Singapore transshipment hubs preserve oxidation-sensitive compounds for Australian buyers specifying Mediterranean crushing protocols.
- Black Olives:Brine-cured fruit at 2–4% salinity supplies Australian pizza chains and Japanese bento manufacturers through consolidated national distributors with direct Spanish sourcing contracts. Controlled-atmosphere storage at import hubs extends shelf stability for retail private-label programs.
- Green Olives:Fermented whole fruit serves Mediterranean-themed restaurant chains across Melbourne and Seoul with predictable year-round demand tied to menu standardization requirements.
- Olive Paste:Concentrated olive-derived bases integrate into Malaysian and Thai marinade manufacturing for halal-certified export lines targeting Middle Eastern markets.
Mature deployment sits with Olive Oil. Newer deployment is concentrated in Olive Paste.
End User:
Procurement scale and certification requirements diverge sharply between institutional volume buyers and fragmented premium channels where traceability documentation commands sourcing priority.
- Food Service:Hospital and corporate cafeteria operators across Japan's Kanto region specify single-origin extra-virgin oils with blockchain traceability to satisfy tightening Ministry of Health, Labour and Welfare labeling rules. Bulk contracts route through consolidated distributors with direct Mediterranean crushing partnerships.
- Retail:Australian supermarket chains capture the largest volume flow through private-label programs sourced from Spanish cooperatives with multi-jurisdiction residue testing capabilities compliant with Food Standards Australia New Zealand protocols.
- Organic Markets:Seoul and Tokyo metropolitan direct-to-consumer subscription platforms bypass traditional importer markups for certified organic single-estate oils with harvest-date documentation.
- Exporters:Southeast Asian condiment manufacturers re-export olive-derived bases to halal-certified markets, with Malaysian processors integrating olive paste into premium marinade formulations.
Volume concentration rests with Retail. Margin expansion is steepest in Organic Markets.
Application:
Functional specifications separate commodity culinary procurement from cosmetic and nutraceutical applications where bioactive compound preservation justifies cold-chain investment.
- Culinary Uses:Heat-stable refined olive oils supply Australian food manufacturing and Japanese frying applications where polyphenol degradation is specification-tolerable. Procurement optimizes for smoke point and oxidative stability rather than volatile aromatic content.
- Cosmetic Products:Squalene and polyphenol extracts from olive pomace feed South Korean skincare manufacturing, with ingredient suppliers specifying cold-pressed separation methods to preserve triterpene structures for topical formulations.
- Health Supplements:Hydroxytyrosol-standardized extracts target Japanese functional food regulations with specific antioxidant claims requiring pre-market notification to the Ministry of Health, Labour and Welfare.
- Industrial Uses:Technical-grade olive oil derivatives enter lubricant and surfactant manufacturing with minimal processing requirements and price-sensitive procurement through commodity chemical distributors.
Established demand anchors Culinary Uses. Bioactive extraction is gaining share fastest in Cosmetic Products.
Distribution Channel:
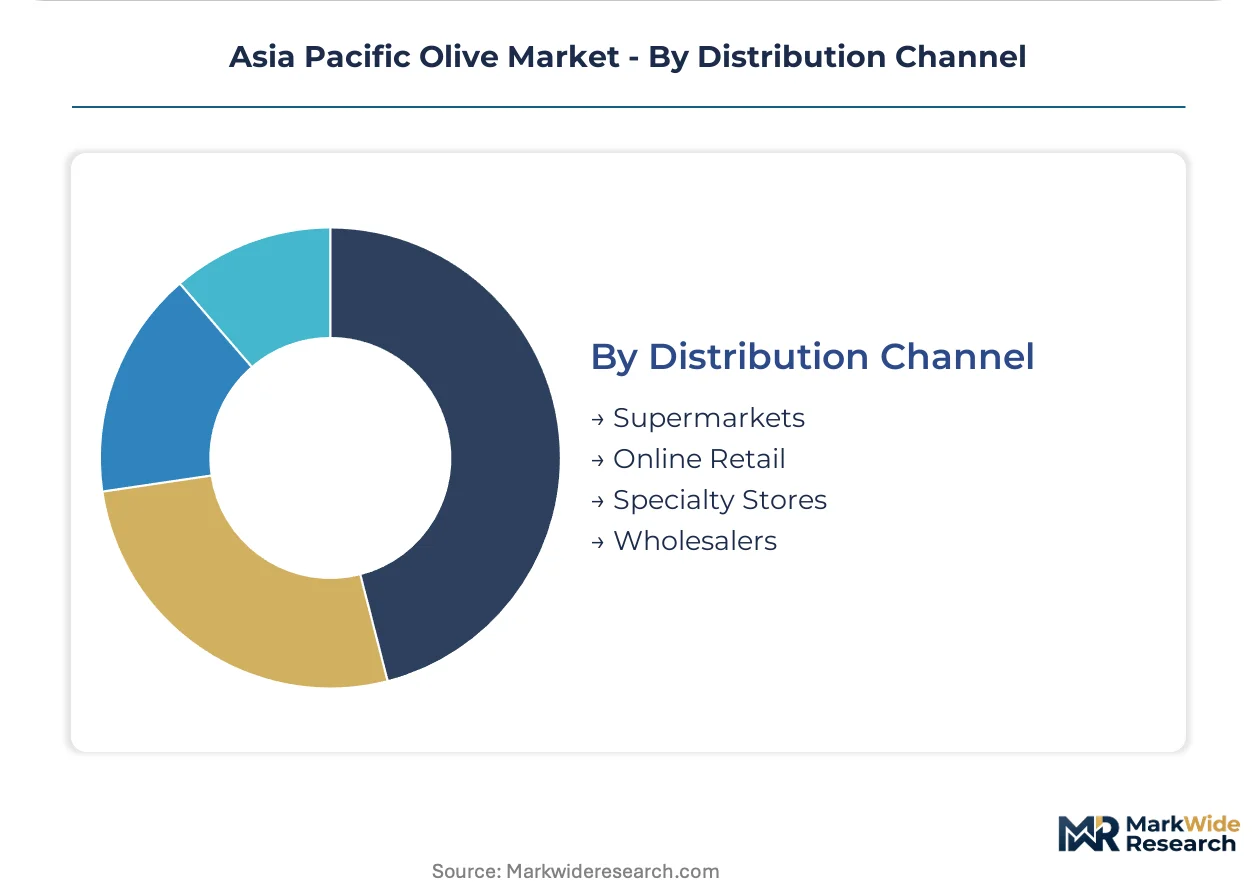
Physical retail infrastructure still captures bulk volume, yet digital channel penetration in Seoul and Tokyo is restructuring margin distribution away from traditional importer-distributor tiers.
- Supermarkets:Australian and Japanese mass-market chains dominate table olive and standard-grade oil volume through centralized procurement with Spanish and Italian cooperative suppliers. Shelf-space negotiations favor suppliers with multi-jurisdiction residue certification.
- Online Retail:South Korean mobile-first platforms exceed regional averages for olive oil e-commerce penetration, with Seoul metropolitan subscription services sourcing single-estate oils direct from Mediterranean crushing facilities.
- Specialty Stores:Melbourne and Sydney gourmet retailers stock high-polyphenol estate-bottled oils with harvest-lot documentation for affluent household segments prioritizing provenance verification.
- Wholesalers:Consolidated national distributors with direct Mediterranean contracts supply Australian food service chains, compressing traditional import-agent margins through volume aggregation.
Volume leadership remains with Supermarkets. Channel expansion is climbing the fastest in Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Australia's olive-growing corridors, Japan's institutional food service networks, and South Korea's emerging direct-to-consumer channels, with each market segment imposing distinct procurement specifications on Mediterranean suppliers.
Australia
Domestic orchard expansion in South Australia and the Murray-Darling basin drives nursery stock demand, while Food Standards Australia New Zealand residue protocols filter procurement toward certified Mediterranean exporters. Biosecurity quarantine extensions for olive plant material imports are elevating working capital requirements for domestic producers establishing new groves.
Japan
Hospital and corporate cafeteria operators in the Kanto region are expanding Mediterranean menu lines, pulling bulk extra-virgin volumes through consolidated national distributors. The Ministry of Health, Labour and Welfare is tightening origin labeling requirements for blended oils, forcing segregation of crush lots at source facilities and shifting procurement toward single-origin certified shipments.
South Korea
Seoul and Busan metropolitan subscription services for single-origin oils are bypassing traditional supermarket markups, with mobile-first platforms exceeding regional averages for olive oil e-commerce penetration. MFDS import documentation requirements for health claim substantiation are shaping supplier selection for functional food positioning.
China
Shanghai and Guangzhou port authorities are piloting pre-cleared Mediterranean supplier programs to reduce customs clearance friction for bulk shipments. SAMR labeling integrity enforcement and maximum residue limit testing are consolidating procurement toward multi-jurisdiction certified Spanish and Italian cooperatives.
Singapore
Transshipment hub operators are deploying nitrogen-flushed tank facilities to reduce polyphenol oxidation during tropical transit, enabling high-grade oil positioning for Australian and Japanese buyers. The city-state's controlled-atmosphere storage infrastructure is absorbing margin compression from extended supply chain investments.
Asia Pacific Olive Market Competitive Environment
Mediterranean cooperatives anchor one tier; California-based specialists hold shorter-lane freight advantages to East Asian ports. Market structure tilts toward consolidated procurement relationships with direct crushing partnerships, though distributor fragmentation persists in premium channels. Three archetypes dominate: Spanish-Italian bulk exporters with nitrogen-sparged processing, Australian domestic growers with biosecurity-certified nursery integration, and direct-to-consumer platform operators in Seoul and Tokyo. Competitive moves concentrate on backward integration into crushing infrastructure and geographic expansion through controlled-atmosphere storage partnerships at transshipment hubs.
Within the Mediterranean bulk-export tier, Deoleo S.A. and Borges International Group represent archetypes of scale-driven suppliers with established nitrogen-flushed logistics chains. California Olive Ranch occupies a position exemplifying shorter-ocean-freight competitive positioning against traditional Mediterranean lanes. These three entities anchor the supplier base referenced across Australian institutional procurement and Japanese distributor consolidation patterns.
| Leading Market Players |
|---|
| Deoleo S.A. |
| Sovena Group |
| Borges International Group |
| Colavita S.p.A. |
| California Olive Ranch |
| Gallo Worldwide |
| Del Monte Foods, Inc |
| Cargill, Incorporated |
| Ybarra Group |
| Others |
Value Chain & Pricing Dynamics
Nitrogen-sparged crushing and malaxation systems are compressing cost economics for high-polyphenol grades while simultaneously concentrating supply relationships around Mediterranean cooperatives with certified processing infrastructure. This technology shift rewards Spanish and Italian exporters with capital-intensive equipment, fragmenting procurement toward direct crushing partnerships and away from commodity spot markets.
Pricing Analysis
Volume concentration in Australian and Japanese institutional kitchens runs at thinner margins than premium direct-to-consumer channels in Seoul and Tokyo. Three-tier pricing structure across premium, standard, and economy levels separates nitrogen-flushed single-origin shipments from commodity bulk grades and refined culinary oils. Pricing pressure stems from substitution toward rice bran and grapeseed oils in Southeast Asian manufacturing when polyphenol specifications relax. Food service buyers exhibit highest price sensitivity, while organic market subscribers accept harvest-date premiums for traceable estate bottlings.
Supply Chain Analysis
Ocean freight lane economics from Mediterranean crush facilities to East Asian ports favor Spanish and Italian exporters over California competitors on pure distance, though nitrogen-flushed tank availability constrains high-grade positioning. Raw material dependencies center on certified nursery stock for Australian domestic expansion, nitrogen gas supply for polyphenol preservation, and refrigerated container capacity for cold-chain grades. Single-source vulnerability concentrates in Singapore transshipment hub infrastructure for controlled-atmosphere storage. Distribution runs through consolidated national distributors with direct Mediterranean contracts, compressing traditional import-agent margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia Pacific olive market sits in a technology-transition phase where nitrogen-sparged processing infrastructure is displacing conventional crushing methods that degrade volatile phenolic compounds through extended transit.
For Market Incumbents: Deepen backward integration into Mediterranean crushing infrastructure to secure nitrogen-flushed capacity ahead of Australian and Japanese institutional procurement consolidation. Invest in multi-jurisdiction residue certification spanning Food Standards Australia New Zealand, Japan's Ministry of Health, Labour and Welfare, and China's SAMR to filter out informal competitors. Defend against California Olive Ranch's shorter-lane freight advantage by locking controlled-atmosphere storage partnerships at Singapore transshipment hubs. For New Entrants and Emerging Players: Direct-to-consumer subscription platforms in Seoul and Busan represent the most penetrable buyer archetype, with mobile-first penetration rates exceeding regional averages and household olive oil consumption still below Japanese benchmarks. Target Southeast Asian condiment manufacturers integrating olive paste into halal-certified export marinades as a white-space manufacturing application. Enter through harvest-date documentation and blockchain traceability positioning that bypasses traditional supermarket markups. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by Mediterranean bulk exporters seeking nitrogen-sparged processing technology and Asia Pacific distributor relationships. Long-term viability hinges on securing biosecurity-certified nursery stock pipelines for Australian domestic orchard expansion and cold-chain logistics partnerships for high-polyphenol grade preservation. Watch for inflection in Singapore controlled-atmosphere storage capacity additions as signal of supply chain investment momentum.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Crushing Infrastructure | Secures nitrogen-sparged capacity for polyphenol preservation demanded by Australian institutional buyers. |
| Controlled-Atmosphere Storage Partnership | Singapore hub deployment reduces oxidation for high-grade oils during tropical transit to Japanese ports. |
| Multi-Jurisdiction Certification Investment | Parallel FSANZ, MHLW, and SAMR testing capabilities filter procurement toward compliant Mediterranean exporters. |
| Direct-to-Consumer Platform Launch | Seoul and Tokyo subscription services bypass traditional importer-distributor markups for single-estate positioning. |
| Biosecurity-Certified Nursery Expansion | Australian domestic grove establishment requires pre-approved Mediterranean stock under tightening quarantine protocols. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with olive oil procurement managers at Australian food service chains, crushing facility operators in Spain and Italy, and Singapore transshipment hub logistics directors. Food Standards Australia New Zealand residue limit documentation, Japan's Ministry of Health, Labour and Welfare labeling requirements, and China's SAMR import clearance records provided regulatory validation. Bottom-up orchard capacity assessments and top-down regional consumption estimates were triangulated against Mediterranean export statistics.
Data-stream reconciliation across crush volume reports, nitrogen-flushed shipment manifests, and retail scanner data from Australian supermarkets and South Korean e-commerce platforms shaped the analytical framework. Segmentation dimensions modeled include product type, end user archetype, application function, and distribution channel across the projection horizon. CAGRs were derived from trend extrapolation of institutional procurement contract values and direct-to-consumer subscription growth rates, with irrigation infrastructure investment cycles and biosecurity protocol evolution as olive-specific forecast inputs.
Revisions become necessary when Australian biosecurity inspection bottlenecks extend nursery stock quarantine periods beyond working capital tolerance, or when Singapore refrigerated container availability constraints force inventory positioning failures ahead of harvest. Forecasts reflect assumptions about nitrogen-sparged processing technology adoption rates and substitution elasticity toward alternative oils in Southeast Asian manufacturing. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Dried Jujubes Market
Fruits and Vegetables
Canada Fruits and Vegetables Market
Fruits and Vegetables
Europe Blueberry Market
Fruits and Vegetables
Global Banana Market
Fruits and Vegetables
Vaccinium Myrtillus Market
Fruits and Vegetables
Japan Avocado Market
Fruits and Vegetables
GCC Fruits and Vegetables Market
Fruits and Vegetables
Bahrain Fruits and Vegetables Market
Fruits and Vegetables
Cambodia Fruits and Vegetables Market
Fruits and Vegetables
Argentina Fruits & Vegetables Market
Fruits and Vegetables
Sea Buckthorn Market
Fruits and Vegetables
Global Hass Avocado Market
Fruits and Vegetables
Fresh Cherries Market
Fruits and Vegetables
Infused Dried Fruits Market
Fruits and Vegetables
Dried Grapes Market
Fruits and Vegetables
Annatto Market