
 Personalized Meals Market | 2026-2036
Personalized Meals Market Size, Share, and Industry Trends Forecast 2026-2036
Personalized Meals Market Analysis
Corporate wellness programs is rebalancing toward personalized nutrition as employers seek measurable health outcomes from food benefits. HelloFresh leverages its logistics infrastructure to sustain national coverage density. Blue Apron competes on recipe complexity, while Trifecta Nutrition specializes in medically tailored meals for restricted-diet populations.
Personalized meals constitute individually configured food preparations calibrated to consumer-specific nutritional profiles, allergen restrictions, and metabolic markers, produced through algorithmic menu generation and portion-controlled assembly lines. The primary commercial purpose centers on reducing dietary-related health risks while eliminating consumer meal-planning friction. Ready-to-eat offerings anchor current revenue pools due to convenience premiums, though meal kits retain stronger engagement metrics among cooking-interested segments. Keto and gluten-free dietary preferences command margin concentration as ingredient sourcing complexity limits competitor entry.
FDA nutrition labeling requirements and USDA organic certification standards shape product formulation transparency across the United States, while state-level cottage food laws create uneven market access for emerging producers. The Federal Trade Commission monitors subscription billing practices, directly influencing customer acquisition cost structures. Stakeholders must weigh biomarker data integration investments against evolving privacy frameworks before committing to next-generation personalization infrastructure.
Market Dynamics
Biomarker-to-kitchen data pipelines are restructuring competitive advantage in personalized meals, forcing providers to integrate continuous glucose monitors and microbiome sequencing into subscription workflows or surrender margin to algorithmic specialists.
Growth Catalysts
- Corporate wellness mandates:Large employers in the United States now subsidize medically tailored meal benefits as deductible preventive health expenditures under IRS Section 213. Human resources departments treat food-as-medicine programs as measurable productivity investments.
- AI recipe generation:Machine learning models trained on metabolic response datasets now automate menu personalization at scale, collapsing the cost gap between mass-produced and individually configured meals.
- California metabolic health clusters:Concentrated demand in Los Angeles and San Francisco Bay Area metros sustains premium pricing power and attracts specialized ingredient suppliers.
Market Restraints
- Perishable ingredient volatility:Avocado, wild-caught salmon, and organic produce prices swing unpredictably, compressing gross margins on keto and paleo meal lines that depend on these inputs.
- Cold-chain infrastructure concentration:Third-party logistics providers controlling refrigerated last-mile delivery in Texas and Florida extract premium rates during peak summer demand windows.
- FDA labeling complexity:Evolving requirements for bioactive compound disclosures on personalized meal packaging extend compliance timelines and raise reformulation costs.
Strategic Opportunities
- Medicare Advantage integration:CMS pilot programs for food-is-medicine benefits in Texas and New York create reimbursement pathways for medically tailored meal providers serving diabetic and renal-diet populations.
- Microbiome-test bundling:Partnerships with at-home gut health testing companies enable predictive personalization before subscription commencement, reducing churn through stickier data relationships.
- Smart kitchen appliance convergence:Integration with WiFi-enabled ovens and precision cookers allows meal kit providers to automate cooking parameters, eliminating user error and standardizing outcomes.
Industry Challenges
- Registered dietitian scarcity:Credentialing bottlenecks slow the hiring of clinical nutrition staff needed to validate algorithm-generated meal plans for restricted-diet subscribers.
- HIPAA-compliant data architecture:Building segregated cloud infrastructure for biomarker storage demands capital commitments that strain Series B-stage providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Personalized Meals Market |
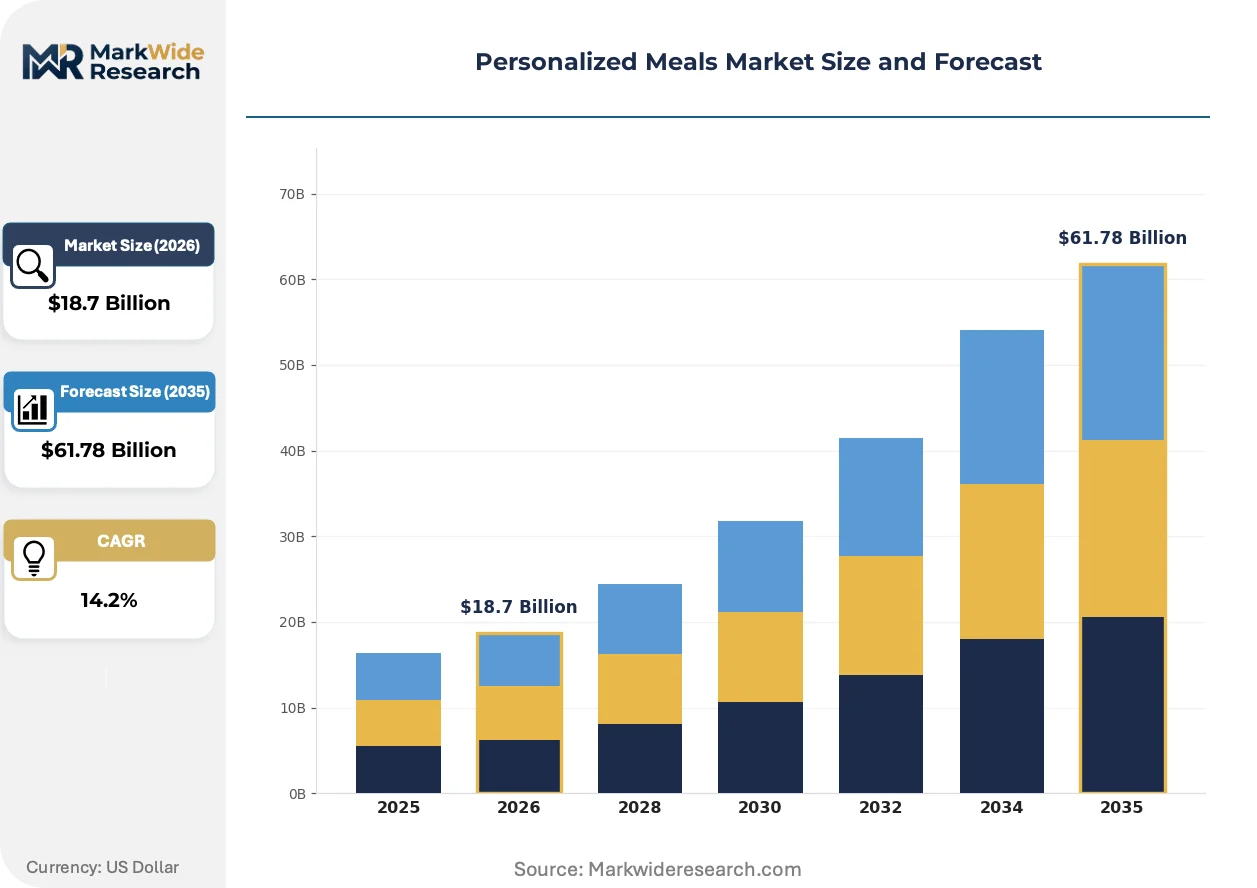
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ready-to-Eat, Meal Kits, Fresh Ingredients, Pre-portioned Dietary Preference: Vegan, Keto, Gluten-Free, Paleo Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Meal Delivery Services Target Audience: Health-Conscious Consumers, Busy Professionals, Families, Fitness Enthusiasts |
| Companies Covered | Home Chef, Freshly, HelloFresh, MightyMeals, Dinnerly, Blue Apron, Sakara, Trifecta Nutrition, Cook Unity, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Personalized Meals Market Emerging Trajectories
Algorithmic personalization is migrating from reactive menu selection to predictive metabolic intervention, with providers investing in continuous monitoring hardware and prescription-food pathways that reposition meals as clinical tools rather than convenience products.
Continuous glucose monitor integration is absorbing the role of static dietary questionnaires in meal personalization protocols. Corporate wellness programs in California and Texas now subsidize CGM patches for employees enrolled in metabolic health subscriptions. The technology is absorbing diagnostic functions previously performed by laboratory blood panels, compressing feedback loops from weeks to hours and enabling real-time menu adjustments.
The FTC's updated subscription billing rule is tightening consent requirements for recurring meal plan charges. Providers must obtain explicit affirmative consent before each billing cycle change, increasing customer acquisition friction but reducing chargeback rates. Meal kit companies operating across state lines are consolidating billing systems to ensure uniform compliance, with the largest operational burden falling on multi-brand portfolios.
Employer procurement of food benefits is consolidating through benefits administration platforms rather than direct vendor relationships. Third-party administrators like those serving Fortune 500 companies in New York now bundle personalized meal subsidies with mental health and fitness allowances. This channel shift concentrates buyer power among a handful of platform gatekeepers, forcing meal providers to absorb integration costs and standardized pricing tiers to maintain access.
Personalized Meals Market Segmentation
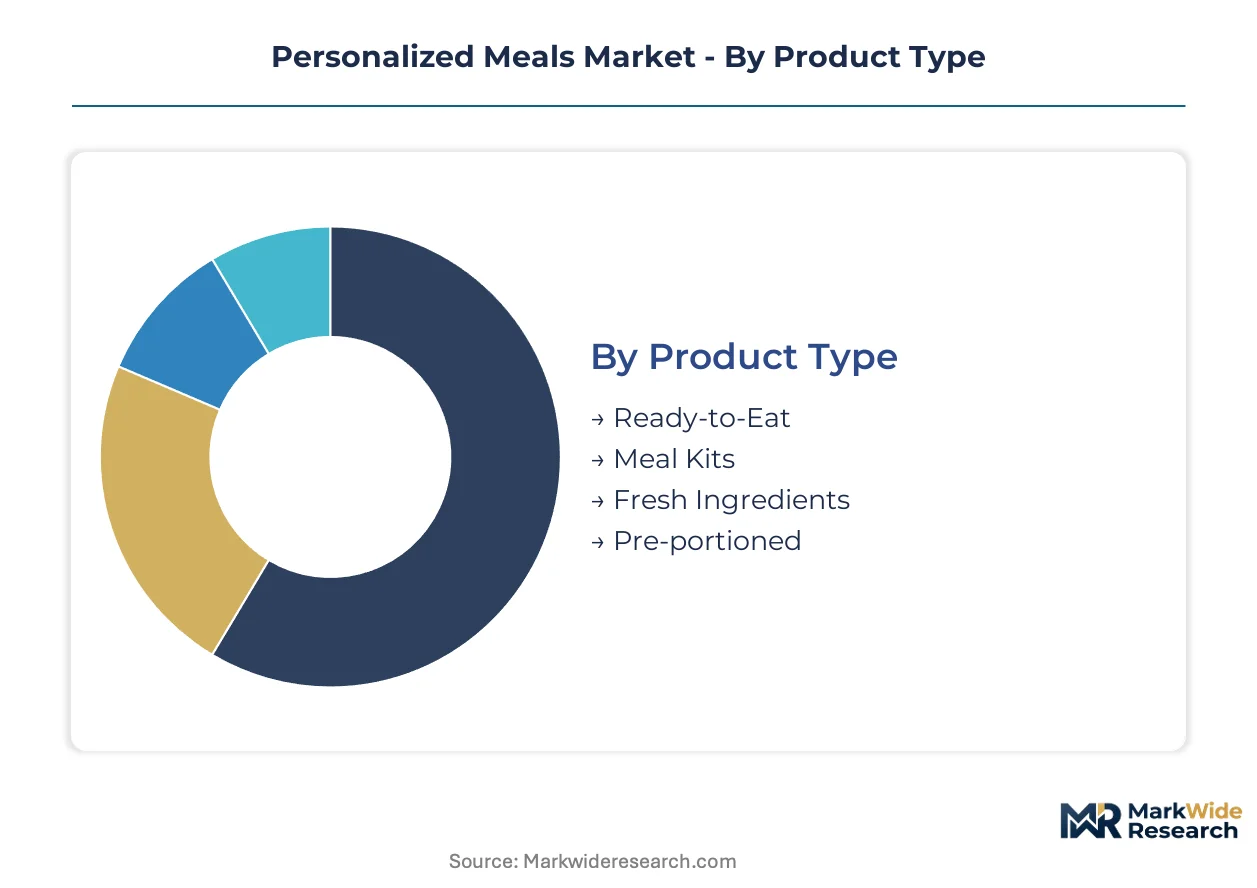
Segmentation in personalized meals determines capital allocation across production infrastructure, with ready-to-eat lines demanding automated assembly investment while meal kits require variable-cost labor pools. Providers must match facility configuration to segment-specific margin profiles and perishability windows.
Product Type:
Capital intensity varies sharply across production formats, with cold-chain packaging automation representing the dominant upfront cost differentiator.
- Ready-to-Eat:Fully prepared meals sealed in modified-atmosphere packaging require blast-chilling tunnels and robotic portioning systems. Demand concentrates in California metropolitan corridors where corporate wellness subsidies offset premium pricing. FDA low-acid canned food regulations extend compliance timelines for shelf-stable extensions.
- Meal Kits:Portioned raw ingredients with recipe cards demand flexible assembly lines and high-SKU inventory management. Texas and Florida logistics clusters absorb the highest fulfillment volumes due to population density and last-mile infrastructure density.
- Fresh Ingredients:Unprocessed produce and proteins sold as personalized bundles require minimal processing capital but demand rapid inventory turnover. USDA organic certification premiums apply.
- Pre-portioned:Individually weighed components for home assembly occupy a midpoint between kits and ingredients. Cottage food law variations across states create uneven market access for emerging producers.
Most installed capacity flows through Ready-to-Eat. Expansion is steepest in Meal Kits.
Dietary Preference:
Ingredient sourcing complexity creates margin tiering, with restricted-diet formulations commanding price premiums that reflect supply base limitations.
- Keto:High-fat, low-carbohydrate formulations depend on avocado, grass-fed beef, and specialty dairy with volatile input costs. California and Texas metabolic health clusters sustain the densest subscriber concentrations.
- Gluten-Free:Certified allergen-free production lines require dedicated facilities and third-party verification. Demand from celiac and non-celiac gluten-sensitive populations concentrates in New York and California urban markets.
- Vegan:Plant-protein formulations leverage pea and soy isolates with improving sensory profiles. Ingredient innovation pipelines focus on texture replication for meat-analog applications.
- Paleo:Grain-free, dairy-free preparations emphasize wild-caught proteins and organic produce with pronounced seasonal price swings.
Keto and Gluten-Free together capture the highest margin concentration. Vegan is gaining share fastest among younger subscriber cohorts.
Distribution Channel:
Channel selection determines customer acquisition economics, with direct-to-consumer models requiring upfront technology investment while retail placement demands slotting fee reserves.
- Meal Delivery Services:Subscription-first platforms with proprietary logistics networks dominate recurring revenue capture. FTC subscription billing rules tighten consent requirements for recurring charges.
- Online Retail:Third-party marketplace listings expand reach but compress margins through platform fees and fulfillment service charges.
- Supermarkets:Refrigerated retail placement requires regional distribution partnerships and promotional spend commitments.
- Specialty Stores:Health food and organic grocers offer targeted access to pre-qualified dietary-restricted consumers with lower acquisition costs.
Meal Delivery Services anchor current revenue pools. Online Retail is expanding most quickly as platform infrastructure matures.
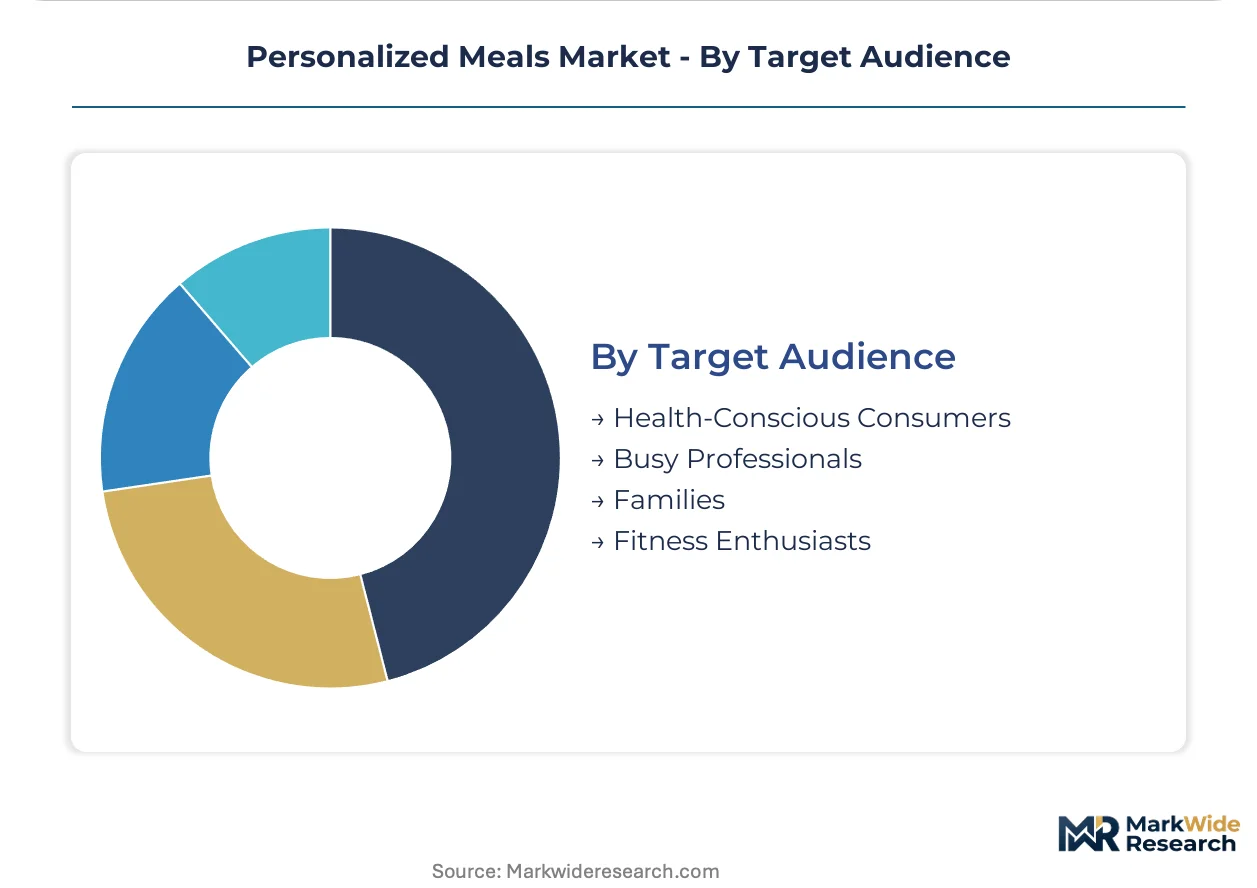
Target Audience:
Audience segmentation shapes personalization algorithm training data requirements, with biomarker integration most advanced among clinically motivated subscriber pools.
- Health-Conscious Consumers:Prevention-focused subscribers with continuous glucose monitor adoption and microbiome test integration. California and New York metro areas concentrate demand.
- Busy Professionals:Time-constrained users prioritizing convenience over cooking engagement, driving ready-to-eat preference.
- Families:Multi-portion meal planning with pediatric allergen management requirements and volume pricing sensitivity.
- Fitness Enthusiasts:Macro-tracking subscribers with protein-targeted formulations and performance-oriented nutrient timing.
Health-Conscious Consumers generate the highest lifetime value. Busy Professionals represent the largest addressable expansion pool.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redrawing production footprints as personalized meal providers migrate assembly capacity toward jurisdictions with streamlined food safety certification and lower cold-chain compliance costs. This reconfiguration concentrates investment in markets where FDA, EFSA, and national health authority frameworks create differential cost structures for biomarker-integrated meal production.
United States
Corporate wellness subsidies and Medicare Advantage food-is-medicine pilots in Texas and New York are accelerating medically tailored meal adoption. FDA nutrition labeling requirements and FTC subscription billing rules shape compliance investments across multi-state operations. The Los Angeles and San Francisco Bay Area metros anchor the densest concentration of metabolic health subscribers and specialized ingredient suppliers.
Germany
EFSA novel food regulations and the EU Green Deal's farm-to-fork traceability mandates are elevating formulation transparency requirements for algorithmic meal providers. BfR (Federal Institute for Risk Assessment) guidance on bioactive compound claims extends product development timelines. The Berlin-Brandenburg corridor hosts emerging precision-nutrition startups integrating with statutory health insurance wellness programs.
United Kingdom
MHRA borderline regulations for nutraceutical-meal hybrids and post-Brexit divergence from EU food law are creating compliance complexity for biomarker-linked subscriptions. The Food Standards Agency's evolving guidance on personalized nutrition claims shapes marketing permissibility. London's venture capital concentration funds AI-driven recipe generation platforms targeting corporate benefits administrators.
Japan
METI's Society 5.0 health data integration policies and PMDA's evolving framework for software-as-medical-device are enabling CGM-meal subscription bundling. Consumer Affairs Agency labeling rules for function-specific foods constrain health claim breadth. The Tokyo metro area concentrates demand among aging populations seeking renal-diet and diabetic meal precision.
Australia
FSANZ novel food approvals and TGA's expanding regulation of companion diagnostic devices are structuring biomarker test-and-meal bundled offerings. The Therapeutic Goods Administration's software-based medical device framework creates pathways for algorithmic meal interventions. Sydney and Melbourne anchor corporate wellness program adoption among mining and financial services employers.
Personalized Meals Market Vendor Landscape
Strategic partnerships dominate the current landscape as algorithmic specialists ally with logistics networks and diagnostic hardware providers to close capability gaps. The vendor base segments across three tiers: vertically integrated meal-kit incumbents with proprietary cold-chain infrastructure, AI-native personalization platforms without production assets, and clinically validated medically tailored meal specialists serving restricted-diet populations. Market structure rewards scale in last-mile refrigerated delivery and regulatory expertise in health claim substantiation. Consolidation pressure concentrates on mid-cap providers lacking either biomarker data pipelines or national fulfillment density.
Within the algorithmic personalization tier, HelloFresh and Blue Apron exemplify divergent strategic postures toward data-driven meal configuration, while Trifecta Nutrition occupies a position within the medically tailored specialization segment. These three anchors represent the spectrum from mass-market convenience optimization through clinically validated dietary intervention, illustrating how competitive positioning stratifies across biomarker integration depth and regulatory compliance intensity rather than production scale alone.
| Leading Market Players |
|---|
| Home Chef |
| Freshly |
| HelloFresh |
| MightyMeals |
| Dinnerly |
| Blue Apron |
| Sakara |
| Trifecta Nutrition |
| Cook Unity |
| Others |
Supply Flow & Price Mechanics
Wild-caught salmon and organic avocado costs cascade through keto and paleo meal tiers, compressing margins at the premium end while subscription billing friction under FTC scrutiny pushes providers toward standardized pricing bands across corporate wellness channels.
Pricing Analysis
Direct-to-consumer subscription margins absorb the highest customer acquisition friction under tightened FTC consent requirements. Three-tier pricing structure across premium medically tailored, standard health-conscious, and economy convenience tiers separates biomarker-integrated offerings from basic meal kit configurations. Pricing pressure stems from perishable ingredient volatility in California and Texas metabolic health clusters. Corporate wellness buyers exhibit lowest price sensitivity due to IRS Section 213 deductibility, while individual subscribers in Florida and New York show highest churn responsiveness to billing changes.
Supply Chain Analysis
Direct-to-corporate-benefits-administrator channels handle Fortune 500 employer demand consolidation, bypassing traditional retail markups. Cold-chain infrastructure concentrates in California, Texas, and Florida logistics clusters, with third-party refrigerated last-mile providers extracting seasonal premiums. Raw material sourcing draws from wild-caught fisheries in Alaska, organic produce networks in California's Central Valley, and specialty dairy suppliers in Wisconsin. Single-source vulnerability in CGM hardware partnerships with metabolic testing companies creates supply risk for algorithmic personalization providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where employer procurement consolidation through benefits platforms shifts demand toward clinically validated, biomarker-integrated meal specifications.
For Market Incumbents: Anchor defensible positioning through backward integration into refrigerated last-mile networks in Texas and Florida, securing capacity before peak summer demand windows. Deepen HIPAA-compliant cloud infrastructure investments to validate algorithm-generated meal plans against registered dietitian credentialing bottlenecks. The priority lever sits with Medicare Advantage reimbursement pathway capture in food-is-medicine pilot states. For New Entrants and Emerging Players: AI-native recipe generation platforms without production assets represent the most penetrable white-space target, enabling asset-light entry before cold-chain infrastructure consolidation hardens. Target microbiome-test bundling partnerships with at-home gut health testing companies to establish predictive personalization before subscription commencement. The go-to-market angle centers on corporate wellness platform integration rather than direct employer sales. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-cap providers lack either biomarker data pipelines or national fulfillment density, creating acquisition opportunities for algorithmic specialists allied with logistics networks. Long-term viability favors vertically integrated meal-kit incumbents with proprietary cold-chain infrastructure and regulatory expertise in health claim substantiation. The signal to watch is CMS pilot program expansion for food-is-medicine benefits across additional states.| Strategic Initiative | Industry Significance |
|---|---|
| CGM-Meal Subscription Bundling | Continuous glucose monitor integration compresses feedback loops from weeks to hours for metabolic health subscribers. |
| HIPAA-Compliant Data Architecture Buildout | Segregated cloud infrastructure for biomarker storage satisfies privacy frameworks before next-generation personalization commitments. |
| Medicare Advantage Reimbursement Pathway Capture | CMS pilot programs in Texas and New York create reimbursement channels for diabetic and renal-diet populations. |
| Corporate Wellness Platform Integration | Benefits administration platform consolidation concentrates buyer power among Fortune 500 gatekeepers in New York. |
| Smart Kitchen Appliance Convergence | WiFi-enabled oven integration eliminates user error and standardizes cooking outcomes for meal kit subscribers. |
Methodological Framework
Coverage spans United States, Germany, United Kingdom, Japan, and Australia, with primary inputs from each market's regulatory and demand clusters. Primary interviews combined insights from registered dietitians at medically tailored meal providers, human resources benefits administrators at Fortune 500 employers, cold-chain logistics operators, CGM hardware procurement leads, and FDA regulatory affairs specialists. Secondary validation drew from FDA nutrition labeling guidance documents, FTC subscription billing rule updates, CMS Medicare Advantage pilot announcements, USDA organic certification databases, and EFSA novel food regulation filings. Bottom-up subscriber and revenue estimates triangulated against top-down market sizing from corporate wellness expenditure tracking.
Rate-of-change decomposition across the projection horizon disaggregated growth into employer subsidy expansion, biomarker test adoption curves, and algorithmic personalization penetration by dietary restriction severity. Segmentation modeling covered product type, dietary preference, distribution channel, and target audience dimensions, with additional granularity on metabolic health cluster density by metropolitan area. CAGRs derived from logistic adoption curve fitting applied to continuous glucose monitor penetration rates and corporate wellness program enrollment trends. Forecast inputs incorporated IRS Section 213 deductibility policy stability and FDA bioactive compound disclosure timeline assumptions.
The model holds under stable employer wellness benefit deductibility and CMS pilot program continuity; deviation in FTC subscription billing enforcement intensity or HIPAA privacy framework expansion would shift customer acquisition cost assumptions and data infrastructure investment requirements. Forecasts reflect base-case assumptions regarding perishable ingredient price volatility and cold-chain capacity expansion timelines. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Low Calorie Desserts Market
Specialty Foods
Low Calorie Popsicles Market
Specialty Foods
Low Calorie Oatmeal Market
Specialty Foods
Goldenseal Market
Specialty Foods
Germany Barbeque Grill Market
Specialty Foods
Cannabis-Infused Burger Market
Specialty Foods
Free-From Food Market
Specialty Foods
Global Cocoa Nibs Market
Specialty Foods
Global Guilt-Free Desserts Market
Specialty Foods
Asia-Pacific Alcohol-Infused Ice Cream Market
Specialty Foods
Sea Moss Market
Specialty Foods
Non-GMO Food Products Market
Specialty Foods
Vegetarian Tacos Market
Specialty Foods
Cultures Market
Specialty Foods
Global Freeze-Dried Pet Food Market
Specialty Foods
Medicinal Herbs Market