
 Asia-Pacific Free from Food Market | 2026-2036
Asia-Pacific Free from Food Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Free from Food Market Outlook
The EU Green Deal's extraterritorial sustainability benchmarks are repositioning procurement standards across Asia-Pacific export-facing food manufacturers. Nestlé SA leverages its R&D intensity to reformulate plant-based portfolios for lactose-intolerant consumers across Southeast Asia. Danone SA anchors its competitive position through specialized fermentation capabilities in dairy-free yogurt alternatives. General Mills Inc competes via controlled distribution networks in Japan's premium supermarket channel.
Asia-Pacific free from food encompasses formulated consumables excluding specific allergens, additives, or animal-derived inputs, typically manufactured through enzymatic hydrolysis, mechanical separation, or controlled fermentation to achieve functional parity with conventional equivalents. These products serve clinical dietary management, lifestyle-based restriction, and ethical consumption frameworks across retail and foodservice channels. Gluten-free product lines sustain margin premiums through dedicated milling infrastructure and certification complexity that limits new entrants. Dairy-free alternatives lead volume growth as oat and pea protein extraction technologies mature. Certification-labeled organic and vegan segments occupy the fastest-expanding price tier, particularly through online retail channels where traceability claims convert at higher rates.
FSSAI in India mandates quantitative allergen disclosure for packaged imports, reshaping label adaptation costs for multinational suppliers. China's SAMR enforces GB standards for gluten-free claims with mandatory laboratory verification, while Australia's FSANZ coordinates with Codex Alimentarius for harmonized free-from definitions across trans-Tasman trade. Stakeholders must monitor regulatory divergence between national labeling regimes and certification reciprocity agreements to optimize regional portfolio deployment.
Market Dynamics
China's SAMR enforcement of GB standards for gluten-free claims and India's FSSAI allergen-labeling mandates are forcing reformulation investments across multinational portfolios, compressing timelines for regional product registration.
Growth Catalysts
- Urban health-conscious cohorts:Australia's metropolitan consumers sustain premium pricing for dairy-free alternatives through specialty retail channels. Japanese lactose-intolerant populations drive oat protein adoption in functional beverages.
- FSSAI import disclosure rules:India's quantitative allergen mandates for packaged imports accelerate domestic contract manufacturing capacity expansion.
- Pea protein extraction maturation:Mechanical separation advances reduce input costs for Southeast Asian dairy-free yogurt processors.
Market Restraints
- Certification infrastructure scarcity:Dedicated gluten-free milling facilities concentrate in Australia's eastern seaboard, limiting ASEAN supplier participation.
- GB standard laboratory verification:China's mandatory gluten-free claim testing creates six-month approval bottlenecks for new market entrants.
- Oat protein supply concentration:Raw oat extraction inputs depend on Nordic and North American suppliers, exposing Asia-Pacific formulators to currency and freight volatility.
Strategic Opportunities
- Vietnam's underpenetrated modern trade:Convenience store chains in Ho Chi Minh City and Hanoi lack dedicated free-from shelf space, creating first-mover positioning for private-label specialists.
- FSANZ-Codex harmonization:Trans-Tasman regulatory alignment reduces dual-labeling costs for products distributed across Australia and New Zealand.
- E-commerce traceability premiums:China's Tmall and JD.com platforms convert certified organic and vegan claims at higher price tiers through blockchain-verified supply chain documentation.
Industry Challenges
- Enzymatic hydrolysis talent scarcity:Fermentation technologists capable of achieving functional parity in dairy-free alternatives command premium compensation in Singapore and Tokyo.
- Multi-jurisdiction label adaptation:Divergent allergen disclosure formats between FSSAI, SAMR, and FSANZ regimes multiply packaging SKU complexity for regional brand managers.
- Legacy cold chain gaps:Temperature-controlled distribution infrastructure in Indonesia's archipelago limits probiotic dairy-free yogurt shelf stability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Free from Food Market |
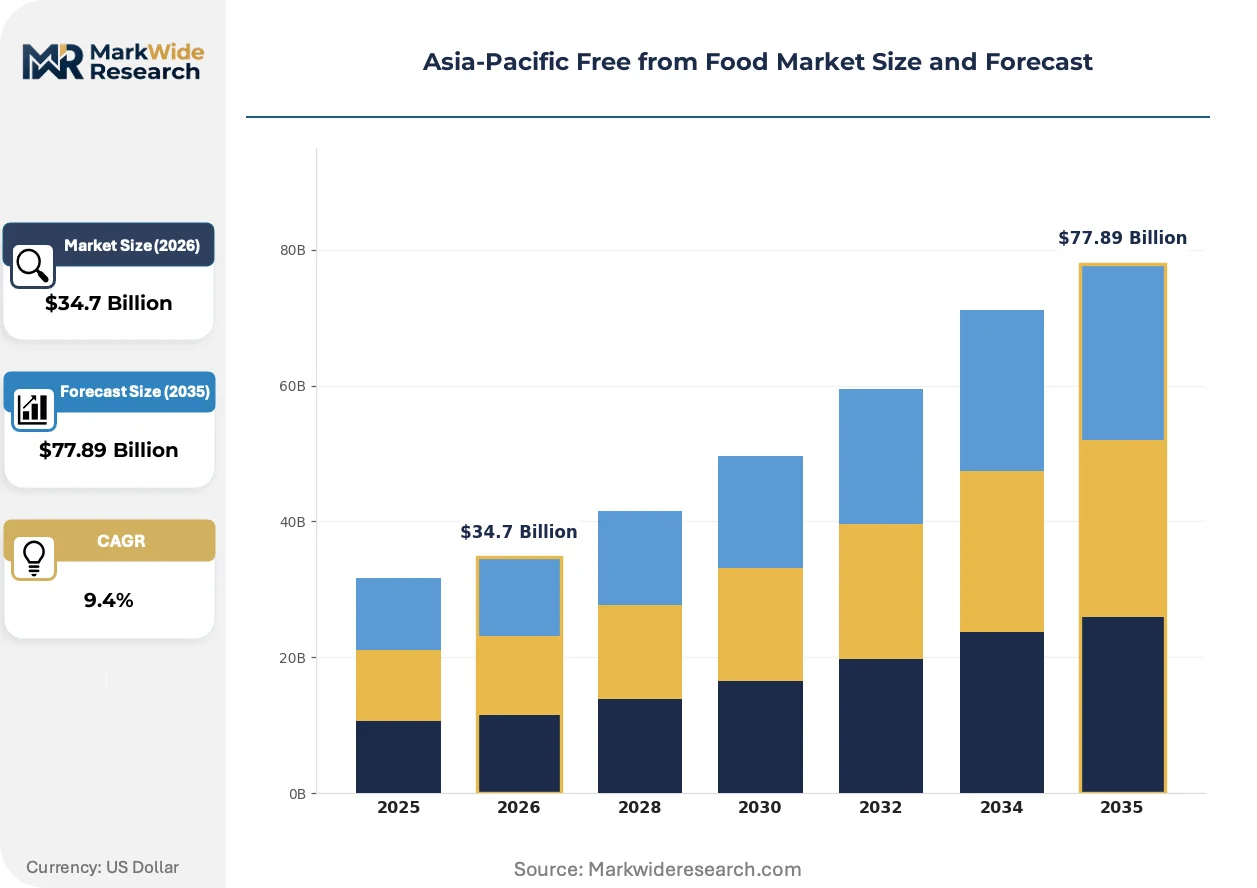
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $77.89 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dairy-Free, Gluten-Free, Nut-Free, Sugar-Free End User: Individuals with Allergies, Health-Conscious Consumers, Diabetics, Vegans Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales Certification: Non-GMO, Organic, Vegan, Others |
| Companies Covered | Conagra Brands Inc, General Mills Inc, Nestlé SA, Hain Celestial Group Inc, Danone SA, The Kraft Heinz Company, Mondelez International, Dr. Schär AG/SPA, Freedom Foods Group Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Free from Food Market Strategic Shifts
Controlled fermentation protocols and enzymatic precision are compressing the functional gap between plant-based and conventional dairy, while regulatory divergence across Asia-Pacific jurisdictions fragments compliance architecture.
Precision fermentation for dairy protein analogs is overtaking traditional mechanical extraction in Southeast Asian manufacturing facilities. Thai and Malaysian contract manufacturers adopt microbial fermentation to replicate casein functionality in cheese alternatives. This biotechnology shift is overtaking capital-intensive whey separation infrastructure and enabling smaller-batch production economics for regional brands.
China's SAMR GB standards for gluten-free claims now mandate laboratory verification with specified detection thresholds. Food manufacturers must submit batch-level test documentation before product registration approval. Australia's FSANZ coordinates with Codex Alimentarius to maintain trans-Tasman harmonization, though China's unilateral threshold definitions create export-labeling friction for Australian suppliers.
Specialty supermarket buyers in Japan's premium channel now require third-party allergen certification as a listing prerequisite. This procurement criterion displaces self-declared free-from claims previously accepted on packaging alone. The certification-driven preference shift concentrates shelf access with suppliers holding ISO 17025-accredited laboratory partnerships, visible in Tokyo and Osaka metropolitan procurement policies.
Asia-Pacific Free from Food Market Segmentation
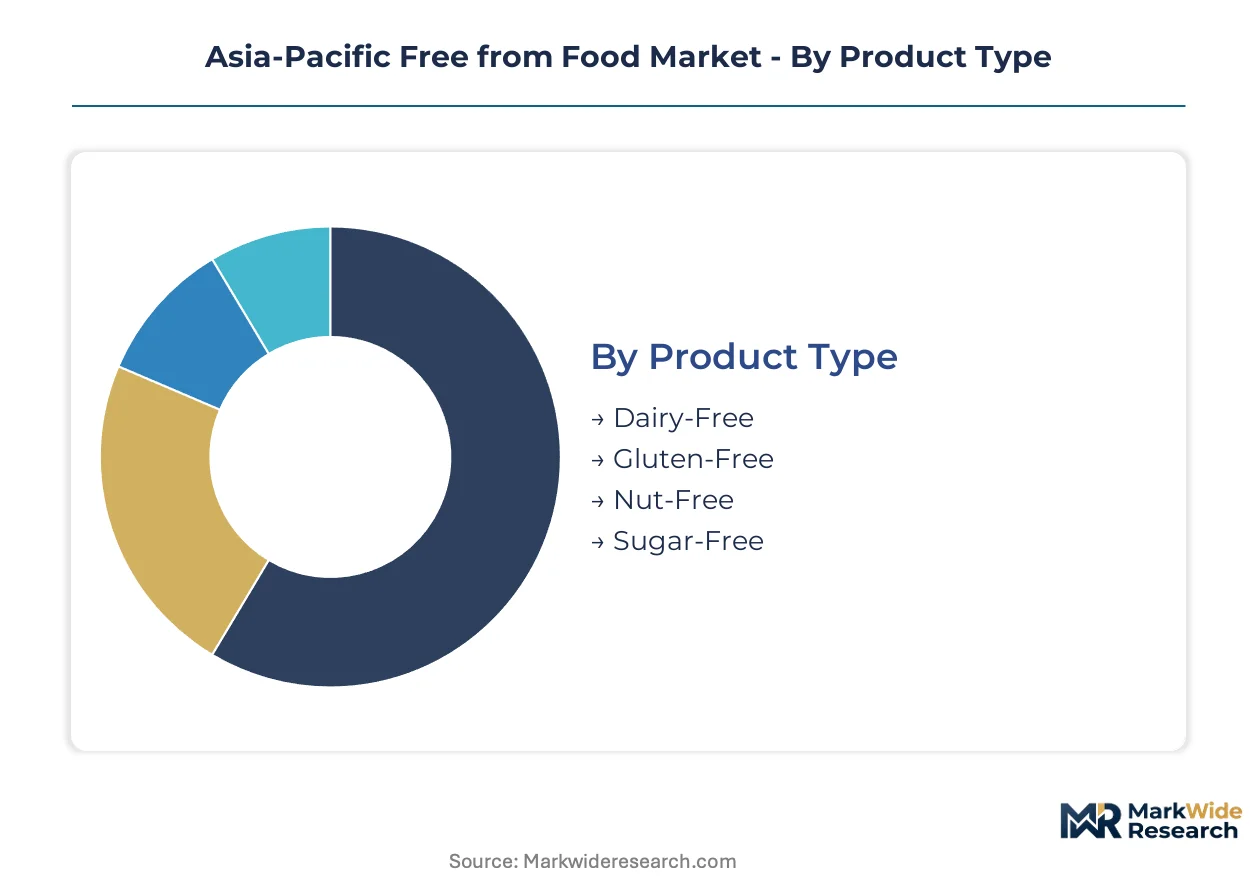
Product differentiation in Asia-Pacific free-from food hinges on certification complexity and extraction technology maturity. Consumer purchasing decisions trace to clinical necessity, lifestyle positioning, and traceability verification across divergent national regulatory regimes.
Product Type:
Buyers prioritize functional parity with conventional equivalents when selecting allergen-excluded formulations.
- Dairy-Free:Oat and pea protein extraction technologies achieve texture replication in yogurt and beverage applications. Australian metropolitan consumers sustain premium pricing through specialty retail channels, while Japanese lactose-intolerant populations drive oat protein adoption in functional beverages.
- Gluten-Free:Dedicated milling infrastructure and enzymatic hydrolysis protocols remove wheat, barley, and rye proteins to specified thresholds. China's SAMR enforces GB standards with mandatory laboratory verification, creating six-month approval bottlenecks that compress multinational registration timelines.
- Nut-Free:Mechanical separation and controlled environment processing eliminate cross-contamination risks for peanut and tree nut allergens. Southeast Asian school nutrition programs in Singapore and Malaysia expand institutional procurement.
- Sugar-Free:Natural and artificial sweetener blends replace sucrose in diabetic-targeted formulations. India's FSSAI quantitative disclosure mandates reshape label adaptation costs for imported packaged goods.
Volume sits with Gluten-Free; growth tilts toward Dairy-Free.
End User:
Application context determines price tolerance and certification requirements across consumer segments.
- Individuals with Allergies:Clinical dietary management demands batch-level allergen testing and quantitative threshold documentation. Australia's FSANZ coordinates with Codex Alimentarius for harmonized definitions supporting trans-Tasman trade.
- Health-Conscious Consumers:Lifestyle-based restriction prioritizes clean-label positioning and ethical sourcing claims. China's Tmall and JD.com platforms convert certified organic and vegan claims at higher price tiers through blockchain-verified supply chain documentation.
- Diabetics:Glycemic control requirements drive sugar-free and low-carbohydrate formulation demand. India's expanding diabetic population accelerates domestic contract manufacturing capacity for specialized nutrition.
- Vegans:Animal-derived input exclusion intersects with environmental and ethical consumption frameworks. Certification-labeled vegan segments occupy the steepest expansion trajectory through online retail channels where traceability claims convert at premium rates.
Allergen-driven necessity commands volume; lifestyle and ethical positioning climbs fastest.
Distribution Channel:
Channel selection reflects supply chain infrastructure maturity and consumer verification behavior.
- Online Retail:E-commerce platforms enable traceability documentation and direct-to-consumer certification transparency. China's fast-scaling digital marketplaces dominate regional volume.
- Supermarkets:Mass-market shelf placement requires FSANZ-aligned labeling for Australia-New Zealand distribution. Japan's premium channel buyers now mandate third-party allergen certification as listing prerequisite.
- Specialty Stores:Dedicated free-from shelf space concentrates in Australia's mature eastern seaboard retail infrastructure. Vietnam's underpenetrated modern trade in Ho Chi Minh City and Hanoi creates first-mover positioning for private-label specialists.
- Direct Sales:Institutional and foodservice contracts bypass retail margin structures. Probiotic dairy-free yogurt distribution faces temperature-controlled infrastructure gaps in Indonesia's archipelago.
Supermarkets anchor current volume; online retail gains share fastest.
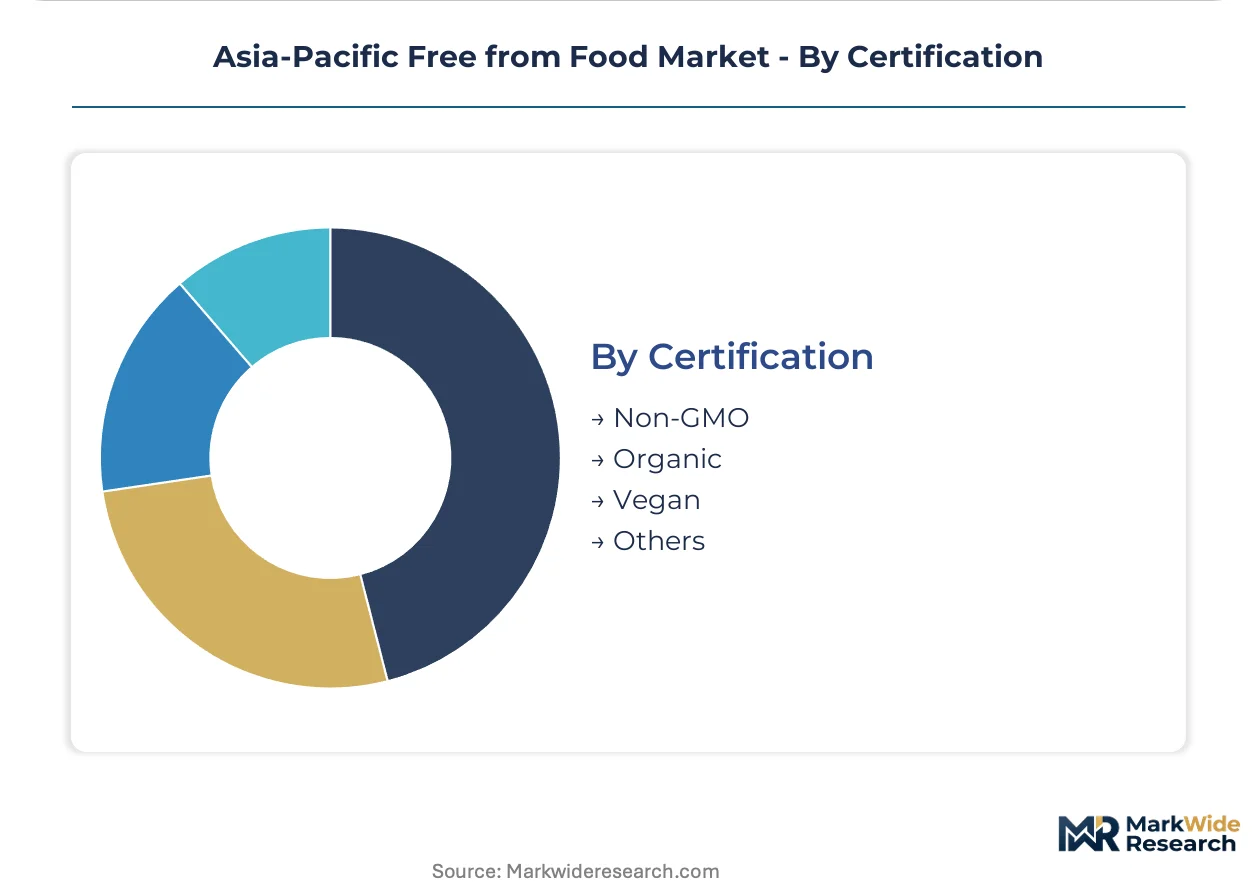
Certification:
Label credibility determines price tier access and export market eligibility.
- Non-GMO:Genetic modification exclusion requires supply chain segregation and testing protocols. Australian export-facing manufacturers align with EU Green Deal extraterritorial sustainability benchmarks.
- Organic:Synthetic input prohibition and soil health standards command premium positioning. Certification complexity limits new entrant participation in this price tier.
- Vegan:Animal-derived input exclusion spans ingredients, processing aids, and cross-contamination controls. ISO 17025-accredited laboratory partnerships concentrate shelf access in Tokyo and Osaka metropolitan procurement policies.
- Others:Halal, kosher, and regional allergen-free designations address niche compliance requirements. Multi-jurisdiction label adaptation multiplies packaging SKU complexity for regional brand managers.
Organic certification holds volume concentration; vegan labeling expands most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production infrastructure for free-from foods concentrates in Australia's eastern seaboard and China's coastal manufacturing zones, while consumption growth accelerates across Southeast Asian urban centers where cold chain investments lag formulation advances.
Australia
Metropolitan consumers in Sydney and Melbourne sustain premium pricing for dairy-free alternatives through mature specialty retail channels. FSANZ coordinates with Codex Alimentarius to maintain trans-Tasman regulatory harmonization with New Zealand. Dedicated gluten-free milling facilities cluster along the eastern seaboard, limiting supplier participation from western states.
China
SAMR enforcement of GB standards for gluten-free claims mandates laboratory verification, creating six-month approval bottlenecks for multinational entrants. E-commerce platforms Tmall and JD.com convert certified organic and vegan claims at higher price tiers through blockchain-verified supply chain documentation. Yangtze River Delta contract manufacturers adopt precision fermentation for dairy protein analogs.
Japan
Lactose-intolerant populations in Tokyo and Osaka drive oat protein adoption in functional beverages. METI-aligned procurement policies now require third-party allergen certification as a supermarket listing prerequisite. Premium channel buyers concentrate shelf access with suppliers holding ISO 17025-accredited laboratory partnerships.
India
FSSAI quantitative allergen disclosure mandates for packaged imports accelerate domestic contract manufacturing capacity expansion. Maharashtra and Gujarat-based processors specialize in sugar-free formulations targeting the country's expanding diabetic population. Label adaptation costs reshape multinational portfolio deployment timelines.
Vietnam
Ho Chi Minh City and Hanoi convenience store chains lack dedicated free-from shelf space, creating first-mover positioning for private-label specialists. Temperature-controlled distribution infrastructure gaps limit probiotic dairy-free yogurt shelf stability across the archipelago. Modern trade penetration remains underdeveloped relative to ASEAN neighbors.
Asia-Pacific Free from Food Market Competitive Environment
The competitive structure tilts toward multinational packaged food conglomerates with existing distribution infrastructure and specialized fermentation capabilities. Tiered positioning separates R&D-intensive reformulators from regional private-label specialists and certified-organic pure-plays. Dominant competitive moves include portfolio diversification into plant-based alternatives and strategic partnerships with ISO-accredited testing laboratories for regulatory compliance acceleration.
Within the multinational conglomerate tier, Nestlé SA and Danone SA exemplify scale-driven positions anchored by specialized fermentation infrastructure and reformulation expertise. General Mills Inc occupies a position representing controlled distribution network advantages in premium retail channels. Among certification-focused specialists, Dr. Schär AG/SPA and Freedom Foods Group Limited exemplify the gluten-free dedicated manufacturing archetype with concentrated milling assets.
| Leading Market Players |
|---|
| Conagra Brands Inc |
| General Mills Inc |
| Nestlé SA |
| Hain Celestial Group Inc |
| Danone SA |
| The Kraft Heinz Company |
| Mondelez International |
| Dr. Schär AG/SPA |
| Freedom Foods Group Limited |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap specialists across Australia's eastern seaboard and China's Yangtze River Delta anchor supply discipline through generational capital commitments, insulating premium tier pricing from volatile oat protein spot markets while compressing margins in commoditized gluten-free flour segments.
Pricing Analysis
Margin tightening in standard-tier dairy-free alternatives reflects maturing pea protein extraction capacity across Thai and Malaysian contract manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates ISO 17025-certified organic lines from FSANZ-aligned mass-market SKUs and private-label economy offerings. Cost-down pressure on economy tiers accelerates because Vietnamese convenience store chains lack dedicated free-from shelf space, forcing price-driven buyer behavior. Health-conscious consumers in Australian metropolitan markets show least price sensitivity, while diabetic-targeted sugar-free segments in India demonstrate highest elasticity.
Supply Chain Analysis
Reverse-logistics infrastructure for temperature-sensitive probiotic dairy-free yogurt remains underdeveloped across Indonesia's archipelago, limiting shelf-stable product returns and refurbishment flows. Raw material inputs draw from Nordic oat extraction suppliers, Australian eastern seaboard gluten-free milling facilities, and Yangtze River Delta precision fermentation operations. Single-source vulnerability concentrates in Nordic oat protein supply, exposing Asia-Pacific formulators to freight and currency volatility. Distribution runs through China's Tmall and JD.com e-commerce platforms for certified organic tiers, with Australia's specialty retail channel anchoring premium offline volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into controlled fermentation infrastructure and captive oat protein supply represents the decisive vertical-integration race, with first movers securing functional parity advantages in dairy-free yogurt alternatives.
For Market Incumbents: Cement defensible positions through ISO 17025-accredited laboratory partnerships that satisfy Japan's METI-aligned procurement prerequisites, while adding dedicated gluten-free milling capacity in Australia's western states to offset eastern seaboard concentration risk. Precision fermentation talent scarcity in Singapore and Tokyo commands premium compensation, threatening margin sustainability for R&D-intensive reformulators.
For New Entrants and Emerging Players: Capture white-space opportunity in Vietnam's underpenetrated modern trade through private-label positioning in Ho Chi Minh City and Hanoi convenience store chains, where dedicated free-from shelf space remains unclaimed. Blockchain-verified supply chain documentation enables premium pricing on Tmall and JD.com platforms for certified vegan entrants.
For Investors and Strategic Acquirers: FSSAI quantitative allergen disclosure mandates accelerating domestic contract manufacturing capacity expansion in India is the leading indicator that regional regulatory divergence will favor localized production assets over import-dependent models. Acquisition targets should demonstrate trans-Tasman FSANZ-Codex harmonization compliance and precision fermentation capabilities. Monitor SAMR GB standard laboratory verification bottlenecks for signals of multinational entrant withdrawal.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Thai and Malaysian contract manufacturers replicate casein functionality without capital-intensive whey separation infrastructure. |
| ISO 17025 Laboratory Partnership | Tokyo and Osaka metropolitan procurement policies now mandate third-party certification as supermarket listing prerequisite. |
| Trans-Tasman Label Harmonization | FSANZ-Codex alignment reduces dual-SKU complexity for products distributed across Australia and New Zealand. |
| E-Commerce Traceability Integration | Blockchain-verified supply chain documentation on Tmall and JD.com converts certified organic claims at premium price tiers. |
| Western Australia Milling Expansion | Dedicated gluten-free capacity outside eastern seaboard concentration addresses ASEAN supplier participation limits. |
Study Parameters
Document review covered FSSAI regulatory filings, SAMR GB standard documentation, FSANZ-Codex alignment protocols, and e-commerce platform traceability specifications, complemented by interviews with fermentation technologists, specialty retail category buyers, contract manufacturing procurement leads, and ISO 17025 laboratory accreditation managers. Secondary validation drew from customs trade data, allergen certification databases, and cold chain infrastructure assessments. Bottom-up volume modeling triangulated against top-down category spend analysis.
Historical volume trajectories cross-referenced against expert panel input on regulatory enforcement timelines and extraction technology maturation curves. Segmentation dimensions spanned product type, end-user clinical necessity versus lifestyle positioning, distribution channel infrastructure maturity, and certification tier complexity. CAGRs derived from regression analysis of adoption rates correlated with urban health-conscious cohort expansion and diabetic population growth across the analysis window. Industry-specific inputs included enzymatic hydrolysis yield improvements and precision fermentation batch economics.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to SAMR unilateral threshold revisions, Nordic oat protein supply disruptions, and FSSAI import disclosure rule expansion. Practitioners should monitor regulatory reciprocity negotiations between FSSAI, SAMR, and FSANZ regimes for early signals of compliance cost reduction or amplification.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Global Hispanic Foods Market
Specialty Foods
Almond-Based Spreads Market
Specialty Foods
Global Diet Food and Beverages Market
Specialty Foods
Personalized Meals Market
Specialty Foods
Gluten-Free Oats Market
Specialty Foods
Miso Market
Specialty Foods
Jams, Jellies & Preserves Market
Specialty Foods
Military Forces Ready to Eat Meals Market
Specialty Foods
Honey Spread Market
Specialty Foods
Fermented Black Beans Market
Specialty Foods
CBD-Infused Ice Cream Market
Specialty Foods
Spirulina Chocolate Market
Specialty Foods
Aloe Butter Market
Specialty Foods
Global Truffle Market
Specialty Foods
Space Food Market
Specialty Foods
High Protein Cat Food Market