
 Silver Food Market | 2026-2036
Silver Food Market Size, Share, and Industry Trends Forecast 2026-2036
Silver Food Market Analysis
Specialty stores and curated e-commerce platforms is rewriting how silver food articles reach end buyers. Pan American Silver leverages its mining scale to anchor supply security for downstream fabricators. First Majestic Silver competes through vertical integration from extraction to refined bullion. Hecla Mining Company sustains North American production dominance with long-life operating assets.
Silver food denotes culinary and tableware articles fabricated from sterling silver or silver-plated substrates, typically comprising 92.5% pure silver alloyed with copper for structural durability, with antimicrobial surface properties that inhibit bacterial colonization during food service. The primary commercial purpose centers on prestige dining, ceremonial gifting, and heritage preservation across institutional and household settings. Silver tableware occupies the mature revenue core where replacement cycles and estate transfers stabilize volume. E-commerce platforms represent the fastest-growing distribution channel as digital authentication and virtual showroom technologies reduce purchase friction for high-value articles. The hospitality sector concentrates margin pools through custom commission contracts and volume procurement agreements.
FDA guidelines on food-contact substances and India's BIS hallmarking regulations govern material purity claims and consumer protection, while the EU REACH framework restricts certain alloy additives in imported metal goods. These standards elevate compliance costs for smaller fabricators but simultaneously reinforce brand trust for certified producers. Stakeholders must monitor evolving digital provenance requirements and traceability mandates that will reshape supplier qualification criteria across major consuming markets.
Market Dynamics
Hallmarking mandates and digital authentication protocols are compressing traditional certification timelines while elevating compliance thresholds for silver food fabricators across major consuming markets.
Growth Catalysts
- BIS Hallmarking Mandates:India's mandatory precious metal certification creates standardized quality benchmarks that expand addressable demand among risk-averse institutional buyers.
- Antimicrobial Surface Properties:Sterling silver's inherent bacterial inhibition drives replacement demand in healthcare-adjacent hospitality settings seeking dual prestige and hygiene credentials.
- Heritage Preservation:Estate transfer cycles in established wealth centers generate recurring volume through ceremonial gifting traditions that resist commoditization pressures.
Market Restraints
- Silver Price Volatility:London Bullion Market Association spot pricing fluctuations compress fabrication margins and deter long-term procurement commitments from price-sensitive hospitality operators.
- Substitution by Stainless Steel:Premium-grade surgical steel tableware captures mid-market volume through comparable durability at fractional material cost.
- EU REACH Additive Restrictions:ECHA limitations on certain copper alloy compositions increase reformulation costs for export-oriented Indian and Chinese fabricators.
Strategic Opportunities
- Virtual Showroom Technologies:Augmented reality visualization tools reduce purchase friction for high-value custom commissions by institutional hospitality buyers.
- Digital Provenance Systems:Blockchain-anchored supply chain documentation responds to emerging traceability mandates from Dubai Multi Commodities Centre and Singapore Bullion Market Association.
- Secondary Market Reactivation:Refurbishment and re-certification services unlock dormant inventory in estate holdings across Japan's aging demographic cohort.
Industry Challenges
- Artisan Skill Attrition:Master silversmith apprenticeship pipelines face demographic collapse in traditional fabrication clusters including Sheffield and Jodhpur.
- Certification Timeline Compression:BIS assay office backlogs extend product launch cycles, constraining responsiveness to seasonal hospitality procurement windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silver Food Market |
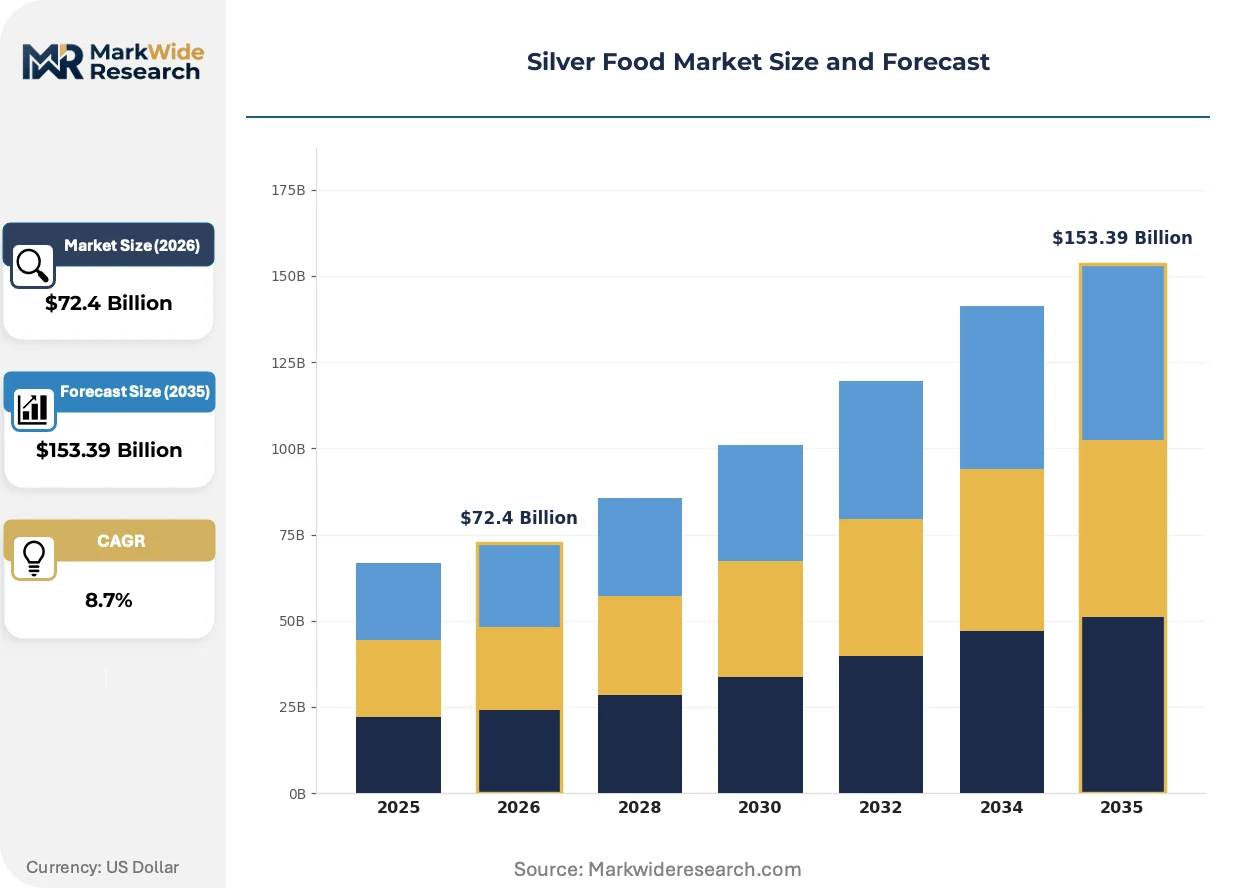
| Market Size in 2026 | $72.4 Billion |
| Market Size in 2035 | $153.39 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silver Plated Utensils, Silver Cookware, Silver Decorative Items, Silver Tableware End User: Households, Restaurants, Hospitality Sector, Online Retailers Distribution Channel: Offline Retail, E-commerce Platforms, Wholesale, Specialty Stores Price Tier: Luxury, Premium, Mid-range, Economical |
| Companies Covered | Pan American Silver, Endeavour Silver, Hecla Mining Company, SilverCrest Metals, Silvercorp Metals, Coeur Mining, First Majestic Silver, Dolly Varden Silver, Americas Gold and Silver, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silver Food Market Emerging Trajectories
Authentication technologies and supply chain transparency tools are redrawing competitive boundaries between heritage fabricators and digitally native entrants.
Laser-induced breakdown spectroscopy is collapsing the cost structure of non-destructive purity verification. Hospitality procurement departments at luxury hotel chains now deploy handheld LIBS devices for inbound inspection. This capability compression is collapsing third-party assay dependencies and accelerating supplier qualification cycles.
India's BIS hallmarking regulations for precious metal articles now mandate four-mark certification including year of manufacture and jeweler identification. Fabricators serving export markets must maintain parallel compliance documentation for EU REACH and FDA food-contact substance guidelines. Small-scale producers in Moradabad and Jaipur are consolidating to share centralized assay and documentation infrastructure.
Direct-to-institutional sales models are displacing layered distributor networks for volume hospitality accounts. Premium hotel groups now negotiate frame contracts directly with certified fabricators, bypassing traditional wholesale channels. This disintermediation is most visible in Dubai's hospitality procurement clusters and Singapore's integrated resort supply chains.
Silver Food Market Segmentation
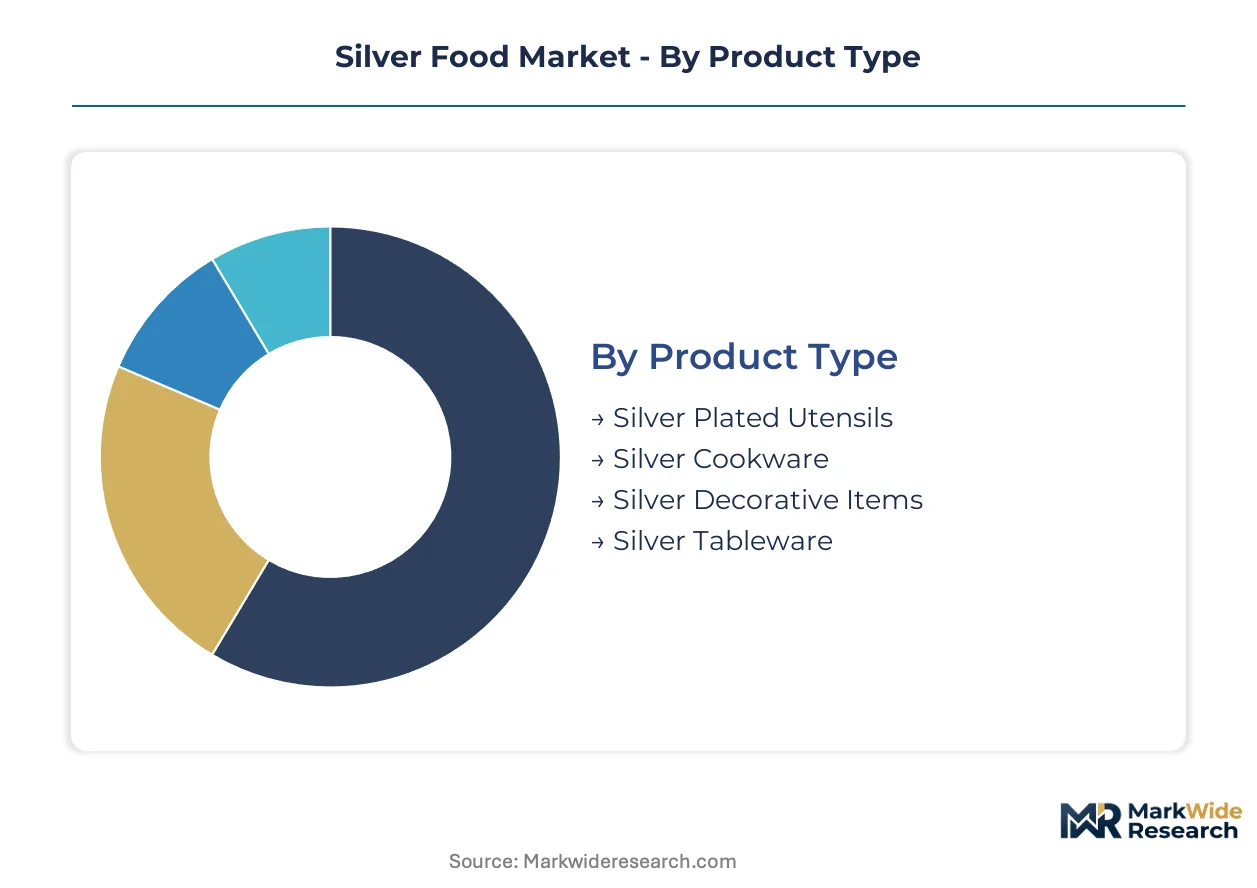
Segmentation in silver food markets exposes divergent margin structures and service intensity requirements across fabrication tiers. Procurement patterns in institutional hospitality diverge sharply from household acquisition cycles, reshaping how fabricators configure warranty and refurbishment offerings.
Product Type:
After-sales service intensity varies dramatically across product categories, with heirloom-grade tableware demanding multi-decade repair networks versus disposable-plated utensils requiring minimal post-purchase support.
- Silver Tableware:Comprises sterling silver flatware, serving pieces, and hollowware with 92.5% purity certification. Demand concentrates in India's wedding gifting corridors and Dubai's hotel procurement clusters, driven by BIS hallmarking mandates that elevate trust premiums for certified heritage fabricators. By volume, silver tableware leads. By growth pace, silver plated utensils is ahead.
- Silver Plated Utensils:Features electro deposited silver layers over nickel or copper substrates, offering antimicrobial surface properties at reduced material intensity. Replacement cycles accelerate in North American casual dining chains seeking hygiene credentials without capital commitment to solid silver. By volume, silver tableware leads. By growth pace, silver plated utensils is ahead.
- Silver Cookware:Encompasses serving vessels and specialty cooking implements with thermal conductivity advantages for precision temperature control. Moradabad fabrication clusters supply India's domestic ceremonial market.
- Silver Decorative Items:Includes centerpieces, candelabras, and presentation stands with lower functional duty cycles. Estate transfer volumes in Japan sustain refurbishment service demand.
Cost tier stratification separates investment-grade solid silver from accessible plated alternatives, with fabrication labor intensity driving the wedge.
End User:
Customer type determines contract structure complexity, with hospitality frame contracts demanding serialized traceability versus household spot purchases.
- Hospitality Sector:Comprises luxury hotel chains, integrated resorts, and premium cruise operators procuring through multi-year frame agreements with direct-to-institutional fabricators. Singapore's Marina Bay and Dubai's Palm Jumeirah procurement offices negotiate volume discounts tied to digital provenance documentation. Volume concentration favors hospitality procurement. Margin expansion concentrates in household gifting.
- Households:Encompasses individual consumers acquiring through retail channels for ceremonial gifting, heritage preservation, and prestige dining occasions. India's tier-2 cities are expanding addressable demand as hallmarking literacy spreads.
- Restaurants:Covers independent fine-dining establishments and regional chain operators balancing durability requirements against capital constraints. Stainless steel substitution pressure is most acute in this segment.
- Online Retailers:Represents curated e-commerce platforms and digital-native brands leveraging virtual showroom technologies to reduce purchase friction for high-value articles.
Application context determines purity specification stringency, with healthcare-adjacent hospitality settings demanding certified antimicrobial performance.
Distribution Channel:
Channel selection directly shapes authentication burden, with direct institutional sales collapsing traditional assay verification steps.
- E-commerce Platforms:Digital marketplaces deploy augmented reality visualization and blockchain-anchored provenance documentation to substitute for physical inspection. Dubai Multi Commodities Centre traceability mandates are accelerating platform investment in supplier qualification infrastructure.
- Specialty Stores:Curated retail environments offer in-person hallmark verification and bespoke commission services for wedding and corporate gifting segments.
- Offline Retail:Traditional department stores and jewelry chains with established assay partnerships and heritage brand concessions.
- Wholesale:Layered distributor networks serving mid-market hospitality and restaurant accounts, increasingly disintermediated by direct fabricator relationships.
Supply concentration in direct-to-institutional channels is compressing wholesale margin pools while elevating platform commission structures.
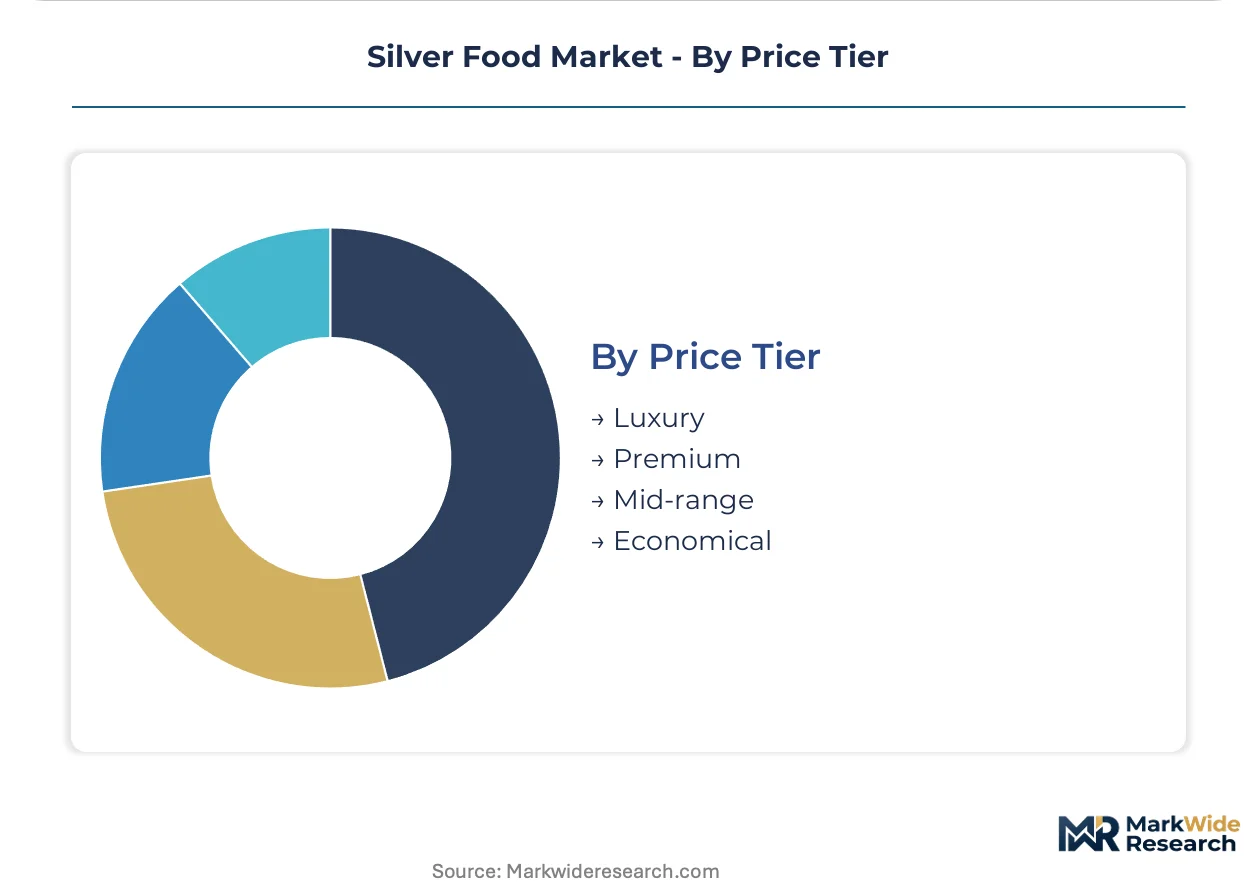
Price Tier:
Maturity gradients separate established luxury heritage brands from emerging digital-native entrants in accessible tiers.
- Luxury:Investment-grade solid silver articles from heritage fabricators with multi-generational brand equity, commanding premiums for master craftsmanship and documented provenance. Sheffield and Jaipur ateliers dominate commissioning queues.
- Premium:High-purity plated articles and certified sterling pieces from scaled fabricators with centralized assay infrastructure, capturing institutional hospitality volume.
- Mid-range:Standardized plated utensils and decorative items serving replacement demand and casual gifting occasions.
- Economical:Thin-plated or silver-tone alternatives for price-sensitive hospitality operators and occasional-use households.
Certification grade stratification is displacing simple material-based tiering as BIS and EU REACH compliance costs filter through pricing structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Indian silver food markets commands premiums exceeding Dubai procurement benchmarks by double-digit margins, while Chinese fabrication clusters compete on throughput velocity rather than certification premiums. This asymmetry reshapes how fabricators configure regional go-to-market architectures.
India
Wedding gifting corridors in tier-2 cities drive volume expansion as BIS hallmarking literacy spreads beyond metropolitan centers. The Bureau of Indian Standards mandates four-mark certification including year of manufacture and jeweler identification. Moradabad and Jaipur fabrication clusters consolidate to share centralized assay infrastructure, reducing compliance costs for mid-scale producers.
China
Domestic ceremonial demand and export-oriented plated utensil production sustain dual-track manufacturing bases. GB standards and SAMR oversight govern food-contact metal safety specifications. Shenzhen and Guangzhou industrial zones prioritize electroplating throughput for North American casual dining chain procurement.
United States
Healthcare-adjacent hospitality settings seek antimicrobial surface credentials for premium positioning against stainless steel alternatives. FDA food-contact substance guidelines and EPA antimicrobial claims oversight shape material specification protocols. Newport and Providence heritage fabricators maintain master silversmith apprenticeship pipelines for heirloom-grade commissioning.
United Arab Emirates
Dubai Multi Commodities Centre traceability mandates accelerate blockchain-anchored provenance adoption among hospitality procurement offices. MOHAP food safety standards intersect with precious metal import regulations. Jumeirah and Downtown Dubai hotel clusters negotiate direct frame contracts with certified fabricators, bypassing traditional wholesale layers.
Japan
Estate transfer volumes among aging demographic cohorts sustain refurbishment service demand for pre-war silver collections. METI consumer protection standards and JIS precious metal marking requirements govern resale authentication. Tokyo and Osaka metropolitan areas concentrate heritage dealer networks and re-certification service providers.
Silver Food Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower scope but deeper technical positioning. The vendor base stratifies between mining-scale upstream anchors, mid-tier refiners with captive fabrication capacity, and downstream heritage brands with multi-generational commissioning queues. Three archetypes dominate: extraction-backed supply guarantors, vertically integrated refiners, and design-forward heritage houses. Competitive moves concentrate on direct-to-institutional procurement relationships and digital provenance infrastructure deployment.
Among North American mining enterprises, Pan American Silver, Hecla Mining Company, and First Majestic Silver occupy positions spanning extraction scale and downstream integration depth. Pan American Silver exemplifies the supply-security anchor archetype through mining breadth. Hecla Mining Company represents sustained production dominance within long-life asset frameworks. First Majestic Silver sits within the vertical integration tier, bridging extraction through refined bullion stages.
| Leading Market Players |
|---|
| Pan American Silver |
| Endeavour Silver |
| Hecla Mining Company |
| SilverCrest Metals |
| Silvercorp Metals |
| Coeur Mining |
| First Majestic Silver |
| Dolly Varden Silver |
| Americas Gold and Silver |
| Others |
Supply Flow & Price Mechanics
Dubai-Jebel Ali freight corridors carry hallmark-certified silver food articles from Indian fabrication clusters to UAE hospitality procurement offices, with container cost dynamics amplifying the spread between Moradabad bulk exports and Jumeirah luxury retail markups. This logistics architecture concentrates pricing power among heritage fabricators with direct-to-institutional frame contracts while compressing wholesale margin pools for layered distributor networks.
Pricing Analysis
Customization-premium spreads separate configured-to-order ceremonial commissions from standardized plated utensil catalogs. Three-tier pricing structure across heritage-certified, assay-verified, and economy-plated levels anchors transactional models in the silver food market. Price differentiation hinges on BIS hallmark grade and master silversmith attribution, with stainless steel substitution pressure intensifying cost compression in mid-range hospitality procurement. Casual dining chains exhibit acute price sensitivity, while luxury hotel groups prioritize provenance documentation over unit economics.
Supply Chain Analysis
Export-control regimes on precious metal refining technology limit equipment flows to Moradabad and Jaipur fabrication clusters, constraining assay automation adoption. Supply concentrates in India, China, and the United Arab Emirates, with raw material dependencies on London Bullion Market Association-certified silver feedstock, copper alloying elements, and nickel substrate for electroplating. Single-source vulnerability runs through BIS assay office backlogs that extend certification timelines. Distribution runs through direct-to-institutional frame contracts displacing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silver food incumbents face substitution defense imperatives against surgical steel tableware capturing mid-market hospitality volume through comparable durability at fractional material cost.
For Market Incumbents: Pre-empt stainless steel encroachment by embedding antimicrobial performance guarantees into frame contract terms with Dubai and Singapore hospitality clusters. Consolidate master silversmith apprenticeship pipelines in Sheffield and Jodhpur before demographic collapse accelerates. Backward integration into captive refining secures margin against London Bullion Market Association spot volatility.
For New Entrants and Emerging Players: Establish a beachhead in India's tier-2 wedding gifting corridors where BIS hallmarking literacy expansion creates addressable demand among first-time certified buyers. Target digital-native curation platforms with blockchain-anchored provenance documentation as the primary go-to-market angle, bypassing legacy wholesale layers entirely.
For Investors and Strategic Acquirers: Carve-out targets emerge from family-owned heritage fabricators with dormant commissioning queues and unmonetized estate refurbishment service networks. Long-term viability hinges on certification infrastructure ownership rather than brand equity alone. Watch for BIS assay office capacity expansion announcements as inflection indicators for launch cycle compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Certification Infrastructure Consolidation | Shared BIS assay facilities in Moradabad reduce compliance costs for mid-scale fabricators competing against heritage houses. |
| Direct-to-Institutional Frame Contracts | Marina Bay and Palm Jumeirah procurement offices bypass wholesale layers, collapsing traditional distributor margins. |
| Digital Provenance Platform Deployment | Blockchain-anchored documentation satisfies Dubai Multi Commodities Centre traceability mandates for hospitality buyers. |
| Master Silversmith Apprenticeship Programs | Sheffield and Jodhpur ateliers secure generational craft continuity against demographic attrition in traditional clusters. |
| Secondary Market Reactivation Services | Refurbishment and re-certification unlock dormant estate inventory across Japan's aging demographic cohort. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of BIS regulatory filings, EU REACH substance restriction updates, and hospitality procurement database extracts. Primary interviews engaged heritage fabricator operations directors, luxury hotel group procurement officers, precious metal assay laboratory managers, and curated e-commerce platform category leads. Secondary validation drew from Bureau of Indian Standards circulars, Dubai Multi Commodities Centre traceability guidelines, and London Bullion Market Association pricing archives. Bottom-up volume estimates from fabrication cluster output data triangulate against top-down spending flow analysis across end-use segments.
Forecast inputs span product type segmentation across sterling tableware and plated utensils, end-user categories distinguishing hospitality frame contracts from household ceremonial gifting, and distribution channel evolution tracking e-commerce platform penetration. Modeled projections incorporate purity grade stratification, certification tier adoption curves, and regional hallmarking mandate implementation timelines across the analysis window. CAGR derivation rests on replacement cycle analysis for heirloom-grade articles and procurement volume elasticity in healthcare-adjacent hospitality settings.
Macroeconomic conditions sit as an overlay; deviation in silver spot price volatility, freight rate spikes through Red Sea corridors, or BIS assay office capacity constraints would shift the trajectory. Forecasts reflect documented assumptions on hallmarking literacy diffusion rates and stainless steel substitution elasticity. Material shifts in EU REACH additive restriction scope or India BIS four-mark enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Halal Foods Market
Specialty Foods
Sweet Spreads Market
Specialty Foods
Halal Products Market
Specialty Foods
Global Truffle Market
Specialty Foods
Tahini Market
Specialty Foods
Gluten-Free Oats Market
Specialty Foods
Gluten-Free Desserts and Ice Creams Market
Specialty Foods
Global Nata De Coco Market
Specialty Foods
Hot Pot Market
Specialty Foods
Vegan Salad Dressing Market
Specialty Foods
Hot and Sour Noodles Market
Specialty Foods
Grain Free Dog Food Market
Specialty Foods
Global Bee Products Market
Specialty Foods
Super Foods Market
Specialty Foods
Grain-Free Pet Food Market
Specialty Foods
North American Jam, Jelly, and Preserve Market